
 Crypto Automated Teller Machine Market | 2026-2036
Crypto Automated Teller Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Crypto Automated Teller Machine Market Outlook
The Crypto Automated Teller Machine market is expanding along a widening gap between premium two-way machines with full Know-Your-Customer compliance and stripped-down one-way kiosks competing on placement density. GENERAL BYTES s.r.o. leverages its open-source software architecture to sustain rapid hardware customization for regional operators. Genesis Coin Inc. anchors the North American installed base through its long-standing Genesis1 and Satoshi1 product lines. Bitcoin Depot Inc. competes aggressively on retail footprint, controlling thousands of active locations across the United States.
A crypto automated teller machine functions as a self-service terminal enabling cash-to-cryptocurrency or cryptocurrency-to-cash conversion, typically integrating bill validators, thermal printers, and encrypted network connections to exchange APIs. These machines serve commercial purposes by bridging fiat banking infrastructure and blockchain networks for unbanked or privacy-seeking users. Two-way ATMs command the highest transaction fees and margin pools due to their dual-direction capability and enhanced compliance overhead. One-way ATMs represent the volume leader in unit deployments, particularly among cost-conscious merchants seeking minimal maintenance. Kiosks segment growth concentrates in high-traffic retail environments where space constraints favor compact footprints over full ATM specifications.
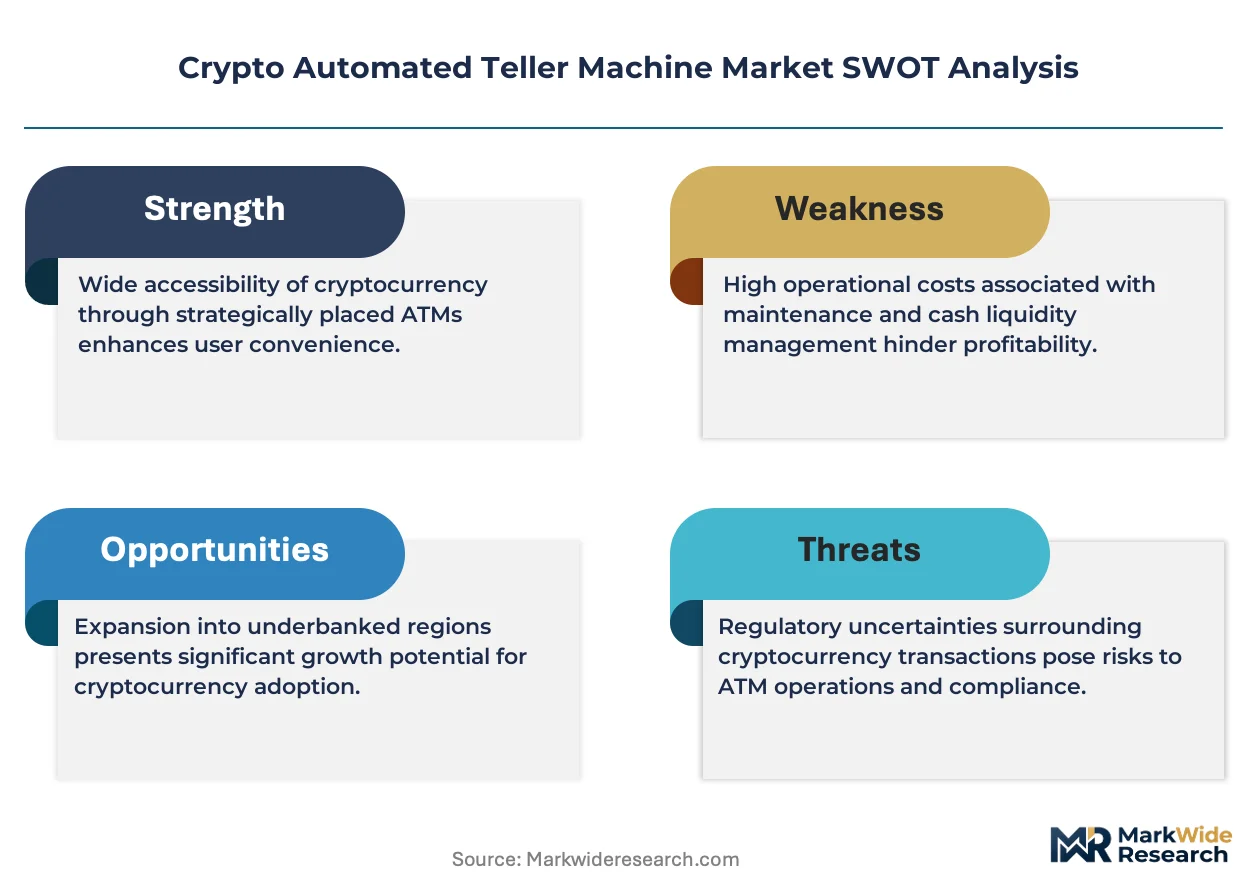
FinCEN's Bank Secrecy Act requirements impose anti-money laundering protocols on operators, while state-level money transmitter licenses create fragmented market access barriers across the United States. The EU's Markets in Crypto-Assets regulation extends compliance obligations to kiosk operators serving European users, shaping product design for identity verification modules. ISO standards for financial device security influence hardware certification requirements in multiple jurisdictions. Stakeholders must monitor evolving custodial versus non-custodial classification debates, as regulatory reclassification would fundamentally alter operator capital requirements and liability structures.
Market Dynamics
The Crypto Automated Teller Machine market operates on a widening capability gap between full-service two-way terminals with embedded compliance stacks and stripped-down one-way kiosks optimized for placement velocity. This structural tension shapes capital allocation, operator licensing requirements, and hardware procurement cycles across every geography.
Growth Catalysts
- FinCEN's Bank Secrecy Act:Federal anti-money laundering protocols create a compliance moat that rewards scaled operators with established AML infrastructure, pushing smaller competitors toward consolidation or exit.
- Retail merchant channel:Convenience stores and gas stations deploy kiosks to capture alternative revenue streams from foot traffic without expanding payroll, creating a low-friction expansion pathway for operators.
- Bill validator miniaturization:Next-generation cash acceptance hardware reduces machine footprints by approximately forty percent, enabling deployment in space-constrained urban retail environments previously inaccessible to full-size terminals.
Market Restraints
- State money transmitter licensing:Fragmented fifty-state compliance requirements impose six-figure entry costs and twelve-to-eighteen-month approval timelines, structurally limiting new operator formation in the United States.
- Encrypted network infrastructure:Dedicated secure connectivity for blockchain API access adds recurring operational overhead that compresses margins on low-volume kiosk placements.
- Biometric identity modules:Hardware costs for fingerprint and facial recognition components required by emerging compliance standards inflate unit economics for two-way machine deployments.
Strategic Opportunities
- EU Markets in Crypto-Assets framework:MiCA's unified licensing regime replaces fragmented national regimes, creating a regulatory tailwind for kiosk operators seeking pan-European footprint expansion without repeated jurisdictional registration.
- Remittance corridor terminals:Cross-border cash-to-crypto conversion at source-market kiosks paired with stablecoin settlement addresses unbanked recipient populations in Mexico, the Philippines, and Nigeria.
- Non-custodial wallet integration:Direct-to-user wallet architecture eliminates operator custody risk and capital reserve requirements, rewiring liability structures and enabling leaner balance sheet deployment.
Industry Challenges
- Blockchain forensics expertise:Operators struggle to recruit analysts capable of interpreting transaction patterns for suspicious activity reporting, creating compliance execution risk even where policies are documented.
- Legacy banking relationship maintenance:De-risking pressures from correspondent banks force operators to maintain redundant depository relationships across multiple financial institutions, fragmenting treasury operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crypto Automated Teller Machine Market |
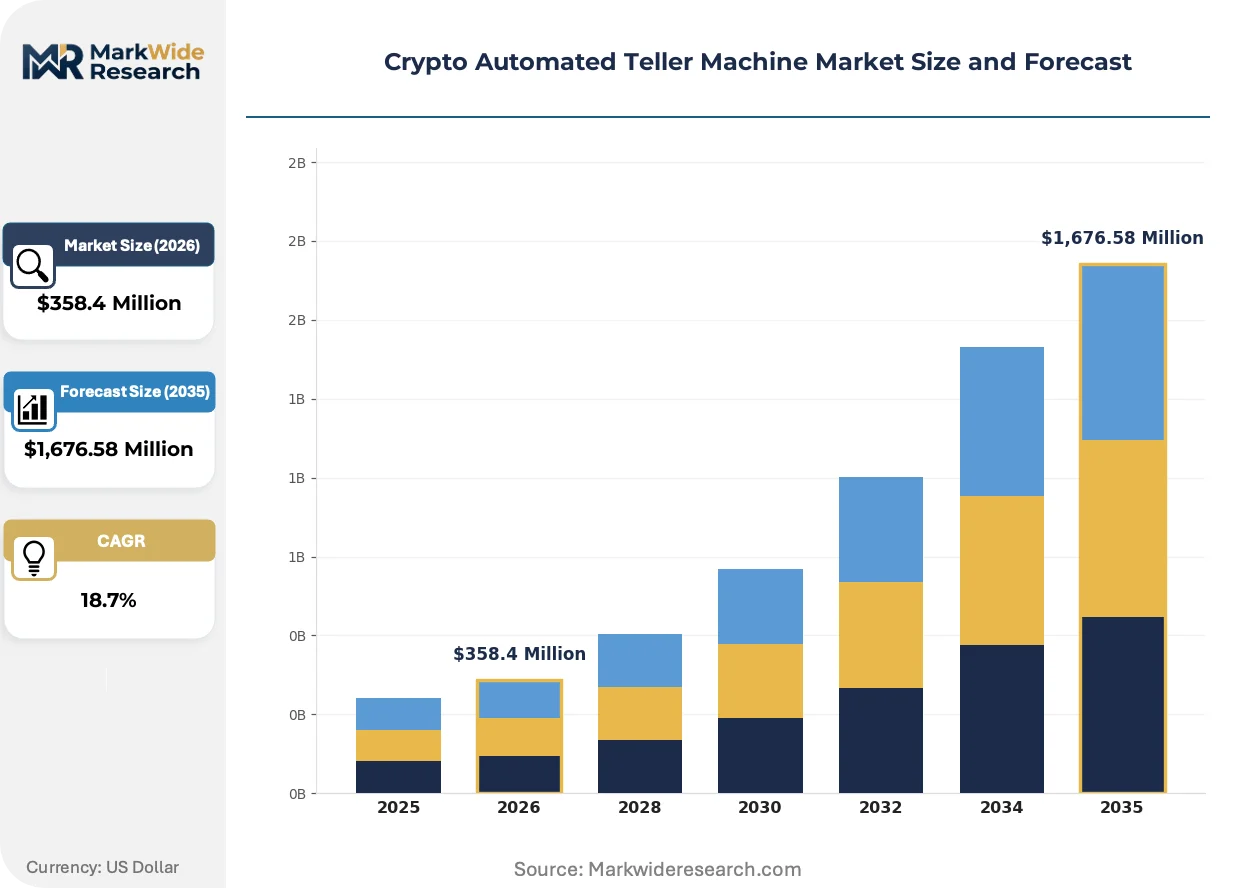
| Market Size in 2026 | $358.4 Million |
| Market Size in 2035 | $1,676.58 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Two-Way ATMs, One-Way ATMs, Kiosks, Mobile ATMs Transaction Volume: Low Volume, Medium Volume, High Volume, Premium Volume User Type: Individual Users, Merchants, Investors, Businesses Payment Method: Cryptocurrency, Credit Card, Debit Card, Cash |
| Companies Covered | GENERAL BYTES s.r.o., Genesis Coin Inc., Bitcoin Depot Inc., Lamassu Industries AG, Bitstop, Coinsource, Byte Federal, Inc., RockItCoin, Coinme, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crypto Automated Teller Machine Market Strategic Shifts
Hardware manufacturers and kiosk operators are racing to embed modular compliance architectures that adapt to diverging jurisdictional requirements without full machine replacement. This capability arms race is compressing product lifecycles and rewiring procurement relationships between software and hardware layers.
Contactless NFC authentication is rewriting customer onboarding workflows at high-traffic urban placements. Retail operators in New York and Los Angeles deploy terminals with tap-to-verify identity modules that reduce transaction friction for repeat users. This interface standard is compressing queue times and enabling higher throughput per machine hour, directly impacting revenue per square foot calculations for host merchants.
FinCEN's 2013 guidance on virtual currency money services businesses continues to shape enforcement patterns across the United States. State banking commissioners in Texas, New York, and California have built specialized examination teams targeting kiosk operators for BSA program adequacy. Two-way machine networks face disproportionate scrutiny due to bidirectional flow monitoring complexity, driving investment in automated transaction surveillance systems.
Merchant procurement preferences are gravitating toward revenue-share arrangements that eliminate upfront hardware capital requirements. Host locations in high-traffic convenience retail now demand guaranteed minimum payments or percentage-of-gross structures rather than flat monthly rent. This shift is visible most acutely in Florida and Georgia, where Bitcoin Depot and Coinsource compete aggressively for shelf space through differentiated partnership economics.
Crypto Automated Teller Machine Market Segmentation
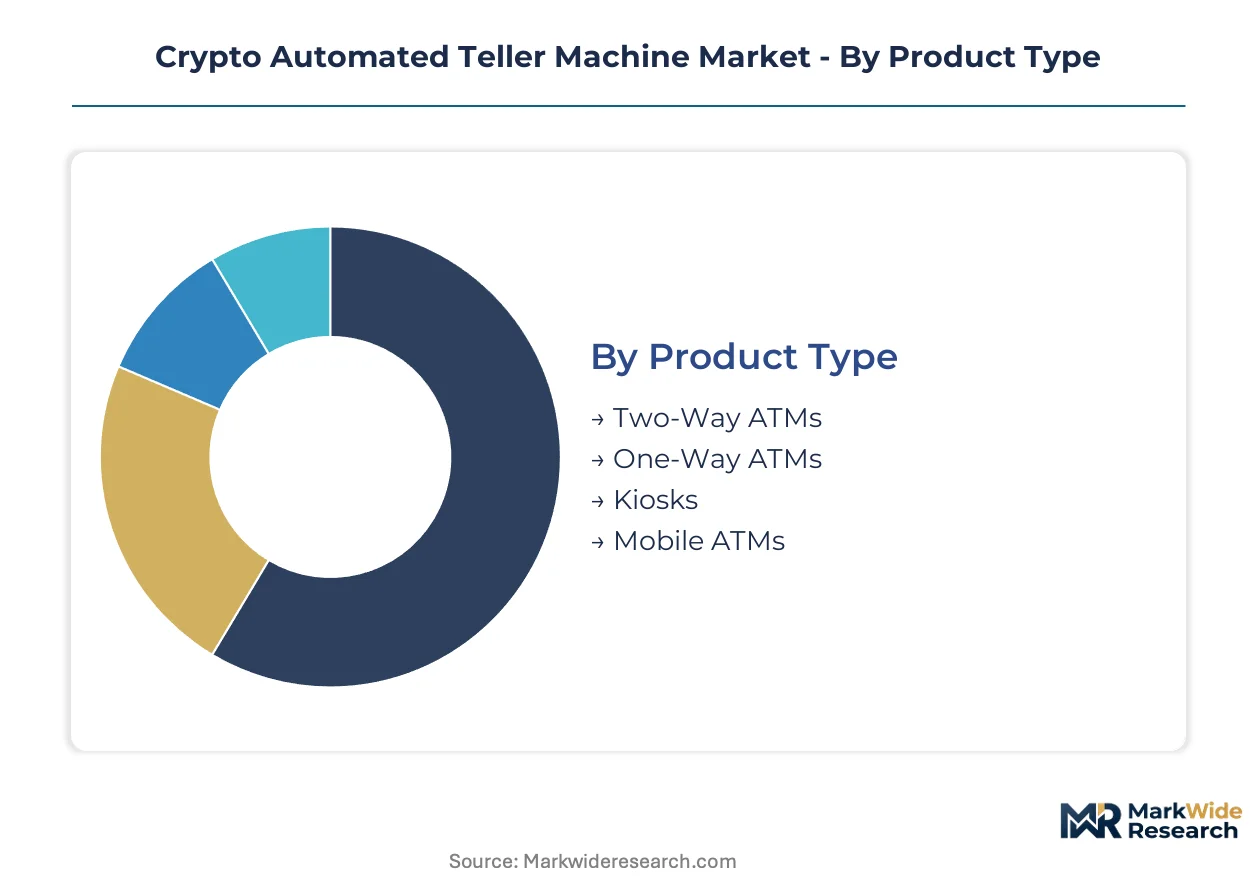
Segmentation in the Crypto Automated Teller Machine market reveals how hardware specifications, transaction patterns, and user profiles determine placement economics. Operators calibrate machine configurations to match local regulatory density and foot traffic profiles.
Product Type:
Customization intensity spans from fully configurable two-way terminals to standardized one-way kiosks optimized for rapid deployment.
- Two-Way ATMs:Bidirectional machines enable cash-to-crypto and crypto-to-cash conversion through integrated bill validators and cash dispensers. Demand concentrates in high-compliance jurisdictions like New York and Texas where FinCEN's Bank Secrecy Act enforcement is strictest, driving premium placement fees.
- One-Way ATMs:Single-direction terminals accept cash for cryptocurrency purchase only, reducing hardware complexity and maintenance overhead. Volume leadership sits with convenience store operators in Florida and Georgia seeking minimal-touch revenue streams without custody risk.
- Kiosks:Compact footprint machines prioritize space efficiency over full ATM specifications.
- Mobile ATMs:Portable units deploy at temporary events and seasonal high-traffic locations.
Most installed capacity flows through One-Way ATMs. Expansion is steepest in Kiosks.
Transaction Volume:
Cost tier separation distinguishes capital-intensive premium installations from lean low-volume placements.
- Low Volume:Machines processing under fifty transactions monthly serve rural markets and experimental placements.
- Medium Volume:Terminals handling fifty to two hundred transactions monthly anchor suburban retail corridors.
- High Volume:Machines exceeding two hundred monthly transactions dominate urban convenience store clusters in Los Angeles and Miami.
- Premium Volume:Ultra-high throughput terminals at transportation hubs and entertainment districts command maximum revenue-share percentages from host merchants.
Hardware procurement prioritizes Medium Volume specifications. Merchant acquisition targets Premium Volume locations.
User Type:
Customer type fragmentation separates privacy-seeking individuals from compliance-tolerant institutional accounts.
- Individual Users:Unbanked and underbanked consumers seeking cash-to-crypto conversion without traditional banking relationships.
- Merchants:Retail location owners deploying machines as ancillary revenue generators alongside core operations.
- Investors:High-net-worth individuals executing large-block transactions requiring enhanced identity verification and transaction monitoring.
- Businesses:Corporate treasury operations utilizing cryptocurrency for cross-border settlement and vendor payments.
Transaction frequency peaks with Individual Users. Average ticket size climbs highest among Businesses.
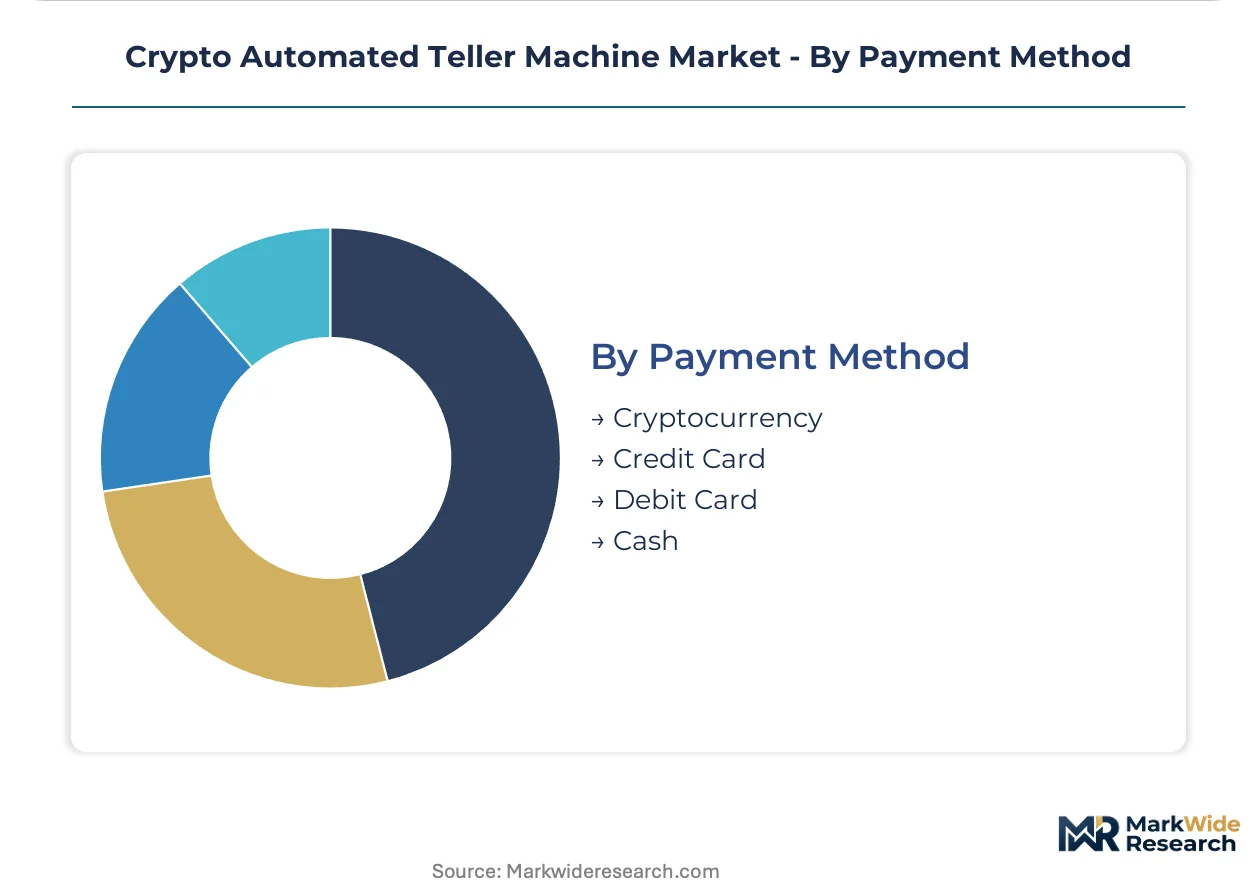
Payment Method:
Maturity gradients separate established cash infrastructure from emerging digital-native rails.
- Cryptocurrency:Direct wallet-to-wallet transfers enabling non-custodial settlement without operator intermediation.
- Credit Card:Card-present transactions subject to chargeback risk and higher processing fees.
- Debit Card:Lower-fee electronic payments favored by compliance-conscious operators reducing fraud exposure.
- Cash:Physical currency acceptance through bill validators remains the dominant input method for unbanked user acquisition.
Cash dominates input flows. Cryptocurrency is gaining share fastest for output settlements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized compliance talent clusters in New York, London, and Singapore anchor kiosk network expansion strategies. These regulatory expertise concentrations enable operators to navigate fragmented licensing regimes across jurisdictions. The geographic footprint of active machines tracks closely to where AML legal specialists and blockchain forensics analysts concentrate.
United States
Retail merchant partnerships in Florida and Georgia drive placement velocity as convenience store chains seek ancillary revenue streams. FinCEN's Bank Secrecy Act enforcement creates compliance moats that reward scaled operators with established AML infrastructure. Los Angeles and Miami host the densest urban kiosk clusters, where high foot traffic justifies premium two-way machine deployments.
Canada
Cross-border remittance corridors linking Toronto and Vancouver to source markets in the Philippines and Nigeria sustain demand for cash-to-crypto conversion terminals. The Financial Transactions and Reports Analysis Centre of Canada imposes reporting obligations on virtual currency money services businesses. Calgary and Montreal emerge as secondary hubs where regional operators test compact kiosk configurations.
Germany
Privacy-conscious consumers in Berlin and Munich sustain demand for non-custodial wallet integration at retail terminals. BaFin's classification of crypto ATMs as financial commission business shapes operator licensing requirements across federal states. The Rhine-Ruhr metropolitan region concentrates hardware deployment trials for contactless NFC authentication modules.
Switzerland
Crypto Valley proximity in Zug canton attracts kiosk operators seeking regulatory dialogue with FINMA on custody classification. The country's dual-track approach to blockchain innovation permits controlled experimentation with two-way machines in high-compliance environments. Zurich and Geneva host premium-volume placements serving high-net-worth investor segments.
Singapore
Remittance corridor demand from Southeast Asian guest worker populations anchors kiosk placement strategies in Little India and Geylang. The Monetary Authority of Singapore's payment services framework imposes AML and technology risk management standards on digital payment token service providers. The city-state's compact geography enables rapid network density testing for compact footprint machines.
Crypto Automated Teller Machine Market Competitive Environment
Capital-heavy hardware manufacturers compete with asset-light kiosk operators across divergent margin structures. The vendor base separates into three tiers: open-source software platforms enabling rapid regional customization, vertically integrated operators controlling end-to-end placement and compliance, and specialized hardware fabricators supplying bill validator and thermal printer subsystems. Consolidation pressures concentrate among scaled operators capable of absorbing state-level money transmitter licensing costs. Dominant competitive moves include retail footprint expansion through revenue-share partnerships and modular compliance architecture development for multi-jurisdictional deployment.
Among Czech Republic-based software platforms, GENERAL BYTES s.r.o. exemplifies the open-source archetype enabling rapid hardware customization for regional operators. Genesis Coin Inc. and Bitcoin Depot Inc. occupy positions on the vertically integrated spectrum, with the former anchoring North American installed base relationships and the latter representing aggressive retail footprint competition across thousands of active United States locations. These three anchors illustrate the structural tension between software flexibility and operational scale in kiosk network economics.
| Leading Market Players |
|---|
| GENERAL BYTES s.r.o. |
| Genesis Coin Inc. |
| Bitcoin Depot Inc. |
| Lamassu Industries AG |
| Bitstop |
| Coinsource |
| Byte Federal, Inc. |
| RockItCoin |
| Coinme |
| Others |
Value Chain & Pricing Dynamics
Blockchain forensics analysts cluster in New York and London, driving labor-cost differentials that widen pricing-tier spreads between premium two-way terminals and stripped-down one-way kiosks. Regional wage premiums for compliance-certified technicians inflate service bundling costs for full-service deployments while lean kiosk networks absorb lower-skill installation labor.
Pricing Analysis
Bundled compliance-as-a-service packages separate from unbundled hardware-only procurement. Three-tier pricing structure across premium, standard, and economy levels reflects FinCEN audit readiness, biometric identity module inclusion, and software customization depth. Price differentiation hinges on AML infrastructure certification and after-sales regulatory update coverage. Pricing pressure stems from merchant revenue-share demands that compress operator margins on low-volume placements. Individual users exhibit highest price sensitivity to transaction fees, while corporate treasury clients tolerate premium pricing for enhanced settlement speed.
Supply Chain Analysis
Warehouse-distribution layers concentrate in Texas, Florida, and Georgia hub-and-spoke patterns serving domestic kiosk operators. Hardware assembly draws from Taiwan for bill validator subsystems, China for thermal printer modules, and the Czech Republic for open-source software platforms. Raw material dependencies include precision sheet metal enclosures, encrypted network chipsets, and cash-handling mechanisms. Single-source vulnerability in bill validator miniaturization components creates supply chain risk. Distribution runs through regional operator field teams deploying directly to convenience store and gas station host locations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through bill validator miniaturization cost-down curves and merchant demand shifts toward premium two-way machines with embedded compliance stacks.
For Market Incumbents: Lock in retail footprint advantages through exclusive revenue-share arrangements with top-ten convenience store chains before state money transmitter licensing barriers harden. Deepen backward integration into bill validator supply relationships to secure component allocation during shortage periods. Acquire regional operators in Texas and Florida to consolidate AML infrastructure overhead across expanded transaction volumes. For New Entrants and Emerging Players: Launch via white-label software partnerships with hardware fabricators in the Czech Republic and Switzerland to bypass proprietary platform development costs. Target underpenetrated remittance corridor terminals linking Toronto and Vancouver to Southeast Asian settlement markets. Pursue EU Markets in Crypto-Assets licensing early to capture pan-European footprint expansion without repeated jurisdictional registration. For Investors and Strategic Acquirers: Payment processors with existing AML infrastructure represent the most active acquirer category in this space, seeking kiosk networks to extend cash-to-digital conversion capabilities. Long-term viability centers on operators capable of absorbing state-level licensing costs while maintaining banking relationships under de-risking pressure. Target acquisition archetypes include scaled two-way machine networks with established FinCEN examination histories. Monitor blockchain forensics analyst hiring velocity as an inflection indicator for compliance execution risk.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Compliance Architecture Development | Enables rapid jurisdictional adaptation without full machine replacement across EU MiCA and US state regimes. |
| Revenue-Share Partnership Expansion | Eliminates upfront merchant capital barriers and accelerates placement velocity in Florida and Georgia retail corridors. |
| Non-Custodial Wallet Integration | Rewires liability structures and reduces capital reserve requirements for leaner balance sheet deployment. |
| Contactless NFC Authentication Rollout | Compresses queue times at high-traffic Los Angeles and Miami urban clusters to maximize throughput. |
| Blockchain Forensics Capability Buildout | Addresses FinCEN suspicious activity reporting demands and defends against enforcement examination risk. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from kiosk network operators, convenience store franchise owners, state banking commissioners, bill validator hardware engineers, and AML compliance officers. Secondary validation drew from FinCEN enforcement action databases, state money transmitter licensing records, EU MiCA regulatory texts, and ISO financial device security standards. Bottom-up transaction volume modeling triangulated against top-down market sizing from installed base counts and average revenue per machine estimates.
Segment-weighting approaches distributed value across product type, transaction volume tier, user category, and payment method dimensions. CAGRs derived from machine deployment trajectories, merchant acquisition rates, and fee structure evolution across the analysis window. Industry-specific inputs included bill validator miniaturization adoption curves, state licensing approval timelines, and biometric identity module cost declines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory reclassification of custodial versus non-custodial operator status. Forecasts reflect documented assumptions regarding FinCEN enforcement continuity, merchant revenue-share structure stability, and correspondent banking relationship persistence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Assets and Cryptocurrency Finance
Crypto ATM Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency Hardware Wallet Market
Digital Assets and Cryptocurrency Finance
Digital Finance Market
Digital Assets and Cryptocurrency Finance
Global Cryptocurrency Market
Digital Assets and Cryptocurrency Finance
Blockchain Distributed Ledger Market
Digital Assets and Cryptocurrency Finance
Tokenization Solution Market
Digital Assets and Cryptocurrency Finance
Digital Asset Trading Platform Market
Digital Assets and Cryptocurrency Finance
Bitcoin Market
Digital Assets and Cryptocurrency Finance
NFT Analytics Tools Market
Digital Assets and Cryptocurrency Finance
Global Cryptocurrency Custody Software Market
Digital Assets and Cryptocurrency Finance
Blockchain Financial Network Market
Digital Assets and Cryptocurrency Finance
United States Digital Asset Management Market
Digital Assets and Cryptocurrency Finance
Decentralized Finance Market
Digital Assets and Cryptocurrency Finance
Bitcoin and Cryptocurrency Atms Market
Digital Assets and Cryptocurrency Finance
Crypto Trading Platform Market
Digital Assets and Cryptocurrency Finance
South Korea Online Trading Platform Market