
 Cryptocurrency and Blockchain Market | 2026-2036
Cryptocurrency and Blockchain Market Size, Share, and Industry Trends Forecast 2026-2036
Cryptocurrency and Blockchain Market Insights
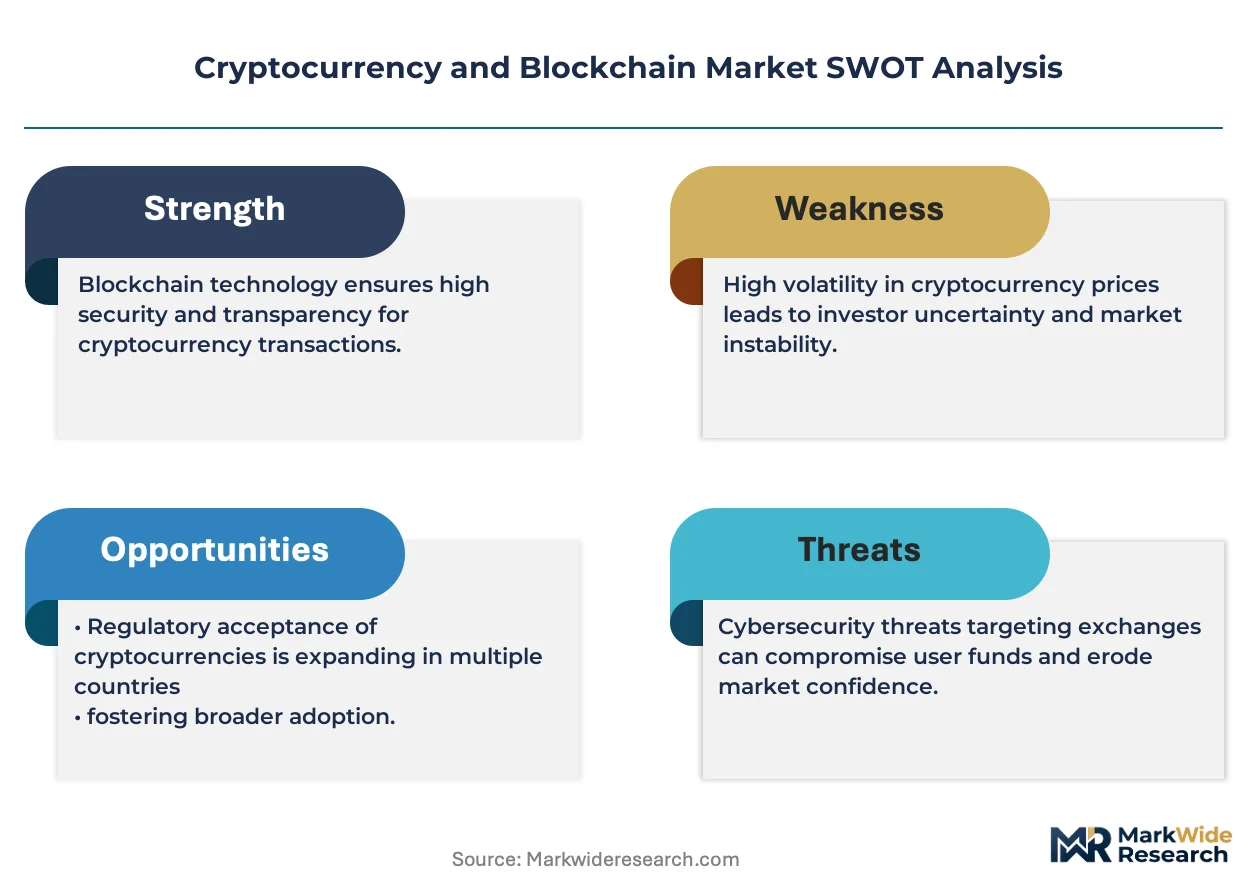
Blockchain developer talent scarcity is bifurcating the competitive landscape between well-capitalized platforms and emerging protocols. Coinbase leverages its regulatory licenses across multiple jurisdictions to sustain institutional onboarding pipelines. Amber Group anchors its position through proprietary trading infrastructure and staking services. Core Scientific competes on energy-efficient mining operations and hosting scale.
Cryptocurrency and blockchain systems employ distributed ledger architectures with cryptographic hashing, consensus mechanisms such as proof-of-stake or proof-of-work, and programmable smart contracts to validate and record transactions without centralized intermediaries. These systems enable peer-to-peer value transfer, automated contractual execution, and transparent asset tracking across financial and industrial workflows. Public deployment models dominate transaction volume and developer activity, while private and consortium configurations capture enterprise blockchain spending from financial institutions and supply chain consortia. Decentralized finance applications within the payments and digital identity segments represent the fastest-expanding use case category, drawing capital from both retail participants and institutional treasuries.
The US SEC and CFTC maintain overlapping enforcement authority that shapes exchange registration requirements and derivatives product availability, while the EU MiCA framework establishes uniform licensing standards for crypto-asset service providers across member states. Financial institutions must navigate this fragmented regulatory terrain when designing cross-border tokenization and custody offerings. Stakeholders should monitor how jurisdictional clarity evolves around stablecoin reserve requirements and decentralized protocol governance liabilities.
Market Dynamics
Regulatory fragmentation across jurisdictions is fragmenting custody infrastructure investments, forcing institutions to maintain parallel compliance stacks for MiCA in Europe, state-level licensing in the US, and the Monetary Authority of Singapore's framework.
Growth Catalysts
- MiCA Uniform Licensing:The EU Markets in Crypto-Assets regulation eliminates passporting friction for stablecoin issuers and exchanges operating across member states, compressing compliance overhead.
- Proof-of-Stake Yields:Institutional treasuries in Singapore and Hong Kong are rotating capital into on-chain staking instruments, pulling demand from traditional fixed-income allocations.
- Tokenization Infrastructure:Private blockchain deployments for real-world asset settlement are expanding in Swiss and Liechtenstein banking consortia, creating captive demand for custody middleware.
Market Restraints
- Energy Input Volatility:Mining operations face margin compression from fluctuating renewable energy certificate prices and grid congestion in Texas and Kazakhstan hosting clusters.
- Developer Talent Scarcity:Rust and Solidity engineering capacity concentrates in Zurich, Singapore, and San Francisco, inflating compensation costs for protocol teams outside these hubs.
- SEC-CFTC Overlap:Dual enforcement authority over derivatives and spot markets creates registration uncertainty for US-based exchanges launching structured products.
Strategic Opportunities
- India Regulatory Clarity:Pending central bank digital currency integration and G20 presidency momentum position the jurisdiction for custody and remittance infrastructure buildout.
- Zero-Knowledge Convergence:Pairing zk-rollup architectures with institutional identity verification opens compliant privacy rails for cross-border settlement networks.
- Brazilian Pension Allocation:CVM regulatory guidance permitting crypto exposure in fund-of-funds structures creates a channel for yield-bearing on-chain instruments into retirement assets.
Industry Challenges
- Smart Contract Audit Bottlenecks:Formal verification expertise for high-value custody contracts queues 8-14 weeks at accredited security firms, delaying mainnet deployments.
- Cross-Chain Integration Complexity:Bridging assets between Ethereum, Solana, and Cosmos ecosystems requires maintaining fragmented validator sets and liquidity pools, inflating operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryptocurrency and Blockchain Market |
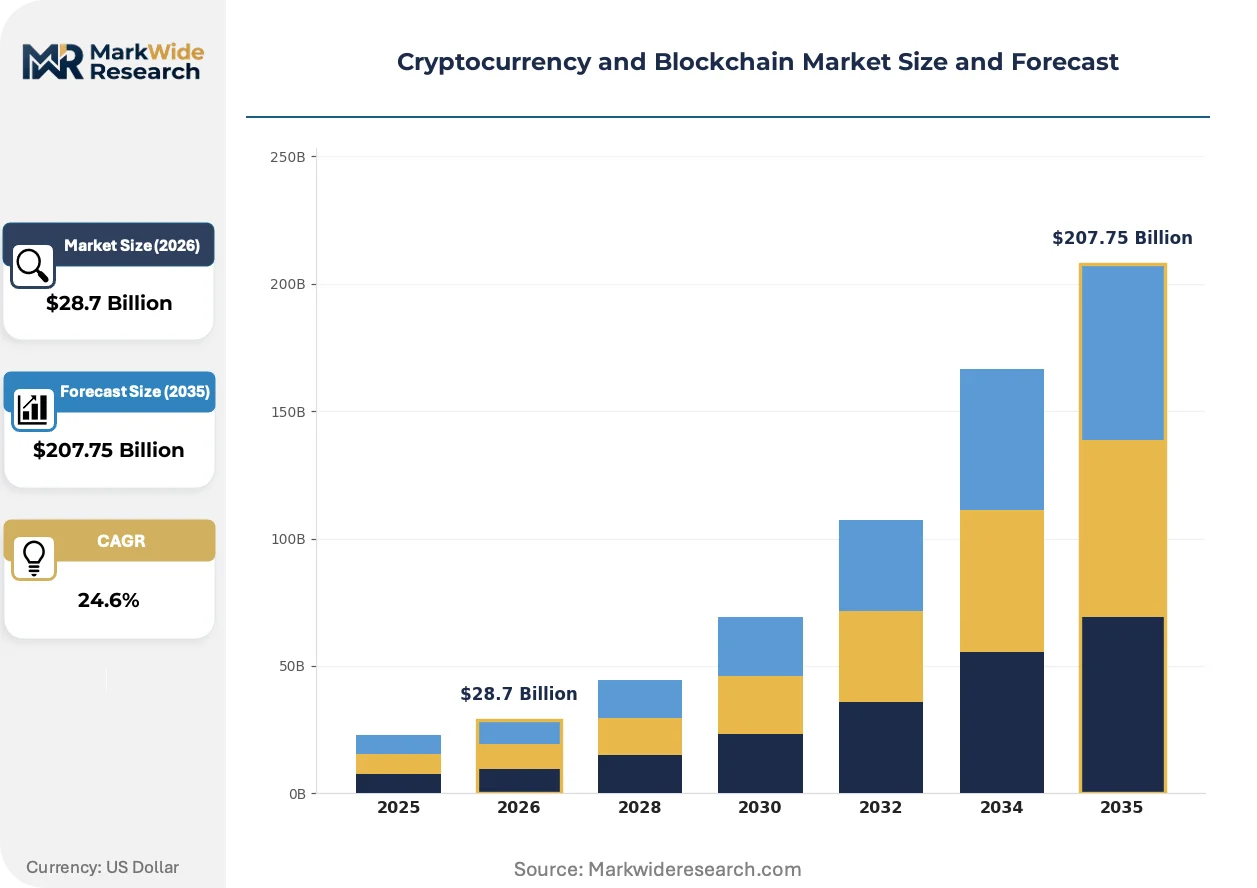
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $207.75 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Blockchain, Distributed Ledger, Smart Contracts, Consensus Algorithms, Cryptography, Tokenization Application: Payments, Digital Identity, Supply Chain Management, Decentralized Finance, Voting Systems, Data Management Deployment: Public, Private, Consortium, Hybrid End User: Financial Institutions, Government Agencies, Technology Providers, Energy Sector, Nonprofit Organizations, Telecommunications |
| Companies Covered | Binance, Coinbase, DWF Labs, Cumberland, Amber Group, B2C2, Keyrock, Kronos Research, Core Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryptocurrency and Blockchain Market Trends and Innovations
Modular blockchain architectures are displacing monolithic layer-one competition, while programmable compliance layers embed regulatory logic directly into transaction execution paths.
Zero-knowledge proof systems are decomposing the tradeoff between transaction privacy and regulatory auditability. Swiss private banks and Singaporean wealth managers are piloting zk-based credential verification for high-net-worth onboarding. This compression of compliance into cryptographic primitives is collapsing the latency between KYC completion and asset movement.
The EU's Markets in Crypto-Assets regulation mandates reserve attestations for stablecoin issuers and exchange segregation requirements. Custody providers must reconfigure cold-wallet architectures and audit reporting pipelines to satisfy national competent authorities. MiCA-registered entities in Germany, France, and the Netherlands are consolidating smaller competitors unable to absorb compliance infrastructure costs.
Institutional buyers are unbundling staking services from exchange relationships, contracting directly with specialized infrastructure operators for non-custodial delegation. This disintermediation compresses fee capture for integrated platforms while expanding validator node operator margins. The shift is most visible in Hong Kong and Singapore, where family offices and hedge funds negotiate bespoke slashing insurance and MEV extraction terms.
Cryptocurrency and Blockchain Market Segmentation
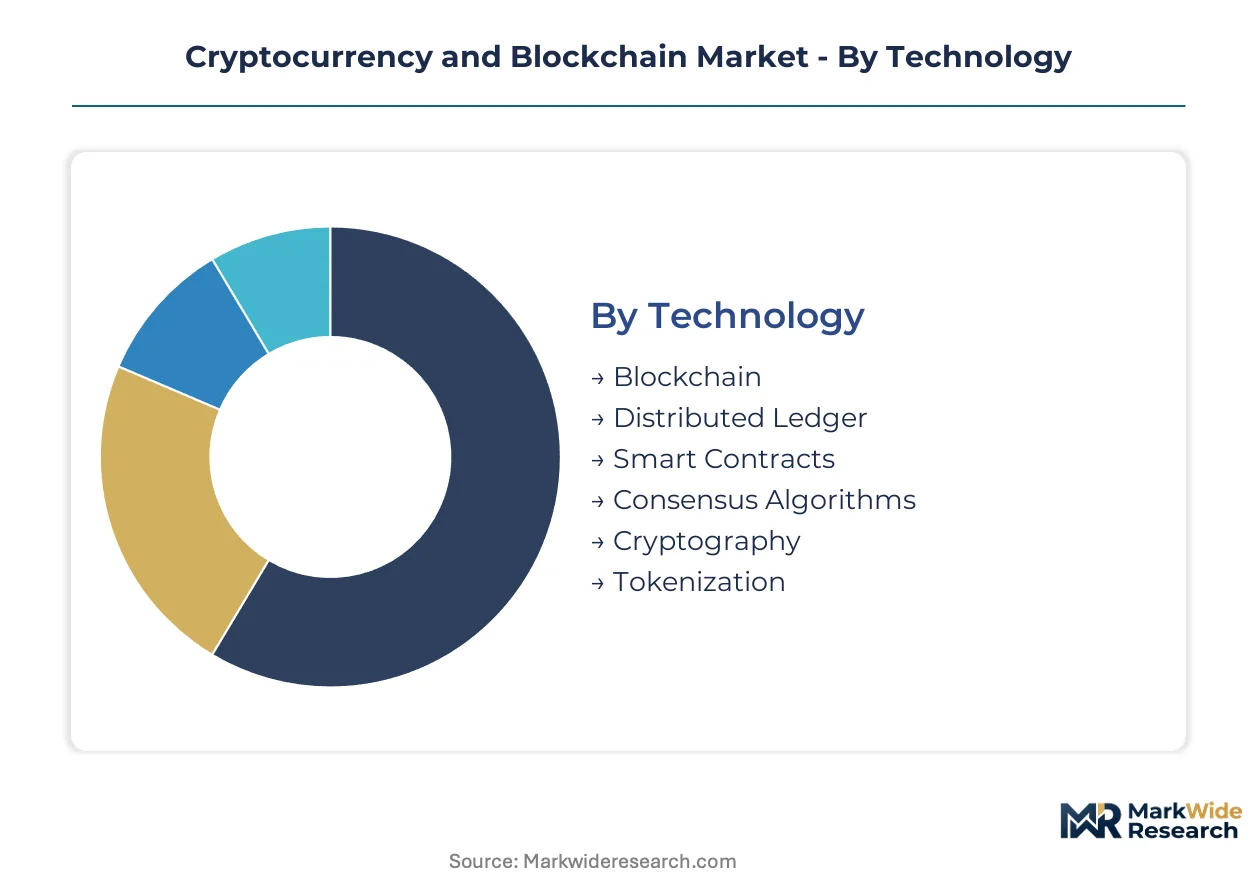
Cryptocurrency and blockchain architectures fragment across technology layers, use cases, infrastructure models, and buyer constituencies. Margin capture concentrates where regulatory compliance intersects with specialized infrastructure deployment.
Technology:
Margin pools sit heaviest in consensus infrastructure and programmable settlement layers where energy costs and developer scarcity erect barriers.
- Blockchain:Distributed ledger infrastructure maintains immutable transaction records through cryptographic chaining. Demand clusters in Swiss banking consortia and Singaporean wealth management platforms seeking compliant asset settlement rails.
- Smart Contracts:Self-executing programmable agreements automate conditional value transfer without intermediary enforcement. Institutional treasuries in Hong Kong are deploying these for yield-bearing on-chain instruments, compressing traditional custody timelines.
- Consensus Algorithms:Proof-of-stake validation mechanisms dominate new protocol launches.
- Cryptography:Zero-knowledge proof systems enable privacy-preserving verification.
- Tokenization:Real-world asset digitization creates captive demand from Liechtenstein private banks.
- Distributed Ledger:Permissioned variants serve supply chain consortia with audit requirements.
Blockchain holds installed capacity. Smart Contracts is rotating up the share rankings.
Application:
Revenue concentration follows capital deployment patterns, with institutional yield-seeking and cross-border settlement commanding premium pricing.
- Decentralized Finance:On-chain lending, derivatives, and liquidity protocols disintermediate traditional credit intermediation. Family offices in Singapore negotiate bespoke slashing insurance and MEV extraction terms for direct validator delegation.
- Payments:Peer-to-peer value transfer and remittance corridors reduce correspondent banking friction. Brazilian pension funds channel allocations into yield-bearing instruments through CVM-permitted fund-of-funds structures.
- Digital Identity:Self-sovereign credential systems enable compliant KYC compression.
- Supply Chain Management:Provenance tracking satisfies ESG audit requirements for commodities.
- Data Management:Immutable audit trails serve healthcare and legal document verification.
- Voting Systems:Transparent ballot recording pilots in municipal governance experiments.
Payments holds installed capacity. Decentralized Finance is climbing the fastest.
Deployment:
Operational cost structures diverge sharply between permissionless and permissioned configurations.
- Public:Open-access networks bear validator infrastructure costs and energy input volatility. These deployments dominate transaction volume and developer activity despite margin compression from fluctuating renewable energy certificate prices.
- Private:Enterprise-controlled ledgers capture banking consortia spending with predictable compliance overhead. Swiss and Liechtenstein institutions deploy these for real-world asset settlement with captive custody middleware demand.
- Consortium:Multi-party governed networks balance decentralization with regulatory auditability.
- Hybrid:Interoperable architectures bridge public settlement with private execution.
Public holds installed capacity. Private is rotating up the share rankings.
End User:
Procurement authority and compliance budgets vary dramatically across regulated financial entities, state actors, and industrial adopters.
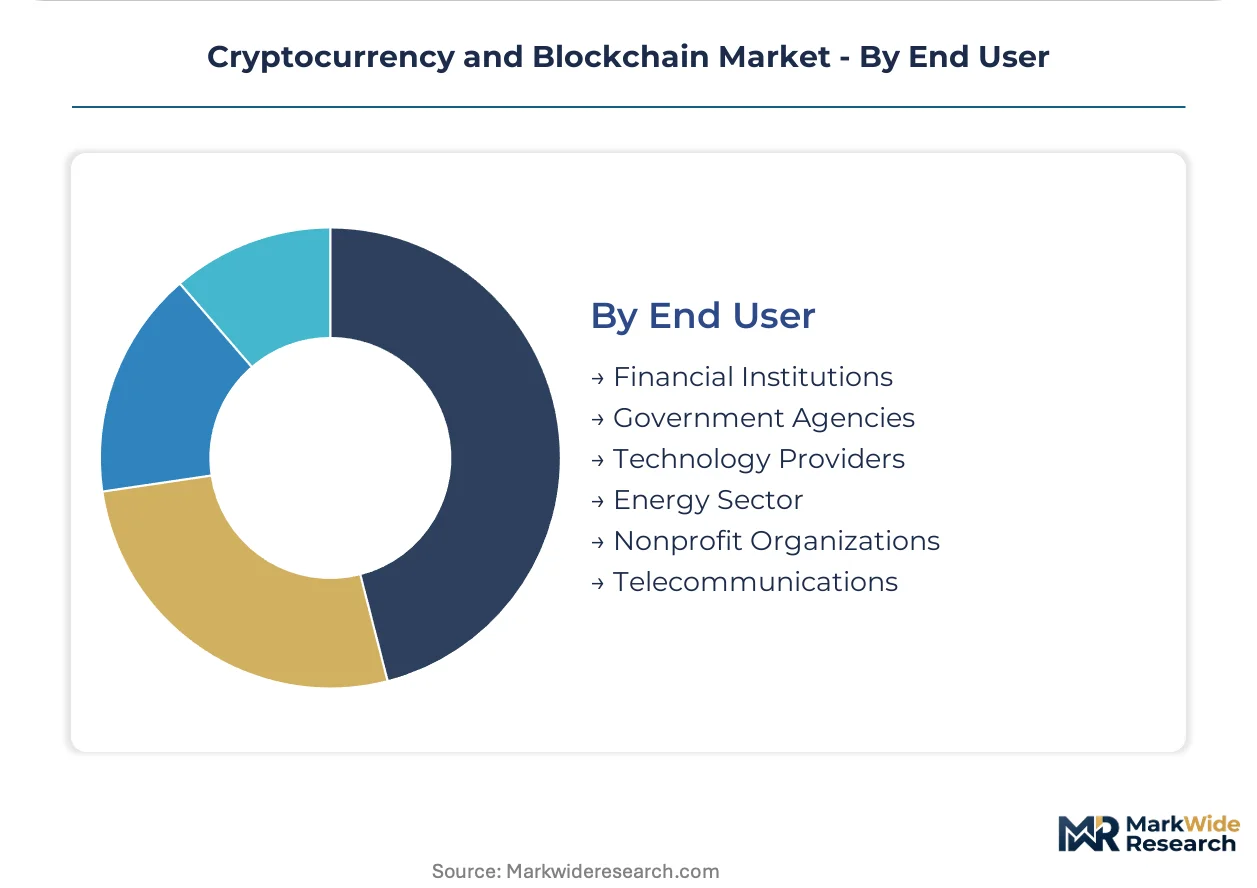
- Financial Institutions:Banks, asset managers, and exchanges invest in custody infrastructure and tokenization platforms. These entities navigate SEC-CFTC dual enforcement overlap and EU MiCA reserve attestation requirements when structuring cross-border offerings.
- Government Agencies:Central banks and regulators pilot central bank digital currency integration. India's pending CBDC rollout and G20 presidency momentum position the jurisdiction for remittance infrastructure buildout.
- Technology Providers:Infrastructure operators and protocol developers concentrate in Zurich, Singapore, and San Francisco talent clusters.
- Energy Sector:Mining operations and grid balancing services face hosting cost pressures in Texas and Kazakhstan.
- Telecommunications:Identity verification and micropayment rails explore subscriber-facing deployments.
- Nonprofit Organizations:Transparent fund disbursement and donor tracking drive limited pilots.
Financial Institutions holds installed capacity. Government Agencies is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore deploys cryptocurrency infrastructure primarily for institutional treasury management and cross-border settlement, diverging from retail-driven adoption patterns seen in other financial hubs. Regulatory clarity from the Monetary Authority of Singapore shapes custody and staking service deployment.
United States
Texas and Wyoming host energy-intensive mining clusters facing margin pressure from renewable certificate volatility. The SEC and CFTC maintain overlapping enforcement authority that fragments exchange registration requirements. Core Scientific anchors mining scale in Texas while custody providers navigate state-level licensing fragmentation.
Switzerland
Zurich private banks drive demand for tokenized real-world asset settlement and compliant custody middleware. FINMA guidance on digital asset segregation shapes cold-wallet architecture investments. The Crypto Valley cluster in Zug concentrates protocol development and smart contract audit capacity.
Singapore
Family offices and hedge funds rotate capital into on-chain staking instruments with bespoke slashing insurance terms. MAS licensing frameworks for digital payment token services compress compliance timelines for custody entrants. The Marina Bay financial district hosts Amber Group and other institutional infrastructure operators.
Germany
BaFin-registered crypto custodians absorb MiCA reserve attestation requirements for stablecoin offerings. Frankfurt banking consortia pilot private blockchain deployments for securities settlement. Berlin concentrates Rust and Solidity engineering talent for protocol development teams.
India
The Reserve Bank of India pilots central bank digital currency integration with G20 presidency momentum. Mumbai fintech clusters build remittance infrastructure targeting cross-border payment corridors. Pending regulatory clarity positions the jurisdiction for custody service expansion.
Cryptocurrency and Blockchain Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with vertical integration into proprietary trading infrastructure and energy-efficient mining operations separating the tiers. The upper tier captures institutional onboarding pipelines through multi-jurisdictional regulatory licenses, while specialists compete on validator node operations and staking service customization. Two strategic archetypes dominate: exchange-integrated platforms with custody and trading stacks, and infrastructure-native operators with direct energy and hardware control. Competitive moves concentrate on M&A for regulatory licenses and geographic expansion into pending clarity jurisdictions.
Within the exchange-integrated tier, Coinbase occupies a position exemplifying multi-jurisdictional license leverage for institutional pipelines. Amber Group anchors the Asia-Pacific specialist vector through Singapore-based staking and trading infrastructure. Core Scientific represents the energy-scale archetype, with Texas mining operations demonstrating hosting and power cost management positioning.
| Leading Market Players |
|---|
| Binance |
| Coinbase |
| DWF Labs |
| Cumberland |
| Amber Group |
| B2C2 |
| Keyrock |
| Kronos Research |
| Core Scientific |
| Others |
Pricing and Supply Chain Analysis
Eight-to-fourteen-week smart contract audit queues at accredited security firms compress mainnet deployment timelines and amplify pricing power for formal verification specialists serving high-value custody contracts. This lead-time bottleneck concentrates margin capture with Zurich, Singapore, and San Francisco talent clusters while forcing protocol teams outside these hubs to absorb inflated compensation costs or accept delayed revenue recognition.
Pricing Analysis
Long-term offtake contracts dominate institutional staking and custody arrangements, with Singaporean family offices and Hong Kong hedge funds negotiating bespoke slashing insurance and MEV extraction terms spanning multi-year horizons. Spot pricing prevails in retail exchange transactions and mining hosting services, where Texas and Kazakhstan energy input volatility compresses margins unpredictably. Price differentiation rests on jurisdictional licensing breadth and energy cost management capabilities, with MiCA-registered entities in Germany and France commanding premiums over unlicensed competitors. Pricing pressure stems from renewable energy certificate volatility in mining operations, squeezing hosting providers lacking captive power arrangements. Retail participants exhibit highest price sensitivity, while institutional treasuries prioritize compliance infrastructure and validator reliability over fee minimization.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes inflate hardware delivery costs for mining equipment and validator node infrastructure sourced from Chinese and Taiwanese manufacturing clusters. Geographic supply concentration centers on Switzerland for private banking custody middleware, Singapore for institutional staking infrastructure, and the United States for energy-scale mining operations. Raw material dependencies span specialized ASIC fabrication capacity, renewable energy certificate markets, and Rust/Solidity engineering talent pools. Supply chain risk manifests in single-source vulnerability for formal verification expertise, where accredited security firms maintain eight-to-fourteen-week audit queues. Distribution runs through direct institutional contracting for staking services, disintermediating integrated exchange platforms in favor of specialized infrastructure operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cryptocurrency and blockchain market represents high-growth infrastructure disruption, with EU MiCA implementation and zero-knowledge proof maturation constituting simultaneous regulatory and technological inflection points reshaping competitive boundaries.
For Market Incumbents: Compound regulatory license portfolios across MiCA jurisdictions, Singapore MAS frameworks, and US state-level regimes to defend institutional onboarding pipelines against emerging protocol-native competitors. Acquire specialized validator node operators in Hong Kong and Swiss banking consortia to capture disintermediated staking demand from family offices rotating capital away from integrated exchange relationships. Prioritize formal verification capacity expansion to collapse smart contract audit bottlenecks currently delaying mainnet deployments. For New Entrants and Emerging Players: Anchor in Brazilian pension fund infrastructure, where CVM regulatory guidance permitting crypto exposure in fund-of-funds structures creates unmet demand for yield-bearing on-chain instruments compliant with retirement asset allocation requirements. Target Indian custody and remittance buildout ahead of Reserve Bank of India central bank digital currency integration, leveraging G20 presidency momentum to establish regulatory relationships. Deploy zero-knowledge credential verification pilots with Swiss private banks as reference architecture for compliant privacy rails. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because jurisdictional clarity divergence between MiCA uniformity and US SEC-CFTC fragmentation creates acquisition opportunities for multi-license platforms capable of cross-border institutional onboarding. Prioritize targets with proprietary energy arrangements in Texas hosting clusters and established MAS licensing in Singapore. Monitor stablecoin reserve attestation compliance timelines as inflection indicator for MiCA-registered entity consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory License Acquisition | MiCA registration in Germany, France, and Netherlands compresses compliance overhead for cross-border stablecoin issuance. |
| Zero-Knowledge Infrastructure Deployment | zk-rollup architectures paired with institutional identity verification enable compliant privacy rails for Swiss private banking clients. |
| Energy Cost Management Expansion | Captive renewable power arrangements in Texas mining clusters defend margins against certificate price volatility. |
| Direct Validator Delegation Services | Non-custodial staking contracts with Hong Kong hedge funds capture fee compression from exchange disintermediation. |
| Formal Verification Capacity Buildout | In-house smart contract audit capabilities collapse eight-to-fourteen-week bottlenecks delaying high-value custody deployments. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, with blockchain protocol developers, institutional treasury managers, digital asset custody architects, and regulatory compliance officers providing operational perspective. Secondary validation drew from SEC enforcement actions, EU MiCA regulatory texts, Monetary Authority of Singapore licensing frameworks, and central bank digital currency pilot disclosures. Bottom-up protocol deployment metrics and top-down institutional capital flow estimates were triangulated to anchor segmentation assumptions.
Across the analysis window, the forecasting framework modeled technology layer adoption curves, deployment configuration splits between public and private architectures, application segment revenue concentration, and end-user procurement authority patterns. CAGRs were derived from institutional onboarding pipeline velocities, staking instrument capital rotation rates, and tokenization infrastructure deployment timelines. Energy input cost trajectories and developer talent supply constraints informed supply-side capacity assumptions.
Material uncertainties — regulatory enforcement intensity variations, stablecoin reserve requirement modifications, and consensus mechanism migration timelines — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding jurisdictional clarity progression and institutional risk appetite normalization. Recalibration cycles align with material shifts in MiCA implementation velocity and central bank digital currency integration milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Assets and Cryptocurrency Finance
Blockchain Financial Network Market
Digital Assets and Cryptocurrency Finance
Global Non-Fungible Tokens Market
Digital Assets and Cryptocurrency Finance
Global Blockchain in Supply Chain Finance Market
Digital Assets and Cryptocurrency Finance
Global Cryptocurrency Custody Software Market
Digital Assets and Cryptocurrency Finance
Bitcoin Exchange Market
Digital Assets and Cryptocurrency Finance
Global Smart Contracts Market
Digital Assets and Cryptocurrency Finance
Global Cryptocurrency Market
Digital Assets and Cryptocurrency Finance
Online Microtransaction Market
Digital Assets and Cryptocurrency Finance
United States Crypto ATM Market
Digital Assets and Cryptocurrency Finance
Crypto Trading Platform Market
Digital Assets and Cryptocurrency Finance
Digital Currency Wallet Market
Digital Assets and Cryptocurrency Finance
Smart Contracts Platforms Market
Digital Assets and Cryptocurrency Finance
Decentralized Finance Market
Digital Assets and Cryptocurrency Finance
Crypto Asset Management Platform Market
Digital Assets and Cryptocurrency Finance
Digital Asset Transaction Market
Digital Assets and Cryptocurrency Finance
Trading Data Platform Market