
 Crypto Trading Platform Market | 2026-2036
Crypto Trading Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Crypto Trading Platform Market Outlook
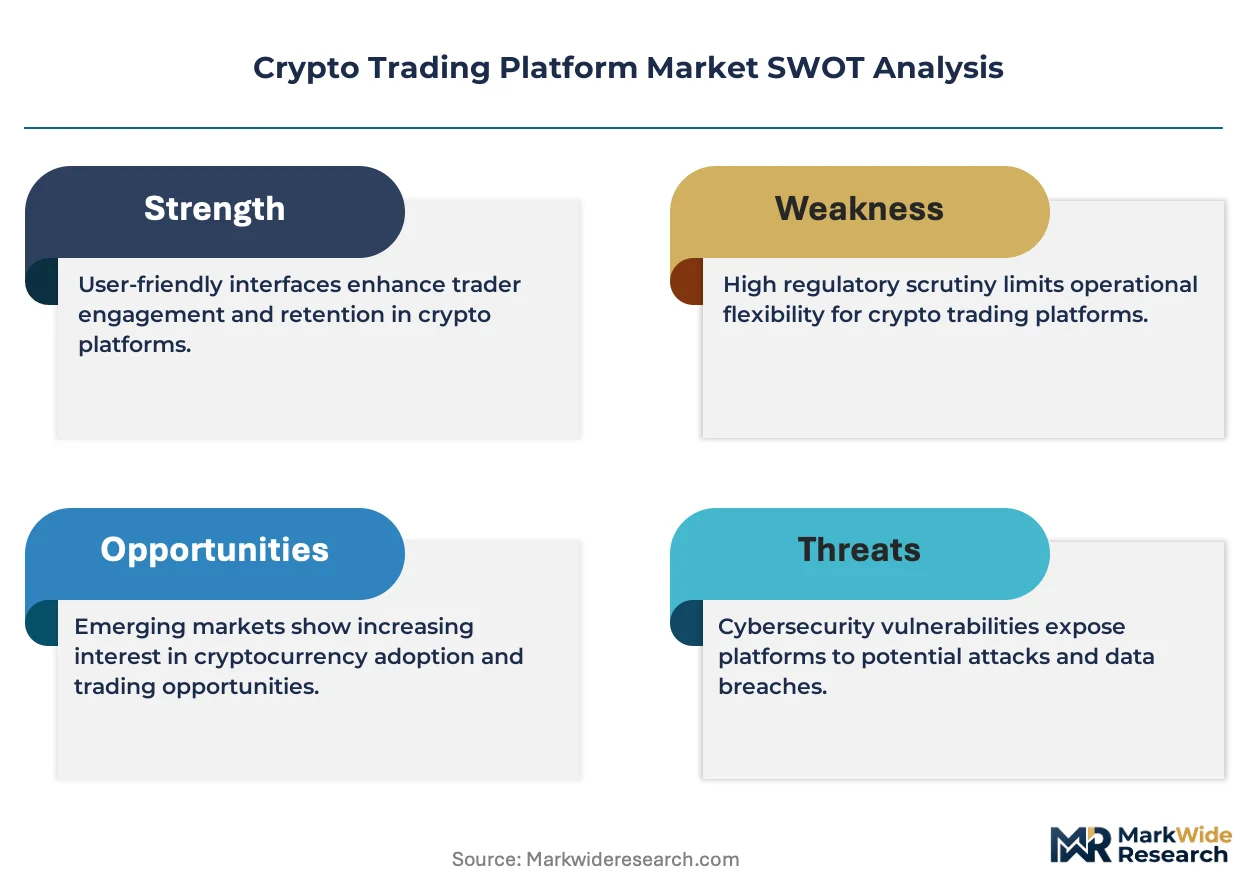
Asset-light SaaS infrastructure and white-label licensing is tilting competitive dynamics toward lean entrants that avoid proprietary custody costs. Coinbase sustains its position through deep regulatory relationships and US state-level licensing density. Kraken differentiates via advanced staking infrastructure and European banking integration. Binance operates the broadest geographic footprint, though its structure navigates fragmented national registration demands.
A crypto trading platform constitutes a digital marketplace infrastructure enabling order matching, price discovery, and settlement for tokenized assets, typically processing throughput exceeding 100,000 transactions per second on centralized architectures. The primary commercial purpose centers on extracting transaction fees and spread revenue while managing counterparty risk through hot-cold wallet segregation and multi-signature protocols. Mobile app deployment leads in retail user acquisition velocity, while API integration captures the fastest expansion as algorithmic funds demand co-located execution. Brokerage services anchor the largest fee pool, though exchange-native wallet solutions concentrate margin as self-custody regulations tighten.
SEC registration mandates under US federal securities law reshape product availability for American users, while MiCA licensing in Europe standardizes reserve requirements and consumer disclosure. The FCA in the UK imposes enhanced anti-money laundering protocols that filter platform eligibility. Stakeholders must monitor how jurisdictional arbitrage between Singapore's MAS framework and Dubai's VARA regime influences operational licensing strategy.
Market Dynamics
Asset-light SaaS infrastructure and white-label licensing is collapsing the capital barrier for new entrants, forcing established platforms to defend margin through regulatory density and custody specialization rather than scale alone.
Growth Catalysts
- MiCA Licensing Standardization:Europe's unified reserve requirements and consumer disclosure rules reduce compliance fragmentation for cross-border operators, accelerating platform consolidation.
- Institutional Custody Demand:Hedge funds and asset managers require segregated wallet infrastructure with insurance-backed guarantees, pulling specialized providers into high-fee service tiers.
- Singapore MAS Framework:The city-state's payment institution licensing creates jurisdictional clarity that attracts regional headquarters and operational capital.
Market Restraints
- SEC Registration Friction:US federal securities mandates force product delistings and state-by-state licensing, compressing available token pairs for American users.
- Hot Wallet Insurance Costs:Cyber liability premiums for custodial assets scale non-linearly with AUM, eroding profitability for retail-focused platforms.
- Stablecoin Reserve Requirements:MiCA-mandated 1:1 backing rules for euro-denominated tokens constrain yield-generating strategies and narrow spread capture.
Strategic Opportunities
- UAE VARA Licensing:Dubai's virtual asset regulatory authority offers accelerated approval timelines that attract talent and capital fleeing restrictive jurisdictions.
- API-First Infrastructure:Algorithmic funds and quant shops demand co-located execution and sub-millisecond latency, creating premium service tiers.
- Staking-as-a-Service:Proof-of-stake validation yields present recurring revenue streams distinct from volatile transaction fees.
Industry Challenges
- Multi-Jurisdiction Compliance Talent:Platforms require legal and engineering staff fluent in SEC, FCA, MAS, and VARA frameworks simultaneously, creating wage inflation.
- Legacy Banking Integration:Fiat on-ramp relationships depend on correspondent banking partnerships that terminate abruptly amid reputational risk concerns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crypto Trading Platform Market |
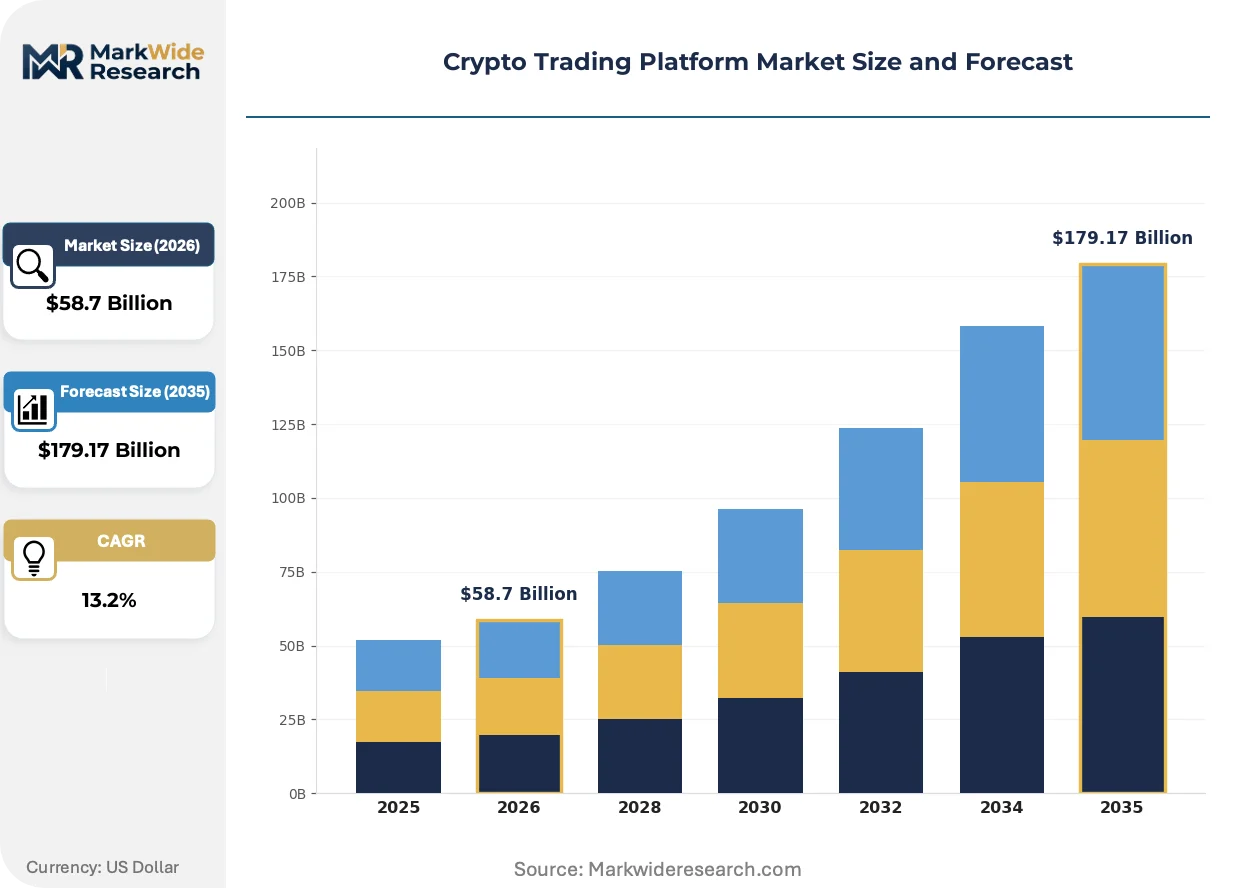
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $179.17 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Web-Based, Mobile App, Desktop Application, API Integration Service Type: Brokerage, Exchange, Wallet, Consulting User Type: Retail Investors, Institutional Traders, High-Frequency Traders, Beginners Feature: Margin Trading, Automated Trading, Security Protocols, Analytics Tools |
| Companies Covered | Binance, Coinbase, Kraken, Bybit, OKX, Huobi Global, Kucoin, Gemini, Crypto.com, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crypto Trading Platform Market Strategic Shifts
Execution infrastructure and custody architecture are converging in ways that compress fee structures while raising the technical bar for competitive participation.
Modular matching engines built on Rust and C++ is collapsing latency differentials between tier-one and tier-two platforms. Quantitative funds now demand sub-100 microsecond round-trip times, forcing mid-market operators to license third-party infrastructure rather than build proprietary stacks. The technology is collapsing the historical advantage of vertically integrated incumbents.
MiCA's travel rule implementation and reserve disclosure mandates reshape product design across European operations. Issuers must publish white papers with binding legal commitments, while exchanges face enhanced due diligence for self-hosted wallet transfers. DeFi-integrated platforms are responding by geofencing certain yield products or creating separate legal entities.
Retail acquisition is shifting from performance marketing toward embedded finance partnerships. Neobanks and fintech apps white-label exchange infrastructure, capturing users who never directly interface with standalone platforms. This channel rotation is most visible in Latin America and Southeast Asia where banking penetration lags but mobile money adoption is dense.
Crypto Trading Platform Market Segmentation
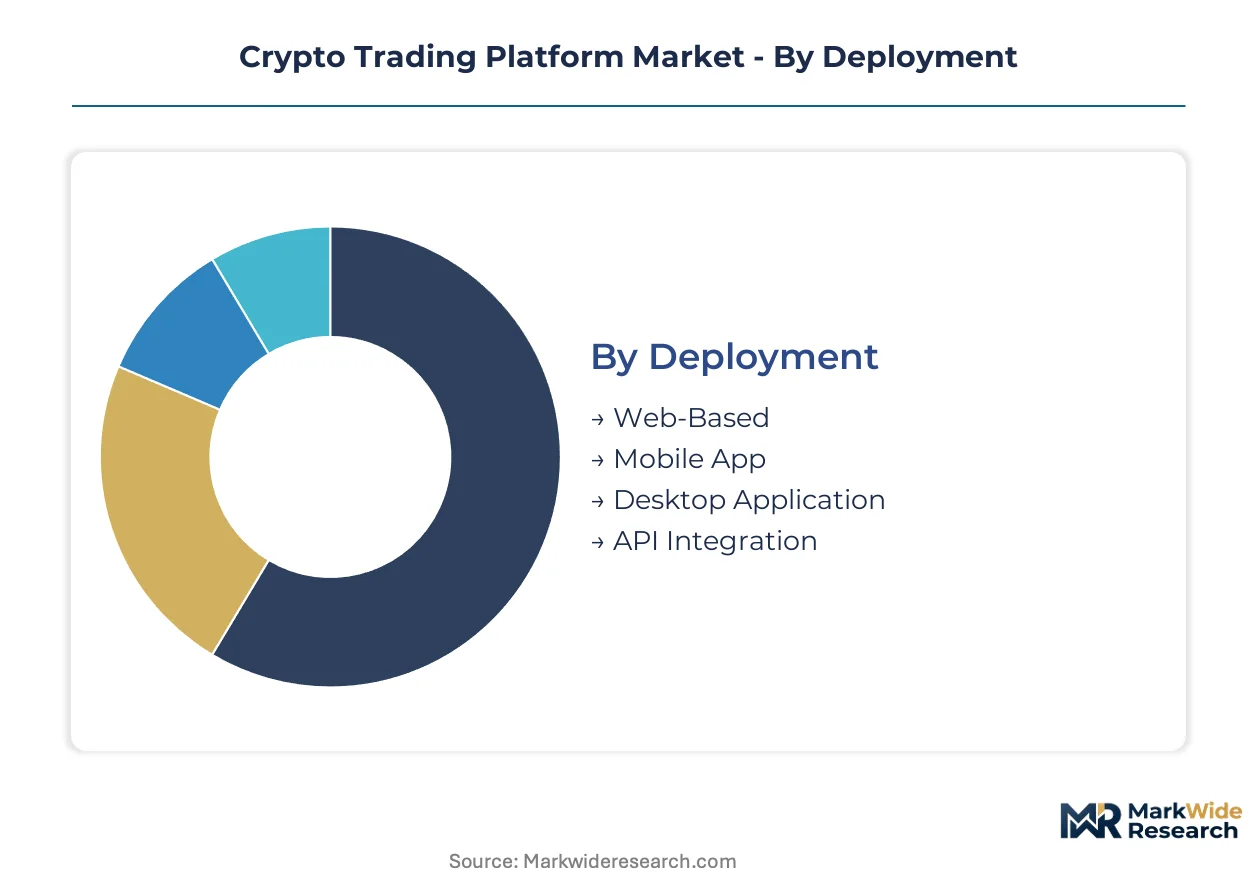
Segmentation in crypto trading platforms reveals how infrastructure investments and user acquisition strategies diverge across technical architectures and service models. Deployment mode determines latency requirements and custody risk profiles, while user type dictates compliance spend and fee structure design.
Deployment:
Mobile app deployments turn over fastest on user acquisition metrics, while desktop applications retain longest on session duration and trade size.
- Web-Based:Browser-accessible interfaces with responsive design architectures serve retail users across emerging markets where app store restrictions limit distribution. Demand concentrates in Southeast Asian corridors where mobile data costs push users toward lightweight browser solutions rather than native downloads.
- Mobile App:Native iOS and Android applications with biometric authentication and push notification systems dominate retail onboarding velocity. Singapore and the UAE drive premium feature adoption as licensed operators compete on execution speed for mobile-first demographics.
- Desktop Application:Electron-based or native clients with advanced charting and multi-monitor support serve professional traders requiring complex order types. UK-based proprietary trading firms anchor demand for co-located desktop terminals with direct market access.
- API Integration:REST and WebSocket endpoints with FIX protocol compatibility enable algorithmic execution and systematic fund integration. Quantitative shops in Chicago and London represent the fastest-expanding customer tier as latency thresholds compress below 100 microseconds.
Web-based platforms dominate installed base across unbanked populations. API integration is where expansion concentrates as institutional capital flows accelerate.
Service Type:
Margin structures and regulatory capital requirements create sharp cost tier differentiation between execution-only and full-service models.
- Brokerage:Agency execution with best-execution obligations and conflict-of-interest disclosures matches retail orders against external liquidity pools. MiCA-licensed operators in Germany and France face heightened conduct standards that compress spreads but extend customer lifetime value.
- Exchange:Centralized order books with proprietary matching engines and custody infrastructure extract fees from both maker and taker flows. Dubai VARA-registered venues capture regional volume as Middle Eastern capital seeks regulated onshore alternatives.
- Wallet:Self-custody and custodial storage solutions with multi-signature and hardware security module protection address post-FTX demand for asset segregation. Singapore MAS frameworks mandate insurance-backed guarantees that elevate pricing for retail-focused providers.
- Consulting:Regulatory navigation, tax optimization, and institutional onboarding advisory services attach to high-net-worth segments. Demand clusters in Switzerland and Liechtenstein where private banking relationships intersect with crypto allocation mandates.
Exchange services anchor fee pool concentration. Wallet solutions are gaining share fastest as self-custody regulations tighten across European and Asian jurisdictions.
User Type:
Customer lifetime value and support cost intensity separate high-frequency automation from educational hand-holding requirements.
- Retail Investors:Individual account holders with sub-institutional position sizes and educational content dependencies drive mobile app adoption curves. Latin American markets exhibit steepest expansion trajectories as currency instability pushes savings into dollar-denominated stablecoin instruments.
- Institutional Traders:Hedge funds, family offices, and corporate treasuries with segregated wallet demands and service-level agreements command premium pricing tiers. US SEC registration requirements filter platform eligibility, compressing available providers for American allocators.
- High-Frequency Traders:Quantitative firms with co-location requirements and sub-millisecond latency sensitivity license dedicated infrastructure rather than shared retail pools. London and Singapore datacenter proximity determines venue selection for Asia-Europe arbitrage strategies.
- Beginners:First-time crypto purchasers requiring guided onboarding, simplified interfaces, and educational guardrails exhibit highest churn but largest addressable population. Neobank partnerships in Brazil and Nigeria embed exchange functionality without standalone platform registration.
Retail investors dominate active account counts. Institutional traders are climbing the fastest as pension fund mandates and corporate treasury policies formalize crypto allocation frameworks.
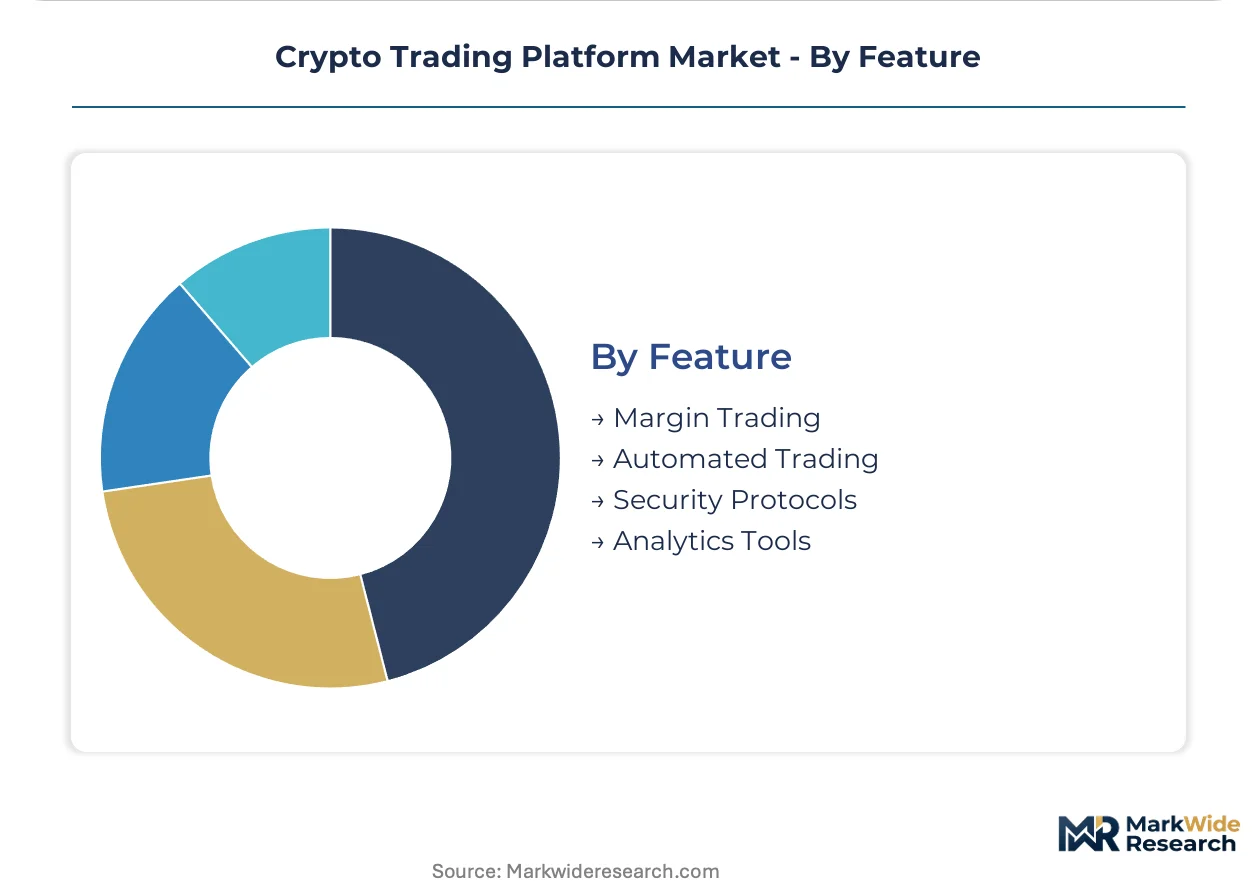
Feature:
Regulatory permissiveness and technical sophistication create maturity gradients across leveraged and automated product categories.
- Margin Trading:Collateralized leverage with liquidation engines and funding rate mechanisms amplifies position exposure for sophisticated users. FCA restrictions in the UK and CFTC scrutiny in the US limit retail availability, concentrating demand in Singapore and UAE jurisdictions.
- Automated Trading:Bot infrastructure, copy-trading marketplaces, and strategy backtesting tools reduce manual execution overhead for systematic participants. Korean and Japanese retail markets show dense adoption of social trading features integrated with exchange-native automation.
- Security Protocols:Multi-factor authentication, withdrawal whitelisting, and cold storage attestation address counterparty risk concerns post-platform failures. Enterprise demand from regulated funds drives insurance-backed custody certification as a competitive differentiator.
- Analytics Tools:On-chain data visualization, portfolio attribution, and tax reporting automation reduce operational friction for self-directed investors. German and Austrian users exhibit highest willingness-to-pay for integrated tax reporting given local compliance complexity.
Security protocols dominate R&D allocation across established platforms. Automated trading features are expanding most quickly as retail sophistication matures and API accessibility improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MiCA's unified reserve requirements and consumer disclosure rules are accelerating platform consolidation across Europe, while Singapore's MAS framework and Dubai's VARA regime create jurisdictional clarity that attracts operational capital fleeing restrictive environments.
United States
Hedge funds and asset managers in New York and Chicago drive institutional custody demand for segregated wallet infrastructure with insurance-backed guarantees. SEC registration mandates under federal securities law force product delistings and state-by-state licensing, compressing available token pairs for American users. Miami and Austin emerge as operational clusters where platforms establish regional headquarters to access talent pools outside traditional financial centers.
Singapore
Payment institution licensing from the Monetary Authority of Singapore creates jurisdictional clarity that attracts regional headquarters and operational capital from across Southeast Asia. The MAS framework mandates insurance-backed guarantees for retail-focused custody providers, elevating pricing but extending customer lifetime value. Raffles Place and Marina Bay financial districts concentrate licensed exchange operations serving mobile-first demographics across Indonesia, Malaysia, and Thailand.
Germany
MiCA-licensed operators in Frankfurt and Berlin face heightened conduct standards that compress spreads but extend customer lifetime value through regulatory trust. The Federal Financial Supervisory Authority enforces enhanced anti-money laundering protocols that filter platform eligibility, creating barriers for unregulated entrants. BaFin's implementation of travel rule requirements reshapes product design, forcing exchanges to enhance due diligence for self-hosted wallet transfers.
United Arab Emirates
Dubai's Virtual Asset Regulatory Authority offers accelerated approval timelines that attract talent and capital fleeing restrictive jurisdictions in Europe and North America. VARA-registered venues capture regional volume as Middle Eastern capital seeks regulated onshore alternatives to offshore operators. Dubai International Financial Centre clusters licensed custody providers serving family offices and sovereign wealth funds across Saudi Arabia, Qatar, and Kuwait.
United Kingdom
Proprietary trading firms in London anchor demand for co-located desktop terminals with direct market access and sub-millisecond execution latency. The Financial Conduct Authority imposes enhanced anti-money laundering protocols that filter platform eligibility, creating compliance cost inflation for cross-border operators. Canary Wharf and the City of London concentrate API infrastructure serving quantitative funds executing Asia-Europe arbitrage strategies.
Crypto Trading Platform Market Competitive Environment
Channel-controlling players compete with product-specialist players across a market structure that fragments between vertically integrated incumbents and lean SaaS entrants. Asset-light white-label licensing collapses capital barriers for new entrants, forcing established platforms to defend margin through regulatory density and custody specialization rather than scale alone. Three archetypes dominate: vertically integrated exchanges with proprietary matching engines, custody-specialized providers serving institutional mandates, and API-first infrastructure vendors licensing modular execution stacks. Competitive moves concentrate on regulatory licensing density across multiple jurisdictions and strategic partnerships with neobanks for embedded finance distribution.
Within the vertically integrated tier, Binance and Coinbase exemplify contrasting geographic strategies, with the former operating the broadest footprint navigating fragmented national registration demands and the latter sustaining position through deep regulatory relationships and US state-level licensing density. Kraken occupies a position emphasizing advanced staking infrastructure and European banking integration, differentiating through service tier design rather than geographic breadth. These three entities anchor the competitive landscape as archetypes of scale-driven, regulation-driven, and specialization-driven positioning respectively.
| Leading Market Players |
|---|
| Binance |
| Coinbase |
| Kraken |
| Bybit |
| OKX |
| Huobi Global |
| Kucoin |
| Gemini |
| Crypto.com |
| Others |
Value Chain & Pricing Dynamics
Singapore-Jakarta undersea cable latency costs shape competitive positioning across Southeast Asian trading venues, concentrating pricing power with co-located infrastructure providers while compressing spreads for retail-accessible platforms dependent on distant server farms.
Pricing Analysis
Regulatory certification level creates the primary spread between MiCA-licensed European venues and offshore operators serving the same user base. Three-tier pricing structure across institutional co-location, retail brokerage, and white-label API licensing dominates revenue architecture. Pricing pressure stems from zero-commission retail entrants eroding transaction fee pools. Algorithmic funds exhibit lowest price sensitivity, while emerging market retail users drive hardest bargain on spread capture.
Supply Chain Analysis
Upstream cloud compute and custody hardware feeds from Taiwan semiconductor foundries, US-based HSM manufacturers, and Swiss vault infrastructure providers. Raw material dependencies center on specialized ASIC chips, FIPS-certified security modules, and cold storage metallurgy. Single-source vulnerability concentrates in TSMC's advanced node production for matching engine acceleration. Distribution runs through hyperscaler partnerships and direct datacenter leasing to licensed operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where cross-chain interoperability protocols are collapsing liquidity fragmentation, rewarding venues that embed multi-chain settlement into core infrastructure.
For Market Incumbents: Pre-empt SaaS-native entrants by deepening regulatory licensing density across VARA, MAS, and MiCA frameworks simultaneously. Anchor margin defense through captive custody infrastructure rather than outsourced wallet partnerships. Vertical integration into staking validation hardware secures yield-generating revenue streams distinct from volatile transaction fees. For New Entrants and Emerging Players: Establish a beachhead in white-label API infrastructure serving neobank embedded finance channels across Latin America and Southeast Asia. Target regulatory arbitrage opportunities between Dubai's accelerated VARA timelines and restrictive European onboarding. Lead with modular matching engine licensing to bypass proprietary stack development costs. For Investors and Strategic Acquirers: Custody-specialized providers with insurance-backed guarantees and MAS licensing anchor the most defensible acquisition profile for long-term viability. Monitor institutional wallet infrastructure mandates from pension funds and corporate treasuries as the critical signal for platform consolidation timing. Stress-test target valuations against MiCA compliance cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| MiCA Licensing Acceleration | Early approval in Germany or France captures cross-border European volume before competitors complete compliance buildout. |
| Staking Infrastructure Acquisition | Proof-of-stake validation yields provide recurring revenue insulated from transaction fee volatility. |
| Neobank Embedded Partnership | White-label distribution through Nubank or Grab Financial captures users without standalone platform registration friction. |
| Co-Location Datacenter Expansion | Sub-100 microsecond latency in Singapore or London secures quantitative fund order flow. |
| Insurance-Backed Custody Certification | Lloyd's of London coverage differentiates institutional offerings post-FTX counterparty risk aversion. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SEC registration filings, MAS licensing disclosures, MiCA regulatory texts, and hyperscaler infrastructure capex reports. Interviews with exchange compliance officers, custody infrastructure engineers, quantitative fund technology heads, and neobank partnership directors informed demand-side validation. Bottom-up transaction volume modeling triangulates against top-down addressable market sizing across deployment modes and service tiers.
Forecast inputs incorporate algorithmic trading volume elasticity, regulatory licensing timeline distributions, and staking yield compression dynamics across the projection horizon. Segmentation dimensions span deployment architecture, service type, user sophistication tier, and jurisdictional regulatory cluster. CAGRs derive from fitted growth curves against historical adoption patterns in comparable fintech infrastructure markets.
Stress conditions across SEC enforcement intensity, MiCA reserve requirement implementation, and stablecoin depegging scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against CME Group crypto derivatives open interest trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Assets and Cryptocurrency Finance
Crypto ATM Market
Digital Assets and Cryptocurrency Finance
Global Smart Contracts Market
Digital Assets and Cryptocurrency Finance
Bitcoin and Cryptocurrency Atms Market
Digital Assets and Cryptocurrency Finance
Crypto Asset Management Platform Market
Digital Assets and Cryptocurrency Finance
Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
US Cryptocurrency Payment Apps Market
Digital Assets and Cryptocurrency Finance
Digital Finance Market
Digital Assets and Cryptocurrency Finance
Global Bitcoin and Cryptocurrency Wallets Market
Digital Assets and Cryptocurrency Finance
Online Microtransaction Market
Digital Assets and Cryptocurrency Finance
Crypto Asset Management Market
Digital Assets and Cryptocurrency Finance
Decentralized Finance Market
Digital Assets and Cryptocurrency Finance
Global Hardware Wallets Market
Digital Assets and Cryptocurrency Finance
Digital Collectibles Platform Market
Digital Assets and Cryptocurrency Finance
Blockchain Finance Market
Digital Assets and Cryptocurrency Finance
GCC Digital Asset Management Market
Digital Assets and Cryptocurrency Finance
Bitcoin Exchange Market