
 Europe Digital Asset Management Market | 2026-2036
Europe Digital Asset Management Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Digital Asset Management Market Intelligence
Institutional sales channels for tokenized securities and digital collateral management are reconfiguring across European capital markets. Deutsche Bank leverages its custody infrastructure to anchor institutional client onboarding for regulated digital assets. Societe Generale competes through blockchain-native security issuance platforms that extend its traditional investment banking franchise. Flow Traders specializes in market-making liquidity provision, differentiating its position across regulated European trading venues.
Europe Digital Asset Management encompasses software platforms and institutional infrastructure for storing, organizing, retrieving, and distributing rich media files, cryptographic tokens, and brand assets through centralized metadata architectures with role-based access controls. These systems serve commercial purposes from marketing asset governance to regulatory-compliant token lifecycle management. Cloud-based deployments lead current adoption curves across the region, while workflow automation solutions capture expanding margin pools as enterprises integrate AI-driven tagging and approval pipelines. The SaaS delivery model within deployment categories is accelerating fastest among mid-market buyers seeking reduced infrastructure overhead.
GDPR mandates from European data protection authorities shape platform architecture requirements around consent tracking and cross-border data residency. The EU AI Act imposes additional conformity obligations on automated metadata generation and predictive asset tagging systems deployed at scale. EBA guidelines on crypto-asset custody and the EU Green Deal's digital reporting standards through CSRD further constrain vendor design choices. Stakeholders must monitor evolving MiCA implementation timelines and assess whether their current infrastructure can absorb successive waves of compliance-driven platform upgrades.
Market Dynamics
EU AI Act conformity obligations are forcing DAM vendors to re-architect automated metadata engines around auditable decision trails, while GDPR cross-border data residency rules fragment cloud deployment strategies across member states.
Growth Catalysts
- CSRD Digital Reporting Mandates:The EU Corporate Sustainability Reporting Directive requires granular ESG data traceability that DAM platforms with embedded metadata lineage now supply to asset-intensive enterprises.
- France:Broadcast media groups in Paris and Lyon are consolidating creative production workflows onto unified asset repositories to compress campaign-to-air timelines for streaming and linear channels.
- AI-Driven Tagging Pipelines:Machine learning classification engines trained on brand-specific taxonomies are reducing manual metadata entry burdens by orders of magnitude for high-volume content operations.
Market Restraints
- GDPR Consent Architecture Costs:Building granular consent tracking into asset metadata frameworks adds substantial development overhead that squeezes vendor margins on mid-market SaaS tiers.
- Hyperscaler Concentration:Cloud infrastructure for European DAM deployments concentrates among three US-based providers, creating geopolitical exposure to extraterritorial data access statutes.
- Interoperability Limitations:Proprietary metadata schemas from incumbent vendors lock creative assets into walled gardens that resist migration to competing platforms.
Strategic Opportunities
- Poland:Enterprise DAM penetration remains below Western European benchmarks, leaving white space for workflow automation vendors targeting manufacturing and retail verticals in Warsaw and Krakow industrial corridors.
- EU Green Deal Alignment:Digital product passport requirements under the Circular Economy Action Plan create demand for asset lifecycle tracking that DAM systems can extend into sustainability documentation.
- Blockchain-DAM Convergence:Immutable provenance logging for high-value creative assets combines distributed ledger verification with traditional repository functions for luxury goods and fine art markets.
Industry Challenges
- AI Ethics Specialist Scarcity:Vendors struggle to hire personnel capable of auditing automated tagging systems for bias and ensuring EU AI Act conformity across multilingual training datasets.
- Legacy CMS Integration Friction:Enterprises with entrenched content management systems face protracted API mapping exercises to synchronize DAM metadata with decades-old database architectures.
- Certification Timeline Compression:MiCA implementation deadlines for crypto-asset custody functions pressure DAM providers to accelerate security audits without destabilizing existing release cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Digital Asset Management Market |
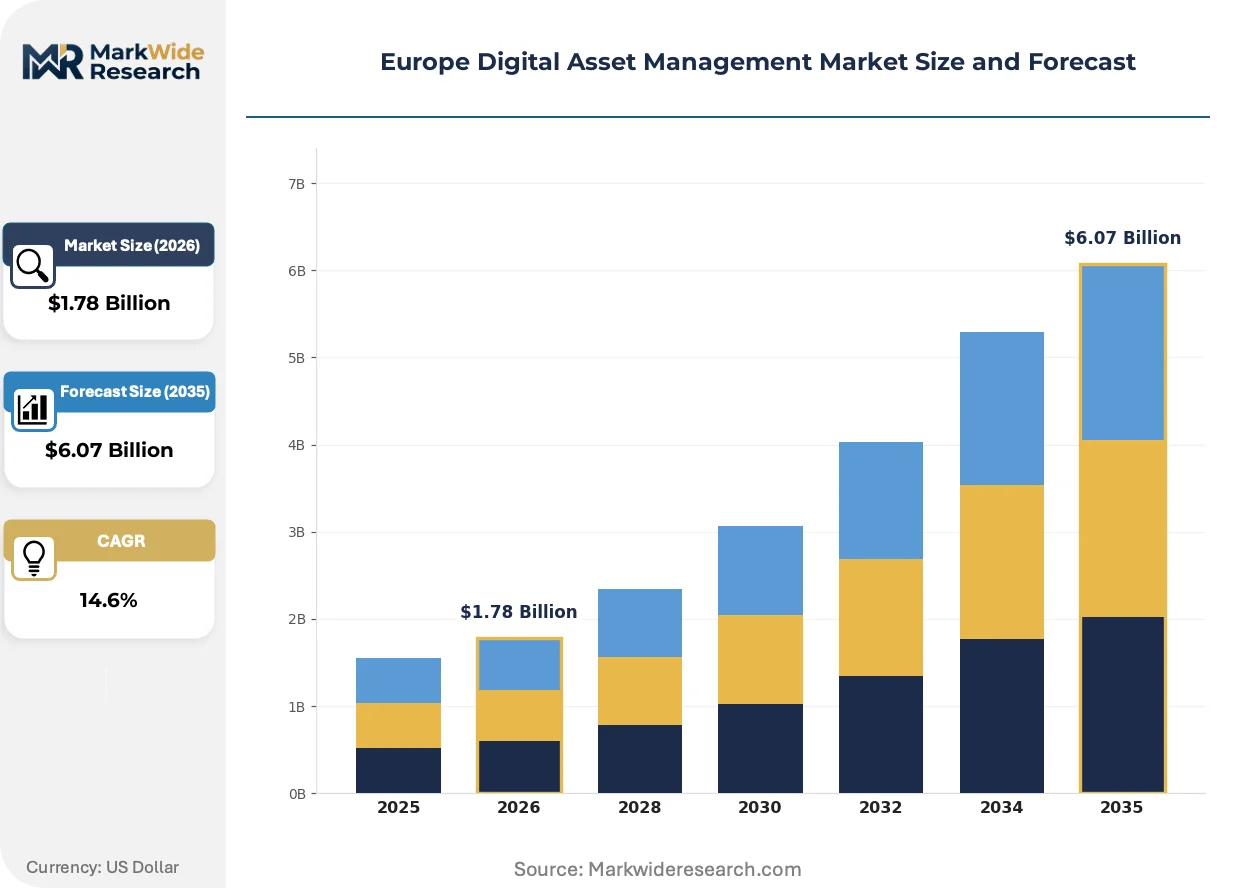
| Market Size in 2026 | $1.78 Billion |
| Market Size in 2035 | $6.07 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: Media & Entertainment, Retail, Healthcare, Education Solution: Content Creation, Asset Management, Workflow Automation, Analytics Application: Brand Management, Digital Marketing, E-Commerce, Social Media |
| Companies Covered | Fidelity Digital Assets, Galaxy Digital, Deutsche Bank, Euroclear, Deribit, Societe Generale, Flow Traders, Clearstream, DWS Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Digital Asset Management Market Strategic Shifts & Innovations
Workflow virtualization is collapsing the boundary between creative production and asset distribution, compressing approval cycles while fragmenting vendor competitive moats around integration depth rather than storage scale.
Edge computing nodes deployed at creative agency premises are virtualizing rendering and transcoding workloads that previously centralized in hyperscale facilities. Post-production houses in London and Amsterdam are adopting these distributed architectures to reduce latency on 4K and 8K video pipelines. The technology is virtualizing capital expenditure patterns, shifting spend from perpetual infrastructure toward consumption-based edge service contracts.
The EU AI Act's risk classification framework for automated decision systems imposes documentation burdens on DAM platforms using predictive metadata generation. Vendors must now maintain technical files proving conformity for high-risk deployments in financial services and broadcast media. German and Dutch regulators are interpreting these obligations most stringently, forcing earlier compliance investments than Mediterranean member states.
Subscription fatigue among mid-market creative teams is fragmenting procurement patterns away from bundled enterprise suites toward modular best-of-breed stacks. Buyers in Scandinavia and the Benelux are unbundling DAM from adjacent marketing operations platforms, selecting specialized vendors for taxonomy management and rights clearance. This pattern concentrates most acutely in Denmark's design-intensive agency sector, where tool-switching costs have fallen below retraining thresholds.
Europe Digital Asset Management Market Segmentation
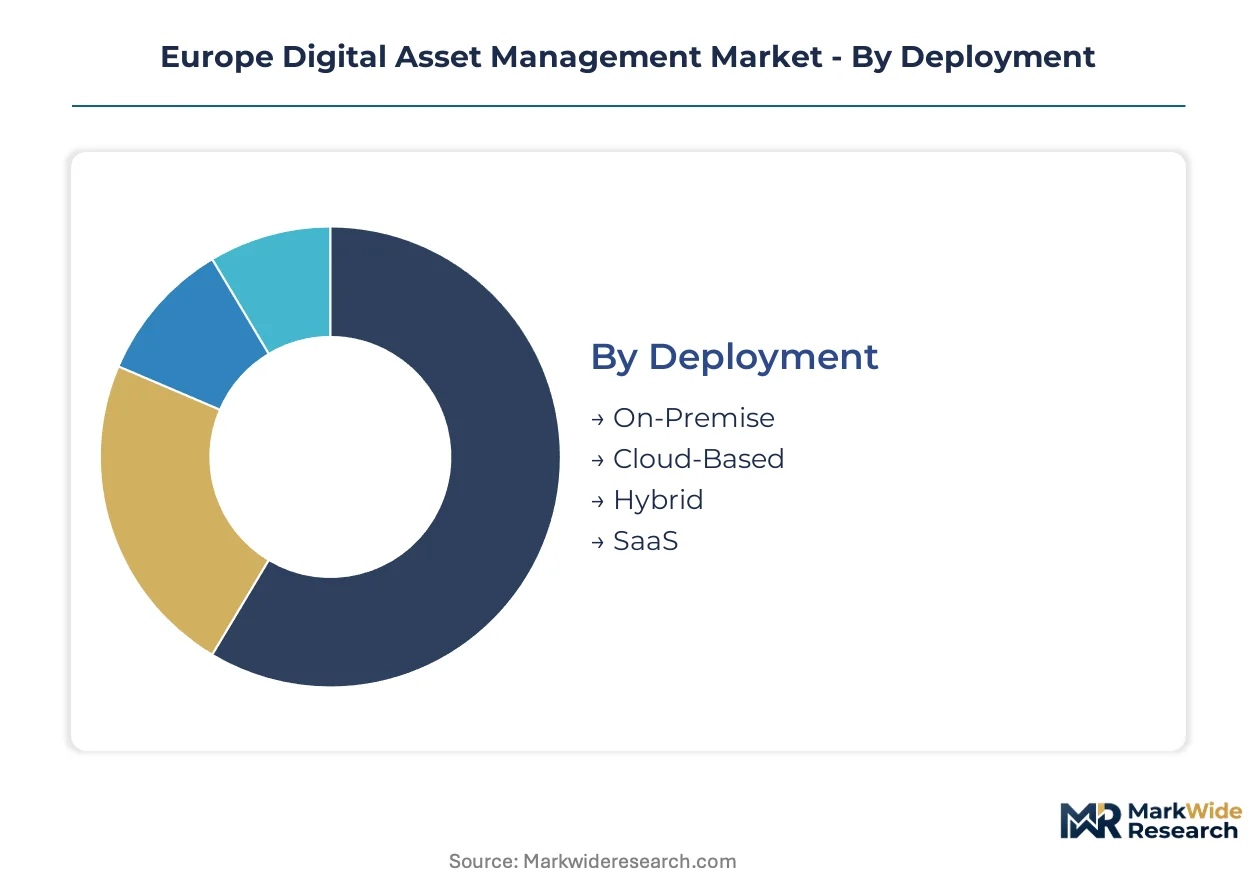
Segmentation in the Europe Digital Asset Management Market reveals how deployment architectures, end-user verticals, and solution capabilities fragment procurement priorities across the region. Buyers optimize for GDPR data residency, AI Act conformity, and workflow integration depth rather than storage scale alone.
Deployment:
Mature cloud delivery dominates mid-market adoption while hybrid architectures gain traction among institutions with legacy infrastructure investments.
- On-Premise:Dedicated hardware installations within enterprise data centers provide direct control over data residency. German financial institutions and French broadcasters favor these deployments to satisfy national regulator interpretations of GDPR cross-border transfer restrictions.
- Cloud-Based:Multi-tenant infrastructure delivered over public networks reduces capital expenditure for creative agencies. United Kingdom media groups in London and Manchester are consolidating dispersed asset repositories onto unified cloud platforms to compress campaign production timelines.
- Hybrid:Split architectures keep sensitive metadata on-premises while pushing distribution workloads to edge nodes. Dutch post-production houses deploy these configurations to balance latency requirements with client confidentiality obligations.
- SaaS:Subscription software layers abstract infrastructure management entirely. Scandinavian retail chains adopt these tiers to accelerate omnichannel asset rollout without dedicated IT staffing.
Cloud-Based deployments retain volume leadership across the region; SaaS represents the steepest expansion trajectory as mid-market buyers prioritize operational flexibility.
End User:
Application intensity varies sharply by sector, with media operations demanding real-time collaboration tools while healthcare prioritizes audit trails.
- Media & Entertainment:Broadcasters and streaming platforms manage petabyte-scale video libraries with frame-accurate retrieval requirements. Paris-based production groups invest heavily in AI-driven transcription and automated subtitling pipelines integrated with asset repositories.
- Retail:Omnichannel merchants synchronize product imagery across e-commerce, marketplace, and physical display channels. German fashion retailers leverage DAM metadata to automate variant generation for size and color permutations.
- Healthcare:Hospital networks and pharmaceutical marketers govern clinical imagery and promotional content under strict consent frameworks. United Kingdom NHS trusts implement these systems to track patient authorization across diagnostic photography usage.
- Education:Universities and research libraries curate digital collections for remote access. Spanish and Italian academic consortia deploy open-source DAM layers to minimize licensing expenditure on public-sector budgets.
Media & Entertainment commands the deepest per-seat investment; Retail is climbing fastest as digital commerce penetration accelerates across Southern and Eastern Europe.
Solution:
Capability bundling determines vendor competitive positioning, with workflow automation capturing expanding margin pools.
- Content Creation:Native editing tools and template libraries embedded within asset repositories. Benelux design agencies favor these integrated suites to reduce application-switching friction during campaign development.
- Asset Management:Core repository functions encompassing ingestion, storage, metadata governance, and retrieval. These capabilities form the baseline procurement tier across all European verticals.
- Workflow Automation:Rules-based routing and approval pipelines that compress creative production cycles. Financial services marketers in Frankfurt and Dublin adopt these modules to accelerate compliance review of promotional materials.
- Analytics:Usage dashboards and performance metrics tracking asset utilization and audience engagement. These tools gain traction among data-mature organizations seeking to optimize content investment returns.
Asset Management remains the foundational revenue layer; Workflow Automation is gaining share fastest as enterprises prioritize operational efficiency over storage expansion.
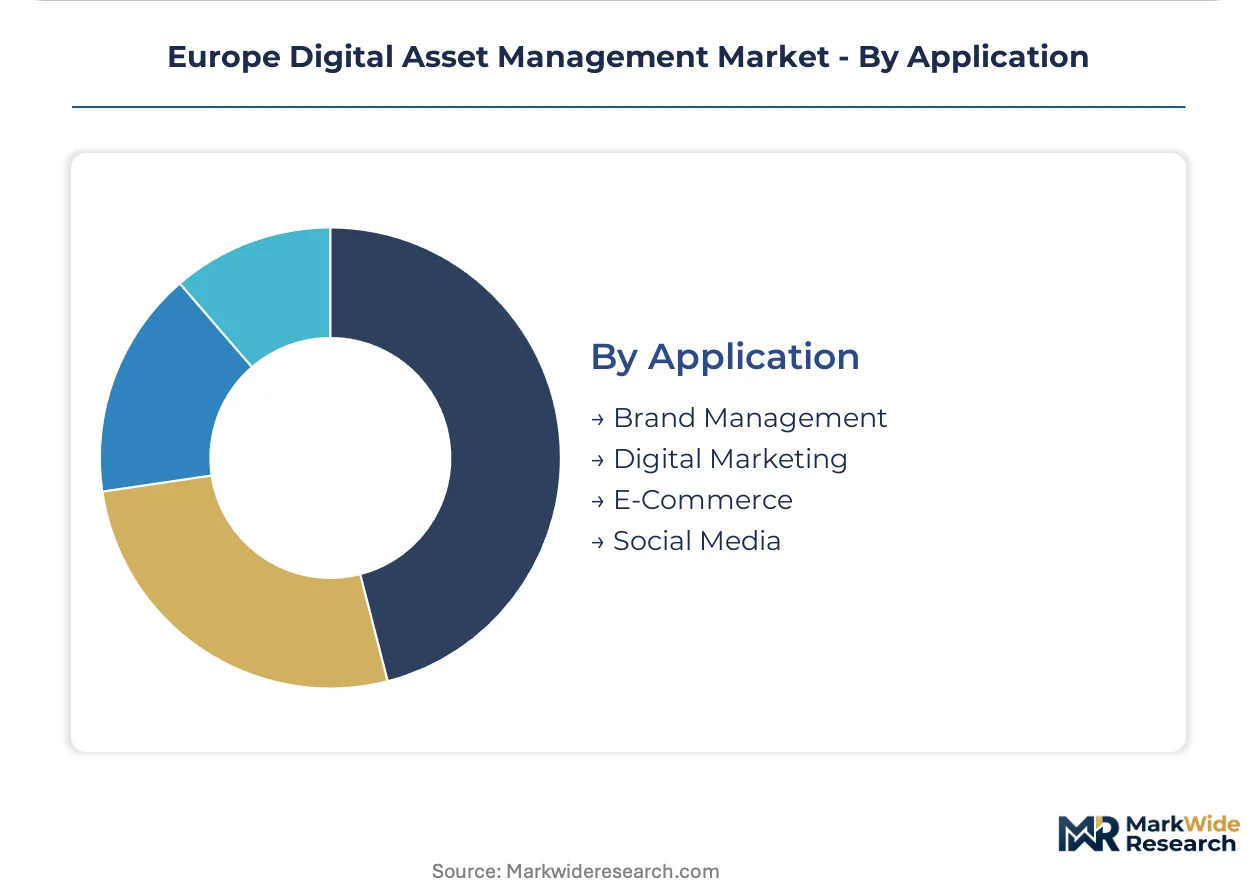
Application:
Use-case specialization drives vendor selection, with brand governance and digital marketing commanding distinct procurement committees.
- Brand Management:Centralized control over logo usage, typography, and visual identity standards. Luxury goods houses in Milan and Geneva deploy these configurations to enforce consistency across franchise and licensee networks.
- Digital Marketing:Campaign asset orchestration across programmatic, display, and email channels. United Kingdom and Netherlands performance marketing teams prioritize these applications for dynamic creative optimization.
- E-Commerce:Product content syndication to marketplace and direct-to-consumer platforms. Polish and Czech retailers expanding into cross-border sales invest here to automate localization workflows.
- Social Media:Format adaptation and publishing integration for platform-native content. These applications concentrate among influencer marketing agencies and direct-to-consumer brands with high posting velocity.
Digital Marketing captures the broadest deployment base; E-Commerce is expanding most quickly as Central European retail digitalization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in London and Frankfurt, where financial services institutions pay premiums for MiCA-compliant custody infrastructure, while Southern European buyers negotiate harder on SaaS tiers amid tighter IT budgets.
United Kingdom
Financial services firms in the City of London and broadcasters in Manchester drive enterprise DAM deployments for regulatory documentation and streaming asset pipelines. FCA guidelines on operational resilience push banks toward auditable metadata frameworks. The Manchester MediaCityUK cluster houses post-production groups consolidating creative workflows onto unified cloud repositories.
Germany
Automotive marketing teams and industrial manufacturers in Stuttgart and Munich demand workflow automation for product imagery localization. KBA interpretations of GDPR cross-border rules favor hybrid deployments with on-premise metadata storage. The Frankfurt financial district anchors institutional token custody DAM implementations under EBA crypto-asset guidelines.
France
Luxury goods houses in Paris and broadcast groups in Lyon invest in brand governance DAM for franchise network consistency and streaming content acceleration. CNIL enforcement on consent tracking shapes vendor selection for customer-facing asset systems. The Lyon audiovisual cluster compresses campaign-to-air timelines through AI-driven transcription pipelines.
Netherlands
Post-production houses in Amsterdam and Rotterdam adopt edge-computing DAM nodes to reduce latency on 4K video pipelines. Dutch DPA stringent GDPR interpretations force earlier compliance investments than Mediterranean regulators. The Amsterdam Zuidas financial district experiments with blockchain-DAM convergence for digital art provenance.
Poland
Retail chains in Warsaw and Krakow industrial corridors expand omnichannel asset management as e-commerce penetration accelerates. Enterprise DAM penetration remains below Western European benchmarks, creating white space for workflow automation vendors. The Krakow technology corridor attracts shared service centers seeking reduced infrastructure overhead through SaaS DAM tiers.
Europe Digital Asset Management Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying taxonomy engines and consent-tracking modules. The vendor base stratifies across three tiers: hyperscale cloud providers delivering infrastructure, European banks extending custody franchises into software, and pure-play DAM vendors competing on workflow depth. Strategic archetypes include regulated financial incumbents leveraging trust advantages, fintech specialists optimizing for crypto-asset lifecycle management, and cloud-native entrants undercutting on implementation speed. Competitive moves concentrate on MiCA certification acceleration and API ecosystem expansion to reduce client switching costs.
Within the regulated incumbent tier, Deutsche Bank and Societe Generale exemplify institutions repurposing custody infrastructure for digital asset software services. Flow Traders occupies a position among liquidity-focused specialists bridging traditional market-making with tokenized instrument support. These entities represent contrasting archetypes: universal banks extending franchise reach versus trading specialists deepening functional concentration in high-velocity execution environments.
| Leading Market Players |
|---|
| Fidelity Digital Assets |
| Galaxy Digital |
| Deutsche Bank |
| Euroclear |
| Deribit |
| Societe Generale |
| Flow Traders |
| Clearstream |
| DWS Group |
| Others |
Cost & Logistics Intelligence
Frankfurt's financial district anchors the highest-value DAM deployments, where MiCA-compliant custody infrastructure commands substantial premiums over standard SaaS tiers. German automotive marketing clusters in Stuttgart and Munich drive mid-market volume, while Polish retail corridors absorb entry-level pricing as e-commerce penetration accelerates.
Pricing Analysis
Configured-to-order deployments for regulated financial institutions carry 40-60% premiums above standard cloud tiers. Subscription-SaaS models dominate, with price differentiation resting on GDPR data residency certification and AI Act conformity documentation. Cost compression in mid-market tiers intensifies as Scandinavian buyers unbundle enterprise suites. Healthcare networks in the United Kingdom exhibit lowest price sensitivity due to NHS procurement frameworks, while Polish retail chains negotiate hardest on per-seat costs.
Supply Chain Analysis
Upstream cloud infrastructure feeds from hyperscale facilities concentrated in Ireland, Germany, and the Netherlands. Compute hardware draws from Taiwan and South Korea, while specialized AI accelerators source from United States vendors. Single-source vulnerability concentrates around three US-based hyperscalers, exposing European deployments to extraterritorial data access statutes. Distribution runs through channel partners and direct enterprise sales teams, with systems integrators capturing implementation margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform engineering talent capable of auditing automated tagging systems for EU AI Act conformity remains acutely scarce, compressing vendor release cycles and inflating specialist compensation. This capability gap separates vendors who can accelerate certification timelines from those facing protracted compliance delays.
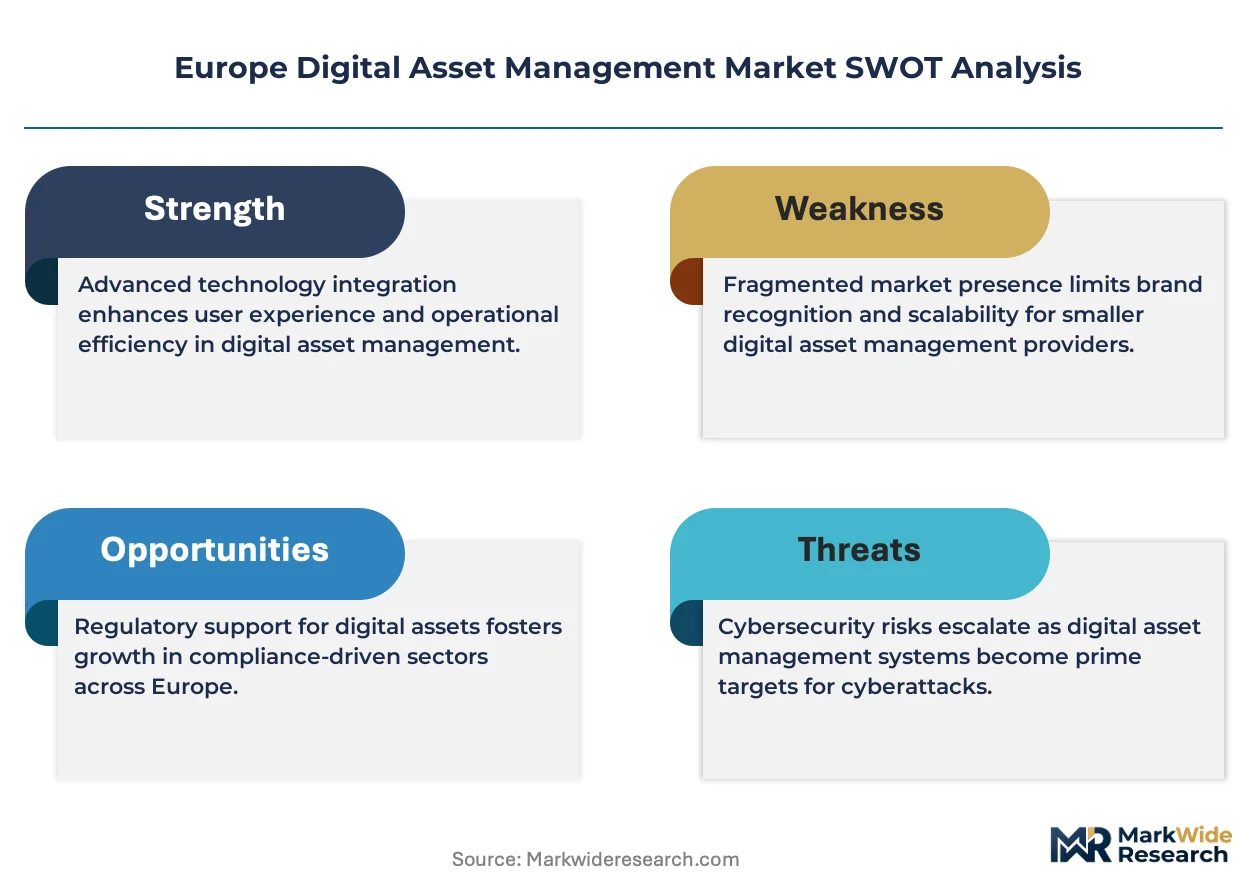
For Market Incumbents: Harden API ecosystem depth to reduce client switching costs against modular best-of-breed competitors. Invest in backward integration into edge computing nodes for post-production latency reduction. Channel control over systems integrator relationships defends margin position as unbundling pressures intensify. For New Entrants and Emerging Players: Establish a beachhead in Poland's underpenetrated manufacturing and retail verticals, where Western European workflow automation benchmarks have yet to diffuse. Target SaaS tiers for shared service centers in Krakow's technology corridor seeking reduced infrastructure overhead. Lead with rapid implementation speed against incumbent deployment timelines. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-infrastructure play because successive regulatory waves—MiCA implementation, CSRD digital reporting mandates, EU AI Act risk classifications—force recurring platform upgrades. Acquisition targets should demonstrate established conformity documentation workflows. The signal to watch is EBA guidance evolution on crypto-asset custody functions, which will reshape competitive positioning for institutional-facing vendors.| Strategic Initiative | Industry Significance |
|---|---|
| MiCA Certification Acceleration | Early conformity documentation secures institutional onboarding pipelines ahead of implementation deadlines. |
| API Ecosystem Expansion | Deep integration layers reduce switching costs and capture workflow automation margins from modular competitors. |
| Edge Computing Node Deployment | Distributed transcoding infrastructure reduces latency for Amsterdam and London post-production houses. |
| AI Ethics Specialist Acquisition | Technical audit capacity for automated tagging systems enables EU AI Act conformity across multilingual datasets. |
| Blockchain-DAM Convergence Development | Immutable provenance logging captures luxury goods and fine art market premiums in Milan and Geneva. |
Research Approach
Initial hypotheses were tested against primary input from DAM platform engineers, enterprise IT procurement officers, creative agency operations directors, and regulatory compliance specialists, then refined through secondary validation. Sources included EBA crypto-asset guidance documents, CNIL enforcement precedents on consent tracking, hyperscaler European infrastructure disclosures, and CSRD technical implementation standards. Bottom-up deployment estimates across cloud, hybrid, and on-premise architectures were triangulated against top-down market sizing from vendor revenue disclosures.
Demand-supply balance modeling segmented the market by deployment architecture, end-user vertical, solution capability, and application use case across the projection horizon. CAGRs were derived from installed base growth rates and average revenue per account expansion patterns. Forecast inputs incorporated MiCA implementation timeline assumptions, AI Act risk classification adoption curves, and GDPR cross-border data residency enforcement intensity variations across member states.
Macroeconomic conditions sit as an overlay; deviation in eurozone IT capital expenditure cycles or hyperscaler pricing adjustments would shift the trajectory. Forecasts reflect documented assumptions about regulatory implementation sequencing and enterprise cloud migration pace. Cross-checking against EBA and ESMA guidance updates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Assets and Cryptocurrency Finance
South Korea Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
Blockchain Financial Network Market
Digital Assets and Cryptocurrency Finance
Germany Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
US and Europe Crypto Asset Management Market
Digital Assets and Cryptocurrency Finance
Blockchain Finance Market
Digital Assets and Cryptocurrency Finance
US Cryptocurrency Payment Apps Market
Digital Assets and Cryptocurrency Finance
Bitcoin Exchange Market
Digital Assets and Cryptocurrency Finance
Investor ESG Software Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency Atms Market
Digital Assets and Cryptocurrency Finance
Crypto Asset Management Market
Digital Assets and Cryptocurrency Finance
Tokenization Solution Market
Digital Assets and Cryptocurrency Finance
Bitcoin Market
Digital Assets and Cryptocurrency Finance
Crypto Trading Platform Market
Digital Assets and Cryptocurrency Finance
Decentralized Finance Market
Digital Assets and Cryptocurrency Finance
Spain Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
Online Trading Platform Market