
 Blockchain Finance Market | 2026-2036
Blockchain Finance Market Size, Share, and Industry Trends Forecast 2026-2036
Blockchain Finance Market Analysis
Institutional buyer concentration is restructuring as sovereign wealth funds and pension managers consolidate blockchain treasury mandates. IBM leverages enterprise-grade permissioned networks to anchor institutional trust frameworks. Consensys specializes in Ethereum-based infrastructure for programmable settlement rails. R3 dominates interbank consortium architectures through its Corda protocol.
Blockchain finance encompasses distributed ledger systems, cryptographic consensus mechanisms, and smart contract automation that enable peer-to-peer value transfer without centralized intermediaries. Public blockchain networks operate on permissionless consensus with native token incentives, while private deployments enforce identity-gated participation for regulated settlement. Decentralized finance segments are capturing margin pools from traditional correspondent banking through algorithmic lending protocols. Smart contract infrastructure is maturing fastest in trade finance applications where automated execution reduces documentary processing cycles.
The SEC enforces securities classification for digital asset offerings, constraining token issuance structures in US jurisdictions. MiCA establishes uniform licensing requirements for crypto-asset service providers across EU member states, reshaping market access thresholds. The Monetary Authority of Singapore's Project Guardian pilots institutional-grade tokenization standards for private markets. Stakeholders must monitor how divergent custody rulemakings between the SEC and EU regulators fragment cross-border platform architecture decisions.
Market Dynamics
Institutional treasury departments are migrating settlement infrastructure onto distributed ledger networks to eliminate correspondent banking delays and reduce counterparty exposure in cross-border transactions. This operational restructuring is compressing implementation timelines for enterprise-grade blockchain platforms.
Growth Catalysts
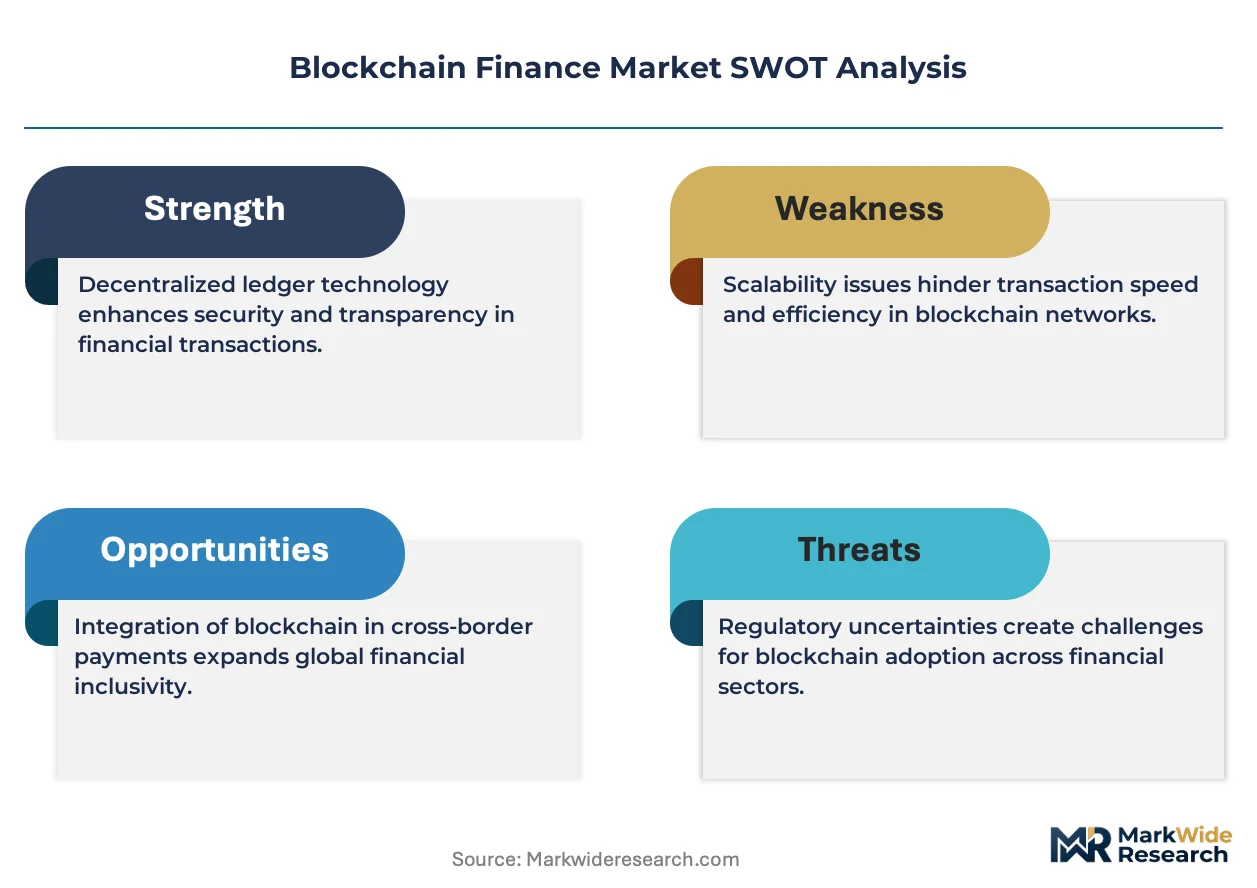
- MiCA Framework Implementation:The EU's Markets in Crypto-Assets regulation establishes uniform licensing standards across member states, compelling financial institutions to upgrade compliance infrastructure and accelerating platform procurement cycles.
- Asset Tokenization Protocols:Singapore's Project Guardian pilots institutional standards for private market tokenization, creating demand for regulated custody and settlement infrastructure among sovereign wealth funds and pension managers.
- Smart Contract Automation:Trade finance applications are absorbing automated documentary processing through programmable execution, reducing letter-of-credit settlement cycles from weeks to hours.
Market Restraints
- Securities Classification Uncertainty:The SEC's enforcement posture on digital asset offerings creates jurisdictional friction, constraining token issuance structures and limiting US-based platform development.
- Interoperability Fragmentation:Corda, Ethereum, and Hyperledger protocol silos prevent seamless cross-platform settlement, forcing institutions to maintain redundant infrastructure stacks.
- Quantum Cryptography Threat:Elliptic curve encryption underlying current blockchain signatures faces long-term vulnerability to quantum computing advances, necessitating costly cryptographic migration roadmaps.
Strategic Opportunities
- Carbon Credit Tokenization:Singapore's regulatory sandbox is piloting environmental asset tokenization standards, opening settlement infrastructure demand from commodity traders and ESG-focused institutional portfolios.
- Real-World Asset Collateralization:Private credit funds are exploring tokenized real estate and invoice receivables as on-chain collateral, creating demand for oracle networks and automated valuation systems.
- Cross-Border CBDC Bridges:The Monetary Authority of Singapore's participation in multi-currency wholesale CBDC experiments is generating infrastructure requirements for atomic settlement across heterogeneous central bank networks.
Industry Challenges
- Distributed Systems Engineering Talent:Smart contract auditing and zero-knowledge proof implementation require specialized cryptographic expertise that remains concentrated among a limited pool of protocol developers.
- Legacy Core Banking Integration:Mainframe-based treasury management systems require expensive middleware development to interface with blockchain settlement rails, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blockchain Finance Market |
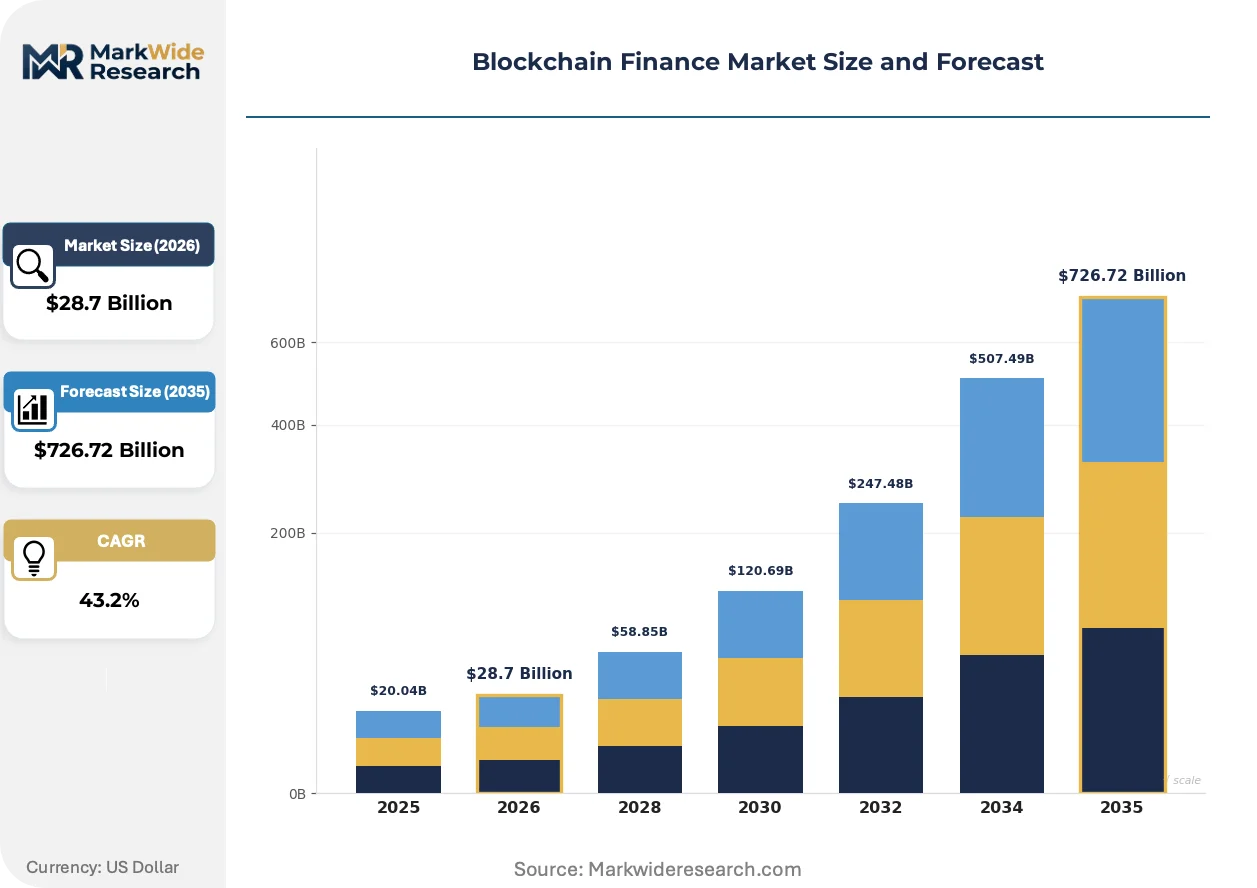
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $726.72 Billion |
| CAGR (2026 – 2036) | 43.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cryptocurrency, Smart Contracts, Decentralized Finance, Tokenization Technology: Public Blockchain, Private Blockchain, Consortium Blockchain, Hybrid Blockchain End User: Financial Institutions, Retail Investors, Corporates, Startups Deployment: Cloud-Based, On-Premises, Hybrid Solution, Managed Service |
| Companies Covered | IBM, Oracle, AWS, Accenture, Huawei, Coinbase, Consensys, R3, Stellar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blockchain Finance Market Emerging Trajectories
Programmable settlement infrastructure is absorbing functions previously executed through correspondent banking networks, compressing transaction finality from multi-day cycles to near-instant confirmation. This architectural shift is restructuring competitive positioning among infrastructure providers.
Zero-knowledge proof systems are absorbing verification workloads for institutional privacy requirements, enabling transaction validation without exposing counterparty balances or trade details. Private banking divisions and asset managers in Switzerland and Singapore are adopting zk-rollup architectures for client confidentiality compliance. The technology is absorbing regulatory scrutiny over data protection while maintaining audit trail integrity for supervisors.
MiCA's implementation timeline is forcing crypto-asset service providers to consolidate EU licensing operations under unified compliance frameworks, eliminating regulatory arbitrage between member states. Custody providers and exchange operators are restructuring entity architectures to meet capital reserve and operational continuity mandates. German and French regulators are coordinating supervisory technology to monitor cross-border platform compliance in real time.
Treasury procurement patterns are rotating toward outcome-based settlement service contracts rather than licensed software deployments, compressing vendor selection cycles and shifting implementation risk to infrastructure operators. Singaporean commodity trading houses and Swiss private banks are piloting transaction-fee-only pricing for cross-border payment corridors. This model is displacing perpetual license and maintenance fee structures that dominated enterprise blockchain procurement through 2023.
Blockchain Finance Market Segmentation
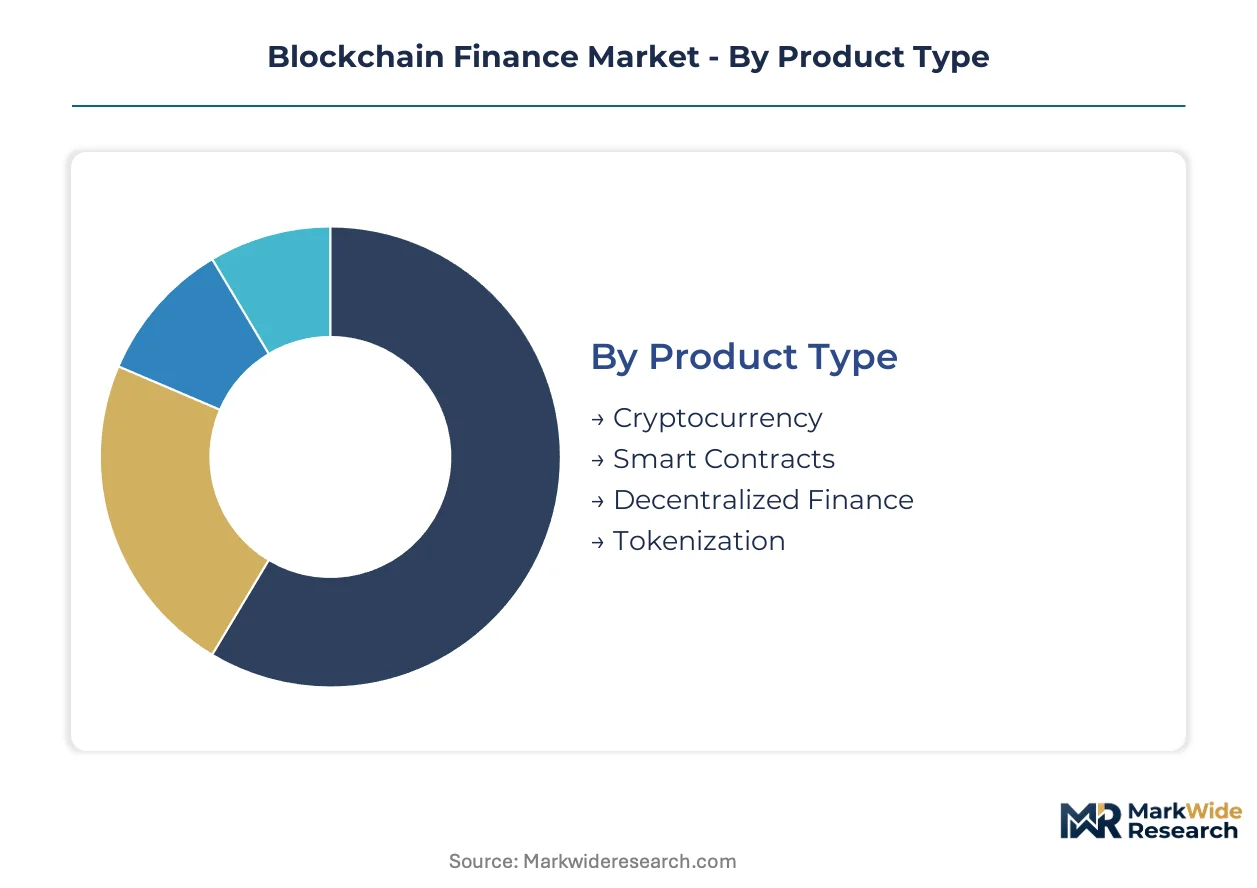
Blockchain finance infrastructure fragments across four orthogonal dimensions that determine procurement priorities, compliance burdens, and integration complexity. Product type governs regulatory classification and capital treatment. Technology architecture dictates permissioning models and interoperability constraints. Deployment mode shapes operational control and cybersecurity exposure.
Product Type:
Cryptocurrency platforms attract fundamentally different buyers than tokenization infrastructure—sovereign wealth funds prioritize regulated custody rails while retail-facing exchanges optimize for throughput.
- Cryptocurrency:Native digital assets operate on permissionless consensus with programmable monetary policy. Demand concentrates among Singaporean commodity trading houses seeking atomic settlement for cross-border commodity payments, constrained by the SEC's securities classification enforcement limiting US institutional participation.
- Tokenization:Real-world asset representation on distributed ledgers enables fractional ownership and automated corporate action processing. Singapore's Project Guardian pilots are absorbing infrastructure investment from pension managers and private credit funds exploring real estate and invoice receivables collateralization.
- Smart Contracts:Self-executing code automates documentary processing in trade finance applications.
- Decentralized Finance:Algorithmic lending protocols capture margin pools from traditional correspondent banking.
Volume sits with Cryptocurrency; growth tilts toward Tokenization.
Technology:
Permissioning models separate regulated institutions requiring identity-gated participation from pseudonymous retail networks.
- Private Blockchain:Identity-verified nodes enforce compliance through cryptographic access controls. Swiss private banks and German custody providers are consolidating procurement around Hyperledger Fabric deployments to satisfy MiCA operational continuity mandates while maintaining supervisory audit trails.
- Consortium Blockchain:Interbank architectures distribute trust among pre-approved financial institutions. R3's Corda protocol dominates correspondent banking replacement projects where multiple regulated entities require shared state without full transparency.
- Public Blockchain:Permissionless networks rely on economic incentives for consensus security.
- Hybrid Blockchain:Selective disclosure architectures balance transparency with confidentiality.
Private Blockchain holds current deployment volume; Consortium Blockchain is expanding most quickly among cross-border settlement consortia.
End User:
Balance sheet scale and regulatory sophistication determine platform selection criteria across buyer categories.
- Financial Institutions:Banks, asset managers, and insurers require enterprise-grade resilience and regulatory certification. Treasury departments at German universal banks and French asset managers are migrating settlement infrastructure onto distributed ledgers to compress correspondent banking cycles from days to hours.
- Corporates:Non-financial enterprises seek working capital optimization and supply chain transparency. Singaporean commodity trading houses are piloting transaction-fee-only pricing models for cross-border payment corridors, displacing perpetual license structures.
- Retail Investors:Individual participants access blockchain finance through exchange and wallet interfaces.
- Startups:Early-stage ventures prototype novel financial primitives on public infrastructure.
Financial Institutions dominate current procurement; Corporates are climbing the fastest as treasury digitization accelerates.
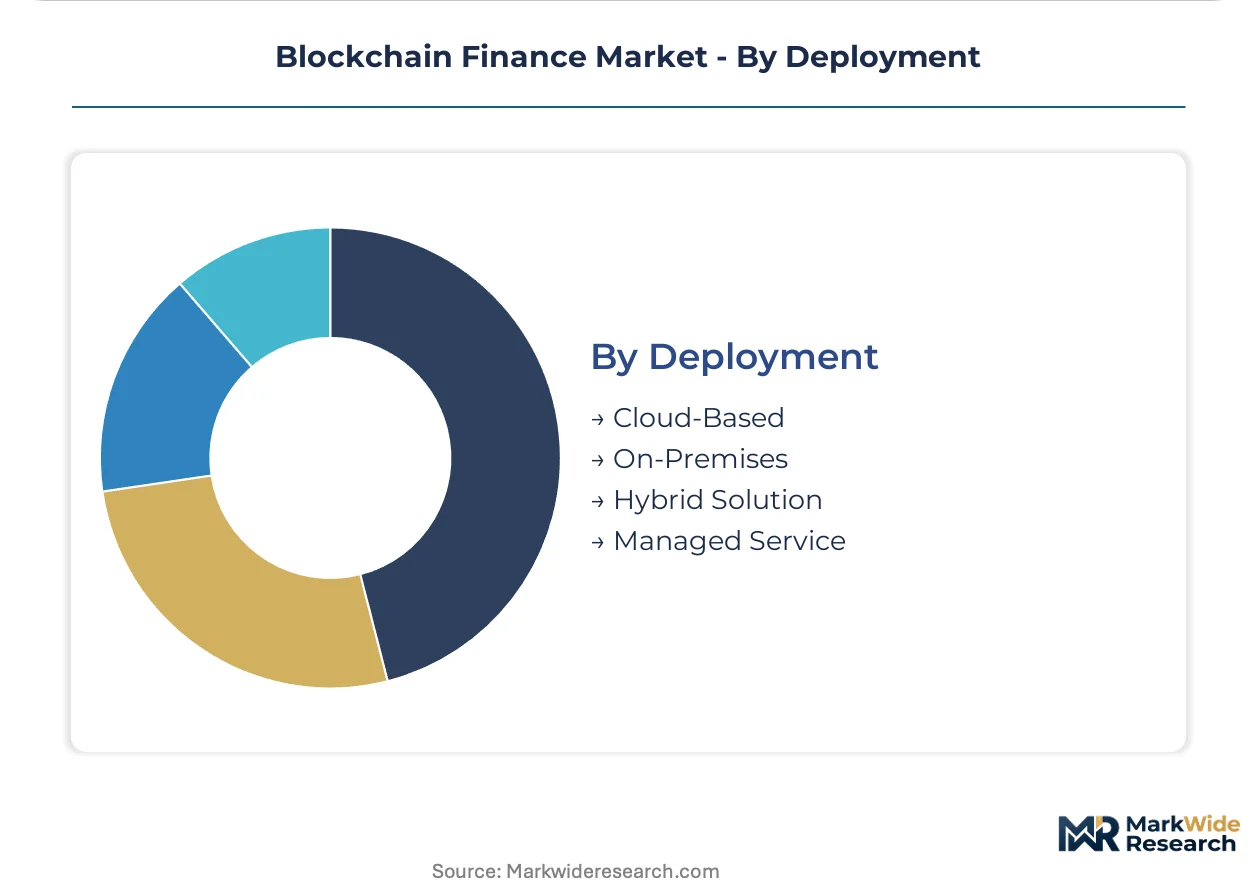
Deployment:
Operational control requirements separate regulated entities maintaining on-premises key custody from cost-optimized adopters accepting cloud abstraction.
- On-Premises:Dedicated hardware enforces hardware security module key protection and air-gapped signing ceremonies. Swiss private banking divisions mandate on-premises deployment for client asset custody to satisfy FINMA operational risk requirements.
- Managed Service:Outsourced infrastructure operators assume implementation risk and compliance certification burden. German and French regulators are coordinating supervisory technology to monitor cross-border managed service compliance in real time.
- Cloud-Based:Hyperscaler-hosted nodes reduce capital expenditure for non-critical workloads.
- Hybrid Solution:Sensitive operations remain on-premises while scalability layers migrate to cloud.
On-Premises retains volume among Tier-1 banks; Managed Service is gaining share fastest as outcome-based contracting displaces licensed software procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Energy infrastructure in Singapore and financial services density in Switzerland anchor geographic demand concentration for blockchain settlement systems. Regulatory sandboxes in these jurisdictions attract institutional treasury migration. Talent pools in Germany and the United States sustain protocol development velocity.
United States
Pension managers and sovereign wealth funds drive institutional custody demand. SEC enforcement on securities classification constrains token issuance structures. New York and Chicago financial centers host enterprise blockchain procurement decisions for cross-border settlement infrastructure.
Singapore
Commodity trading houses and private credit funds absorb tokenization infrastructure. MAS Project Guardian pilots institutional-grade standards for private markets. The Marina Bay financial district concentrates custody provider licensing and compliance technology development.
Germany
Universal banks and asset managers migrate treasury settlement onto distributed ledgers. MiCA implementation compels operational continuity upgrades. Frankfurt and Berlin clusters coordinate supervisory technology for cross-border platform monitoring.
Switzerland
Private banking divisions adopt zero-knowledge architectures for client confidentiality. FINMA operational risk requirements mandate on-premises key custody. Zurich and Geneva anchor institutional-grade infrastructure procurement for wealth management.
United Kingdom
Interbank consortiums and fintech ventures pilot programmable settlement rails. FCA consultation frameworks shape custody rulemaking for institutional participants. London's Square Mile concentrates R&D partnerships between banks and protocol developers.
Blockchain Finance Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized compliance infrastructure and carbon credit tokenization. The vendor base distributes across three maturity tiers: hyperscale cloud operators, enterprise software incumbents, and protocol-native specialists. Strategic archetypes include permissioned network architects, public chain infrastructure providers, and verticalized custody operators. Competitive moves concentrate on consortium formation for cross-border settlement standards and outcome-based service contracting displacing perpetual licenses.
Within the enterprise software tier, IBM and Oracle represent legacy technology vendors adapting distributed ledger capabilities for regulated financial institutions. Among protocol-native specialists, Consensys and R3 exemplify divergent architectural approaches—Ethereum-based programmability versus interbank consortium design. Coinbase occupies a position bridging retail exchange operations with institutional custody services.
| Leading Market Players |
|---|
| IBM |
| Oracle |
| AWS |
| Accenture |
| Huawei |
| Coinbase |
| Consensys |
| R3 |
| Stellar |
| Others |
Supply Flow & Price Mechanics
Sovereign wealth funds and pension managers consolidating blockchain treasury mandates have shifted procurement toward outcome-based settlement service contracts. This buyer concentration compresses vendor selection cycles and displaces perpetual license structures that dominated enterprise blockchain procurement through 2023.
Pricing Analysis
Volume concentrates in transaction-fee-only pricing models for cross-border payment corridors, while margin pools accrue to managed service operators assuming implementation risk. Three-tier pricing structure across premium, standard, and economy levels separates Swiss private banks demanding on-premises custody from Singaporean commodity trading houses accepting cloud abstraction. Cost compression in the standard tier intensifies because hyperscaler-hosted nodes reduce capital expenditure barriers for non-critical workloads. Retail-facing exchanges exhibit highest price sensitivity; Tier-1 banks mandate premium tiers regardless of cost.
Supply Chain Analysis
Regional distribution centers for blockchain infrastructure cluster in Singapore, Germany, and Switzerland where regulatory sandboxes attract institutional treasury migration. Protocol development draws from talent pools concentrated in the United States and Germany, while hardware security module manufacturing rests on semiconductor supply chains anchored in Taiwan and South Korea. Single-source vulnerability runs through specialized cryptographic engineering expertise concentrated among limited protocol developer pools. Distribution runs through managed service operators consolidating EU licensing operations under unified MiCA compliance frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain finance infrastructure is becoming a vertical-integration race as players pursue captive control over zero-knowledge proof implementation and smart contract auditing capabilities.
For Market Incumbents: To counter outcome-based contracting displacing perpetual licenses, deepen backward integration into managed service operations and secure exclusive channel control over German and French regulatory technology partnerships. Anchor defensive positioning through certification investment in MiCA operational continuity mandates. For New Entrants and Emerging Players: Begin with carbon credit tokenization pilots in Singapore's regulatory sandbox, the most penetrable segment for unproven infrastructure providers. Target ESG-focused institutional portfolios through oracle network specialization as the primary go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor protocol-native specialists with Corda or Ethereum expertise in Switzerland and Singapore, where private banking confidentiality requirements sustain premium pricing. Long-term viability hinges on acquisition targets demonstrating live deployments with sovereign wealth fund mandates. Watch for inflection signals in multi-currency wholesale CBDC experiment participation rates.| Strategic Initiative | Industry Significance |
|---|---|
| Consortium Formation for Settlement Standards | R3's Corda protocol anchors interbank trust architectures across correspondent banking replacement projects. |
| Managed Service Operator Acquisition | IBM leverages enterprise-grade permissioned networks to capture outcome-based contracting migration. |
| Zero-Knowledge Proof Capability Buildout | Swiss private banking divisions adopt zk-rollup architectures for FINMA client confidentiality compliance. |
| MiCA Compliance Technology Licensing | German and French regulators coordinate supervisory technology for real-time cross-border platform monitoring. |
| Carbon Credit Tokenization Platform Launch | Singapore's regulatory sandbox pilots environmental asset standards for commodity trader settlement demand. |
Methodological Framework
Document review covered SEC enforcement actions, MiCA regulatory filings, and MAS Project Guardian pilot documentation, complemented by interviews with blockchain infrastructure procurement officers at German universal banks, Singaporean commodity trading house treasurers, Swiss private banking division CTOs, and Consensys platform engineers. Secondary validation drew from trade finance documentary processing databases, custody provider licensing records, and central bank CBDC experiment disclosures. Bottom-up deployment counts across on-premises, managed service, and cloud-based installations were triangulated against top-down infrastructure spending estimates from financial institution technology budgets.
Cross-referencing historical procurement patterns with panel input from infrastructure operators and regulatory technology vendors shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology architecture, deployment mode, and end-user regulatory sophistication. CAGRs were derived from elasticity-adjusted adoption curves calibrated to MiCA implementation timelines and Project Guardian pilot expansion signals.
Underlying measurement precision varies by segment; cryptocurrency platform volumes carry tighter precision than emerging tokenization infrastructure forecasts. Projections reflect documented assumptions regarding regulatory harmonization velocity and quantum cryptography migration timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Assets and Cryptocurrency Finance
Tokenization Solution Market
Digital Assets and Cryptocurrency Finance
Germany Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
Music NFT Market
Digital Assets and Cryptocurrency Finance
NFT Analytics Tools Market
Digital Assets and Cryptocurrency Finance
Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
United States Digital Asset Management Market
Digital Assets and Cryptocurrency Finance
Digital Asset Management (DAM) Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency and Blockchain Market
Digital Assets and Cryptocurrency Finance
Asset Tokenization Software Market
Digital Assets and Cryptocurrency Finance
Global Non-Fungible Tokens Market
Digital Assets and Cryptocurrency Finance
Digital Collectibles Platform Market
Digital Assets and Cryptocurrency Finance
Bitcoin and Cryptocurrency Atms Market
Digital Assets and Cryptocurrency Finance
Bitcoin Exchange Market
Digital Assets and Cryptocurrency Finance
Investor ESG Software Market
Digital Assets and Cryptocurrency Finance
Crypto Art Market
Digital Assets and Cryptocurrency Finance
Crypto ATM Market