
 US Cryptocurrency Payment Apps Market | 2026-2036
US Cryptocurrency Payment Apps Market Size, Share, and Industry Trends Forecast 2026-2036
US Cryptocurrency Payment Apps Market Insights
E-commerce merchant onboarding is decoupling from traditional payment processor relationships as crypto-native checkout options proliferate. Block, Inc. leverages its Square merchant ecosystem to bridge fiat and crypto rails for small businesses. Coinbase Global, Inc. anchors institutional credibility through its regulated exchange infrastructure. PayPal Holdings, Inc. competes by extending familiar consumer interfaces into stablecoin settlement.
Cryptocurrency payment apps are software platforms that execute digital asset transfers through blockchain networks, typically settling transactions within minutes using cryptographic verification rather than bank-mediated clearing. These systems serve commercial and retail users seeking programmable, censorship-resistant value movement outside legacy correspondent banking. Merchant Payments services dominate transaction volume as retailers integrate QR-code and gateway-based settlement, while P-to-P Transfers sustain the highest user growth through social payment features. Mobile Apps capture the largest share of consumer engagement, though Web Platforms retain significance for enterprise treasury operations requiring multi-signature controls.
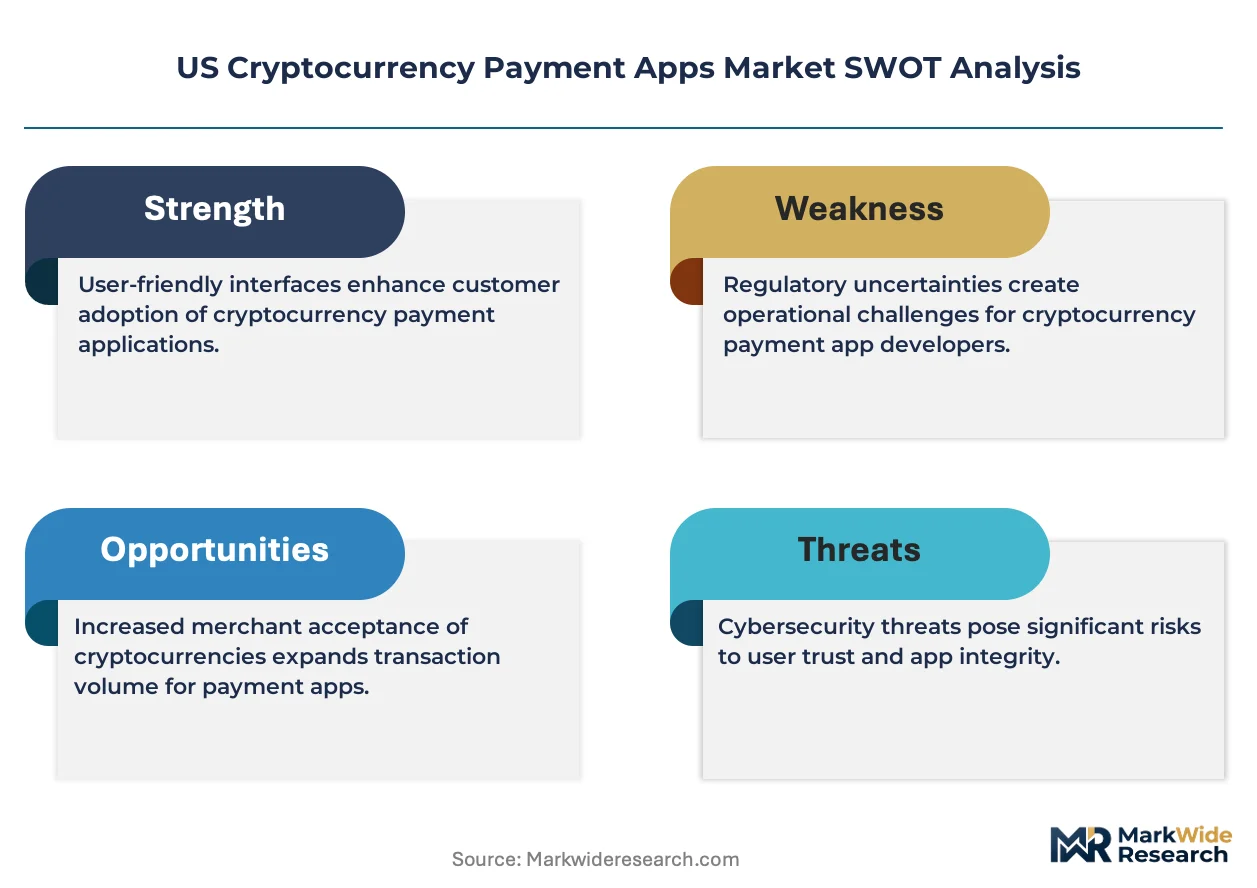
The Financial Crimes Enforcement Network, state-level money transmitter regulators, and SEC enforcement divisions collectively shape product architecture through know-your-customer mandates and securities classification risks. New York's BitLicense and Wyoming's SPDI charter create divergent compliance costs that fragment state-by-state market access. Stakeholders must monitor how the Federal Reserve's FedNow instant payment network intersects with private stablecoin rails, as this convergence will determine whether crypto payment apps complement or displace bank-led real-time settlement.
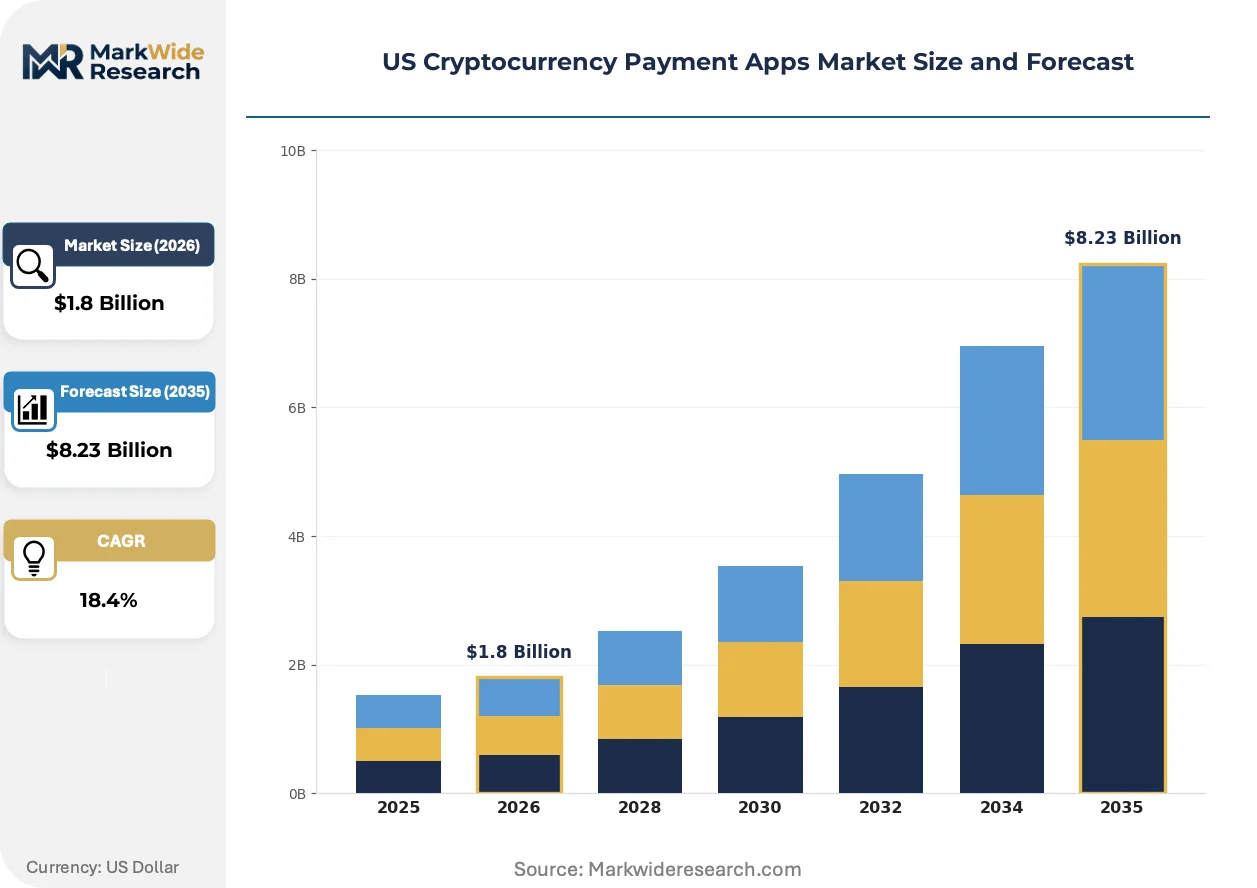
Market Dynamics
State-level licensing fragmentation under the BitLicense framework and Wyoming's SPDI charter is forcing payment app providers to architect multi-jurisdictional compliance stacks, diverting engineering resources from product innovation toward regulatory navigation.
Growth Catalysts
- Merchant cost pressure:Small retailers in high-card-fee verticals are abandoning traditional interchange networks for blockchain settlement rails that eliminate chargeback risk and reduce per-transaction costs by removing acquirer middlemen.
- Texas regulatory arbitrage:The state's crypto-friendly banking charter and absence of money transmitter licensing for certain digital asset activities is concentrating payment app headquarters and operational infrastructure in Austin and Dallas corridors.
- FedNow convergence experimentation:Developers are building hybrid settlement layers that bridge Federal Reserve instant payment rails with private stablecoin networks, creating redundancy for merchant treasury operations.
Market Restraints
- New York BitLicense compliance burden:The state's stringent capital reserves and cybersecurity audit requirements exclude all but the best-capitalized platforms from serving the country's fourth-largest consumer market.
- Banking access concentration:Reliance on a shrinking pool of crypto-friendly correspondent banks creates operational fragility, with single institution policy shifts capable of freezing fiat on-ramps for entire app ecosystems.
- Private key custody limitations:Regulatory uncertainty around self-custody versus qualified custodian models restricts product architecture options and increases insurance costs for consumer-facing wallets.
Strategic Opportunities
- Wyoming SPDI charter expansion:The state's special purpose depository institution framework allows payment apps to obtain banking powers without Federal Reserve master account dependency, enabling direct custody and issuance of tokenized deposits.
- Cross-border remittance corridors:Unbanked recipient populations in Mexico and Central America present white-space demand for stablecoin-based settlement that bypasses Western Union's retail network.
- Merchant rewards tokenization:Integration of programmable loyalty points with payment rails allows retailers to issue branded digital assets that circulate within closed-loop economies, reducing reliance on generic cashback programs.
Industry Challenges
- Blockchain engineering talent scarcity:Smart contract security auditing and layer-2 scaling implementation require specialized skill sets that command premium compensation, constraining platform development velocity.
- Multi-state licensing synchronization:Money transmitter registration across fifty jurisdictions with divergent net worth and surety bond requirements creates administrative overhead that scales linearly with geographic expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Cryptocurrency Payment Apps Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Apps, Web Platforms, eWallets, Software Solutions Service Type: P-to-P Transfers, Merchant Payments, Currency Exchange, Investment Tracking End User: Consumers, Small Businesses, Large Enterprises, Investors Technology: Blockchain, Payment Gateways, QR Code, Digital Wallets |
| Companies Covered | PayPal Holdings, Inc., Block, Inc., Coinbase Global, Inc., BitPay, Inc., Binance.US, Crypto.com, Kraken, Circle Internet Financial, LLC, Robinhood Markets, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Cryptocurrency Payment Apps Market Trends and Innovations
Payment infrastructure is converging around programmable settlement layers that embed compliance logic directly into transaction execution, replacing post-hoc reconciliation with atomic regulatory adherence.
Account abstraction standards are absorbing complexity from end-user key management by enabling social recovery mechanisms and gasless transaction sponsorship. Retail merchants without technical staff are adopting these wallet architectures through white-label SDK integrations. The technology is absorbing friction that previously required dedicated blockchain operations personnel, compressing merchant onboarding timelines from quarters to weeks.
The Financial Crimes Enforcement Network's proposed travel rule extensions for unhosted wallets are forcing platforms to embed transaction monitoring at the protocol level. Industrial consequence includes mandatory address verification for transfers above thresholds, with affected platforms rebuilding user interfaces to surface compliance checkpoints without abandoning pseudonymity promises. California and Texas merchants serving international customers are most affected, responding by geofencing certain jurisdictions to limit regulatory exposure.
Buyer concentration among tech-forward small businesses is rotating demand toward embedded finance models where payment acceptance integrates with inventory and payroll systems. Independent retailers previously served by standalone terminals are selecting app ecosystems that bundle accounting and tax preparation. This pattern is most visible in Austin, Miami, and Denver metropolitan corridors where young merchant demographics overlap with crypto-native consumer bases.
US Cryptocurrency Payment Apps Market Segmentation
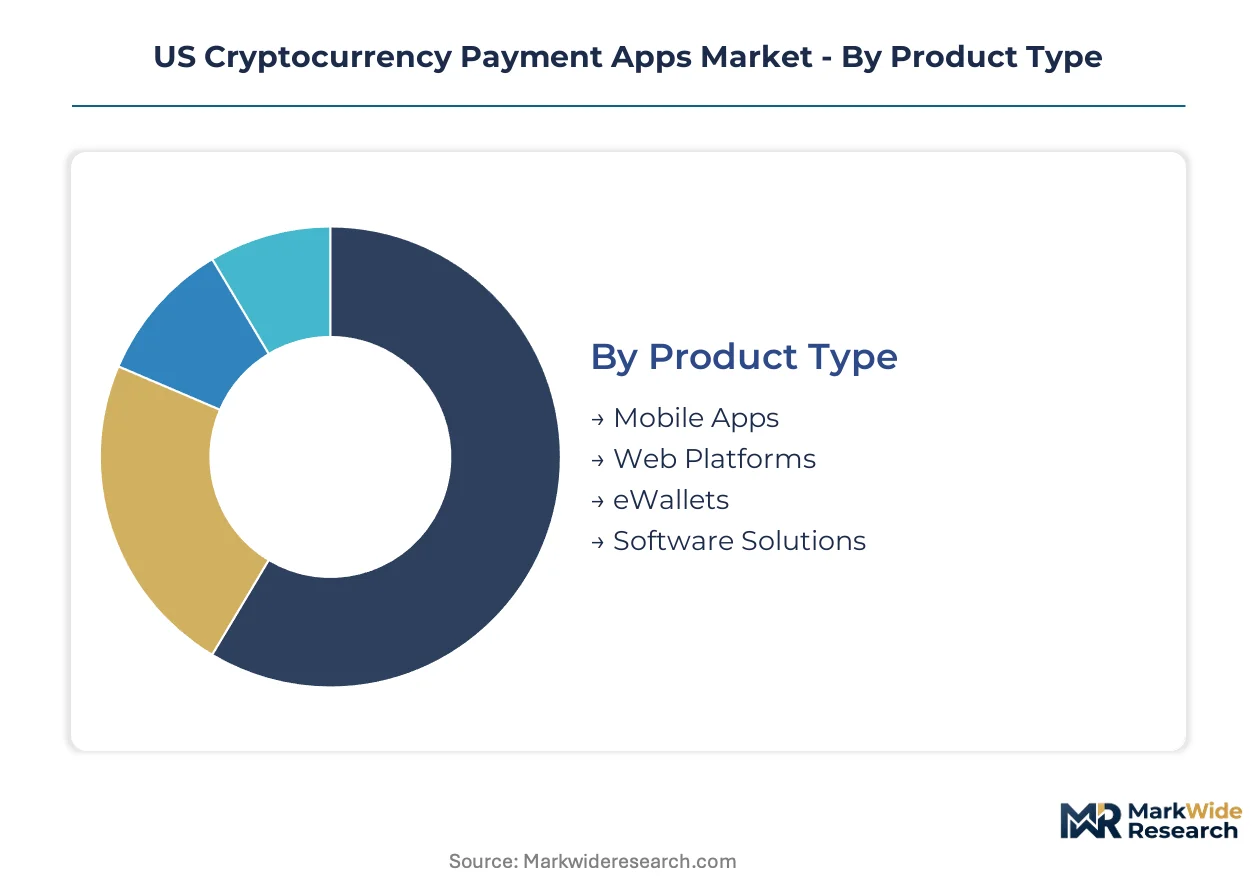
Segmentation in the US cryptocurrency payment apps market reveals divergent capital requirements and regulatory exposure across product architectures. Each category isolates distinct value capture mechanisms—from consumer-facing mobile interfaces to enterprise treasury infrastructure—that shape platform investment priorities and compliance stack design.
Product Type:
Capital intensity varies sharply across delivery mechanisms, with custody-bearing solutions demanding heavier upfront investment than interface layers.
- Mobile Apps:Native iOS and Android applications with embedded key management and biometric authentication dominate consumer engagement. Texas and California merchants prioritize these for QR-code point-of-sale integration where interchange fee elimination drives adoption.
- Web Platforms:Browser-based dashboards with multi-signature controls and API access serve enterprise treasury operations requiring batch transaction capabilities. Demand concentrates among Austin fintech clusters seeking hybrid fiat-crypto settlement rails.
- eWallets:Cloud-hosted custody solutions with simplified recovery mechanisms.
- Software Solutions:White-label SDKs and merchant gateway integrations.
Most installed capacity flows through Mobile Apps. Expansion is steepest in Web Platforms.
Service Type:
Revenue model differentiation separates transaction-fee services from subscription-based tooling, with merchant-facing offerings commanding premium pricing.
- Merchant Payments:QR-code and gateway-based settlement services that eliminate chargeback risk and acquirer middlemen. Small retailers in high-card-fee verticals across Miami and Denver corridors drive demand as they abandon traditional interchange networks.
- P-to-P Transfers:Social payment features with near-instant settlement between individuals. User growth sustains highest velocity among unbanked-adjacent populations in Central American remittance corridors originating from Texas border cities.
- Currency Exchange:Spot conversion between digital assets and fiat denominations.
- Investment Tracking:Portfolio analytics and tax reporting tools.
Merchant Payments captures the largest transaction volume base. P-to-P Transfers is gaining share fastest among user acquisition metrics.
End User:
Customer sophistication determines compliance burden and support infrastructure requirements, with institutional clients demanding qualified custodian arrangements.
- Small Businesses:Tech-forward retailers with limited technical staff seeking bundled accounting and payment acceptance. Austin and Denver metropolitan corridors show strongest concentration where young merchant demographics overlap with crypto-native consumer bases.
- Consumers:Individual users prioritizing social features and simplified key management.
- Large Enterprises:Corporate treasuries requiring multi-signature controls and audit trails.
- Investors:Sophisticated users demanding advanced order types and tax optimization.
Small Businesses account for the steepest adoption curve. Large Enterprises represent the highest contract value per deployment.
Technology:
Underlying infrastructure choices determine scalability limits and regulatory classification risk, with pure blockchain architectures facing SEC securities scrutiny.
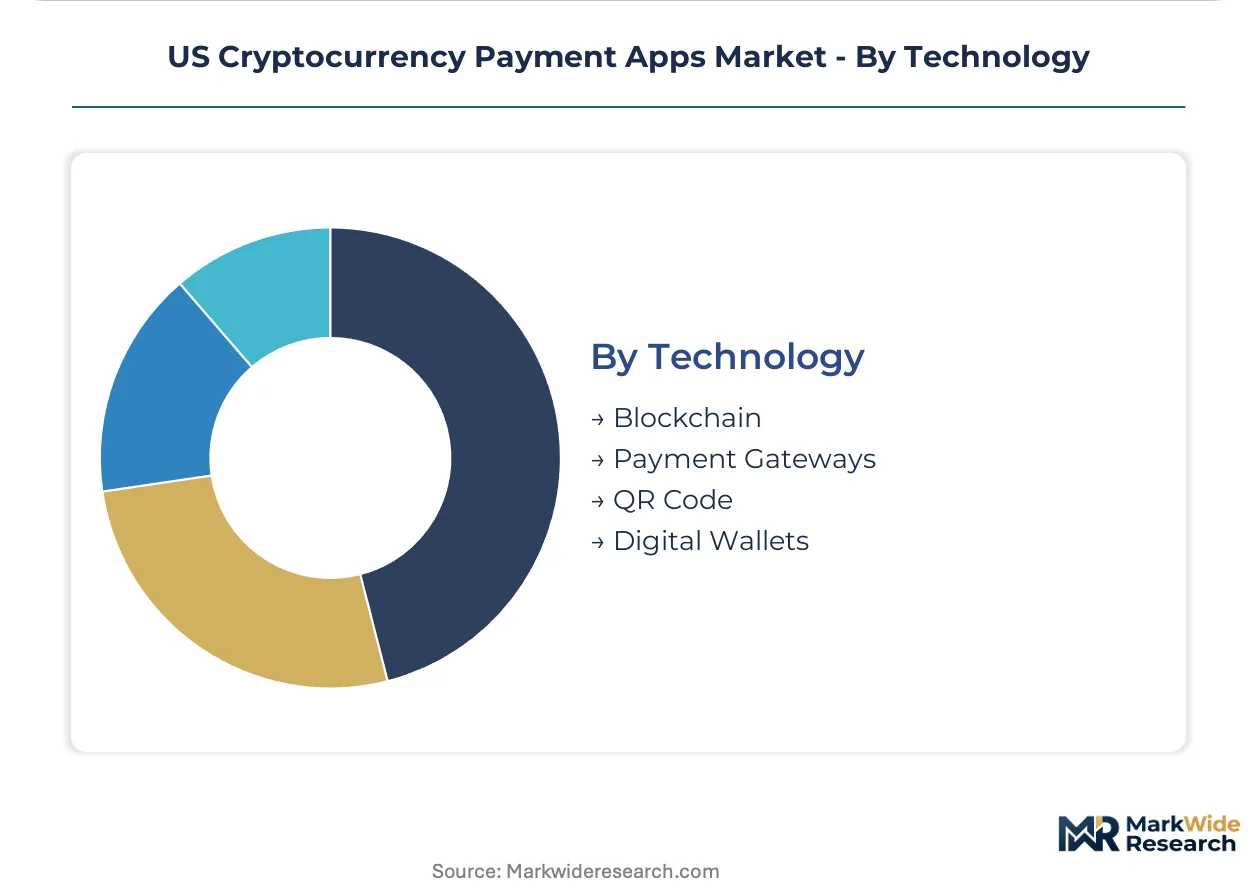
- Blockchain:Layer-1 and layer-2 networks with cryptographic verification replacing bank-mediated clearing. Wyoming SPDI charter holders leverage this for direct tokenized deposit issuance without Federal Reserve master account dependency.
- Payment Gateways:Fiat on-ramp and off-ramp bridges with traditional banking integration.
- QR Code:Optical scanning protocols for merchant-presented payment requests.
- Digital Wallets:Key storage and transaction signing infrastructure.
Blockchain underpins the majority of settlement volume. Payment Gateways show the most rapid infrastructure buildout as banking partnerships expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Austin and Dallas corridors concentrate payment app headquarters as Texas regulatory arbitrage draws operational infrastructure from higher-burden jurisdictions.
California
Tech-savvy consumers in San Francisco and Los Angeles drive merchant adoption of QR-code settlement. The state's Department of Financial Protection and Innovation enforces money transmitter licensing that shapes compliance stack design. San Diego fintech clusters experiment with hybrid stablecoin-FedNow settlement layers for cross-border commerce.
Texas
Small retailers in Houston and Dallas abandon card networks for blockchain rails that eliminate chargeback risk. The state's crypto-friendly banking charter and selective money transmitter exemptions reduce compliance overhead. Austin hosts the densest concentration of payment app engineering talent outside Silicon Valley.
New York
Institutional demand concentrates in Manhattan for regulated exchange infrastructure serving corporate treasuries. The BitLicense framework imposes stringent capital reserves and cybersecurity audits that exclude undercapitalized platforms. Brooklyn-based developers build compliance-first architectures that satisfy state-level requirements.
Wyoming
Rural merchants adopt tokenized deposit solutions through SPDI charter holders seeking banking powers without Federal Reserve master account dependency. The state's special purpose depository institution framework enables direct custody and issuance of digital assets. Cheyenne serves as a jurisdictional hub for platforms architecting multi-state compliance stacks.
Florida
Miami's young merchant demographics overlap with crypto-native consumer bases to accelerate embedded finance adoption. The state's absence of personal income tax attracts payment app operational subsidiaries. Tampa Bay corridors show expanding demand for P-to-P transfer services targeting Central American remittance corridors.
US Cryptocurrency Payment Apps Market Competitive Landscape
Strategic partnerships dominate the current landscape as platforms seek banking access and regulatory coverage. The vendor base fragments across three tiers: regulated exchange infrastructure, merchant ecosystem integrators, and mobile-native consumer interfaces. Two archetypes define positioning: fiat-crypto bridge providers leveraging traditional payment familiarity, and crypto-native platforms emphasizing censorship-resistant settlement. Competitive moves concentrate on geographic licensing expansion and hybrid settlement layer development.
Within the regulated exchange tier, Coinbase Global, Inc. and Kraken exemplify platforms architecting compliance-first stacks for institutional credibility. Block, Inc. occupies a distinct position bridging Square's merchant ecosystem with crypto settlement rails for small business adoption. These three companies represent divergent strategic bets on whether consumer familiarity or crypto-native infrastructure wins merchant preference.
| Leading Market Players |
|---|
| PayPal Holdings, Inc. |
| Block, Inc. |
| Coinbase Global, Inc. |
| BitPay, Inc. |
| Binance.US |
| Crypto.com |
| Kraken |
| Circle Internet Financial, LLC |
| Robinhood Markets, Inc. |
| Others |
Pricing and Supply Chain Analysis
Compliance engineering labor costs cascade through payment app pricing tiers, with platforms bearing New York BitLicense audit expenses passing through premium subscription rates while Texas-chartered operators undercut via leaner regulatory stacks. Merchant-facing solutions absorb these divergent cost bases into per-transaction fees that scale with settlement velocity and custody complexity.
Pricing Analysis
Distributor margin compression in white-label SDK channels forces platform providers toward direct merchant relationships. Three-tier pricing structure across enterprise, mid-market, and small-business levels separates multi-signature treasury suites from QR-code point-of-sale bundles. Pricing pressure stems from interchange fee elimination becoming table stakes rather than premium justification. Small retailers in high-card-fee verticals exhibit acute price sensitivity, while institutional treasuries prioritize audit trail completeness over per-transaction cost.
Supply Chain Analysis
Returns and chargeback dispute flows remain minimal in blockchain-native settlement, eliminating reverse-logistics overhead that burdens traditional card networks. Engineering talent concentrates in Austin, San Francisco, and New York corridors, with smart contract security expertise commanding premium compensation. Custodial infrastructure draws from Wyoming SPDI charter holders, Texas state-chartered banks, and a shrinking pool of crypto-friendly correspondent institutions. Single-source vulnerability runs through banking access concentration, where policy shifts at individual institutions freeze fiat on-ramps. Distribution runs through API-first integrations and white-label merchant gateway deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Texas regulatory arbitrage against New York BitLicense burdens creates geographic margin spreads that reward multi-jurisdictional operational footprints. Platforms optimizing compliance stack location capture structural cost advantages that compound across scaling merchant bases.
For Market Incumbents: Lock in correspondent banking relationships before policy contraction eliminates remaining fiat on-ramp options. Deepen Wyoming SPDI charter utilization to bypass Federal Reserve master account dependency for tokenized deposit issuance. Acquire specialized smart contract audit capabilities to compress security review timelines that currently constrain product velocity. For New Entrants and Emerging Players: Launch via embedded finance partnerships with vertical SaaS providers serving Austin and Denver merchant corridors. Target unbanked-adjacent remittance flows from Texas border cities into Central American corridors where Western Union's retail network retains pricing power. Prioritize white-label SDK distribution over direct consumer acquisition to bypass brand-building capital requirements. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-state licensing overhead exceeds standalone platform revenue scalability. Viable acquisition targets combine Wyoming banking charter access with mature compliance engineering teams capable of BitLicense navigation. Monitor Federal Reserve FedNow interoperability announcements as signals of stablecoin displacement risk versus complementary infrastructure validation.| Strategic Initiative | Industry Significance |
|---|---|
| Wyoming SPDI Charter Acquisition | Banking powers without Federal Reserve master account dependency unlock direct custody and tokenized deposit issuance. |
| Hybrid Stablecoin-FedNow Integration | Redundant settlement rails attract merchant treasuries seeking operational continuity across payment network disruptions. |
| Cross-Border Remittance Corridor Expansion | Stablecoin settlement bypasses Western Union's retail network in Mexico and Central America unbanked populations. |
| Account Abstraction SDK Deployment | Social recovery mechanisms compress merchant onboarding timelines from quarters to weeks for non-technical retailers. |
| Multi-State Licensing Synchronization | Unified compliance stacks reduce administrative overhead that currently scales linearly with geographic expansion. |
Research Methodology
Multiple input streams — primary interviews with payment platform CTOs, state regulatory counsel, and merchant treasury directors; secondary validation through FinCEN guidance documents, state banking commissioner filings, and SEC enforcement action records; plus transaction volume data from blockchain analytics providers — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured engineering resource allocation patterns across compliance and product development functions. Secondary sources included money transmitter licensing databases, SPDI charter application disclosures, and FedNow service provider announcements.
Historical transaction volume trajectories were cross-referenced against panel input from platform executives regarding pipeline conversion rates and merchant churn patterns. The analytical framework modeled deployment model, merchant size tier, settlement technology, and state regulatory cluster across the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market sizing. Forecast inputs incorporated BitLicense application approval timelines, Wyoming SPDI charter issuance velocity, and correspondent banking relationship stability indicators.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt SEC securities classification shifts or Federal Reserve stablecoin issuance decisions. Practitioners should monitor state-level money transmitter exemption modifications and FedNow interoperability specifications for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Assets and Cryptocurrency Finance
Digital Asset Transaction Market
Digital Assets and Cryptocurrency Finance
US and Europe Crypto Asset Management Market
Digital Assets and Cryptocurrency Finance
Trading Data Platform Market
Digital Assets and Cryptocurrency Finance
Crypto Automated Teller Machine Market
Digital Assets and Cryptocurrency Finance
Crypto Asset Management Platform Market
Digital Assets and Cryptocurrency Finance
NFT Art Market
Digital Assets and Cryptocurrency Finance
Music NFT Market
Digital Assets and Cryptocurrency Finance
United States Crypto ATM Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency Atms Market
Digital Assets and Cryptocurrency Finance
United States Digital Asset Management Market
Digital Assets and Cryptocurrency Finance
Bitcoin Trading Software Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency Hardware Wallet Market
Digital Assets and Cryptocurrency Finance
Global Blockchain in Supply Chain Finance Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency and Blockchain Market
Digital Assets and Cryptocurrency Finance
Asset Tokenization Software Market
Digital Assets and Cryptocurrency Finance
NFT Analytics Tools Market