
 Nicorandil Market | 2026-2036
Nicorandil Market Size, Share, and Industry Trends Forecast 2026-2036
Nicorandil Market Insights
Pharmacopeial-grade nicorandil is redrawing competitive benchmarks as clinics and hospitals demand batch-certified purity above standard compendial limits. Tonghua Renmin Pharmaceutical leverages backward integration into potassium channel opener synthesis to control raw material quality. Chugai Pharmaceutical anchors its position through Japan-specific stability data and PMDA-aligned documentation. Shanxi Xinyu Pharmaceutical competes on volume scale across northern China's hospital tender networks.
Nicorandil is a potassium channel opener with nitrate-like properties, chemically defined as N-(2-hydroxyethyl)nicotinamide nitrate, formulated typically as 5 mg or 10 mg tablets for coronary vasodilation in angina pectoris. Tablet formulations dominate volume due to established bioequivalence pathways and long shelf stability, while injection formats capture premium pricing in acute cardiac care settings where rapid onset matters. Hospitals represent the core end-user channel, absorbing bulk procurement through centralized tender systems, whereas outpatient clinics and home care segments expand as post-discharge maintenance protocols lengthen treatment duration.
China's NMPA enforces bioequivalence study requirements for generic nicorandil approvals, raising barriers for subscale manufacturers. Japan's PMDA maintains stringent ICH Q1A stability standards that shape export eligibility for Asian suppliers. India's CDSCO aligns with WHO prequalification norms for cardiovascular APIs, influencing contract manufacturing flows. Stakeholders must monitor evolving pharmacopeial harmonization between Chinese GB standards and European Pharmacopoeia monographs, as divergence in impurity profiling rules will determine which production bases retain cross-border supply contracts.
Market Dynamics
Hospital procurement centralization across China's Shandong and Hebei provinces is compressing supplier margins while elevating batch-certification requirements above standard pharmacopeial limits.
Growth Catalysts
- Cardiovascular protocol expansion:Hospital formularies in China are broadening angina treatment guidelines to include potassium channel openers as first-line maintenance therapy.
- NMPA bioequivalence mandates:China's tightened generic approval standards are filtering subscale manufacturers and consolidating volume with certified producers.
- Injection format adoption:Acute cardiac care units are prioritizing rapid-onset intravenous nicorandil for STEMI protocols over oral loading doses.
Market Restraints
- API supply concentration:Bulk potassium channel opener synthesis clusters in two Chinese provinces, creating geographic vulnerability to environmental compliance shutdowns.
- Impurity profiling divergence:Misalignment between Chinese GB standards and European Pharmacopoeia monographs blocks cross-border contract eligibility for dual-registered suppliers.
- Substitution pressure from ranolazine:Late-generation antianginals with different mechanisms are capturing maintenance therapy slots in Japanese hospital formularies.
Strategic Opportunities
- Post-discharge home care expansion:Extended maintenance protocols are opening outpatient pharmacy channels for 90-day tablet supplies in tier-2 Chinese cities.
- PMDA-aligned documentation exports:Japanese stability data packages are unlocking premium pricing for Asian suppliers meeting ICH Q1A standards.
- Pharmacopeial harmonization timing:Early alignment with converging impurity rules positions certified manufacturers for WHO prequalification eligibility.
Industry Challenges
- Bioequivalence study capacity:Qualified clinical research organizations for cardiovascular generics are backlogged, extending approval timelines for new entrants.
- Stability testing infrastructure:Long-term ICH Q1A studies require climate-controlled warehousing that smaller API producers lack capital to construct.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nicorandil Market |
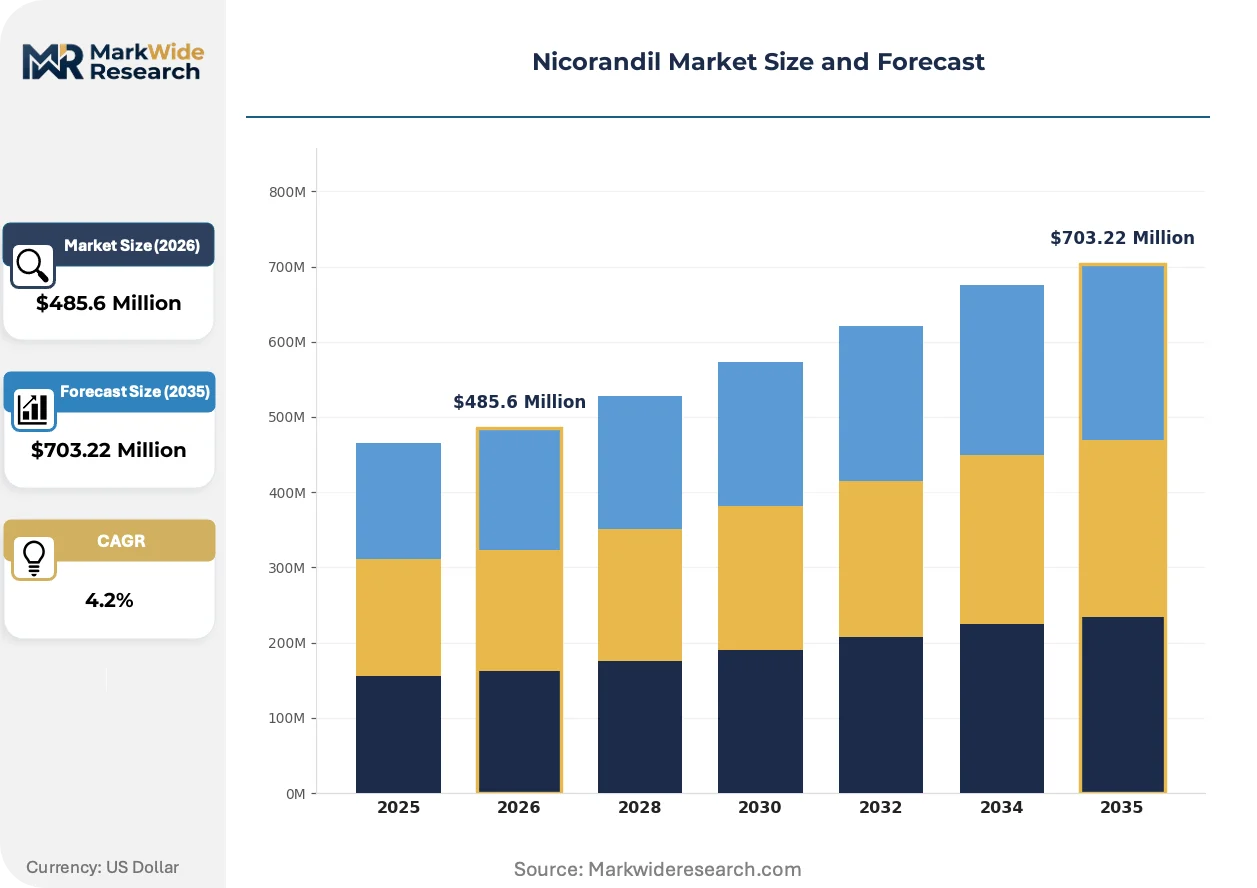
| Market Size in 2026 | $485.6 Million |
| Market Size in 2035 | $703.22 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Formulation Type: Tablet, Injection, Oral Suspension, Topical End User: Hospitals, Outpatient Clinics, Home Care, Pharmacies Distribution Channel: Retail, Wholesale, Online, Direct Sales Disease Indication: Angina Pectoris, Heart Failure, Hypertension, Others |
| Companies Covered | Tonghua Renmin Pharmaceutical Co., Ltd., Shanxi Xinyu Pharmaceutical Co., Ltd., Chugai Pharmaceutical, Pingguang Pharmaceutical Limited, Shijiazhuang No.4 Pharmaceutical Co., Ltd., Henan Topfond Pharmaceutical Co., Ltd., Liaoyuan City Baikang Pharmaceutical Co., Ltd., Cardiacare, Xi'an Han Feng Pharmaceutical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nicorandil Market Trends and Innovations
Batch-certified purity above standard compendial limits is becoming the baseline for hospital tender eligibility, while injection formats capture acute care premium positioning.
Continuous manufacturing for oral solid dosage forms is displacing traditional batch processing in nicorandil tablet production. Tier-1 Chinese manufacturers are adopting flow chemistry for potassium channel opener synthesis to reduce solvent waste and improve batch consistency. This shift is compressing cost structures for pharmacopeial-grade material while raising capital barriers for batch-reactor competitors.
Japan's PMDA maintains ICH Q1A stability standards that shape export eligibility for Asian API suppliers. Manufacturers seeking Japanese market access must generate 36-month accelerated and real-time data packages. Suppliers without existing stability programs are ceding acute care injection contracts to documented competitors.
Hospital tender networks are consolidating procurement authority from individual facilities to provincial consortia. China's Shandong and Hebei provinces now negotiate annual volume contracts covering dozens of tertiary hospitals. This concentration is squeezing supplier margins while rewarding manufacturers with backward integration into API synthesis and captive raw material supply.
Nicorandil Market Segmentation
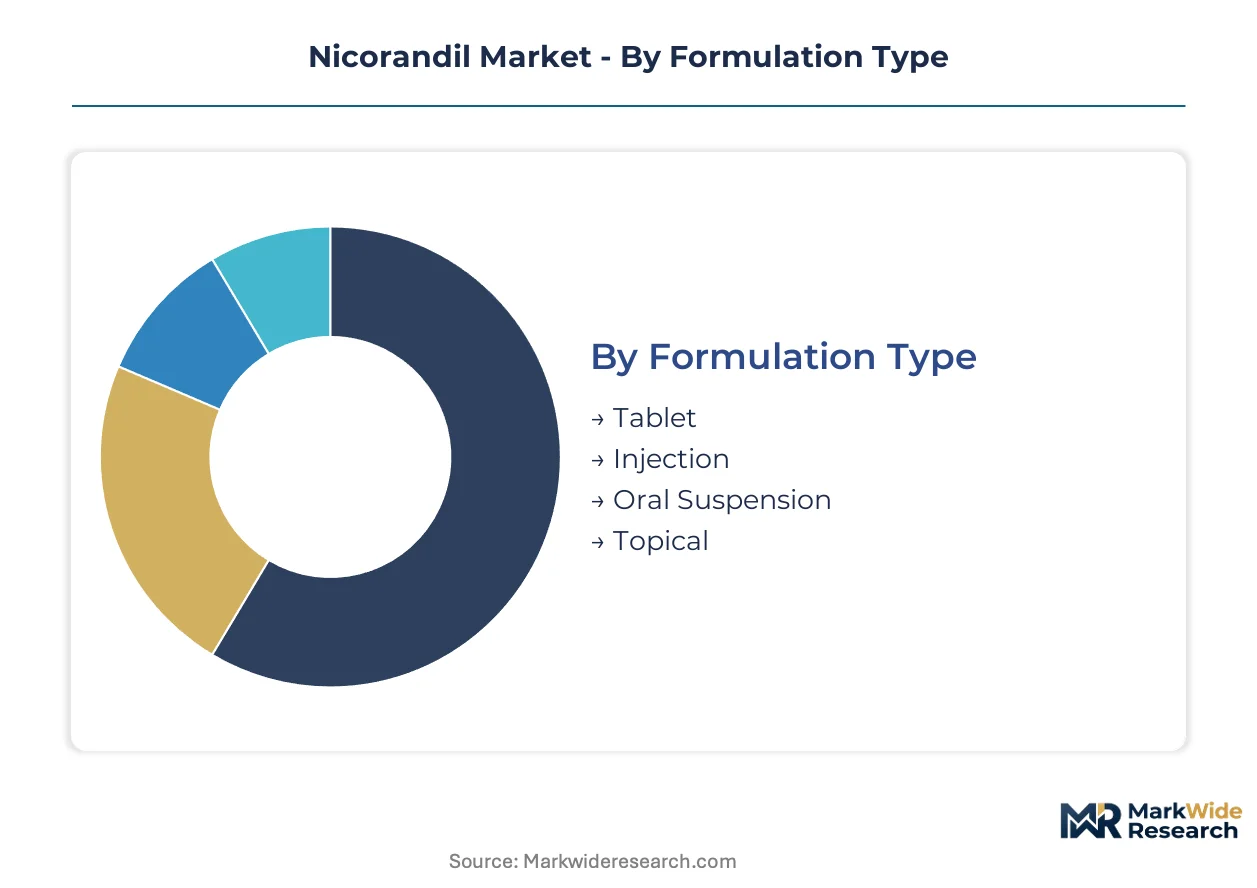
Nicorandil's therapeutic versatility across acute and chronic cardiovascular care creates distinct demand profiles by formulation and delivery setting. Segmentation reveals how procurement centralization, regulatory pathways, and patient acuity reshape competitive positioning across each category.
Formulation Type:
Domestic production concentrates on oral solid dosage forms serving China's hospital tender networks, while injection formats drive export eligibility toward Japan's acute care market.
- Tablet:Standard 5 mg and 10 mg oral formulations dominate procurement volumes through established bioequivalence pathways. China's Shandong and Hebei provinces absorb bulk tablet supply via centralized provincial tenders for maintenance angina therapy.
- Injection:Intravenous presentations command premium positioning in cardiac intensive care units requiring rapid vasodilation onset. Japan's PMDA-aligned stability documentation requirements filter suppliers for STEMI protocol adoption.
- Oral Suspension:Liquid alternatives serve dysphagic patients and pediatric populations where tablet administration fails.
- Topical:Transdermal development remains preclinical with limited commercial penetration in cardiovascular indications.
Tablets hold the largest share; momentum sits with injection formats as acute care protocols expand.
End User:
Cost tier stratification separates high-volume institutional procurement from fragmented outpatient and retail channels.
- Hospitals:Tertiary cardiac centers drive procurement through annual volume contracts covering dozens of facilities. China's provincial consortia in Shandong and Hebei negotiate batch-certified purity thresholds above standard pharmacopeial limits.
- Outpatient Clinics:Post-discharge maintenance protocols extend treatment duration into community-based cardiology practices.
- Home Care:Extended 90-day tablet supplies for stable angina patients are expanding in tier-2 Chinese cities.
- Pharmacies:Retail dispensing captures prescription refills for chronic maintenance therapy outside institutional settings.
Hospitals command the dominant volume position; home care channels are expanding most quickly as discharge protocols lengthen.
Distribution Channel:
Volume concentration favors wholesale networks serving institutional procurement, while digital channels remain nascent for controlled cardiovascular therapies.
- Retail:Pharmacy-level dispensing serves outpatient maintenance prescriptions with limited acute care penetration.
- Wholesale:Distributor networks handle bulk hospital tenders and provincial consortia aggregation across northern China.
- Online:E-pharmacy channels face regulatory constraints for prescription potassium channel openers in most jurisdictions.
- Direct Sales:Manufacturer-to-hospital contracts bypass intermediaries for large-volume tender participants with backward integration into API synthesis.
Wholesale channels capture institutional volume leadership; direct sales are gaining share fastest among integrated manufacturers.
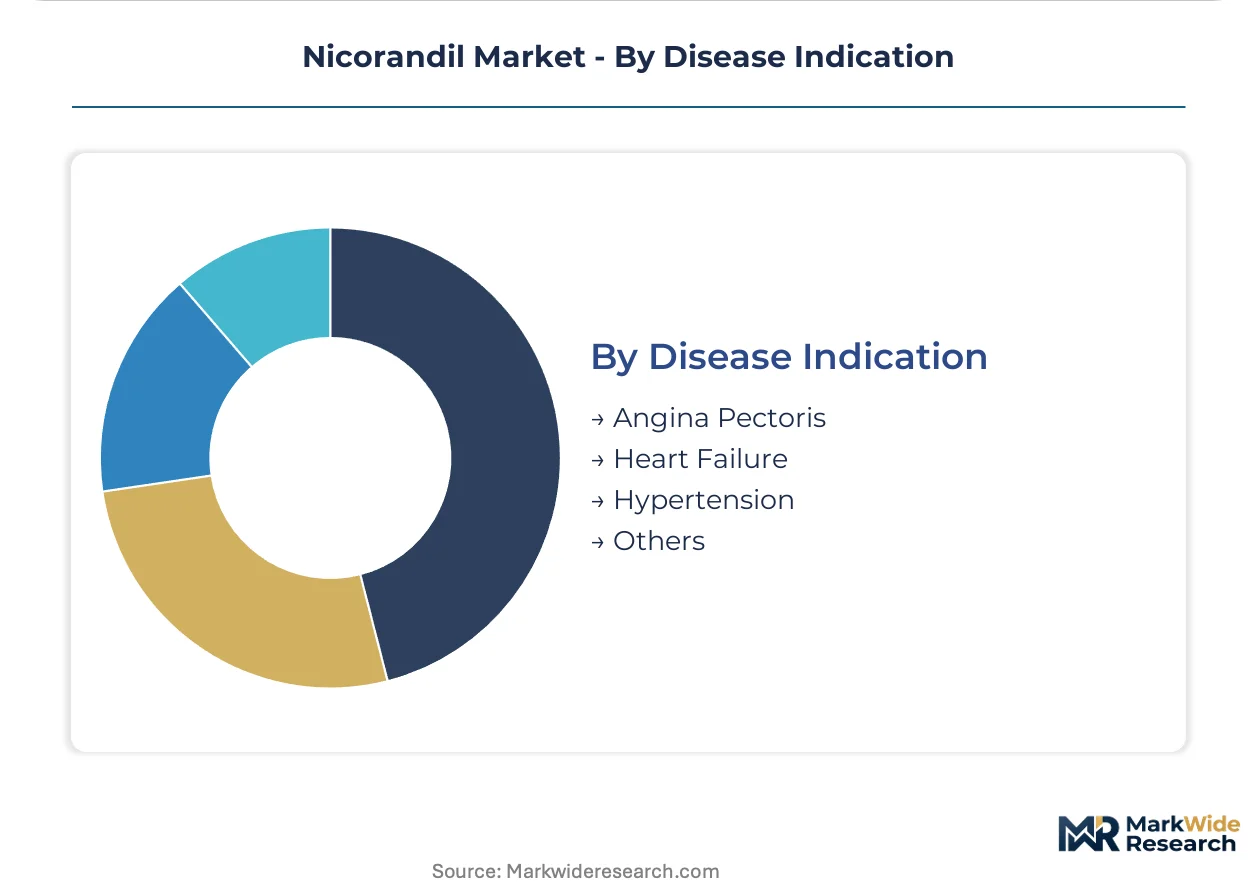
Disease Indication:
Application maturity varies from established angina protocols to exploratory heart failure adjuvant therapy.
- Angina Pectoris:Coronary vasodilation for stable and variant angina represents the core approved indication with longest clinical history. China's NMPA bioequivalence requirements shape generic approval pathways for maintenance therapy expansion.
- Heart Failure:Adjuvant potassium channel opener therapy in acute decompensated settings drives injection format demand in Japanese cardiac units.
- Hypertension:Off-label utilization for resistant hypertension remains limited by competing therapeutic classes.
- Others:Investigational applications in microvascular angina and perioperative cardiac protection occupy preclinical and early clinical stages.
Angina pectoris maintains the foundational revenue base; heart failure applications show the steepest expansion trajectory as acute care protocols evolve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bulk API synthesis clusters in China's Shandong and Hebei provinces, with regulatory divergence between NMPA bioequivalence mandates and Japanese PMDA stability standards fragmenting cross-border supply eligibility.
China
Hospital procurement centralization across Shandong and Hebei provinces drives volume concentration for generic tablet formulations. NMPA tightened bioequivalence study requirements filter subscale manufacturers from tender participation. Jinan and Shijiazhuang host backward-integrated producers capturing provincial consortia contracts through captive API supply.
Japan
Acute cardiac care units in Tokyo and Osaka prioritize injection formats for STEMI protocols requiring rapid vasodilation onset. PMDA enforces ICH Q1A stability standards with 36-month accelerated data packages for API export eligibility. Kanto region hospitals anchor premium pricing for documented suppliers meeting real-time stability benchmarks.
India
Contract manufacturing flows for cardiovascular APIs align with CDSCO harmonization to WHO prequalification norms. Mumbai and Hyderabad house formulation specialists serving export markets through pharmacopeial-grade production. Domestic hospital formularies expand angina maintenance therapy as cardiology protocols broaden.
South Korea
Seoul Capital Area cardiac centers adopt potassium channel openers as adjuvant therapy in heart failure management. MFDS maintains stability documentation requirements compatible with ICH guidelines for regional supply contracts. Busan-Ulsan pharmaceutical corridors process imported APIs for domestic tablet finishing.
Germany
EMA-aligned impurity profiling standards block dual-registered suppliers lacking European Pharmacopoeia certification. Bavaria and North Rhine-Westphalia distribute niche volumes for variant angina cases resistant to standard nitrates. Frankfurt wholesale networks handle limited import flows from Asian API clusters.
Nicorandil Market Competitive Landscape
Concentration sits with backward-integrated pharmaceutical manufacturers controlling potassium channel opener synthesis. Three structural tiers separate provincial tender champions from export-oriented documentation specialists and subscale generic entrants. Competitive moves center on M&A for API capacity capture and strategic partnerships for stability testing infrastructure.
Among Chinese producers, Tonghua Renmin Pharmaceutical Co., Ltd. and Shanxi Xinyu Pharmaceutical Co., Ltd. represent the integrated manufacturing archetype with captive raw material supply, while Chugai Pharmaceutical occupies a position exemplifying Japan-centric regulatory alignment. These three anchors illustrate how geographic regulatory focus determines competitive positioning.
| Leading Market Players |
|---|
| Tonghua Renmin Pharmaceutical Co., Ltd. |
| Shanxi Xinyu Pharmaceutical Co., Ltd. |
| Chugai Pharmaceutical |
| Pingguang Pharmaceutical Limited |
| Shijiazhuang No.4 Pharmaceutical Co., Ltd. |
| Henan Topfond Pharmaceutical Co., Ltd. |
| Liaoyuan City Baikang Pharmaceutical Co., Ltd. |
| Cardiacare |
| Xi'an Han Feng Pharmaceutical Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
China's NMPA bioequivalence certification gates both supplier qualification and price tier differentiation, forcing manufacturers to absorb study costs upfront while capturing premium positioning through batch-certified purity documentation. Hospital procurement centralization in Shandong and Hebei provinces compresses margins for uncertified entrants while rewarding documented producers with volume scale leverage.
Pricing Analysis
PMDA-aligned stability documentation dictates the pricing tier structure for Asian suppliers seeking Japanese market access. Three-tier pricing separates pharmacopeial-grade injection formats for acute cardiac care from standard tablet formulations and uncertified generic alternatives. Price differentiation rests on ICH Q1A certification status and backward integration into potassium channel opener synthesis. Cost compression in standard tablet tiers is intensifying because provincial consortia aggregate purchasing power across dozens of tertiary hospitals. Outpatient clinics and home care segments show highest price sensitivity, while cardiac intensive care units prioritize rapid-onset performance over unit cost.
Supply Chain Analysis
Inventory cycles for potassium channel opener APIs stretch longer than standard cardiovascular actives due to multi-month stability testing requirements. Bulk synthesis clusters in China's Shandong and Hebei provinces, with secondary finishing capacity in Japan and India. Raw material dependencies include 2-hydroxyethylamine derivatives, nicotinic acid precursors, and nitrate esterification reagents. Single-source vulnerability concentrates in environmental compliance exposure at Shandong production bases. Distribution runs through provincial wholesale networks serving hospital tender consortia, with direct manufacturer contracts gaining share among backward-integrated suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
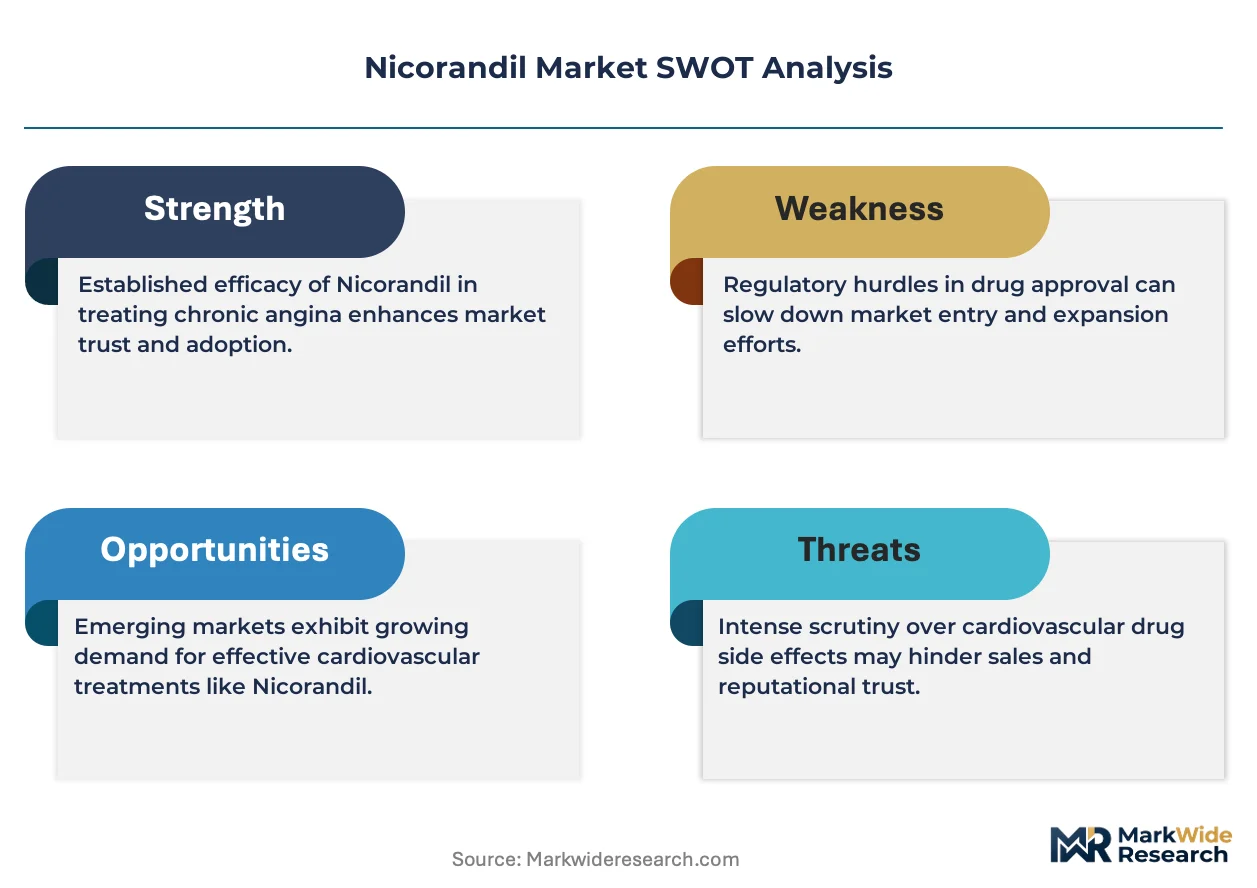
Cardiovascular protocol expansion in Chinese hospital formularies signals early-cycle penetration growth for potassium channel openers as first-line maintenance therapy. Extended post-discharge protocols are lengthening treatment duration and opening outpatient pharmacy channels.
For Market Incumbents: Secure captive API supply through backward integration into Shandong or Hebei production clusters to defend margin position against provincial tender compression. Invest in ICH Q1A stability infrastructure to maintain PMDA-aligned documentation for Japanese export eligibility as ranolazine substitution pressure intensifies in maintenance therapy slots.
For New Entrants and Emerging Players: Lead with bioequivalence study partnerships for injection format approvals targeting Japanese acute cardiac care units, where documentation barriers filter competition. Target tier-2 Chinese cities for 90-day home care tablet supplies, leveraging post-discharge protocol expansion with direct-to-hospital contracts bypassing wholesale intermediaries.
For Investors and Strategic Acquirers: NMPA harmonization with European Pharmacopoeia impurity standards reshapes the acquisition landscape toward manufacturers with pre-positioned dual-registration capability. Five-to-ten year viability favors integrated producers with climate-controlled stability warehousing and captive raw material supply. Watch for WHO prequalification eligibility signals as pharmacopeial convergence timing determines cross-border contract flows.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Synthesis | Captive potassium channel opener production secures Shandong tender eligibility against environmental compliance shutdowns. |
| ICH Q1A Stability Infrastructure Investment | Climate-controlled warehousing generates PMDA-aligned documentation for Japanese acute care injection contracts. |
| Provincial Hospital Consortium Partnerships | Direct annual volume contracts with Shandong and Hebei consortia bypass wholesale margin extraction. |
| Post-Discharge Home Care Channel Development | Ninety-day tablet supplies for tier-2 Chinese cities capture extended maintenance protocol volume. |
| Pharmacopeial Harmonization Alignment | Early European Pharmacopoeia certification positions manufacturers for WHO prequalification eligibility. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital procurement managers, formulary directors at tertiary cardiac centers, regulatory affairs leads at API manufacturers, and provincial tender network administrators. Secondary validation drew from NMPA bioequivalence filings, PMDA stability documentation databases, Chinese provincial procurement disclosure records, and European Pharmacopoeia monograph revision notices. Bottom-up volume estimates from hospital tender aggregation were cross-checked against top-down API production capacity assessments across Shandong and Hebei clusters.
Across the analysis window, projections model formulation type segmentation by tablet, injection, and oral suspension; end-user stratification across hospitals, outpatient clinics, and home care; and distribution channel evolution from wholesale networks toward direct manufacturer contracts. CAGRs were derived from regression analysis of historical tender volume growth correlated with cardiovascular disease protocol expansion indicators. Industry-specific inputs include NMPA approval timeline data and PMDA export eligibility registration flows.
Forecasts assume regulatory continuity in China's NMPA bioequivalence mandates and Japan's PMDA ICH Q1A standards; material policy shifts toward stricter impurity profiling or accelerated stability requirements would demand re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Demerol (Meperidine) Market
Pharmaceuticals
Chemotherapy-Induced Nausea and Vomiting Therapeutics Market
Pharmaceuticals
Global Lidocaine Transdermal Patch Market
Pharmaceuticals
Global Ceftiofur Market
Pharmaceuticals
Anticoagulants Market
Pharmaceuticals
Global Oxytocin Market
Pharmaceuticals
Guanethidine Market
Pharmaceuticals
Croatia Pharmaceutical Market
Pharmaceuticals
Ceftriaxone Market
Pharmaceuticals
Global Shingles Vaccine Market
Pharmaceuticals
Plasma-Derived Protein Therapies Market
Pharmaceuticals
Germany Pneumococcal Vaccines Market
Pharmaceuticals
Asia-Pacific GLP 1 Agonist Market
Pharmaceuticals
Retinal Drugs Market
Pharmaceuticals
North America Novel Drug Delivery Systems (NDDS) Market
Pharmaceuticals
Anticonvulsants Market