
 Asia Pacific Retail Automation Market | 2026-2036
Asia Pacific Retail Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Retail Automation Market Outlook
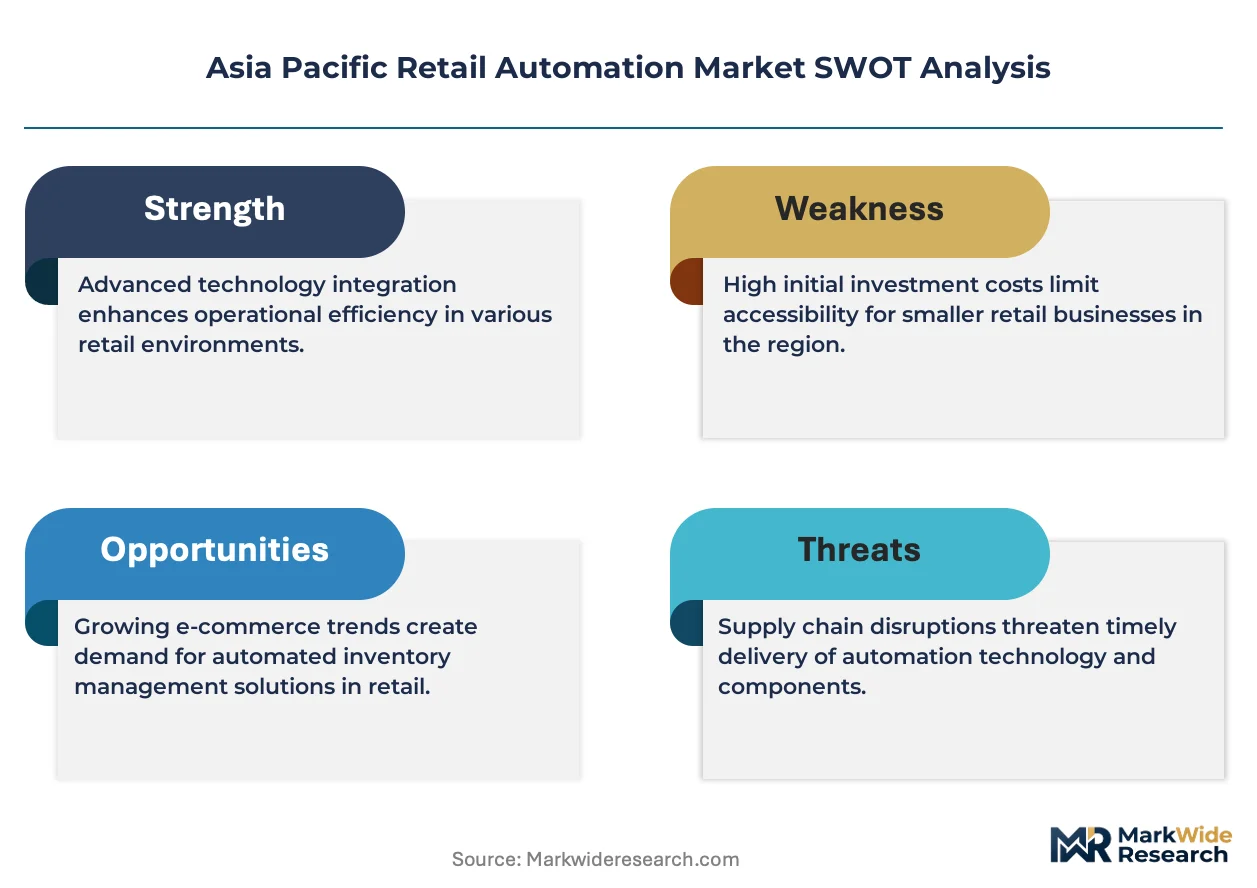
ISO 9001 quality management certification is reorganizing supplier eligibility across the Asia Pacific Retail Automation Market, forcing component vendors to upgrade traceability systems before qualifying for tier-one contracts. Fujitsu Limited leverages its semiconductor heritage to dominate chipset supply for POS terminals across Japan and Taiwan. Zebra Technologies anchors its position through aggressive channel control in Australia's grocery logistics sector. Toshiba Global Commerce Solutions specializes in software-integrated checkout ecosystems that sustain recurring revenue streams.
Retail automation encompasses electromechanical and software systems that execute merchandising, transaction processing, and inventory tracking with minimal human intervention, typically integrating barcode scanning, weight sensors, and payment gateways operating at sub-second response thresholds. Its primary commercial purpose is to compress labor costs per transaction while capturing real-time consumption data for demand forecasting. Self-Service Kiosks lead product type revenue as quick-service restaurants across South Korea and Singapore deploy ordering terminals at scale. Artificial Intelligence within the technology dimension is expanding fastest, powering visual recognition systems that eliminate barcode scanning entirely. Mobile Payment Solutions remain concentrated in China's mature digital wallet ecosystem, though Indonesia and Vietnam are closing adoption gaps.
Japan's METI enforces JIS standards for electromagnetic compatibility in retail terminals, while China's SAMR mandates GB certification for networked payment devices handling biometric data. India's BIS compulsory registration scheme blocks uncertified imports of POS hardware, creating protective conditions for domestic assemblers. Stakeholders must monitor divergence between national data localization rules and cross-border cloud architectures as regulatory fragmentation intensifies deployment complexity.
Market Dynamics
Self-checkout terminal deployment across Southeast Asian supermarkets is compressing labor requirements per transaction while forcing incumbent POS hardware suppliers to reconfigure service revenue models around software subscriptions rather than equipment sales.
Growth Catalysts
- India's PLI scheme for electronics manufacturing:Domestic assemblers now capture preferential access to government incentives when producing POS terminals locally, reducing import dependency for payment hardware.
- Quick-service restaurant automation:South Korean and Singaporean food chains are deploying self-service ordering kiosks at scale to accelerate throughput during peak hours.
- China's unmanned convenience store proliferation:Tier-one cities in the mainland are witnessing rapid rollout of fully automated retail formats that eliminate cashier labor entirely.
Market Restraints
- Semiconductor supply concentration:POS terminal chipset production clusters in Taiwan and South Korea, exposing downstream hardware assemblers to single-source vulnerability during foundry capacity crunches.
- GB certification mandates from China's SAMR:Networked payment devices handling biometric data face extended approval timelines that delay product launches by six to twelve months.
- Legacy barcode infrastructure:Existing inventory management systems in Indonesia and Vietnam require costly retrofitting before visual recognition technologies can achieve full interoperability.
Strategic Opportunities
- Vietnamese mobile payment acceleration:Digital wallet penetration gaps relative to China create first-mover advantage for terminal providers offering integrated QR-code and NFC acceptance.
- Artificial intelligence convergence with edge computing:On-device visual recognition eliminates cloud latency for real-time product identification in high-traffic retail environments.
- Japan's METI electromagnetic compatibility standards:Compliance with JIS certification opens procurement channels to major Japanese retail conglomerates seeking domestically certified terminal suppliers.
Industry Challenges
- ISO 9001 traceability system upgrades:Component vendors must reengineer quality management documentation to qualify for tier-one retail automation contracts, stretching engineering bandwidth.
- Cross-border data localization conflicts:Divergent national rules on cloud architecture storage create deployment complexity for multinational retailers operating standardized POS platforms across multiple jurisdictions.
- Electromechanical integration skill scarcity:The convergence of weight sensors, payment gateways, and barcode scanning at sub-second response thresholds demands specialized firmware engineering talent that remains concentrated in Japan and Taiwan.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Retail Automation Market |
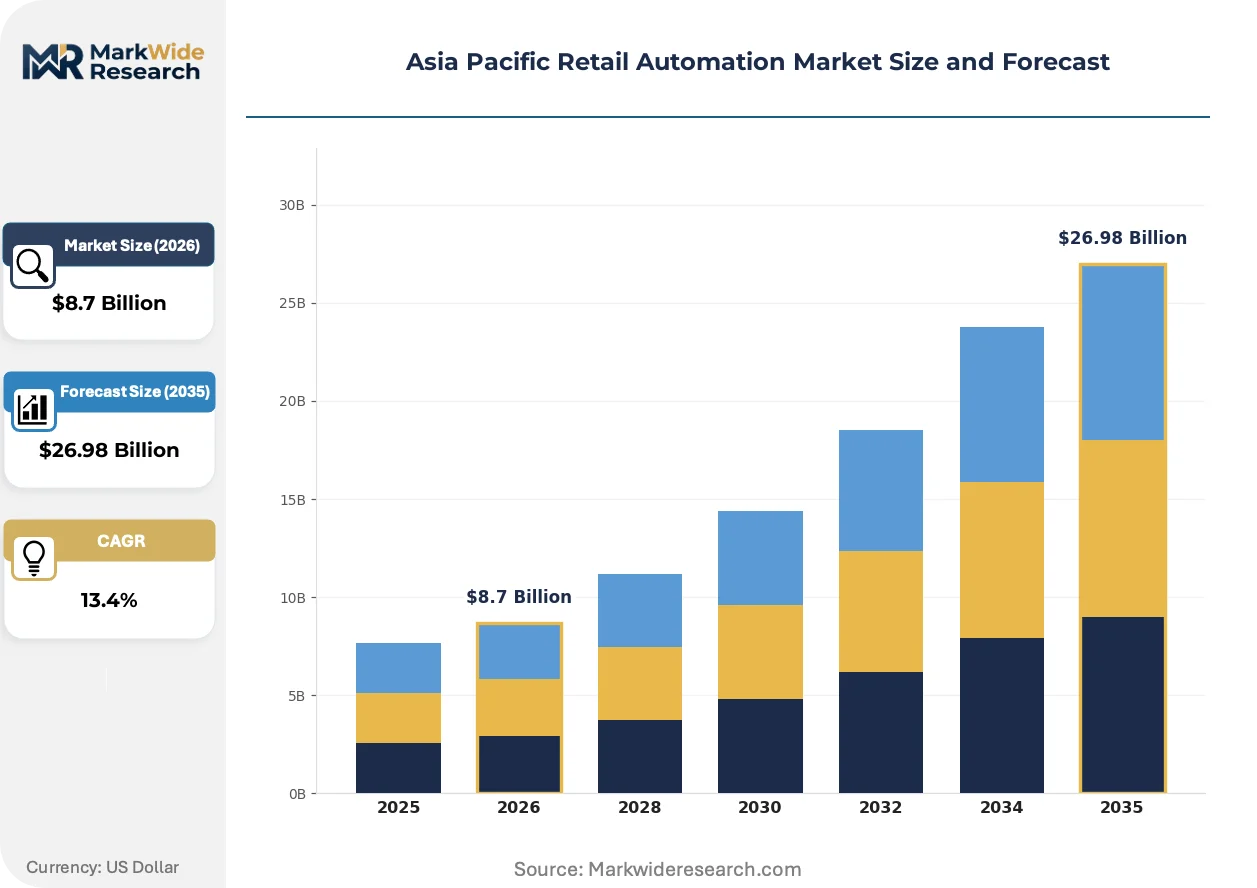
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $26.98 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Service Kiosks, Point of Sale Systems, Inventory Management Solutions, Mobile Payment Solutions Customer Type: Supermarkets, Specialty Retailers, Convenience Stores, E-commerce Platforms Technology: Artificial Intelligence, IoT Solutions, Cloud Computing, Automated Checkout Service Type: Consulting, Implementation, Maintenance, Support |
| Companies Covered | Datalogic S.P.A, Fujitsu Limited, NCR Corporation, Honeywell International Inc., Toshiba Global Commerce Solutions, Seiko Epson Corporation, Zebra Technologies, Diebold Nixdorf, KUKA AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Retail Automation Market Strategic Shifts
Visual recognition systems powered by edge-deployed artificial intelligence are eliminating traditional scanning interfaces across Asia Pacific retail environments, forcing hardware manufacturers to redesign terminal form factors around camera arrays rather than laser-based barcode engines.
Computer vision is displacing conventional barcode scanning in high-volume retail settings. Japanese convenience store operators are piloting camera-based checkout systems that identify products without manual code presentation. This displacement is compressing hardware bill-of-materials costs while shifting value capture toward AI model licensing and cloud-based transaction analytics.
China's SAMR mandates GB certification for all networked payment devices processing biometric authentication data. Hardware manufacturers must submit to extended electromagnetic compatibility and data security testing protocols. Japanese and Taiwanese terminal suppliers are responding by establishing dedicated compliance subsidiaries within mainland China to accelerate approval cycles.
Buyer procurement patterns are fragmenting as Southeast Asian supermarket chains abandon bundled hardware-software contracts in favor of modular component sourcing. Australian grocery logistics operators now separately procure scanning hardware, payment gateways, and inventory management software. This unbundling is most visible in South Korea, where quick-service restaurant chains negotiate directly with AI software vendors while sourcing terminals from competing hardware specialists.
Asia Pacific Retail Automation Market Segmentation
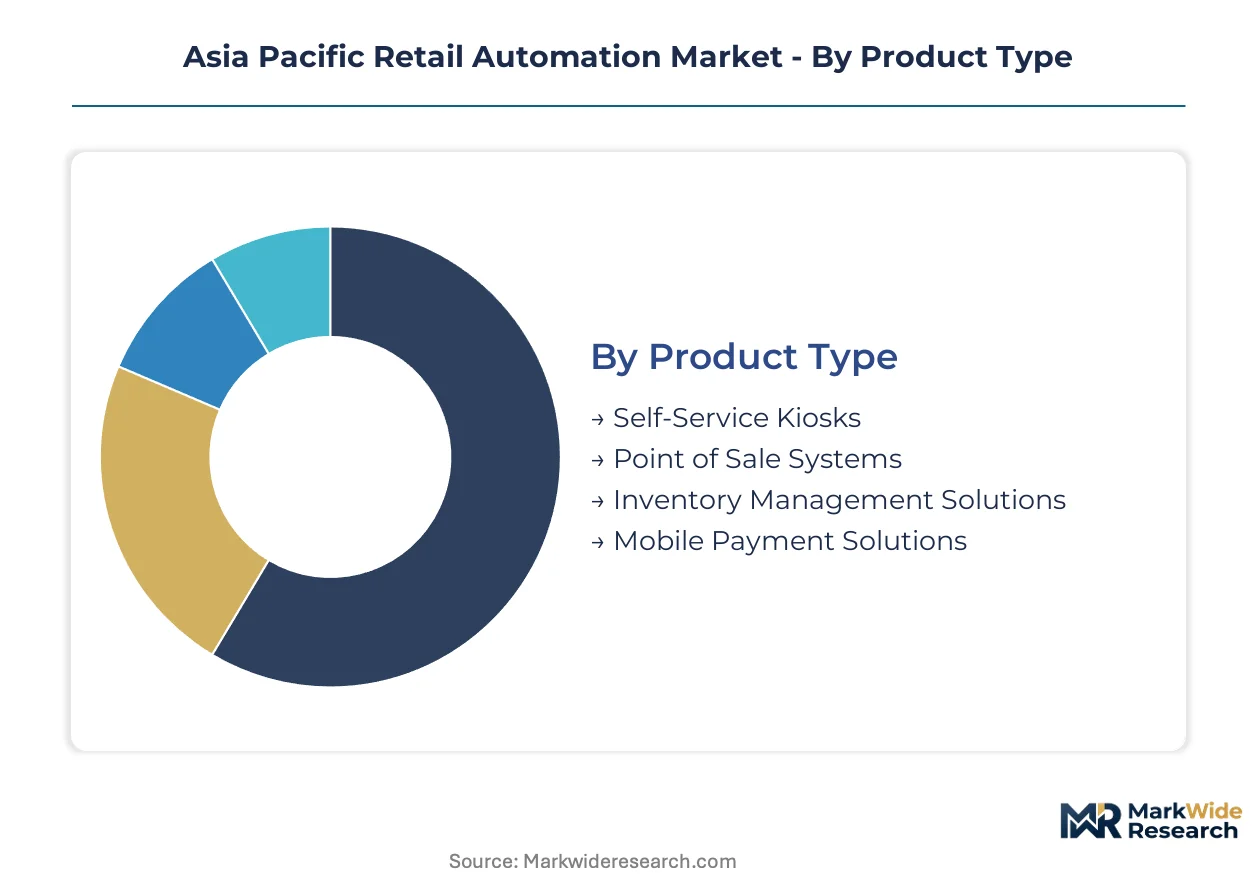
Retail automation procurement patterns diverge sharply across the Asia Pacific region based on store format scale and digital maturity. Understanding these segment boundaries clarifies why hardware vendors reconfigure product portfolios differently for Japanese convenience chains versus Indonesian supermarket operators.
Product Type:
Self-Service Kiosks dominate export-led shipments from Taiwan and South Korea into Southeast Asian markets, while Point of Sale Systems concentrate in domestically oriented production clusters serving China and Japan.
- Self-Service Kiosks:Electromechanical ordering terminals integrating touchscreen interfaces, payment card readers, and thermal printers into floor-standing enclosures. Quick-service restaurant chains across South Korea and Singapore deploy these at scale to compress order-to-fulfillment cycles during peak traffic windows.
- Point of Sale Systems:Countertop transaction processing hardware combining barcode scanners, cash drawers, and receipt printers with embedded operating systems. China's tier-one cities drive concentrated demand as unmanned convenience store operators seek compact, low-latency terminals for 24-hour operations.
- Inventory Management Solutions:RFID-tagged shelving systems and weight-sensor arrays that feed real-time stock data to replenishment algorithms. Japanese retail conglomerates favor domestically certified configurations.
- Mobile Payment Solutions:QR-code scanners and NFC-enabled terminals facilitating digital wallet transactions. Indonesia and Vietnam represent the primary expansion frontier beyond China's mature ecosystem.
Self-Service Kiosks command the established base. The steepest expansion runs through Mobile Payment Solutions.
Customer Type:
Supermarket procurement runs through centralized corporate IT divisions with extended vendor qualification cycles, while Convenience Stores favor rapid-deployment hardware with minimal customization requirements.
- Supermarkets:Large-format grocery operators deploying self-checkout lanes and automated inventory tracking across hundreds of locations. Southeast Asian chains offset labor shortages through terminal deployment at scale.
- Convenience Stores:Small-footprint retailers prioritizing compact, high-throughput automation with 24-hour uptime reliability. Chinese operators in tier-one cities eliminate cashier labor entirely through camera-based checkout systems.
- Specialty Retailers:Category-focused merchants such as electronics or cosmetics chains requiring tailored loyalty program integration.
- E-commerce Platforms:Online-first retailers deploying automated warehousing and last-mile pickup lockers.
Supermarkets anchor current hardware volumes. Convenience Stores are climbing the fastest as unmanned formats proliferate.
Technology:
Artificial Intelligence applications concentrate in high-margin custom development for Japanese and South Korean retail chains, while IoT Solutions spread across standardized hardware platforms for broader Southeast Asian deployment.
- Artificial Intelligence:Edge-deployed computer vision models enabling product identification without barcode scanning. Japanese convenience store operators pilot camera-based checkout that eliminates manual code presentation entirely.
- IoT Solutions:Networked sensor arrays connecting shelving, refrigeration, and lighting systems to centralized management platforms. Australian grocery logistics operators deploy these for cold-chain monitoring.
- Cloud Computing:Remote transaction processing and inventory analytics requiring data localization compliance across fragmented national regulations.
- Automated Checkout:Weight-sensor and camera fusion systems enabling cashierless exit from retail environments.
IoT Solutions command the established base. Artificial Intelligence is gaining share fastest as visual recognition eliminates legacy scanning interfaces.
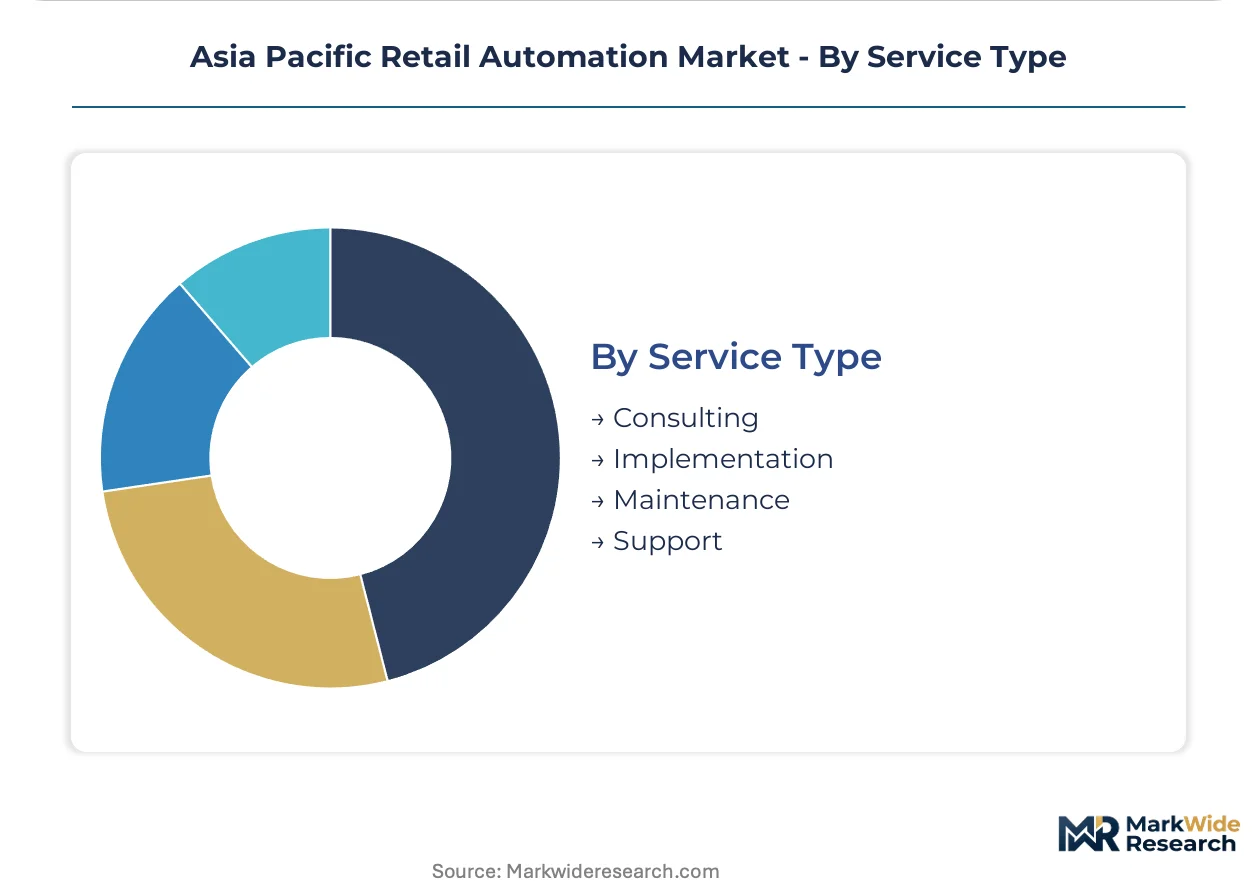
Service Type:
Implementation services cluster around major metropolitan deployments in Shanghai, Tokyo, and Sydney, while Maintenance contracts extend across dispersed Southeast Asian store networks with challenging field access.
- Consulting:Workflow analysis and automation roadmap development for retail chains transitioning from legacy POS infrastructure. Indian supermarket operators engage these services to navigate BIS certification requirements for imported hardware.
- Implementation:Physical installation, software configuration, and staff training for deployed automation systems. South Korean quick-service restaurant chains demand rapid turnaround to minimize revenue disruption.
- Maintenance:Preventive servicing and component replacement ensuring sub-second response thresholds at high-traffic terminals.
- Support:Remote troubleshooting and software update management for distributed retail networks.
Implementation commands the established base. Support is expanding most quickly as software subscription models displace one-time hardware sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for electronics manufacturing is redirecting supply chains toward domestic POS hardware assembly, while China's tier-one cities accelerate unmanned convenience store deployment under SAMR certification mandates. Southeast Asian supermarkets offset labor shortages through self-checkout terminal rollouts.
China
Unmanned convenience stores proliferate across Shanghai, Beijing, and Shenzhen as operators eliminate cashier labor entirely. SAMR mandates GB certification for networked payment devices handling biometric data, extending approval timelines by six to twelve months. The Yangtze River Delta anchors domestic terminal production clusters serving both local deployment and export markets.
Japan
Convenience store operators pilot camera-based checkout systems that identify products without manual barcode presentation. METI enforces JIS standards for electromagnetic compatibility in retail terminals, creating procurement preference for domestically certified suppliers. The Kanto region around Tokyo concentrates firmware engineering talent for sub-second response threshold systems.
India
Domestic assemblers capture preferential access to government incentives when producing POS terminals locally, reducing import dependency for payment hardware. BIS compulsory registration scheme blocks uncertified imports, creating protective conditions for local manufacturers. Maharashtra and Karnataka host emerging electronics manufacturing clusters supplying supermarket chains.
South Korea
Quick-service restaurant chains deploy self-service ordering kiosks at scale to accelerate throughput during peak traffic windows. MFDS alignment with electromagnetic standards supports terminal interoperability across food service applications. Seoul Capital Area drives concentrated demand for AI-powered visual recognition systems.
Australia
Grocery logistics operators procure scanning hardware, payment gateways, and inventory management software through unbundled contracts rather than bundled systems. TGA-equivalent electrical safety standards apply to networked retail equipment deployment. Sydney and Melbourne anchor demand for cold-chain monitoring IoT solutions in automated warehousing.
Asia Pacific Retail Automation Market Competitive Environment
Player mix skews toward diversified technology conglomerates with semiconductor heritage and specialized retail automation pure-plays. Market structure exhibits moderate concentration at the chipset supply tier with downstream fragmentation across terminal assembly. Three archetypes dominate: semiconductor-heritage conglomerates leveraging captive chip supply, retail-focused automation specialists building software-integrated ecosystems, and industrial automation players extending into merchandising applications. Competitive moves center on geographic compliance subsidiaries for certification acceleration and channel control strategies in grocery logistics sectors.
Within the semiconductor-heritage tier, Fujitsu Limited and Toshiba Global Commerce Solutions exemplify players leveraging integrated chipset-to-software capabilities. Fujitsu occupies a position anchored in Japan and Taiwan POS terminal supply chains. Toshiba Global Commerce Solutions represents the software-integrated checkout ecosystem model. Zebra Technologies sits within the specialized retail automation segment, with Australian grocery logistics channel control serving as its geographic anchor point.
| Leading Market Players |
|---|
| Datalogic S.P.A |
| Fujitsu Limited |
| NCR Corporation |
| Honeywell International Inc. |
| Toshiba Global Commerce Solutions |
| Seiko Epson Corporation |
| Zebra Technologies |
| Diebold Nixdorf |
| KUKA AG |
| Others |
Value Chain & Pricing Dynamics
Ninety-day component lead times for POS terminal chipsets compress procurement cycles while amplifying pricing power for Taiwan and South Korea foundries serving downstream hardware assemblers across the Asia Pacific Retail Automation Market. Inventory buffers at Japanese and Australian distribution hubs now determine contract pricing tiers more than volume scale alone.
Pricing Analysis
Certification level creates the primary spread between terminal tiers, with JIS-compliant units commanding substantial premiums over uncertified alternatives in Japanese procurement channels. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 9001 traceability investment, after-sales service bundling, and geographic delivery cost differentials. Cost compression in economy-tier hardware is intensifying because Indian domestic assemblers exploit PLI scheme incentives to undercut import pricing. Quick-service restaurant chains in Southeast Asia exhibit highest price sensitivity, while Japanese convenience store operators prioritize uptime reliability over unit cost.
Supply Chain Analysis
Ninety-day lead times for semiconductor components expose downstream vulnerabilities when foundry capacity tightens unexpectedly. POS terminal production clusters in Taiwan, South Korea, and China draw from concentrated sources of ARM-based chipsets, thermal printers, and camera sensor arrays. Single-source vulnerability in Taiwan foundry output represents the dominant structural risk for hardware assemblers serving tier-one retail contracts. Distribution runs through authorized channel partners in Australia and direct OEM relationships in Japan, with emerging hub-and-spoke logistics developing around Indian electronics manufacturing clusters in Maharashtra and Karnataka.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific Retail Automation Market is approaching a platform-economics inflection where software subscription models decouple value capture from hardware shipment volumes, driven by interoperability mandates between AI-powered visual recognition systems and legacy inventory management infrastructure.
For Market Incumbents: Consolidate firmware engineering capabilities through targeted acquisitions of Japanese and Taiwanese specialists possessing sub-second response threshold expertise, as electromechanical integration skill scarcity threatens service revenue retention. Deepen backward integration into semiconductor supply through captive foundry arrangements or long-term capacity reservations, insulating against Taiwan foundry concentration risk while defending margin position against Indian PLI-subsidized competitors. For New Entrants and Emerging Players: Anchor in Vietnamese mobile payment infrastructure gaps where QR-code and NFC terminal penetration lags China's mature ecosystem by substantial margins, enabling first-mover positioning before incumbent channel lock-in solidifies. Target Indonesian supermarket chains facing labor shortage pressures but lacking capital for full self-checkout lane retrofits, offering modular hardware-software bundles with rapid deployment timelines and minimal customization requirements. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because software-integrated checkout ecosystems generate sticky subscription streams that compound customer lifetime value beyond terminal replacement cycles. Acquisition focus should center on AI software vendors with proven edge-deployed computer vision models and established compliance subsidiaries within mainland China to accelerate SAMR certification timelines. Watch for inflection when unmanned convenience store operators in Chinese tier-one cities achieve sustained profitability without promotional subsidy, signaling hardware-software unit economics maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Subsidiary Establishment | Japanese and Taiwanese suppliers accelerate SAMR GB certification cycles through dedicated mainland China entities. |
| AI Model Licensing Expansion | Computer vision software vendors capture recurring revenue as camera-based checkout displaces barcode scanning interfaces. |
| Channel Control Consolidation | Zebra Technologies and similar specialists lock in Australian grocery logistics procurement through unbundled contract structures. |
| Edge Computing Integration | On-device visual recognition eliminates cloud latency for real-time product identification in high-traffic retail environments. |
| Domestic Manufacturing Scale-Up | Indian assemblers leverage PLI scheme incentives to reduce import dependency for POS terminal hardware production. |
Study Parameters
A standing panel of retail automation hardware procurement managers, POS terminal firmware engineers, supermarket IT directors, and quick-service restaurant operations executives provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with channel partners and OEM account teams across Tokyo, Seoul, Shanghai, Sydney, and Mumbai with secondary validation against customs trade records, BIS registration databases, and SAMR certification filings. Bottom-up shipment estimates from Taiwan and South Korea export data were triangulated against top-down retail automation capex disclosures from major Southeast Asian grocery chains.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product type, customer format scale, technology maturity tier, and service delivery model. CAGRs were derived from curve-fitting observed deployment trajectories against saturation-adjusted penetration ceilings. Industry-specific forecast inputs incorporated JIS and GB certification timeline distributions, PLI scheme incentive uptake rates among Indian assemblers, and mobile payment wallet penetration velocity across Indonesian and Vietnamese markets.
Decision-makers should treat outputs as directional under assumptions of sustained labor cost inflation in Southeast Asian retail and continued SAMR regulatory stringency; material deviation in either factor would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Asia Industry 4.0 Market
Industrial Automation
Mining Automation Solutions Market
Industrial Automation
Modular High-Bay Solutions Market
Industrial Automation
Factory Automation Market
Industrial Automation
Switzerland Industrial Automation Market
Industrial Automation
North America and Europe Retail Automation Market
Industrial Automation
Model Based Manufacturing Technologies Market
Industrial Automation
China Factory Automation and Industrial Controls Market
Industrial Automation
Asia Pacific Industrial Communication Market
Industrial Automation
Sortation Systems Market
Industrial Automation
Europe ICS Market
Industrial Automation
Europe Water Automation and Instrumentation Market
Industrial Automation
Robot Gearboxes Market
Industrial Automation
Linear Actuator Market
Industrial Automation
Europe Sortation Systems Market
Industrial Automation
Global Feeder Automation Market