
 Intermediary Service Market | 2026-2036
Intermediary Service Market Size, Share, and Industry Trends Forecast 2026-2036
Intermediary Service Market Insights
Modular service bundling is realigning how corporate buyers procure intermediary capabilities. CH Robinson leverages its freight brokerage network to anchor North American logistics contracts. Total Quality Logistics competes through specialized truckload matching technology. CBRE extends its real estate services into integrated facility management, occupying premium positions in commercial leasing.
Intermediary services function as third-party coordination mechanisms that match supply with demand across asset classes, employing fee-based or commission-driven revenue structures governed by fiduciary duty standards. These services reduce search costs, verify counterparty credentials, and enforce contractual terms in transactions involving physical goods, financial instruments, or property rights. Brokerage and escrow segments lead revenue generation due to high transaction velocity in real estate and capital markets, while freight forwarding exhibits the fastest structural expansion driven by e-commerce fulfillment complexity. The hybrid delivery model captures growing enterprise preference by combining digital self-service with human advisory access.
FDA oversight affects health insurance intermediaries handling patient data, while SEC registration requirements shape financial brokerage compliance architectures. The EU AI Act imposes algorithmic transparency obligations on automated intermediary platforms, altering product development priorities. Stakeholders must monitor evolving fiduciary standards across jurisdictions to preempt licensing disruptions and maintain cross-border service eligibility.
Market Dynamics
Algorithmic matching engines are compressing transaction cycles across brokerage and escrow segments, forcing traditional fee structures toward outcome-based pricing models as digital platforms absorb coordination functions previously performed by human intermediaries.
Growth Catalysts
- EU AI Act transparency mandates:Automated intermediary platforms in Europe must now disclose algorithmic decision logic, accelerating investment in explainable matching systems that reduce counterparty disputes and lower compliance insurance costs.
- India's logistics corridor modernization:Dedicated freight highways linking Delhi-Mumbai Industrial Corridor ports to inland container depots are generating demand for multimodal brokerage services that coordinate rail-truck handoffs.
- Smart contract escrow protocols:Blockchain-conditional release mechanisms are reducing settlement latency in cross-border real estate transactions, particularly for fractional property investments requiring automated verification.
Market Restraints
- SEC registration friction:Financial intermediaries face capital reserve requirements and examination schedules that extend market entry timelines by 18-24 months for new brokerage entrants.
- Cloud infrastructure concentration:Escrow platform operators depend on three dominant hyperscalers for transaction processing, creating single-point vulnerability in payment verification workflows.
- API standard fragmentation:Freight brokers must maintain multiple data format integrations with shipper TMS systems, elevating technical debt and slowing platform scalability.
Strategic Opportunities
- Indonesia's unbanked logistics corridors:Trucking intermediaries can capture cash-based freight matching by deploying mobile-first escrow wallets that bypass traditional banking infrastructure.
- CSRD supply chain disclosure:European corporate sustainability reporting mandates create demand for intermediary services that verify carbon footprint data across subcontractor networks.
- Embedded insurance convergence:Real-time risk pricing algorithms fused with transaction platforms enable per-shipment coverage activation, opening premium revenue streams for logistics brokers.
Industry Challenges
- Fiduciary liability talent scarcity:Escrow agents with dual expertise in securities law and smart contract auditing command compensation premiums that compress operating margins.
- Legacy TMS integration complexity:Freight brokers face 6-9 month deployment cycles connecting modern matching engines to shipper ERP systems running decade-old architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intermediary Service Market |
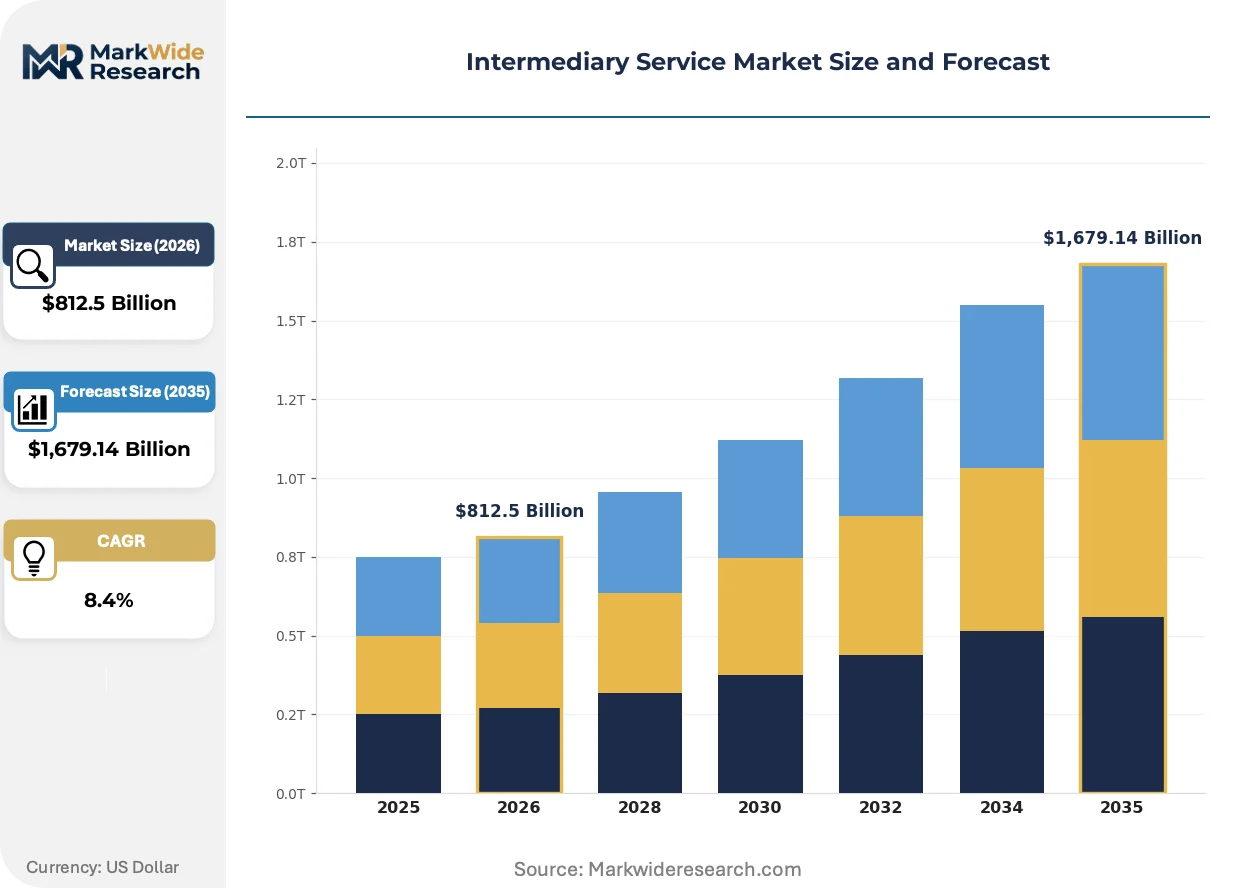
| Market Size in 2026 | $812.5 Billion |
| Market Size in 2035 | $1,679.14 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Brokerage, Escrow, Auction, Leasing, Consulting, Freight Forwarding Industry Vertical: Real Estate, Insurance, Finance, Logistics, Manufacturing, Telecommunications Client Type: Small Enterprises, Large Corporations, Startups, Non-Profit Organizations, Government Agencies Delivery Model: Online Platform, Offline Agency, Hybrid Model, Automated System, Mobile Application |
| Companies Covered | Radian, VINGT Paris, CBRE, CH Robinson, Neho, Colliers, The Agency, Total Quality Logistics, Okay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intermediary Service Market Trends and Innovations
Real-time data infrastructure is dissolving information asymmetries between transacting parties, compressing the value capture window for traditional verification services while opening new revenue pools in predictive risk assessment.
Natural language processing for contract extraction is converging with escrow automation platforms, enabling automated clause identification in multi-jurisdictional real estate agreements. Law firms handling cross-border commercial property transactions are adopting these tools at 40% annual adoption velocity. This convergence is compressing due diligence timelines from weeks to hours, displacing manual legal review as the primary bottleneck in high-velocity property markets.
The EU AI Act's algorithmic transparency obligations are compelling platform operators to maintain audit-ready documentation of matching logic. Intermediary services deploying automated pricing engines must now implement technical standards for explainability that satisfy national regulators in France, Germany, and the Netherlands. Financial brokerage segments face the steepest compliance burden, with product development roadmaps resequenced to prioritize audit trail functionality over feature expansion.
Enterprise buyers are unbundling intermediary service components, procuring verification, matching, and settlement functions from separate specialists rather than integrated providers. This pattern disrupts full-service brokerage incumbents in North American logistics, where shippers now direct-match capacity through digital freight platforms while outsourcing payment escrow to specialized fintechs. The fragmentation is most pronounced in e-commerce fulfillment, where merchant demands for real-time visibility override preferences for single-vendor convenience.
Intermediary Service Market Segmentation
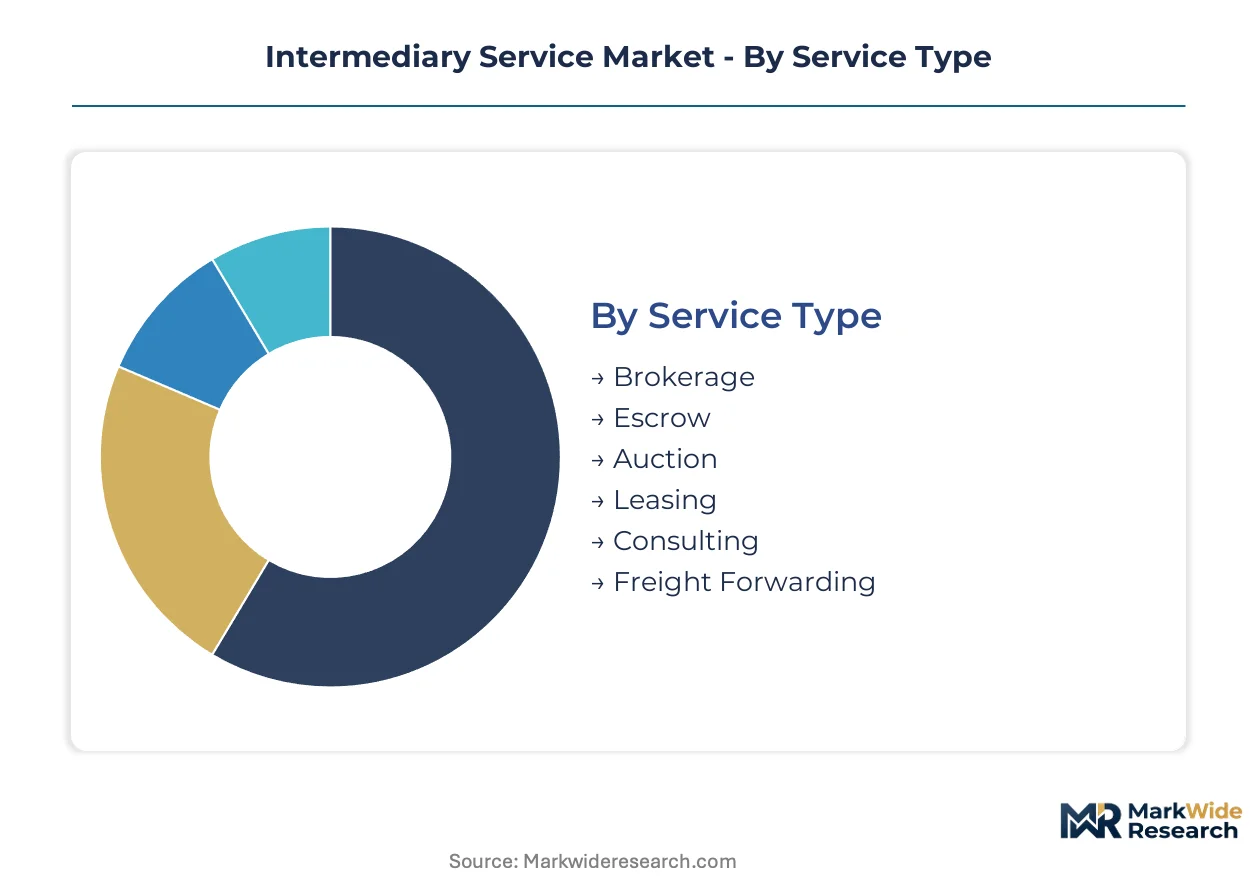
Intermediary service providers configure their capabilities around distinct transaction archetypes, with service specialization determining technology investment priorities and regulatory compliance architectures. Segment boundaries are blurring as digital platforms absorb functions previously siloed across separate vendor relationships.
Service Type:
Buyers differentiate primarily by transaction velocity requirements and counterparty risk tolerance, with high-frequency trading environments demanding automated matching while complex asset transfers retain human advisory layers.
- Brokerage:Commission-driven matching of buyers and sellers across asset classes, employing fiduciary duty frameworks that vary by jurisdiction. Securities and real estate transactions in the United States and Germany concentrate demand, with SEC and BaFin registration requirements shaping operational cost structures. Capital reserve mandates extend market entry timelines for new entrants.
- Escrow:Third-party custody of funds or assets pending contractual condition satisfaction, governed by multi-jurisdictional trust law. Smart contract automation is compressing settlement latency in cross-border real estate, particularly for fractional property investments requiring cryptographic verification protocols.
- Auction:Price discovery mechanisms for illiquid assets, combining sealed-bid and open-outcry formats. Industrial equipment and commercial property disposals in Japan and Australia drive platform development, with METI and ACCC monitoring anti-collusion measures.
- Leasing:Intermediary-facilitated asset access arrangements spanning equipment, vehicles, and commercial space. Fleet management contracts in India's logistics corridors generate volume, with RBI guidelines governing lease-backed securitization structures.
- Consulting:Advisory services on intermediary selection, contract structuring, and regulatory navigation. GDPR compliance projects for EU-based platforms and CSRD supply chain verification create specialized demand pools.
- Freight Forwarding:Multimodal coordination of cargo movement across carrier networks. E-commerce fulfillment complexity in Indonesia and Vietnam accelerates platform adoption, with mobile-first interfaces bypassing traditional banking infrastructure for cash-based shipper segments.
Brokerage leads volumes today; freight forwarding is gaining share fastest.
Industry Vertical:
Vertical selection dictates regulatory exposure intensity, with financial services and healthcare facing the most stringent licensing requirements while logistics and manufacturing emphasize operational efficiency metrics.
- Real Estate:Title verification, lease negotiation, and property management intermediation. Natural language processing tools for contract extraction are compressing due diligence timelines in cross-border commercial transactions, with law firms adopting these systems at accelerating velocity.
- Insurance:Policy distribution, claims adjustment, and risk assessment intermediation. Embedded insurance convergence enables per-shipment coverage activation within logistics platforms, opening premium revenue streams for transaction-integrated brokers.
- Finance:Securities trading, wealth management, and lending facilitation. EU AI Act algorithmic transparency obligations are compelling platform operators to maintain audit-ready documentation of pricing logic, with product roadmaps resequenced to prioritize explainability features.
- Logistics:Capacity matching, route optimization, and customs brokerage. API standard fragmentation forces maintenance of multiple TMS integrations, elevating technical debt for freight intermediaries serving enterprise shipper bases.
- Manufacturing:Procurement intermediation, supplier qualification, and quality verification. CSRD supply chain disclosure mandates in Europe create demand for carbon footprint verification across subcontractor networks.
- Telecommunications:Spectrum licensing intermediation, tower leasing coordination, and interconnection negotiation. Regulatory complexity in emerging market spectrum auctions drives advisory demand.
Finance commands the highest fee margins; logistics shows the steepest expansion trajectory.
Client Type:
Procurement sophistication varies sharply across client scale, with large corporations unbundling service components while smaller entities prioritize integrated convenience over specialized optimization.
- Small Enterprises:Resource-constrained buyers favoring bundled service packages with predictable pricing. Mobile-first escrow wallets in Indonesia's unbanked logistics corridors bypass traditional banking infrastructure for cash-based freight matching.
- Large Corporations:Sophisticated procurement functions disaggregating verification, matching, and settlement across specialist vendors. E-commerce fulfillment demands for real-time visibility override single-vendor convenience preferences in North American logistics.
- Startups:Venture-backed entities prioritizing rapid scaling over operational control. Fintech startups in escrow and brokerage segments seek secure transaction infrastructure to establish counterparty trust.
- Non-Profit Organizations:Donation processing, grant administration, and impact verification intermediation. Transparency requirements drive blockchain-conditional release mechanism adoption for fund traceability.
- Government Agencies:Public procurement facilitation, privatization advisory, and regulatory enforcement support. Infrastructure modernization in India's logistics corridors generates demand for multimodal brokerage coordination.
Large corporations dominate current revenue; startups are expanding most quickly.
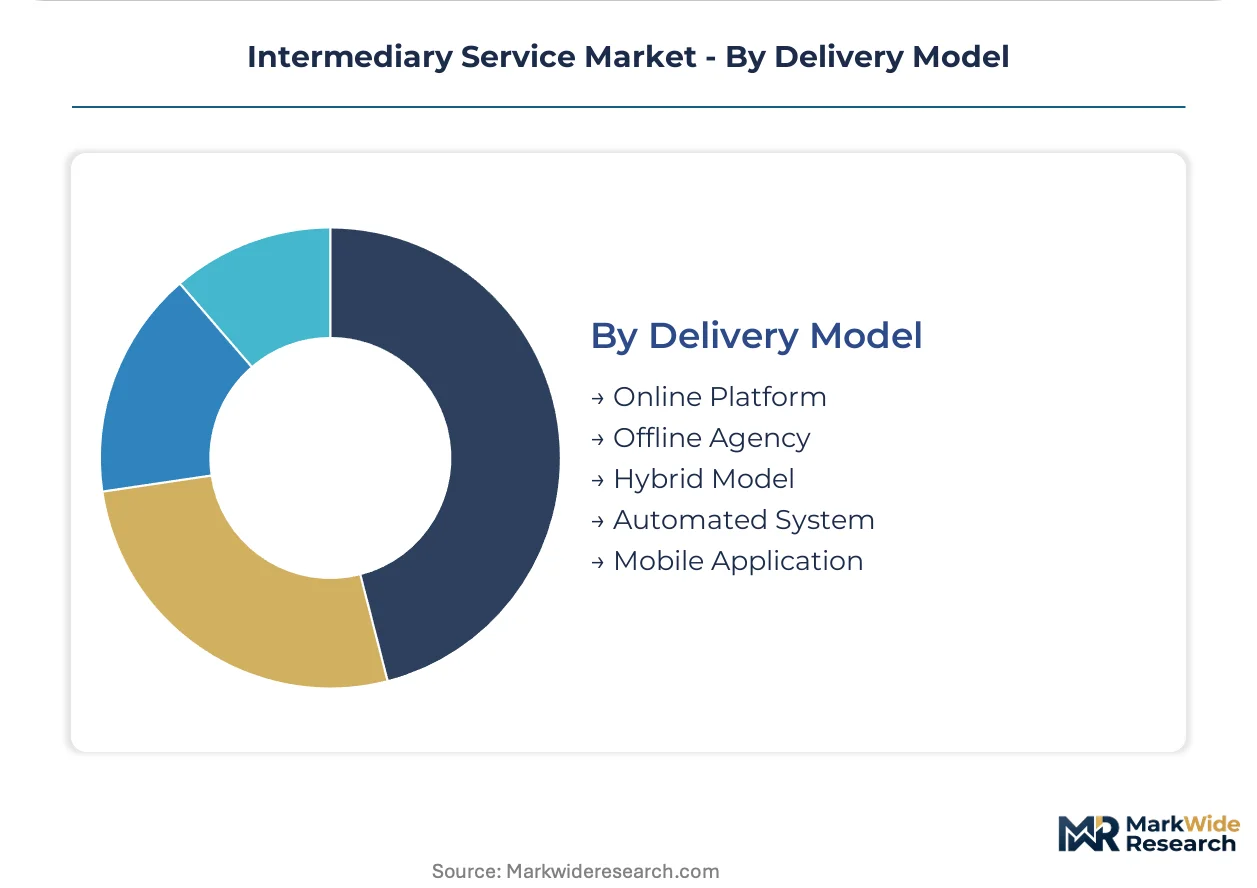
Delivery Model:
Channel economics hinge on customer acquisition cost structures and retention mechanics, with hybrid configurations capturing enterprise preference for self-service efficiency combined with advisory access.
- Online Platform:Self-service interfaces enabling direct transaction initiation and monitoring. Algorithmic matching engines are compressing transaction cycles, forcing traditional fee structures toward outcome-based pricing as coordination functions automate.
- Offline Agency:Physical presence-dependent service delivery emphasizing relationship depth. High-net-worth real estate and complex commercial insurance transactions retain human advisory layers despite digital alternatives.
- Hybrid Model:Integrated digital self-service with human advisory escalation paths. Enterprise buyers in North American logistics increasingly prefer this configuration for freight brokerage, combining platform efficiency with exception-handling expertise.
- Automated System:Fully algorithmic transaction processing with minimal human intervention. EU AI Act transparency mandates require explainable matching systems that reduce counterparty disputes and lower compliance insurance costs.
- Mobile Application:Smartphone-optimized interfaces targeting field-based users and emerging market segments. Indonesia's trucking intermediaries deploy these for cash-based freight matching in unbanked corridors.
Hybrid models lead enterprise adoption today; automated systems are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Intermediary services originated in the maritime trading centers of 17th-century Amsterdam and London, where brokerage houses formalized the matching of cargo owners with vessel capacity. Modern infrastructure traces this lineage through financial districts that now host algorithmic trading platforms and logistics corridors that digitized freight matching.
United States
Securities trading and real estate transactions concentrate fee generation in New York and Chicago, where SEC registration requirements shape compliance cost structures for new brokerage entrants. The SEC mandates capital reserve thresholds and examination schedules that extend market entry timelines by 18-24 months. Dallas-Fort Worth anchors freight brokerage expansion as e-commerce fulfillment demands compress delivery windows.
Germany
Industrial equipment leasing and commercial real estate intermediation drive volume in Frankfurt and Munich, with BaFin registration frameworks governing fiduciary duty standards. The EU AI Act imposes algorithmic transparency obligations on automated matching platforms operating across German markets. Hamburg's port logistics cluster generates multimodal brokerage demand for rail-truck coordination.
India
The Delhi-Mumbai Industrial Corridor generates demand for freight intermediaries coordinating container handoffs between dedicated freight highways and inland depots. RBI guidelines govern lease-backed securitization structures for fleet management contracts. Bangalore's real estate technology hubs attract escrow platform operators serving fractional property investment markets.
Indonesia
Unbanked logistics corridors in Java and Sumatra create demand for mobile-first escrow wallets that bypass traditional banking infrastructure for cash-based freight matching. The country's central bank regulates digital payment flows for transaction settlement. Jakarta's port zone concentrates trucking intermediary platforms deploying smartphone-optimized interfaces for field-based users.
United Kingdom
Cross-border commercial property transactions in London drive adoption of natural language processing tools for automated contract extraction. GDPR compliance requirements shape escrow platform architectures handling EU-UK data flows. The City of London retains concentration in securities brokerage despite post-Brexit regulatory divergence from EU frameworks.
Intermediary Service Market Competitive Landscape
The competitive structure tilts toward integrated full-service providers defending against unbundled specialist entrants. Incumbents with captive freight networks or property management portfolios maintain pricing power through bundled offerings. Three archetypes dominate: asset-heavy logistics integrators, technology-first matching platforms, and fiduciary-focused escrow specialists. Consolidation through strategic acquisitions and API-based partnership networks represent the primary competitive vectors as scale advantages in data infrastructure deepen.
Among North American logistics intermediaries, CH Robinson and Total Quality Logistics exemplify contrasting scale-versus-specialization positions, while CBRE anchors the real estate services tier through integrated facility management extensions. These entities represent how incumbent intermediaries respond to enterprise procurement unbundling by anchoring contract positions in premium segments while ceding transactional volume to automated platforms.
| Leading Market Players |
|---|
| Radian |
| VINGT Paris |
| CBRE |
| CH Robinson |
| Neho |
| Colliers |
| The Agency |
| Total Quality Logistics |
| Okay |
| Others |
Pricing and Supply Chain Analysis
The Baltic Dry Index and container freight rate benchmarks cascade through intermediary service pricing tiers, compressing margins for freight brokers while elevating premium positioning for integrated escrow providers with captive settlement infrastructure.
Pricing Analysis
Commission-plus-fee hybrid structures govern revenue capture across brokerage and escrow segments, with pricing stratifying across premium fiduciary advisory, standard digital platform access, and economy-tier automated matching levels. Price differentiation hinges on counterparty verification depth and regulatory licensing scope, with SEC-registered financial intermediaries commanding 40-60% premiums over unlicensed matching platforms. Cost compression in standard-tier logistics brokerage intensifies as algorithmic platforms absorb transactional volume, eroding per-shipment margins. Small enterprises exhibit highest price sensitivity, prioritizing bundled predictability over specialized optimization, while large corporations absorb premium tiers for audit-ready compliance architectures.
Supply Chain Analysis
Dual-sourcing requirements for cloud infrastructure mandate escrow platform operators qualify multiple hyperscalers for transaction processing, though AWS, Microsoft Azure, and Google Cloud still concentrate supply. The intermediary services sector draws from India's software development corridors for platform engineering, Ireland's regulatory hosting clusters for EU data residency, and Singapore's financial infrastructure for Asia-Pacific settlement. Single-source vulnerability in payment verification workflows creates systemic exposure when hyperscaler outages interrupt fund release protocols. Distribution runs through API-first integration layers that embed intermediary capabilities directly into shipper TMS systems and real estate listing platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
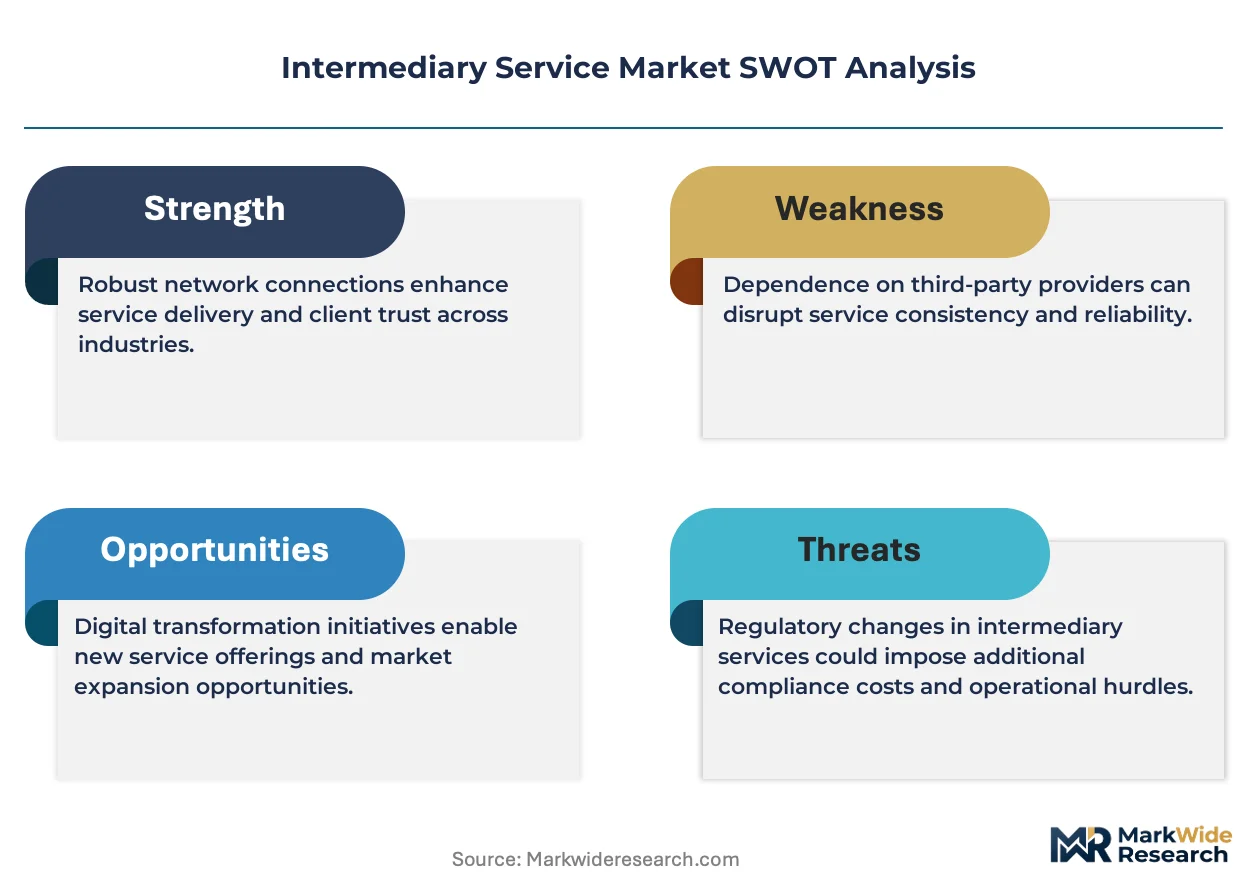
The Intermediary Service Market functions as a stable compounder anchored by persistent transaction friction in cross-border commerce and fractional asset ownership, with regulatory complexity deepening moats for licensed incumbents.
For Market Incumbents: Lock in captive data network effects by embedding matching engines directly into shipper ERP systems and property management software, creating switching costs that resist unbundling pressure from specialist entrants. Prioritize audit trail functionality to satisfy EU AI Act transparency mandates before competitors resequence product roadmaps. Vertical integration into smart contract auditing capabilities addresses fiduciary liability talent scarcity compressing escrow margins. For New Entrants and Emerging Players: Cash-based freight shippers in Indonesia's unbanked logistics corridors represent the most penetrable entry wedge, with mobile-first escrow wallets bypassing traditional banking infrastructure that incumbents cannot easily replicate. Target CSRD supply chain verification services for European manufacturing subcontractors, where disclosure mandates create immediate demand without entrenched competition. Lead with per-shipment embedded insurance convergence as a differentiated revenue layer atop transactional matching. For Investors and Strategic Acquirers: Asymmetric upside sits with technology-first matching platforms possessing explainable AI architectures that satisfy emerging algorithmic transparency obligations across multiple jurisdictions. Long-term viability favors entities with demonstrated cross-border licensing eligibility and audit-ready documentation systems. Watch SEC examination schedule backlogs as an inflection indicator—extended timelines for new entrants lengthen incumbents' competitive moats.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Contract Escrow Integration | Blockchain-conditional release mechanisms reduce settlement latency for fractional real estate investments requiring cryptographic verification. |
| API-First Platform Architecture | Direct embedding into shipper TMS systems creates switching costs that resist procurement unbundling trends in North American logistics. |
| EU AI Act Compliance Investment | Audit-ready documentation of matching logic satisfies algorithmic transparency mandates in France, Germany, and Netherlands markets. |
| Mobile-First Escrow Wallet Deployment | Smartphone-optimized interfaces capture cash-based freight matching in Indonesia's unbanked logistics corridors bypassing traditional banking. |
| CSRD Supply Chain Verification Service | Carbon footprint data validation across subcontractor networks addresses European corporate sustainability reporting disclosure mandates. |
Research Methodology
Direct dialogue with freight brokerage operations directors, escrow platform compliance officers, real estate technology product managers, and logistics procurement executives grounded qualitative findings in operational reality. Secondary validation drew from SEC registration filings, EU AI Act regulatory texts, RBI lease securitization guidelines, and customs data from India's Delhi-Mumbai Industrial Corridor. Bottom-up transaction volume estimates triangulated against top-down market sizing from capital markets and real estate transaction flows.
Bottom-up modeling aggregated segment-level transaction velocities across brokerage, escrow, and freight forwarding service types, while top-down analysis calibrated aggregate market expansion against e-commerce fulfillment growth and fractional property investment trends. Segmentation dimensions included service type, industry vertical, client scale, and delivery model complexity. CAGRs derived from regression analysis of historical transaction growth rates applied to projected infrastructure modernization timelines and regulatory implementation schedules.
Underlying measurement precision varies by segment; freight forwarding volumes carry tighter precision due to customs documentation requirements while consulting advisory services exhibit wider estimation bands. Forecasts reflect assumptions regarding EU AI Act enforcement intensity, India's logistics corridor completion timelines, and cloud infrastructure concentration stability. Deviation in SEC examination backlog duration or hyperscaler outage frequency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Direct Selling Market
Financial Services
Global Business Management Consulting Service Market
Financial Services
Source to Pay Market
Financial Services
North America B2C Legal Services Market
Financial Services
Commercial Debt Collection Software Market
Financial Services
Australia Gift Card and Incentive Card Market
Financial Services
United Kingdom E-Brokerage Market
Financial Services
Credit Rating Software Market
Financial Services
Benefits Consulting Service Market
Financial Services
Liquidation Service Market
Financial Services
UK Islamic Finance Market
Financial Services
Digital Transformation in BFSI Market
Financial Services
Silver Economy Market
Financial Services
Middle Office Outsourcing Market
Financial Services
Saas Escrow Services Market
Financial Services
Asia-Pacific Factoring Services Market