
 Direct Selling Market | 2026-2036
Direct Selling Market Size, Share, and Industry Trends Forecast 2026-2036
Direct Selling Market Intelligence
Commission structures tied to social commerce platforms are reconfiguring the traditional distributor compensation model. This shift prioritizes digital engagement and online influence over conventional in-person sales tactics. Amway leverages its established global network to integrate new digital tools for its independent business owners. In contrast, Herbalife Nutrition specializes in the health and wellness segment, using targeted marketing to connect with consumers focused on nutritional supplements. Primerica operates with a focus on financial services, a distinct niche within the direct sales industry.
Direct selling is a business model that markets and sells products directly to consumers, bypassing a traditional retail infrastructure. This model often utilizes independent contractors who earn commissions based on personal sales and, in some cases, the sales of their recruited network. While Cosmetics and Home Goods are mature product categories, Nutritional Supplements represent the fastest-growing segment. The Online sales channel is rapidly displacing legacy methods like Parties and Catalogs, driven by distributor and consumer preference for digital platforms.
Regulatory oversight significantly shapes market conduct and protects consumers from unfair practices. The US Federal Trade Commission (FTC) actively polices misleading income claims and pyramid scheme structures. Similarly, China's State Administration for Market Regulation (SAMR) and various consumer protection authorities in the European Union enforce strict rules on product advertising and business opportunity representations. Future success depends on a company's ability to navigate evolving digital marketing regulations and maintain consumer trust across diverse legal jurisdictions.
Market Dynamics
The central force shaping the direct selling market is the rapid digitalization of distributor networks and consumer engagement. This shift from in-person relationships to algorithmically-enhanced social commerce is fundamentally altering compensation models, training requirements, and the competitive landscape for all participants.
Growth Catalysts
- AI-Driven Personalization:The integration of artificial intelligence tools allows for hyper-targeted product recommendations and customized marketing content, increasing sales conversion rates for independent distributors and enhancing the consumer experience.
- Emerging Market Demographics:High-growth economies, particularly India, possess large, youthful, and digitally-native populations that are highly receptive to social commerce and entrepreneurial opportunities presented by direct selling models.
- Wellness Consumption Patterns:A sustained consumer pivot towards proactive health management and preventative care directly fuels expansion in the nutritional supplements category, which represents the fastest-growing product segment.
Market Restraints
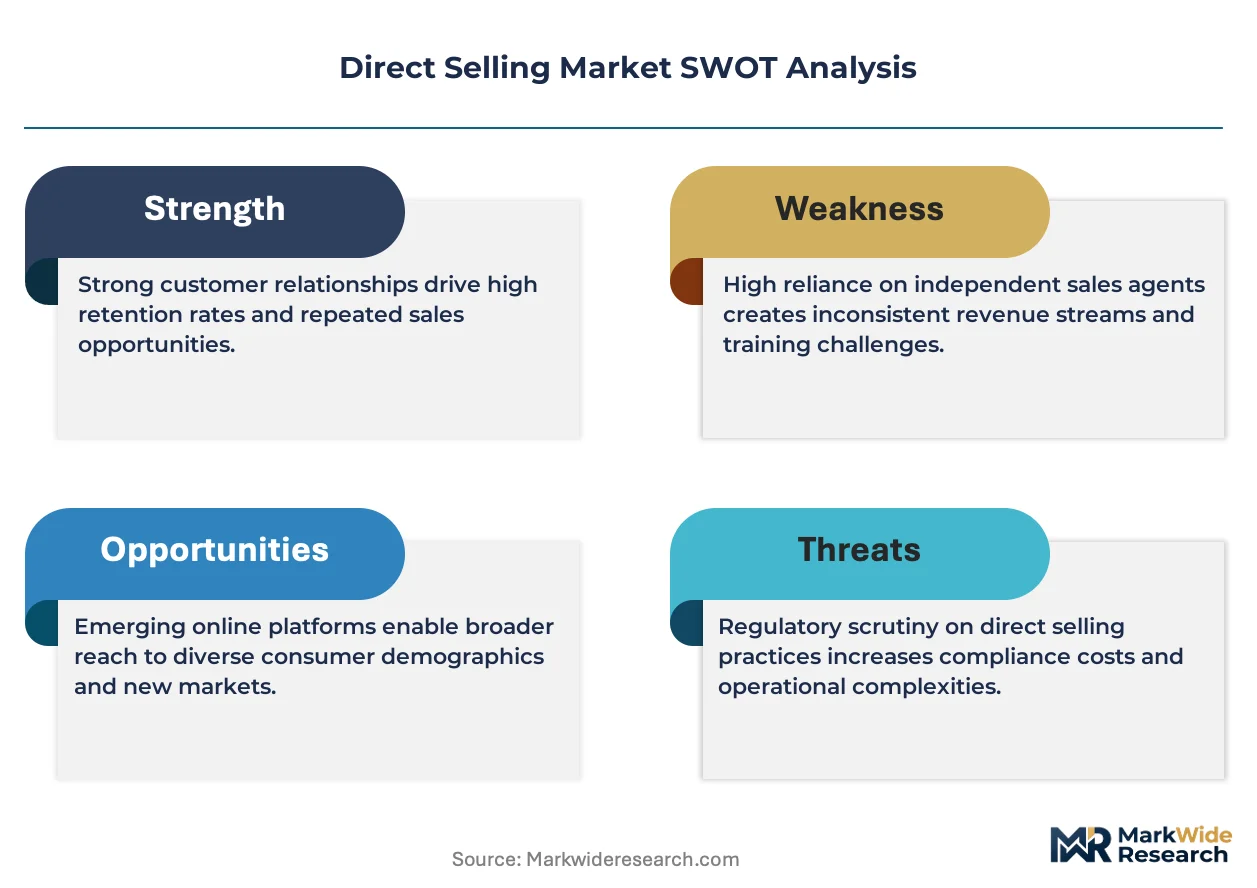
- Intensified Regulatory Scrutiny:Authorities like the US Federal Trade Commission (FTC) and China's SAMR are enforcing stricter rules against pyramid structures and misleading income claims, creating significant compliance burdens and legal risks.
- E-commerce Substitution:The proliferation of direct-to-consumer brands on massive online marketplaces presents a powerful alternative, offering consumers similar products without the multi-level distributor infrastructure.
- Negative Public Perception:Lingering reputational issues and public stigma associated with multi-level marketing business models can create significant headwinds in distributor recruitment and customer acquisition efforts.
Strategic Opportunities
- Hyper-Niche Community Building:Companies can foster dedicated online communities around specific interests, such as vegan nutritional products or eco-friendly home care, creating loyal customer bases and highly effective sales channels.
- Technology Convergence:The fusion of social commerce with augmented reality (AR) presents opportunities for virtual "try-on" experiences, particularly within the cosmetics and personal care segments, driving engagement and sales.
- Financial Services Integration:Expanding beyond physical products into financial services, as demonstrated by niche players, offers a pathway to capture greater consumer wallet share and create stickier customer relationships.
Industry Challenges
- Digital Skill Gaps:A significant portion of the existing distributor base lacks the sophisticated digital marketing, content creation, and analytics skills required to compete effectively in a social commerce-driven environment.
- Cross-Border Compliance Complexity:Navigating the fragmented and evolving landscape of international regulations governing e-commerce, data privacy under frameworks like GDPR, and digital advertising is a major operational hurdle.
- Legacy System Integration:Established direct selling companies face difficulties integrating modern, agile social commerce and AI platforms with their older, often rigid, back-end systems for commissions and logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Direct Selling Market |
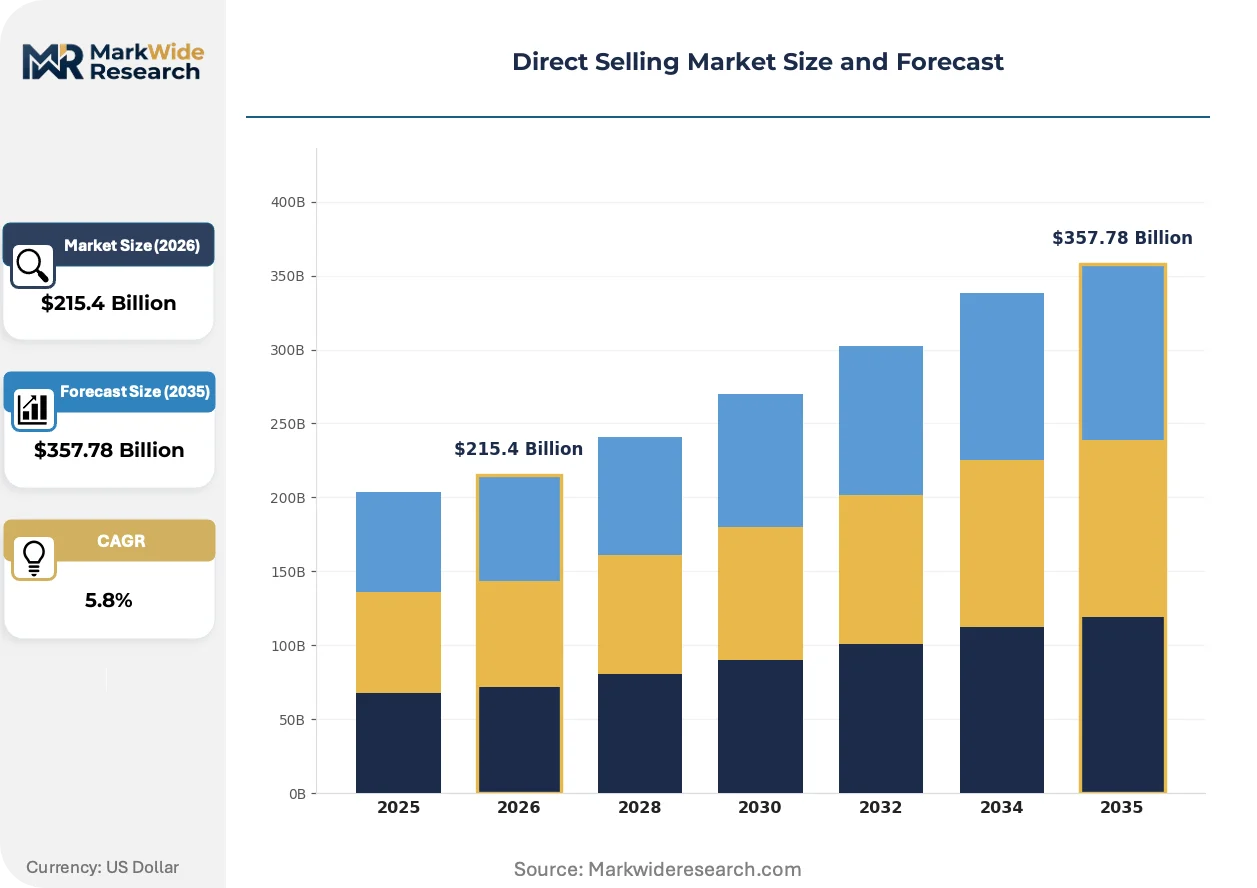
| Market Size in 2026 | $215.4 Billion |
| Market Size in 2035 | $357.78 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetics, Nutritional Supplements, Home Goods, Clothing Sales Channel: Online, In-Person, Parties, Catalogs Customer Type: Retail Consumers, Business Owners, Event Planners, Influencers Distribution Channel: Independent Distributors, Affiliate Marketers, Wholesalers, Direct Agents |
| Companies Covered | Natura & Co, PM-International, Amway, Coway, Primerica, Herbalife Nutrition, Vorwerk, Mary Kay, eXp Realty, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Direct Selling Market Strategic Shifts & Innovations
The market's evolution is defined by the digitalization of relationship-based selling. This transition is moving the core value proposition from personal networks to curated online communities, powered by sophisticated data analysis and content strategies.
AI-powered personalization engines are a key technological development, analyzing vast datasets to generate predictive insights on consumer behavior. Independent distributors are the primary adopters, using these tools to automate lead generation and customize outreach at scale. The use of this technology is collapsing the time and effort required to identify and cultivate sales prospects, transforming a traditionally manual process.
Heightened regulatory oversight from bodies like the US Federal Trade Commission and the European Union's consumer protection authorities is a defining trend. This scrutiny compels companies to ensure their business opportunity representations and income claims are transparent and substantiated. The distributor recruitment and compensation plan design segments are most affected, forcing a strategic shift towards prioritizing retail product sales over network expansion.
Consumer purchasing behavior shows a clear migration from generalized product catalogs to authentic, influencer-led recommendations within digital communities. This shift disrupts the traditional party-plan and door-to-door sales channels, which are being replaced by live-streaming sales events and targeted social media campaigns. This trend is most prominent within the cosmetics and nutritional supplement categories, especially in markets across Asia with high social media engagement.
Direct Selling Market Segmentation
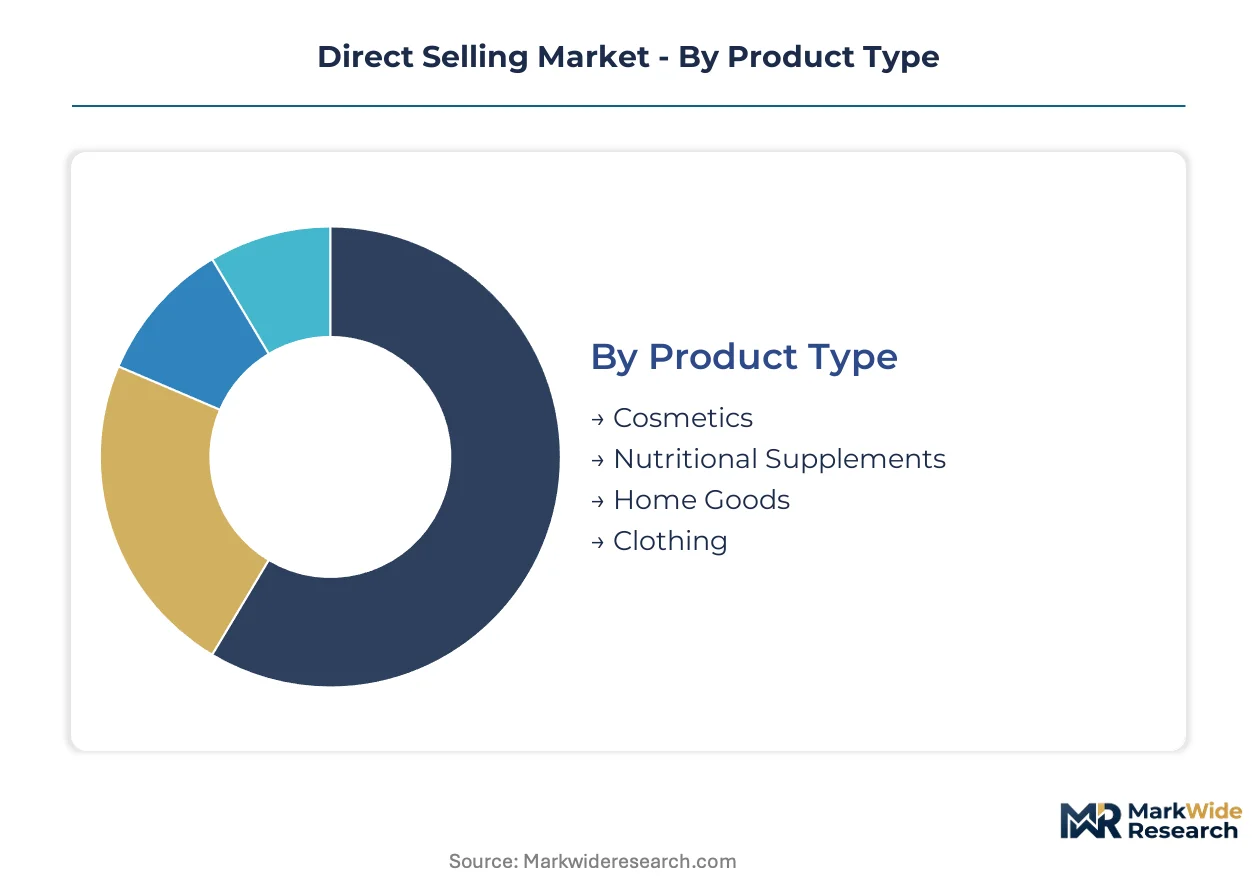
Market segmentation provides a critical framework for understanding the diverse operational models and consumer engagement strategies within the direct selling industry. Analyzing these distinct categories reveals where value creation concentrates and how companies adapt to evolving consumer preferences and technological shifts.
Product Type:
Product categories within direct selling exhibit varying sales cycles, with some requiring frequent repurchase and others representing more considered purchases. This difference impacts distributor training and inventory management.
- Nutritional Supplements:This segment includes vitamins, weight management products, and health-focused beverages designed to support wellness. Demand concentrates in high-growth economies like India, driven by a consumer pivot towards proactive health management and preventative care.
- Cosmetics:This category encompasses skincare, makeup, and personal care items, often relying on visual demonstrations and personalized recommendations. Sales remain strong in Asia, where social media engagement drives influencer-led product discovery.
- Home Goods:Products such as kitchenware, cleaning supplies, and home decor items constitute this segment. These items often target household needs through in-home demonstrations.
- Clothing:This segment includes apparel and fashion accessories sold directly to consumers. Personal styling and fit consultations often characterize sales interactions.
Cosmetics dominates the installed base of long-term product offerings. Nutritional Supplements is where expansion concentrates.
Sales Channel:
Sales channels reflect how direct selling companies reach customers, with digital platforms now driving significant volume over traditional methods. Distributor preference for convenience shapes channel evolution.
- Online:This channel includes e-commerce websites, social commerce platforms, and mobile applications used for direct product sales and distributor recruitment. Consumer preference for digital convenience and global reach drives its rapid expansion.
- In-Person:Traditional face-to-face interactions, including one-on-one meetings and personalized consultations, define this sales channel. Relationship building remains a core strength for high-value product sales.
- Parties:Group gatherings, either in-home or virtual, where products are demonstrated and sold to multiple consumers simultaneously, characterize this channel. These events foster community and generate immediate sales.
- Catalogs:Physical or digital brochures displaying products for customers to order represent this channel. Catalogs offer a curated product overview, often supplementing other sales methods.
Online sales channels are rapidly displacing legacy methods. In-Person interactions still anchor the foundational relationship model.
Customer Type:
Customer segmentation identifies distinct groups based on their purchasing behavior and engagement with the direct selling model. Understanding these groups informs targeted marketing strategies and product development.
- Retail Consumers:These individuals purchase products for personal use without engaging in the direct selling business opportunity. Their demand for authentic, influencer-led recommendations drives product discovery on digital platforms.
- Business Owners:This group comprises independent distributors who not only consume products but also actively build and manage their own sales networks. Their entrepreneurial drive fuels market growth, particularly in emerging economies.
- Event Planners:Individuals who organize and host sales parties or online events for distributors to present products fall into this category. They facilitate group sales and brand exposure.
- Influencers:Social media personalities or content creators who promote direct selling products to their followers represent this customer type. Their online reach amplifies brand messaging.
Retail Consumers represent the largest volume segment. Business Owners drive the market's entrepreneurial expansion.
Distribution Channel:
Distribution channels specify the primary methods direct selling companies use to move products from manufacturer to consumer. The shift towards digital engagement is reconfiguring traditional structures.
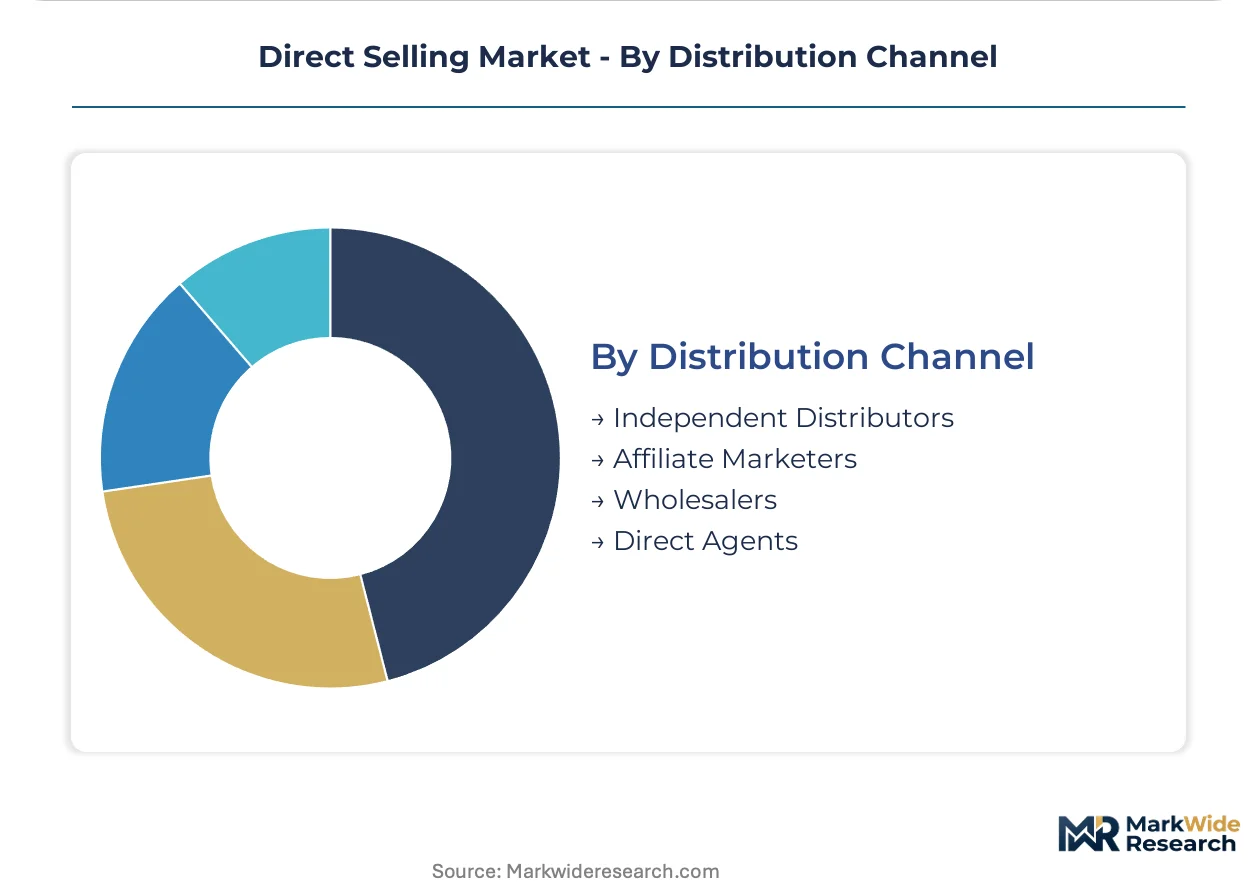
- Independent Distributors:Individuals who operate as independent contractors, selling products directly to consumers and often building downline networks, form this core channel. Their personal networks and digital engagement are critical for sales.
- Affiliate Marketers:These individuals promote products online through unique links and earn commissions on sales generated from their referrals. This model emphasizes digital reach and performance-based compensation.
- Wholesalers:Entities that purchase products in bulk from direct selling companies for resale, sometimes to smaller distributors or retailers, comprise this channel. They facilitate broader market penetration.
- Direct Agents:Company employees or contracted agents who sell products directly, often without building a multi-level network, represent this channel. They provide direct sales support.
Independent Distributors remain the foundational distribution mechanism. Affiliate Marketers are gaining share fastest through digital integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for direct selling products varies significantly across geographies, with some markets exhibiting high price sensitivity while others prioritize product quality and brand trust. High-growth economies, particularly in Asia, drive market expansion through digital adoption and entrepreneurial enthusiasm. Regulatory frameworks in mature markets enforce stringent consumer protection measures, influencing operational strategies.
India
India's youthful and digitally-native population fuels demand for direct selling products, especially nutritional supplements and personal care items. The FSSAI regulates health-related product claims, ensuring consumer safety and transparency. Major cities like Bengaluru and Mumbai serve as hubs for digital commerce and distributor network expansion.
United States
The United States market sees sustained demand for health and wellness products, alongside a robust financial services direct selling niche. The Federal Trade Commission (FTC) actively polices misleading income claims and business opportunity representations. California and New York show strong adoption of social commerce platforms and advanced digital marketing tools.
China
China's market is characterized by high social media engagement, driving sales in cosmetics and nutritional supplements through influencer-led recommendations. The State Administration for Market Regulation (SAMR) enforces strict rules on advertising and business conduct. The Yangtze River Delta region is a key area for e-commerce innovation and large consumer bases.
Germany
Germany presents a mature direct selling market with a preference for home goods and high-quality personal care products. Data privacy regulations under GDPR significantly impact digital marketing and customer data handling. Bavaria and North Rhine-Westphalia remain strong consumer markets for established direct selling brands.
Brazil
Brazil's market experiences strong demand for cosmetics and personal care, driven by a large consumer base and entrepreneurial opportunities. ANVISA oversees health product regulations, impacting the nutritional supplements segment. São Paulo and Rio de Janeiro are primary economic centers for direct selling operations and consumer engagement.
Direct Selling Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, creating a dynamic and often fragmented competitive landscape. The market comprises established global players, specialized regional entities, and a multitude of independent distributors. Strategic archetypes include diversified product portfolios, niche segment focus, and technology-driven sales models. Dominant competitive moves involve integrating new digital tools and fostering hyper-niche community building.
Within the established global network archetype, Amway represents a long-standing participant leveraging its extensive reach. Herbalife Nutrition exemplifies a specialized player focusing on the health and wellness segment with targeted marketing. Primerica occupies a distinct position by concentrating on financial services, offering a unique niche within the broader direct selling industry.
| Leading Market Players |
|---|
| Natura & Co |
| PM-International |
| Amway |
| Coway |
| Primerica |
| Herbalife Nutrition |
| Vorwerk |
| Mary Kay |
| eXp Realty |
| Others |
Cost & Logistics Intelligence
Underpenetration in emerging markets like India drives aggressive recruitment strategies, influencing commission structures and product pricing to attract new distributors. This dynamic shapes both supplier behavior and the overall pricing posture for direct selling products.
Pricing Analysis
Distributor training and support services drive lifetime value within the direct selling model, influencing the overall pricing structure. The dominant pricing model remains commission-based, rewarding personal sales and network expansion. Price differentiation stems from brand premium and perceived product efficacy, especially for nutritional supplements. E-commerce substitution and regulatory scrutiny on income claims exert downward pricing pressure, making retail consumers highly price-sensitive compared to entrepreneurial business owners.
Supply Chain Analysis
Extended payment terms for distributors facilitate product inventory management, supporting the direct selling supply chain. Geographic supply concentration includes India for nutritional supplements and China for cosmetics manufacturing, relying on active pharmaceutical ingredients and specialized cosmetic compounds. Regulatory restrictions on product claims and cross-border logistics chokepoints present structural risks. Downstream distribution runs through independent distributors, increasingly leveraging online sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The direct selling market represents a high-growth disruption, driven by the rapid digitalization of distributor networks. AI-driven personalization tools are fundamentally reconfiguring consumer engagement and sales strategies.
For Market Incumbents: Harden existing distributor networks by integrating advanced social commerce platforms and providing comprehensive digital marketing training. Invest in proprietary AI tools to counter e-commerce substitution from direct-to-consumer brands. Prioritize R&D in nutritional supplements to maintain product differentiation and efficacy. This approach reinforces channel control and distributor loyalty against market fragmentation.
For New Entrants and Emerging Players: Establish a beachhead in hyper-niche communities focused on specific wellness or lifestyle segments. Target digitally-native youth in emerging economies like India, where social commerce adoption is high. Leverage influencer-led recommendations and live-streaming sales events for rapid customer acquisition. This strategy allows new entrants to bypass traditional distribution hurdles.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among companies with strong subscription models for high-repurchase products like nutritional supplements. Long-term viability over a 5-10 year window favors agile players integrating AI and social commerce effectively. Target acquisition profiles include technology-forward firms with proprietary personalization platforms. The signal to watch is evolving regulatory clarity on digital marketing and transparent income claims.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Platform Integration | Integrating AI-driven personalization enhances sales conversion rates for independent distributors. |
| Distributor Skill Development | Launching comprehensive training programs addresses digital skill gaps among existing distributor bases. |
| Hyper-Niche Community Building | Fostering online groups around specific product interests cultivates loyal customer bases for specialized offerings. |
| Regulatory Compliance Enhancement | Investing in robust systems ensures transparent income claims and product advertising, mitigating FTC scrutiny. |
| Financial Services Expansion | Diversifying into financial planning captures greater consumer wallet share, as demonstrated by Primerica's model. |
Research Approach
Operator-level perspectives from independent business owners, direct selling executives, and social commerce platform managers anchored the qualitative base. Primary interviews combined with extensive secondary validation from industry association reports and government regulatory publications (FTC, SAMR). This approach utilized both bottom-up and top-down triangulation.
Scenario-based modeling provided a bracketed outlook for the market across the analysis window. Segmentation dimensions included product type, sales channel, customer type, distribution channel, and regional adoption patterns. Compound annual growth rates were derived from historical trend analysis and projected market dynamics. Key forecast inputs included digital engagement metrics and regulatory enforcement trends.
Sensitivities concentrate around evolving digital marketing regulations and shifts in consumer trust towards direct selling models. Forecasts reflect assumptions concerning market digitalization and economic stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
E-Brokerage Market
Financial Services
BFSI Contact Center Analytics Market
Financial Services
Intermediary Service Market
Financial Services
Power Bank Sharing Services Market
Financial Services
Global Treasury Software Market
Financial Services
Capital Restructuring Services Market
Financial Services
US Online Trading Platform Market
Financial Services
Reverse Factoring Market
Financial Services
Australia Online Gambling Market
Financial Services
Debt Collection Software and Service Market
Financial Services
Europe Insurance Brokerage Market
Financial Services
Treasury Management Market
Financial Services
Financial Services Software Market
Financial Services
Peer-To-Peer (P2P) Market
Financial Services
China Factoring Services Market
Financial Services
North America B2C Legal Services Market