
 Liquidation Service Market | 2026-2036
Liquidation Service Market Size, Share, and Industry Trends Forecast 2026-2036
Liquidation Service Market Insights
Digital auction platforms are recalibrating how surplus inventory moves through secondary markets, compressing recovery timelines and expanding buyer pools. B-Stock Solutions leverages proprietary online bidding infrastructure to connect enterprise sellers with vetted resellers across North America. Liquidation.com sustains market presence through deep relationships with Fortune 500 retailers seeking rapid inventory conversion. Via Trading anchors its position in Los Angeles with specialized handling of customer returns and shelf-pull merchandise.
Liquidation services encompass the professional management of surplus, obsolete, or distressed assets through valuation, aggregation, and resale channels designed to maximize recovery value for sellers. These operations rely on condition grading protocols, lot bundling algorithms, and real-time price discovery mechanisms to match supply with secondary market demand. Asset recovery and remarketing command the largest service-type revenue pools, while returns management applications are expanding fastest as e-commerce penetration deepens. Online platforms dominate distribution channel growth, though wholesale networks retain margin concentration for bulk transactions involving apparel and consumer electronics.
The EPA regulates electronic waste streams under RCRA, compelling liquidation providers to document proper disposal pathways for non-resalable electronics. OSHA standards govern warehouse operations where workers handle returned goods, influencing facility design and labor costs for inventory processors. The EU's WEEE Directive extends producer responsibility requirements to liquidation intermediaries managing end-of-life electrical equipment. Stakeholders must monitor how evolving extended producer responsibility frameworks in California and New York reshape liability allocation between original manufacturers and liquidation service providers.
Market Dynamics
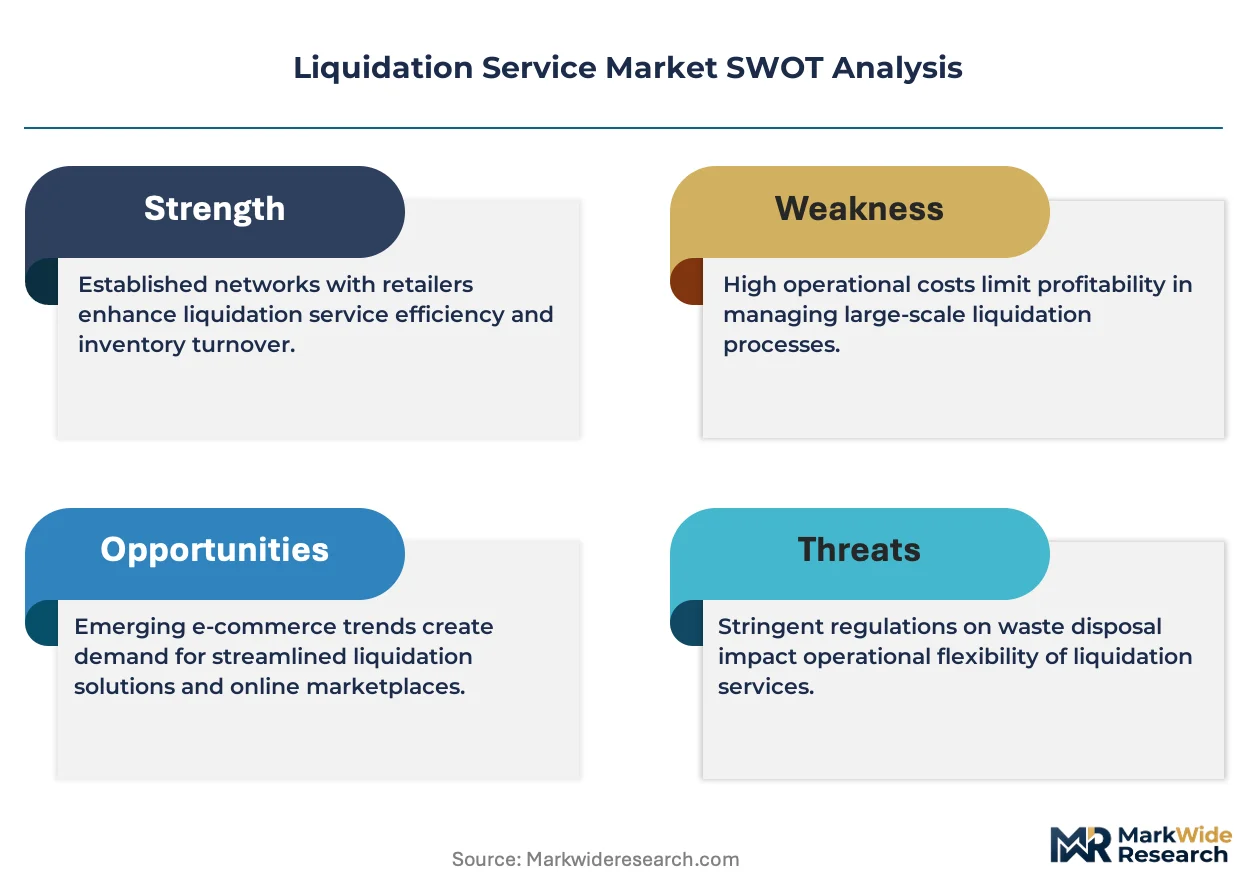
Reverse logistics volumes from e-commerce returns are overwhelming traditional liquidation channels, forcing asset recovery providers to automate condition grading and accelerate resale velocity through digital auction infrastructure.
Growth Catalysts
- E-commerce return proliferation:Online apparel and electronics purchases generate return rates exceeding 20%, creating sustained feedstock for liquidation platforms. Third-party logistics providers now bundle returns management with asset recovery services.
- EU Green Deal circular economy mandates:Extended producer responsibility frameworks compel retailers to document value recovery from end-of-life goods rather than landfill disposal. Liquidation intermediaries capture compliance value through certified remarketing pathways.
- Real-time pricing algorithms:Machine learning models analyze secondary market demand signals to optimize lot bundling and reserve pricing. Sellers recover 15-40% more value compared to static negotiated contracts.
Market Restraints
- Freight cost volatility:Diesel price swings and carrier capacity constraints compress margins on bulk inventory movements. Regional processors face disadvantage against vertically integrated competitors with captive logistics networks.
- Chinese manufacturing overcapacity:Floods of discounted new goods from Guangdong and Zhejiang provinces depress resale values for comparable used electronics and consumer products in North American secondary markets.
- OSHA warehouse safety standards:Compliance costs for facilities handling returned goods—including ergonomic assessments and injury prevention protocols—elevate operating expenses above unregulated informal competitors.
Strategic Opportunities
- India organized retail expansion:Modern trade formats in Mumbai and Delhi generate consistent surplus inventory streams currently served by fragmented local brokers. Professional liquidation platforms can consolidate this dispersed supply.
- Battery second-life applications:Electric vehicle battery packs below automotive performance thresholds retain 70-80% capacity for stationary energy storage. Specialized testing and reconditioning services unlock this emerging asset class.
- California SB 54 plastic packaging law:Source reduction mandates pressure consumer goods companies to recover and resell existing packaging inventory rather than produce virgin materials. Liquidation providers facilitate circular material flows.
Industry Challenges
- Condition grading standardization:Inconsistent quality classifications between sellers and buyers generate disputes, returns, and trust erosion. Universal inspection protocols remain elusive across apparel, electronics, and home goods categories.
- ERP integration complexity:Enterprise sellers require seamless data exchange between inventory management systems and liquidation platforms. Custom API development delays platform onboarding and extends sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquidation Service Market |
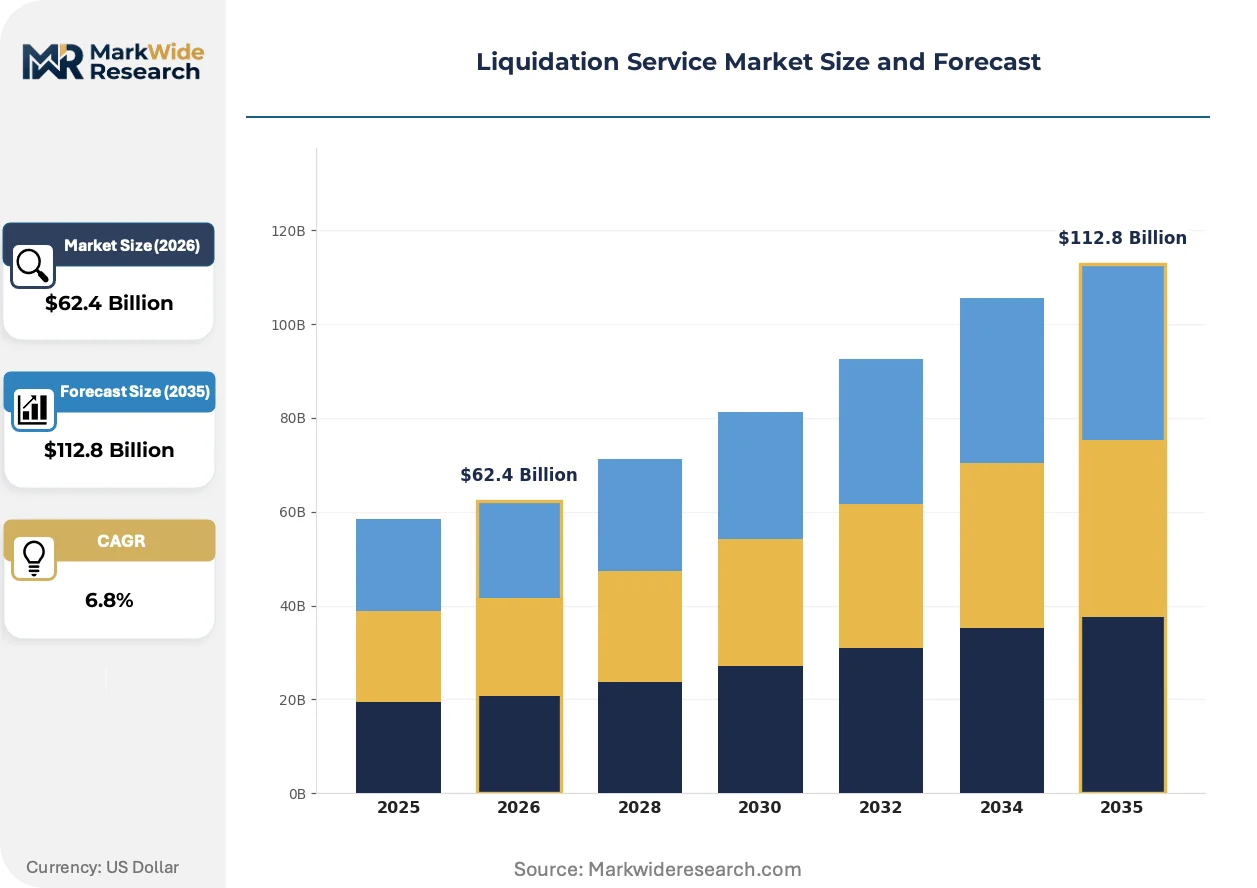
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $112.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Asset Recovery, Inventory Disposal, Debt Collection, Auction Management, Remarketing, Warehousing Client Type: Retailers, Wholesalers, Manufacturers, Financial Institutions, Government Agencies, Property Managers Distribution Channel: Online Platforms, Physical Outlets, Direct Sales, Third-Party Vendors, Consignment, Wholesale Networks Application: Bankruptcy, Overproduction, End-of-Life Products, Overstock Clearance, Seasonal Stock, Returns Management |
| Companies Covered | UpLiquidation, BULQ, B-Stock Solutions, 888 Lots, Via Trading, Direct Liquidation, BlueLots, Dynamic Distributors, Liquidation.com, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquidation Service Market Trends and Innovations
Digital infrastructure is compressing the time between inventory receipt and resale completion, while regulatory pressure on waste streams creates new service layers around compliance documentation and certified destruction alternatives.
Computer vision systems trained on product defect databases are absorbing manual inspection tasks previously performed by warehouse associates. Mid-market apparel liquidators in Texas and California deploy these tools to process 10,000+ returned garments daily with consistent grading accuracy. The technology is absorbing quality control labor costs while enabling same-day lot listing that accelerates cash conversion cycles.
The EU WEEE Directive's 2023 recast tightens documentation requirements for electrical equipment handlers across Germany, France, and Poland. Liquidation providers must now trace individual serial numbers through dismantling and material recovery stages. Small intermediaries lacking compliance infrastructure are exiting the market, consolidating volume with certified processors capable of audit-ready chain-of-custody records.
Reseller buying patterns are fragmenting from bulk pallet purchases toward curated single-SKU acquisitions. Individual Amazon and eBay sellers now source directly through liquidation platform mobile apps, bypassing traditional wholesale brokers. This behavioral shift concentrates in the United States, where gig economy participation and accessible fulfillment infrastructure enable micro-retailer scaling without inventory risk.
Liquidation Service Market Segmentation
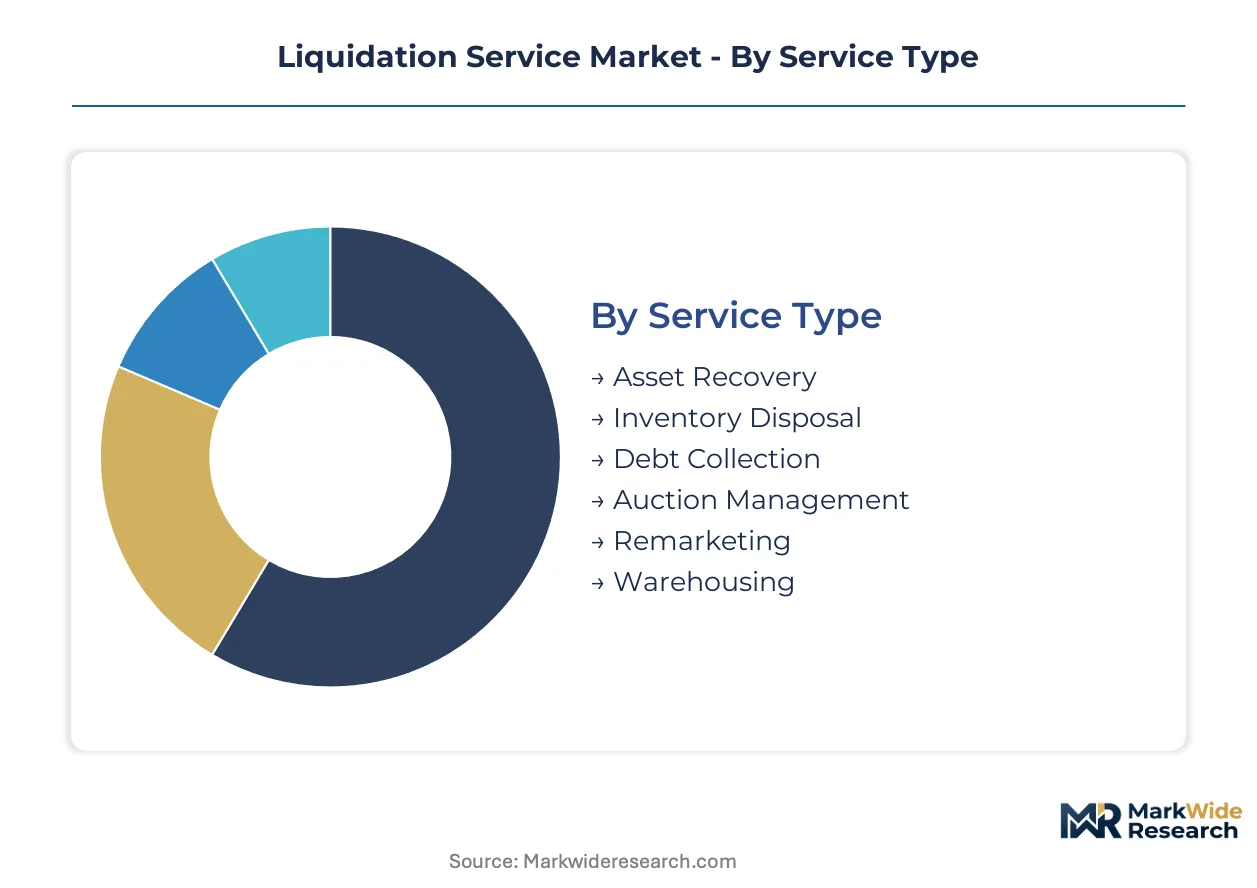
Liquidation service providers configure specialized capabilities around distinct asset classes and client operational needs. Segmentation clarity enables vendors to align pricing models, compliance protocols, and resale velocity with specific inventory origins and buyer expectations.
Service Type:
Replacement-cycle pressures on enterprise asset portfolios are elevating demand for professional recovery and remarketing services that compress time-to-cash.
- Asset Recovery:Comprehensive valuation, aggregation, and resale of surplus industrial equipment and commercial assets. Demand concentrates among manufacturers in Texas and California seeking rapid conversion of obsolete production machinery into working capital.
- Remarketing:Condition-graded redistribution of consumer returns and shelf-pull merchandise through vetted secondary channels. Retailers facing EU Green Deal circular economy mandates deploy certified remarketing pathways to document value recovery and avoid landfill penalties.
- Inventory Disposal:Certified destruction and material recovery for non-resalable goods with full EPA documentation.
- Debt Collection:Recovery of outstanding receivables through secured asset liquidation.
- Auction Management:Digital bidding infrastructure connecting enterprise sellers with reseller networks.
- Warehousing:Short-term storage and lot consolidation prior to resale execution.
Volume placements concentrate in Asset Recovery; the faster expansion belongs to Remarketing.
Client Type:
Margin compression across retail and manufacturing sectors is forcing asset-heavy organizations to externalize surplus inventory management rather than maintain in-house liquidation capabilities.
- Retailers:Department stores and e-commerce operators generating sustained feedstock from customer returns and seasonal overstock. Major hubs in Texas and California produce the highest liquidation volumes due to concentration of distribution centers and fulfillment infrastructure.
- Manufacturers:Industrial producers with end-of-life equipment and production overruns requiring rapid disposition. These clients prioritize asset recovery velocity to free warehouse space and recover capital for operational reinvestment.
- Wholesalers:Distributors managing obsolete stock from supplier relationship terminations.
- Financial Institutions:Banks and lenders liquidating repossessed collateral and defaulted loan assets.
- Government Agencies:Public sector surplus disposal with mandated transparency requirements.
- Property Managers:Commercial real estate operators clearing tenant-abandoned inventory.
Revenue concentration sits with Retailers; Manufacturers are gaining share fastest as industrial asset refresh cycles accelerate.
Distribution Channel:
Buyer behavior fragmentation is reshaping how liquidation inventory reaches end markets, with digital platforms absorbing volume from traditional broker networks.
- Online Platforms:Proprietary auction infrastructure enabling real-time price discovery and global buyer access. Gig economy resellers in the United States source directly through mobile applications, bypassing wholesale intermediaries entirely.
- Wholesale Networks:Established broker relationships moving bulk palletized lots to discount retailers and export traders. These channels retain margin concentration for apparel and consumer electronics transactions requiring physical inspection.
- Physical Outlets:Cash-and-carry warehouse locations serving local reseller communities.
- Direct Sales:Negotiated transactions with large-volume secondary market buyers.
- Third-Party Vendors:Commission-based placement through independent liquidation brokers.
- Consignment:Risk-shared arrangements where payment occurs post-resale completion.
Transaction volume flows heaviest through Online Platforms; Wholesale Networks preserve superior per-unit margins on bulk apparel and electronics.
Application:
Regulatory pressure on waste streams and e-commerce operational scale are expanding the addressable market for specialized liquidation applications beyond traditional bankruptcy scenarios.
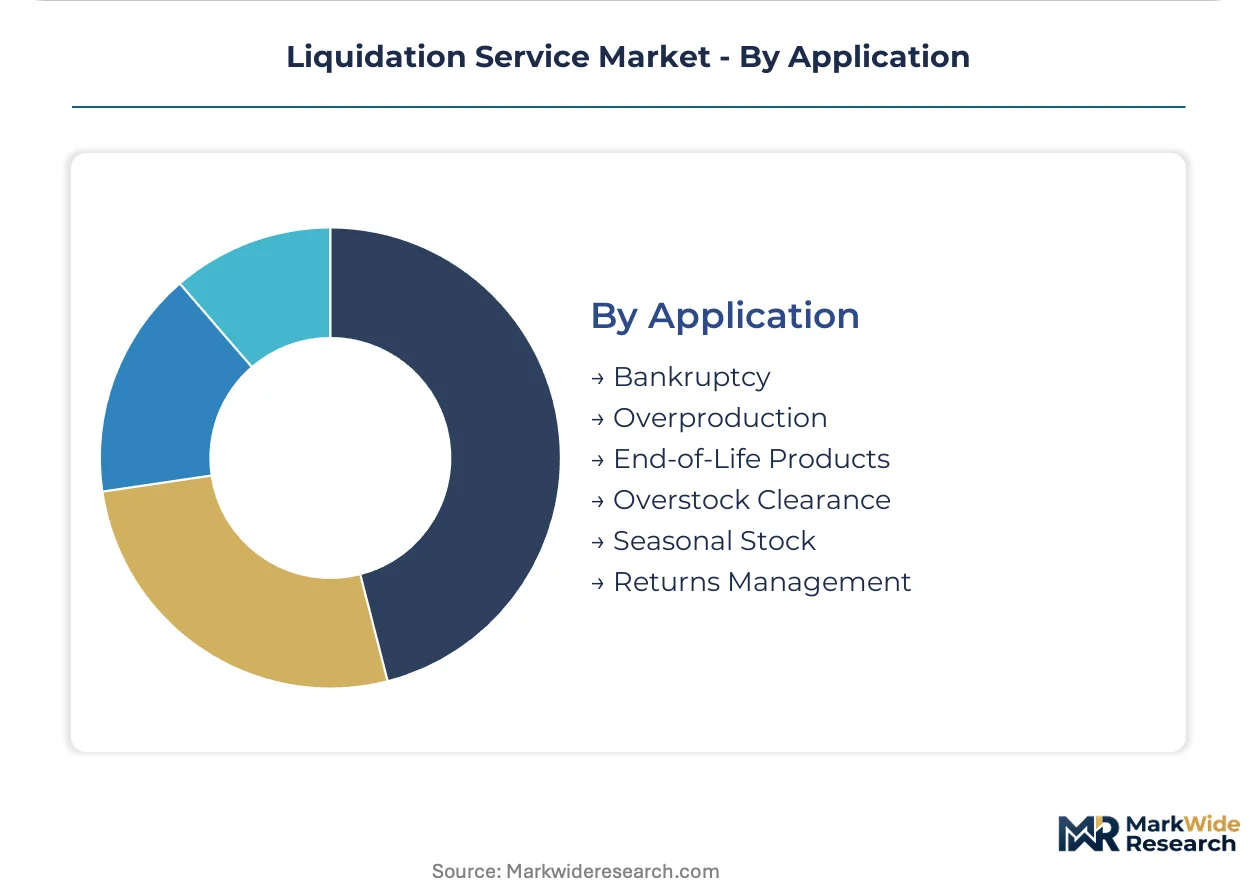
- Returns Management:Systematic processing of e-commerce and retail customer returns through condition grading and rapid resale. Online apparel and electronics purchases generate return rates exceeding 20%, creating sustained feedstock demand for automated liquidation infrastructure.
- End-of-Life Products:Regulatory-compliant disposition of goods reaching obsolescence under EU WEEE Directive and EPA RCRA frameworks. Liquidation providers must now trace individual serial numbers through dismantling stages to satisfy audit-ready chain-of-custody requirements.
- Bankruptcy:Court-supervised asset liquidation for insolvent enterprises.
- Overproduction:Clearance of manufacturing output exceeding contracted demand.
- Overstock Clearance:Seasonal or promotional inventory remaining post-selling period.
- Seasonal Stock:Time-sensitive disposition of holiday or weather-dependent merchandise.
Activity levels peak in Returns Management; End-of-Life Products applications are climbing fastest as extended producer responsibility frameworks expand across the United States and Europe.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Liquidation service demand concentrates in the United States, where retail distribution density and e-commerce return volumes create sustained feedstock. Secondary markets in Germany, India, and Brazil are professionalizing as organized retail expands and regulatory frameworks mature.
United States
Texas and California generate the highest liquidation volumes due to concentration of e-commerce fulfillment centers and major retail distribution hubs. The EPA regulates electronic waste streams under RCRA, compelling providers to document proper disposal pathways for non-resalable electronics. Dallas-Fort Worth anchors asset recovery activity for obsolete industrial equipment from energy sector operations.
Germany
The EU WEEE Directive's 2023 recast tightens documentation requirements for electrical equipment handlers across German processing facilities. Extended producer responsibility frameworks compel retailers to document value recovery from end-of-life goods rather than landfill disposal. The Rhine-Ruhr industrial corridor concentrates remarketing services for manufacturing surplus and production overruns.
India
Modern trade formats in Mumbai and Delhi generate consistent surplus inventory streams currently served by fragmented local brokers. The country's central bank and securities regulator oversee financial institution asset liquidation with increasing formalization requirements. Maharashtra's organized retail expansion creates opportunity for professional platforms to consolidate dispersed supply from emerging mall and hypermarket operations.
Brazil
São Paulo's retail concentration produces sustained bankruptcy and overstock liquidation volume as consumer credit cycles create inventory distress. The country's national environmental regulator extends producer responsibility requirements to electronics handlers managing end-of-life equipment. The Southeast region's logistics infrastructure supports bulk inventory aggregation for export to secondary markets across Latin America.
United Kingdom
London's financial services sector generates court-supervised asset liquidation for insolvent enterprises with mandated transparency requirements. The country's securities regulator oversees financial institution collateral recovery with strict audit protocols. The Midlands manufacturing belt sustains demand for industrial asset recovery as production facility refresh cycles accelerate.
Liquidation Service Market Competitive Landscape
Branded specialists and contract liquidators split share differently across service segments, with digital platforms absorbing volume from traditional broker networks. The vendor base organizes around three strategic archetypes: technology-enabled auction platforms, relationship-driven wholesale networks, and specialized regional processors. Consolidation pressure favors scaled operators with captive logistics infrastructure and compliance certification. Competitive moves center on API integration with enterprise ERP systems and geographic expansion into underpenetrated secondary markets.
Within the technology-enabled tier, B-Stock Solutions and Liquidation.com exemplify platform-centric positioning through proprietary bidding infrastructure. Via Trading anchors the specialized regional processor archetype with Los Angeles-based operations. These three occupy positions across the spectrum from pure digital marketplaces to hybrid physical-digital models, reflecting the market's structural segmentation between velocity-focused online channels and margin-preserving wholesale relationships.
| Leading Market Players |
|---|
| UpLiquidation |
| BULQ |
| B-Stock Solutions |
| 888 Lots |
| Via Trading |
| Direct Liquidation |
| BlueLots |
| Dynamic Distributors |
| Liquidation.com |
| Others |
Pricing and Supply Chain Analysis
Certified remarketing pathways versus informal liquidation channels create a stark bifurcation in both recovery rates and compliance infrastructure requirements. EU WEEE Directive mandates and EPA RCRA documentation standards force enterprise sellers toward premium-tier providers with audit-ready chain-of-custody systems, while unregulated brokers compete on speed alone without environmental liability coverage.
Pricing Analysis
High-volume transactional flows through digital auction platforms compress per-unit margins while accelerating cash conversion cycles. Pricing stratifies across certified remarketing, standard wholesale, and informal broker tiers based on documentation depth and buyer vetting rigor. Cost compression in the standard tier intensifies because Chinese manufacturing overcapacity floods secondary markets with discounted new goods. Small resellers sourcing through mobile applications exhibit the highest price sensitivity; Fortune 500 retailers prioritizing compliance velocity show the least.
Supply Chain Analysis
Direct-to-reseller digital channels handle hyperscale buyer demand from gig economy operators in Texas and California, bypassing traditional wholesale intermediaries entirely. Inventory aggregation draws from United States, Germany, and India based on retail distribution density and e-commerce return volumes. Operations rest on diesel freight networks, warehouse labor pools, and ERP integration specialists. Single-source vulnerability concentrates in carrier capacity constraints during peak return seasons. Distribution runs through proprietary auction infrastructure, wholesale broker relationships, and physical cash-and-carry locations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The liquidation service market functions as a cost-of-compliance story where EU WEEE Directive recast requirements and EPA RCRA documentation standards erect barrier-to-entry moats favoring certified processors over informal competitors.
For Market Incumbents: Extend compliance certification coverage into battery second-life testing and electric vehicle pack reconditioning before specialized competitors capture this emerging asset class. Build captive logistics networks in Dallas-Fort Worth and Los Angeles to defend against freight cost volatility eroding regional processor margins. Deepen ERP integration capabilities to accelerate enterprise seller onboarding cycles threatened by API complexity delays. For New Entrants and Emerging Players: Mobile-first auction platforms targeting individual Amazon and eBay sellers in the United States represent the most penetrable white-space opportunity as reseller buying patterns fragment from bulk pallets toward curated single-SKU acquisitions. India's organized retail expansion in Mumbai and Delhi offers secondary geographic entry with fragmented local broker competition. Pursue certified remarketing partnerships with EU-facing retailers needing Green Deal compliance documentation. For Investors and Strategic Acquirers: Re-rating potential sits with technology-enabled auction platforms given machine learning pricing algorithm adoption and real-time lot bundling capabilities. Long-term viability favors scaled operators with captive logistics infrastructure and multi-jurisdiction compliance certification. Monitor OSHA warehouse safety enforcement intensity as signal for informal competitor exit acceleration and volume consolidation toward certified processors.| Strategic Initiative | Industry Significance |
|---|---|
| ERP Integration Development | Seamless data exchange with enterprise inventory management systems accelerates platform onboarding and reduces sales cycle friction for major retailers. |
| Computer Vision Deployment | Automated condition grading systems trained on product defect databases absorb manual inspection labor costs while enabling same-day lot listing velocity. |
| Certified Remarketing Expansion | EU WEEE Directive compliance infrastructure captures mandated value recovery documentation demand from retailers avoiding landfill penalties. |
| Battery Second-Life Testing | Specialized electric vehicle pack reconditioning services unlock stationary energy storage applications for assets below automotive performance thresholds. |
| Geographic Consolidation | Acquisition of fragmented local brokers in India and Brazil concentrates dispersed supply from emerging organized retail operations. |
Research Methodology
Document review covered SEC 10-K filings from retail and logistics operators, EPA enforcement databases, EU WEEE Directive implementation reports, and customs trade records, complemented by interviews with returns management executives at e-commerce platforms, warehouse operations directors, secondary market resellers, and compliance officers at electronics processors. Bottom-up modeling of transaction volumes and top-down validation against retail sales and return rate benchmarks provided cross-check triangulation.
Market size and growth trajectory outputs emerged from segmented demand modeling across service type, client category, distribution channel, and application dimensions throughout the forecast period. CAGRs were derived from regression analysis of historical liquidation volume patterns against e-commerce penetration curves and regulatory implementation timelines. Key inputs included diesel freight cost indices, warehouse labor rate trends, and ERP integration adoption rates among Fortune 500 retailers.
The model holds under stable regulatory enforcement intensity and continued e-commerce return volume growth; deviation in Chinese export subsidy policies or OSHA warehouse safety standard expansion would shift competitive dynamics toward certified processors. Periodic stress-testing of base assumptions regarding freight cost volatility and resale platform technology adoption is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Peer-To-Peer (P2P) Market
Financial Services
Global Business Management Consulting Service Market
Financial Services
Contract for Difference Broker Market
Financial Services
North America B2C Legal Services Market
Financial Services
Back-Office Outsourcing in Financial Services Market
Financial Services
India Trade Finance Market
Financial Services
Commodity Trade Finance Market
Financial Services
Europe Factoring Services Market
Financial Services
Global Management Consulting Services Market
Financial Services
Belgium Gift Card and Incentive Card Market
Financial Services
CFD Trading Affiliate Programs Market
Financial Services
Foreign Exchange Services Market
Financial Services
Trade Finance Market
Financial Services
Legal Management Consulting Service Market
Financial Services
Reverse Factoring Market
Financial Services
ATM Software Market