
 UK Islamic Finance Market | 2026-2036
UK Islamic Finance Market Size, Share, and Industry Trends Forecast 2026-2036
UK Islamic Finance Market Analytics
The divergence between premium advisory services and commodity retail banking products is hardening in the UK Islamic Finance Market. Gatehouse Bank specializes in real estate-backed Sukuk structuring for institutional clients. Al Rayan Bank dominates the retail deposit and home finance segment through its branch network. HSBC Amanah UK leverages its parent bank's corporate relationships to sustain wholesale Islamic banking operations.
UK Islamic Finance denotes financial services and instruments structured to comply with Islamic law, prohibiting riba (interest), gharar (excessive uncertainty), and haram (forbidden) activities such as alcohol or gambling investments, while employing asset-backed mechanisms like profit-sharing or lease-based returns. Its primary commercial purpose centers on channeling capital from Muslim and ethically oriented investors into productive economic activity without conventional interest-bearing structures. Murabaha cost-plus financing occupies the mature volume position among product types, while Sukuk issuance commands the deepest margin pools as sovereign and corporate issuers seek alternative funding. Retail investor participation through digital platforms represents the fastest-expanding investor type category, though institutional investors still anchor absolute transaction values.
The Prudential Regulation Authority and Financial Conduct Authority jointly supervise Islamic banks under modified capital adequacy frameworks that accommodate profit-sharing investment accounts. HM Treasury's Sovereign Sukuk issuance program and the UK government's Islamic finance taskforce shape institutional credibility and cross-border market access. Stakeholders must monitor whether regulatory clarity on Shariah governance standards crystallizes ahead of competing European financial centers.
Market Dynamics
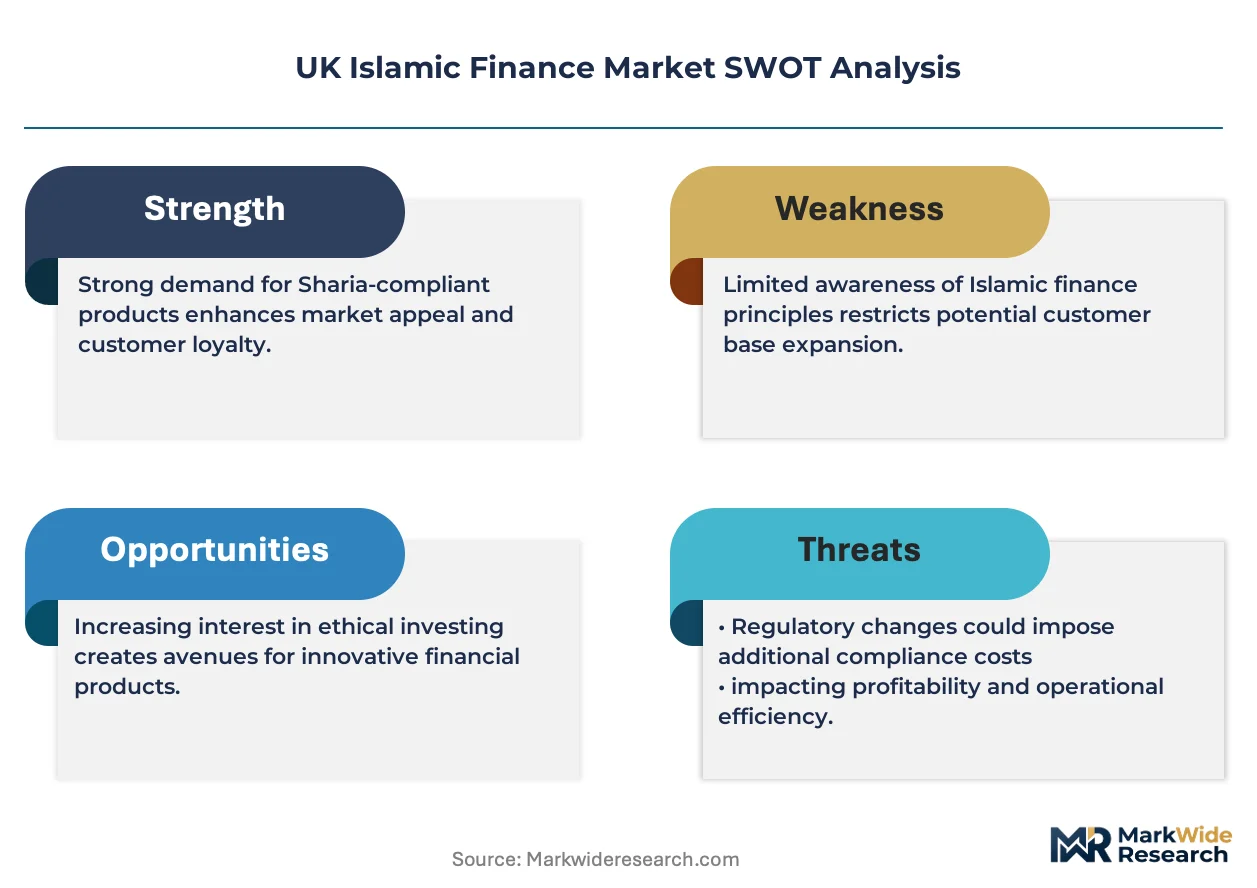
The Prudential Regulation Authority's modified capital adequacy framework for profit-sharing investment accounts is forcing UK Islamic banks to restructure liability management, while retail demand for Shariah-compliant home finance accelerates branch network competition between specialist and mainstream lenders.
Growth Catalysts
- HM Treasury Sovereign Sukuk program:The government's Islamic bond issuance builds institutional credibility and establishes London as a listing venue for Middle Eastern sovereign issuers seeking dual-currency structures.
- West Midlands demographic concentration:Birmingham's Muslim population density creates scalable retail banking demand that supports dedicated branch economics and localized product marketing.
- Digital onboarding platforms:Mobile-first account opening and automated Shariah compliance screening reduce customer acquisition costs and expand geographic reach beyond traditional branch footprints.
Market Restraints
- Shariah scholar scarcity:The limited pool of qualified Islamic jurists with financial expertise concentrates governance costs and creates bottlenecks for product approval timelines at smaller institutions.
- Benchmark rate dependency:Murabaha and Ijara contracts typically reference LIBOR successors for pricing mechanics, exposing profit margins to conventional interest rate volatility despite theological prohibition of riba.
- Real estate collateral concentration:Asset-backed financing requirements tie portfolio performance to UK property market cycles, amplifying systemic exposure in economic downturns.
Strategic Opportunities
- Scotland and Northern England underpenetration:Islamic banking presence concentrates in London and the Midlands, leaving Glasgow, Manchester, and Leeds corridors open for first-mover branch expansion.
- ESG convergence with Islamic principles:Ethical investment screening overlaps between Shariah compliance and environmental-social-governance mandates attract non-Muslim capital seeking values-aligned returns.
- SME trade finance gap:Islamic working capital solutions for halal-certified food exporters and modest fashion manufacturers address underserved segments outside conventional bank risk appetites.
Industry Challenges
- Shariah governance standardization:Divergent rulings between UK-based scholars and Middle Eastern jurists on controversial instruments like Tawarruq create product portability friction and reputational risk.
- Legacy core banking integration:Conventional IT systems require expensive customization to handle profit-sharing account mechanics, deferred payment scheduling, and zakat calculation automation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Islamic Finance Market |
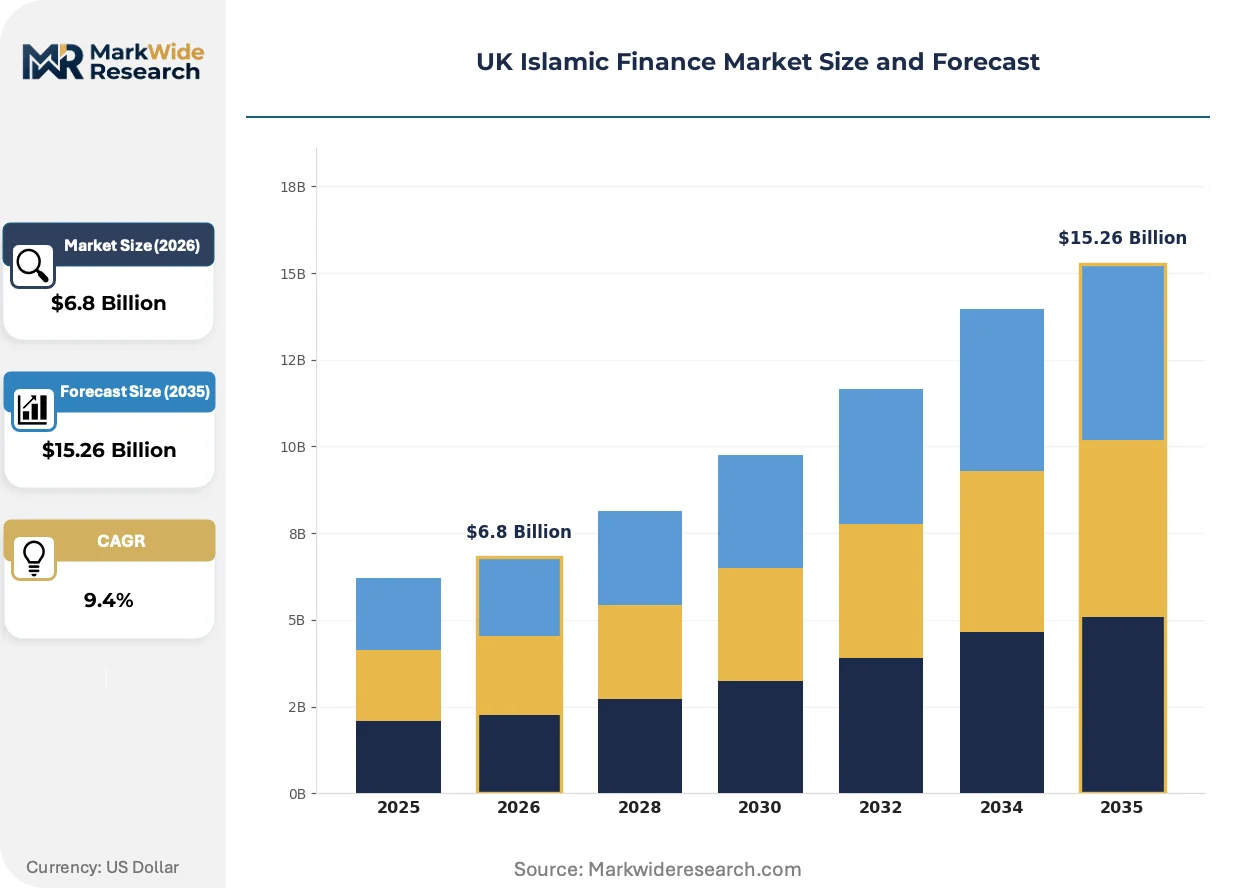
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mudharabah, Murabaha, Ijarah, Sukuk Investor Type: Institutional Investors, High Net-Worth Individuals, Retail Investors, Islamic Banks Customer Type: Corporates, SMEs, Government Entities, Non-Profits Service Type: Advisory, Asset Management, Leasing, Investment Banking |
| Companies Covered | QIB UK, Lloyds Islamic Window, Al Rayan Bank, ABC International Bank, United National Bank – Islamic Window, Gatehouse Bank, HSBC Amanah UK, Standard Chartered Saadiq, Bank of London & The Middle East (BLME), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Islamic Finance Market Evolving Landscape
Technology deployment and regulatory refinement are compressing the cost structure of Islamic product origination while broadening distribution channels beyond traditional branch networks. These shifts are reshaping competitive entry barriers and customer acquisition economics.
API-based open banking infrastructure is expanding into Islamic retail banking, enabling third-party fintechs to offer Shariah-compliant savings comparison and mortgage brokerage through embedded finance partnerships. Challenger banks and neobanks are adopting these interfaces to launch Islamic product lines without building proprietary Shariah governance capabilities. The structural consequence is fragmenting deposit market share away from established players with captive branch networks.
The Financial Conduct Authority's tailored authorization pathway for Islamic financial products is clarifying regulatory expectations for Shariah governance disclosure and consumer protection. This framework reduces compliance uncertainty for new entrants while mandating enhanced transparency around profit-rate mechanics and risk-sharing allocation. Specialist Islamic banks and Islamic windows of conventional groups are responding by standardizing product documentation and centralizing Shariah board functions.
First-time buyer segments are prioritizing Shariah-compliant home finance alternatives to conventional mortgages, driven by theological conviction and intergenerational wealth transfer patterns in British Muslim communities. Digital mortgage brokers and price comparison platforms are capturing this demand shift by adding Islamic finance filters and dedicated advisory pathways. This behavioral pivot is most visible in London's outer boroughs and the West Midlands corridor where housing affordability pressures intersect with religious demographic concentration.
UK Islamic Finance Market Segmentation
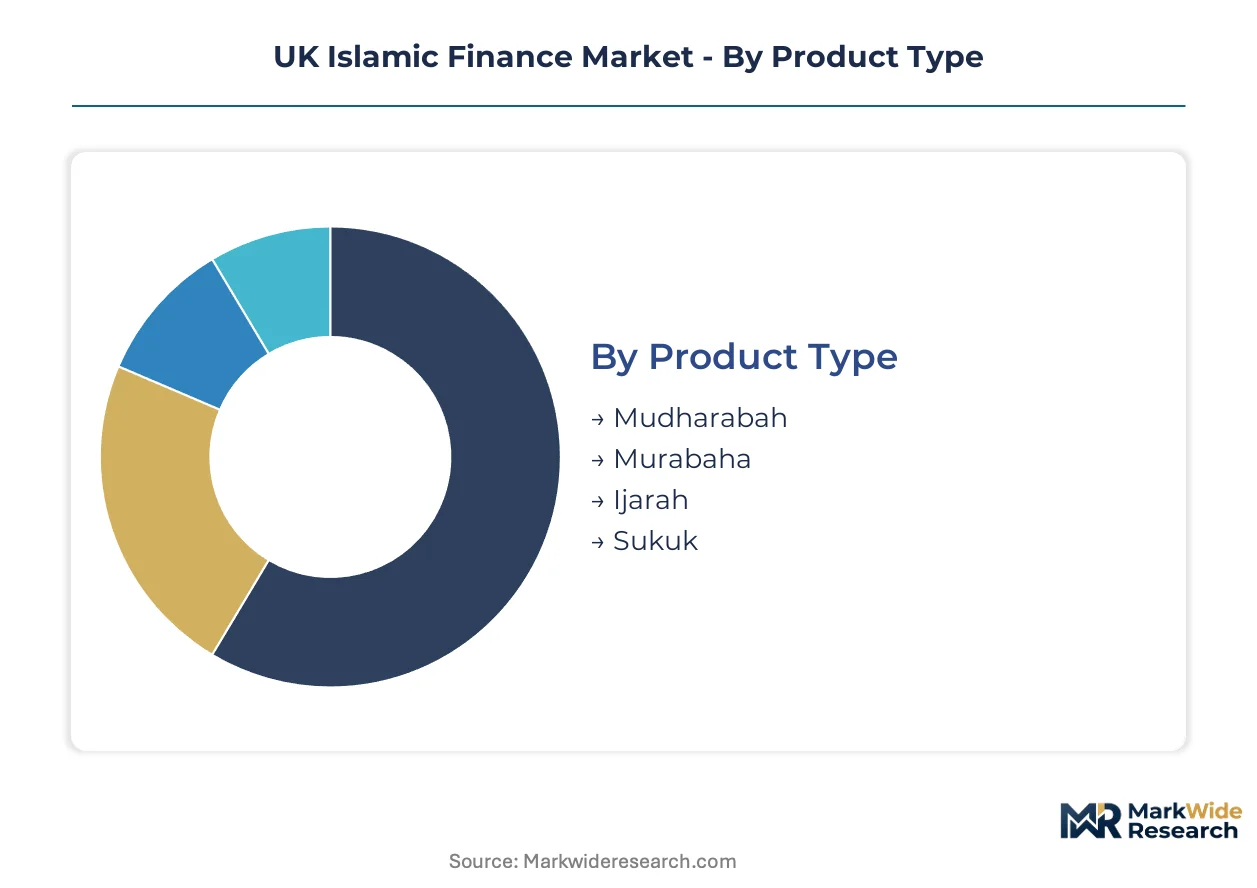
Segmentation in the UK Islamic Finance Market reveals how Shariah compliance requirements reshape product architecture across investor sophistication levels and service delivery models. Understanding these divisions exposes where capital formation concentrates and where regulatory arbitrage opportunities emerge.
Product Type:
Standardization dominates commodity financing structures while bespoke structuring persists in capital markets instruments.
- Murabaha:Cost-plus financing contracts specify asset acquisition with disclosed markup percentages, eliminating interest rate exposure through transparent profit mechanics. Demand concentrates in Birmingham and London's outer boroughs where first-time Muslim homebuyers seek Shariah-compliant alternatives to conventional mortgages, constrained by the Prudential Regulation Authority's modified capital adequacy treatment of profit-sharing accounts.
- Sukuk:Asset-backed trust certificates transfer beneficial ownership of underlying assets to investors, generating returns through lease income or profit participation rather than coupon payments. Sovereign and corporate issuers listing in London's financial district drive deepest margin pools, though Shariah scholar scarcity lengthens structuring timelines for complex hybrid instruments.
- Mudharabah:Profit-sharing partnerships allocate returns between capital providers and managing partners according to pre-agreed ratios.
- Ijarah:Lease-based financing structures transfer asset usage rights for periodic rental payments without ownership transfer.
Most installed capacity flows through Murabaha. Expansion is steepest in Sukuk.
Investor Type:
Institutional capital anchors absolute transaction values while digital platforms democratize retail participation.
- Retail Investors:Individual savers and homebuyers access Shariah-compliant products through mobile-first onboarding platforms that automate compliance screening. West Midlands corridor demographics support scalable branch economics, with Birmingham's Muslim population density enabling localized marketing that reduces customer acquisition costs below London benchmarks.
- Institutional Investors:Pension funds, sovereign wealth vehicles, and asset managers deploy large-ticket capital into Sukuk and structured Islamic products. Demand concentrates in London's financial district where the HM Treasury Sovereign Sukuk program established listing credibility for Middle Eastern issuers seeking dual-currency structures.
- High Net-Worth Individuals:Family offices and private wealth vehicles seek tailored Shariah-compliant portfolio construction.
- Islamic Banks:Specialist institutions deploy proprietary capital and manage profit-sharing investment accounts on behalf of depositors.
Most installed capacity flows through Institutional Investors. Retail Investors are gaining share fastest.
Customer Type:
Corporate relationships sustain wholesale operations while SME gaps create specialist lender opportunities.
- SMEs:Halal-certified food exporters and modest fashion manufacturers require working capital solutions outside conventional bank risk appetites. Demand concentrates in Manchester and Leeds corridors where Islamic banking presence remains underdeveloped, creating first-mover expansion opportunities for specialist lenders with localized Shariah governance capabilities.
- Corporates:Large enterprises access project finance, trade facilities, and treasury management through Islamic windows of mainstream banks or specialist institutions. London-headquartered multinationals leverage HSBC Amanah UK's corporate relationships for cross-border Sukuk issuance and commodity Murabaha programs.
- Government Entities:Public sector bodies utilize Islamic financing for infrastructure and social housing development.
- Non-Profits:Charitable organizations and waqf institutions deploy endowment capital into Shariah-compliant income-generating assets.
Most installed capacity flows through Corporates. SMEs show the steepest expansion trajectory.
Service Type:
Advisory and asset management command premium margins while leasing and investment banking scale through standardization.
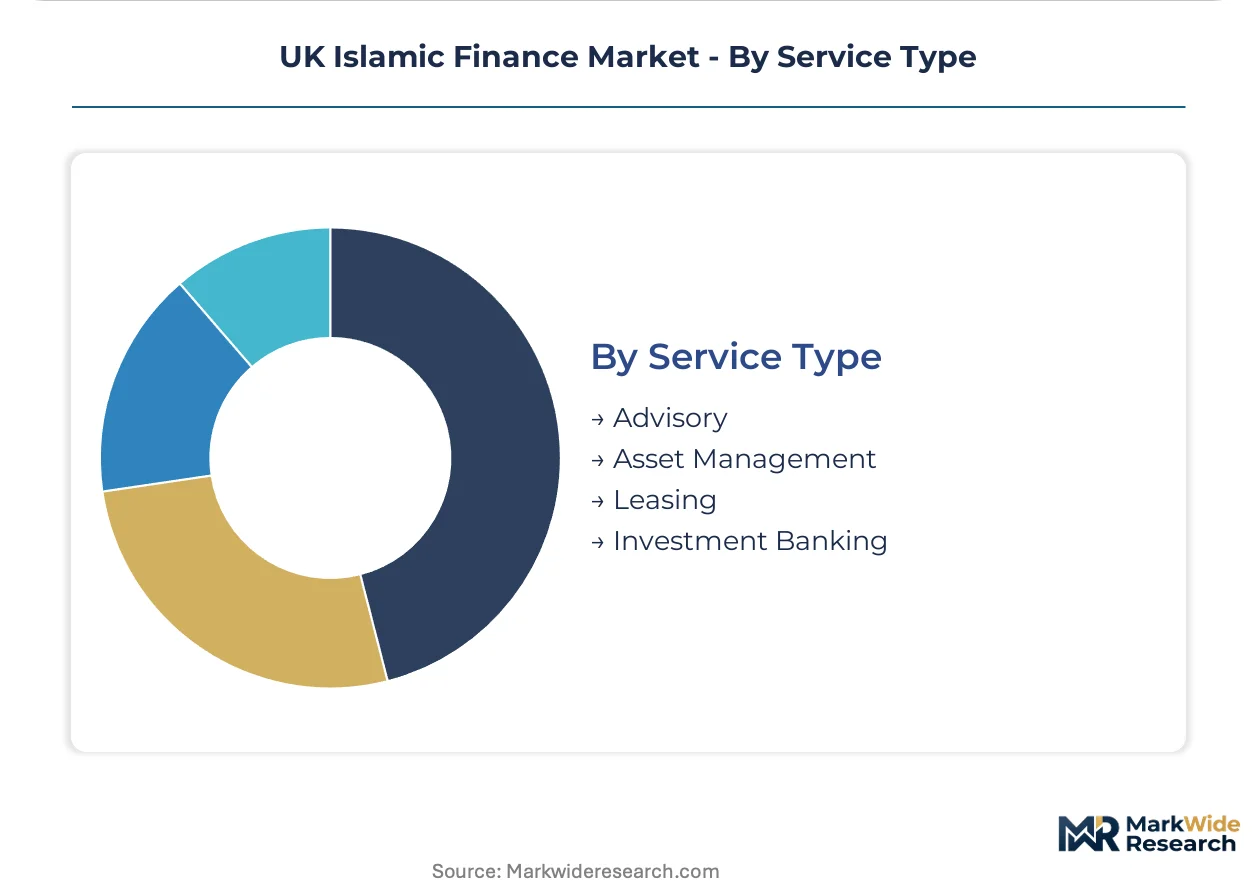
- Advisory:Shariah structuring, regulatory navigation, and transaction design services require qualified jurist involvement. Gatehouse Bank specializes in real estate-backed Sukuk structuring for institutional clients, concentrating governance costs among established players with captive Shariah board functions.
- Asset Management:Portfolio construction and fund administration integrate Shariah screening with conventional investment processes. ESG convergence with Islamic principles attracts non-Muslim capital seeking values-aligned returns, broadening addressable demand beyond religious demographic boundaries.
- Leasing:Ijarah-based equipment and vehicle financing provides operational solutions for corporate fleet and SME asset acquisition.
- Investment Banking:Underwriting, syndication, and market-making activities support primary and secondary Sukuk markets.
Most installed capacity flows through Asset Management. Advisory commands the highest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London's Shariah scholar concentration anchors the UK's Islamic finance workforce, with Birmingham's retail banking specialists and Manchester's emerging SME lenders forming secondary talent clusters across England's urban corridor.
London and Southeast England
Institutional Sukuk issuance and sovereign wealth fund relationships concentrate in the City of London and Canary Wharf. HM Treasury's Sovereign Sukuk program established London as a listing venue for Middle Eastern issuers seeking dual-currency structures. The Financial Conduct Authority's tailored authorization pathway for Islamic products shapes regulatory expectations for Shariah governance disclosure.
West Midlands
Birmingham's Muslim population density creates scalable retail banking demand for Shariah-compliant home finance and deposit products. The Prudential Regulation Authority's modified capital adequacy framework for profit-sharing investment accounts shapes local bank liability management. Branch network competition between specialist and mainstream lenders accelerates in this corridor.
North England
SME trade finance gaps for halal-certified food exporters and modest fashion manufacturers concentrate in Manchester and Leeds corridors. Islamic banking presence remains underdeveloped here, creating first-mover expansion opportunities. Localized Shariah governance capabilities would support specialist lender entry into this underserved segment.
Scotland
Islamic banking penetration in Glasgow and Edinburgh lags behind English urban centers despite significant Muslim demographic presence. The Prudential Regulation Authority's supervision extends to Scottish-registered Islamic banks under modified capital frameworks. Edinburgh's asset management cluster presents ESG convergence opportunities with Islamic ethical screening principles.
Wales and Northern Ireland
Cardiff and Belfast represent minimal current Islamic banking infrastructure relative to demand potential. The Financial Conduct Authority's regulatory perimeter encompasses any UK-authorized Islamic financial institutions operating in these jurisdictions. Digital onboarding platforms reduce geographic barriers for retail customer acquisition in these underpenetrated markets.
UK Islamic Finance Market Competitive Landscape
Capital-heavy full-license Islamic banks compete with asset-light Islamic windows of conventional lenders for customer relationships and balance sheet share. The market structure fragments between specialist institutions with captive Shariah governance capabilities and mainstream banks offering Islamic product lines through dedicated divisions. Three strategic archetypes dominate: retail-focused deposit and home finance specialists, wholesale-oriented Sukuk structurers, and corporate relationship-driven Islamic windows. Competitive moves center on digital platform investment and geographic expansion into underpenetrated English regions.
Within the specialist bank tier, Al Rayan Bank and Gatehouse Bank occupy positions representing distinct strategic emphases—retail branch networks versus institutional real estate-backed Sukuk structuring. HSBC Amanah UK exemplifies the Islamic window archetype, leveraging parent bank corporate relationships for wholesale operations. These three entities anchor the competitive topology, with their respective archetypes shaping how product development resources and Shariah governance costs distribute across the market.
| Leading Market Players |
|---|
| QIB UK |
| Lloyds Islamic Window |
| Al Rayan Bank |
| ABC International Bank |
| United National Bank – Islamic Window |
| Gatehouse Bank |
| HSBC Amanah UK |
| Standard Chartered Saadiq |
| Bank of London & The Middle East (BLME) |
| Others |
Value Network & Pricing Analysis
Sovereign wealth-backed Islamic banks and family-controlled specialist lenders anchor supply-side discipline across UK Islamic finance, translating captive Shariah governance capabilities into pricing power that commodity retail products cannot replicate. Their ownership structures insulate margin pools from the rate volatility that squeezes conventional interest-dependent competitors.
Pricing Analysis
The bundled-vs-unbundled service split separates advisory-led Sukuk structuring from standardized Murabaha home finance. Three-tier pricing structure across premium advisory, standard retail, and economy digital-only tiers reflects Shariah scholar involvement depth and documentation complexity. Pricing pressure stems from digital neobanks automating compliance screening and compressing customer acquisition costs in the retail deposit segment. First-time homebuyers in Birmingham and London's outer boroughs show highest price sensitivity, while Middle Eastern sovereign issuers in the City of London demonstrate lowest sensitivity to structuring fees.
Supply Chain Analysis
Direct-to-institutional channels handle sovereign wealth fund and pension fund demand through London's financial district, while branch networks and digital platforms distribute retail products across England's urban corridors. Shariah scholar talent concentrates in London and the Gulf states, creating supply bottlenecks for smaller institutions seeking product approval. UK property assets and Malaysian legal expertise feed into Sukuk structuring workflows. Single-source vulnerability runs through the limited pool of qualified jurists with UK regulatory familiarity. Distribution runs through a hybrid model combining captive branch networks, open banking API partnerships, and wholesale correspondent relationships with Middle Eastern banks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK Islamic Finance Market functions as a regulatory compounder where HM Treasury's Sovereign Sukuk program and the Financial Conduct Authority's tailored authorization pathway continuously validate institutional credibility and expand addressable demand.
For Market Incumbents: Lock in Shariah governance capabilities through captive scholar relationships and centralized board functions before digital neobanks fragment retail deposit share. Defend margin position by deepening vertical integration into real estate origination for Sukuk collateral pools. The threat of API-based open banking distribution demands accelerated investment in proprietary digital onboarding platforms. For New Entrants and Emerging Players: Enter via Scotland and Northern England corridors where Islamic banking presence remains minimal relative to Muslim demographic concentration. Manchester and Leeds SME trade finance gaps for halal-certified exporters offer the most penetrable white-space target. A mobile-first account opening experience with automated Shariah compliance screening provides the necessary go-to-market angle against established branch networks. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier Islamic windows of conventional banks lacking dedicated Shariah governance infrastructure. Long-term viability across the analysis window hinges on regulatory clarity crystallizing ahead of competing European financial centers. The signal to watch is whether the Prudential Regulation Authority extends modified capital adequacy recognition to profit-sharing investment accounts at challenger-scale institutions.| Strategic Initiative | Industry Significance |
|---|---|
| Shariah Governance Centralization | Consolidating scholar functions at Gatehouse Bank and Al Rayan Bank reduces product approval timelines and governance cost duplication. |
| Digital Onboarding Platform Launch | Mobile-first account opening with automated compliance screening expands geographic reach beyond traditional Birmingham and London branch footprints. |
| SME Trade Finance Expansion | Islamic working capital solutions for Manchester halal food exporters address segments outside conventional bank risk appetites. |
| Scotland Branch Network Entry | First-mover presence in Glasgow captures underserved Muslim demographic demand before incumbent geographic expansion. |
| ESG Convergence Product Development | Values-aligned screening overlaps between Shariah compliance and environmental mandates attract non-Muslim capital from Edinburgh asset managers. |
Research Methodology
Multiple input streams — regulatory filings with the Financial Conduct Authority and Prudential Regulation Authority, primary interviews with Islamic bank product directors and Shariah advisory board members, and secondary validation through HM Treasury Sukuk program disclosures and Bank of England systemic risk assessments — were reconciled to construct market estimates. Bottom-up transaction data from Sukuk issuance calendars and Murabaha home finance originations were triangulated against top-down macroeconomic indicators and demographic projections across the analysis window.
Data-stream reconciliation applied a structured analytical framework across product type, investor sophistication tier, customer segment, and geographic service delivery model dimensions. CAGRs were derived through trend extrapolation of historical issuance volumes and origination growth rates, calibrated against regulatory milestone timing and competitive entry patterns. Forecast inputs incorporated profit-sharing investment account liability treatment under modified capital adequacy frameworks and digital platform adoption curves in retail banking.
The model holds under continued regulatory support for Islamic product authorization and stable UK property market collateral values; deviation in Shariah governance standardization delays or conventional interest rate volatility spikes would shift trajectory. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Financial Advisory Services Market
Financial Services
Europe Insurance Brokerage Market
Financial Services
Financial Services Operational Risk Management Solution Market
Financial Services
Global P2P Fundraising Tool Market
Financial Services
Source to Pay Market
Financial Services
Treasury Management Market
Financial Services
ATM Outsourcing Services Market
Financial Services
E-KYC Market
Financial Services
China Financial Services Software Market
Financial Services
Capital Restructuring Services Market
Financial Services
Online Sports Betting Market
Financial Services
Intellectual Property Valuation Market
Financial Services
United Kingdom E-Brokerage Market
Financial Services
Digital Transformation in BFSI Market
Financial Services
Global Executive Search (Headhunting) Market
Financial Services
Australia Online Trading Platform Market