
 Digital Transformation in BFSI Market | 2026-2036
Digital Transformation in BFSI Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Transformation in BFSI Market Analysis
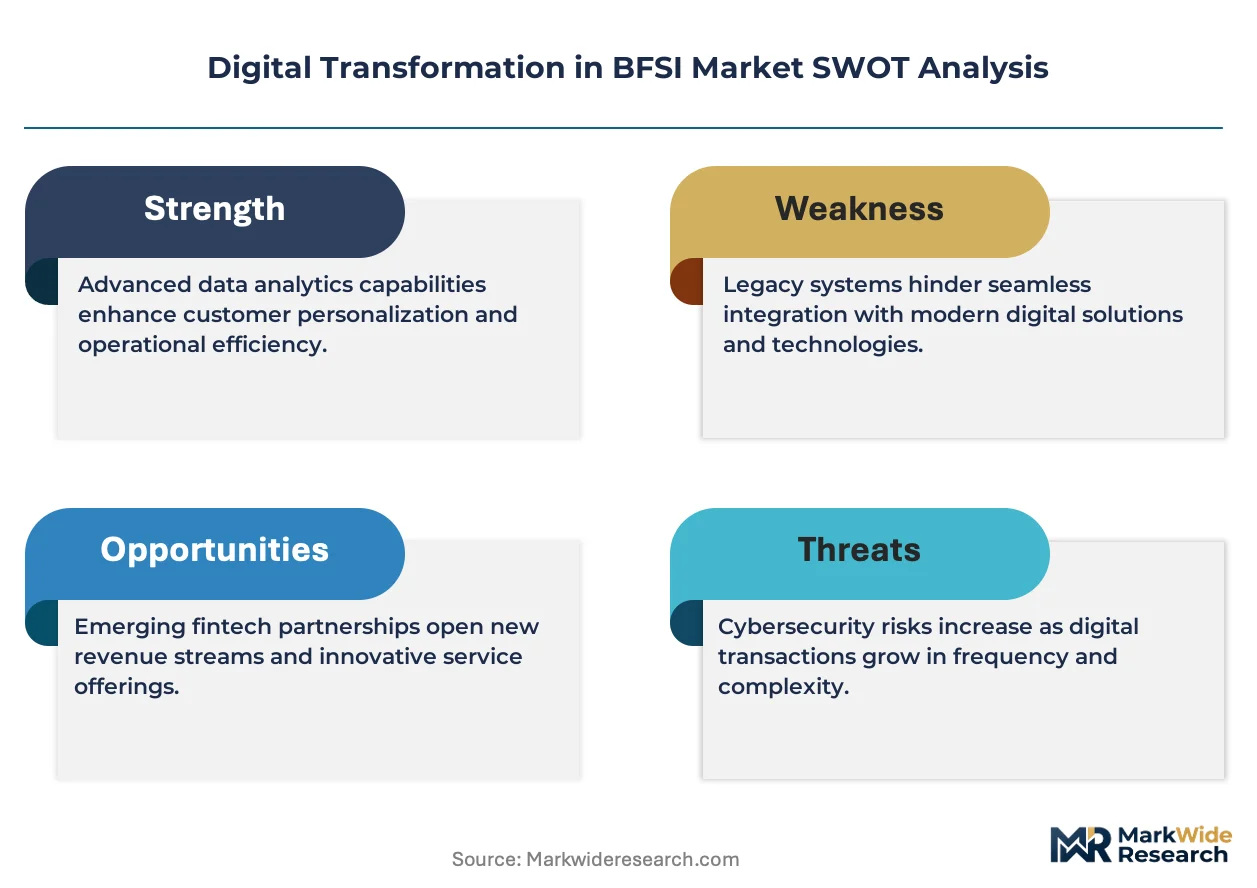
GDPR enforcement is realigning the cost-of-entry calculus for vendors serving European financial institutions. Accenture leverages its regulatory compliance practice to anchor multi-year transformation contracts with tier-one banks. TCS sustains competitive positioning through its India-based delivery scale and specialized BFSI domain centers. Infosys differentiates via its cloud-first modernization methodology and proprietary Finacle platform integrations.
Digital transformation in BFSI encompasses the systematic replacement of legacy banking infrastructure with API-driven, cloud-native architectures that enable real-time transaction processing and automated regulatory reporting. The practice integrates machine learning models for credit risk scoring and blockchain protocols for settlement finality, serving the commercial purpose of reducing operational cost bases while accelerating product velocity. Cloud Services and AI Solutions command the largest share of service-type expenditure as institutions retire mainframe dependencies. Robotic Process Automation within the technology dimension exhibits the steepest adoption curve, particularly in mortgage processing and claims adjudication workflows where labor arbitrage meets accuracy thresholds.
The EU AI Act, GDPR, and RBI's digital lending guidelines collectively reshape product standards and vendor qualification criteria across multiple jurisdictions. Institutions must now demonstrate algorithmic auditability and data residency compliance before procurement approval, elevating implementation complexity. Stakeholders should monitor how central bank digital currency pilots and open banking mandate expansions redefine platform architecture requirements and partnership ecosystems.
Market Dynamics
Cloud-native core banking migration is forcing institutions to dismantle decades-old mainframe dependencies while simultaneously rearchitecting compliance frameworks for algorithmic auditability mandates.
Growth Catalysts
- RBI Digital Payment Infrastructure:India's central bank mandates and UPI ecosystem expansion are driving large-scale technology procurement across retail and commercial banking segments.
- EU AI Act Compliance:European institutions must restructure algorithmic governance frameworks, creating sustained demand for audit-ready AI solutions and regulatory technology services.
- Real-time Transaction Processing:API-driven architectures are automating settlement finality and compressing product development cycles for competitive positioning.
Market Restraints
- Legacy System Entrenchment:Core banking modernization requires parallel operation of COBOL-dependent infrastructure alongside cloud-native platforms, inflating transitional cost structures.
- Data Residency Fragmentation:Divergent sovereignty requirements across EU member states, India, and Gulf jurisdictions multiply compliance architecture complexity.
- Specialized Talent Scarcity:Shortage of engineers proficient in both mainframe systems and containerized microservices constrains implementation velocity.
Strategic Opportunities
- Central Bank Digital Currency Pilots:Active experimentation by monetary authorities in India, the EU, and Gulf states is redefining platform architecture requirements and partnership ecosystems.
- Open Banking Mandate Expansion:Regulatory-driven data sharing protocols are creating white space for API management and consent orchestration specialists.
- Blockchain-Settlement Convergence:Distributed ledger protocols integrated with real-time gross settlement systems are compressing counterparty risk exposure windows.
Industry Challenges
- Algorithmic Auditability Certification:Institutions face extended timelines demonstrating model explainability and bias mitigation before procurement approval.
- Hybrid Cloud Orchestration:Managing workload portability across private, public, and sovereign cloud instances requires reconfigured operational playbooks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Transformation in BFSI Market |
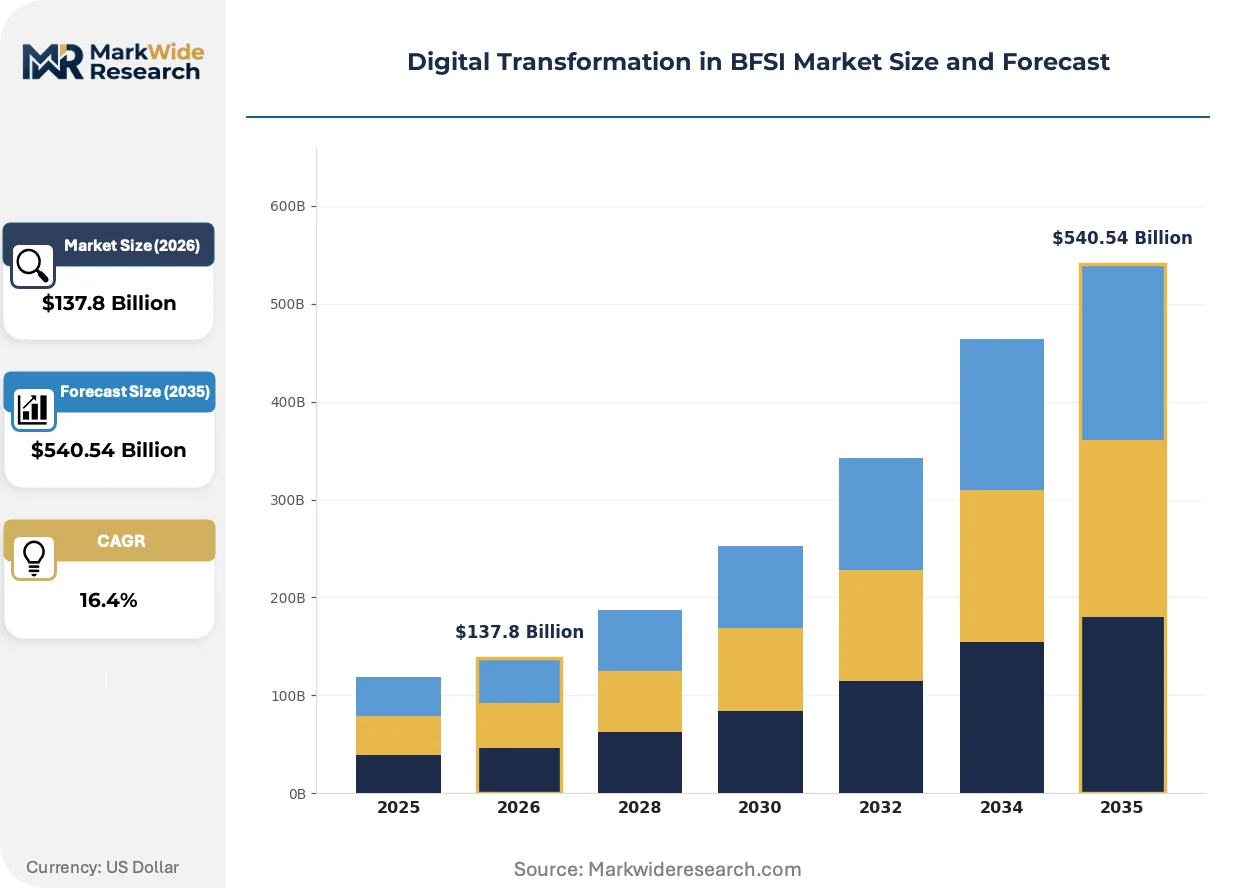
| Market Size in 2026 | $137.8 Billion |
| Market Size in 2035 | $540.54 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cloud Services, Cybersecurity Solutions, Data Analytics, AI Solutions Client Type: Retail Banks, Investment Firms, Insurance Companies, Payment Processors Technology: Blockchain, Big Data, Machine Learning, Robotic Process Automation Engagement Type: Consulting, Implementation, Managed Services, Support Services |
| Companies Covered | Accenture, Atos, Tata Consultancy Services (TCS), Mphasis, Hexaware Technologies, Infosys, Ernst & Young (EY), Persistent Systems, Capgemini, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Transformation in BFSI Market Emerging Trajectories
Machine learning credit scoring and robotic process automation are compressing operational cost bases while regulatory technology investments accelerate to meet algorithmic governance mandates.
Robotic Process Automation is automating mortgage processing and claims adjudication workflows where labor arbitrage intersects with accuracy thresholds. Tier-two banks and insurance carriers are deploying intelligent document processing at scale. This technology is automating routine decision gates previously requiring manual intervention, compressing turnaround times from days to minutes.
The EU AI Act establishes binding requirements for high-risk AI systems in credit scoring and insurance pricing. Financial institutions must implement conformity assessment procedures and maintain technical documentation for algorithmic audit trails. European retail banks are restructuring procurement criteria to prioritize vendors with certified governance frameworks.
Subscription-based platform licensing is displacing perpetual software ownership across mid-market banking segments. Cloud-native core banking vendors are capturing recurring revenue streams while buyers reduce upfront capital commitments. This shift is most visible in India and Southeast Asia where digital-native challenger banks prioritize operational flexibility over asset ownership.
Digital Transformation in BFSI Market Segmentation
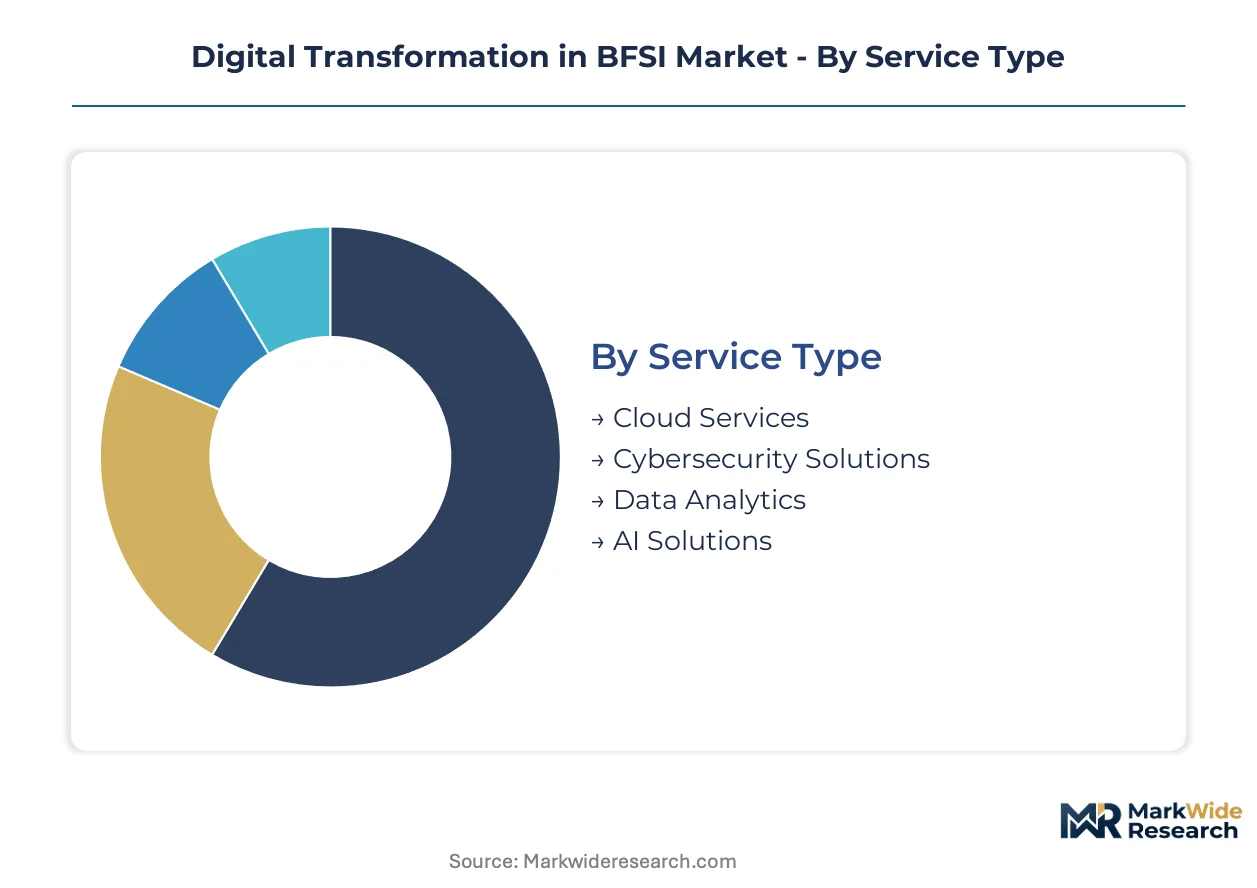
Segmentation in digital transformation reveals how procurement priorities diverge across service models, client risk profiles, and technology maturity curves. Institutions allocate budgets differentially based on regulatory pressure intensity and legacy system entrenchment.
Service Type:
Supply concentration tilts toward vendors with sovereign cloud certifications and AI governance frameworks pre-validated for EU AI Act and RBI compliance.
- Cloud Services:Multi-tenant infrastructure with data residency controls dominates procurement from European retail banks navigating GDPR fragmentation. Indian institutions prioritize auto-scaling architectures to absorb UPI transaction volume spikes without capital-heavy provisioning.
- AI Solutions:Credit scoring and fraud detection models require explainability documentation for regulatory submission. European demand concentrates on bias audit tooling; Indian banks prioritize vernacular language processing for customer service automation.
- Cybersecurity Solutions:Zero-trust architectures with quantum-resistant encryption protocols.
- Data Analytics:Real-time customer intelligence platforms with privacy-preserving computation.
Cloud Services absorbs the bulk of installed capacity; AI Solutions is expanding most quickly.
Client Type:
Application context determines solution complexity — retail banks demand consumer-facing omnichannel stacks while investment firms prioritize low-latency trading infrastructure.
- Retail Banks:Core banking modernization with API-first architectures enables open banking compliance and embedded finance partnerships. European tier-one institutions drive demand for algorithmic auditability tooling; Indian banks scale UPI integration and digital lending workflows.
- Payment Processors:Real-time gross settlement systems with blockchain finality layers reduce counterparty exposure. Indian NPCI-linked processors and EU instant payment schemes drive infrastructure replacement cycles.
- Investment Firms:Alternative data ingestion platforms with regulatory reporting automation.
- Insurance Companies:Claims adjudication automation with IoT telemetry integration.
Retail Banks commands the largest share of transformation spend; Payment Processors is gaining share fastest as real-time payment mandates proliferate.
Technology:
Volume concentration follows regulatory trigger points — machine learning adoption accelerates where credit decisions face algorithmic audit mandates.
- Machine Learning:Supervised learning pipelines for risk scoring with SHAP-based explainability outputs. EU AI Act high-risk system classifications force documentation standards that reshape vendor selection criteria across European institutions.
- Robotic Process Automation:Document processing bots with cognitive capture capabilities automate mortgage underwriting and KYC verification. Tier-two Indian banks deploy at scale to compress cost-to-serve metrics.
- Blockchain:Distributed ledger settlement with smart contract programmability.
- Big Data:Lakehouse architectures with federated query engines.
Machine Learning carries the heaviest implementation backlog; Robotic Process Automation shows the steepest adoption curve in cost-sensitive segments.
Engagement Type:
Customer type stratification separates capital-constrained mid-market buyers from institutions preferring outcome-based commercial structures.
- Managed Services:Multi-year operational takeovers of legacy infrastructure with SLA-governed modernization roadmaps. European banks favor this model to transfer compliance liability; Indian institutions use it to access scarce mainframe-to-cloud engineering talent.
- Consulting:Regulatory readiness assessments and cloud-native architecture design. Demand concentrates in EU AI Act preparation and RBI digital lending guideline implementation.
- Implementation:System integration with parallel run requirements.
- Support Services:Tiered maintenance with critical incident response guarantees.
Managed Services dominates contract value; Consulting is climbing the fastest as regulatory deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates BFSI technology procurement through RBI-mandated digital payment infrastructure and UPI ecosystem expansion. European institutions restructure algorithmic governance under EU AI Act compliance deadlines. North American banks accelerate cloud-native core banking migration amid fragmented state-level data privacy laws.
India
RBI digital lending guidelines and UPI transaction volume spikes drive demand for auto-scaling cloud architectures. The central bank's regulatory sandbox framework accelerates fintech partnership approvals. Mumbai and Bengaluru host concentrated vendor delivery centers serving domestic banks and payment processors.
United States
Legacy mainframe retirement and real-time payment network modernization absorb the largest technology budgets. State-level data privacy laws in California and New York multiply compliance architecture complexity. New York City anchors tier-one bank headquarters driving vendor consolidation.
Germany
EU AI Act high-risk system classifications force documentation standards for credit scoring algorithms. BaFin supervisory mandates accelerate audit-ready AI solution procurement. Frankfurt's banking cluster demands sovereign cloud certifications for core infrastructure replacement.
United Kingdom
Open banking mandate expansions and CBDC experimentation reshape platform architecture requirements. FCA regulatory technology expectations elevate vendor qualification criteria. London's fintech corridor concentrates API management and consent orchestration specialists.
Singapore
MAS digital banking licenses and cross-border payment corridor initiatives drive technology investment. The regulator's AI fairness assessment framework influences procurement criteria. The city-state's wealth management hub demands low-latency trading infrastructure upgrades.
Digital Transformation in BFSI Market Vendor Landscape
Indian service providers anchor one tier through delivery scale and specialized BFSI domain centers; European consultancies hold regulatory compliance positioning through algorithmic governance expertise. The vendor base stratifies across three tiers: global integrators with multi-year transformation contracts, regional specialists with sovereign cloud certifications, and niche firms with pre-validated AI audit frameworks. Dominant competitive moves include strategic partnerships with hyperscale cloud providers and portfolio diversification into regulatory technology services.
Within the global integrator tier, Accenture exemplifies regulatory compliance anchoring through multi-year transformation contracts with tier-one European banks. TCS occupies a position representing India-based delivery scale advantages. Infosys sits within the cloud-first modernization archetype through proprietary platform integration capabilities.
| Leading Market Players |
|---|
| Accenture |
| Atos |
| Tata Consultancy Services (TCS) |
| Mphasis |
| Hexaware Technologies |
| Infosys |
| Ernst & Young (EY) |
| Persistent Systems |
| Capgemini |
| Others |
Supply Flow & Price Mechanics
RBI-mandated auto-scaling cloud architectures and EU AI Act algorithmic auditability requirements are forcing vendors to restructure delivery models and certification investments, compressing margins in commoditized service tiers while premium compliance-ready offerings command pricing power.
Pricing Analysis
Volume concentrates in subscription-based SaaS tiers while margin accrues to managed services with embedded regulatory compliance. Three-tier pricing structure across premium, standard, and economy levels separates vendors with pre-validated EU AI Act and RBI governance frameworks from undifferentiated cloud infrastructure providers. Pricing pressure stems from hyperscale cloud providers entering core banking modernization directly, eroding mid-market systems integrator margins. Tier-two Indian banks and European mutual insurers exhibit highest price sensitivity; tier-one European banks prioritize audit-ready AI solutions over cost optimization.
Supply Chain Analysis
Workforce availability constraints in India and Poland are reshaping delivery center geography as vendors compete for engineers proficient in both COBOL mainframe systems and Kubernetes container orchestration. Supply concentrates in India for cloud-native development scale, Germany for regulatory technology specialization, and Singapore for wealth management platform engineering. Raw material dependencies include hyperscale cloud compute capacity, proprietary core banking software licenses, and certified AI governance tooling. Single-source vulnerability runs through AWS, Azure, and GCP infrastructure commitments with limited portability. Distribution runs through direct enterprise sales for tier-one banks and channel partnerships for mid-market institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Digital Transformation in BFSI Market operates as a cost-of-compliance arena where EU AI Act algorithmic auditability mandates erect barrier-to-entry moats favoring vendors with pre-certified governance frameworks and documented technical documentation capabilities.
For Market Incumbents: Acquire specialized regulatory technology firms with validated EU AI Act conformity assessment procedures to anchor multi-year transformation contracts. Defensive consolidation must address hyperscale cloud providers encroaching on core banking modernization through direct service offerings. Capacity addition in Bengaluru and Frankfurt delivery centers secures scarce mainframe-to-cloud engineering talent pools. For New Entrants and Emerging Players: RBI digital lending guidelines in India open a window for API management and consent orchestration specialists targeting UPI-integrated digital-native challenger banks. White-space concentration sits in mid-tier Indian payment processors requiring auto-scaling architectures without legacy mainframe dependencies. Go-to-market through MAS regulatory sandbox partnerships accelerates credibility building for ASEAN expansion. For Investors and Strategic Acquirers: The window for entry favors vertically integrated service providers with sovereign cloud certifications and captive AI governance tooling development. Long-term viability rests on regulatory technology capability depth rather than generic cloud migration services. Monitor central bank digital currency pilot announcements as inflection signals for platform architecture replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Technology Acquisition | EU AI Act compliance deadlines force consolidation of audit-ready AI governance tooling vendors. |
| Sovereign Cloud Certification | BaFin and RBI data residency mandates elevate vendors with in-country infrastructure control. |
| Core Banking Platform Integration | API-first architectures enable open banking compliance and embedded finance partnership revenue. |
| Central Bank Digital Currency Partnership | Active pilots by RBI and ECB redefine settlement infrastructure requirements and vendor selection criteria. |
| Delivery Center Geographic Expansion | Workforce scarcity in containerized microservices drives Bengaluru and Warsaw engineering hub investments. |
Methodological Framework
Document review covered regulatory filings with RBI, BaFin, and FCA, complemented by interviews with chief technology officers at tier-one European banks, digital transformation leads at Indian payment processors, regulatory affairs directors at global systems integrators, and procurement officers at insurance carriers. Secondary validation drew from EU AI Act implementation guidance, RBI digital lending circulars, SEC 10-K disclosures by listed service providers, and hyperscaler cloud revenue segment reporting. Bottom-up service line estimates and top-down market sizing triangulated across primary and secondary sources.
Cross-reference between historical contract value trajectories and expert panel input on procurement budget allocation shaped the analytical framework. Segmentation dimensions modeled across the analysis window include service type, client risk profile, technology maturity tier, and engagement commercial structure. CAGRs derived from slope consistency checks against disclosed revenue growth in comparable service categories. Forecast inputs incorporated UPI transaction volume trajectories and EU AI Act enforcement timeline assumptions.
The model assumes a particular technology adoption path; alternative pathways for blockchain-settlement convergence or quantum-resistant encryption would alter the outlook. Forecasts reflect documented assumptions regarding regulatory deadline adherence and central bank pilot progression. Material deviation in EU AI Act enforcement intensity or RBI sandbox approval velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Financial Advisory Services Market
Financial Services
Foreign Exchange Services Market
Financial Services
Spain E-Brokerage Market
Financial Services
Australia Gift Card and Incentive Card Market
Financial Services
Investment Trading Software Market
Financial Services
Middle East Islamic Finance Market
Financial Services
BFSI A2P SMS Market
Financial Services
South Korea Trade Finance Market
Financial Services
Back-Office Outsourcing in Financial Services Market
Financial Services
Intellectual Property Valuation Market
Financial Services
White Glove Services Market
Financial Services
Southeast Asia E-Invoicing Market
Financial Services
Europe Insurance Brokerage Market
Financial Services
Financial Services Software Market
Financial Services
Power Bank Sharing Services Market
Financial Services
Direct Selling Market