
 United Kingdom E-Brokerage Market | 2026-2036
United Kingdom E-Brokerage Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom E-Brokerage Market Insights
London's fintech infrastructure is restructuring around API-first brokerage architectures. Hargreaves Lansdown PLC leverages its established brand trust and adviser network to sustain retail loyalty. AJ Bell PLC anchors the mid-market with competitive pricing on SIPPs and ISAs. Interactive Investor Services Ltd differentiates through scale, operating the UK's largest flat-fee investment platform.
United Kingdom E-Brokerage denotes digitally intermediated securities and derivatives execution, delivered through web portals and native applications with sub-second order routing and real-time portfolio analytics. The primary commercial purpose is disintermediating traditional wealth managers while lowering per-transaction costs for self-directed investors. Online trading occupies the largest revenue pool among service types, though robo-advisory is capturing the fastest growth as algorithmic portfolio construction penetrates mass-affluent segments. Mobile platforms dominate technology deployment, while commission-based pricing faces structural pressure from zero-commission entrants and spread-pricing specialists.
The Financial Conduct Authority enforces conduct standards through its consumer duty framework, mandating fair value demonstrations and sludge reduction across platform interfaces. The Bank of England's Prudential Regulation Authority supervises capital adequacy for e-brokerage entities with banking licenses, while GDPR compliance shapes client data architecture and cross-border service limitations. Stakeholders must monitor how the FCA's evolving digital assets guidance intersects with blockchain-integrated trading infrastructure and whether forthcoming pension reforms redirect SIPP flows toward consolidated platform models.
Market Dynamics
The Financial Conduct Authority's consumer duty framework is compressing platform margins while mandating interface transparency that only API-first architectures can deliver at scale. This regulatory compression is forcing incumbents to rebuild core infrastructure mid-cycle.
Growth Catalysts
- Consumer Duty Framework:The FCA's rules on fair value demonstration and sludge reduction are accelerating platform consolidation toward firms with compliant tech stacks. Retail investors gain clearer cost comparisons, driving volume toward transparent providers.
- Self-Directed Investor Cohorts:Digitally native investors across England's urban centers are abandoning advised wealth management for direct platform control. This demographic shift expands addressable market for execution-only services.
- API-First Architectures:Open banking standards and modular brokerage infrastructure are enabling real-time portfolio analytics. London's fintech corridor attracts engineering talent that accelerates platform modernization.
Market Restraints
- Zero-Commission Pricing Pressure:Spread-pricing specialists and commission-free entrants are eroding per-transaction revenue models. Traditional platforms face margin compression without volume offsets.
- GDPR Compliance Architecture:Client data localization requirements increase infrastructure costs for cross-border service expansion. Data residency rules constrain platform scaling into adjacent European markets.
- Legacy System Technical Debt:Incumbent platforms operate on monolithic codebases that resist rapid feature deployment. Modernization timelines extend 18-36 months, delaying competitive response.
Strategic Opportunities
- Robo-Advisory Mass-Affluent Penetration:Algorithmic portfolio construction remains underdeveloped for sub-£100k accounts. Automated advice engines can capture this segment without human adviser cost structures.
- SIPP Consolidation Flows:Forthcoming pension reforms may redirect defined contribution flows toward unified platform models. Firms with integrated SIPP-ISA architecture capture rollover volume.
- Blockchain-Integrated Settlement:Distributed ledger infrastructure offers T+0 settlement compression versus traditional clearing. Early movers in tokenized securities gain latency advantages for derivatives execution.
Industry Challenges
- Cloud-Native Engineering Talent Scarcity:Financial services compete with technology firms for platform developers familiar with microservices and event-driven architecture. Compensation inflation stretches fixed-cost ratios.
- FCA Digital Assets Guidance Uncertainty:Evolving cryptocurrency custody and trading rules create compliance ambiguity. Platforms must architect for multiple regulatory scenarios without clear final standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom E-Brokerage Market |
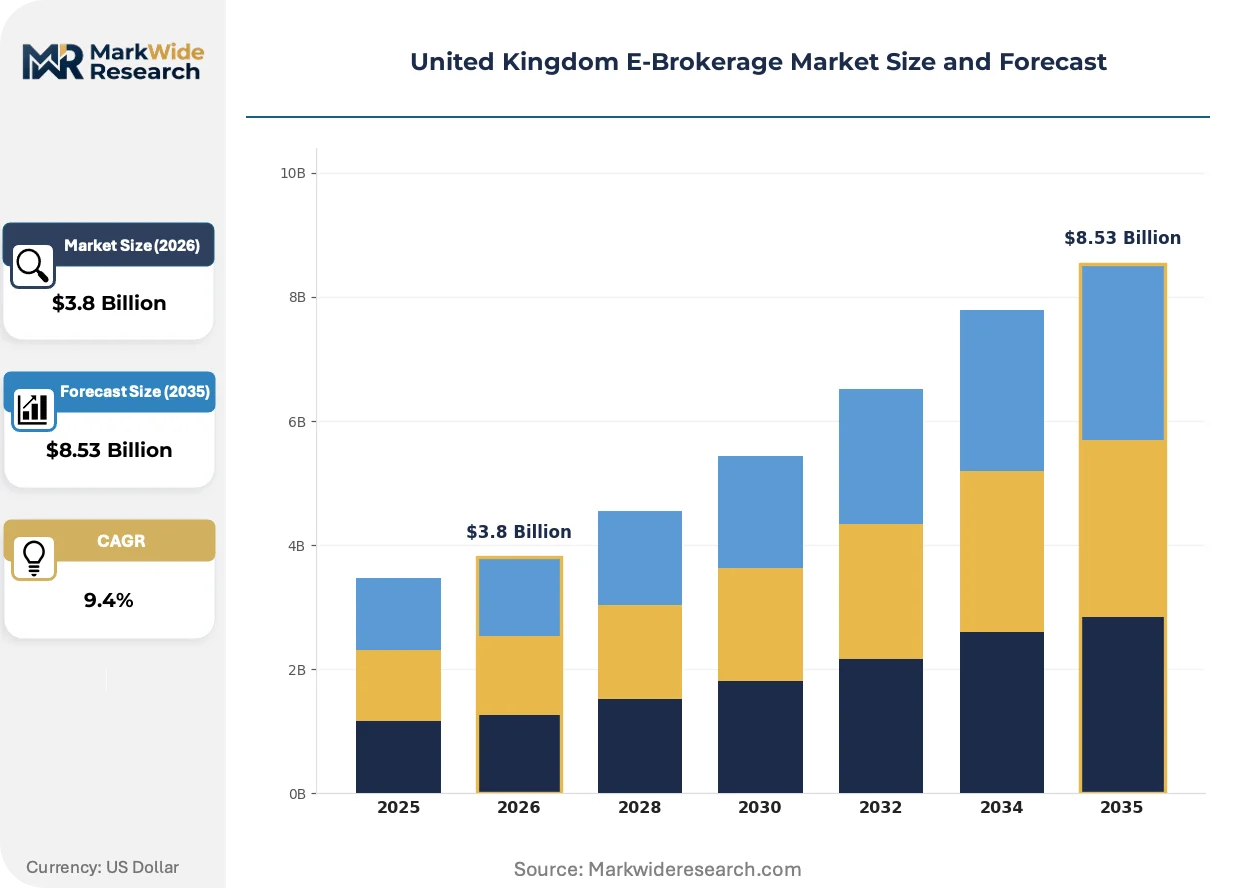
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Online Trading, Robo-Advisory, Wealth Management, Forex Trading Customer Type: Retail Investors, Institutional Investors, High Net-Worth Individuals, Small Business Owners Technology: Mobile Platforms, Desktop Platforms, Algorithmic Trading, Blockchain Pricing Model: Commission-Based, Subscription, Fee-Only, Spread Pricing |
| Companies Covered | Hargreaves Lansdown PLC, AJ Bell PLC, Interactive Investor Services Ltd, IG Group Holdings PLC, Freetrade Ltd, Interactive Brokers, eToro, Plus500, Capital.com, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom E-Brokerage Market Trends and Innovations
Platform infrastructure is fragmenting into composable service layers that separate execution, custody, and analytics functions. This decomposition enables specialist vendors to capture value at specific stack layers while compressing full-stack platform economics.
Microservices-based brokerage stacks are modularizing core trading functions into independently deployable components. Mid-market wealth managers are adopting these architectures to bypass legacy vendor lock-in. The structural consequence is compressing time-to-market for new product launches from quarters to weeks.
The FCA's consumer duty framework is mandating pre-trade cost disclosure and post-trade performance reporting. Platforms must rebuild client interfaces to surface embedded fees and sludge patterns. Retail-facing segments bear the heaviest compliance burden, with smaller platforms outsourcing reporting infrastructure to specialized regtech providers.
Investor switching behavior is compressing platform loyalty cycles as comparison tools improve. Execution-only clients migrate toward lowest-cost providers within 18-month windows, displacing sticky advised relationships. This churn concentrates in London and Southeast England where digital literacy and platform awareness run highest.
United Kingdom E-Brokerage Market Segmentation
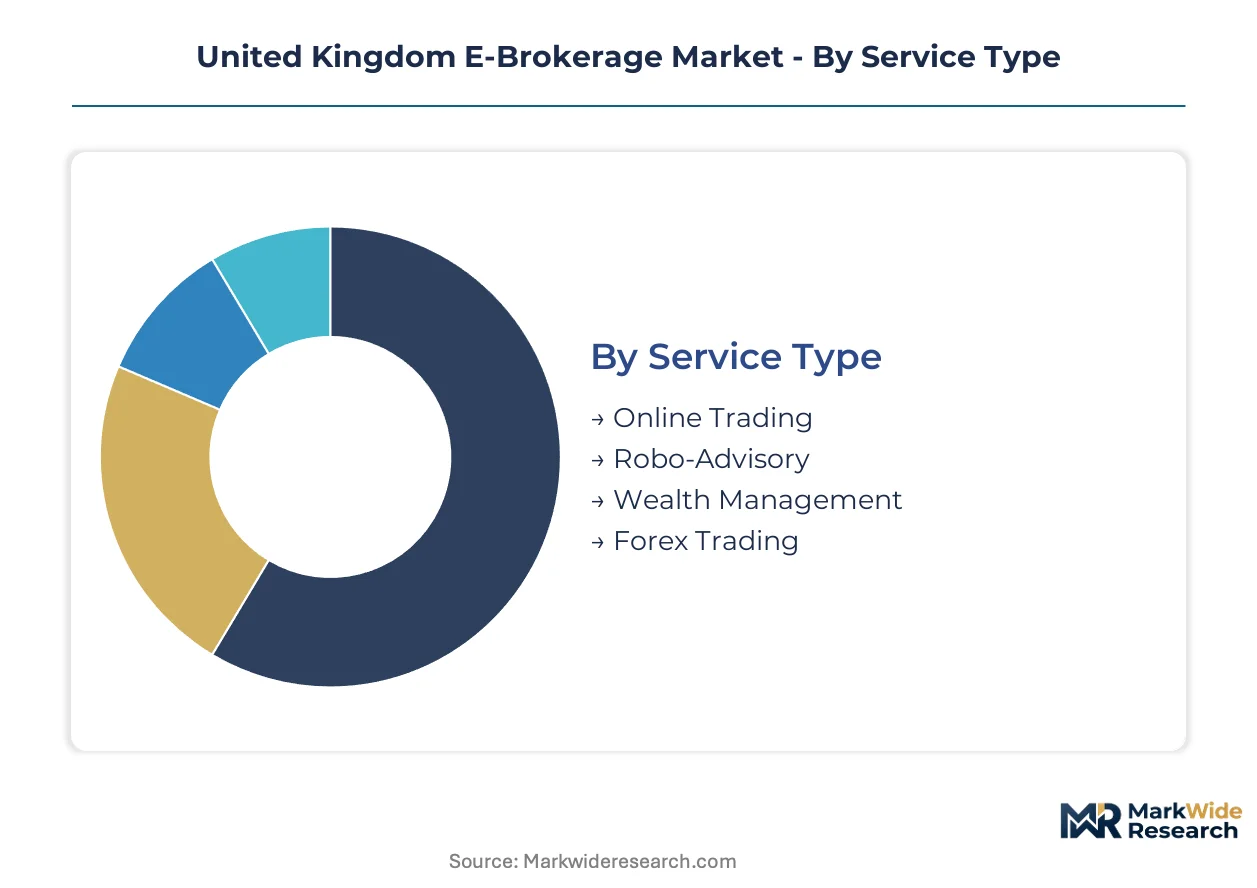
Platform operators in the United Kingdom E-Brokerage Market segment their offerings across four dimensions that determine regulatory exposure, infrastructure investment, and customer acquisition economics. Each segmentation axis carries distinct FCA compliance obligations and margin profiles that shape competitive positioning.
Service Type:
FCA authorization requirements vary sharply across service types, with advised wealth management demanding full suitability assessments while execution-only trading operates under lighter conduct rules.
- Online Trading:Web and mobile-native order execution for equities, ETFs, and derivatives with sub-second routing. Demand concentrates among self-directed retail investors in London and Southeast England where digital literacy drives platform switching behavior.
- Robo-Advisory:Algorithmic portfolio construction with automated rebalancing and tax-loss harvesting. Mass-affluent segments across England's urban centers adopt these services as human adviser costs become prohibitive for sub-£100k accounts.
- Wealth Management:Hybrid digital-advised services combining platform execution with human financial planning.
- Forex Trading:Leveraged currency pair execution with 24-hour market access.
Online Trading sits at the top of the volume ranking, with Robo-Advisory climbing the fastest.
Customer Type:
Customer acquisition costs and lifetime value diverge substantially across investor categories, with institutional mandates requiring dedicated sales teams while retail onboarding scales through digital marketing.
- Retail Investors:Individual account holders executing self-directed trades through web and mobile interfaces. Digitally native cohorts in Manchester, Birmingham, and Bristol migrate from advised relationships toward execution-only platforms.
- High Net-Worth Individuals:Clients with investable assets exceeding £1 million requiring bespoke custody and reporting. London's financial district concentrates demand for white-glove platform services with dedicated relationship management.
- Institutional Investors:Pension funds, insurers, and asset managers with block trading requirements.
- Small Business Owners:Entrepreneurs seeking integrated business and personal investment platforms.
Retail Investors dominate current account volumes, though High Net-Worth Individuals deliver the steepest expansion trajectory.
Technology:
Technology deployment choices determine infrastructure capital intensity and the pace of feature iteration, with mobile-first architectures demanding continuous UX investment.
- Mobile Platforms:Native iOS and Android applications with biometric authentication and push-notification alerts. England's urban investor base executes over half of all trades through smartphones, displacing desktop dominance.
- Algorithmic Trading:API-accessible execution engines enabling systematic strategy deployment. Quantitative hedge funds and sophisticated retail traders in London's fintech corridor drive adoption of low-latency infrastructure.
- Desktop Platforms:Feature-rich web interfaces with advanced charting and screening tools.
- Blockchain:Distributed ledger infrastructure for tokenized securities and settlement compression.
Mobile Platforms capture the largest user base, while Algorithmic Trading gains share fastest among professional segments.
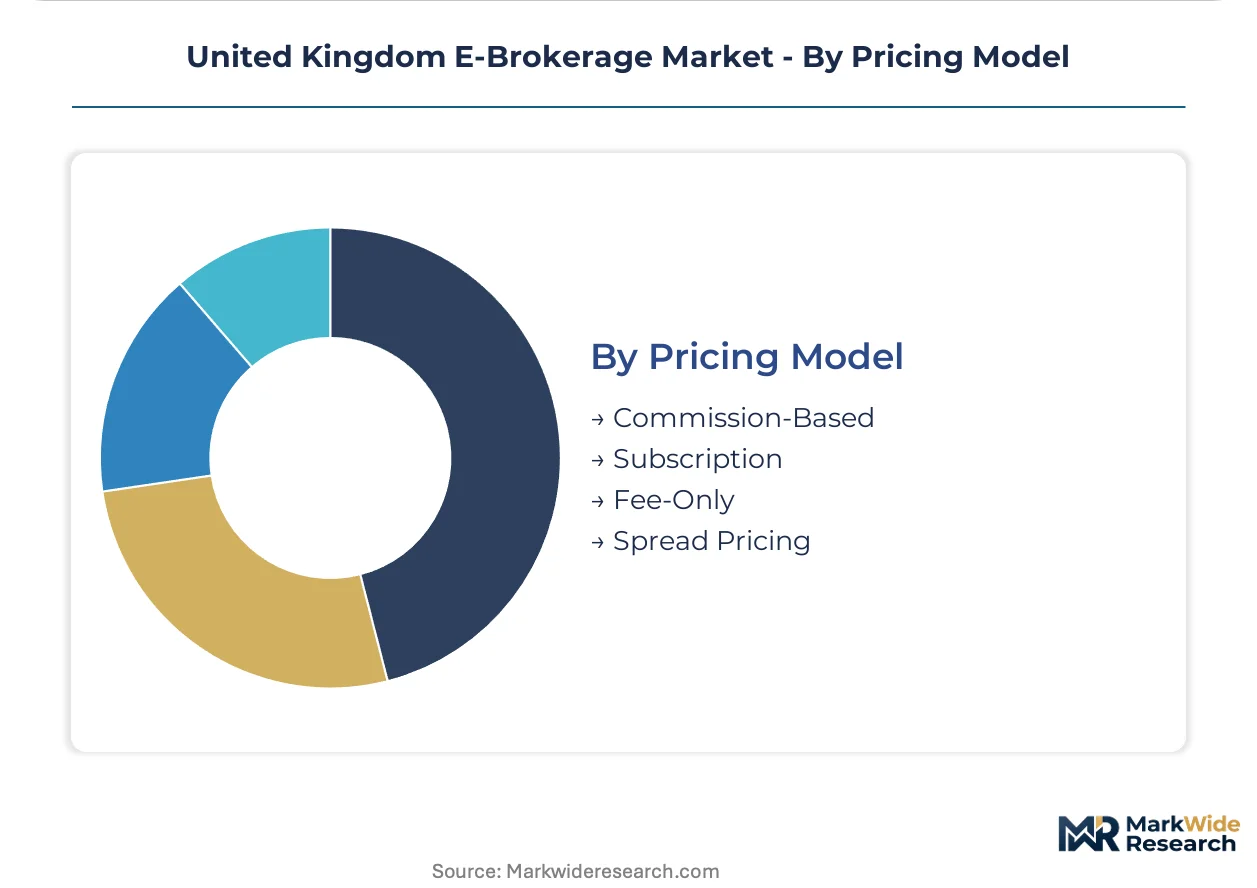
Pricing Model:
Revenue architecture choices face structural pressure from zero-commission entrants, forcing incumbents to rebuild monetization around spread capture and subscription services.
- Commission-Based:Per-trade fees typically ranging from £5-£12 for UK equities. Traditional platforms in the United Kingdom face margin compression as spread-pricing specialists and commission-free entrants erode transaction revenue.
- Spread Pricing:Embedded bid-ask markups with explicit zero-commission positioning. Retail forex and CFD platforms deploy this model aggressively, capturing revenue through execution quality arbitrage.
- Subscription:Flat monthly fees for unlimited trading and premium analytics.
- Fee-Only:Advisory charges decoupled from transaction volume.
Commission-Based models still anchor the revenue mix, though Spread Pricing is expanding most quickly among new entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
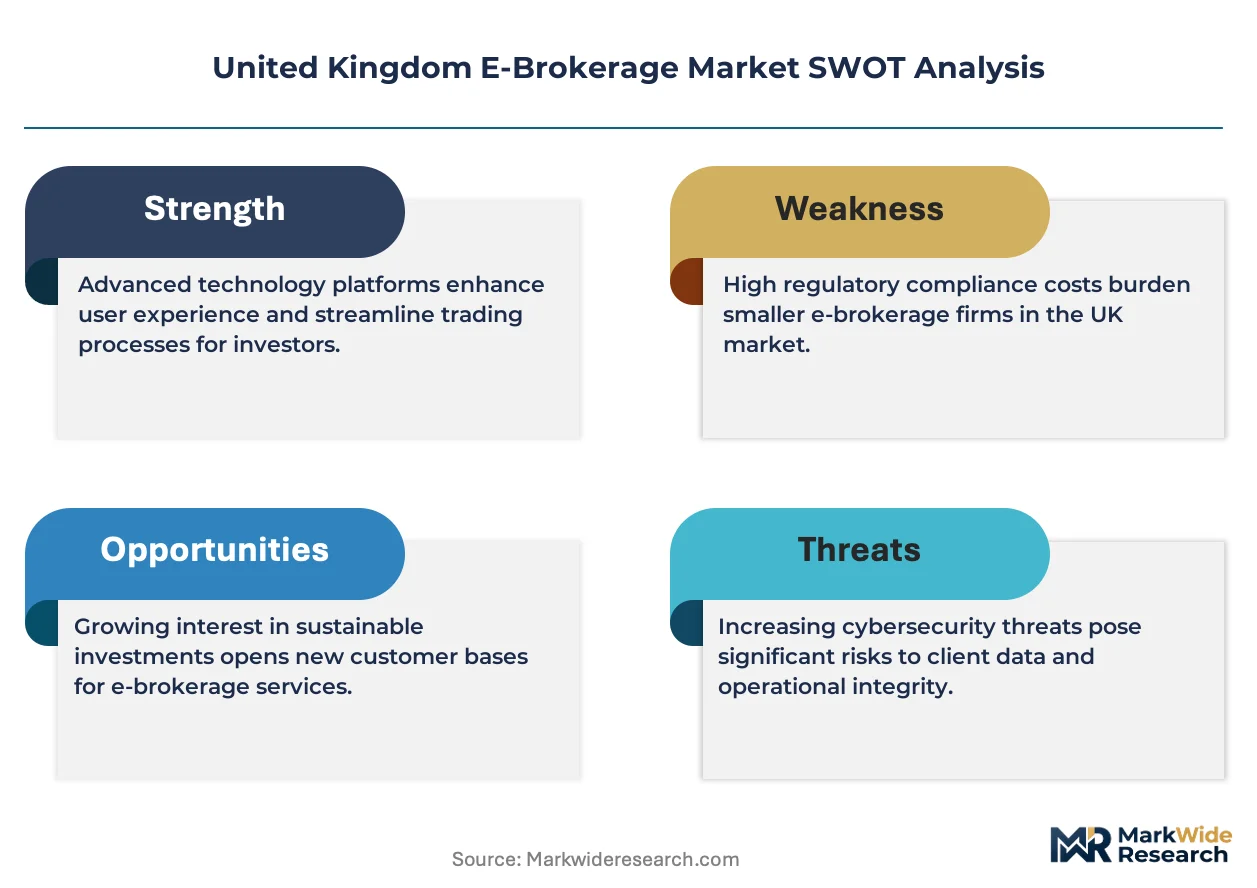
Cost-of-compliance arbitrage is redirecting platform development toward jurisdictions with clearer fintech licensing pathways. The United Kingdom's Financial Conduct Authority consumer duty rules impose infrastructure burdens that smaller platforms struggle to absorb, accelerating consolidation toward firms with compliant tech stacks and established regulatory relationships.
London and Southeast England
The capital's fintech corridor concentrates API-first brokerage development and cloud-native engineering talent. The FCA's consumer duty framework mandates fair value demonstrations and sludge reduction that only modular architectures can deliver at scale. Canary Wharf and Shoreditch clusters host execution-only platforms and robo-advisory startups competing for digitally native investor cohorts.
Midlands
Birmingham and Manchester anchor mid-market wealth management platform operations with lower fixed-cost ratios than London. The Bank of England's Prudential Regulation Authority supervises capital adequacy for e-brokerage entities with banking licenses across this corridor. Platform providers here target self-directed investors migrating from traditional advised relationships in England's urban centers.
North England
Leeds and Newcastle host regional platform operations focused on SIPP consolidation and ISA wrapper services. GDPR compliance architecture increases infrastructure costs for cross-border expansion, constraining scaling into adjacent European markets. Northern platforms compete on flat-fee pricing models that appeal to cost-conscious retail investors outside London's financial district.
Scotland
Edinburgh's established fund management heritage supports hybrid digital-advised platform development. The FCA's evolving digital assets guidance creates compliance ambiguity for blockchain-integrated trading infrastructure. Scottish platforms leverage Edinburgh's asset management talent pool to build algorithmic portfolio construction capabilities for mass-affluent segments.
United Kingdom E-Brokerage Market Competitive Landscape
London-based platforms anchor the premium tier with established brand trust and adviser networks; fintech specialists from England's secondary cities hold the mid-market with competitive pricing on tax-advantaged wrappers. The vendor base stratifies across three tiers: full-service incumbents with legacy client bases, API-native challengers with zero-commission positioning, and spread-pricing specialists in derivatives execution. Strategic moves concentrate on SIPP-ISA architecture integration and robo-advisory mass-affluent penetration.
Within the established incumbent tier, Hargreaves Lansdown PLC and AJ Bell PLC exemplify platform operators leveraging brand trust and adviser networks to sustain retail loyalty. Interactive Investor Services Ltd occupies a position as scale-driven flat-fee platform, differentiating through execution volume rather than per-transaction markups. These three entities represent divergent responses to FCA consumer duty compression: heritage brand defense, mid-market pricing discipline, and scale-based cost absorption.
| Leading Market Players |
|---|
| Hargreaves Lansdown PLC |
| AJ Bell PLC |
| Interactive Investor Services Ltd |
| IG Group Holdings PLC |
| Freetrade Ltd |
| Interactive Brokers |
| eToro |
| Plus500 |
| Capital.com |
| Others |
Pricing and Supply Chain Analysis
Zero-commission positioning by API-native challengers is forcing established platforms to absorb margin compression while rebuilding monetization around subscription services and spread capture. This demand-side pricing pressure feeds directly into supply chain restructuring, as incumbents must source cloud-native engineering talent and modular infrastructure at premium cost to remain competitive.
Pricing Analysis
Direct-to-investor platform access eliminates intermediary markups and compresses channel margins to near-zero for execution-only services. Subscription pricing stratifies across premium analytics tiers, standard flat-fee wrappers, and economy execution-only levels, with price differentiation driven by brand trust and API integration depth. Pricing pressure stems from spread-pricing specialists capturing retail forex and CFD volume. Price-sensitive self-directed investors in England's urban centers migrate fastest toward lowest-cost providers.
Supply Chain Analysis
Regional data center distribution in London, Frankfurt, and Amsterdam anchors hub-and-spoke latency optimization for order routing and portfolio analytics. Cloud infrastructure draws from Ireland, the Netherlands, and the UK for GDPR-compliant data residency. Single-source vulnerability concentrates in hyperscaler dependency for core platform hosting. Distribution runs through API-first middleware layers that separate execution, custody, and analytics into composable service tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in UK e-brokerage hinges on automated advice engines reducing human adviser cost structures while capturing mass-affluent rollover flows into integrated SIPP-ISA architectures.
For Market Incumbents: Anchor brand trust in adviser networks against zero-commission erosion by accelerating API-first infrastructure rebuilds that deliver FCA-compliant transparency at scale. Defensive consolidation toward firms with consumer duty-ready tech stacks will absorb smaller platforms unable to absorb compliance costs. Priority lever rests on robo-advisory capability investment for sub-£100k account penetration. For New Entrants and Emerging Players: Mobile-native onboarding routes offer the lowest customer acquisition friction for digitally native investor cohorts abandoning advised relationships. White-space targets concentrate in SIPP consolidation flows and blockchain-integrated settlement infrastructure. Go-to-market angle should emphasize flat-fee transparency that surfaces hidden costs incumbent platforms obscure. For Investors and Strategic Acquirers: Asymmetric upside sits with API-native challengers possessing modular architectures capable of rapid feature deployment against legacy technical debt. Long-term viability favors firms with established FCA regulatory relationships and compliant consumer duty tech stacks. Watch for pension reform implementation as inflection signal redirecting defined contribution flows toward unified platform models.| Strategic Initiative | Industry Significance |
|---|---|
| Robo-Advisory Capability Buildout | Automated advice engines capture mass-affluent segments without human adviser cost structures. |
| SIPP-ISA Architecture Integration | Unified tax-advantaged wrappers capture pension reform rollover volume from fragmented legacy accounts. |
| API-First Platform Modernization | Modular microservices infrastructure delivers FCA consumer duty compliance at scale with faster iteration cycles. |
| Blockchain Settlement Infrastructure | Distributed ledger integration enables T+0 compression versus traditional clearing for derivatives execution. |
| Strategic Partnership with Cloud Providers | Hyperscaler relationships ensure GDPR-compliant data residency and elastic capacity for volatile trading volumes. |
Research Methodology
Coverage spans the United Kingdom with primary inputs from London's fintech corridor, the Midlands, and North England, combining structured interviews with platform CTOs, FCA regulatory affairs leads, wealth management product directors, and retail investor UX specialists. Secondary validation draws from FCA authorization registers, Bank of England Prudential Regulation Authority disclosures, platform annual reports, and GDPR compliance filings. Bottom-up account-level modeling triangulates against top-down market sizing across service type, customer segment, technology deployment, and pricing architecture dimensions.
Rate-of-change decomposition separates volume expansion from pricing trajectory shifts across the projection horizon. Segmentation modeling incorporates service type evolution, customer cohort migration patterns, technology platform transitions, and regulatory compliance cost absorption. CAGRs derive from historical platform asset growth trajectories, investor switching behavior analysis, and pension flow redirection scenarios. Industry-specific inputs include FCA consumer duty implementation timelines and open banking API adoption curves.
Regulatory enforcement intensity, pension reform sequencing, and cloud infrastructure cost inflation are the dominant revision risks that could compress or extend modeled outcomes. Forecasts reflect documented assumptions around platform consolidation velocity and investor demographic shifts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Banking Cloud Services Market
Financial Services
Hong Kong Trade Finance Market
Financial Services
North America Financial Advisory Services Market
Financial Services
North America B2C Legal Services Market
Financial Services
Africa Factoring Services Market
Financial Services
Belgium Gift Card and Incentive Card Market
Financial Services
Canada Credit Cards Market
Financial Services
India Payroll Services Market
Financial Services
South Korea Financial Services Software Market
Financial Services
Debt Settlement Solution Market
Financial Services
Capital Restructuring Services Market
Financial Services
Germany Factoring Services Market
Financial Services
BFSI A2P SMS Market
Financial Services
United States Payroll Services Market
Financial Services
Outsource Debt Collection Services Market
Financial Services
Banknote Counters Market