
 Commercial Debt Collection Software Market | 2026-2036
Commercial Debt Collection Software Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Debt Collection Software Market Insights
Buyer concentration among large financial institutions is decoupling from the long tail of mid-market collection agencies, creating divergent product requirements across the demand base. HighRadius leverages AI-driven cash application tools to anchor enterprise relationships with Fortune 500 treasuries. Gaviti sustains its position through specialized A/R automation workflows designed for high-volume B2B receivables. Tesorio competes by embedding predictive analytics directly into ERP connectors, reducing implementation friction for mid-market CFOs.
Commercial debt collection software encompasses platforms that automate receivables recovery through predictive dialing algorithms, machine learning-based debtor scoring, and multi-channel communication orchestration across email, SMS, and voice. These systems process delinquency data in real time to prioritize collection queues and generate compliance-auditable interaction logs for regulatory examination. Cloud-based deployment leads segment adoption as collection agencies seek elastic infrastructure without capital-intensive server commitments. Payment processing solutions capture disproportionate margin pools by embedding transaction fees into recovery workflows, while skip tracing functionality grows fastest among debt buyers pursuing portfolio acquisition strategies.
The US Consumer Financial Protection Bureau enforces debt collection communication standards under Regulation F, compelling software vendors to build consent management and contact-frequency guardrails into platform architectures. State-level debt collection licensing regimes in California, New York, and Texas add jurisdictional complexity that favors configurable compliance engines over rigid legacy systems. Stakeholders must monitor evolving state privacy laws and open banking API standards as these frameworks determine which platforms can maintain lawful data access and automated payment initiation capabilities.
Market Dynamics
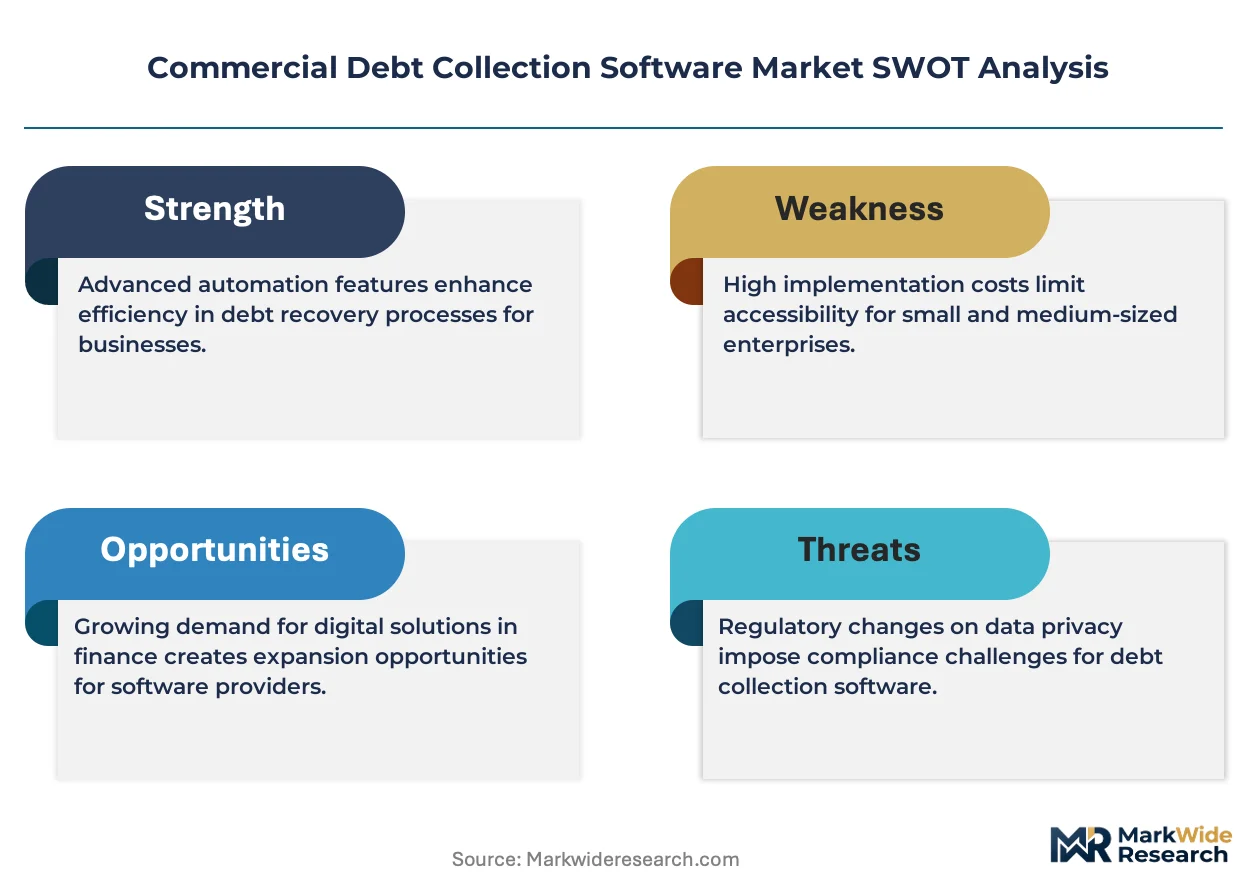
Automated compliance engines are restructuring competitive positioning across the commercial debt collection software landscape, as vendors race to embed real-time regulatory guardrails that satisfy the US Consumer Financial Protection Bureau's evolving enforcement posture.
Growth Catalysts
- Regulation F Enforcement:The US Consumer Financial Protection Bureau's contact-frequency rules are compelling financial institutions to replace legacy systems with platforms featuring built-in consent management and auditable interaction logs.
- Open Banking APIs:Payment initiation capabilities through standardized banking interfaces are accelerating automated recovery workflows and reducing manual reconciliation overhead for collection agencies.
- Cloud Infrastructure Elasticity:Collection agencies are migrating from on-premise servers to cloud-based deployments that scale processing capacity during seasonal delinquency spikes without capital-intensive hardware commitments.
Market Restraints
- State Licensing Fragmentation:California, New York, and Texas maintain divergent debt collection licensing regimes that force vendors to engineer configurable compliance modules rather than standardized platforms.
- Legacy System Entrenchment:Large financial institutions operate decades-old mainframe architectures that resist API-based integration with modern collection orchestration tools.
- Data Privacy Constraints:Emerging state privacy laws in the United States are restricting skip-tracing data sources and complicating debtor contact information acquisition for collection agencies.
Strategic Opportunities
- Mid-Market CFO Automation:ERP-embedded predictive analytics remain underpenetrated among mid-market enterprises seeking reduced implementation friction for receivables management.
- Multi-Channel Communication Convergence:Platforms combining machine learning-based debtor scoring with SMS, email, and voice orchestration are capturing premium positioning in high-volume B2B segments.
- Payment Processing Integration:Transaction fee embedding within recovery workflows creates recurring revenue streams that decouple vendor economics from pure software licensing.
Industry Challenges
- Compliance Engineering Talent Scarcity:Vendors struggle to recruit software architects capable of translating Regulation F's contact-frequency guardrails into automated platform logic.
- Integration Complexity:Collection agencies face extended deployment timelines when connecting modern cloud platforms to existing core banking systems and credit bureau interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Debt Collection Software Market |
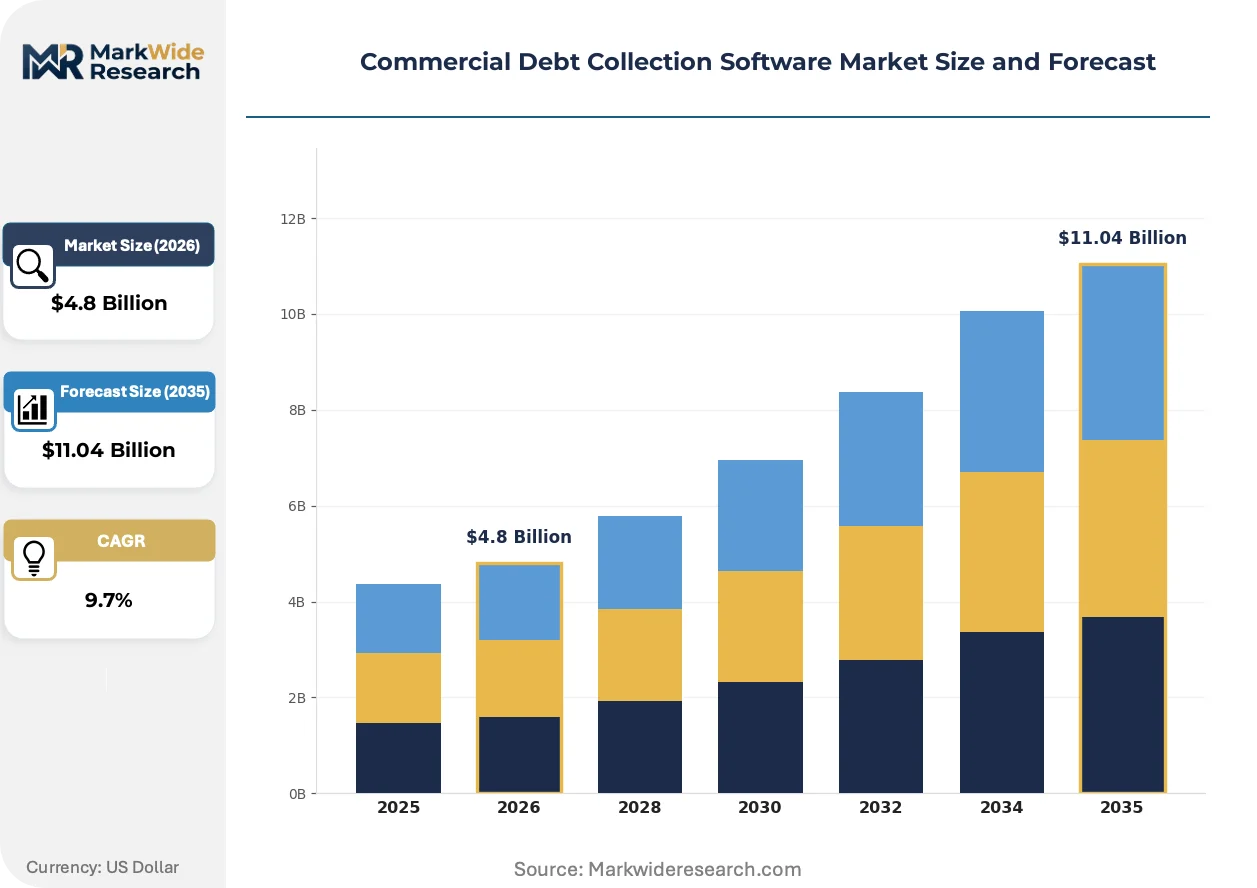
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS Solution Type: Automated Dialer, Skip Tracing, Payment Processing, Credit Reporting Application: Corporate Collections, Utility Billing, B2B Receivables, Healthcare Billing End User: Debt Buyers, Financial Institutions, Collection Agencies, Creditors |
| Companies Covered | Gaviti, Kolleno, HighRadius, Tesorio, Chaser, C&R Software, Versapay, Upflow, Daylit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Debt Collection Software Market Trends and Innovations
Artificial intelligence is compressing decision cycles across receivables recovery, with predictive models now prioritizing collection queues in real time rather than relying on static rules-based scoring.
Machine learning-based debtor scoring is integrating behavioral prediction algorithms that forecast payment probability using transaction history, employment data, and communication response patterns. Enterprise treasuries at Fortune 500 manufacturers are adopting these tools at accelerated pace to reduce days sales outstanding. The technology is integrating cash application workflows with collection prioritization, collapsing previously separate software categories into unified platforms.
The US Fair Debt Collection Practices Act amendments and Regulation F implementation are mandating consent management architectures that log every debtor contact attempt for regulatory examination. Vendors must now engineer time-zone-aware dialing restrictions and seven-contact-per-week ceilings directly into platform codebases. Mid-market collection agencies in the United States are responding by abandoning rigid legacy systems in favor of configurable compliance engines that adapt to state-level variations.
Buyer procurement patterns are fragmenting between enterprise treasuries demanding end-to-end A/R automation and specialized collection agencies seeking point solutions for skip tracing or payment processing. Traditional software vendors with monolithic suites are losing ground to modular platforms that embed through ERP connectors. This bifurcation is most visible in the United States, where CFOs at mid-market B2B enterprises increasingly favor predictive analytics modules over comprehensive collection system replacements.
Commercial Debt Collection Software Market Segmentation
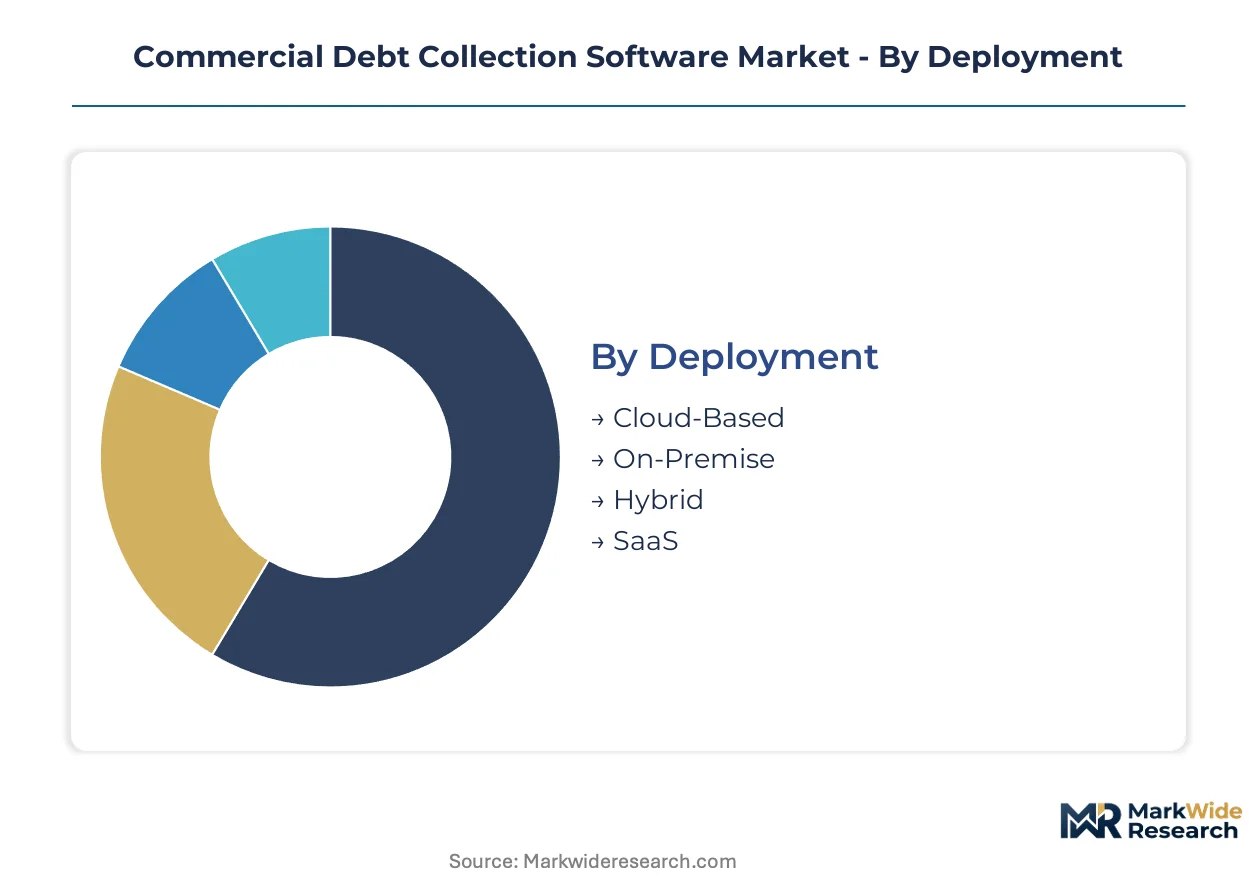
Commercial debt collection software segments diverge sharply in capital requirements, with cloud-native architectures demanding minimal upfront infrastructure while legacy on-premise installations require substantial hardware commitments. Procurement patterns across these categories reflect divergent risk tolerances among debt buyers, collection agencies, and financial institutions.
Deployment:
Capital intensity varies dramatically across deployment modes, with on-premise installations requiring server hardware, data center leases, and dedicated IT staffing while cloud alternatives shift costs to recurring operational expenditure.
- Cloud-Based:Elastic infrastructure provisions processing capacity through distributed server networks, eliminating capital-intensive hardware procurement for collection agencies. Demand concentrates among mid-market agencies in Texas and Florida seeking rapid scaling during seasonal delinquency spikes without fixed asset commitments.
- On-Premise:Dedicated server installations within agency-controlled facilities demand substantial upfront capital for hardware acquisition and facility preparation. Large financial institutions in New York and California maintain these deployments to satisfy internal data sovereignty policies and legacy security audit protocols.
- Hybrid:Split architectures combine on-premise core systems with cloud burst capacity for peak processing periods.
- SaaS:Fully managed software subscriptions deliver collection platforms through browser interfaces without local installation requirements.
On-Premise absorbs the bulk of installed capacity among legacy financial institutions; Cloud-Based is expanding most quickly among digitally native collection agencies.
Solution Type:
Functional specialization determines margin capture, with payment processing solutions embedding recurring transaction fees while dialer and tracing tools rely on seat-based licensing.
- Automated Dialer:Predictive algorithms prioritize call queues using machine learning models that forecast debtor contact probability and optimal timing. Demand concentrates at collection agencies serving healthcare billing verticals, where Regulation F contact-frequency limits necessitate precision targeting to maximize recovery rates per permissible interaction.
- Skip Tracing:Data aggregation engines locate debtor contact information through credit bureau interfaces, employment records, and utility connection databases. Debt buyers pursuing portfolio acquisitions in California and Texas drive adoption, leveraging expanded data access before emerging state privacy constraints tighten skip-tracing source availability.
- Payment Processing:Embedded transaction infrastructure captures fees on recovered amounts, creating recurring revenue streams decoupled from software licensing cycles.
- Credit Reporting:Automated bureau submission tools streamline delinquency reporting to Equifax, Experian, and TransUnion.
Automated Dialer commands the largest installed base; Skip Tracing is climbing the fastest as debt buyers expand portfolio acquisition strategies.
Application:
Regulatory complexity shapes application-level procurement, with healthcare and utility verticals facing distinct compliance architectures that favor specialized platform configurations.
- Corporate Collections:Enterprise receivables management platforms integrate with SAP and Oracle ERP systems to automate dunning workflows for Fortune 500 manufacturers. Demand concentrates in Illinois and Ohio industrial corridors, where days sales outstanding reduction drives CFO sponsorship of predictive analytics implementations.
- B2B Receivables:High-volume commercial account platforms prioritize customer relationship preservation through graduated escalation sequences. Mid-market enterprises in Georgia and North Carolina favor these tools, balancing recovery velocity against ongoing vendor relationship maintenance in concentrated supply chain ecosystems.
- Utility Billing:Municipal and investor-owned utility deployments incorporate service shutoff coordination and low-income assistance program integration.
- Healthcare Billing:Patient account platforms embed HIPAA compliance guardrails and charity care eligibility screening alongside standard collection workflows.
Corporate Collections retains the deepest installed base; B2B Receivables is gaining share fastest as mid-market CFOs prioritize ERP-embedded solutions.
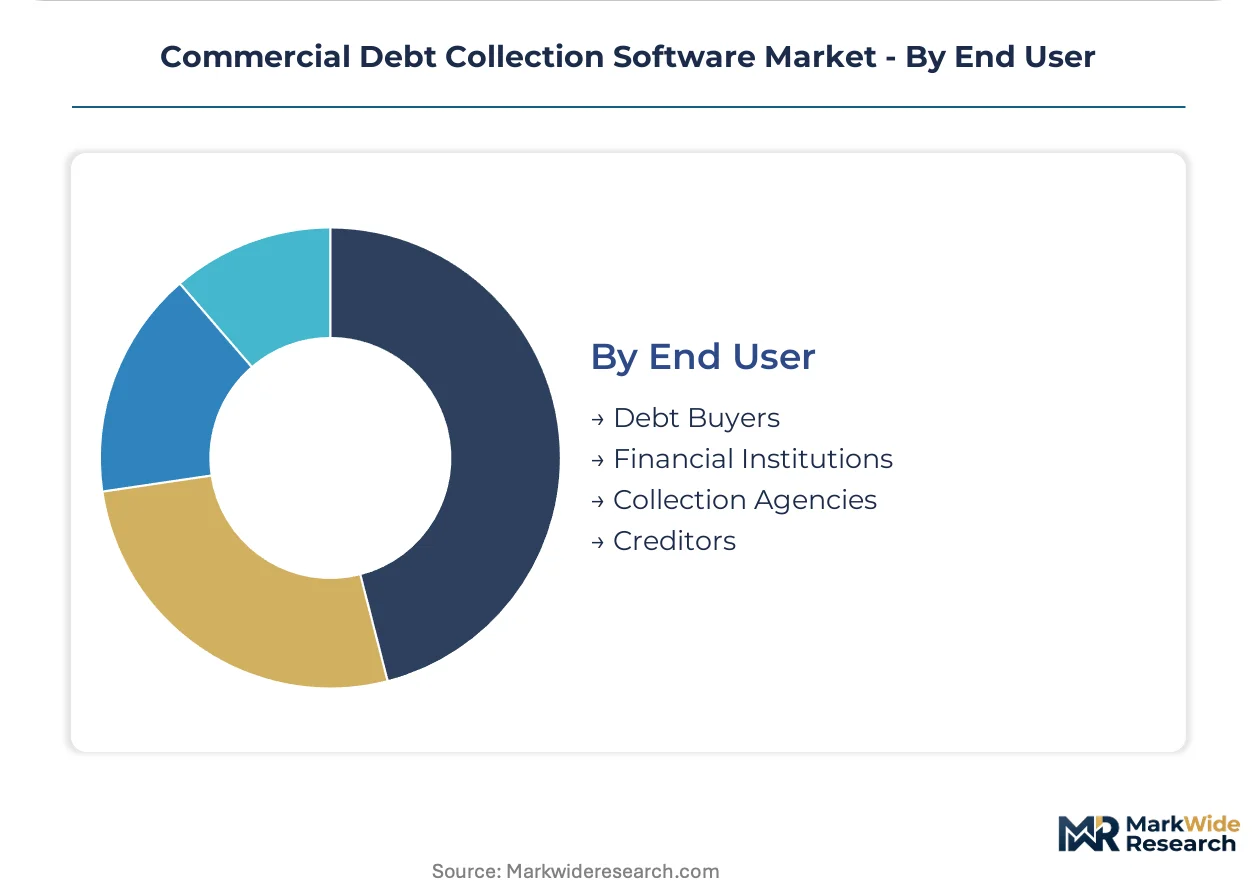
End User:
Buyer sophistication and procurement scale fragment sharply across end-user categories, with financial institutions demanding enterprise-grade integration while debt buyers prioritize portfolio-level analytics.
- Collection Agencies:Third-party recovery specialists operating under contingency fee structures require high-volume processing capacity with minimal per-seat cost escalation. Demand concentrates among agencies in Arizona and Nevada serving national creditor portfolios, where seasonal staffing fluctuations favor elastic cloud infrastructure over fixed licensing commitments.
- Financial Institutions:Banks and credit unions maintain first-party collection operations with direct borrower relationships and regulatory examination exposure. Institutions in Massachusetts and Washington deploy these platforms to satisfy Consumer Financial Protection Bureau consent order requirements for auditable interaction logging and contact-frequency enforcement.
- Debt Buyers:Distressed asset investors prioritize skip tracing and valuation analytics for portfolio acquisition due diligence.
- Creditors:Original lenders retaining collection in-house focus on customer retention and brand protection alongside recovery optimization.
Collection Agencies represent the largest addressable user base; Financial Institutions are expanding most quickly as first-party recovery operations replace legacy mainframe systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial debt collection software procurement concentrates in the United States, where regulatory enforcement and legacy system replacement cycles generate sustained demand. Financial institutions across North America and Europe are accelerating platform investments to satisfy evolving compliance mandates. Cloud-native vendors are capturing share in Asia-Pacific markets as digital lending volumes expand.
United States
Financial institutions in New York and California are replacing decades-old mainframe systems with API-enabled collection platforms. The Consumer Financial Protection Bureau's Regulation F contact-frequency rules compel vendors to embed consent management architectures directly into software codebases. Collection agencies in Texas and Florida favor elastic cloud infrastructure to scale processing during seasonal delinquency spikes.
United Kingdom
Mid-market B2B enterprises in London and the Southeast are adopting ERP-embedded predictive analytics to reduce days sales outstanding. The Financial Conduct Authority's consumer credit rules shape platform requirements for consent logging and auditable interaction trails. Fintech clusters in Manchester and Edinburgh are driving demand for modular collection tools that integrate with open banking APIs.
Germany
Industrial manufacturers in Bavaria and North Rhine-Westphalia deploy receivables automation to manage complex supply chain payment terms. The Federal Financial Supervisory Authority's conduct standards influence vendor engineering priorities for transparency and debtor protection. Software procurement in Frankfurt's banking corridor emphasizes compliance-first architectures for cross-border recovery operations.
India
Digital lending platforms in Maharashtra and Karnataka are integrating collection orchestration tools as unsecured credit volumes surge. The Reserve Bank of India's guidelines on fair practices in debt collection mandate structured communication protocols and grievance redressal mechanisms. Fintech hubs in Bangalore and Mumbai are driving adoption of multi-channel debtor engagement platforms with regional language capabilities.
Australia
Utilities and telecommunications providers in New South Wales and Victoria are modernizing billing recovery systems to reduce customer churn. The Australian Securities and Investments Commission's debt collection guidelines require platforms to document contact attempts and honor hardship arrangements. Sydney-based financial services firms are investing in cloud-native solutions to satisfy APRA operational resilience standards.
Commercial Debt Collection Software Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue ERP-embedded specialization and AI-driven cash application. The vendor landscape fragments across three functional tiers: enterprise treasuries demanding end-to-end A/R automation, mid-market CFOs seeking reduced implementation friction, and specialized collection agencies prioritizing skip-tracing and payment processing modules. Strategic differentiation concentrates on compliance engine configurability and open banking API integration. Competitive moves center on strategic partnerships with ERP providers and geographic expansion through cloud delivery models.
Within the enterprise automation tier, HighRadius and Tesorio represent distinct architectural approaches to receivables intelligence. Gaviti occupies a position among specialized A/R workflow providers serving high-volume B2B segments. These three companies exemplify the market's bifurcation between comprehensive platforms and modular point solutions, with each archetype capturing distinct procurement budgets across financial institutions and mid-market enterprises.
| Leading Market Players |
|---|
| Gaviti |
| Kolleno |
| HighRadius |
| Tesorio |
| Chaser |
| C&R Software |
| Versapay |
| Upflow |
| Daylit |
| Others |
Pricing and Supply Chain Analysis
Cloud infrastructure spot pricing indices cascade through commercial debt collection software supply chains, compressing margins for on-premise vendors while amplifying pricing power for elastic SaaS providers serving seasonal collection agencies.
Pricing Analysis
Volume concentration among large financial institutions against margin capture by specialized mid-market modules defines the pricing architecture. Three-tier pricing structure across enterprise, professional, and basic levels separates API-rich compliance engines from stripped-down dialer tools. Pricing pressure stems from open-source communication libraries commoditizing core dialer functionality. Mid-market collection agencies exhibit highest price sensitivity, while Fortune 500 treasuries prioritize integration depth over license cost.
Supply Chain Analysis
Telephony API supply rests on Twilio and Vonage infrastructure concentrated in the United States, with regional redundancy from European providers. Cloud compute capacity draws from AWS, Azure, and Google Cloud data centers, while compliance engine development hinges on specialized legal-software engineering talent pools. Single-source vulnerability concentrates in voice recognition training datasets licensed from narrow AI providers. Distribution runs through direct enterprise sales teams and ERP marketplace channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compliance engineering talent scarcity props pricing power for vendors with automated regulatory guardrails, as financial institutions face CFPB consent orders demanding auditable system replacements.
For Market Incumbents: Lock in enterprise relationships by embedding cash application workflows directly into SAP and Oracle ERP connectors. Acquire mid-market predictive analytics specialists before modular competitors capture CFO procurement budgets. Prioritize compliance engine configurability for state-level licensing variations. For New Entrants and Emerging Players: Mid-market B2B enterprises in Georgia and North Carolina represent the most penetrable buyer archetype, underserved by legacy dialer vendors. White-space exists in healthcare billing verticals requiring HIPAA-embedded collection platforms. Go-to-market through QuickBooks and Xero marketplace integrations reduces sales cycle friction. For Investors and Strategic Acquirers: Distressed-cycle entries favor cloud-native compliance engine developers in Texas and Florida, where seasonal delinquency spikes drive elastic infrastructure demand. Long-term viability hinges on open banking API integration depth. Watch CFPB enforcement intensity as inflection signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ERP Connector Development | SAP and Oracle integrations reduce implementation timelines for Fortune 500 treasuries. |
| Compliance Engine Acquisition | Regulation F expertise accelerates time-to-market for auditable interaction logging. |
| Open Banking Partnership | Payment initiation APIs automate recovery workflows and reduce manual reconciliation. |
| Cloud Infrastructure Expansion | Elastic capacity serves Texas and Florida agencies during seasonal delinquency spikes. |
| Healthcare Vertical Specialization | HIPAA-embedded workflows capture patient account management procurement budgets. |
Research Methodology
SEC filings, CFPB enforcement actions, and cloud infrastructure capex disclosures formed the secondary backbone, cross-referenced with interviews of collection agency operations directors, bank compliance officers, ERP integration specialists, and SaaS procurement managers. Bottom-up sizing of vendor licensing revenue triangulated against top-down financial institution IT spending estimates.
Historical trendline analysis of legacy system replacement cycles informed projection modeling across deployment mode, organization size, vertical application, integration complexity, and regional regulatory cluster dimensions. CAGRs derived from segment-level growth rate reconciliation with aggregate market expansion. Forecast inputs incorporated open banking API adoption curves and state privacy law implementation timelines.
Revisions become necessary when CFPB enforcement posture shifts, state licensing regimes fragment further, or cloud infrastructure pricing experiences sustained volatility. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
BFSI A2P SMS Market
Financial Services
Global Product Cost Management Market
Financial Services
US Online Trading Platform Market
Financial Services
Global Temporary Labor Market
Financial Services
Credit Rating Software Market
Financial Services
North America Financial Advisory Services Market
Financial Services
UK Islamic Finance Market
Financial Services
Pawn Shop Market
Financial Services
Account Aggregators Market
Financial Services
Global Trust and Corporate Service Market
Financial Services
Cash Flow Market
Financial Services
Currency Management Market
Financial Services
North America Trade Finance Market
Financial Services
Financial Services Operational Risk Management Solution Market
Financial Services
ATM Managed Services Market
Financial Services
Mobile Notary Service Market