
 Tyrosine Kinase Inhibitors Market | 2026-2036
Tyrosine Kinase Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Tyrosine Kinase Inhibitors Market Outlook
Hospital formulary access is narrowing as pharmacy benefit managers tighten prior authorization criteria for oral oncology agents. Novartis leverages its established imatinib franchise to sustain institutional relationships across academic medical centers. Pfizer competes through differentiated kinase selectivity profiles in its late-stage pipeline. Bristol Myers Squibb anchors its position via integrated diagnostic partnerships that pair biomarker testing with targeted therapy enrollment.
Tyrosine kinase inhibitors are small-molecule pharmaceuticals that competitively bind ATP sites on receptor and non-receptor tyrosine kinases, blocking phosphorylation cascades that drive oncogenic cell proliferation. These compounds are synthesized through multi-step organic chemistry involving Suzuki coupling and chiral resolution, then formulated for oral bioavailability to enable chronic outpatient administration in cancer treatment. The therapy area segmentation shows oncology commanding the dominant share, with cardiovascular and autoimmune applications representing earlier-stage expansion zones where investigators are repurposing select agents. Oral delivery mode dominates commercial volume due to patient convenience and cost advantages over intravenous administration, though injectable formulations retain higher per-dose pricing in hospital outpatient settings.
The FDA, EMA, and China's NMPA collectively shape market access through divergent evidentiary standards for accelerated approval and post-marketing confirmatory trial requirements. The FDA's Project Optimus is pushing dose-optimization studies earlier in development, while EMA's revised oncology guidelines demand richer quality-of-life data for full marketing authorization. Stakeholders must monitor how regulator convergence or divergence on confirmatory trial design affects portfolio prioritization and geographic launch sequencing.
Market Dynamics
Pharmacy benefit managers are tightening prior authorization protocols for oral oncology agents, compressing formulary access and forcing manufacturers to demonstrate superior biomarker specificity earlier in clinical development.
Growth Catalysts
- FDA Project Optimus:The dose-optimization mandate accelerates adaptive trial designs, reducing late-stage failure rates for kinase-selective candidates.
- Academic medical center expansion:Major hospital systems in the United States, China, and Germany are scaling precision medicine infrastructure and integrated diagnostic pathways.
- Chiral resolution advances:Improved enantioselective synthesis methods are lowering production costs for ATP-competitive small molecules.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient manufacturing clusters in coastal China create single-point vulnerability for multi-step Suzuki coupling intermediates.
- Confirmatory trial burden:EMA's revised oncology guidelines demanding richer quality-of-life data extend timelines to full marketing authorization.
- Generic erosion pressure:Imatinib and first-generation BCR-ABL inhibitors face accelerating substitution from compounding pharmacies.
Strategic Opportunities
- Cardiovascular repurposing:VEGF and PDGF pathway inhibitors show promise in heart failure and pulmonary arterial hypertension indications.
- China NMPA breakthrough pathway:Accelerated approval for domestic innovation creates first-mover advantage for localized kinase development.
- Companion diagnostic bundling:Integrated biomarker testing with targeted therapy enrollment locks in institutional formulary placement.
Industry Challenges
- Translational pharmacology expertise:Scarcity of investigators capable of bridging preclinical kinase selectivity data to clinical biomarker strategy.
- Post-marketing surveillance infrastructure:Manufacturers must build real-world evidence collection systems to satisfy FDA confirmatory requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tyrosine Kinase Inhibitors Market |
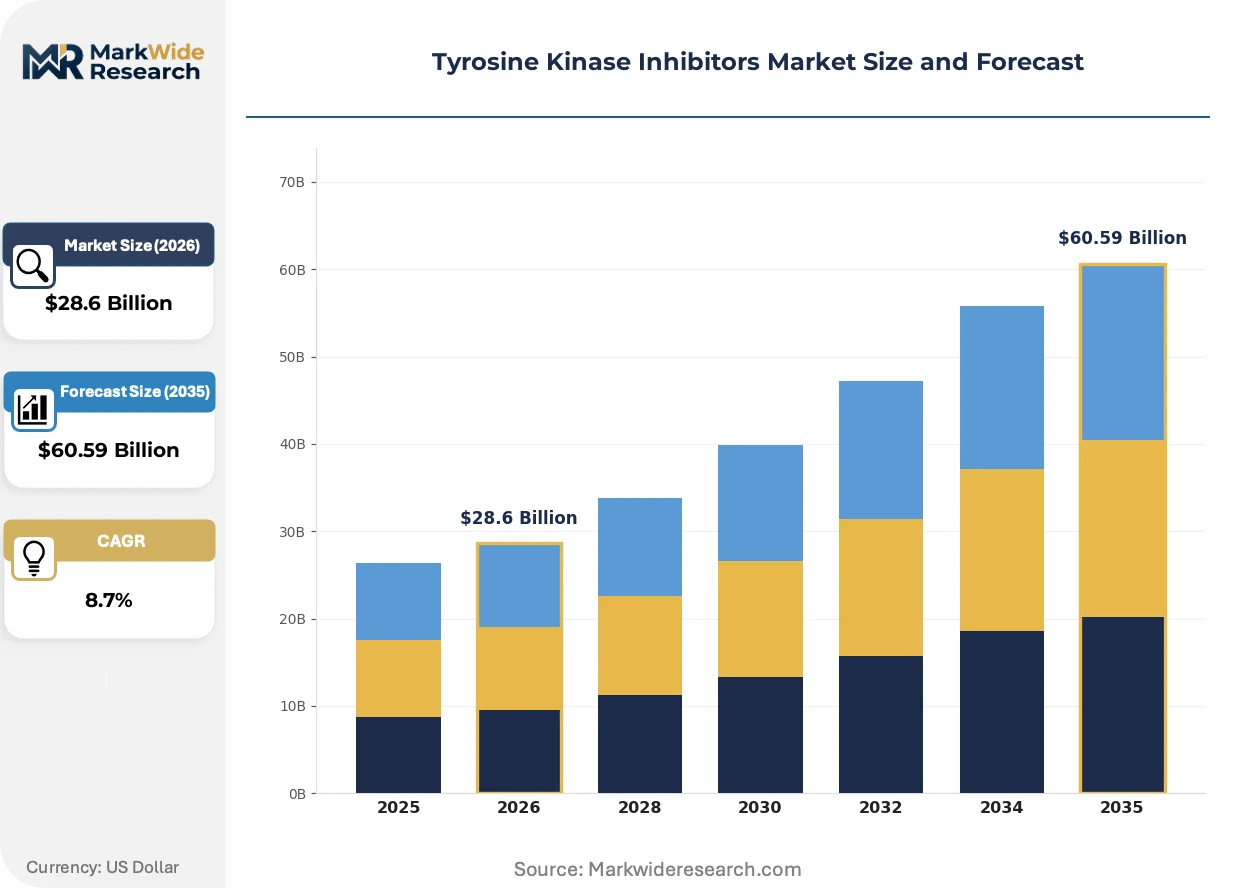
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imatinib, Erlotinib, Dasatinib, Sorafenib Therapy Area: Cancer, Cardiovascular Disorders, Autoimmune Disorders, Neurological Disorders Delivery Mode: Oral, Injectable, Transdermal, Intravenous End User: Hospitals, Clinics, Home Care, Research Labs |
| Companies Covered | AstraZeneca, Novartis, F. Hoffmann-La Roche, Boehringer Ingelheim International, Bayer, Pfizer, Bristol Myers Squibb, Johnson & Johnson, Merck & Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tyrosine Kinase Inhibitors Market Strategic Shifts
Artificial intelligence platforms are compressing target identification timelines, while regulator convergence on dose-optimization standards and hospital consolidation reshape competitive positioning.
Next-generation sequencing is digitizing patient stratification for kinase inhibitor trials. Oncology departments at academic medical centers in the United States and Germany are adopting comprehensive genomic profiling as standard-of-care within 14 days of diagnosis. This molecular characterization is digitizing enrollment into biomarker-matched protocols, collapsing the traditional 90-day screening window.
REACH and RoHS compliance requirements in Europe are forcing reformulation of synthetic intermediates containing residual palladium catalysts. Contract manufacturers serving EU markets are investing in continuous flow chemistry to eliminate heavy metal contamination. Small-molecule API suppliers targeting EMA approval must now document green chemistry metrics alongside traditional purity specifications.
Hospital procurement departments are consolidating oral oncology purchasing through specialty pharmacy networks, displacing traditional wholesale distribution. Integrated delivery networks in the United States are negotiating risk-sharing arrangements that tie reimbursement to progression-free survival metrics. This performance-linked contracting is most advanced in Medicare Advantage populations, where pharmacy benefit managers extract deeper discounts for preferred kinase inhibitor placement.
Tyrosine Kinase Inhibitors Market Segmentation
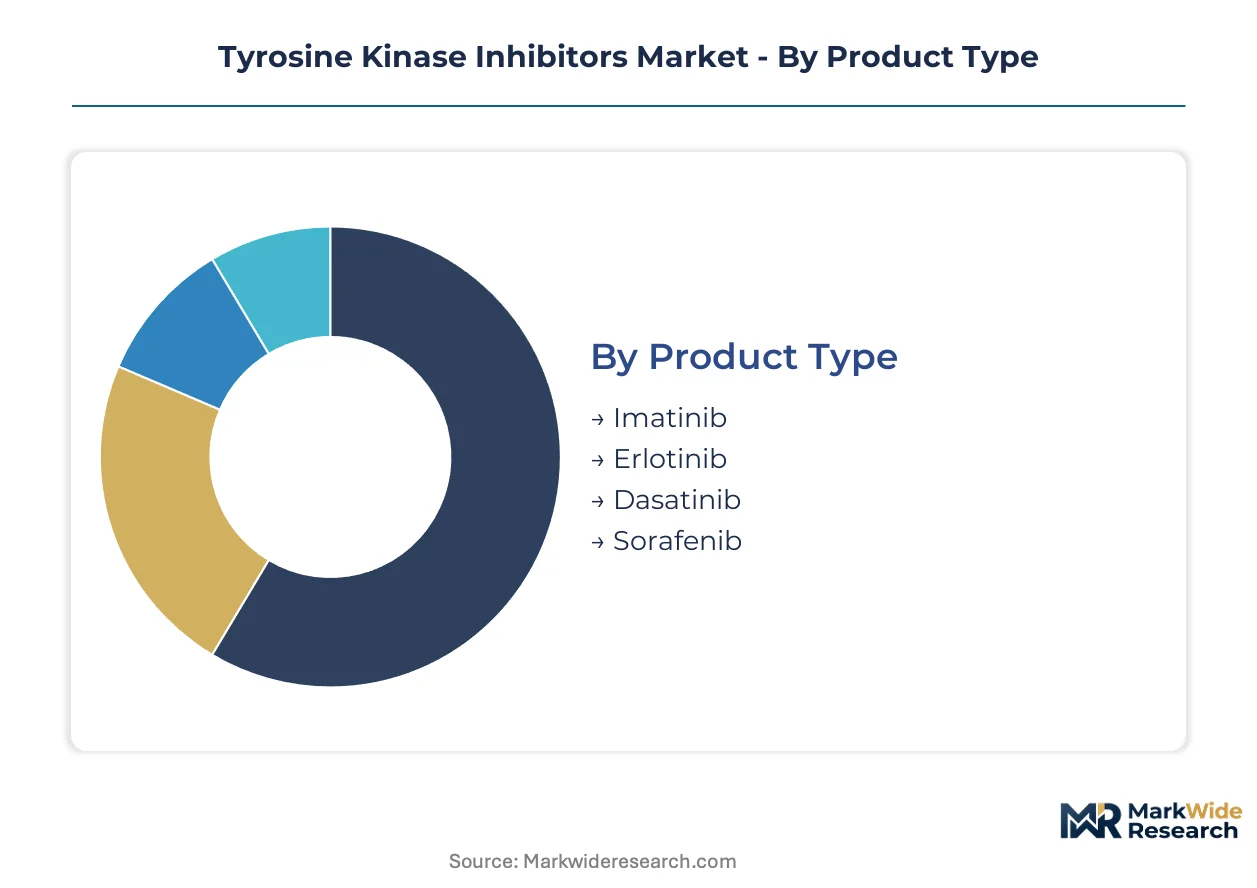
Tyrosine kinase inhibitors segment across four critical dimensions that determine pricing power, distribution pathways, and patient access protocols. Each category carries distinct regulatory, clinical, and commercial characteristics that shape manufacturer strategy.
Product Type:
After-sales service intensity varies sharply across this category, with first-generation agents requiring extensive pharmacovigilance infrastructure while newer entrants demand specialized biomarker support programs.
- Dasatinib:A second-generation BCR-ABL inhibitor with broader kinase selectivity against imatinib-resistant mutations. Demand concentrates in academic medical centers across Germany and the United States where Philadelphia chromosome-positive leukemia protocols are most advanced, driven by mutation profiling capabilities that identify T315I resistance.
- Sorafenib:A multi-kinase inhibitor targeting VEGFR, PDGFR, and RAF pathways with established hepatocellular carcinoma and renal cell carcinoma indications. Prescription volume clusters in hospital outpatient departments in China and the United States where liver cancer screening programs are scaling, constrained by hepatotoxicity monitoring requirements that limit community prescribing.
- Imatinib:The foundational BCR-ABL tyrosine kinase inhibitor with chronic myeloid leukemia as its primary indication.
- Erlotinib:An EGFR-targeting agent approved for non-small cell lung cancer and pancreatic cancer.
By volume, imatinib leads due to generic substitution and chronic myeloid leukemia prevalence. By growth pace, dasatinib is expanding most quickly as resistance testing becomes standard-of-care.
Therapy Area:
Cost tier stratification dominates this category, with oncology commanding premium pricing and cardiovascular applications requiring value-based contracting frameworks.
- Cancer:The dominant therapeutic application spanning hematologic malignancies and solid tumors. Treatment protocols concentrate in tertiary oncology centers across the United States, China, and Germany where comprehensive genomic profiling enables biomarker-matched therapy selection, with FDA Project Optimus dose-optimization mandates reshaping clinical trial design.
- Cardiovascular Disorders:Emerging repurposing opportunity for VEGF and PDGF pathway inhibitors in heart failure and pulmonary arterial hypertension. Clinical investigation clusters at German and United States academic medical centers with established cardiovascular regenerative medicine programs, driven by unmet need in rare cardiopulmonary conditions.
- Autoimmune Disorders:Early-stage investigation of kinase inhibitors in rheumatoid arthritis and inflammatory bowel disease.
- Neurological Disorders:Preclinical exploration of blood-brain barrier penetrant compounds for glioblastoma and neurodegenerative conditions.
By revenue concentration, cancer dominates. By pipeline investment velocity, cardiovascular disorders are gaining share fastest as repurposing studies advance.
Delivery Mode:
Volume distribution patterns separate this category, with oral formulations reaching chronic outpatient populations while injectable agents retain hospital-based administration.
- Oral:Small-molecule tablets and capsules enabling chronic outpatient administration with superior patient adherence and cost efficiency. Manufacturing scale concentrates with contract development organizations in coastal China and India serving United States and European markets, driven by pharmacy benefit manager preference for oral oncology agents that reduce infusion center utilization.
- Intravenous:Hospital-administered formulations for acute oncology protocols and patients with compromised gastrointestinal absorption. Utilization concentrates in Medicare Advantage hospital outpatient departments across the United States where reimbursement differentials favor injectable administration, constrained by prior authorization requirements that limit community infusion center access.
- Injectable:Subcutaneous and intramuscular formulations for specific clinical scenarios.
- Transdermal:Experimental delivery systems under investigation for chronic pain and localized therapy.
By prescription volume, oral delivery leads. By per-dose pricing, intravenous administration commands premium reimbursement.
End User:
Customer type differentiation structures this category, with institutional procurement patterns diverging sharply from retail and direct-to-patient channels.
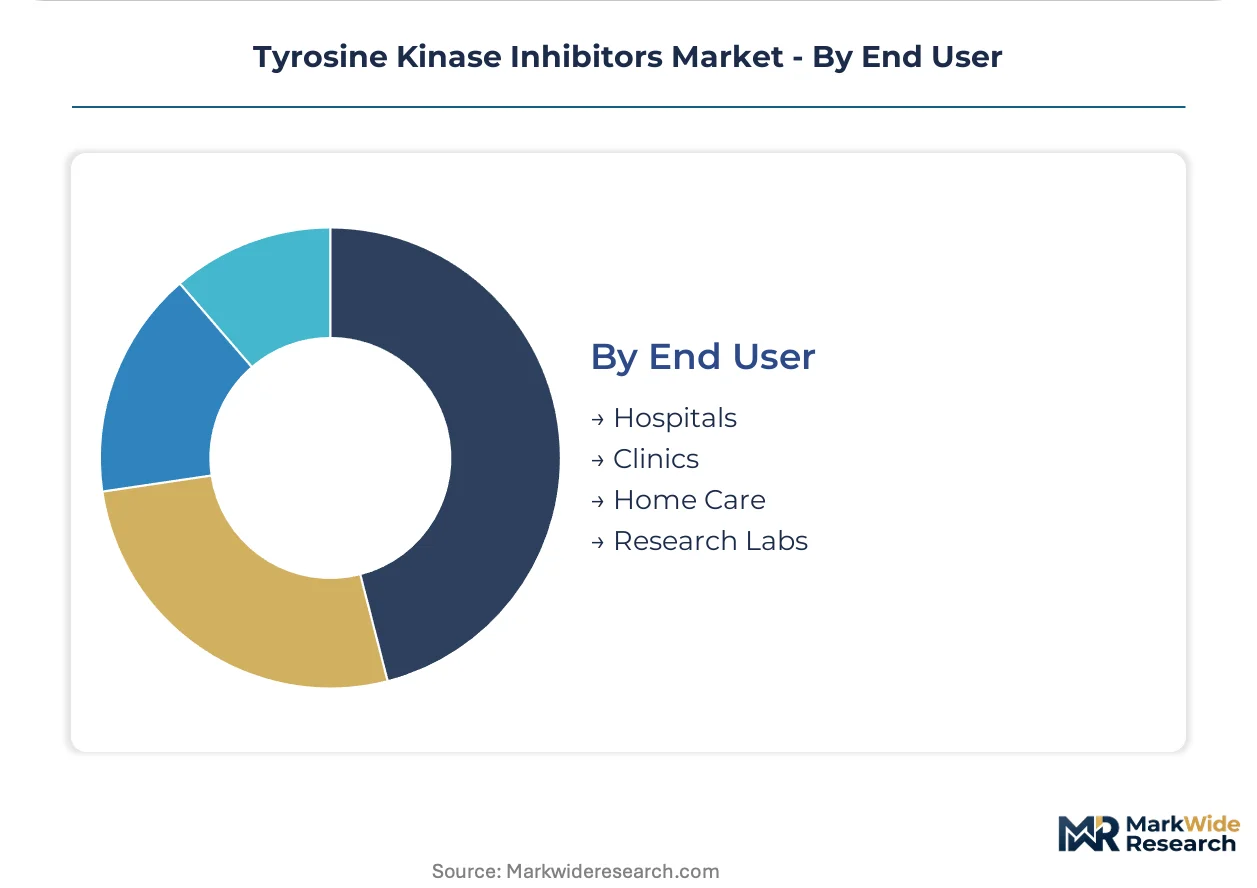
- Hospitals:Integrated delivery networks and academic medical centers with specialty pharmacy capabilities and comprehensive oncology service lines. Procurement concentrates through group purchasing organizations in the United States and centralized hospital procurement in China and Germany, driven by risk-sharing arrangements that tie formulary placement to progression-free survival outcomes.
- Clinics:Community oncology practices and specialized treatment centers without full inpatient capabilities.
- Home Care:Direct-to-patient distribution for chronic oral therapy with remote monitoring support.
- Research Labs:Preclinical and clinical investigation supply for academic and commercial drug development.
By absolute volume, hospitals absorb the majority of kinase inhibitor utilization. By channel growth rate, home care is expanding most quickly as oral therapy protocols mature and remote patient monitoring infrastructure scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany where integrated diagnostic pathways command premium reimbursement, while coastal China absorbs manufacturing volume at compressed margins. Japan and the United Kingdom occupy intermediate positions with strong regulatory gatekeeping but constrained formulary budgets.
United States
FDA Project Optimus accelerates dose-optimization trials, compressing development timelines for kinase-selective candidates. Medicare Advantage risk-sharing arrangements tie oral oncology reimbursement to progression-free survival metrics. Academic medical centers in Boston and Houston scale precision medicine infrastructure with 14-day genomic profiling protocols.
Germany
EMA's revised oncology guidelines demand richer quality-of-life data for full marketing authorization, extending regulatory timelines. REACH and RoHS compliance force reformulation of palladium-containing synthetic intermediates. The Rhine-Ruhr pharmaceutical cluster invests in continuous flow chemistry to eliminate heavy metal contamination from Suzuki coupling processes.
China
NMPA's breakthrough therapy pathway compresses approval timelines for domestic kinase innovation. Coastal manufacturing clusters in Zhejiang and Jiangsu dominate API production for multi-step organic synthesis. Shanghai and Beijing academic medical centers expand biomarker-matched enrollment protocols for targeted therapy trials.
Japan
PMDA maintains stringent evidentiary standards for accelerated approval, favoring domestic sponsors with established pharmacovigilance infrastructure. METI promotes green chemistry metrics in pharmaceutical manufacturing. The Kanto region's tertiary oncology centers adopt comprehensive genomic profiling as standard-of-care for solid tumor diagnosis.
United Kingdom
NICE technology appraisals constrain pricing power for oral oncology agents through incremental cost-effectiveness thresholds. MHRA post-Brexit regulatory autonomy enables divergence from EMA timelines on confirmatory trial design. The Cambridge-London life sciences corridor concentrates early-phase kinase inhibitor development and biomarker platform integration.
Tyrosine Kinase Inhibitors Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with kinase selectivity expertise and manufacturing scale. The market structures around three tiers: established oncology franchises with diagnostic partnerships, mid-cap developers with differentiated selectivity profiles, and generic manufacturers eroding first-generation BCR-ABL inhibitors. Competitive moves concentrate on companion diagnostic bundling and backward integration into API manufacturing to secure supply chains.
Among Swiss-based pharmaceutical conglomerates, Novartis and Roche occupy anchor positions through established imatinib franchises and integrated diagnostic capabilities. Bristol Myers Squibb exemplifies the platform-integrator archetype via biomarker testing partnerships that lock institutional formulary placement. Pfizer represents the selective-kinase development tier with late-stage pipeline differentiation.
| Leading Market Players |
|---|
| AstraZeneca |
| Novartis |
| F. Hoffmann-La Roche |
| Boehringer Ingelheim International |
| Bayer |
| Pfizer |
| Bristol Myers Squibb |
| Johnson & Johnson |
| Merck & Co. |
| Others |
Value Chain & Pricing Dynamics
Coastal China's dominance in Suzuki coupling intermediates for multi-step organic synthesis anchors margin capture at the API tier, leaving finished formulation manufacturers exposed to input cost volatility and regulatory compliance premiums.
Pricing Analysis
The customization-premium spread between mutation-specific kinase inhibitors and commoditized first-generation BCR-ABL agents spans three distinct tiers: premium-priced next-generation compounds with companion diagnostic bundling, standard-tier selective kinase inhibitors with established biomarker protocols, and economy-tier generic imatinib facing accelerating substitution. Price differentiation rests on kinase selectivity profiles and integrated diagnostic partnerships, with academic medical centers in the United States and Germany least sensitive due to risk-sharing arrangements, while community oncology practices in Medicare Advantage populations exhibit highest price elasticity.
Supply Chain Analysis
Upstream feedstock dependencies for palladium-catalyzed cross-coupling reactions draw from specialized catalyst suppliers in Germany and Japan, with final API synthesis concentrating in Zhejiang and Jiangsu provinces alongside backup capacity in India. Raw material inputs hinge on high-purity boronic acids, chiral auxiliaries, and enantioselective ligands. Single-source vulnerability in coastal Chinese manufacturing clusters creates exposure to environmental regulatory enforcement and shipping chokepoints. Distribution runs through specialty pharmacy networks displacing traditional wholesale channels for oral oncology agents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Tyrosine Kinase Inhibitors Market exhibits cyclical recovery characteristics as FDA Project Optimus compresses dose-optimization timelines and hospital systems rebuild precision medicine infrastructure post-pandemic.
For Market Incumbents: Entrench formulary position through backward integration into companion diagnostic development and captive API manufacturing in Germany's Rhine-Ruhr cluster to offset coastal China supply risk. Deepen institutional relationships via integrated biomarker testing protocols that lock academic medical center enrollment. Prioritize EMA quality-of-life data collection early to preempt regulatory timeline extension.
For New Entrants and Emerging Players: Cardiovascular repurposing applications in pulmonary arterial hypertension represent the most penetrable white-space entry point, with German and United States academic medical centers actively recruiting for VEGF pathway studies. China's NMPA breakthrough pathway offers accelerated approval for domestic kinase innovation with localized manufacturing requirements. Pursue licensing arrangements with established diagnostic platform holders rather than standalone commercialization.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap developers with differentiated kinase selectivity profiles and existing Phase II biomarker-matched protocols. Long-term viability over the next decade depends on pipeline diversification beyond oncology into cardiovascular and autoimmune indications. Monitor FDA confirmatory trial completion rates as the critical inflection signal for portfolio revaluation.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Bundling | Locks institutional formulary placement through integrated biomarker testing with targeted therapy enrollment. |
| Regulatory Approval Pathway | NMPA breakthrough designation in China compresses timelines for domestic kinase innovation. |
| Manufacturing Scale-Up | Continuous flow chemistry investment eliminates palladium contamination for EMA REACH compliance. |
| Pipeline Diversification | Cardiovascular repurposing of VEGF inhibitors opens heart failure and pulmonary arterial hypertension indications. |
| Backward Integration | Captive API production in Germany's Rhine-Ruhr cluster reduces coastal China supply concentration risk. |
Study Parameters
Desk research of FDA Project Optimus guidance documents, EMA revised oncology guidelines, ClinicalTrials.gov kinase inhibitor protocols, and formulary database trends preceded structured interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from NMPA breakthrough therapy announcements, SEC 10-K pharmaceutical filings, and academic medical center precision medicine expansion disclosures. Bottom-up prescription volume modeling and top-down therapeutic category sizing enabled triangulation across data sources.
Assumptions held fixed include regulatory convergence on dose-optimization standards and continued hospital consolidation through integrated delivery networks, while variables included NMPA approval velocity for domestic innovation and EMA quality-of-life data requirements. The analytical framework segmented by product type, therapy area, delivery mode, and end user across the analysis window. CAGRs derived from patient population epidemiology, biomarker testing penetration curves, and formulary access expansion trajectories. Forecast inputs incorporated mutation profiling adoption rates and generic substitution elasticity for first-generation agents.
Macroeconomic conditions sit as an overlay; deviation in Medicare Advantage reimbursement rates, pharmaceutical trade policy, or environmental enforcement in coastal Chinese manufacturing zones would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory timeline convergence and hospital procurement consolidation. Cross-checking against IQVIA prescription audit data and CMS Medicare Part D spending benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Nfkb P65 Antibody Market
Biopharmaceuticals
Influenza Vaccine Market
Biopharmaceuticals
Protein Therapeutics Market
Biopharmaceuticals
Plasmid DNA Manufacturing Market
Biopharmaceuticals
Global Rheumatoid Arthritis Drugs Market
Biopharmaceuticals
Benzbromarone API Market
Biopharmaceuticals
Atipamezole Market
Biopharmaceuticals
North America Diabetes Drugs Market
Biopharmaceuticals
Plasma Protein System Market
Biopharmaceuticals
Ewing Sarcoma Drugs Market
Biopharmaceuticals
Bio-Identical Hormones Replacement Therapy Market
Biopharmaceuticals
Liposomal Doxorubicin Market
Biopharmaceuticals
Large Macrolide Drugs Market
Biopharmaceuticals
Human Chorionic Gonadotropin Market
Biopharmaceuticals
Insulin Secretagogues Market
Biopharmaceuticals
Insulin Delivery Pens Market