
 Morocco Automotive Industry Market | 2026-2036
Morocco Automotive Industry Market Size, Share, and Industry Trends Forecast 2026-2036
Morocco Automotive Industry Market Insights
Electrification of powertrain architectures is reconfiguring component sourcing patterns across Moroccan assembly operations. Renault Group leverages its Tangier manufacturing complex to anchor North African EV export capacity. Stellantis sustains multi-brand production flexibility across its Kenitra facility. BYD competes through battery technology specialization for regional electrification partnerships.
The Morocco automotive industry encompasses vehicle assembly, powertrain manufacturing, and component supply chains serving both domestic consumption and export markets, with stamping and welding processes producing body-in-white structures rated for Euro NCAP safety protocols. Passenger vehicles occupy the dominant production volume position, while electric vehicles represent the fastest-expanding technology segment as battery assembly localizes. OEM customer relationships command the largest value share of revenue flows, though Tier-1 suppliers capture critical margin pools in electrified subsystems.
Morocco's Ministry of Industry and Trade enforces local content thresholds through its national automotive development strategy, while BIS-equivalent conformity assessment procedures align finished vehicles with European type-approval standards for export access. Stakeholders must monitor regulatory tightening on battery material traceability and carbon border adjustment mechanisms affecting Moroccan-EU trade corridors.
Market Dynamics
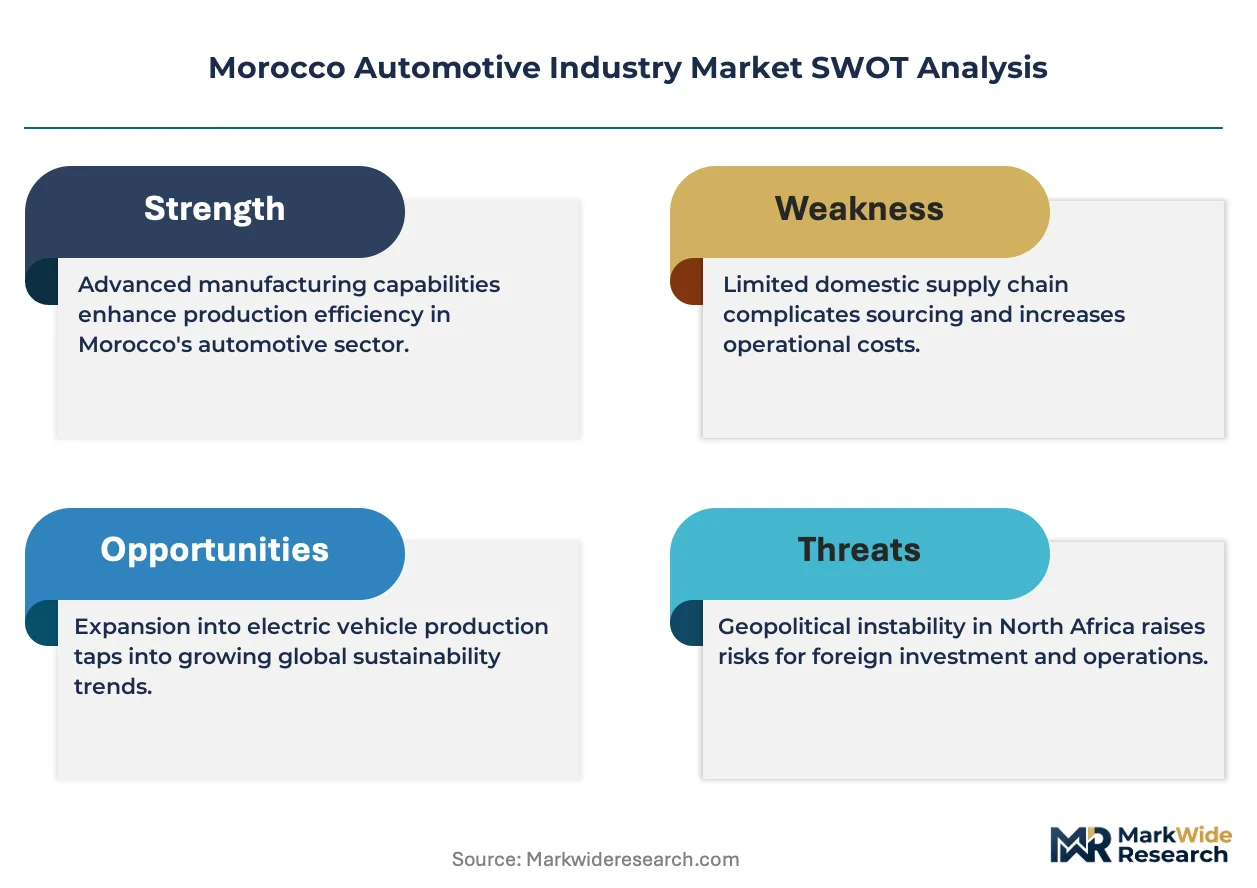
Electrification mandates from the European Union are compressing export timelines for Moroccan assembly plants, forcing powertrain localization decisions before supplier ecosystems mature. The tension between accelerated EV quotas and domestic battery capacity buildout defines current strategic planning.
Growth Catalysts
- EU Battery Regulation:Traceability requirements for critical raw materials are incentivizing Moroccan mining and processing partnerships for cobalt and lithium supply chain integration.
- Casablanca-Rabat corridor clustering:Component manufacturing density is reducing logistics costs for stamped metal parts and wiring harness assemblies serving multiple OEM plants.
- Renault Group Tangier expansion:Dedicated EV platform allocation is drawing Tier-1 supplier co-location for electric motor and inverter production.
Market Restraints
- Lithium carbonate price volatility:Battery cell input costs fluctuate with Chilean and Australian mining output, compressing margin visibility for localized pack assembly investments.
- Single-port dependency:Tanger Med container terminal handles over 80% of automotive exports, creating congestion risk during peak shipping seasons.
- Technical workforce scarcity:Moroccan engineering institutes produce insufficient mechatronics specialists for high-voltage system integration roles.
Strategic Opportunities
- Kenitra supplier park expansion:Undeveloped industrial land adjacent to Stellantis operations offers greenfield sites for battery module assembly.
- Phosphate-to-LFP conversion:OCP Group mineral processing capabilities could pivot toward lithium iron phosphate cathode material production for cost-sensitive EV segments.
- EU Carbon Border Adjustment Mechanism:Moroccan renewable energy share in manufacturing creates competitive advantage against carbon-intensive competitor exports.
Industry Challenges
- High-voltage technician certification:IEC 61482 arc-flash training programs remain underdeveloped at Moroccan vocational institutes, slowing EV line maintenance staffing.
- Legacy ICE supplier transition:Internal combustion component manufacturers face stranded asset risk as OEMs consolidate platform architectures.
- Homologation timeline compression:Euro NCAP protocol updates require faster crash-test iteration cycles than domestic certification infrastructure currently supports.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Morocco Automotive Industry Market |
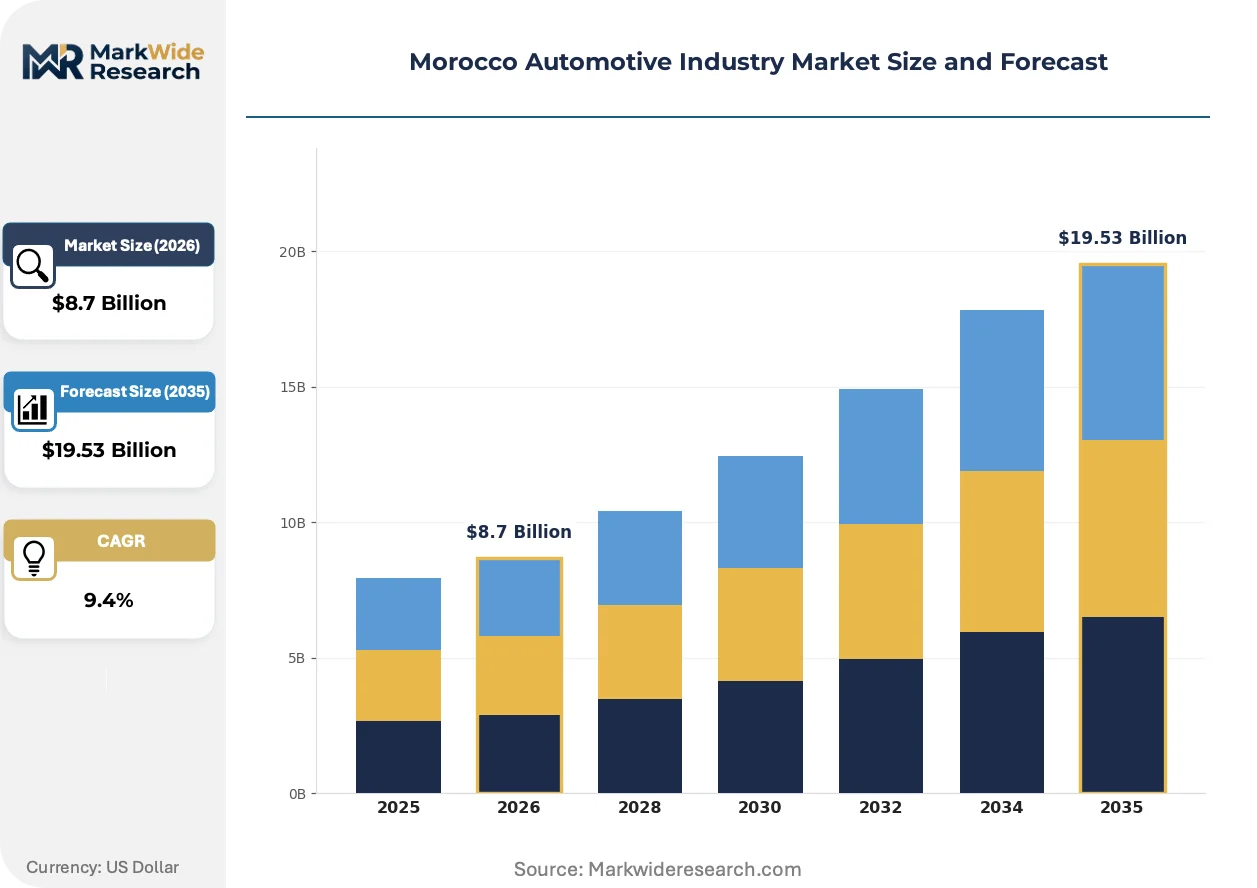
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Hybrid Vehicles Customer Type: OEMs, Tier-1 Suppliers, Aftermarket Providers, Dealerships Technology: Internal Combustion, Battery Electric, Plug-in Hybrid, Autonomous Application: Fleet Management, Personal Use, Ride Sharing, Logistics |
| Companies Covered | Renault Group, Stellantis, BYD, Dacia, Volkswagen, Peugeot, Hyundai, Citroen, NEO Motors Morocco, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Morocco Automotive Industry Market Trends and Innovations
Digital thread integration across Moroccan assembly operations is compressing quality feedback loops and enabling predictive maintenance deployment. Three distinct vectors are accelerating simultaneously.
Industrial IoT sensor networks are digitizing weld seam inspection and dimensional tolerance verification across body-in-white production lines. Renault Group's Tangier plant deploys machine vision systems for real-time defect detection, reducing rework rates. This connectivity layer is digitizing maintenance scheduling and spare parts inventory optimization.
EU Green Deal automotive CO2 targets are tightening fleet-average emissions thresholds for export-bound production. Moroccan plants must demonstrate renewable energy input shares to maintain preferential tariff access. Battery electric vehicle output is displacing hybrid allocations as the primary compliance pathway.
Fleet procurement centralization among European leasing companies is consolidating order volumes and compressing model-mix flexibility. Large buyers now specify software update capability and battery state-of-health transparency as standard contract terms. This concentration is most visible in German and French corporate fleet channels sourcing from Moroccan assembly.
Morocco Automotive Industry Market Segmentation
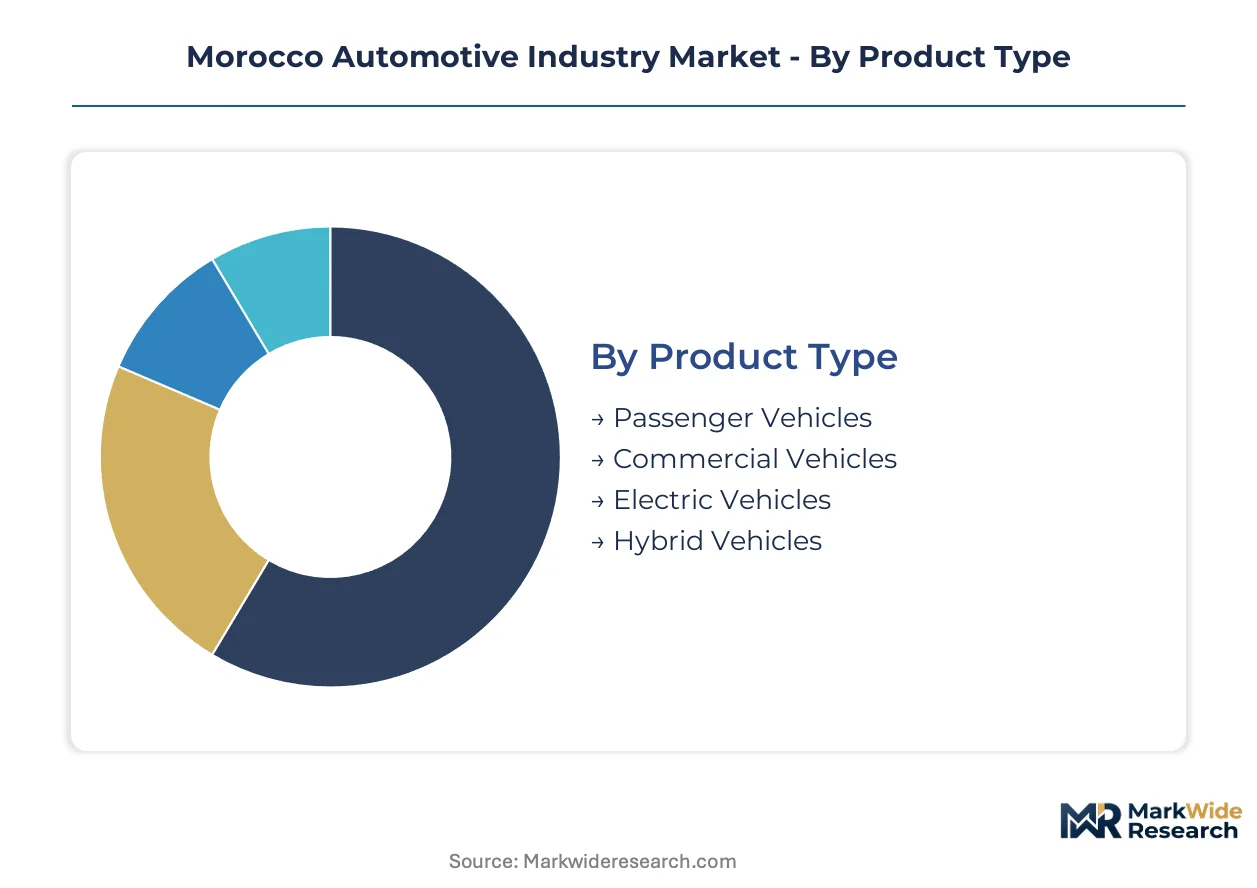
Segmentation reveals how electrification timelines and customer concentration reshape revenue pools across Moroccan automotive operations. Distinct cycle speeds across product categories and technology tiers determine capital allocation priorities for suppliers and assemblers.
Product Type:
Passenger vehicles turn inventory fastest through Casablanca-Rabat corridor distribution, while commercial platforms sustain longer production runs with fleet contract anchoring.
- Passenger Vehicles:Body-in-white stamping and welding operations at Renault Tangier and Stellantis Kenitra generate highest unit volumes for Euro NCAP-compliant export. Demand concentrates among German and French corporate fleet lessors specifying software-update capability and battery health transparency as contract terms.
- Electric Vehicles:Battery pack assembly localization is accelerating as EU Battery Regulation traceability mandates force cobalt and lithium supply chain integration. Expansion concentrates at Renault Tangier's dedicated EV platform lines, drawing Tier-1 supplier co-location for motor and inverter production.
- Commercial Vehicles:Stellantis Kenitra maintains multi-brand production flexibility for van and light truck architectures serving logistics operators.
- Hybrid Vehicles:Transitional powertrain category bridging ICE legacy and full electrification for price-sensitive export segments.
Passenger vehicles dominate installed base. Electric vehicles are where expansion concentrates.
Customer Type:
Margin capture varies sharply across the value chain, with OEM relationships commanding largest revenue flows while Tier-1 suppliers extract critical returns from electrified subsystems.
- OEMs:Renault Group and Stellantis anchor production capacity decisions and supplier qualification timelines for Moroccan assembly operations.
- Tier-1 Suppliers:Electric motor, inverter, and battery module manufacturers capture premium margin pools as EV platform allocation expands at Tangier and Kenitra facilities.
- Aftermarket Providers:Service networks for high-voltage system maintenance remain underdeveloped due to IEC 61482 arc-flash certification gaps at Moroccan vocational institutes.
- Dealerships:Distribution concentration in Casablanca-Rabat corridor limits rural market penetration for personal use segments.
OEM relationships structure supply base investment. Tier-1 suppliers are climbing the fastest margin trajectory.
Technology:
Powertrain architecture choices determine local content compliance paths and renewable energy input verification for EU Carbon Border Adjustment Mechanism eligibility.
- Internal Combustion:Legacy component manufacturers face stranded asset risk as OEMs consolidate platform architectures and Moroccan government incentives accelerate local content thresholds.
- Battery Electric:High-voltage system integration roles outpace Moroccan engineering institute output of mechatronics specialists, creating technical workforce scarcity.
- Plug-in Hybrid:Transitional technology segment requiring dual powertrain supply chain maintenance during EV capacity buildout.
- Autonomous:Sensor fusion and compute hardware integration remains nascent in Moroccan assembly, with homologation timeline compression for Euro NCAP protocol updates exceeding domestic certification infrastructure capacity.
Internal combustion anchors current installed base. Battery electric is gaining share fastest.
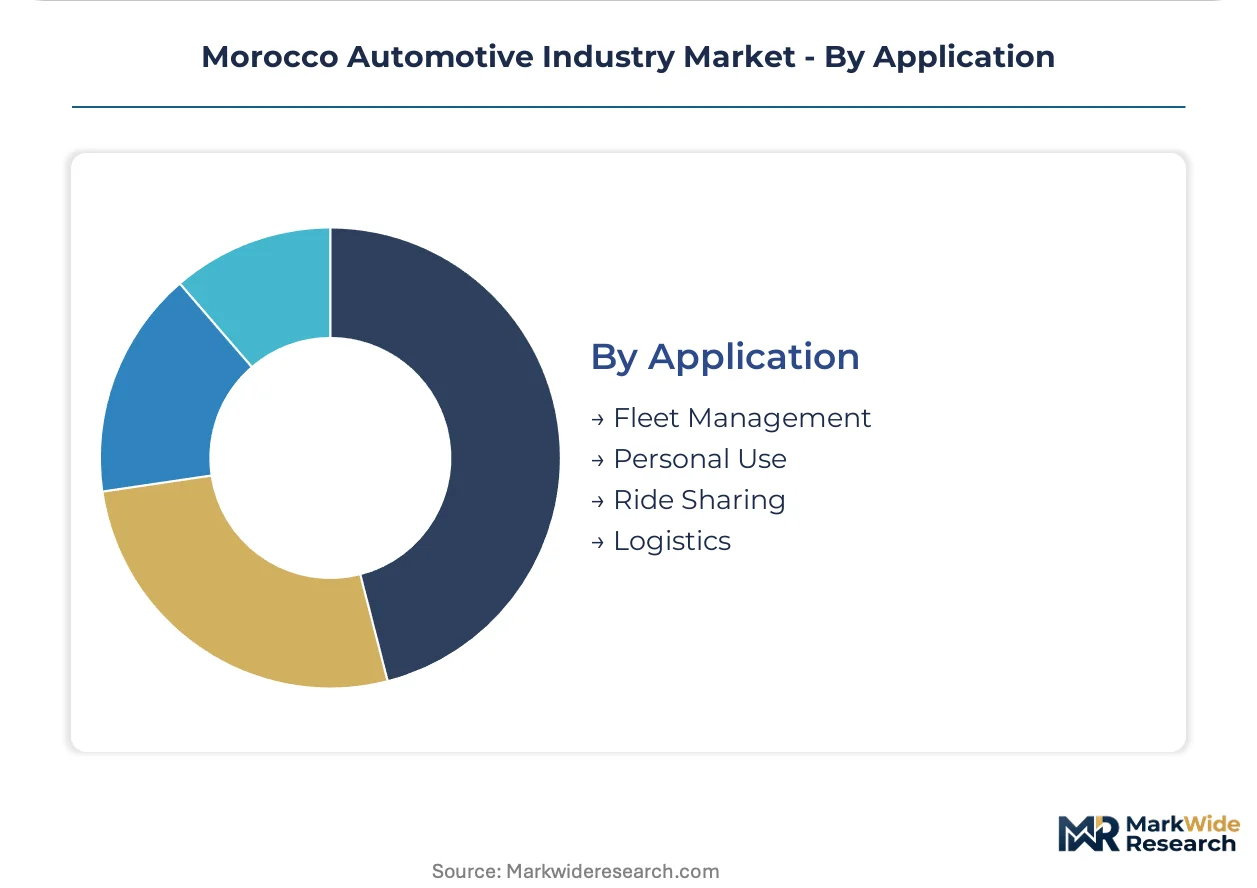
Application:
End-use concentration shapes order batch sizes and model-mix flexibility requirements across Moroccan export corridors.
- Fleet Management:Centralized procurement among European leasing companies consolidates order volumes and compresses specification variance for Renault and Stellantis output.
- Personal Use:Retail demand fragmentation requires broader model-mix flexibility than Moroccan plants currently optimize for.
- Ride Sharing:Platform operators prioritize total cost of ownership metrics and charging infrastructure compatibility for urban deployment.
- Logistics:Commercial vehicle specifications from Stellantis Kenitra serve last-mile delivery fleet operators with durability and payload requirements.
Fleet management dominates order concentration. Ride sharing is where demand diversification concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Moroccan automotive exports flow primarily through the Tanger Med port corridor toward European Union markets, with assembly plants serving as manufacturing outposts for French and German fleet buyers. This trade configuration shapes regional investment patterns and supplier location decisions across the kingdom.
Casablanca-Settat
Industrial land scarcity near Morocco's economic capital is pushing component suppliers toward peripheral zones. The Ministry of Industry and Trade administers automotive development incentives through dedicated industrial zones. Kenitra's supplier park expansion offers greenfield sites for battery module assembly serving Stellantis operations.
Tangier-Tetouan-Al Hoceima
Renault Group's Tangier manufacturing complex anchors North African EV export capacity with dedicated platform lines. EU Battery Regulation traceability requirements are drawing cobalt and lithium processing partnerships toward this northern corridor. Tanger Med container terminal handles over 80% of automotive exports, creating congestion risk during peak shipping seasons.
Rabat-Salé-Kénitra
Stellantis sustains multi-brand production flexibility across its Kenitra facility for van and light truck architectures. BIS-equivalent conformity assessment procedures align finished vehicles with European type-approval standards. The Casablanca-Rabat corridor clustering reduces logistics costs for stamped metal parts and wiring harness assemblies.
Fès-Meknès
Phosphate-to-LFP conversion opportunities leverage OCP Group mineral processing capabilities for lithium iron phosphate cathode material. Moroccan government automotive sector incentives are accelerating local content requirements in this central region. Technical workforce scarcity for mechatronics specialists persists across engineering institutes.
Marrakech-Safi
Renewable energy share in manufacturing creates competitive advantage against carbon-intensive competitor exports under EU Carbon Border Adjustment Mechanism. BYD competes through battery technology specialization for regional electrification partnerships. Aftermarket service networks for high-voltage system maintenance remain underdeveloped due to certification gaps.
Morocco Automotive Industry Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Moroccan automotive operations. OEMs anchor production capacity decisions and supplier qualification timelines, while Tier-1 suppliers extract premium returns from electrified subsystems. Three archetypes dominate: integrated assemblers with platform control, component specialists with subsystem expertise, and emerging local challengers seeking technology partnerships. Competitive moves center on supplier co-location for EV platform allocation and backward integration into battery material processing.
Among integrated assemblers, Renault Group and Stellantis occupy positions as anchor investors with dedicated manufacturing complexes. BYD represents the technology-licensing archetype, competing through battery specialization rather than assembly scale. These three exemplify distinct strategic postures: platform-control dominance, multi-brand flexibility, and vertical technology capture.
| Leading Market Players |
|---|
| Renault Group |
| Stellantis |
| BYD |
| Dacia |
| Volkswagen |
| Peugeot |
| Hyundai |
| Citroen |
| NEO Motors Morocco |
| Others |
Pricing and Supply Chain Analysis
Renault Tangier's EV line capacity utilization above 85% is compressing supplier lead times and tilting contract negotiations toward annual price-down targets for Tier-1 motor and inverter suppliers. This tightness propagates through the Casablanca-Rabat corridor, where component manufacturers face volume-commitment penalties if they cannot match OEM production cadence.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange cobalt and lithium carbonate benchmarks dominate battery pack assembly pricing. Three-tier pricing structure across premium, standard, and economy levels separates OEM-direct Tier-1 relationships from distributor-mediated component sales and aftermarket service tiers. Price differentiation hinges on IEC 61482 arc-flash certification status and volume scale commitments above 50,000 units annually. Cost compression in standard-tier wiring harness assemblies is intensifying because Moroccan stamping suppliers are absorbing logistics premiums to retain Stellantis and Renault platform allocation. Fleet procurement managers at European leasing companies exhibit lowest price sensitivity, prioritizing battery state-of-health transparency and software update capability over per-unit discounts.
Supply Chain Analysis
EU Battery Regulation traceability requirements and US Inflation Reduction Act critical mineral sourcing rules are restricting cobalt and lithium flows from unverified mining jurisdictions. Geographic supply concentration centers on Chilean and Australian lithium carbonate, Indonesian nickel processing, and DRC cobalt refining for Moroccan cell assembly inputs. Raw material dependencies include copper busbar stock, rare-earth permanent magnets for traction motors, and semiconductor-grade silicon for power electronics. Single-source vulnerability persists for high-voltage connector assemblies sourced from German Tier-2 specialists. Distribution runs through Tanger Med container terminal consolidation, with 80% of finished vehicle exports flowing to EU port destinations under preferential tariff arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Morocco automotive sector's expansion trajectory is constrained by mechatronics specialist output from domestic engineering institutes, creating a bottleneck for high-voltage system integration roles that cannot be filled through expatriate recruitment alone.
For Market Incumbents: Insulate platform allocation by securing exclusive supplier park co-location agreements at Kenitra and Tangier before greenfield sites exhaust. Accelerate backward integration into phosphate-to-LFP cathode material processing through OCP Group partnerships to reduce lithium iron phosphate input cost exposure. Defensive patent positioning around battery thermal management architectures will block emerging technology licensors from displacing established Tier-1 relationships. For New Entrants and Emerging Players: Aftermarket high-voltage service networks in Marrakech-Safi and Fès-Meknès represent the most penetrable entry point given IEC 61482 certification gaps at incumbent dealership operations. Battery second-life applications for stationary energy storage offer alternative revenue streams without direct OEM supply qualification. Go-to-market execution should anchor on vocational institute training partnerships that generate certified technician pipelines ahead of competitor staffing. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Tier-1 electric motor and inverter manufacturers with multi-OEM platform supply agreements spanning Renault and Stellantis operations. Long-term viability across the analysis window favors suppliers with demonstrated local content compliance and renewable energy input verification for EU Carbon Border Adjustment Mechanism eligibility. Acquisition targets should demonstrate phosphate processing adjacencies or battery module assembly capabilities. The signal to watch is EU Battery Regulation delegated act timing on recycled content mandates, which would force accelerated cathode material localization decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term cobalt and lithium offtake contracts with Chilean and Australian miners secure input cost visibility for Tangier EV line expansion. |
| Platform Standardization | Renault Group's dedicated EV architecture consolidation reduces tooling changeover costs and accelerates Tier-1 supplier qualification cycles. |
| Backward Integration | OCP Group phosphate-to-LFP conversion investments would capture cathode material margin pools currently flowing to Chinese processors. |
| Software-Defined Vehicle Investment | Over-the-air update capability is becoming a fleet contract requirement from German and French corporate leasing companies. |
| Charging Infrastructure Partnership | Grid interconnection agreements with ONEE for high-power charging corridors support ride-sharing platform operator total cost of ownership targets. |
Research Methodology
A standing panel of OEM platform engineers, Tier-1 supplier procurement directors, Moroccan Ministry of Industry and Trade officials, and Tanger Med port operations managers provided ongoing calibration across primary fieldwork phases. Secondary validation drew from vehicle production databases, IHS Markit registration data, EU Battery Regulation delegated act drafts, and OCP Group mineral processing disclosures. Bottom-up assembly plant capacity modeling was triangulated against top-down Moroccan automotive export value flows.
Scenario-bracketing around EU EV mandate acceleration and lithium carbonate price volatility bands framed the analytical approach across the projection horizon. Segmentation dimensions modeled include vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs were derived from installed base turnover rates and technology substitution curves rather than extrapolated linear trends. Forecast inputs incorporated Moroccan renewable energy share verification protocols for EU Carbon Border Adjustment Mechanism eligibility and Euro NCAP protocol update timelines.
Macroeconomic conditions sit as an overlay; deviation in euro-dirham exchange rates and EU automotive fleet CO2 target stringency would shift the trajectory. Forecasts reflect assumptions regarding Tanger Med capacity expansion timing and Moroccan vocational institute output scaling. Material shifts in EU Battery Regulation enforcement timelines or lithium supply chain nationalization policies would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
North America Automotive Upholstery Market
Automotive Interior & Exterior
Mexico Automotive Sunroof Market
Automotive Interior & Exterior
Argentina Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Flooring Market
Automotive Interior & Exterior
Automotive Ambient Lighting Market
Automotive Interior & Exterior
Advanced Vehicle Side Mirror Market
Automotive Interior & Exterior
France Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Door Latch Market
Automotive Interior & Exterior
Asia Pacific Automotive Interiors Market
Automotive Interior & Exterior
Automotive Smart Seating Systems Market
Automotive Interior & Exterior
Automotive Insulation Market
Automotive Interior & Exterior
Automotive Center Console Market
Automotive Interior & Exterior
Automotive Grab Handle Market
Automotive Interior & Exterior
Global Automotive Window Power Sunshade Market
Automotive Interior & Exterior
Automotive Smart Dashboard Display Market
Automotive Interior & Exterior
Automotive Automatic Liftgate Market