
 Timing Relay Market | 2026-2036
Timing Relay Market Size, Share, and Industry Trends Forecast 2026-2036
Timing Relay Market Analysis
The capital-intensity divergence between integrated manufacturers and component assemblers is unwinding competitive stability across the timing relay sector. Siemens leverages captive semiconductor fabrication to secure supply continuity for solid-state relay lines. ABB anchors its position through deep domain expertise in heavy-industrial timing applications. Schneider Electric differentiates via extensive DIN rail product portfolios and channel density in European electrical distribution.
A timing relay is an electromechanical or solid-state control device that introduces a predetermined delay between input activation and output switching, typically operating within voltage ranges of 12V to 480V AC/DC and delay intervals from milliseconds to hours. Its primary commercial purpose centers on sequencing motor starts, protecting equipment from overload conditions, and coordinating automated process steps across manufacturing infrastructure. Digital and solid-state categories are capturing margin pools as analog electromechanical designs face material cost pressures from silver-alloy contact requirements. Multi-function relays are expanding fastest in HVAC and motor control applications where programmable delay profiles reduce inventory complexity for systems integrators.
UL 508 industrial control equipment standards in the United States, IEC 61810 electromechanical relay specifications in Europe, and China's GB/T 21711 relay standards collectively dictate insulation ratings, contact endurance testing, and environmental compliance thresholds for market access. RoHS and REACH frameworks in the European Union restrict hazardous substances in contact materials, pushing manufacturers toward tungsten-copper or gold-plated alternatives. Stakeholders must monitor evolving efficiency mandates from the EU Ecodesign Directive and emerging dual-carbon requirements from China's MEE that will reshape material selection and product certification pathways.
Market Dynamics
Digital solid-state architectures are systematically displacing electromechanical relay cores across industrial control cabinets, compressing maintenance cycles and rewiring supplier economics toward semiconductor-capable manufacturers.
Growth Catalysts
- EU Ecodesign Directive:Efficiency mandates for motor-driven systems are mandating precision timing controls in HVAC and pumping infrastructure across Germany, France, and Italy.
- Automotive electrification:Battery assembly lines and electric motor test rigs require sequenced relay networks for high-voltage safety interlocks and thermal management protocols.
- Silver-copper contact alloys:Advanced metallurgy extends contact life beyond 10 million operations, reducing replacement frequency in continuous-duty manufacturing environments.
Market Restraints
- Input cost volatility:Silver and palladium price swings directly compress margins on electromechanical contact assemblies, forcing inventory hedging strategies.
- Supply concentration risk:Specialty semiconductor foundry capacity for solid-state relay substrates concentrates in Taiwan and South Korea, creating single-source vulnerability.
- Technical limitation:Solid-state devices exhibit residual leakage current and heat dissipation constraints that disqualify them from certain safety-critical isolation applications.
Strategic Opportunities
- India industrial corridor expansion:PLI scheme incentives for manufacturing automation are creating fresh demand pockets in Gujarat and Tamil Nadu factory zones.
- Renewable energy integration:Solar inverter and wind turbine control cabinets require programmable timing relays for grid synchronization and fault ride-through sequences.
- Convergence of IoT connectivity:Embedded sensors and edge analytics are enabling predictive relay maintenance, opening recurring revenue streams for diagnostic services.
Industry Challenges
- Embedded systems engineering shortage:Solid-state relay design requires mixed-signal expertise combining power electronics with firmware development, a talent profile scarce outside Munich, Shenzhen, and Boston technology clusters.
- Multi-standard certification timelines:Simultaneous UL 508, IEC 61810, and GB/T 21711 testing extends product launch cycles by 14-18 months for universal-platform strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Timing Relay Market |
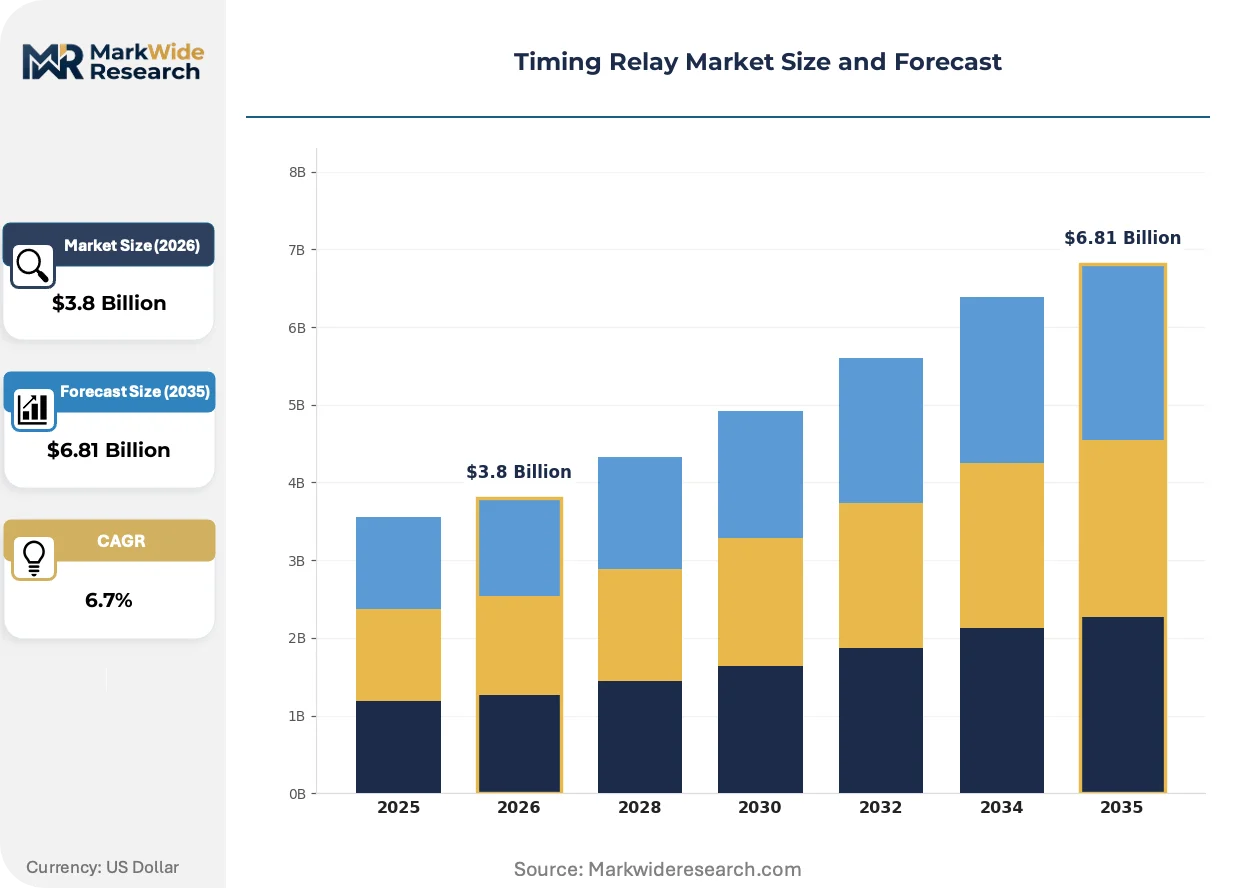
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Analog, Digital, Multi-Function, Solid State Application: Industrial Automation, HVAC, Home Appliances, Motor Controls Mounting Type: Panel Mounted, DIN Rail Mounted, Socket Mounted, PCB Mounted End User: Manufacturing, Construction, Automotive, Energy |
| Companies Covered | Siemens, ABB, Schneider Electric, Eaton, OMRON Corporation, General Electric, Rockwell Automation, TE Connectivity, Phoenix Contact, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Timing Relay Market Emerging Trajectories
Component-level intelligence is migrating into timing relays through embedded microcontrollers and communication protocols, transforming standalone switches into networked nodes within distributed control architectures.
Silicon-carbide power semiconductors are decomposing the thermal and switching-speed limitations that historically constrained solid-state relay penetration in heavy-industrial current ranges. Steel mills and mining equipment OEMs in Australia and Canada are piloting SiC-based timing modules for motor protection, enabling faster fault response and reduced heat-sink footprint. This technology is decomposing the traditional voltage-current tradeoffs that segmented electromechanical from solid-state procurement decisions.
REACH substance restrictions are forcing contact material migrations across European supply chains, with ECHA authorization lists now covering certain silver-cadmium oxide formulations common in high-inrush applications. Manufacturers are accelerating tungsten-copper and gold-nickel plating qualifications to maintain CE marking compliance. German automotive suppliers face the tightest transition deadlines, with material requalification costs concentrated in 2026-2027 product cycles.
Systems integrators are consolidating relay vendor relationships around programmable multi-function platforms that collapse inventory SKUs across delay-range variants. Distributor technical support requirements are shifting from product selection toward application programming and diagnostic troubleshooting. This consolidation pattern is most pronounced in North American HVAC and water treatment verticals, where specification complexity previously sustained fragmented supplier bases.
Timing Relay Market Segmentation
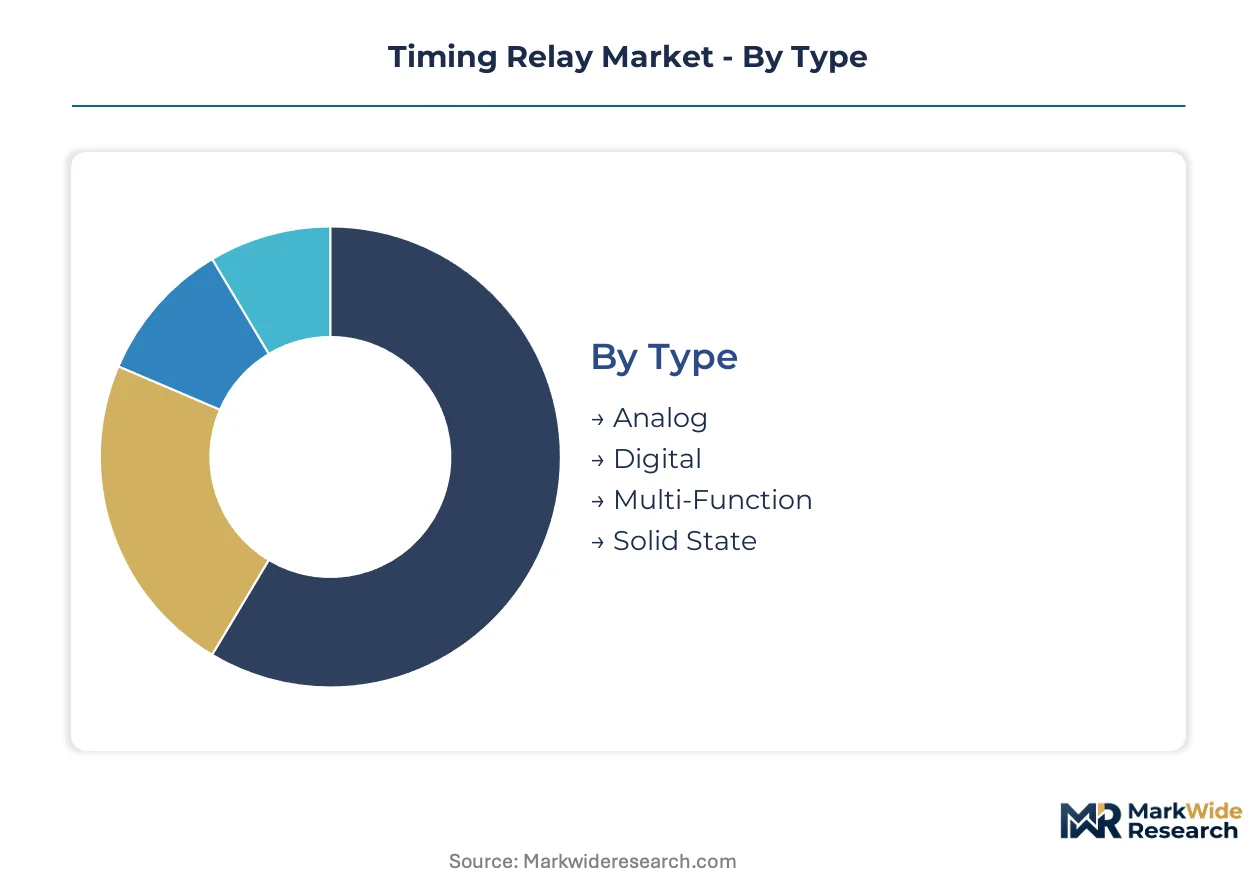
Segmentation in the timing relay market reveals how solid-state architectures are systematically displacing electromechanical alternatives across voltage and current ranges. Understanding substitution dynamics by type, application, mounting configuration, and end-use sector exposes where margin pools are concentrating and which specifications face commoditization pressure.
Type:
Solid-state variants face the strongest substitution pressure against electromechanical cores, with digital and multi-function architectures capturing programmable logic demand.
- Analog:Electromechanical designs with mechanical contact assemblies and RC timing circuits operate across 12V to 480V ranges. Demand concentrates in legacy industrial infrastructure across Germany's Ruhr industrial corridor, where RoHS-compliant silver-alloy contact upgrades extend service life in continuous-duty motor protection applications.
- Digital:Microcontroller-based delay programming enables millisecond-to-hour precision with LCD configuration interfaces. Automotive battery assembly lines in Stuttgart and Munich require sequenced digital relays for high-voltage safety interlocks, driven by IEC 61810 compliance mandates for electromechanical switching components.
- Multi-Function:Programmable platforms collapse delay-range variants into single SKUs, reducing distributor inventory complexity. HVAC systems integrators in North American water treatment verticals consolidate procurement around these configurable units.
- Solid State:Silicon-controlled rectifier and triac-based switching eliminates mechanical wear, though residual leakage current limits safety-critical isolation deployments. Taiwan and South Korean foundry concentration creates substrate supply vulnerability for heavy-industrial current ranges.
Analog retains volume leadership; solid-state holds the steepest expansion curve.
Application:
Cost tier stratification separates premium precision controls from specification-grade commodity relays across deployment environments.
- Industrial Automation:Sequencing motor starts and coordinating process steps in manufacturing infrastructure demands IEC 61810-certified endurance ratings. Factory modernization programs across Germany's industrial corridor require precision timing controls for automated production lines.
- HVAC:Pumping and ventilation systems under EU Ecodesign Directive efficiency mandates require programmable delay profiles for motor-driven equipment. Multi-function relays reduce specification complexity for systems integrators in this vertical.
- Home Appliances:White goods manufacturers specify compact PCB-mounted variants for dishwasher and washing machine cycle control. Cost pressure dominates procurement decisions in this segment.
- Motor Controls:Overload protection and star-delta starting sequences require contact endurance beyond 10 million operations. Silver-copper alloy metallurgy extends replacement intervals in continuous-duty environments.
Industrial automation commands premium pricing; HVAC is expanding most quickly on regulatory efficiency mandates.
Mounting Type:
Volume concentration favors DIN rail configurations in European electrical distribution, while panel and socket mounting persist in retrofit-heavy installed bases.
- Panel Mounted:Direct enclosure installation with screw terminals dominates legacy infrastructure retrofit. Mining equipment OEMs in Australia pilot SiC-based modules with reduced heat-sink footprints.
- DIN Rail Mounted:Schneider Electric's channel density in European distribution anchors this configuration's prevalence. Quick installation and standardized rail spacing reduce wiring labor in control cabinet builds.
- Socket Mounted:Plug-in bases enable field replacement without rewiring, favored in maintenance-intensive steel mill environments. Tungsten-copper contact migrations address REACH substance restrictions.
- PCB Mounted:Compact surface-mount variants serve appliance and embedded controller integration. Space constraints drive miniaturization requirements.
DIN rail mounting retains volume leadership; PCB mounting gains share fastest on appliance electrification trends.
End User:
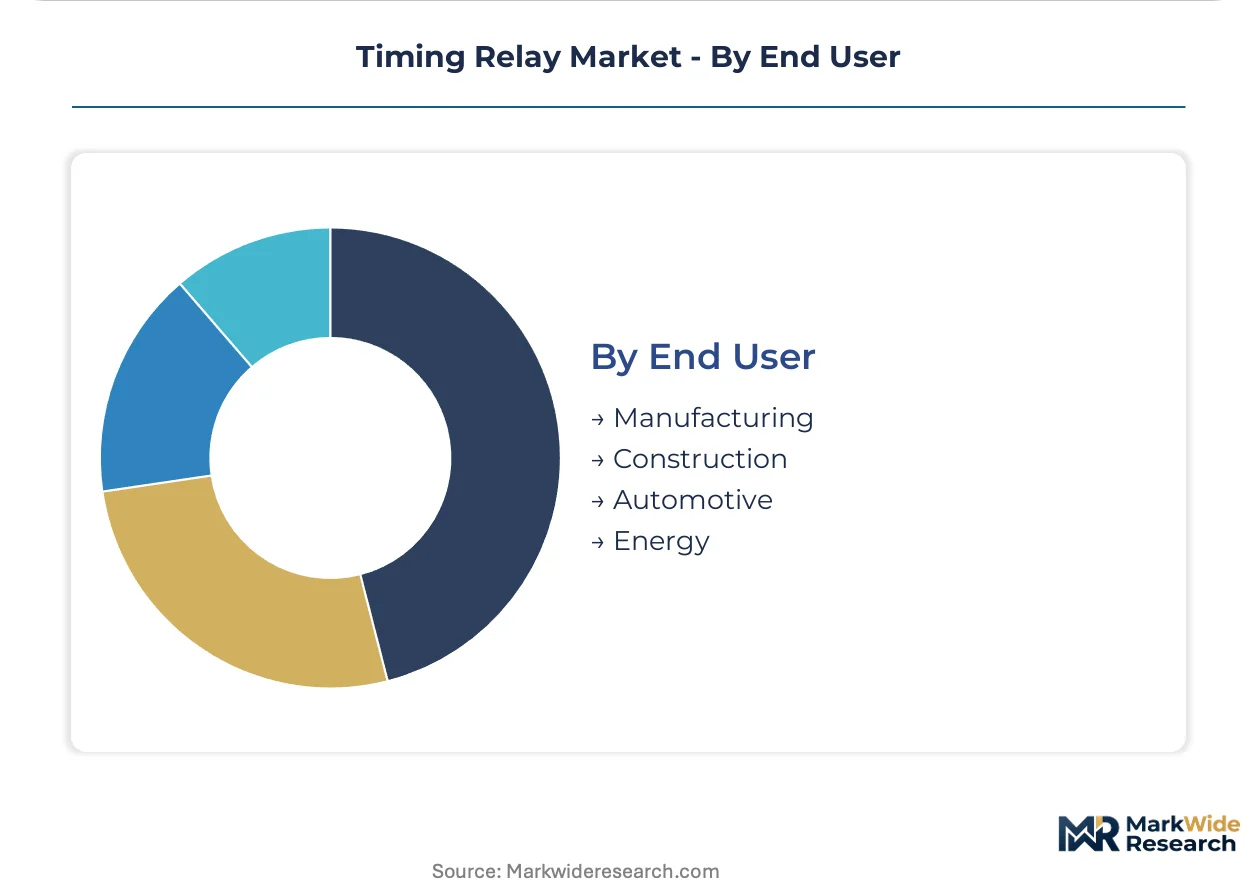
Customer type segmentation reveals how automotive electrification and renewable integration are reshaping demand concentration away from traditional manufacturing dominance.
- Manufacturing:Automotive production lines and general factory automation represent the core installed base. India's PLI scheme incentives for manufacturing automation create fresh demand pockets in Gujarat and Tamil Nadu factory zones.
- Construction:Building infrastructure and temporary power distribution specify robust electromechanical variants for harsh-environment reliability. Project-based procurement creates demand lumpiness.
- Automotive:Battery assembly lines and electric motor test rigs require sequenced relay networks for thermal management protocols. ECHA authorization deadlines force material requalification costs concentrated in German automotive supplier cycles.
- Energy:Solar inverter and wind turbine control cabinets require programmable timing relays for grid synchronization and fault ride-through sequences. Renewable integration mandates reshape procurement specifications.
Manufacturing retains volume leadership; energy holds the steepest expansion curve on renewable buildout.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in timing relays track divergent manufacturing capabilities, with Germany and China running structural surpluses while India and Brazil remain import-dependent for precision digital variants. Currency-adjusted trade flows concentrate in intra-European distribution networks and Asia-Pacific semiconductor substrate corridors.
Germany
Factory modernization programs across the Ruhr industrial corridor and Stuttgart automotive clusters drive precision timing control procurement. EU Ecodesign Directive efficiency mandates for motor-driven systems tighten specification requirements for HVAC and pumping infrastructure. Bavarian automation suppliers in Munich and Nuremberg anchor electromechanical relay production for legacy industrial retrofit markets.
United States
Automotive battery assembly lines in Michigan and Ohio require sequenced relay networks for high-voltage safety interlocks. UL 508 industrial control equipment standards dictate insulation ratings and contact endurance testing for market access. Texas and California industrial zones concentrate demand for programmable multi-function platforms in oilfield automation and semiconductor fabrication facilities.
China
Dual-carbon requirements from MEE reshape material selection and product certification pathways for domestic manufacturers. GB/T 21711 relay standards govern insulation ratings and environmental compliance thresholds. Yangtze River Delta factory automation clusters in Shanghai and Suzhou drive solid-state relay adoption for motor control and grid synchronization applications.
India
PLI scheme incentives for manufacturing automation create fresh demand pockets in Gujarat and Tamil Nadu factory zones. BIS certification requirements for industrial control equipment extend product qualification timelines for imported electromechanical variants. Pune and Chennai automotive supplier corridors concentrate procurement for sequenced timing controls in electric motor test rigs.
Japan
METI efficiency mandates for industrial machinery accelerate digital relay deployment in precision manufacturing. JIS standards for electromechanical switching components align with IEC 61810 specifications for export market access. Nagoya automotive equipment clusters and Osaka industrial automation zones anchor demand for solid-state architectures with embedded microcontroller programming.
Timing Relay Market Vendor Landscape
Concentration sits with diversified electrical conglomerates possessing captive semiconductor fabrication and deep domain expertise in heavy-industrial applications. The vendor base stratifies across three tiers: integrated manufacturers controlling upstream substrate supply, component assemblers sourcing specialty silicon from concentrated foundry networks, and regional specialists serving retrofit-heavy installed bases. Strategic moves center on multi-standard certification acceleration and programmable platform consolidation to collapse distributor inventory SKUs.
Among European-headquartered electrical conglomerates, Siemens and ABB exemplify integrated manufacturing archetypes with upstream control over solid-state relay substrate supply, while Schneider Electric occupies a position emphasizing DIN rail product breadth and channel density in electrical distribution. These three entities anchor competitive dynamics through divergent capability emphases rather than direct product overlap.
| Leading Market Players |
|---|
| Siemens |
| ABB |
| Schneider Electric |
| Eaton |
| OMRON Corporation |
| General Electric |
| Rockwell Automation |
| TE Connectivity |
| Phoenix Contact |
| Others |
Supply Flow & Price Mechanics
Captive semiconductor fabrication capacity at Siemens and ABB creates asymmetric scale economies that compress price floors for solid-state relay tiers while elevating entry barriers for component assemblers sourcing from Taiwan foundries. This concentration dynamic forces pricing discipline across electromechanical alternatives as silver-alloy contact costs transmit directly through bill-of-material structures.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with differentiation hinging on IEC 61810 certification grade and volume scale. Pricing pressure stems from silver and palladium volatility in electromechanical contact assemblies, compressing margins for analog relay manufacturers. Automotive battery assembly lines exhibit lowest price sensitivity due to safety-critical specification requirements, while white goods OEMs drive hardest bargain on PCB-mounted commodity variants.
Supply Chain Analysis
Taiwan Strait transit vulnerability underwrites supply risk for silicon-controlled rectifier substrates that Taiwan and South Korean foundries fabricate for solid-state relay cores. The supply chain draws from German precision electromechanical component clusters, Chinese GB/T 21711-certified assembly plants, and Japanese JIS-standard contact metallurgy specialists. Raw material dependencies center on silver-copper alloys, silicon carbide wafers, and gold-nickel plating chemistries. Distribution runs through Schneider Electric's European channel density and North American industrial distributor networks serving HVAC and motor control verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The timing relay market sits in early-cycle recovery as factory automation capital expenditure rebounds from pandemic-deferred modernization programs across Germany's industrial corridor.
For Market Incumbents: Fortify captive semiconductor fabrication positions against Taiwan foundry concentration risk through qualification of secondary substrate sources in South Korea and Japan. Deepen DIN rail channel control in European electrical distribution to lock out programmable multi-function competitors. Accelerate tungsten-copper contact requalification ahead of ECHA authorization deadlines to preserve CE marking compliance in automotive supplier cycles. For New Entrants and Emerging Players: Anchor in India's PLI scheme-subsidized factory zones in Gujarat and Tamil Nadu, where domestic electromechanical relay production capacity lags demand from automotive supplier corridors. Target renewable energy integration applications—solar inverter and wind turbine control cabinets—where programmable timing relay specifications remain fluid and incumbent relationships are unformed. Pursue systems integrator partnerships in North American water treatment verticals consolidating vendor relationships around configurable platforms. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors mixed-signal engineering capabilities combining power electronics with firmware development, a talent profile scarce outside Munich, Shenzhen, and Boston clusters. Long-term viability hinges on semiconductor-capable manufacturing footprints rather than pure-play electromechanical assembly. Watch SiC substrate cost curves as inflection indicator for solid-state relay penetration into heavy-industrial current ranges historically reserved for electromechanical designs.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Standard Certification Acceleration | Simultaneous UL 508, IEC 61810, and GB/T 21711 qualification collapses 14-18 month launch cycles for universal platforms. |
| Silicon-Carbide Module Development | SiC power semiconductors decompose thermal constraints that segmented solid-state from electromechanical procurement in steel and mining applications. |
| Programmable Platform Consolidation | Multi-function relay SKUs reduce distributor inventory complexity and shift technical support toward application programming services. |
| Embedded IoT Sensor Integration | Edge analytics enable predictive maintenance revenue streams and transform standalone switches into networked control nodes. |
| REACH-Compliant Contact Migration | Tungsten-copper and gold-nickel plating qualifications preserve CE marking access as ECHA restricts silver-cadmium oxide formulations. |
Methodological Framework
A spread of perspectives from plant engineers, OEM procurement teams, aftermarket service heads, and distributor technical specialists converged on the working assumptions shaping this analysis. Primary fieldwork combined with secondary validation from SEC filings, IEC certification databases, customs trade records, and EU Ecodesign Directive implementation reports. Bottom-up demand modeling across voltage ranges and mounting configurations triangulated against top-down industrial automation expenditure tracking.
Segmentation dimensions modeled include relay type architecture, application environment, mounting configuration, and end-use sector concentration across the projection horizon. CAGRs were derived from installed base replacement cycles, regulatory mandate timelines, and technology substitution curves in motor control applications. Forecast inputs incorporated silver price volatility scenarios and Taiwan foundry capacity utilization assumptions.
Decision-makers should treat outputs as directional under base assumptions of sustained factory automation investment and stable semiconductor substrate supply; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as EU Ecodesign Directive enforcement intensity and China's MEE dual-carbon implementation pace evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
United States Radiation-Hardened Electronics Market
Electronic Components
Europe Radiation-Hardened Electronics Market
Electronic Components
Resonators Market
Electronic Components
Chip Shield Market
Electronic Components
Electromechanical Relay Market
Electronic Components
Semiconductor Micro Components Market
Electronic Components
Acoustic Diaphragm Market
Electronic Components
Efuse Market
Electronic Components
Battery Holders Market
Electronic Components
Electric Fuse Market
Electronic Components
Electrolytic Capacitor Market
Electronic Components
Motherboard Market
Electronic Components
Data Bus Market
Electronic Components
Power Inductors Market
Electronic Components
Ceiling Microphone Market
Electronic Components
Display Port Adapters Market