
 China Video Surveillance Market | 2026-2036
China Video Surveillance Market Size, Share, and Industry Trends Forecast 2026-2036
China Video Surveillance Market Insights
A capital-intensity divergence between players is reorganizing competitive tiers across the China video surveillance landscape. Hangzhou Hikvision Digital Technology Co., Ltd. leverages its captive chip design and sensor manufacturing to control cost structures at scale. Zhejiang Dahua Technology Co., Ltd. anchors its position through deep vertical integration into storage and transmission hardware. Uniview Technologies Co., Ltd. competes aggressively on price in mid-tier municipal contracts while sustaining thinner margins.
China video surveillance encompasses networked camera systems, video management software, and analytics platforms engineered for real-time monitoring, recording, and threat detection across physical environments. IP cameras now dominate new installations, with edge-computing-enabled devices processing facial recognition and behavior analysis locally to reduce bandwidth loads and cloud dependency. Cloud-based technology segments are expanding fastest as municipal buyers shift from on-premise NVR architectures to centralized command platforms. The government end-user category retains the deepest procurement budgets, though banking and commercial verticals are diversifying demand toward AI-integrated access control.
MIIT cybersecurity certification mandates and SAMR product quality standards are raising compliance barriers for non-domestic component suppliers. GB standards governing data encryption and facial recognition storage are forcing firmware architecture redesigns across the vendor base. Stakeholders must weigh the trade-off between algorithmic sophistication and the regulatory risk of stricter biometric data governance.
Market Dynamics
MIIT cybersecurity certification mandates and SAMR product quality standards are forcing firmware architecture redesigns across the vendor base, compressing product development cycles while raising compliance costs for non-domestic component suppliers.
Growth Catalysts
- Smart city infrastructure spending:Municipal governments in Shenzhen and Hangzhou are accelerating procurement cycles for networked camera systems and centralized command platforms.
- GB standards compliance:Data encryption and facial recognition storage mandates are creating captive demand for certified domestic vendors with pre-approved firmware architectures.
- Edge-computing-enabled devices:IP cameras processing facial recognition and behavior analysis locally are reducing bandwidth loads and cloud dependency for coastal manufacturing hubs.
Market Restraints
- Component ecosystem concentration:Sensor and chip manufacturing clusters in Shenzhen and Hangzhou create geographic supply vulnerability to regional disruptions.
- Biometric data governance friction:Stricter GB standards governing facial recognition storage are extending product certification timelines and increasing compliance overhead.
- Legacy NVR architecture substitution:Municipal buyers shifting from on-premise storage to cloud-based command platforms are stranding installed base investments.
Strategic Opportunities
- Banking vertical diversification:Commercial demand for AI-integrated access control is expanding beyond government end-users into financial services procurement budgets.
- Dual carbon goals alignment:Energy-efficient edge-computing devices qualify for preferential procurement scoring under MEE sustainability directives.
- Analytics platform convergence:Video management software integrating with IoT sensor networks is creating new service revenue streams for municipal command centers.
Industry Challenges
- Firmware engineering talent scarcity:MIIT cybersecurity certification requirements are outpacing the supply of qualified embedded systems developers familiar with GB encryption protocols.
- Legacy system integration complexity:Municipal buyers face technical debt when connecting cloud-based command platforms to existing analog camera infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Video Surveillance Market |
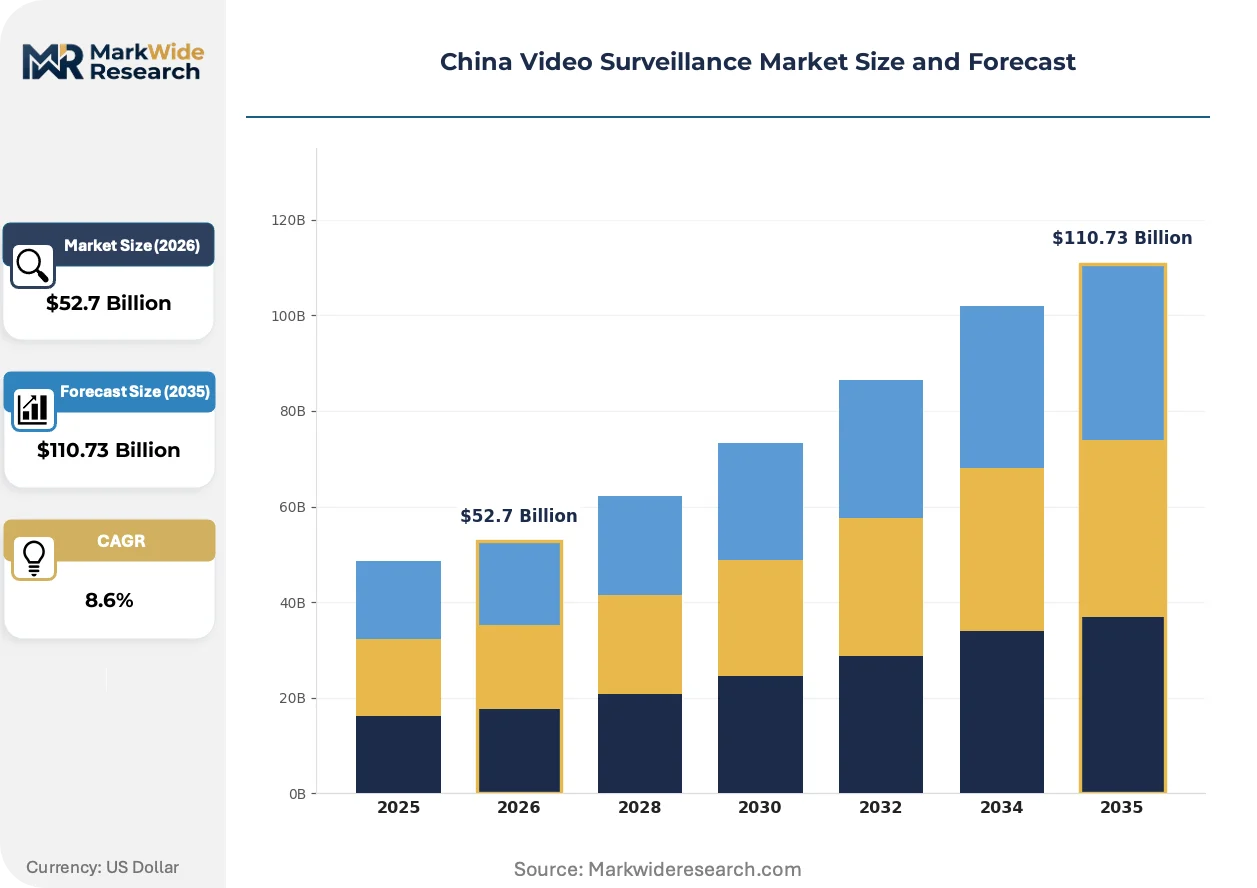
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $110.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CCTV Cameras, IP Cameras, Hybrid Cameras, Video Analytics Technology: Analog, Digital, Cloud-based, Edge Computing Application: Public Safety, Traffic Monitoring, Industrial Surveillance, Retail Security End User: Government, Transportation, Banking, Commercial |
| Companies Covered | Tiandy Technologies Co., Ltd., The Infinova Group, Hangzhou Hikvision Digital Technology Co., Ltd., Kedacom Technology Co., Ltd., Shenzhen TVT Digital Technology Co., Ltd., Zhejiang Dahua Technology Co., Ltd., Sunell Technology Corporation, Hikrobot Co., Ltd., Uniview Technologies Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Video Surveillance Market Trends and Innovations
Edge-computing architectures and AI-embedded chipsets are compressing the traditional hardware-software boundary in surveillance systems, while regulatory pressure on biometric data handling is forcing architectural pivots across the vendor ecosystem.
Edge-based facial recognition processing is fragmenting the traditional centralized server model for video analytics. Municipal command centers in Hangzhou and Shenzhen are deploying cameras with on-device inference engines to reduce backhaul bandwidth requirements. This distributed architecture is fragmenting procurement patterns, with buyers now evaluating chip-level performance metrics alongside camera hardware specifications.
MIIT cybersecurity certification mandates are tightening firmware compliance requirements for networked surveillance devices. Vendors must now submit source code audits and encryption module validations before product registration, extending development cycles by four to six months. The government end-user segment is responding by consolidating procurement around pre-certified domestic suppliers with established SAMR quality track records.
Municipal buyers are unbundling after-sales service contracts from initial hardware procurement, creating standalone recurring revenue streams for system integrators. Traditional bundled pricing models are losing share to separate maintenance and software subscription agreements in coastal manufacturing hubs. This shift is most visible in Shenzhen, where smart city project tenders now specify multi-year analytics platform licensing independent of camera hardware volumes.
China Video Surveillance Market Segmentation
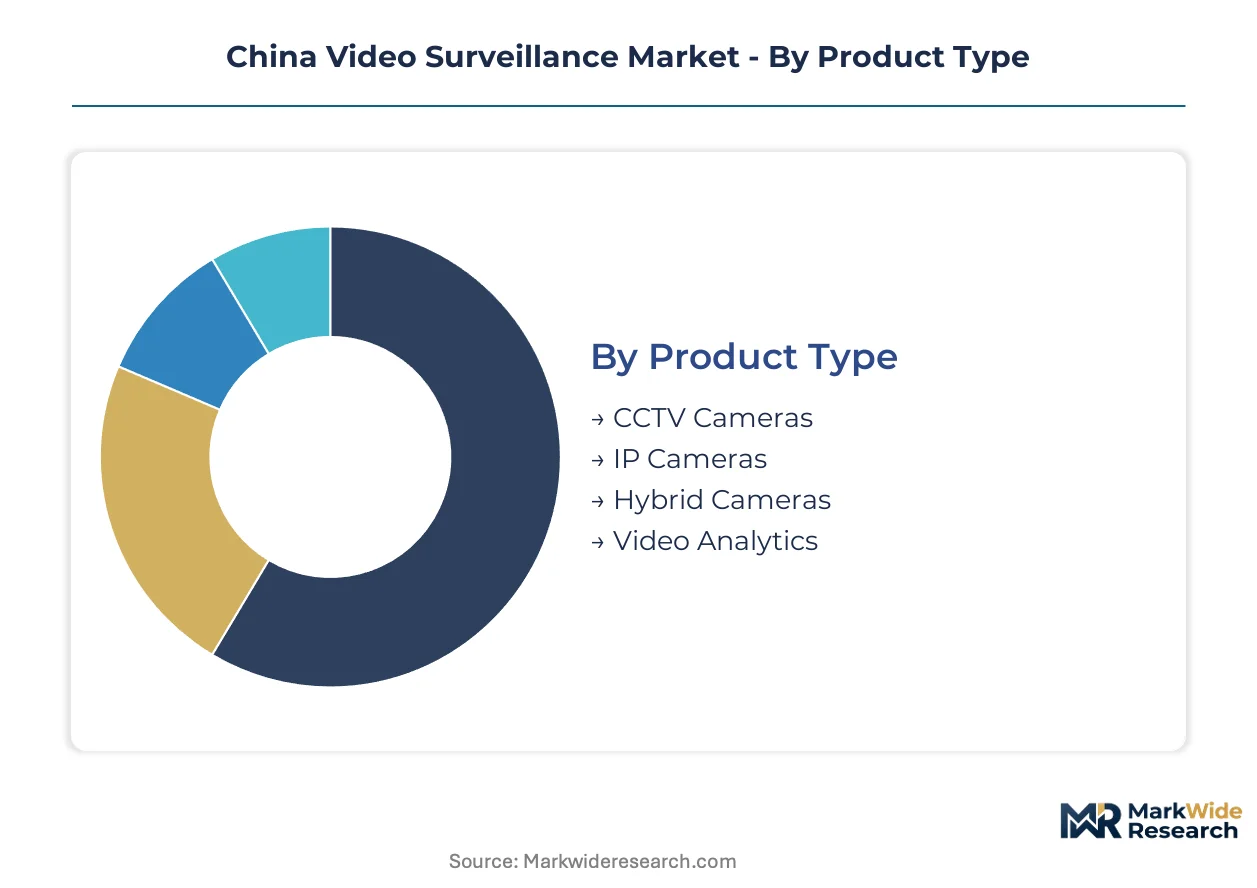
Segmentation in the China video surveillance market reveals how procurement patterns fragment across technical architectures and compliance tiers. Buyers prioritize certified firmware over raw specifications, reshaping competitive positioning across product categories.
Product Type:
IP Cameras face the strongest substitution pressure from edge-computing-enabled alternatives, while legacy CCTV hardware struggles against municipal cloud-migration mandates.
- IP Cameras:Networked devices with embedded AI chipsets process facial recognition and behavior analysis locally. Shenzhen smart city tenders specify these for bandwidth reduction in coastal manufacturing hubs facing MIIT cybersecurity deadlines.
- Video Analytics:Software platforms integrating IoT sensor networks generate recurring licensing revenue. Hangzhou municipal command centers unbundle these from hardware procurement, creating standalone service contracts independent of camera volumes.
- CCTV Cameras:Analog and early digital systems dominate legacy installed bases in tier-three cities. Stranded investments complicate cloud-platform migration for buyers with limited infrastructure budgets.
- Hybrid Cameras:Transitional hardware bridging analog and IP architectures addresses technical debt in phased municipal upgrades. SAMR quality certification requirements extend deployment timelines for these intermediate solutions.
IP Cameras anchors the volume base while Video Analytics gains share at the steepest rate.
Technology:
Cost tier differentiation separates premium edge-computing deployments from budget analog alternatives, with cloud-based platforms capturing mid-market municipal budgets.
- Edge Computing:On-device inference engines reduce backhaul bandwidth requirements for real-time facial recognition. Shenzhen and Hangzhou procurement specifications now evaluate chip-level performance metrics alongside camera hardware.
- Cloud-based:Centralized command platforms replace on-premise NVR architectures in municipal tenders. MEE sustainability directives award preferential scoring to energy-efficient cloud deployments aligned with dual carbon goals.
- Digital:Compressed video transmission standards comply with GB encryption mandates for government end-users. Firmware architecture redesigns extend product development cycles by four to six months under MIIT certification requirements.
- Analog:Legacy coaxial infrastructure persists in cost-constrained installations. Technical debt accumulates as buyers delay cloud-migration investments.
Edge Computing commands premium pricing while Cloud-based deployments expand most quickly across municipal procurement channels.
Application:
Volume concentration in government-funded verticals creates margin pressure, while commercial diversification offers escape routes from price-competitive municipal tenders.
- Public Safety:Government command centers deploy networked camera systems with centralized analytics for real-time threat detection. GB standards governing biometric data storage force architectural pivots across vendor firmware.
- Traffic Monitoring:Smart city infrastructure spending in Shenzhen accelerates procurement for intersection-mounted edge devices. Local processing of vehicle recognition reduces latency for enforcement applications.
- Industrial Surveillance:Manufacturing facilities in coastal hubs integrate video with access control and environmental sensors. Cybersecurity certification requirements filter supplier selection toward pre-approved domestic vendors.
- Retail Security:Banking and commercial verticals diversify demand toward AI-integrated access control beyond government budgets. Shorter procurement cycles reward vendors with rapid firmware compliance capabilities.
Public Safety absorbs the dominant procurement volume while Retail Security climbs the fastest as commercial buyers accelerate AI-integrated security spending.
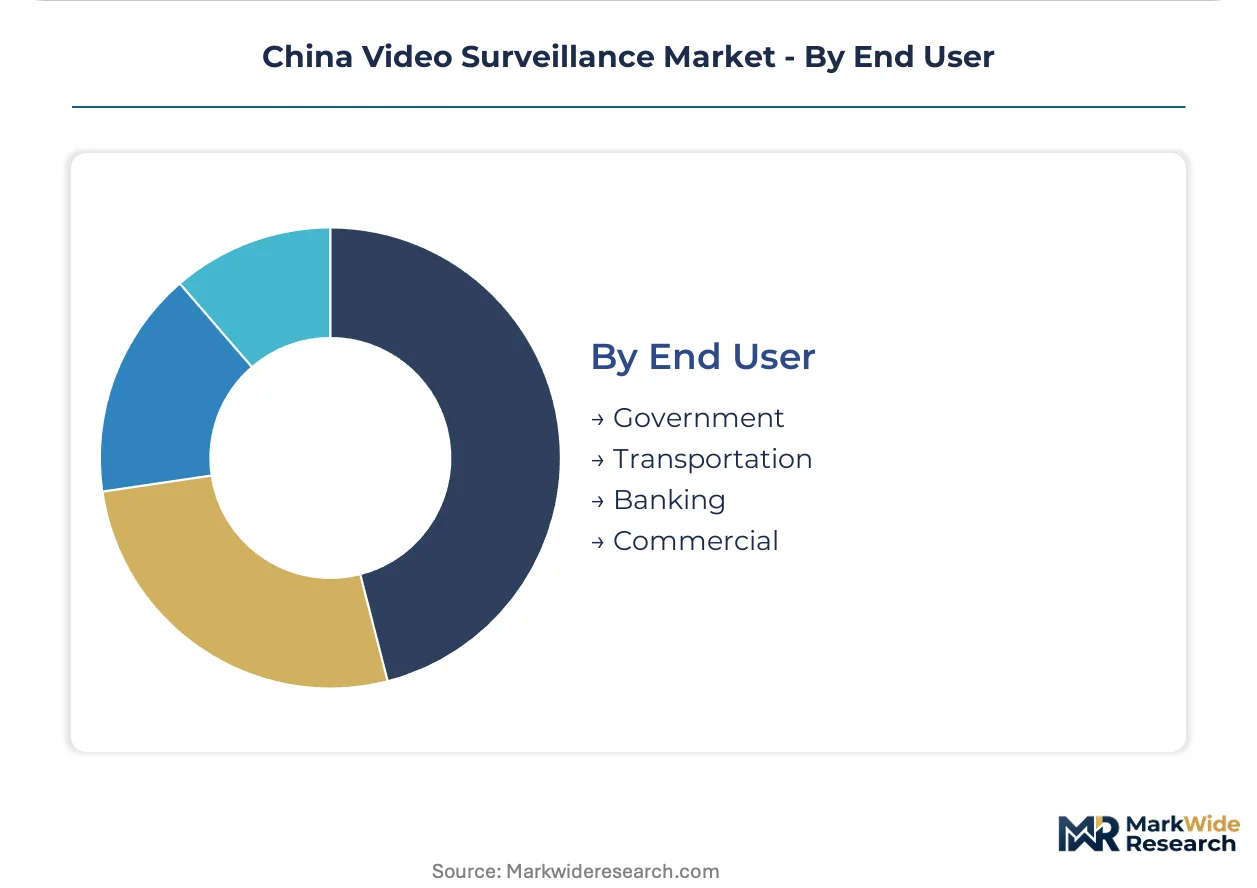
End User:
Customer type determines compliance burden intensity, with government mandates cascading technical requirements through adjacent verticals.
- Government:The deepest procurement budgets concentrate in municipal command centers with mandatory MIIT cybersecurity certification. Pre-certified domestic suppliers with established SAMR quality track records consolidate market access.
- Banking:Financial services procurement for AI-integrated access control expands beyond traditional government demand. Shorter sales cycles and higher margin tolerance attract vendors escaping municipal price competition.
- Transportation:Airports and rail networks require redundant edge-to-cloud architectures with failover capabilities. GB encryption standards for passenger data extend vendor qualification timelines.
- Commercial:Office complexes and logistics facilities prioritize cost-efficient hybrid deployments. Firmware engineering talent scarcity limits supplier options for buyers seeking rapid GB-compliant installation.
Government end-users anchor procurement volume while Banking verticals attract vendor repositioning for margin recovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal buyers in coastal provinces demonstrate low price elasticity for certified systems, while inland tier-three cities exhibit high sensitivity to upfront hardware costs. This demand-elasticity contrast shapes procurement patterns across sub-regional markets. GB standards enforcement intensity varies by local government fiscal capacity.
Yangtze River Delta
Shanghai municipal command centers drive demand for cloud-based command platforms with edge-to-cloud failover architectures. MEE sustainability directives award preferential procurement scoring to energy-efficient deployments aligned with dual carbon goals. Hangzhou clusters anchor sensor and chip manufacturing ecosystems where component vendors co-locate with system integrators.
Pearl River Delta
Shenzhen smart city infrastructure spending accelerates procurement cycles for intersection-mounted edge devices with on-device inference engines. MIIT cybersecurity certification mandates filter supplier selection toward pre-certified domestic vendors with established SAMR quality track records. Local firmware engineering talent pools support rapid GB encryption protocol compliance.
Beijing-Tianjin-Hebei
Government command centers in Beijing deploy networked camera systems for real-time threat detection with centralized analytics. Stricter GB standards governing biometric data storage force architectural pivots across vendor firmware submitted for national security project qualification. Tianjin logistics facilities prioritize cost-efficient hybrid deployments bridging analog and IP architectures.
Sichuan-Chongqing
Western China municipal budgets face constraints that extend cloud-migration timelines for legacy CCTV installations. SAMR product quality standards raise compliance barriers for non-domestic component suppliers seeking access to provincial procurement channels. Chengdu manufacturing facilities integrate video with access control systems under filtered supplier programs.
Shandong Peninsula
Qingdao port authorities require redundant edge-to-cloud architectures for cargo monitoring and perimeter security applications. Technical debt accumulates as buyers delay full cloud-platform investments while maintaining compliance with evolving data encryption mandates. Jinan municipal tenders specify multi-year analytics platform licensing independent of camera hardware volumes.
China Video Surveillance Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the China video surveillance landscape. The upper tier controls captive chip design and sensor manufacturing to compress cost structures at scale. Mid-tier municipal contractors compete aggressively on price while sustaining thinner margins. Specialist archetypes cluster around vertical software platforms and edge-computing hardware. Dominant competitive moves include backward integration into semiconductor supply chains and geographic expansion into banking verticals beyond government procurement channels.
Among Hangzhou-based integrated leaders, Hangzhou Hikvision Digital Technology Co., Ltd. and Zhejiang Dahua Technology Co., Ltd. occupy positions exemplifying the captive supply archetype. Uniview Technologies Co., Ltd. represents the aggressive mid-tier municipal contractor model. These three companies anchor the competitive structure visible in coastal manufacturing hub procurement patterns.
| Leading Market Players |
|---|
| Tiandy Technologies Co., Ltd. |
| The Infinova Group |
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Kedacom Technology Co., Ltd. |
| Shenzhen TVT Digital Technology Co., Ltd. |
| Zhejiang Dahua Technology Co., Ltd. |
| Sunell Technology Corporation |
| Hikrobot Co., Ltd. |
| Uniview Technologies Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
MIIT cybersecurity certification gates both supplier qualification and price differentiation simultaneously. Vendors with pre-approved firmware architectures command premium positioning in municipal tenders, while uncertified alternatives face exclusion regardless of hardware specifications. This regulatory filter compresses margin dispersion among qualified suppliers while amplifying cost penalties for compliance laggards.
Pricing Analysis
Multi-year analytics platform licensing drives lifetime value as municipal buyers unbundle service contracts from initial hardware procurement. Three-tier pricing structure across premium, standard, and economy levels separates edge-computing-enabled systems with on-device inference from basic IP cameras and legacy CCTV alternatives. Pricing pressure stems from aggressive mid-tier municipal contracting where vendors sacrifice margins for volume scale. Government command centers exhibit lowest price sensitivity due to mandatory certification requirements, while commercial office complexes and logistics facilities demonstrate highest sensitivity to upfront hardware costs.
Supply Chain Analysis
Inbound logistics costs through Shenzhen and Shanghai ports influence component sourcing economics for sensor and chipset procurement. Manufacturing concentration in China, South Korea, and Taiwan feeds the coastal hub ecosystem where Hikvision and Dahua maintain captive production. The supply chain rests on CMOS image sensors, AI inference chipsets, and precision optical lenses as critical inputs. Single-source vulnerability concentrates in advanced semiconductor nodes for edge-computing devices. Distribution runs through municipal system integrators and direct procurement channels to government command centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated municipal procurement offices that aggregate demand across smart city verticals. This consolidation fragments vendor access and intensifies price competition in tier-one coastal markets.
For Market Incumbents: Secure firmware engineering talent pools in Hangzhou and Shenzhen to maintain MIIT certification velocity against compliance deadlines. Deepen backward integration into sensor manufacturing to compress cost structures as mid-tier price competition intensifies. Anchor positioning through multi-year analytics platform licensing that locks in recurring revenue independent of hardware refresh cycles. For New Entrants and Emerging Players: SAMR quality certification fast-track programs offer entry pathways into banking and commercial verticals beyond saturated government channels. White-space concentrates in AI-integrated access control for financial services procurement and energy-efficient edge devices qualifying under MEE sustainability directives. Target tier-three cities with hybrid camera solutions that bridge legacy analog infrastructure toward cloud migration. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across edge-computing chipset design as AI-embedded architectures displace commoditized camera hardware. Long-term viability favors vendors with captive semiconductor supply chains and established SAMR quality track records. Acquisition target archetype: mid-tier municipal contractors with MIIT pre-certification status and unpenetrated banking vertical relationships. Signal to watch: municipal tender specifications shifting from hardware volumes to per-camera analytics licensing metrics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chipset Design | Captive AI inference engine production secures margin control against foundry cost volatility. |
| MIIT Certification Fast-Track Investment | Accelerated firmware compliance opens municipal procurement channels before competitor redesign cycles complete. |
| Banking Vertical Partnership Program | AI-integrated access control contracts escape government tender price compression with shorter sales cycles. |
| Multi-Year Analytics Licensing Model | Unbundled software subscriptions generate recurring revenue independent of camera hardware replacement demand. |
| Edge-to-Cloud Failover Architecture Development | Redundant systems qualify for transportation and critical infrastructure procurement with premium pricing tolerance. |
Research Methodology
A spread of perspectives from municipal procurement officers, system integration specialists, firmware engineering directors, and semiconductor supply planners converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against MIIT certification databases, SAMR product registration filings, and municipal tender documentation from Shenzhen and Hangzhou. Bottom-up unit economics triangulated against top-down smart city infrastructure budget allocations across coastal manufacturing hubs.
Segmentation dimensions modeled include product architecture, deployment technology, application vertical, and end-user compliance tier across the projection horizon. CAGRs were derived from installed base substitution rates for legacy CCTV systems and cloud-platform migration timelines. Forecast inputs incorporated edge-computing device penetration curves and GB standards enforcement intensity by provincial fiscal capacity.
Underlying assumptions cover sustained municipal smart city spending, stable MIIT certification timelines, and continued concentration of component ecosystems in coastal hubs, with deviation risk concentrated in biometric data governance tightening or regional supply disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
United Kingdom Surveillance IP Camera Market
Video Surveillance Systems
City Surveillance Market
Video Surveillance Systems
Brazil Surveillance Camera Market
Video Surveillance Systems
Global Body Worn Cameras Market
Video Surveillance Systems
China Surveillance Storage Market
Video Surveillance Systems
Asia-Pacific Video Surveillance Storage Market
Video Surveillance Systems
Asia-Pacific Surveillance Analog Camera Market
Video Surveillance Systems
Canada Surveillance Analog Camera Market
Video Surveillance Systems
Europe Video Surveillance Storage Market
Video Surveillance Systems
Coastal Surveillance Systems Market
Video Surveillance Systems
Latin America Video Surveillance Storage Market
Video Surveillance Systems
Latin America Video Surveillance Market
Video Surveillance Systems
3D Surveillance Software Market
Video Surveillance Systems
Asia Pacific Surveillance IP Camera Market
Video Surveillance Systems
Europe Surveillance Camera Market
Video Surveillance Systems
Global Night Vision System and Driver Monitoring System Market