
 Europe Insulin Pens Market | 2026-2036
Europe Insulin Pens Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Insulin Pens Market Foresight
A shift from single-source to multi-source component procurement is restructuring supply economics for pen manufacturers across Europe. Novo Nordisk leverages captive production of dosing mechanisms to protect margin pools. Sanofi anchors its competitive stance through deep specialization in disposable pen formats. Eli Lilly and Company competes by extending distribution partnerships with hospital procurement networks in Western Europe.
Europe insulin pens are precision drug-delivery devices engineered to administer calibrated insulin doses via subcutaneous injection, typically incorporating dose-setting dials, disposable needle interfaces, and spring-driven plunger systems manufactured to ISO 11608 tolerances. Their primary purpose centers on enabling accurate glycemic control for diabetes patients outside clinical settings. Smart pens and Bluetooth-enabled technology segments are capturing outsized investment as connectivity becomes a reimbursement differentiator, while reusable pens retain entrenched share in cost-sensitive Southern European markets. Disposable pens dominate volume in hospital and clinic channels where infection control protocols drive single-use preference.
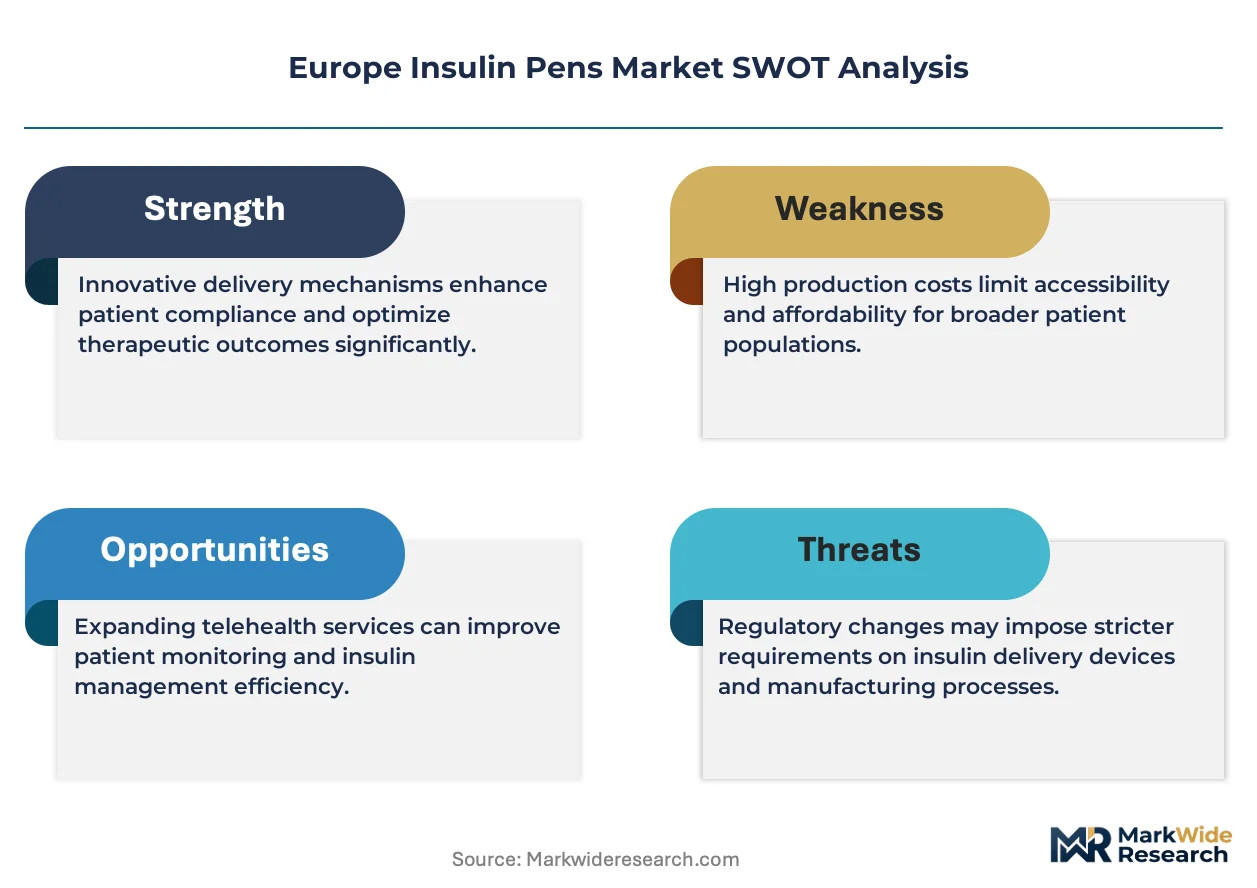
The EU Medical Device Regulation (MDR) and EMA guidance on combination products are elevating compliance costs and extending approval timelines for new pen introductions. REACH chemical restrictions and the EU Green Deal packaging directives are forcing material transitions in pen bodies and secondary packaging. Stakeholders must weigh MDR conformity investments against the accelerating shift toward connected delivery systems that promise data-integrated reimbursement models.
Market Dynamics
The EU MDR conformity transition is compressing approval timelines and forcing manufacturers to revalidate legacy pen platforms, creating a structural bottleneck that favors incumbents with dedicated regulatory affairs infrastructure.
Growth Catalysts
- Homecare channel expansion:Germany's ambulatory diabetes management programs are reimbursing connected pen systems, pulling administration out of clinical settings.
- EMA combination product guidance:The framework is clarifying pre-filled pen pathways, reducing regulatory uncertainty for drug-device integrators.
- Bluetooth-enabled dose logging:The technology is capturing reimbursement differentiators in France and the Netherlands where glycemic data integration determines coverage tiers.
Market Restraints
- MDR compliance cost escalation:notified body capacity constraints are extending technical file review cycles to 18-24 months for new pen submissions.
- Spring mechanism supply concentration:Swiss and German precision metal component specialists control critical dosing subassembly capacity.
- Polymer feedstock volatility:medical-grade ABS and polycarbonate pricing fluctuates with EU ETS carbon border adjustments affecting pen body molding costs.
Strategic Opportunities
- Spain and Italy cost-sensitive segments:reusable pen formats retain 40%+ volume share where national health systems limit disposable reimbursement.
- Hospital-at-home transition:The UK's NHS Long Term Plan is shifting infusion therapy to domiciliary settings, expanding pen-based basal-bolus protocols.
- EU Green Deal packaging mandates:The directive is creating first-mover advantage for manufacturers with bio-based pen body materials and reduced secondary packaging formats.
Industry Challenges
- Biocompatibility testing backlog:ISO 10993 cytotoxicity validation queues at EU reference laboratories are delaying pen coating qualification schedules.
- Legacy device MDR recertification:Manufacturers must recompile clinical evidence for pre-2021 pen platforms without original design dossier completeness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Insulin Pens Market |
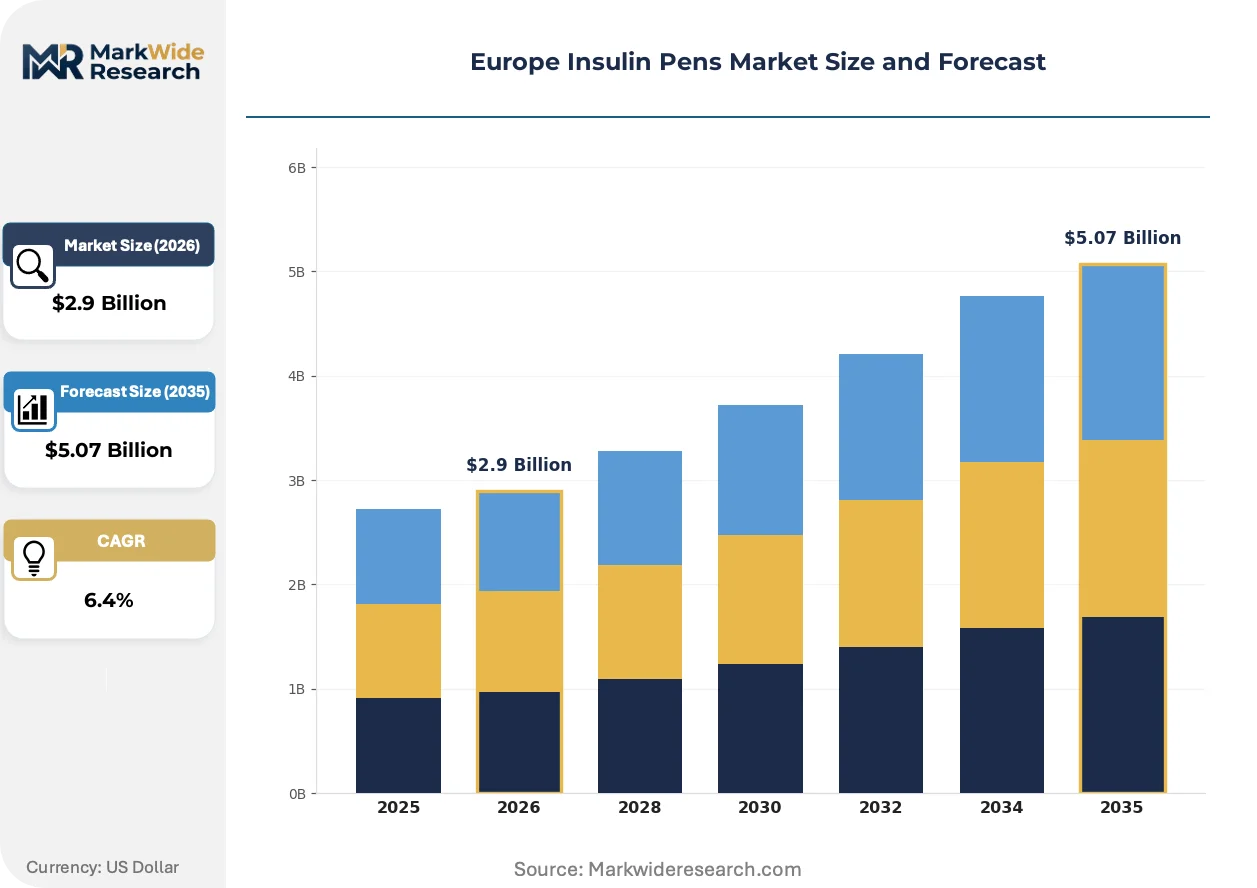
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $5.07 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reusable Pens, Disposable Pens, Smart Pens, Insulin Pump Pens End User: Hospitals, Clinics, Homecare, Diabetes Specialists Technology: Conventional Injection, Automated Delivery, Integrated Monitoring, Bluetooth-enabled Packaging Type: Single-use, Multi-pack, Bulk Packaging, Eco-friendly Packaging |
| Companies Covered | Novo Nordisk, Sanofi, Eli Lilly and Company, Medtronic, Ypsomed, Biocon, Owen Mumford, Haselmeier, Becton Dickinson and Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Insulin Pens Market Shifts & Advancements
Connected delivery systems and sustainable material transitions are restructuring competitive advantage in European insulin pen manufacturing, with data integration capabilities becoming as critical as mechanical precision.
Smart pen ecosystems incorporating near-field communication and cloud-based dose analytics are automating adherence monitoring for payers and clinicians. Germany's Techniker Krankenkasse and France's Assurance Maladie are piloting outcomes-linked reimbursement for Bluetooth-enabled devices. The shift is compressing market share for mechanical-only pens in Northern European markets where digital health infrastructure supports real-time glycemic data transmission.
REACH chemical restrictions on phthalates and bisphenol-A are forcing material transitions in pen barrel and plunger rod production. ECHA substance of very high concern listings are disqualifying legacy polymer grades, compelling reformulation of medical-grade plastics. Southern European manufacturers with captive compounding capabilities are responding faster than outsourced supply chains dependent on Asian resin distributors.
Centralized hospital procurement consortia in the UK and Scandinavia are consolidating volume negotiations and unbundling after-sales service from device pricing. NHS Supply Chain and regional purchasing cooperatives in Sweden are mandating total cost-of-ownership metrics that penalize high-maintenance reusable formats. The behavioral shift is most visible in England's secondary care trusts where disposable pen adoption has accelerated despite higher per-unit acquisition costs.
Europe Insulin Pens Market Segmentation
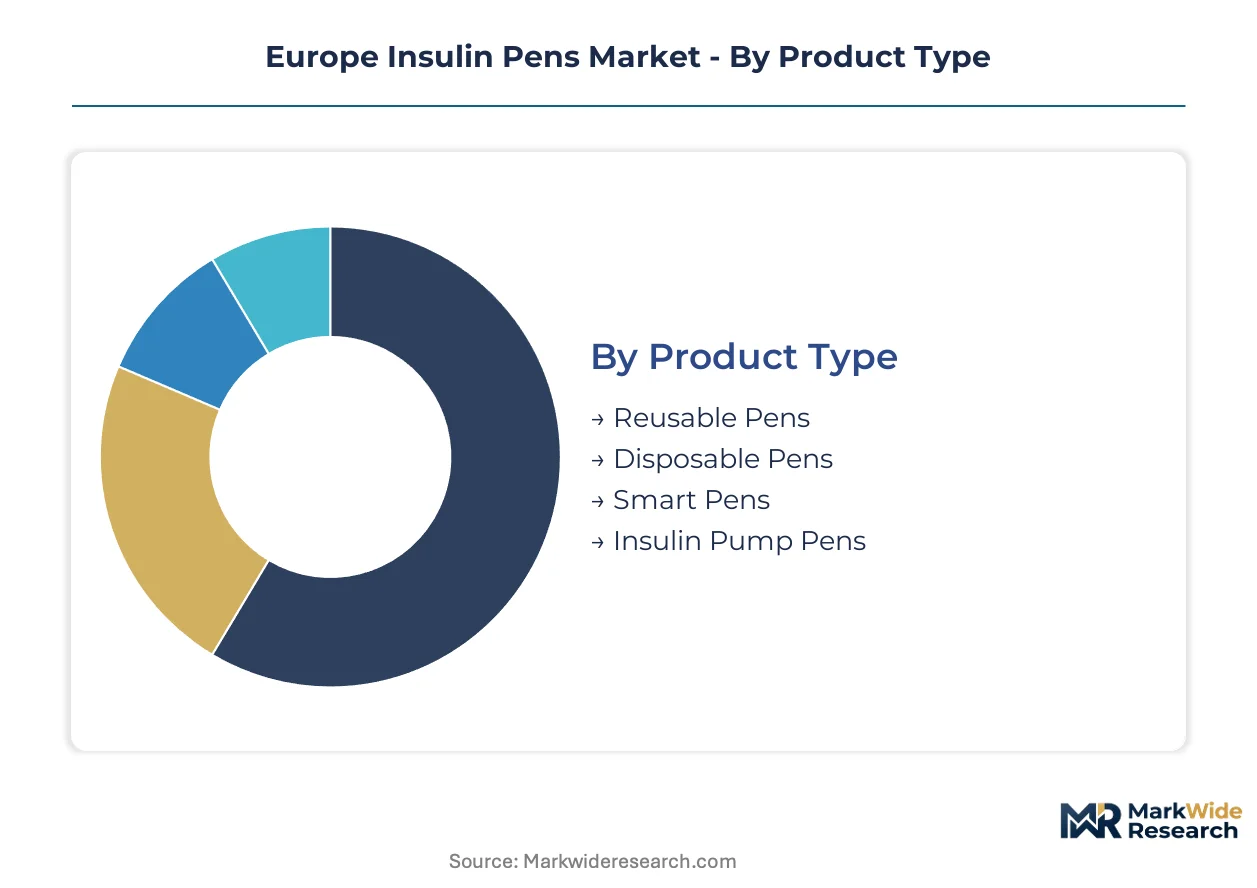
Insulin pen segmentation in Europe tracks reimbursement tiering, infection control mandates, and connectivity infrastructure readiness. Procurement patterns diverge sharply between hospital consortia prioritizing disposables and homecare programs incentivizing data-integrated devices.
Product Type:
Cost sensitivity and reimbursement tiering determine format selection across national health systems.
- Reusable Pens:Metal-bodied devices with replaceable insulin cartridges and detachable needles, engineered for 3-5 year service life. Spain's SNS and Italy's SSN limit disposable reimbursement, preserving 40%+ volume share in Southern Europe where acquisition cost outweighs lifetime maintenance burden.
- Disposable Pens:Pre-filled, single-use units integrating drug reservoir and delivery mechanism in sealed construction. NHS Supply Chain and Scandinavian hospital consortia mandate infection control protocols that override per-unit cost premiums, consolidating procurement volume in Northern European acute care settings.
- Smart Pens:Dose-logging devices with NFC connectivity and adherence analytics. Germany's TK and France's Assurance Maladie pilot outcomes-linked coverage.
- Insulin Pump Pens:Hybrid devices combining continuous subcutaneous infusion with bolus pen functionality. Netherlands and Belgium reimbursement frameworks favor integrated therapy.
Volume sits with disposable formats; growth tilts toward smart pens as glycemic data integration becomes a coverage determinant.
End User:
Channel economics and regulatory liability shape device specification requirements.
- Hospitals:Acute care settings with centralized procurement and sterilization protocols. England's secondary care trusts and German Klinikums prioritize single-use formats to eliminate cross-contamination risk and reduce pharmacy compounding burden.
- Clinics:Outpatient diabetes centers with mixed patient populations and variable reimbursement pathways. France's Centre de Santé and Poland's przychodnie balance cost containment against patient education needs.
- Homecare:Domiciliary administration programs expanding under Germany's ambulatory diabetes management initiatives and the UK's NHS Long Term Plan.
- Diabetes Specialists:Endocrinology practices prescribing connected devices with adherence monitoring capabilities. Netherlands and Denmark lead specialist adoption of Bluetooth-enabled systems.
Procurement concentrates in hospital channels; expansion accelerates fastest in homecare as administration shifts from clinical to domiciliary settings.
Technology:
Connectivity infrastructure maturity and payer data requirements determine technology penetration by geography.
- Conventional Injection:Spring-driven mechanical systems with manual dose setting and passive safety shields. Southern and Eastern European markets with limited digital health infrastructure and restrictive reimbursement for connected devices.
- Automated Delivery:Motorized dose administration with programmable basal-bolus algorithms. Sweden and Finland healthcare regions with advanced diabetes management protocols.
- Integrated Monitoring:Devices incorporating continuous glucose sensor data for real-time dose adjustment. Germany and Netherlands pilot programs.
- Bluetooth-enabled:Wireless dose logging and cloud-based adherence analytics. France, Netherlands, and Denmark reimbursement frameworks incentivizing glycemic data transmission.
Mechanical systems retain installed base; Bluetooth capability climbs fastest where payer infrastructure supports real-time monitoring integration.
Packaging Type:
EU Green Deal mandates and hospital inventory management systems are restructuring secondary packaging specifications.
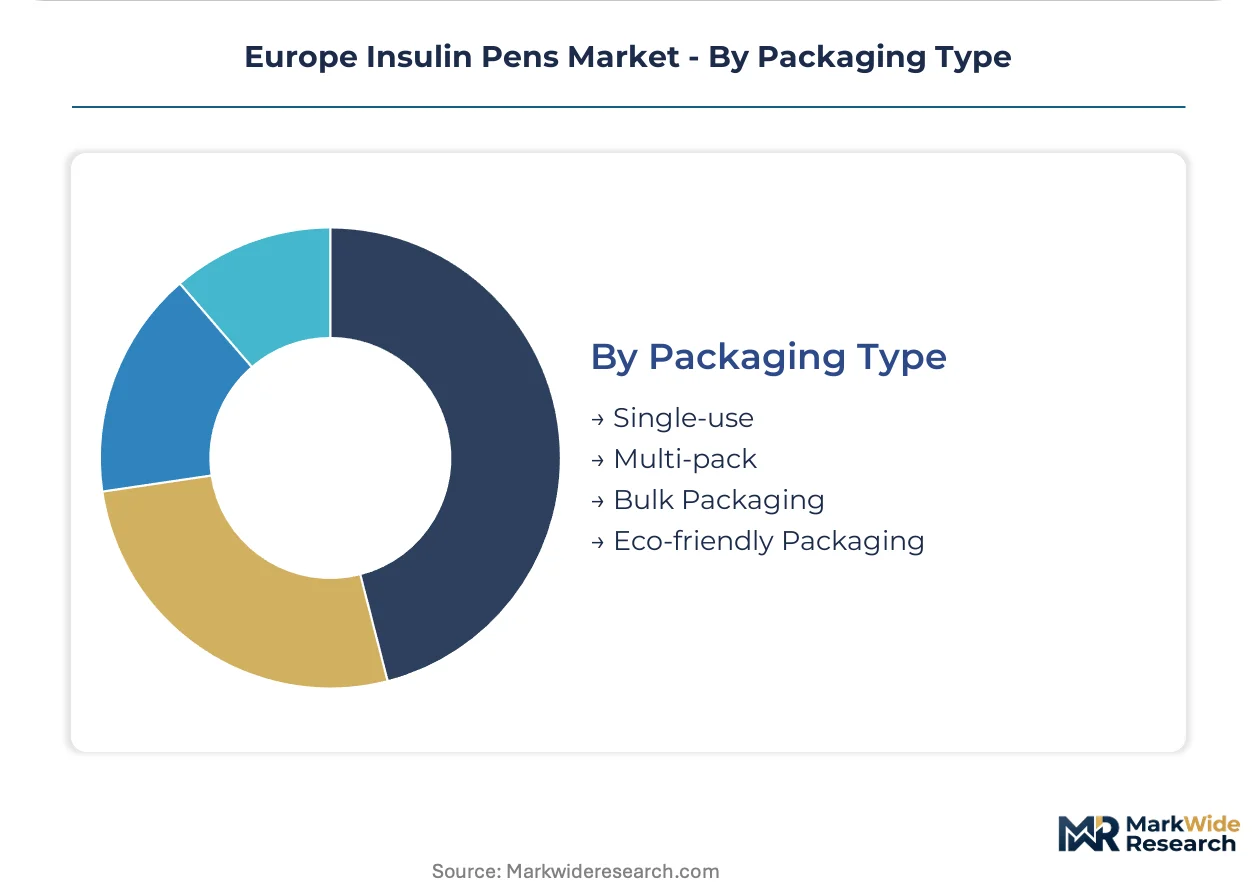
- Single-use:Individual unit packaging with sterilization barrier and patient instruction inserts. Required by UK and Scandinavian hospital consortia for infection control traceability.
- Multi-pack:3-5 unit configurations for pharmacy dispensing and patient convenience. Preferred by German Apotheken and French officines for chronic therapy continuity.
- Bulk Packaging:Hospital-scale cartons with 50-100 units for centralized procurement. NHS Supply Chain and Swedish regional purchasing cooperatives mandate total cost-of-ownership metrics favoring reduced per-unit packaging overhead.
- Eco-friendly Packaging:Bio-based polymers and reduced secondary material formats complying with EU Green Deal packaging directives. First-mover advantage for manufacturers with captive compounding capabilities in Italy and Spain.
Bulk configurations dominate hospital procurement; sustainable formats gain share fastest as ECHA substance restrictions and packaging mandates tighten compliance windows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade polymer compounding capabilities in Germany's Rhine-Ruhr corridor anchor pen manufacturing supply chains across the continent. Swiss precision metalworking clusters in the Jura Arc supply critical dosing subassemblies to assembly plants throughout Western Europe.
Germany
Techniker Krankenkasse and other statutory insurers reimburse Bluetooth-enabled pen systems under ambulatory diabetes management programs, accelerating homecare channel expansion. The EU MDR transition compresses approval timelines at notified bodies in Berlin and Munich, favoring incumbents with established regulatory infrastructure. Manufacturing concentrates in Baden-Württemberg and North Rhine-Westphalia where Bosch and Ypsomed operate precision molding and assembly facilities.
France
Assurance Maladie pilots outcomes-linked coverage for dose-logging devices, creating reimbursement differentiation for connected delivery systems. ANSM enforces combination product oversight alongside EMA guidance, clarifying pre-filled pen regulatory pathways. Industrial activity clusters in Île-de-France and the Rhône-Alpes region around Lyon, where Sanofi maintains device development operations.
United Kingdom
NHS Supply Chain consolidates hospital procurement volume through centralized tenders mandating infection-control traceability for single-use formats. The NHS Long Term Plan shifts infusion therapy to domiciliary settings, expanding pen-based basal-bolus protocols outside acute care. Manufacturing and distribution hubs concentrate in the Midlands and Greater London, serving England's secondary care trusts.
Italy
SSN reimbursement limitations preserve 40% volume share for reusable pen formats in cost-sensitive Southern European markets. REACH chemical restrictions on phthalates compel material transitions at compounding facilities in Lombardy and Emilia-Romagna. Captive polymer reformulation capabilities in Northern Italy enable faster response to ECHA substance of very high concern listings than outsourced Asian supply chains.
Netherlands
Zorgverzekeraars integrate glycemic data transmission into coverage tier determinations, accelerating specialist adoption of Bluetooth-enabled systems. The country's advanced digital health infrastructure supports real-time adherence monitoring for diabetes patients. Device distribution and logistics operations concentrate in the Randstad region, connecting to Belgian and German hospital networks.
Europe Insulin Pens Market Competitive Landscape
Global majors compete with regional champions across regulatory sophistication and reimbursement integration. The market structure consolidates around three strategic tiers: integrated pharmaceutical-device conglomerates with captive insulin portfolios, specialized pen mechanics suppliers serving multiple drug partners, and emerging connectivity-focused entrants. Competitive moves center on MDR conformity investments and partnerships with hospital procurement consortia to secure volume commitments.
Within the integrated pharmaceutical-device tier, Novo Nordisk and Sanofi exemplify archetypes of captive production and format specialization respectively. Eli Lilly and Company occupies a position emphasizing distribution depth across Western European hospital networks. Among precision mechanics specialists, Ypsomed and Haselmeier represent Swiss and German engineering traditions in dosing subassembly manufacturing.
| Leading Market Players |
|---|
| Novo Nordisk |
| Sanofi |
| Eli Lilly and Company |
| Medtronic |
| Ypsomed |
| Biocon |
| Owen Mumford |
| Haselmeier |
| Becton Dickinson and Company |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between MDR-conformant connected pens and legacy mechanical formats manifests in both acquisition premiums and supply chain qualification burdens across European procurement channels. NHS Supply Chain and German Klinikums unbundle after-sales service from device pricing for disposable formats, while Southern European systems bundle lifetime maintenance into reusable pen contracts.
Pricing Analysis
Warranty and service-bundling unbundling now separates Northern European hospital procurement from Southern European pharmacy dispensing models. Three-tier pricing structure across premium smart pens, standard disposables, and economy reusables tracks MDR certification investment and Bluetooth connectivity integration. Pricing pressure stems from centralized NHS and Scandinavian consortia mandating total cost-of-ownership metrics that penalize high-maintenance formats. Homecare channels in Germany and France exhibit lowest price sensitivity due to outcomes-linked reimbursement, while Italy's SSN and Spain's SNS limit disposable coverage, preserving reusable volume.
Supply Chain Analysis
Precision metal component supply rests on Swiss Jura Arc specialists and German Baden-Württemberg metalworkers for critical dosing subassemblies. Medical-grade ABS and polycarbonate feedstock draws from Rhine-Ruhr polymer compounders, with secondary resin sourcing from Lombardy facilities. Single-source vulnerability concentrates in spring mechanism manufacturing, where two German specialists control capacity. Distribution runs through regional hospital procurement consortia in England, Sweden, and Germany, consolidating volume negotiations and compressing intermediary margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe insulin pens market sits in a technology-transition phase, with Bluetooth-enabled dose logging displacing mechanical-only systems as reimbursement differentiators in Northern European markets.
For Market Incumbents: Deploy MDR conformity infrastructure as a competitive moat, accelerating legacy platform recertification before notified body capacity constraints worsen. Incumbents should deepen captive production of dosing mechanisms to protect margin pools against precision component supply concentration, while securing multi-year volume commitments with NHS Supply Chain and Scandinavian hospital consortia to lock out emerging connectivity-focused entrants. For New Entrants and Emerging Players: Launch via specialist diabetes clinics and endocrinology practices in Netherlands and Denmark, where digital health infrastructure supports real-time glycemic data transmission and payer integration is most advanced. White-space targets include cost-sensitive reusable segments in Southern Italy and Spain where SSN reimbursement limitations preserve 40% volume share, and hospital-at-home transition programs under the UK's NHS Long Term Plan expanding domiciliary basal-bolus protocols. For Investors and Strategic Acquirers: Re-rating potential sits with precision mechanics specialists possessing MDR-compliant manufacturing infrastructure and captive polymer compounding capabilities given REACH chemical restriction compliance windows. Long-term viability favors targets with backward integration into dosing subassembly production and established regulatory affairs capacity across Berlin and Munich notified body relationships. Watch NHS Long Term Plan procurement shifts and EMA combination product guidance clarifications as inflection indicators for connected device adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Conformity Pathway Investment | Accelerated technical file compilation at Berlin and Munich notified bodies compresses approval timelines for new pen introductions. |
| Bluetooth Connectivity Integration | Germany's Techniker Krankenkasse and France's Assurance Maladie pilot outcomes-linked reimbursement for dose-logging devices. |
| Hospital Procurement Consortium Partnership | NHS Supply Chain centralized tenders mandate infection-control traceability, consolidating volume for compliant suppliers. |
| Bio-based Material Transition | EU Green Deal packaging directives create first-mover advantage for manufacturers with captive Lombardy compounding capabilities. |
| Homecare Channel Expansion | Germany's ambulatory diabetes management programs and UK NHS Long Term Plan shift administration from clinical to domiciliary settings. |
Research Methodology
Multi-period observation of reimbursement tier shifts, MDR approval timelines, and procurement consortium contract awards anchored the trend analysis, supplemented by interviews with hospital purchasing committee members, biomedical engineers at German Klinikums, regulatory affairs leads at notified bodies, GPO contracts managers, and endocrinology practice administrators. Secondary validation drew from EMA combination product guidance documents, NHS Supply Chain tender databases, EU MDR implementation reports, and hospital procurement databases. Bottom-up volume modeling triangulated against top-down market sizing across the analysis window.
Segment-weighting approaches distributed value projections across product type, end user channel, technology connectivity level, and packaging format dimensions. CAGRs were derived from regression analysis of historical adoption curves and reimbursement policy trajectories throughout the forecast period. Industry-specific inputs incorporated notified body capacity constraints, REACH chemical restriction implementation schedules, and digital health infrastructure readiness indices by member state.
Notified body capacity bottlenecks, REACH substance of very high concern listing expansions, and NHS procurement policy reversals are the dominant revision risks to volume and value projections. Forecasts reflect documented assumptions on reimbursement pathway stability and MDR transition timelines. A small set of regulatory and procurement triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Asia-Pacific Plant-Based Biologics Market
Biopharmaceuticals
Global Mono Vaccine Market
Biopharmaceuticals
Single-Domain Antibody Platforms Market
Biopharmaceuticals
North America Generic Oncology Drug Market
Biopharmaceuticals
Italy Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Terbinafine Tablet Market
Biopharmaceuticals
Canada Generic Drug Market
Biopharmaceuticals
Human Chorionic Gonadotropin Market
Biopharmaceuticals
North America Monoclonal Antibody Market
Biopharmaceuticals
Biopharmaceutical Contract Research and Manufacturing Services (CRAMS) Market
Biopharmaceuticals
Global Swine Fever Vaccine Market
Biopharmaceuticals
Global Carcinoembryonic Antigen (CEA) Market
Biopharmaceuticals
Plasma Protein System Market
Biopharmaceuticals
Somatostatin Analogs Market
Biopharmaceuticals
Primary Biliary Cholangitis (PBC) Therapeutics Market
Biopharmaceuticals
Global Myelodysplastic Syndrome (MDS) Drugs Market