
 Botanical and Plant Derived Drugs Market | 2026-2036
Botanical and Plant Derived Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Botanical and Plant Derived Drugs Market Analysis
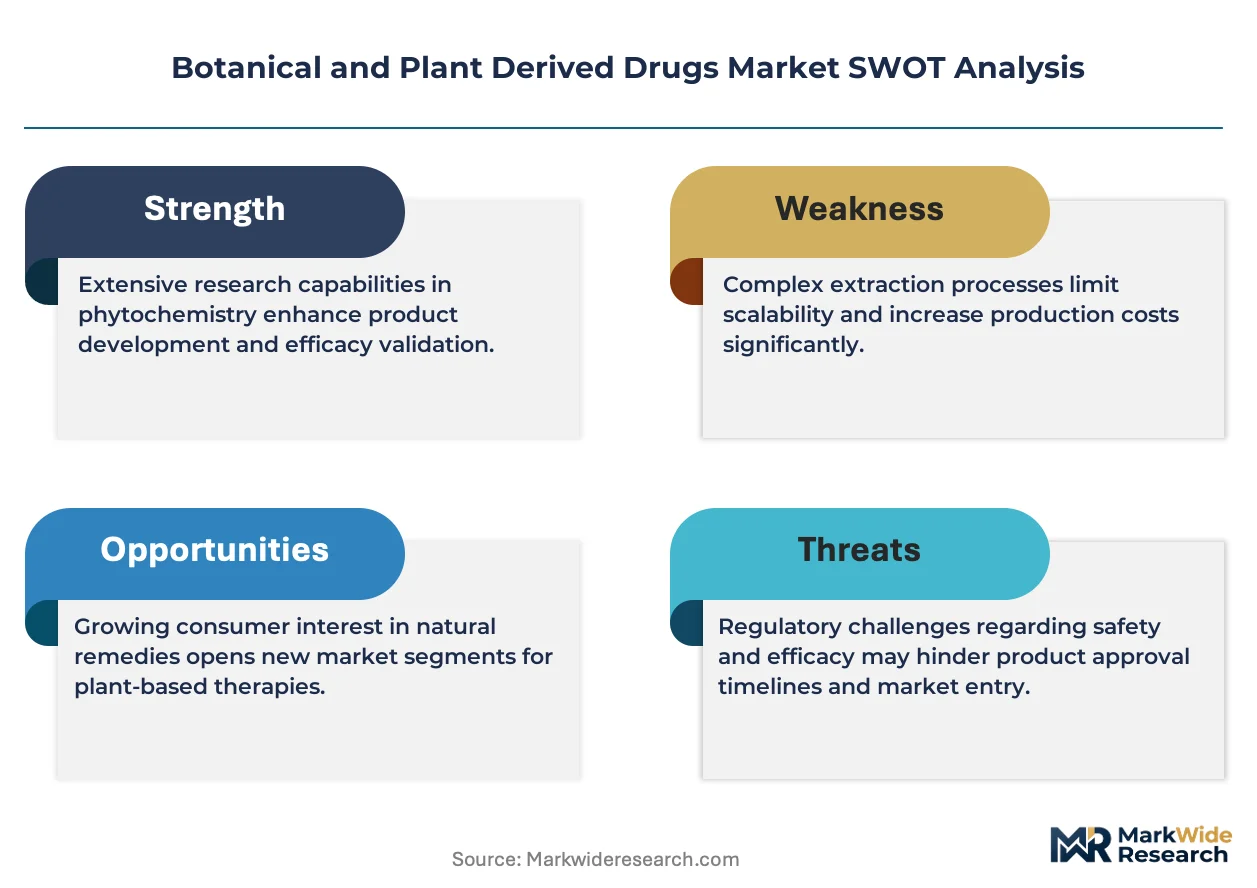
Phytochemistry expertise shortages across contract research organizations is reorganizing how developers access specialized extraction and standardization capabilities. Bayer AG leverages its historical strength in botanical extraction to sustain leadership in cardiovascular phytotherapies. Schwabe Pharmaceuticals anchors European supply through its integrated cultivation-to-tablet operations for Ginkgo biloba and Echinacea preparations. Tsumura & Co. dominates the Japanese kampo medicine sector through its control of premium raw material sourcing from domestic growers.
Botanical and plant derived drugs comprise purified, semi-purified, or crude preparations from plant biomass, typically standardized to marker compounds such as alkaloids, glycosides, or terpenoids with defined potency specifications. These therapeutics serve as prescription medicines, adjuvant treatments, and prophylactic agents across human and veterinary health systems. Herbal extracts command the largest revenue share within product type categories due to their established clinical documentation and regulatory acceptance in multiple jurisdictions. Cancer treatment represents the fastest-expanding therapy area as paclitaxel, vincristine, and irinotecan derivatives face supply pressure from oncology pipeline expansion. Pharmaceutical applications retain the dominant end-use position, though nutraceuticals are gaining shelf space through pharmacy channels in European markets.
FDA botanical drug guidance, EMA herbal monograph requirements, and China's NMPA traditional medicine registration pathways collectively shape development timelines and market access conditions for plant-derived therapeutics. The FDA's allowance of mixed botanical-to-synthetic development pathways reduces regulatory friction for sponsors with existing phytochemical infrastructure. Stakeholders must monitor evolving pharmacovigilance expectations for complex botanical mixtures as regulators tighten post-market surveillance requirements.
Market Dynamics
Phytochemistry expertise shortages across contract research organizations are reorganizing how developers access specialized extraction and standardization capabilities, forcing sponsors to restructure their externalization strategies and build captive competency centers.
Growth Catalysts
- FDA Botanical Drug Guidance:The FDA's streamlined pathway from herbal preparation to approved prescription product reduces regulatory friction for sponsors with existing phytochemical infrastructure, accelerating time-to-market for standardized botanical mixtures.
- Germany Commission E Monographs:The world's most established reimbursement framework for phytomedicines creates predictable market access conditions that attract formulation investment and clinical documentation spending.
- Oncology Pipeline Expansion:Academic medical centers are broadening formularies to include paclitaxel and other plant-derived chemotherapeutics, generating supply pressure that pulls capacity investment toward high-potency extraction.
Market Restraints
- Raw Material Concentration Risk:Premium sourcing for kampo and traditional Chinese medicine preparations concentrates among domestic Japanese and Chinese growers, exposing formulators to harvest volatility and geopolitical friction.
- EMA Herbal Monograph Compliance Costs:European documentation requirements for marker compound standardization impose fixed cost burdens that disadvantage smaller extract houses lacking analytical infrastructure.
- Synthetic Biology Substitution:Microbial production platforms for artemisinin and cannabinoids threaten long-term demand for agricultural cultivation of high-value therapeutic plants.
Strategic Opportunities
- Veterinary Phytomedicine Underpenetration:Livestock and companion animal health systems show minimal botanical drug adoption relative to human medicine, presenting first-mover expansion potential for standardized veterinary formulations.
- Pharmacy Channel Integration:European nutraceuticals are gaining shelf space through pharmacy channels, creating hybrid prescription-OTC positioning that captures consumer trust and professional recommendation.
- China NMPA Traditional Medicine Registration:Accelerated review pathways for classical formula preparations offer foreign sponsors expedited access to the world's largest traditional medicine market.
Industry Challenges
- Phytochemistry Talent Scarcity:Contract research organizations face acute shortages of extraction chemists capable of developing scalable processes for complex botanical mixtures, compressing project timelines and inflating specialist compensation.
- Post-Market Surveillance Intensification:Regulators are tightening pharmacovigilance expectations for multi-component botanical products, requiring sponsors to maintain costly traceability systems from cultivation batch to patient outcome.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Botanical and Plant Derived Drugs Market |
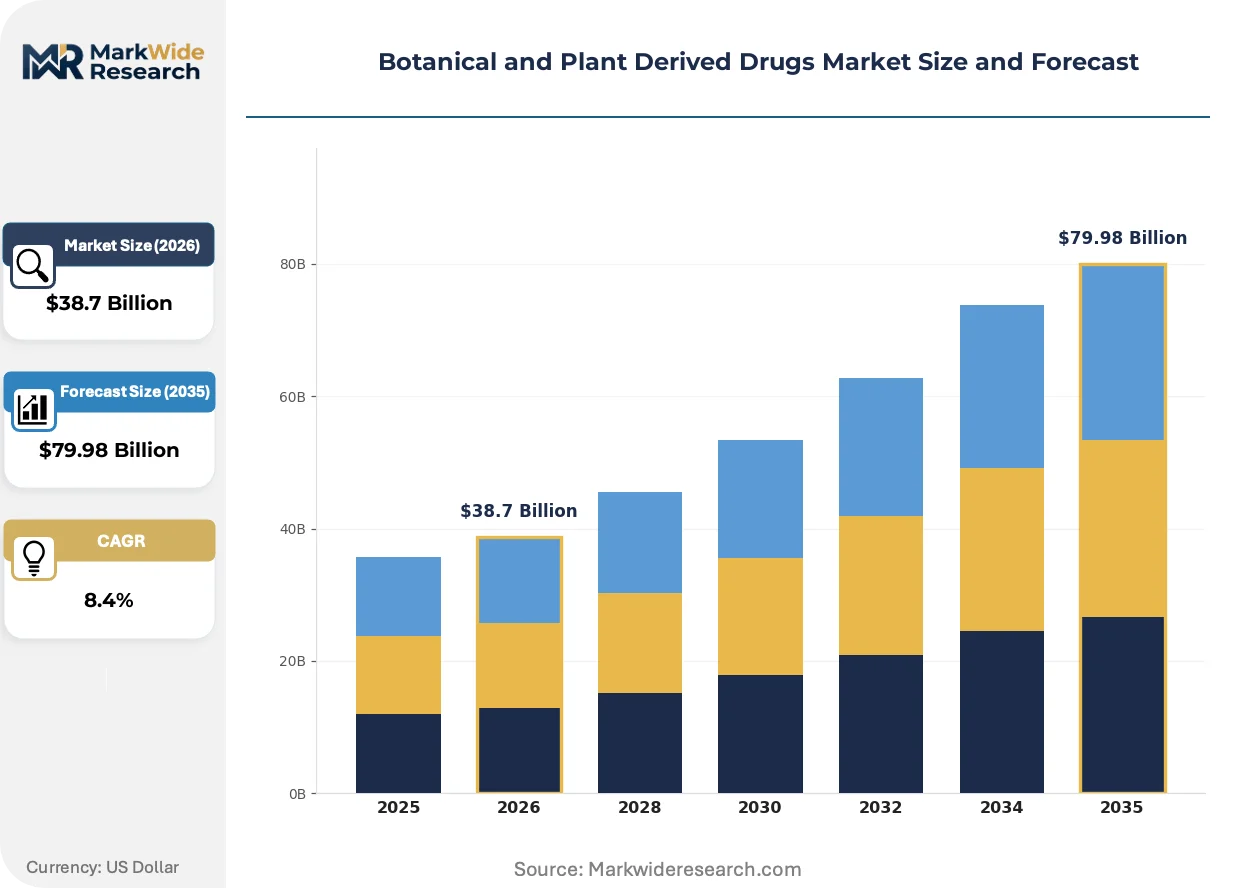
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Extracts, Essential Oils, Phytochemicals, Plant-based Compounds Therapy Area: Cardiovascular Disorders, Gastrointestinal Issues, Neurological Conditions, Cancer Treatment Application: Pharmaceuticals, Nutraceuticals, Cosmeceuticals, Veterinary Medicine End User: Hospitals, Clinics, Research Institutions, Pharmacies |
| Companies Covered | Bayer AG, Jazz Pharmaceuticals, Schwabe Pharmaceuticals, Tasly Pharmaceutical Group, Sun Pharmaceutical Industries, Tsumura & Co., Bionorica SE, Jaguar Health, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Botanical and Plant Derived Drugs Market Emerging Trajectories
Continuous processing technologies and precision fermentation are actively displacing batch extraction conventions, while regulatory frameworks on three continents converge toward quality-by-design documentation standards.
Supercritical CO2 extraction is supplanting conventional solvent-based methods in high-value alkaloid recovery. Oncology API manufacturers are adopting these systems to meet residual solvent specifications for paclitaxel and docetaxel production. The shift is compressing purification stages and reducing environmental compliance burdens for facilities operating under EPA and MEE oversight.
REACH registration requirements for botanical substances are forcing European extract houses to invest in substance identity dossiers for complex plant matrices. The regulation's industrial consequence is consolidation among suppliers capable of funding chronic toxicity studies. German and Swiss manufacturers with existing chemical registration infrastructure are capturing contract manufacturing share from smaller Mediterranean competitors.
Hospital formulary committees are tightening botanical drug evaluation protocols, demanding head-to-head comparator data against synthetic alternatives. Academic medical centers in the US and Japan are replacing traditional procurement with value-assessment frameworks that weight total cost of care. This behavioral shift is most visible in oncology departments, where pharmacy directors now require real-world evidence packages before adding plant-derived chemotherapeutics to restricted distribution lists.
Botanical and Plant Derived Drugs Market Segmentation
Channel strategy in botanical drugs hinges on standardization levels. Pharmacy-dispensed phytomedicines require different marker compound specifications than hospital-administered oncology APIs, forcing manufacturers to maintain parallel production lines and documentation systems.
Product Type:
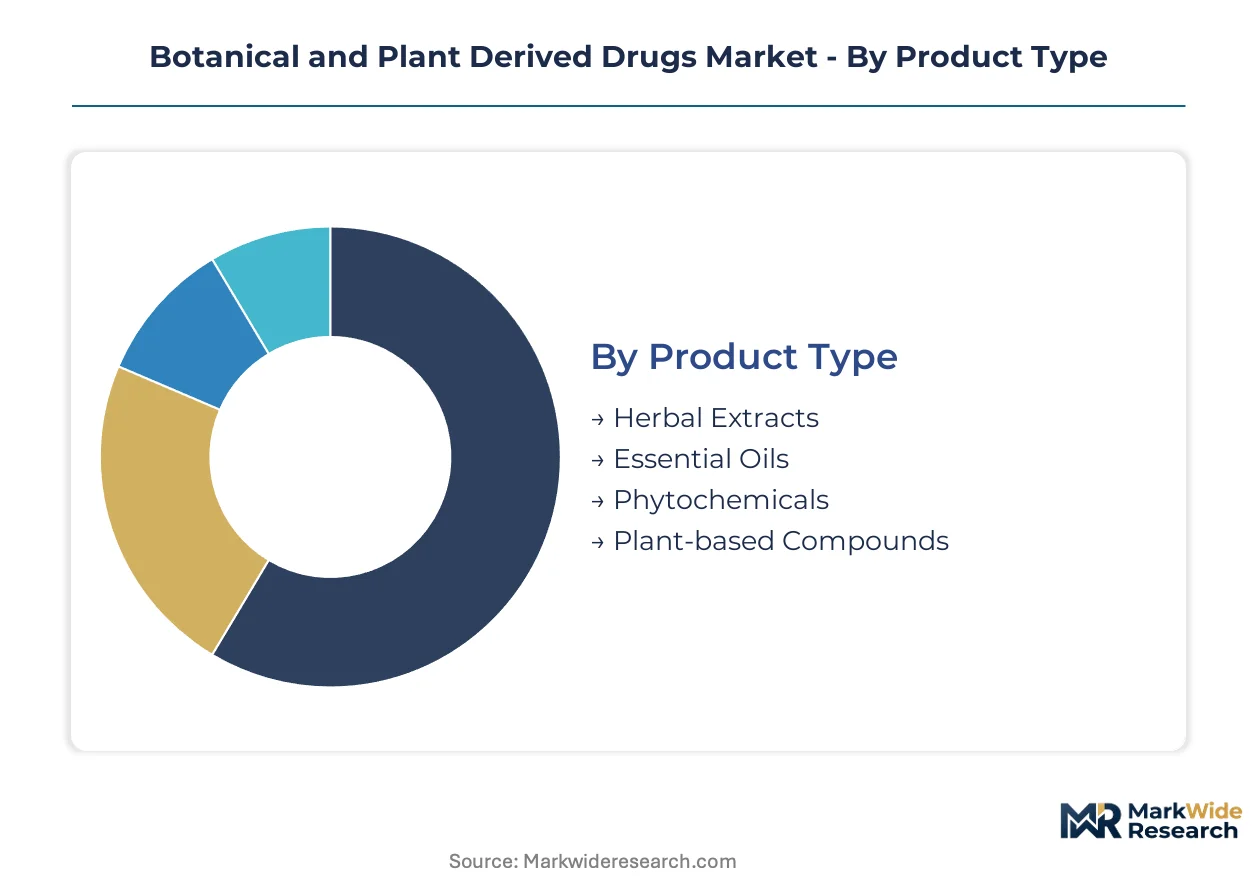
Channel access varies sharply by purification tier. Crude preparations dominate pharmacy and wellness retail, while standardized extracts capture hospital procurement through pharmacopeial compliance.
- Herbal Extracts:Semi-purified preparations standardized to marker compounds such as flavonoids or saponins, typically delivered as dry powders or soft extracts. Demand concentrates in German pharmacy channels where Commission E monographs mandate defined potency specifications for reimbursement eligibility.
- Phytochemicals:Isolated single compounds including alkaloids, glycosides, and terpenoids at high chemical purity. Oncology API manufacturers in Japan and the US source paclitaxel and camptothecin derivatives through restricted distribution networks subject to FDA and PMDA batch release protocols.
- Essential Oils:Volatile aromatic fractions obtained through steam distillation or cold pressing, used in topical and aromatherapy applications.
- Plant-based Compounds:Crude botanical preparations including tinctures and dried plant materials for traditional medicine systems.
Herbal extracts dominate installed base. Phytochemicals are where expansion concentrates.
Therapy Area:
Clinical documentation intensity drives cost-to-serve across therapeutic categories. Oncology applications require phase III equivalence data, while gastrointestinal indications rely on established monograph citations.
- Cancer Treatment:Plant-derived cytotoxic agents including vinca alkaloids, taxanes, and camptothecin derivatives administered in infusion protocols. Academic medical centers in the US and Germany are broadening formularies to include these agents, generating supply pressure that pulls capacity investment toward high-potency extraction facilities.
- Cardiovascular Disorders:Standardized extracts of hawthorn, garlic, and ginkgo targeting chronic disease management. German statutory health insurance reimburses these preparations through the Commission E framework, creating predictable demand pull through pharmacy channels.
- Gastrointestinal Issues:Bitter preparations and mucilaginous botanicals for functional digestive disorders.
- Neurological Conditions:Ginkgo and St. John's wort extracts positioned for cognitive and mood indications.
Cardiovascular disorders dominate installed base. Cancer treatment is climbing the fastest.
Application:
Margin structure diverges by regulatory pathway. Pharmaceutical applications bear full GMP compliance costs, while nutraceuticals exploit notification frameworks with lighter documentation burdens.
- Pharmaceuticals:Prescription botanical drugs subject to FDA botanical drug guidance or EMA herbal monograph requirements. These products command premium positioning through hospital formularies and restricted distribution networks in the US, Germany, and Japan.
- Nutraceuticals:Dietary supplements and functional foods with botanical ingredients, gaining shelf space through European pharmacy channels that confer professional endorsement and consumer trust.
- Cosmeceuticals:Topical botanical preparations with therapeutic claims bridging cosmetic and pharmaceutical regulation.
- Veterinary Medicine:Livestock and companion animal phytotherapeutics showing minimal adoption relative to human medicine, presenting first-mover expansion potential for standardized veterinary formulations.
Pharmaceuticals dominate installed base. Nutraceuticals are where expansion concentrates.
End User:
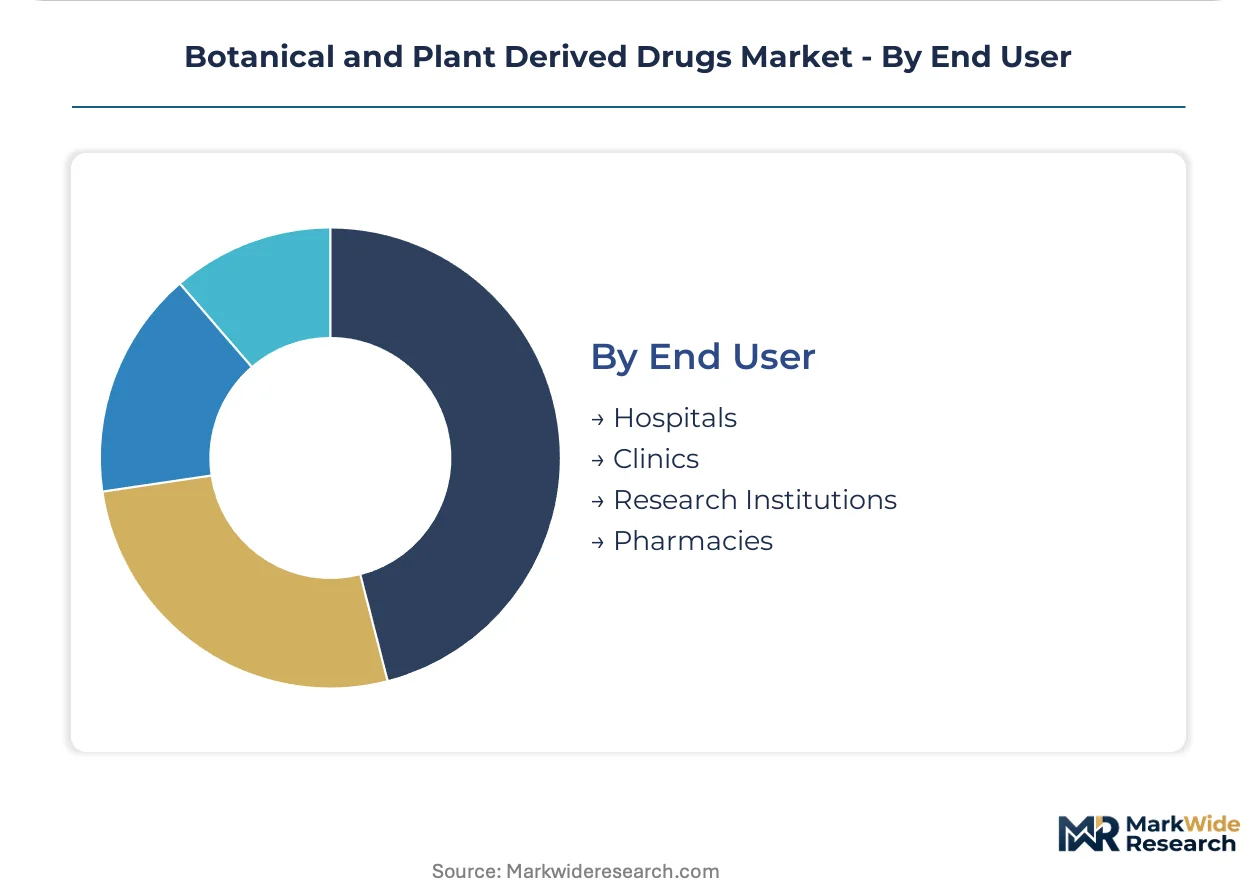
Procurement authority determines specification stringency. Hospital pharmacy directors demand batch certificates and stability data, while retail pharmacies rely on supplier reputation and monograph compliance.
- Hospitals:Institutional purchasers of high-potency injectable botanicals for oncology and critical care. Formulary committees in US academic medical centers now require real-world evidence packages before adding plant-derived chemotherapeutics to restricted distribution lists.
- Pharmacies:Primary dispensing channel for oral phytomedicines in Germany, where statutory reimbursement creates volume concentration.
- Clinics:Outpatient settings administering botanical therapies in integrated medicine frameworks.
- Research Institutions:Academic centers conducting clinical trials under FDA botanical drug guidance or NMPA traditional medicine registration pathways.
Pharmacies dominate installed base. Hospitals are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands pricing premiums through Commission E reimbursement security, while Chinese suppliers compete on cultivation scale without equivalent regulatory validation. This asymmetry shapes investment flows toward European markets with established monograph frameworks.
United States
Oncology departments at academic medical centers in Boston and Houston are expanding paclitaxel formularies, pulling demand toward high-potency extraction capacity. FDA botanical drug guidance creates a streamlined pathway from herbal preparation to prescription product. Manufacturing clusters in North Carolina and Puerto Rico host contract extraction facilities serving hospital procurement networks.
Germany
Statutory health insurance reimbursement through the Commission E monograph system generates predictable demand pull for hawthorn and ginkgo preparations. EMA herbal monograph requirements enforce marker compound standardization that filters smaller competitors from pharmacy channels. Schwabe Pharmaceuticals anchors supply through integrated cultivation-to-tablet operations in Bielefeld and Ettlingen.
Japan
Domestic kampo medicine consumption concentrates demand for premium raw materials sourced from contract growers in Hokkaido and Kyushu. PMDA batch release protocols govern restricted distribution networks for injectable botanical APIs. Tsumura & Co. controls sourcing infrastructure through long-term cultivation agreements with regional agricultural cooperatives.
China
NMPA traditional medicine registration pathways offer accelerated review for classical formula preparations, attracting foreign sponsor investment. MEE oversight of extraction facilities is tightening residual solvent and wastewater discharge standards. Industrial clusters in Zhejiang and Sichuan provinces concentrate contract manufacturing for export-oriented botanical extract houses.
Switzerland
Swissmedic registration requirements for complex botanical mixtures maintain quality barriers that favor manufacturers with existing pharmacopeial infrastructure. REACH substance identity dossier costs are consolidating supplier base among German and Swiss competitors. Basel and Zurich host formulation specialists serving hospital pharmacy networks across German-speaking Europe.
Botanical and Plant Derived Drugs Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the botanical drug value chain. European and Japanese incumbents dominate standardized extract production through regulatory documentation advantages, while Chinese and Indian suppliers compete on cultivation scale and solvent extraction throughput. The market structure separates into three strategic archetypes: integrated cultivation-to-tablet operators, specialized oncology API manufacturers, and regional traditional medicine houses. Competitive moves concentrate on backward integration into premium raw material sourcing and capacity expansion for high-potency alkaloid extraction.
Within the integrated cultivation tier, Schwabe Pharmaceuticals and Tsumura & Co. represent archetypes of geographic sourcing control. Bayer AG occupies a position spanning cardiovascular phytotherapies and broader pharmaceutical infrastructure. Among oncology-focused developers, Jazz Pharmaceuticals exemplifies the specialized API manufacturer archetype serving hospital formulary networks.
| Leading Market Players |
|---|
| Bayer AG |
| Jazz Pharmaceuticals |
| Schwabe Pharmaceuticals |
| Tasly Pharmaceutical Group |
| Sun Pharmaceutical Industries |
| Tsumura & Co. |
| Bionorica SE |
| Jaguar Health |
| Novartis AG |
| Others |
Supply Flow & Price Mechanics
REACH substance identity dossier requirements gate both supplier qualification and price differentiation in European botanical extraction. German and Swiss manufacturers leverage existing chemical registration infrastructure to command premium positioning, while Mediterranean competitors without analytical capabilities face margin compression or exit.
Pricing Analysis
Configured-to-order pricing for marker-compound-standardized extracts commands substantial premiums over commodity crude preparations. Three-tier pricing structure across premium, standard, and economy levels stratifies by pharmacopeial compliance tier and batch certification depth. Cost compression in standard-grade herbal extracts is intensifying because Chinese suppliers are expanding solvent-extraction throughput without equivalent documentation investment. Hospital procurement directors show lowest price sensitivity due to formulary committee oversight, while wellness retail channels exhibit highest elasticity.
Supply Chain Analysis
Premium raw material sourcing for kampo preparations concentrates among domestic Japanese growers in Hokkaido and Kyushu, creating single-source vulnerability for Tsumura and competing formulators. High-potency alkaloid production draws from specialized cultivation contracts in Zhejiang and Sichuan provinces, with paclitaxel precursor supply resting on yew tree bark and needle harvesting cycles. Tariff exposure on Chinese-origin extracts is forcing European formulators to qualify alternative suppliers in India and Vietnam. Distribution runs through restricted oncology API networks in Japan and the US, while oral phytomedicines flow through German pharmacy wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extraction chemist scarcity sits at the center of competitive advantage in this market. Sponsors who secure captive phytochemistry capability or lock in long-term CRO partnerships will outpace rivals facing project delays and specialist wage inflation.
For Market Incumbents: Shield market position by deepening backward integration into premium cultivation contracts in Japan and Germany, insulating supply from harvest volatility and geopolitical friction. Expand high-potency extraction capacity in North Carolina or Puerto Rico to capture oncology API demand from academic medical centers. Synthetic biology substitution of artemisinin and cannabinoids represents the priority threat requiring R&D hedging through microbial platform partnerships.
For New Entrants and Emerging Players: Differentiate on veterinary phytomedicine formulations, where standardization requirements remain minimal and first-mover branding opportunity is wide open. Target European pharmacy channel integration for nutraceutical positioning that captures professional endorsement and consumer trust. Pursue China NMPA classical formula registration as the most penetrable regulatory pathway for foreign sponsors seeking access to traditional medicine markets.
For Investors and Strategic Acquirers: FDA botanical drug guidance expansion reshapes the acquisition landscape by validating mixed botanical-to-synthetic development pathways. Long-term viability favors integrated cultivation-to-tablet operators with existing pharmacopeial infrastructure over pure-play extraction houses facing REACH compliance cost escalation. Watch for EMA herbal monograph revision schedules as the signal indicating when smaller European competitors will face forced consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Premium Cultivation | Schwabe and Tsumura models demonstrate sourcing control reduces harvest volatility exposure. |
| Supercritical CO2 Extraction Scale-Up | Oncology API manufacturers adopting these systems meet EPA residual solvent specifications. |
| Veterinary Formulation Development | Livestock and companion animal health systems show minimal botanical drug adoption currently. |
| China NMPA Classical Formula Registration | Accelerated review pathways offer foreign sponsors expedited access to traditional medicine demand. |
| Continuous Processing Technology Adoption | Precision fermentation platforms threaten long-term agricultural cultivation economics for high-value compounds. |
Methodological Framework
A standing panel of extraction chemists at contract research organizations, formulary directors at US academic medical centers, regulatory affairs leads at German phytomedicine manufacturers, and pharmacy procurement managers in Japanese hospital systems provided ongoing calibration. Primary interviews combined with secondary validation against FDA botanical drug guidance filings, EMA herbal monograph submissions, NMPA traditional medicine registration databases, and Commission E reimbursement records. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Consistency checks against external benchmarks validated projections across the analysis window. Segmentation dimensions included purification tier, therapy area clinical documentation intensity, application regulatory pathway, and end-user procurement authority. CAGRs derived from slope analysis of historical capacity expansion and demand pull from oncology pipeline expansion. Forecast inputs incorporated supercritical extraction adoption curves and REACH registration cost trajectories.
Material uncertainties — regulatory monograph revision timing, synthetic biology substitution rates, geopolitical friction in East Asian sourcing — sit outside the modeled envelope. Forecasts reflect assumptions about sustained reimbursement security in Germany and continued FDA pathway utilization. Practitioners should keep alternative scenarios live as EMA herbal monograph compliance costs and microbial production platform economics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Compounded Bioidentical Hormone Therapy Market
Biopharmaceuticals
Lupus Nephritis Market
Biopharmaceuticals
HIV Drugs Market
Biopharmaceuticals
Canada Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
South Korea Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Global Breast Cancer Drugs Market
Biopharmaceuticals
Discovery Bioanalysis Market
Biopharmaceuticals
Insulin Aspart Market
Biopharmaceuticals
Global Drug Discovery Market
Biopharmaceuticals
Antibody Pair Kits Market
Biopharmaceuticals
APAC Insulin Market
Biopharmaceuticals
Global Insulin Glargine Market
Biopharmaceuticals
Rivaroxaban Market
Biopharmaceuticals
Influenza Vaccine Market
Biopharmaceuticals
Heparin API Market
Biopharmaceuticals
Insulin Delivery Pens Market