
 North America Plasma Fractionation Market | 2026-2036
North America Plasma Fractionation Market Size, Share, and Industry Trends Forecast 2026-2036
North America Plasma Fractionation Market Analytics
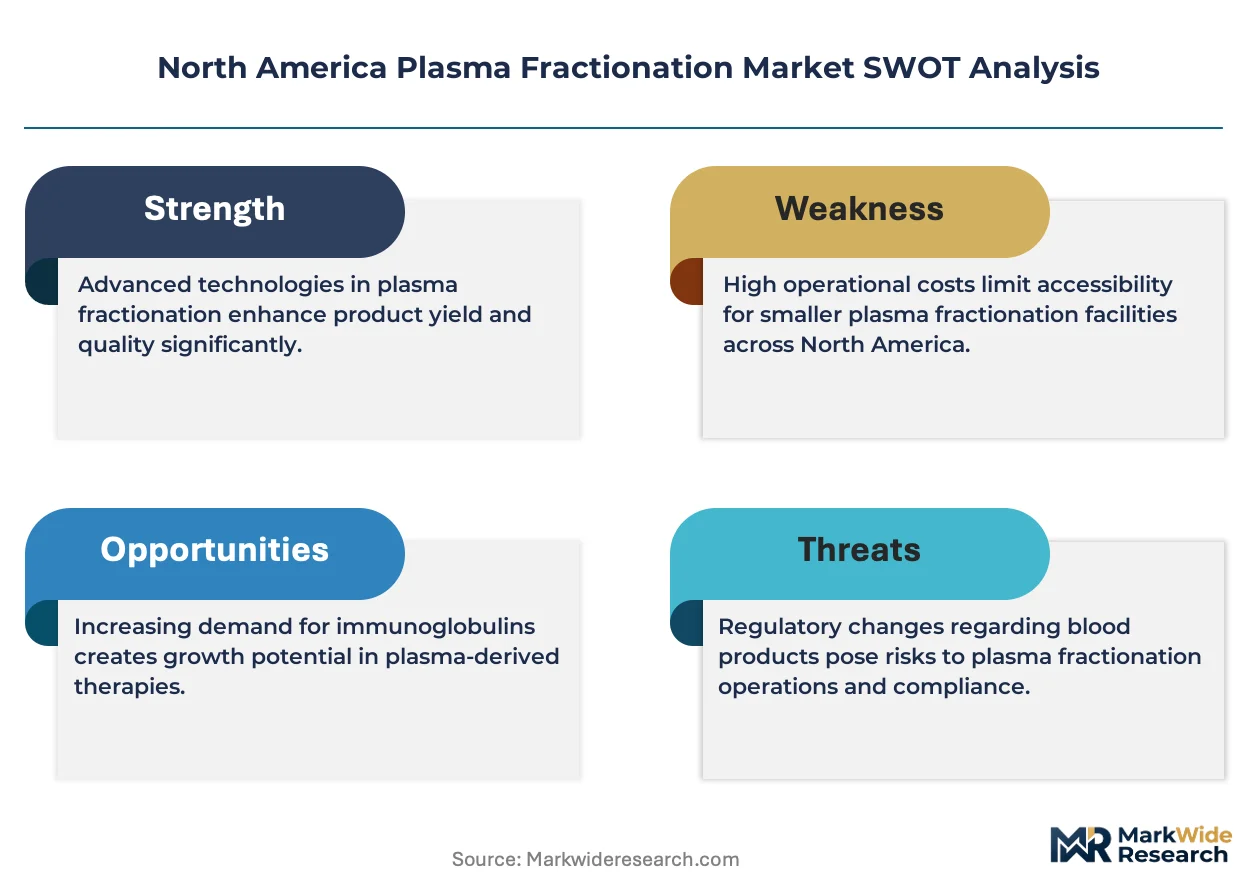
Hospital procurement consolidation is hardening across the North America plasma fractionation landscape. CSL Behring leverages its vertically integrated plasma collection network to sustain supply security for major health systems. Grifols anchors its position through high-volume fractionation capacity and specialized immunoglobulin output. Takeda Pharmaceutical Company Limited competes on recombinant and plasma-derived coagulation factor portfolios across Canadian and U.S. academic medical centers.
Plasma fractionation separates blood plasma into therapeutic proteins through cold ethanol precipitation, chromatography, and viral inactivation steps yielding immunoglobulins, albumin, and coagulation factors with defined purity thresholds. The process serves critical therapeutic functions in immunodeficiency management, hemophilia treatment, and volume resuscitation protocols. Immunoglobulin segment margins reflect chronic therapy dependence in neurology and immunology applications. Coagulation factors capture premium positioning within hematology despite recombinant competition. Albumin maintains steady hospital utilization though pricing pressure persists from synthetic colloid alternatives.
FDA plasma donor deferral policies and Health Canada's Biologics and Genetic Therapies Directorate standards govern collection volumes, viral safety testing, and lot release protocols across U.S. and Canadian operations. OSHA bloodborne pathogen regulations and state-level pharmacy compounding rules further shape facility certification and operational compliance burdens. Stakeholders must monitor evolving FDA guidance on transfusion-transmitted infection screening and pathogen reduction technology validation requirements to secure market access and avoid supply disruption.
Market Dynamics
Hospital procurement consolidation across the United States and Canada is compressing vendor rosters and favoring fractionators with captive plasma supply networks. This structural concentration is forcing mid-scale operators to secure long-term supply agreements or exit hospital formulary access entirely.
Growth Catalysts
- FDA Pathogen Reduction Mandates:Updated validation requirements for solvent-detergent and nanofiltration steps are accelerating facility upgrades across U.S. fractionation plants. Academic medical centers now specify certified pathogen-reduced immunoglobulin lots in tender documents.
- Immunoglobulin Chronic Therapy Dependence:CIDP and multifocal motor neuropathy treatment protocols require sustained IVIG or SCIG administration. Neurology and immunology patient volumes at integrated delivery networks are expanding fractionation pull-through.
- Canada's Biologics and Genetic Therapies Directorate Standards:Harmonized lot release protocols with FDA viral safety testing are reducing cross-border regulatory friction. Canadian plasma collectors are scaling collection center networks to serve dual-registered fractionators.
Market Restraints
- Plasma Collection Input Volatility:Donor deferral policies and seasonal recruitment challenges constrain source plasma volumes. Collection economics depend on paid donor compensation models that face periodic state-level legislative pressure.
- Recombinant Coagulation Factor Substitution:Hemophilia A and B treatment guidelines increasingly favor recombinant FVIII and FIX products. Plasma-derived factor concentrates are losing share in pediatric and previously untreated patient populations.
- Supply-Side Geographic Concentration:Fractionation capacity clusters in select U.S. metropolitan corridors and southern Ontario. Single-site production disruptions risk continental supply shortages for albumin and specific immunoglobulin formulations.
Strategic Opportunities
- Underpenetrated Subcutaneous Immunoglobulin Home Infusion:U.S. Medicare reimbursement pathways for SCIG self-administration are expanding patient eligibility. Home infusion providers are building specialized nursing networks to capture this shift from hospital-based IVIG delivery.
- Health Canada Priority Review Pathways:Accelerated biologics licensing for rare disease indications offers faster market entry for novel plasma-derived therapies. Canadian regulatory submissions can leverage U.S. FDA approval packages to compress timeline risk.
- Chromatography and Nanofiltration Convergence:Integrated capture and viral clearance platforms are reducing processing steps and yield loss. Fractionators deploying combined affinity and membrane technologies are achieving higher specific activity in immunoglobulin output.
Industry Challenges
- Plasma Collection Center Workforce Scarcity:Phlebotomist and licensed practical nurse recruitment lags U.S. center expansion plans. Training pipelines for specialized donor screening personnel require 12-18 month certification cycles.
- Legacy ERP Integration with Track-and-Trace Systems:DSCSA compliance deadlines are forcing upgrades to serialization infrastructure. Fractionators with outdated manufacturing execution systems face lot reconciliation failures and delayed release timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Plasma Fractionation Market |
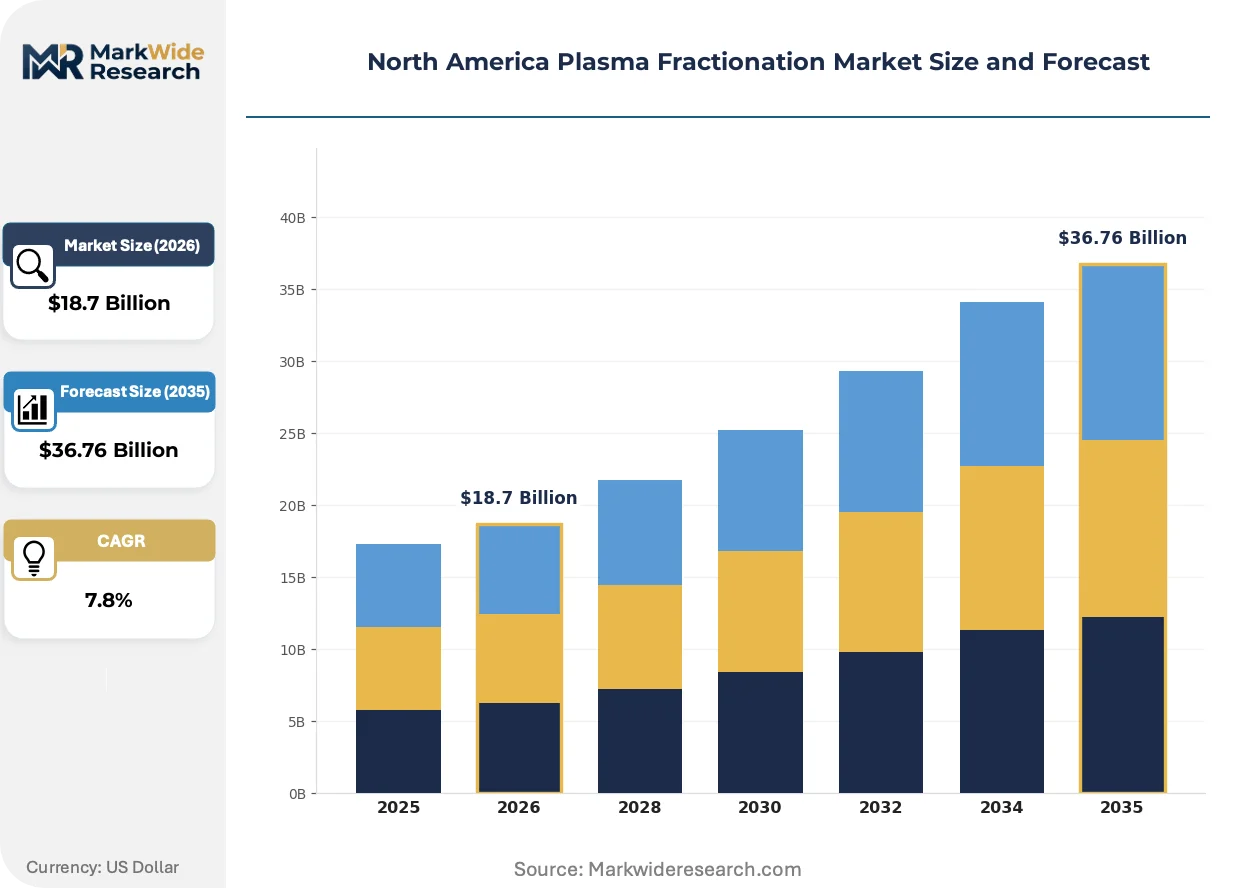
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $36.76 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunoglobulins, Albumin, Coagulation Factors, Protease Inhibitors Application: Neurology, Hematology, Immunology, Infectious Diseases End User: Hospitals, Clinics, Research Facilities, Blood Banks Technology: Chromatography, Filtration, Precipitation, Pasteurization |
| Companies Covered | Grifols, CSL Behring, Takeda Pharmaceutical Company Limited, Octapharma, Kedrion, Bio Products Laboratory, ADMA Biologics, Baxter, Bharat Serums and Vaccines Limited, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Plasma Fractionation Market Evolving Landscape
Pathogen reduction technologies and automated plasma processing platforms are compressing production timelines while tightening safety specifications. These advances are reshaping capital deployment priorities across North American fractionation facilities.
Continuous processing technology is converging with single-use bioreactor systems in plasma fractionation pilot programs. CSL Behring and Grifols are evaluating perfusion-based immunoglobulin capture at select U.S. manufacturing sites. This convergence is enabling smaller batch footprints and faster product release cycles without compromising viral safety margins.
Health Canada's Biologics and Genetic Therapies Directorate issued updated guidance on transfusion-transmitted disease screening in 2024. The directive mandates extended nucleic acid testing panels for West Nile virus and Babesia microti in Canadian-sourced plasma. U.S. fractionators with cross-border collection networks are harmonizing donor screening protocols to maintain dual-registered status.
Academic medical centers in the United States are consolidating immunoglobulin purchasing through group purchasing organizations and direct manufacturer agreements. Traditional wholesale distribution margins are compressing as IDNs negotiate price protection clauses and guaranteed supply allocations. This consolidation is most visible in the Northeast and Great Lakes hospital systems managing large neurology and hematology patient bases.
North America Plasma Fractionation Market Segmentation
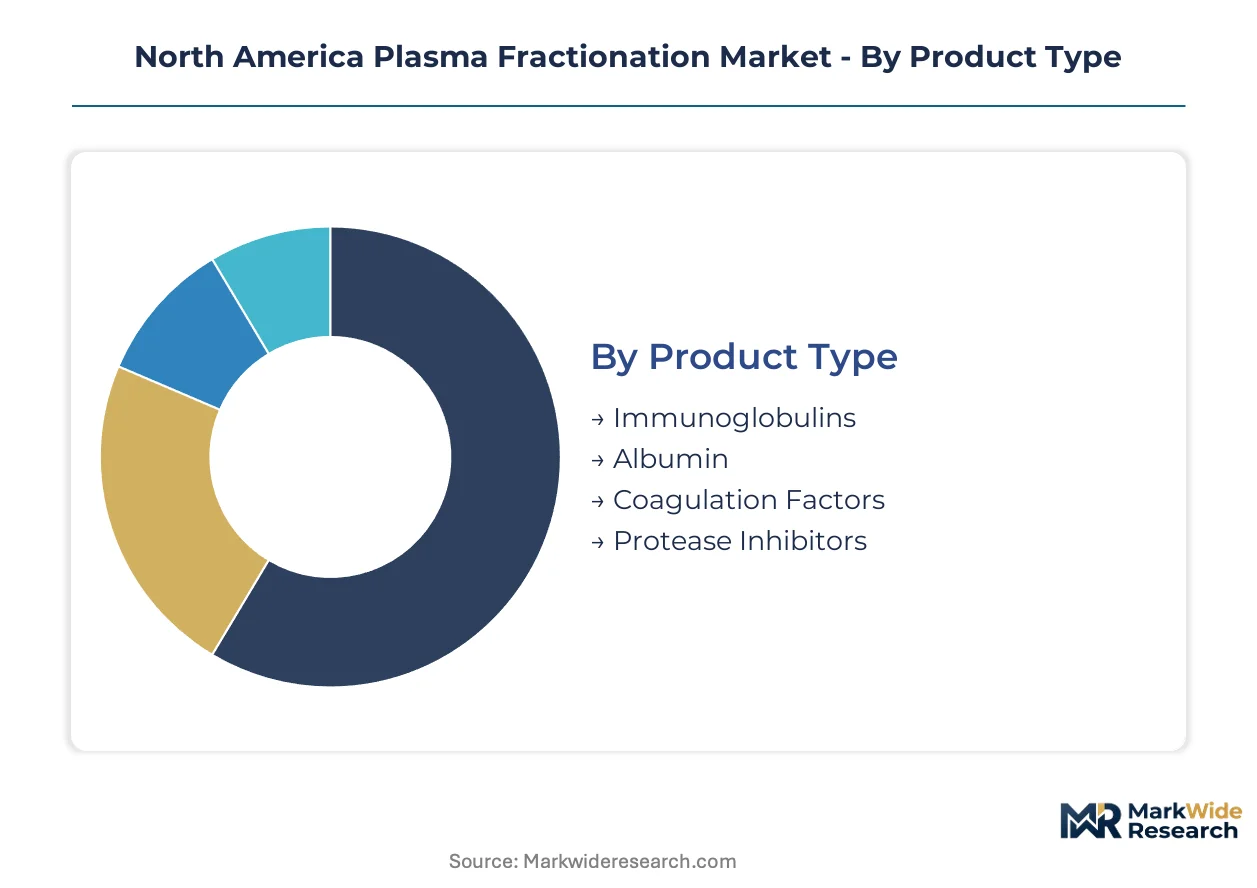
Plasma fractionation segments diverge sharply in regulatory burden and margin structure. FDA lot release protocols and Health Canada viral safety standards create tiered compliance costs that reshape competitive positioning across product categories and end-use channels.
Product Type:
FDA's updated pathogen reduction mandates and Health Canada Biologics and Genetic Therapies Directorate certification requirements fall unevenly across therapeutic protein categories, with immunoglobulin and albumin lots facing the most stringent validation thresholds.
- Immunoglobulins:Polyclonal antibody preparations derived from pooled plasma through cold ethanol fractionation and chromatographic purification. Academic medical centers in the U.S. Northeast and Great Lakes regions concentrate demand for IVIG and SCIG formulations driven by CIDP and multifocal motor neuropathy protocol expansion. FDA-certified pathogen-reduced lots now command formulary preference in integrated delivery network tenders.
- Albumin:Heat-stabilized plasma protein fraction with colloid osmotic pressure maintenance properties. Hospital utilization concentrates in surgical and critical care units across Ontario and the U.S. Midwest, though pricing pressure from synthetic colloid alternatives constrains margin expansion despite steady volume.
- Coagulation Factors:Plasma-derived FVIII and FIX concentrates for hemophilia management.
- Protease Inhibitors:Alpha-1 antitrypsin and C1 esterase inhibitor fractions for rare genetic conditions.
Leading the category by volume: Immunoglobulins. Expanding most quickly: Coagulation factors in Canadian academic centers despite recombinant substitution headwinds.
Application:
Clinical application segments map directly to prescriber specialty concentration and reimbursement pathway structure, with neurology and hematology anchoring hospital procurement consolidation.
- Neurology:IVIG and SCIG protocols for chronic inflammatory demyelinating polyneuropathy and multifocal motor neuropathy. U.S. Medicare reimbursement expansion for home-based SCIG self-administration is redirecting patient volumes from hospital infusion centers to specialty pharmacy networks.
- Hematology:Coagulation factor replacement for hemophilia A and B, plus albumin for plasma volume expansion. Pediatric treatment centers in Texas and California drive plasma-derived factor demand despite recombinant product guideline preference.
- Immunology:Primary and secondary immunodeficiency replacement therapy.
- Infectious Diseases:Hyperimmune globulin and passive immunization applications.
Neurology commands the largest revenue pool. Infectious diseases applications are climbing fastest on emerging pathogen-specific hyperimmune development.
End User:
Channel concentration reflects procurement scale economies and regulatory custody requirements, with hospital systems leveraging consolidated purchasing power against fragmented clinic and research demand.
- Hospitals:Integrated delivery networks and academic medical centers with centralized pharmacy and therapeutics committees. Group purchasing organization consolidation in the U.S. Northeast compresses vendor rosters to fractionators with captive plasma supply and guaranteed allocation contracts.
- Clinics:Outpatient infusion centers and specialty physician practices.
- Research Facilities:Academic and commercial investigators requiring GMP-grade plasma derivatives for protocol development.
- Blood Banks:Collection and processing centers with therapeutic plasma exchange programs.
Hospitals dominate procurement volume. Clinics are gaining share fastest on subcutaneous immunoglobulin home infusion migration.
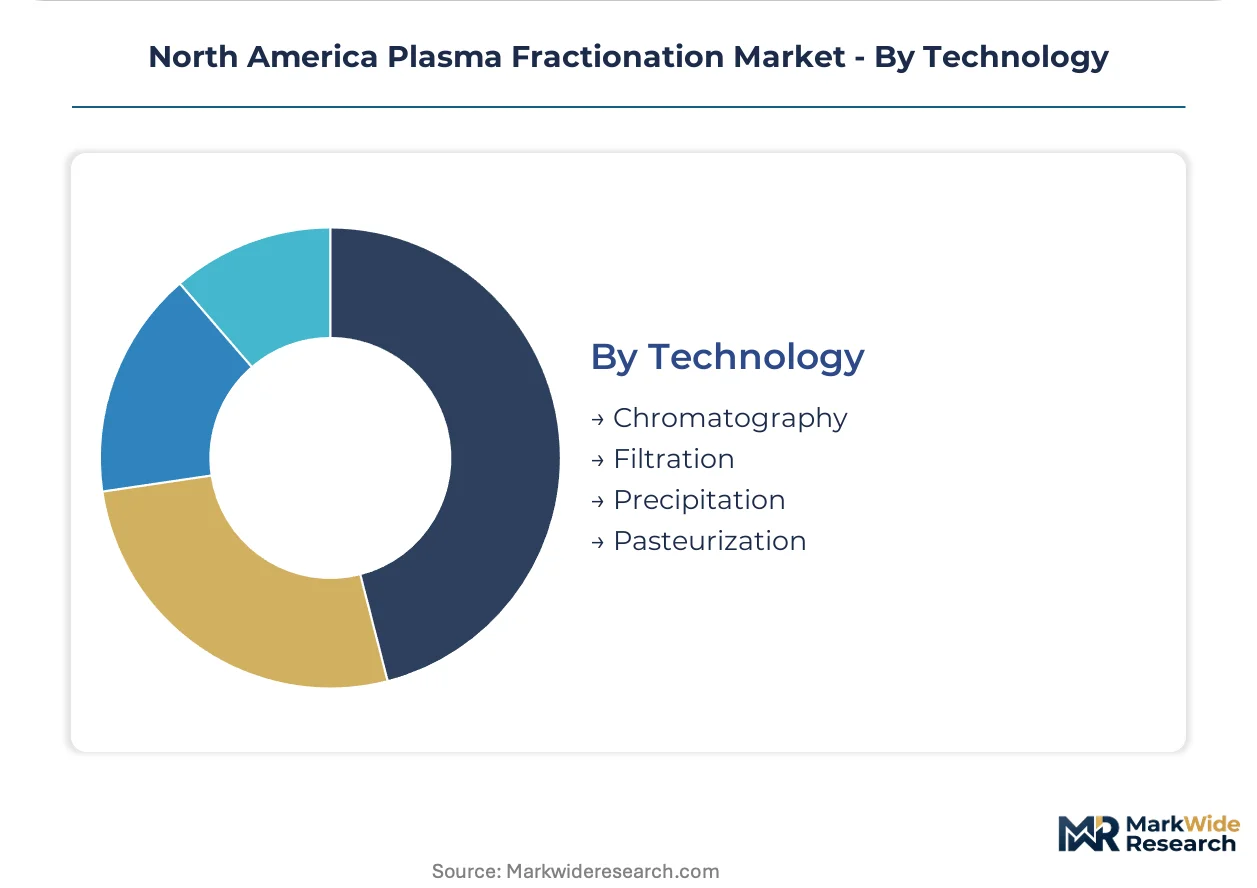
Technology:
Process technology segments align with capital intensity and viral safety validation burden, with integrated chromatography-nanofiltration platforms commanding premium positioning.
- Chromatography:Affinity and ion-exchange resin-based protein capture with defined purity specifications. CSL Behring and Grifols deployment of continuous perfusion chromatography at U.S. manufacturing sites is reducing batch footprints while maintaining FDA-mandated viral clearance margins.
- Filtration:Nanofiltration and ultrafiltration for viral particle removal and protein concentration. Southern Ontario fractionation facilities concentrate capacity for dual-registered U.S.-Canada product release.
- Precipitation:Cold ethanol fractionation, the foundational Cohn process methodology.
- Pasteurization:Heat treatment for viral inactivation in albumin and specific immunoglobulin formulations.
Chromatography leads installed capacity. Filtration is expanding fastest on pathogen reduction technology mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, where academic medical centers and integrated delivery networks manage complex immunodeficiency and hematology patient populations. Canada anchors secondary volume through Ontario-based fractionation capacity serving dual-registered U.S.-Canada supply chains. Mexico's emerging plasma collection infrastructure remains nascent compared to its northern neighbors.
United States
Hospital procurement consolidation across the Northeast and Great Lakes regions compresses vendor rosters to fractionators with captive plasma networks. FDA pathogen reduction mandates for solvent-detergent and nanofiltration steps accelerate facility upgrades at U.S. manufacturing plants. Academic medical centers in Boston and New York specify certified pathogen-reduced immunoglobulin lots in tender documents.
Canada
Canadian plasma collectors scale collection center networks to serve dual-registered fractionators under harmonized lot release protocols. Health Canada's Biologics and Genetic Therapies Directorate mandates extended nucleic acid testing panels for West Nile virus and Babesia microti in Canadian-sourced plasma. Southern Ontario fractionation facilities concentrate capacity for cross-border product release to U.S. health systems.
Mexico
Mexico's plasma collection infrastructure remains underdeveloped relative to therapeutic protein demand from its hospital sector. The country's national pharmaceutical regulator maintains alignment with FDA viral safety testing standards for imported plasma derivatives. Guadalajara and Mexico City house emerging distribution hubs for U.S.- and Canadian-sourced immunoglobulin and albumin products.
North America Plasma Fractionation Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized immunoglobulin formulations and regional supply agreements. The vendor base clusters around three dominant players with vertically integrated plasma collection networks, while mid-scale operators secure long-term supply contracts or exit hospital formulary access. Strategic archetypes include captive plasma suppliers, high-volume fractionators, and recombinant-focused portfolios. Competitive moves center on capacity expansion in pathogen-reduced production lines and strategic partnerships with integrated delivery networks.
Within the captive supply tier, CSL Behring and Grifols exemplify backward integration into plasma collection networks. CSL Behring leverages its U.S. center footprint to sustain supply security for major health systems. Grifols anchors positioning through high-volume fractionation capacity. Takeda Pharmaceutical Company Limited occupies a recombinant-portfolio position, competing on coagulation factor offerings across Canadian and U.S. academic medical centers.
| Leading Market Players |
|---|
| Grifols |
| CSL Behring |
| Takeda Pharmaceutical Company Limited |
| Octapharma |
| Kedrion |
| Bio Products Laboratory |
| ADMA Biologics |
| Baxter |
| Bharat Serums and Vaccines Limited |
| Others |
Value Network & Pricing Analysis
Continuous processing technology convergence with single-use bioreactor systems is compressing production timelines while concentrating capital deployment among fractionators with scale to absorb facility upgrade costs, tightening supply-side economics and reinforcing price premiums for certified pathogen-reduced lots.
Pricing Analysis
Volume concentrates in standard-grade immunoglobulin and albumin lots while margins concentrate in pathogen-reduced specialty formulations. Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified pathogen-reduced immunoglobulin from standard viral-inactivated grades and economy-positioned synthetic colloid alternatives. Cost compression in standard albumin is intensifying because synthetic colloid substitution in surgical protocols constrains hospital formulary pricing. Academic medical centers with consolidated procurement through group purchasing organizations exhibit highest price sensitivity; specialty home infusion providers capturing subcutaneous immunoglobulin migration show lowest sensitivity due to reimbursement pathway insulation.
Supply Chain Analysis
Reverse-logistics flows for returned plasma units and expired product lots require specialized cold-chain handling back to fractionation facilities for reprocessing or disposal, adding cost layers that concentrate among operators with integrated collection networks. Supply concentrates in the United States and Canada, with southern Ontario fractionation capacity serving dual-registered cross-border release. Raw material dependencies center on source plasma volumes, specialized chromatography resins, and nanofiltration membrane cassettes. Single-site production vulnerability in select U.S. metropolitan corridors creates continental shortage risk for specific immunoglobulin formulations. Distribution runs through integrated delivery network direct agreements and group purchasing organization channels, compressing traditional wholesale margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plasma collection input scarcity and fractionation capacity concentration prop pricing power for incumbent operators with captive supply networks, while collection center workforce gaps constrain expansion timelines across the analysis window.
For Market Incumbents: Acquire underutilized plasma collection center networks in the U.S. Southeast and Midwest to secure source volume ahead of competitor expansion. Lock in long-term supply allocation contracts with integrated delivery networks in the Northeast and Great Lakes regions before formulary consolidation completes. Recombinant coagulation factor substitution in pediatric hemophilia treatment and emerging mid-scale fractionators with regional supply agreements represent dual threats requiring defensive positioning through guaranteed supply clauses and pathogen-reduced certification investment. For New Entrants and Emerging Players: Specialty home infusion providers represent the most penetrable channel partner type for subcutaneous immunoglobulin distribution, bypassing hospital formulary barriers entirely. Target Canadian academic medical centers with novel plasma-derived therapies eligible for Health Canada priority review pathways, leveraging U.S. FDA approval packages to compress regulatory timeline risk. White-space opportunities sit in hyperimmune globulin development for emerging infectious disease indications and chromatography-nanofiltration convergence platforms reducing processing yield loss. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by incumbent fractionators seeking collection network density and regional manufacturing footprint. Long-term viability favors operators with backward integration into plasma collection and certified pathogen-reduced production capacity, as regulatory mandates harden compliance barriers. Acquisition target archetype: mid-scale fractionators with dual-registered U.S.-Canada status and underutilized southern Ontario capacity. Monitor FDA guidance on transfusion-transmitted infection screening expansion and pathogen reduction technology validation requirements as inflection indicators for compliance cost step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Collection Network Expansion | CSL Behring and Grifols center footprint growth secures source plasma volume for hospital system contracts. |
| Pathogen-Reduced Production Line Certification | FDA solvent-detergent and nanofiltration mandates position certified lots for formulary preference in academic medical center tenders. |
| Subcutaneous Immunoglobulin Home Infusion Partnership | Medicare reimbursement pathway expansion redirects patient volumes from hospital infusion to specialty pharmacy networks. |
| Dual-Registered U.S.-Canada Manufacturing Status | Health Canada harmonized lot release protocols reduce cross-border regulatory friction for Ontario-based fractionators. |
| Continuous Processing Technology Pilot Deployment | Perfusion-based immunoglobulin capture at select U.S. sites enables smaller batch footprints and faster release cycles. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews with plasma center operations directors, fractionation facility quality assurance leads, hospital pharmacy and therapeutics committee members, and group purchasing organization contract managers. FDA guidance documents, Health Canada Biologics and Genetic Therapies Directorate directives, OSHA bloodborne pathogen regulations, and state-level pharmacy compounding rules provided regulatory boundary conditions. Bottom-up patient population modeling and top-down fractionation capacity assessment enabled cross-validation of volume estimates.
Granularity-level modeling captured immunoglobulin, albumin, coagulation factor, and protease inhibitor product categories; neurology, hematology, immunology, and infectious disease applications; hospitals, clinics, research facilities, and blood bank end-user channels; and chromatography, filtration, precipitation, and pasteurization technology segments. CAGRs derived from segment-level volume trajectories and pricing dynamics across the analysis window, with specific inputs including CIDP and multifocal motor neuropathy patient prevalence, hemophilia A and B treatment guideline evolution, and plasma collection center expansion timelines.
Several conditions sit outside the modeled scope, including sudden FDA donor deferral policy shifts, state-level paid donor compensation legislative changes, and recombinant coagulation factor guideline acceleration beyond current pediatric preference trends. Forecasts reflect documented assumptions on collection center workforce availability, pathogen reduction technology validation timelines, and integrated delivery network procurement consolidation pace. Practitioners should monitor Health Canada nucleic acid testing panel expansion, DSCSA serialization compliance deadline adherence, and single-site production disruption events for early signals of supply constraint or pricing inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Bioequivalence Studies Market
Biopharmaceuticals
Atipamezole Market
Biopharmaceuticals
Global Biopharmaceuticals Contract Manufacturing Market
Biopharmaceuticals
Hemophilia B Market
Biopharmaceuticals
NF-KB Inhibitors Market
Biopharmaceuticals
Global Bovine Blood Plasma Derivatives Market
Biopharmaceuticals
Russia Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Global Diagnostic Specialty Antibodies Market
Biopharmaceuticals
Insulin Aspart Market
Biopharmaceuticals
Global Thrombin Market
Biopharmaceuticals
Neurodegenerative Diseases Drugs Market
Biopharmaceuticals
Global Biopharmaceuticals Market
Biopharmaceuticals
Discovery Bioanalysis Market
Biopharmaceuticals
Erythropoietin Drugs Market
Biopharmaceuticals
Lupus Nephritis Market
Biopharmaceuticals
Antibody Discovery Market