
 Logistics Packaging Market | 2026-2036
Logistics Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Logistics Packaging Market Outlook
Multi-source procurement toward integrated packaging-service partnerships is recalibrating how logistics operators manage total cost of ownership. Sealed Air leverages automation-enabled inflatable systems to reduce dimensional weight penalties for air freight shippers. DS Smith anchors European corrugated supply through recycled fiber networks and on-site box-making installations at customer distribution centers. Smurfit WestRock competes via containerboard mill integration and regional sheet-feeder density across North American freight corridors.
Logistics packaging encompasses engineered containment and unitization systems designed to protect goods through multimodal transit, distribution handling, and warehouse storage cycles, typically incorporating load-bearing specifications such as edge crush test ratings for corrugated or rack-load capacities for plastic pallets. Its primary purpose is to minimize product damage, optimize cube utilization in transport assets, and enable mechanized handling through standardized footprints. Pallets and stretch films command the largest volume positions, while reusable packaging systems capture expanding margin pools as closed-loop pool programs penetrate automotive and beverage supply chains. Corrugated paper leads material consumption by tonnage, though plastic crates and totes are displacing single-trip alternatives in grocery and pharmaceutical distribution where return logistics infrastructure exists.
The EPA promotes sustainable materials management priorities that influence packaging recovery and recycled content mandates for domestic shippers, while ISO 18600 series standards govern reusable transport item performance testing and interoperability across international trade lanes. FDA food contact regulations and EU REACH chemical restrictions further constrain material formulations for food and pharmaceutical logistics packaging applications. Stakeholders must monitor regulatory divergence between jurisdictions and assess whether regional material compliance investments align with customer supply base consolidation trends.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing material substitutions across European supply chains, compelling logistics operators to redesign load-bearing systems for fiber-based alternatives while maintaining performance specifications for automotive and pharmaceutical freight.
Growth Catalysts
- REACH chemical restrictions:EU regulatory pressure on plastic formulations accelerates investment in bio-based barrier coatings for corrugated applications in food logistics.
- E-commerce fulfillment networks:Parcel volume concentration in automated sortation hubs drives demand for dimensionally optimized box designs and machine-readable labeling standards.
- Returnable packaging systems:Closed-loop pool programs in German automotive supply chains demonstrate measurable total cost of ownership reductions versus single-trip alternatives.
Market Restraints
- Recycled fiber cost volatility:Old corrugated container price swings compress margins for integrated box producers dependent on post-consumer feedstock.
- Containerboard mill concentration:North American linerboard capacity clusters among a handful of producers, creating supply vulnerability during maintenance outages or force majeure events.
- Rack-load capacity limitations:Plastic pallet structural performance gaps in high-bay warehouse applications constrain substitution rates versus wooden alternatives in ambient storage.
Strategic Opportunities
- Indian pharmaceutical cold chain:Temperature-controlled packaging infrastructure gaps in domestic distribution create entry points for qualified passive thermal shippers.
- Digital watermark integration:Convergence of printed electronics with corrugated substrates enables item-level tracking without secondary label application.
- CSRD disclosure mandates:EU corporate sustainability reporting requirements create advisory service revenue streams around packaging carbon footprint quantification and reduction pathways.
Industry Challenges
- Automation engineering talent scarcity:Design of robotic palletizing cells for heterogeneous SKU mixes requires cross-functional expertise in mechanical handling and vision systems integration.
- ISO 18600 certification timelines:Reusable transport item performance testing protocols extend product development cycles for pool operators seeking interoperability across multinational retail networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Logistics Packaging Market |
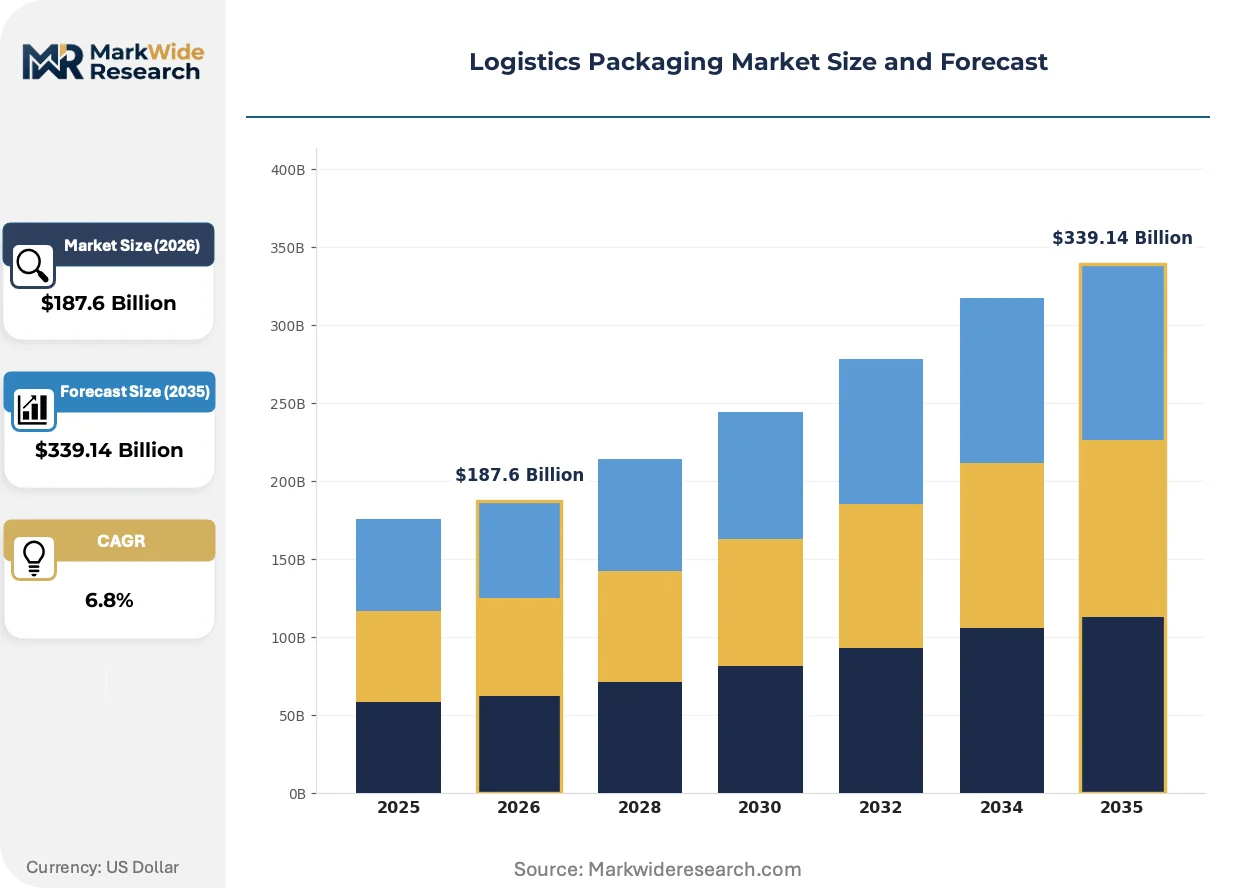
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $339.14 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pallets, Boxes, Crates, Stretch Films Material: Wood, Plastic, Corrugated Paper, Metal End User: Food & Beverage, Electronics, Pharmaceuticals, Retail Packaging Type: Reusable, Disposable, Bulk, Individual |
| Companies Covered | Packaging Corporation of America, Berry Global, International Paper Co., Sonoco, Crown Holdings, Smurfit WestRock, DS Smith, Sealed Air, WestRock, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
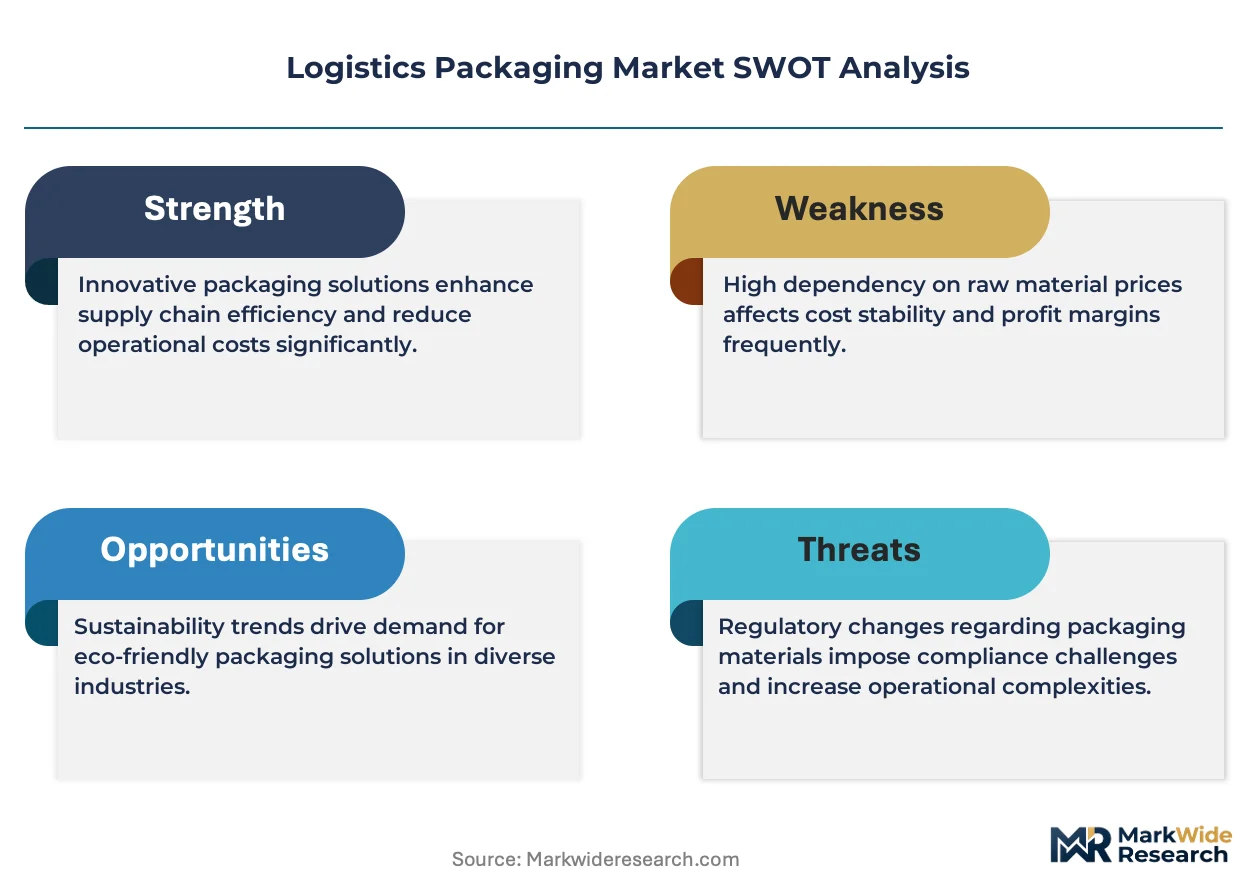
Logistics Packaging Market Strategic Shifts
Machine vision and adaptive robotics are compressing changeover times in packaging automation, while regulatory pressure on material circularity accelerates design-for-recovery engineering priorities across container formats.
Automated inflatable void-fill systems are automating protective packaging placement in high-velocity e-commerce fulfillment centers. Third-party logistics operators in North American parcel hubs deploy these systems to reduce dimensional weight charges for air freight shipments. The technology is automating labor out of the final packing station while improving cube utilization in outbound trailers.
EU Green Deal packaging waste reduction targets are mandating minimum recycled content thresholds for plastic transport items by 2030. German automotive suppliers face compliance timelines requiring rapid qualification of post-industrial polypropylene in returnable tote applications. The regulation is compressing virgin resin dependence in closed-loop pool systems serving assembly plants.
Integrated packaging-service partnerships are displacing transactional procurement of boxes and pallets as standalone commodities. Large retail distributors in France and the Netherlands now contract for cube-optimization consulting alongside physical container supply. The model concentrates vendor relationships among operators capable of delivering total cost reduction rather than unit price competition.
Logistics Packaging Market Segmentation
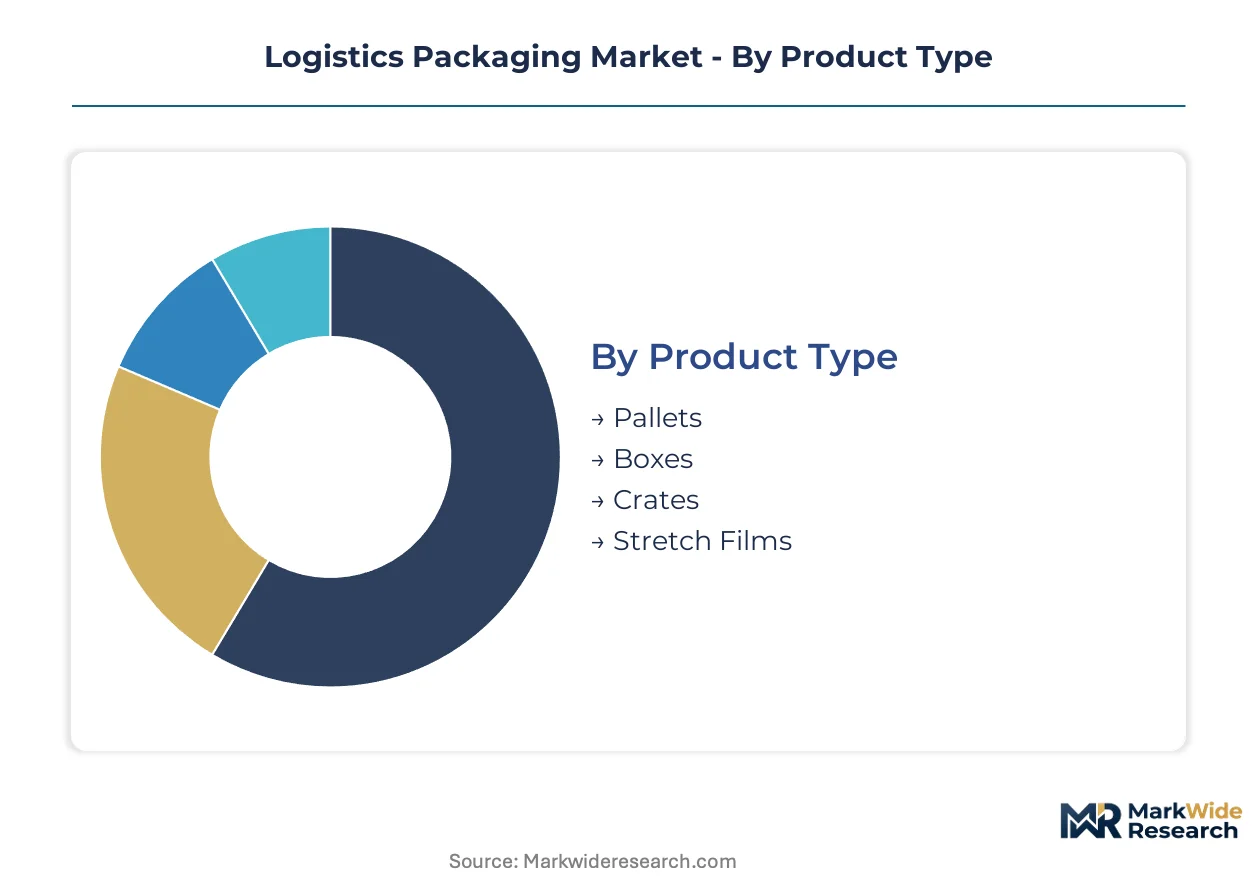
Logistics packaging segmentation reflects divergent performance requirements across transit modes and handling intensity. Material selection and reusability economics determine total cost of ownership for shippers operating multimodal networks.
Product Type:
Pallets and boxes command divergent volume positions, with pallets anchoring unitization economics while boxes capture e-commerce velocity premiums.
- Pallets:Wooden platforms dominate ambient freight corridors with standardized 48x40 inch footprints compatible with racking systems. Demand concentrates in German automotive assembly plants where rack-load capacity specifications exceed 2,000 kg for engine block transport.
- Boxes:Corrugated containers with edge crush test ratings above 32 ECT protect electronics through automated sortation hubs. Parcel volume concentration in North American fulfillment centers drives specification toward machine-readable labeling compatibility and dimensional optimization for trailer cube utilization.
- Crates:Rigid containment for pharmaceutical cold chain applications requiring validated thermal performance across domestic distribution legs.
- Stretch Films:Linear low-density polyethylene unitization for pallet load containment in high-velocity cross-dock operations.
Mature deployment sits with pallets. Newer deployment is concentrated in boxes engineered for automated handling.
Material:
Cost tiers separate commodity feedstocks from performance-engineered alternatives, with recycled fiber networks competing against virgin resin formulations on sustainability credentials.
- Corrugated Paper:Recycled fiber-based containers with flute profiles optimized for compression strength in stacked warehouse configurations. EU Packaging and Packaging Waste Regulation mandates accelerate substitution toward fiber-based alternatives in French retail distribution.
- Plastic:High-density polyethylene and polypropylene formulations for returnable tote applications in closed-loop pool programs. German automotive suppliers face compliance timelines requiring rapid qualification of post-industrial resin in assembly line feed systems.
- Wood:Hardwood and softwood pallet construction for single-trip export applications where ISPM-15 heat treatment certification satisfies phytosanitary requirements.
- Metal:Steel and aluminum rigid packaging for hazardous materials transport requiring UN certification and collapsible return logistics.
Corrugated paper captures the steepest expansion trajectory on regulatory tailwinds. Plastic maintains margin concentration in pool system contracts.
End User:
Application intensity varies by damage sensitivity and handling automation penetration, with pharmaceutical and electronics segments commanding specification premiums over commodity freight.
- Pharmaceuticals:Temperature-controlled packaging infrastructure with validated passive thermal shipper performance for domestic cold chain distribution. Indian market gaps create entry points for qualified container suppliers.
- Electronics:Electrostatic discharge protection and vibration damping specifications for semiconductor and consumer device transit through multimodal hubs.
- Food & Beverage:FDA food contact compliance and moisture barrier requirements for corrugated applications in grocery distribution networks.
- Retail:E-commerce fulfillment specifications prioritizing dimensional weight reduction and returns-ready container design.
Pharmaceuticals drive the fastest specification escalation. Retail captures volume concentration on parcel velocity.
Packaging Type:
Reusability economics determine procurement model selection, with closed-loop infrastructure availability constraining pool program penetration to dense freight corridors.
- Reusable:Returnable transport items governed by ISO 18600 performance testing protocols for interoperability across multinational retail networks. Extended product development cycles challenge pool operators seeking network density.
- Disposable:Single-trip containers for export applications where reverse logistics economics prohibit return freight.
- Bulk:Intermediate bulk containers and flexible intermediate bulk bags for chemical and agricultural commodity flow.
- Individual:Item-level protective packaging for high-value electronics and pharmaceutical unit doses.
Reusable systems concentrate in German automotive corridors. Disposable formats dominate export-oriented manufacturing clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recycled fiber networks in Germany anchor European corrugated supply chains. Containerboard mill integration shapes competitive positioning across North American freight corridors. Returnable packaging infrastructure concentrates in automotive assembly clusters.
United States
E-commerce fulfillment velocity and pharmaceutical cold chain expansion drive specification escalation. FDA food contact regulations constrain barrier coating formulations for grocery distribution. Chicago-Midwest automotive suppliers deploy automated palletizing cells for heterogeneous SKU mixes.
Germany
Automotive and pharmaceutical exporters require high-performance returnable packaging systems with rack-load capacities exceeding 2,000 kg. EU Packaging and Packaging Waste Regulation mandates accelerate fiber-based material substitutions. Stuttgart-Baden-Württemberg assembly plants source post-industrial polypropylene totes from closed-loop pool programs.
China
Domestic e-commerce parcel concentration and electronics export manufacturing shape container demand. MIIT standards govern reusable transport item interoperability across multimodal networks. Yangtze River Delta fulfillment hubs install machine-readable labeling systems for automated sortation.
India
Temperature-controlled pharmaceutical distribution gaps create infrastructure entry points for passive thermal shippers. CDSCO quality guidelines constrain cold chain packaging validation protocols. Maharashtra pharmaceutical clusters seek qualified container suppliers for domestic vaccine logistics.
France
Retail distributors contract for cube-optimization consulting alongside physical container procurement. EU Green Deal packaging waste reduction targets mandate minimum recycled content thresholds by 2030. Paris-Northern France logistics operators redesign load-bearing systems for fiber-based alternatives.
Logistics Packaging Market Competitive Environment
Capacity expansion dominates the current landscape as integrated producers add containerboard mill assets. The vendor base clusters around three tiers: multinational paperboard conglomerates with captive fiber networks, specialized pool operators managing returnable asset fleets, and regional fabricators serving dense freight corridors. Two strategic archetypes prevail: backward-integrated producers controlling recycled fiber feedstock, and service-integrated vendors combining physical supply with cube-optimization consulting. Geographic expansion and portfolio diversification represent the dominant competitive moves.
Among North American paperboard producers, Packaging Corporation of America and International Paper Co. exemplify scale-driven archetypes with mill network density. Sealed Air occupies a position within the automation-enabled protective packaging tier. DS Smith represents European corrugated integration through recycled fiber networks and on-site box-making installations.
| Leading Market Players |
|---|
| Packaging Corporation of America |
| Berry Global |
| International Paper Co. |
| Sonoco |
| Crown Holdings |
| Smurfit WestRock |
| DS Smith |
| Sealed Air |
| WestRock |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between ISO 18600-validated reusable systems and commodity single-trip containers manifests in both pricing premiums and supply chain network density. Buyers of qualified returnable packaging pay embedded service fees for pool management and reverse logistics infrastructure, while commodity corrugated procurement competes on unit cost and regional mill proximity.
Pricing Analysis
Service-bundling separates pool-operated reusable systems from unbundled commodity box procurement. Three-tier pricing structure across premium validated totes, standard-grade corrugated, and economy single-trip wood pallets reflects performance certification and reverse logistics inclusion. Cost compression in commodity corrugated intensifies because recycled fiber feedstock volatility squeezes integrated producer margins. Automotive assemblers demonstrate lowest price sensitivity given total cost of ownership focus, while export-oriented commodity shippers prioritize unit cost minimization.
Supply Chain Analysis
Freight cost differentials concentrate containerboard supply in Germany, the United States, and China where mill networks anchor regional corrugated production. Feedstock draws from post-consumer old corrugated container collection networks, virgin pulp imports, and post-industrial plastic resin recovery streams. Single-source vulnerability sits with North American linerboard capacity concentration among limited producers. Distribution runs through integrated sheet-feeder networks and on-site box-making installations at major customer distribution centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Machine vision-enabled robotic palletizing is displacing manual handling configurations in high-velocity fulfillment networks, compressing changeover times and labor content simultaneously.
For Market Incumbents: Anticipate margin compression from automated inflatable void-fill systems by securing backward integration into recycled fiber networks and expanding on-site box-making service contracts. Capacity addition in German automotive corridors defends pool system relationships against emerging regional operators. ISO 18600 certification investment preserves interoperability premiums in multinational retail networks. For New Entrants and Emerging Players: Digital watermark integration offers technology-first entry into corrugated tracking applications without secondary label infrastructure. White-space concentration sits with Indian pharmaceutical cold chain packaging where qualified passive thermal shipper supply gaps persist. Go-to-market positioning through CDSCO validation partnerships accelerates domestic vaccine logistics qualification. For Investors and Strategic Acquirers: Re-rating potential sits with specialized pool operators given EU Green Deal packaging waste reduction mandates accelerating returnable system adoption. Long-term viability favors asset-light service-integrated vendors over commodity container producers facing fiber cost volatility. Monitor post-industrial polypropylene qualification timelines at German automotive suppliers as inflection signal for pool program expansion rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Fiber Networks | DS Smith and Smurfit WestRock control post-consumer feedstock flows through captive collection infrastructure. |
| On-Site Box-Making Installation Expansion | Proximity production at customer distribution centers reduces freight cost and improves order responsiveness. |
| ISO 18600 Certification Investment | Pool operators achieve interoperability across multinational retail networks through standardized performance testing. |
| Digital Watermark Technology Integration | Printed electronics convergence enables item-level tracking without secondary label application labor. |
| Post-Industrial Polypropylene Qualification | German automotive suppliers meet EU Green Deal recycled content mandates in closed-loop tote applications. |
Study Parameters
Independent corroboration across packaging procurement directors, pool operations managers, and corrugated mill technical leads underwrites the qualitative findings. Primary interviews with logistics executives at German automotive assemblers, French retail distributors, and North American e-commerce fulfillment operators combined with secondary validation from EPA sustainable materials management disclosures, EU Packaging and Packaging Waste Regulation filings, and SEC 10-K containerboard producer reports. Bottom-up demand modeling and top-down supply capacity assessment triangulate volume estimates.
Comparable-period anchoring to historical containerboard consumption and returnable asset fleet deployment patterns structured the projection framework. Segmentation modeling across material type, reusability format, end-use intensity, and regional regulatory cluster dimensions generated discrete growth trajectories. CAGR derivation incorporated recycled fiber price elasticity, automation penetration rates, and pool network density thresholds specific to closed-loop logistics infrastructure.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt recycled fiber cost spikes or accelerated EU packaging waste enforcement timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Cooler Box Market
Packaging Containers
Middle East and Africa Aerosol Cans Market
Packaging Containers
Insulated Food Containers Market
Packaging Containers
Acrylic Boxes Market
Packaging Containers
Packing Boxes Market
Packaging Containers
Africa Flexitank Market
Packaging Containers
Pillow Pack Packaging Market
Packaging Containers
Assembly Trays Market
Packaging Containers
Sanitizer Bottles Market
Packaging Containers
Latin America Aerosol Cans Market
Packaging Containers
Trigger Spray Bottle Market
Packaging Containers
Wrist Watch Packaging Market
Packaging Containers
Foldable Mailer Box Market
Packaging Containers
Bottles Market
Packaging Containers
Telescope Box Market
Packaging Containers
Insulated Storage Vessel Market