
 Laser Displacement Sensor Market | 2026-2036
Laser Displacement Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Displacement Sensor Market Outlook
Modular sensor bundling with software analytics suites is expanding buyer choice beyond standalone hardware. KEYENCE Corporation leverages its direct sales model to control channel access across Japanese and North American factory floors. SICK AG anchors its position through deep specialization in industrial safety-integrated measurement systems. Panasonic Corporation competes by extending its component ecosystem into semiconductor and battery manufacturing lines.
A laser displacement sensor emits a focused beam and calculates target distance via triangulation, confocal chromatic aberration, or time-of-flight principles, achieving sub-micron resolution for dimensional metrology. Non-contact variants dominate high-speed production environments where mechanical probe wear would corrupt repeatability. Laser triangulation technology occupies the largest installed base, while confocal sensors capture premium margin pools in semiconductor wafer inspection. Automotive end users sustain the heaviest volume demand, though quality control applications across packaging lines are registering the fastest uptake as traceability mandates tighten.
FDA calibration traceability requirements shape biomedical device manufacturing sensor selection in the United States, while REACH substance restrictions and CE marking obligations govern European product compliance. Japan's METI energy efficiency directives and China's GB standards for intelligent manufacturing are accelerating replacement of legacy contact probes with laser-based systems. Stakeholders must weigh R&D allocation between higher-resolution confocal platforms and cost-optimized triangulation units as factory automation procurement criteria diverge across regional certification regimes.
Market Dynamics
Automotive quality control lines in Germany, Japan, and the United States are replacing mechanical contact probes with non-contact laser systems to meet tightening ISO calibration requirements and traceability mandates. This hardware replacement cycle is compressing sensor lifecycles and reshaping procurement patterns across precision manufacturing clusters.
Growth Catalysts
- MIIT dual carbon goals:China's Ministry of Industry and Information Technology mandates energy efficiency improvements that accelerate laser sensor deployment in intelligent manufacturing lines, displacing legacy contact measurement systems.
- Semiconductor wafer inspection:Confocal chromatic aberration sensors capture premium positioning in sub-micron dimensional metrology as East Asian electronics clusters expand advanced packaging capacity.
- ISO calibration tightening:Precision manufacturing facilities across German automotive supplier networks face mandatory recertification cycles that drive replacement demand for traceable non-contact measurement hardware.
Market Restraints
- Optical component supply concentration:High-precision laser diodes and specialized optics concentrate among Japanese and German component suppliers, creating input bottlenecks during demand surges.
- Confocal cost premium:Confocal chromatic technology requires specialized optical assemblies that maintain 3-4x cost multiples over triangulation equivalents, limiting penetration in cost-sensitive packaging applications.
- REACH substance restrictions:ECHA regulations on hazardous substances in electronics complicate material selection for sensor housings and optical coatings destined for European industrial markets.
Strategic Opportunities
- Battery manufacturing expansion:Lithium-ion cell production lines in China and South Korea require in-line thickness monitoring for electrode coatings, creating dedicated demand for high-speed triangulation sensors.
- Software-analytics bundling:Modular packaging of displacement sensors with edge-computing analytics suites opens recurring revenue streams beyond standalone hardware sales to system integrators.
- FDA traceability mandates:Biomedical device manufacturers in the United States face calibration documentation requirements that favor laser-based dimensional verification over mechanical alternatives.
Industry Challenges
- Optomechanical engineering scarcity:Design and calibration of sub-micron resolution sensors requires specialized expertise in laser physics and precision alignment that concentrates among aging specialist workforces in Stuttgart and Osaka.
- Multi-protocol integration complexity:Factory automation buyers demand seamless communication across EtherCAT, Profinet, and OPC-UA networks, forcing sensor vendors to maintain parallel firmware development tracks.
- CE-MDR dual certification timelines:European market entry requires synchronized compliance with machinery directives and measurement instrument regulations, extending product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Displacement Sensor Market |
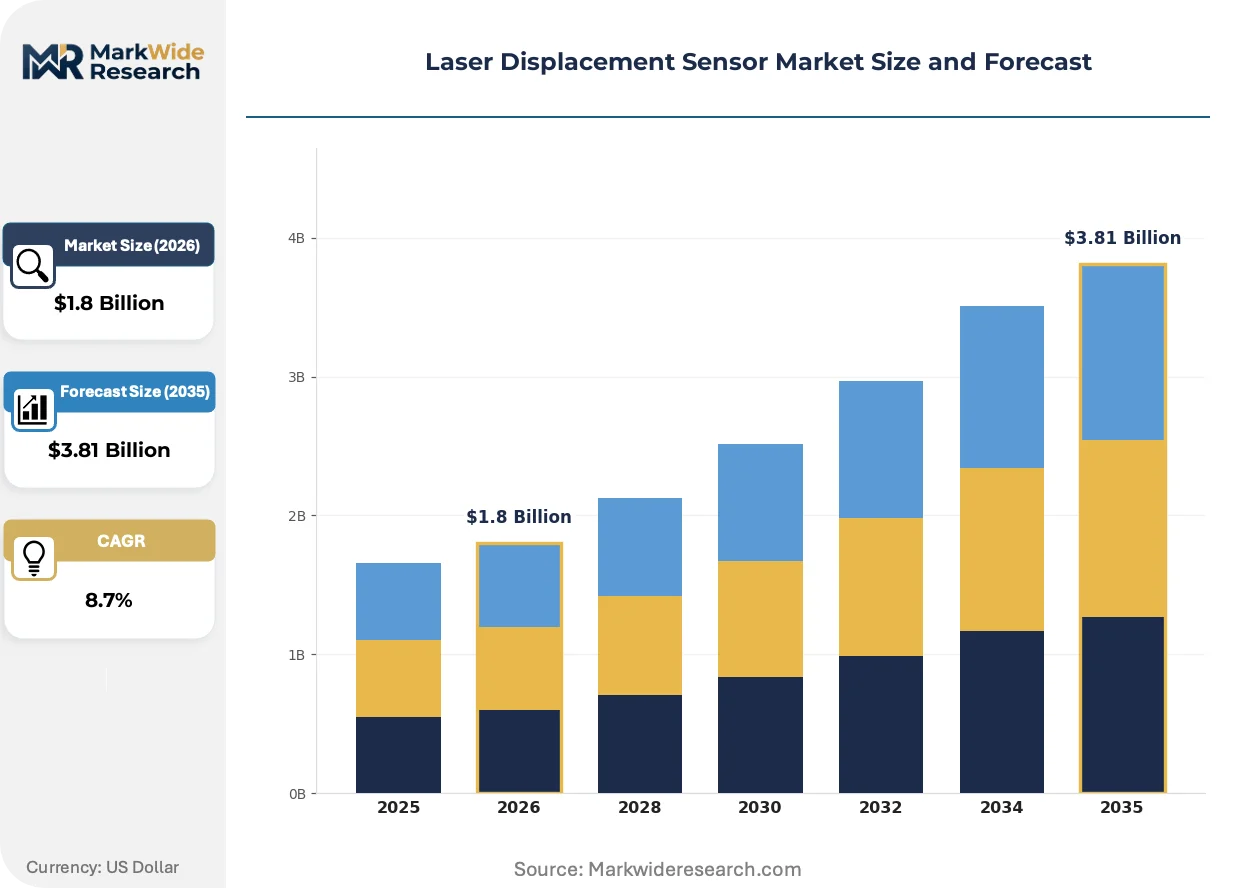
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contact Sensors, Non-Contact Sensors, 2D Sensors, 3D Sensors End User: Aerospace, Automotive, Consumer Electronics, Packaging Technology: Optical Sensors, Laser Triangulation, Confocal Sensors, Time-of-Flight Application: Position Measurement, Thickness Measurement, Profile Measurement, Quality Control |
| Companies Covered | KEYENCE Corporation, SICK AG, Panasonic Corporation, Micro-Epsilon, OMRON Corporation, TURCK GmbH & Co. KG, Cognex Corporation, Banner Engineering Corp., Schmitt Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Displacement Sensor Market Strategic Shifts
Sensor vendors are converging hardware miniaturization with embedded edge-processing capabilities to enable real-time dimensional feedback without external controller dependency. This integration is compressing system architectures and displacing traditional multi-component measurement chains.
Confocal chromatic displacement sensors are consolidating their position in semiconductor front-end manufacturing through single-head multi-layer thickness measurement capabilities. Taiwan-based foundries and memory manufacturers are adopting these systems at accelerated rates to support 3D NAND and advanced packaging architectures. The technology is consolidating supplier margins by capturing value previously distributed across separate film thickness and topography tools.
Japan's METI energy efficiency directives are mandating power consumption reductions in factory automation equipment that favor solid-state laser sources over legacy gas laser systems. Industrial sensor vendors are redesigning optical engines to meet these standby power thresholds. Japanese automotive component suppliers are responding by specifying METI-compliant hardware in new equipment purchase orders.
Buyer preference is migrating toward subscription-structured sensor analytics platforms that unbundle hardware acquisition from software feature access. German automotive tier-one suppliers are piloting per-inspection pricing models that replace capital expenditure with operational expenditure classification. This shift is most visible in Bavaria and Baden-Württemberg production networks where procurement departments face working capital constraints.
Laser Displacement Sensor Market Segmentation
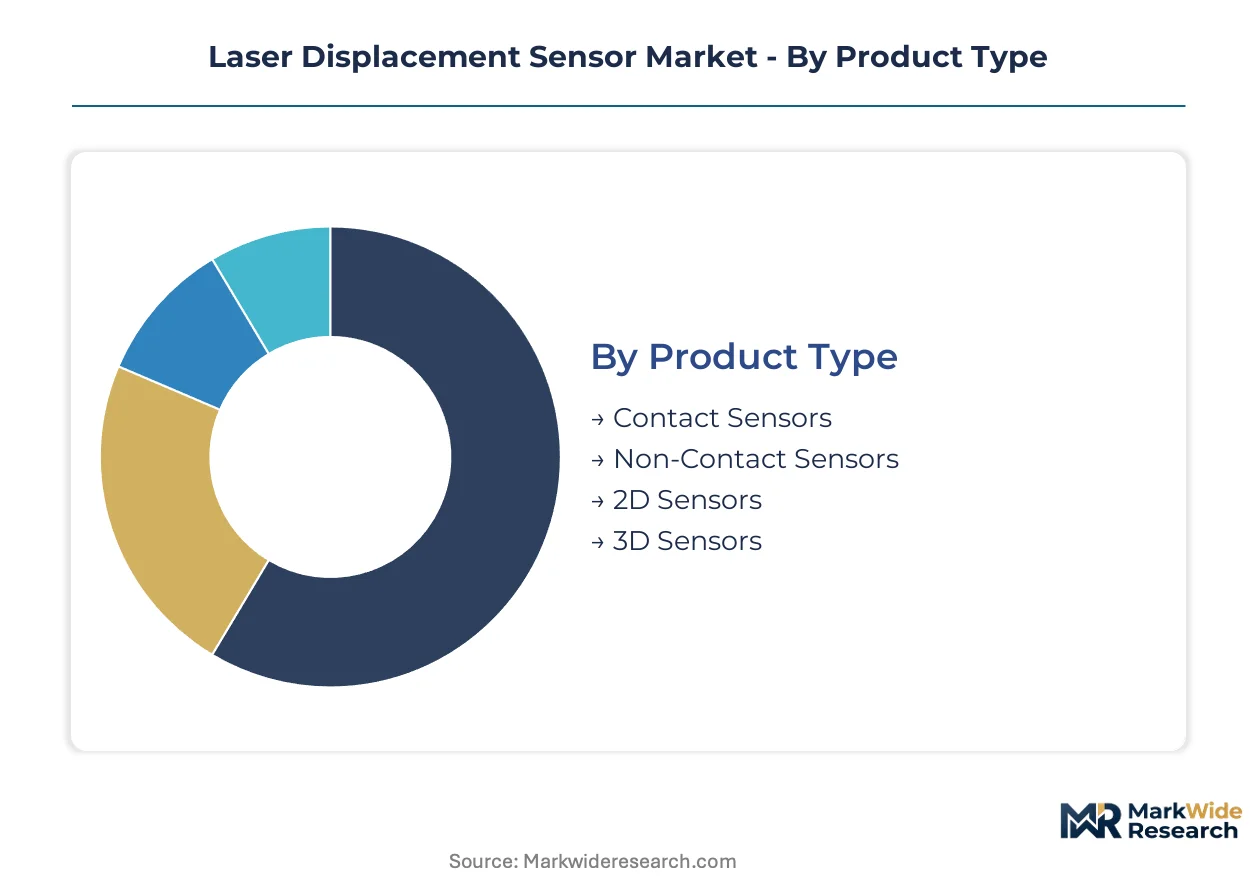
Segmentation in the laser displacement sensor market reveals how certification requirements, performance specifications, and end-use environments shape procurement decisions across precision manufacturing clusters. Understanding these divisions exposes where margin concentrates and where volume scales.
Product Type:
CE marking and ISO calibration traceability requirements vary sharply across product categories, with non-contact variants facing stricter electromagnetic compatibility testing than contact equivalents while 3D sensors trigger additional machinery directive compliance layers.
- Contact Sensors:Mechanical probe systems with physical stylus engagement remain specified for heavy-duty gauging in legacy automotive stamping lines where surface toughness exceeds optical penetration limits. German tool-and-die manufacturers in Stuttgart and Wolfsburg maintain these systems for forged component verification despite accelerating replacement with laser alternatives.
- Non-Contact Sensors:Laser-based measurement without mechanical contact dominates high-speed production environments where probe wear would corrupt repeatability. Japanese automotive tier-one suppliers specify these systems for in-line cylinder head dimensional verification to meet JIS calibration standards and METI energy efficiency directives.
- 2D Sensors:Single-plane displacement capture serves cost-optimized packaging line applications where profile complexity remains limited.
- 3D Sensors:Multi-axis volumetric measurement commands premium positioning in semiconductor advanced packaging inspection.
Leading the category by volume: Non-Contact Sensors. Growing fastest: 3D Sensors.
End User:
Cost tier stratification separates aerospace qualification-heavy procurement from high-volume automotive standardization and price-sensitive packaging deployments.
- Aerospace:FAA traceability mandates and AS9100 quality system requirements govern sensor selection for airframe component dimensional verification. Boeing suppliers in Washington state and Airbus subcontractors in Toulouse specify laser triangulation systems with full calibration documentation chains.
- Automotive:ISO calibration tightening across German, Japanese, and US production networks drives the heaviest absolute demand volume. Volkswagen Group's Wolfsburg and Chattanooga plants specify non-contact sensors for powertrain assembly verification to meet IATF certification cycles.
- Consumer Electronics:East Asian contract manufacturers in Shenzhen and Taipei deploy confocal sensors for smartphone camera module assembly.
- Packaging:High-speed line integration favors compact triangulation units with EtherCAT connectivity for traceability compliance.
Automotive dominates absolute volume. Packaging applications expand most quickly as traceability mandates tighten across food and pharmaceutical sectors.
Technology:
Application environment dictates technology selection, with sub-micron semiconductor inspection demanding confocal chromatic platforms while high-speed battery coating lines prioritize triangulation throughput.
- Laser Triangulation:Angle-based distance calculation through reflected beam position sensing occupies the largest installed base across industrial automation. Chinese battery manufacturers in Ningde and Shenzhen specify these systems for lithium-ion electrode thickness monitoring to meet MIIT intelligent manufacturing standards.
- Confocal Sensors:Chromatic aberration-based multi-layer thickness measurement captures premium margins in semiconductor wafer inspection. Taiwan Semiconductor Manufacturing Company and Samsung Electronics deploy these systems for 3D NAND and advanced packaging metrology.
- Optical Sensors:Broad category encompassing non-laser photoelectric displacement measurement serves general factory automation.
- Time-of-Flight:Pulse transit measurement suits long-range industrial positioning where sub-micron resolution is unnecessary.
Triangulation leads installed base. Confocal platforms command steepest expansion trajectory in electronics manufacturing.
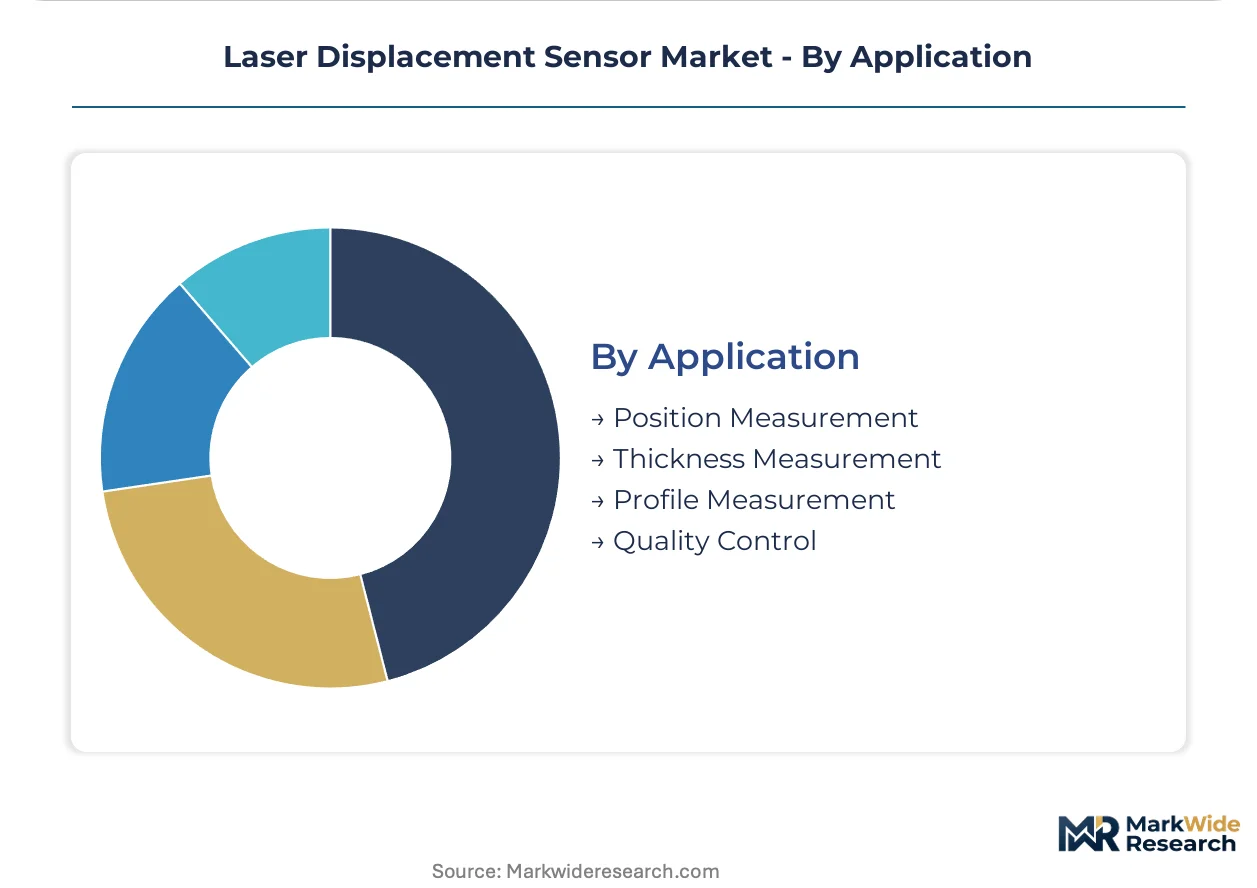
Application:
Customer type stratification separates capital-equipment OEM specifications from end-user quality department procurement with diverging software bundling preferences.
- Quality Control:In-line dimensional verification with statistical process control integration represents the fastest-expanding application category. German automotive suppliers in Bavaria pilot subscription-structured analytics platforms that unbundle hardware from software access.
- Thickness Measurement:Single-point or scanning film and coating thickness monitoring concentrates in battery and semiconductor production lines. South Korean battery manufacturers in Gwangju and Ulsan specify high-speed triangulation for electrode coating verification.
- Position Measurement:Real-time displacement feedback for closed-loop machine control serves general automation.
- Profile Measurement:Continuous surface contour capture supports tire manufacturing and rolled metal inspection.
Quality Control leads category growth. Thickness Measurement scales fastest in East Asian battery and electronics clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate battery and electronics manufacturing, pulling sensor procurement toward high-volume triangulation platforms. Germany's Industrie 4.0 tax incentives anchor European demand for precision metrology hardware. Japanese METI subsidies for energy-efficient factory equipment reshape replacement cycles across East Asian supplier networks.
China
MIIT dual carbon mandates accelerate laser sensor deployment in Ningde and Shenzhen battery production corridors. GB standards for intelligent manufacturing tighten calibration requirements for electrode thickness monitoring systems. CATL and BYD supplier networks in Fujian and Guangdong provinces specify high-speed triangulation units for lithium-ion coating verification.
Germany
Automotive quality control lines in Wolfsburg and Stuttgart replace mechanical probes with non-contact systems. CE marking and machinery directive compliance extend product launch timelines for sensor vendors serving Bavarian tier-one suppliers. Baden-Württemberg production networks pilot subscription-structured analytics platforms to bypass capital expenditure constraints.
Japan
METI energy efficiency directives mandate standby power reductions that favor solid-state laser sources over legacy gas systems. JIS calibration standards govern sensor selection for Toyota and Honda component suppliers in Aichi prefecture. Osaka-based precision optics clusters face aging specialist workforce constraints in sub-micron alignment engineering.
United States
FDA calibration traceability requirements shape biomedical device manufacturing sensor selection in Minnesota and Massachusetts medical device corridors. FAA mandates govern laser triangulation systems for Boeing suppliers in Washington state. Chattanooga automotive plants specify non-contact sensors for powertrain assembly verification under IATF certification cycles.
South Korea
Battery manufacturers in Gwangju and Ulsan deploy high-speed triangulation for electrode coating thickness verification. MFDS medical device regulations extend to metrology equipment used in pharmaceutical packaging lines. Samsung Electronics and SK Innovation supplier networks in Gyeonggi province drive confocal sensor demand for semiconductor advanced packaging.
Laser Displacement Sensor Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base stratifies between full-line factory automation suppliers and dedicated measurement technology developers. Three archetypes dominate: component ecosystem extenders, direct-sales channel controllers, and safety-integrated measurement specialists. Competitive moves concentrate on software-analytics bundling and edge-computing integration to displace traditional multi-component measurement chains.
Within the direct-sales archetype, KEYENCE Corporation exemplifies channel control strategies across Japanese and North American factory floors. SICK AG anchors the safety-integrated measurement tier through deep specialization in industrial systems combining dimensional metrology with functional safety compliance. Panasonic Corporation represents the component ecosystem extension model, leveraging semiconductor and battery manufacturing line relationships to position displacement sensors within broader automation portfolios.
| Leading Market Players |
|---|
| KEYENCE Corporation |
| SICK AG |
| Panasonic Corporation |
| Micro-Epsilon |
| OMRON Corporation |
| TURCK GmbH & Co. KG |
| Cognex Corporation |
| Banner Engineering Corp. |
| Schmitt Industries |
| Others |
Value Chain & Pricing Dynamics
German automotive tier-one suppliers concentrate procurement authority in Bavaria and Baden-Württemberg production networks, anchoring contract-based long-term offtake pricing with subscription-structured analytics bundling displacing standalone hardware transactions.
Pricing Analysis
Short lead-time premiums command 15-25% markups over standard delivery schedules as Japanese and German optical component bottlenecks extend procurement cycles. Three-tier pricing structure across premium confocal, standard triangulation, and economy optical sensor levels separates ISO-certified calibration tiers from uncertified alternatives. Cost compression in economy triangulation units intensifies because Chinese battery manufacturers negotiate volume-scale discounts for electrode coating lines. Packaging line integrators exhibit highest price sensitivity, while semiconductor wafer inspection buyers prioritize sub-micron resolution over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Volkswagen Group and CATL, while distributor networks serve mid-tier system integrators across European packaging corridors. High-precision laser diodes and specialized optics concentrate among Japanese and German component suppliers, with raw material dependencies spanning gallium arsenide substrates, precision aspheric lenses, and rare-earth doped optical coatings. Single-source vulnerability in confocal chromatic objective manufacturing creates supply risk during East Asian electronics demand surges. Distribution runs through factory automation specialists and measurement technology distributors with embedded calibration service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where ISO calibration traceability requirements and CE-MDR dual certification timelines erect barrier-to-entry moats favoring incumbents with established regulatory documentation infrastructure.
For Market Incumbents: Cement channel control through exclusive calibration service contracts with German automotive supplier networks, while deepening backward integration into precision optical component manufacturing to offset Japanese supply bottlenecks. Confocal sensor margin erosion from Chinese triangulation alternatives demands defensive patent portfolio expansion in multi-layer thickness measurement algorithms. For New Entrants and Emerging Players: Cloud-based sensor analytics platforms bypass capital expenditure constraints among Bavarian tier-one suppliers facing working capital limitations. Battery manufacturing thickness monitoring in South Korean and Chinese production corridors offers the most penetrable white-space, with FDA traceability mandates in Minnesota biomedical device corridors providing a secondary entry vector through calibration documentation differentiation. For Investors and Strategic Acquirers: The window for entry favors pure-play confocal specialists with semiconductor front-end relationships and aging optomechanical engineering workforces in Stuttgart or Osaka. Acquisition targets should demonstrate captive calibration laboratory infrastructure and METI energy efficiency compliance certification. Watch for MIIT intelligent manufacturing subsidy expansion as inflection signal for Chinese demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Optics | Captive supply of laser diodes from Osaka and Stuttgart clusters reduces lead-time vulnerability. |
| Software-Analytics Bundling | Subscription platforms with edge-computing capabilities displace standalone hardware at Volkswagen supplier networks. |
| CE-MDR Dual Certification Investment | Synchronized machinery directive and measurement instrument compliance extends moat against unqualified competitors. |
| Battery Manufacturing Line Partnership | Electrode coating verification specifications at CATL and BYD anchor high-volume triangulation demand. |
| Confocal Chromatic R&D Expansion | Multi-layer thickness measurement patents consolidate value capture in Taiwan Semiconductor advanced packaging. |
Study Parameters
Multi-period observation of sensor procurement patterns, replacement cycle compression, and certification mandate diffusion anchored the trend analysis, supplemented by interviews with precision metrology product managers, automotive quality control directors, semiconductor process engineers, and factory automation procurement leads. Secondary validation drew from ISO calibration registry data, MIIT intelligent manufacturing subsidy disclosures, METI energy efficiency directive filings, and SEC 10-K equipment supplier disclosures. Bottom-up triangulation across end-user demand segments converged with top-down supply-side capacity assessments.
Input-output matrices modeled unit shipments and average selling prices across product type, technology platform, end-use vertical, and regional certification cluster dimensions over the projection horizon. CAGRs derived from segment-level growth rate synthesis weighted by base-year revenue contribution. Industry-specific forecast inputs encompassed semiconductor wafer fab capacity expansion timelines and automotive powertrain electrification sensor content trajectories.
The model holds under stable regulatory enforcement intensity and continuous optical component supply availability; deviation in tariff escalation or rare-earth export restrictions would shift volume and value outputs. Forecasts reflect documented assumptions regarding MIIT subsidy continuity and ISO recertification cycle timing. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Europe Digital Thermometer Market
Sensors and Controls
Odor Sensor Market
Sensors and Controls
Factory Automation Sensor Market
Sensors and Controls
3D Profile Sensors Market
Sensors and Controls
Manifold Absolute Pressure Sensor Market
Sensors and Controls
Europe Touch Sensor Market
Sensors and Controls
Automotive MEMS Sensor Market
Sensors and Controls
Digital Humidity Sensor Market
Sensors and Controls
RET Controller Market
Sensors and Controls
Wind Vane Sensor Market
Sensors and Controls
Earthquake Sensor Market
Sensors and Controls
Door Control Modules Market
Sensors and Controls
Semiconductor Sensor Market
Sensors and Controls
Refrigeration Gauge Market
Sensors and Controls
Rangefinder Market
Sensors and Controls
Wearable Temperature Sensors Market