
 India Packaged Food Products Market | 2026-2036
India Packaged Food Products Market Size, Share, and Industry Trends Forecast 2026-2036
India Packaged Food Products Market Insights
Maharashtra is fragmenting as new processing capacity comes online near Mumbai-Pune logistics corridors. Nestlé India leverages its dairy and nutrition R&D infrastructure to sustain premium positioning in infant cereals and noodles. Britannia Industries anchors its competitive stance through deep distribution into tier-two towns and rural stockists. Patanjali Foods differentiates via Ayurveda-positioned portfolios that compete on wellness claims rather than price alone.
Packaged food products encompass shelf-stable and refrigerated consumables processed under controlled conditions with specified moisture content, pH levels, and preservative thresholds to ensure safety and extended viability. These items serve commercial purposes ranging from household convenience to institutional catering supply chains. Frozen foods and ready-to-eat meals capture expanding margin pools as urban time-scarcity intensifies, while snacks dominate volume throughput through kirana and modern trade overlap. Tetra packs and pouches displace rigid formats in liquid and semi-liquid categories, driven by cost efficiency and shelf-visibility advantages.
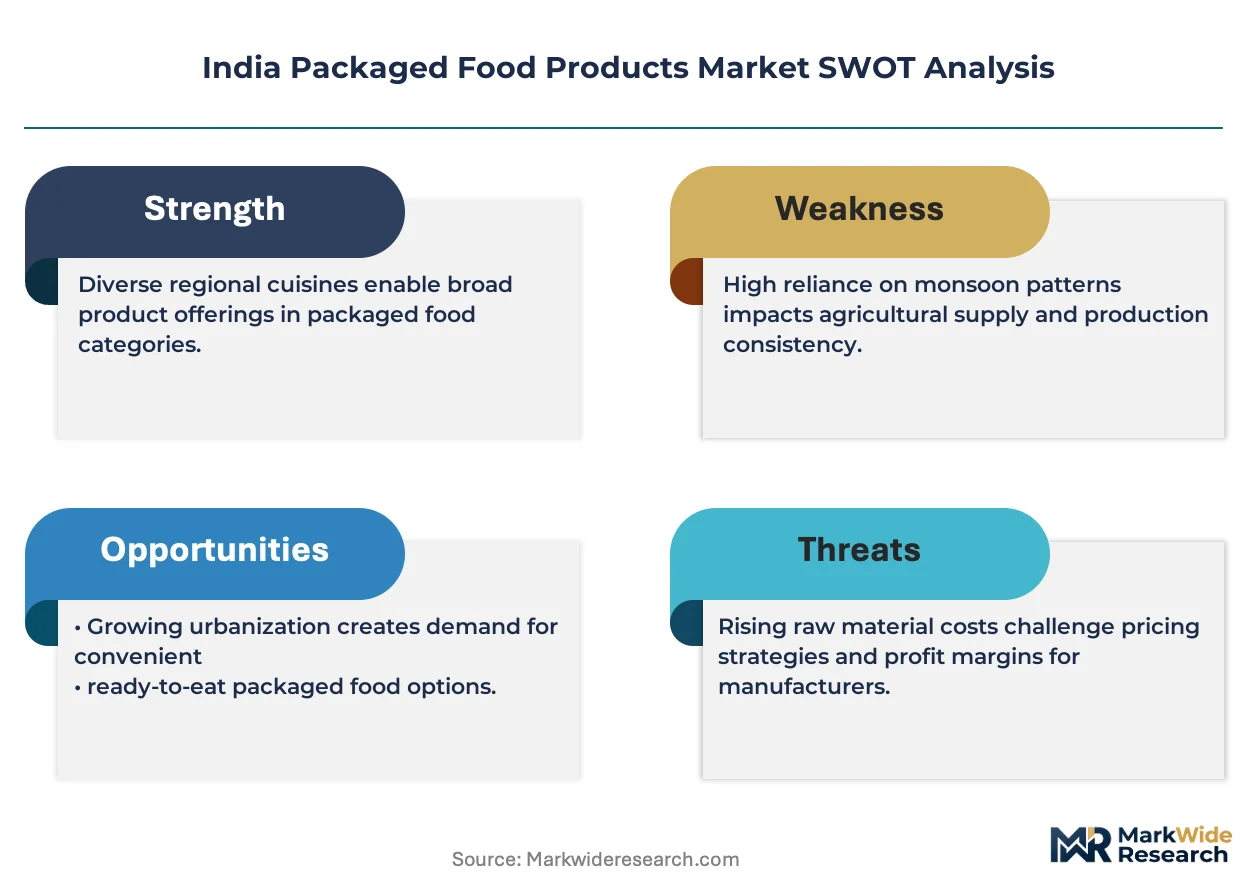
FSSAI fortification rules, BIS packaging standards, and state-level FDA enforcement collectively elevate compliance costs for unorganized processors while accelerating formalization. The PLI scheme for food processing incentivizes capital deployment into cold-chain and packaging automation, tightening entry barriers for sub-scale competitors. Stakeholders must monitor enforcement variance across state FDAs and assess backward integration into ingredient sourcing as a defensive posture against input cost volatility.
Market Dynamics
FSSAI fortification mandates and cold-chain infrastructure investments are restructuring competitive entry barriers across India, forcing processors to absorb compliance costs or exit formal channels entirely.
Growth Catalysts
- PLI scheme for food processing:Capital subsidies accelerate automation adoption and cold-chain deployment, tightening quality standards while expanding distribution reach into underserved districts.
- Urban household time-scarcity:Dual-income families in Mumbai, Bengaluru, and Delhi-NCR drive ready-to-eat and frozen meal penetration through modern trade and quick-commerce channels.
- Retort pouch technology:Flexible packaging formats displace rigid containers in liquid and semi-liquid categories, cutting logistics costs and improving shelf visibility in kirana stores.
Market Restraints
- Palm oil and dairy input volatility:Global commodity price swings compress margins for biscuit and confectionery manufacturers dependent on imported fats and domestic milk solids.
- State FDA enforcement variance:Inconsistent laboratory testing protocols and penalty structures across Maharashtra, Gujarat, and Karnataka create compliance navigation costs for multi-state operators.
- Fresh produce substitution:Traditional wet markets and direct farm linkages retain price-sensitive consumers in tier-three towns and rural hinterlands, limiting packaged food penetration.
Strategic Opportunities
- Fortified staples mandate expansion:FSSAI's edible oil and milk fortification rules create volume anchors for processors with certified blending infrastructure and laboratory partnerships.
- Quick-commerce dark stores:Zepto, Blinkit, and Swiggy Instamart networks demand SKU rationalization and 15-minute fulfillment-compatible pack sizes, rewarding localized production.
- Ayurveda-positioned wellness segments:Ayurveda claims on digestive health and immunity attract premium pricing in urban wellness cohorts, differentiating against commodity competition.
Industry Challenges
- Food safety auditor scarcity:FSSAI-notified laboratory capacity and trained inspection personnel lag processing growth, creating certification bottlenecks for new product launches.
- Legacy distributor credit systems:Kirana stockist payment cycles and inventory financing requirements strain working capital for mid-scale processors expanding beyond metro anchors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Packaged Food Products Market |
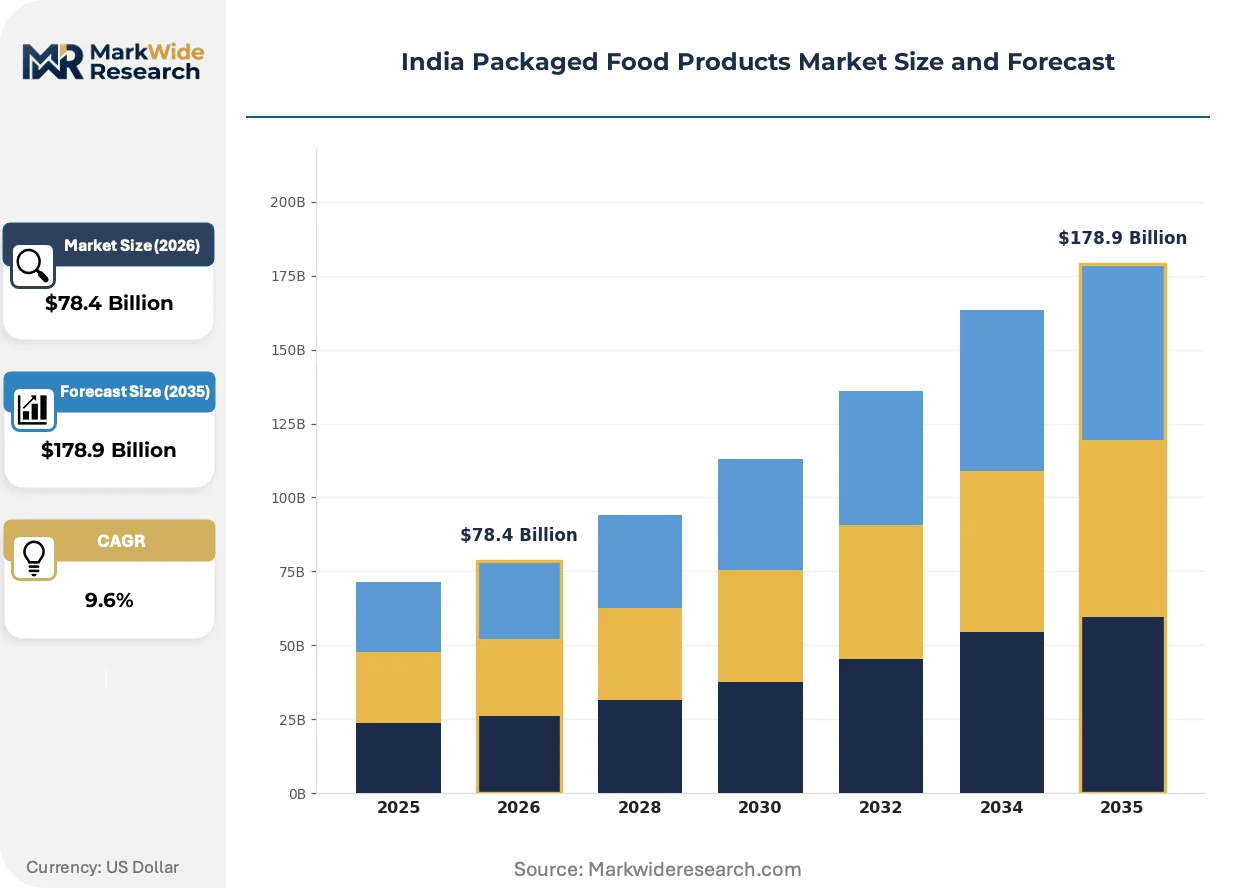
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $178.9 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snacks, Frozen Foods, Ready-to-Eat Meals, Sauces Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Shops Consumer Age Group: Children, Adults, Seniors, Teenagers Packaging Type: Bottles, Pouches, Cans, Tetra Packs |
| Companies Covered | Nestlé India, ITC Foods, Britannia Industries, Patanjali Foods, Amul, PepsiCo India, Haldiram’s, Parle Products, Tata Consumer Products, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Packaged Food Products Market Trends and Innovations
Digital traceability systems and AI-driven demand forecasting are compressing planning cycles and reshaping how processors align production with channel-specific velocity patterns.
Blockchain-enabled supply chain tracking is virtualizing quality assurance documentation for export-oriented spice and marine processors. APEDA-registered exporters in Kerala and Gujarat deploy distributed ledger systems to satisfy EU and US import documentation requirements. This technology is virtualizing audit costs while accelerating customs clearance timelines.
FSSAI's 2022 microbiological standards revision for ready-to-eat foods tightened Salmonella and Listeria thresholds, forcing processors to upgrade thermal processing and environmental monitoring systems. Cold-chain operators in the National Capital Region and Mumbai-Pune corridor have absorbed capital costs for automated temperature logging. Infant cereal and dairy-based dessert manufacturers face the steepest compliance recalibration.
Direct-to-retailer procurement models are disintermediating traditional stockist layers in tier-one cities. Modern trade buyers at Reliance Retail and D-Mart negotiate annual rate contracts with processors, compressing distributor margins. This channel shift concentrates most visibly in Maharashtra and Karnataka where organized retail density supports centralized replenishment systems.
India Packaged Food Products Market Segmentation
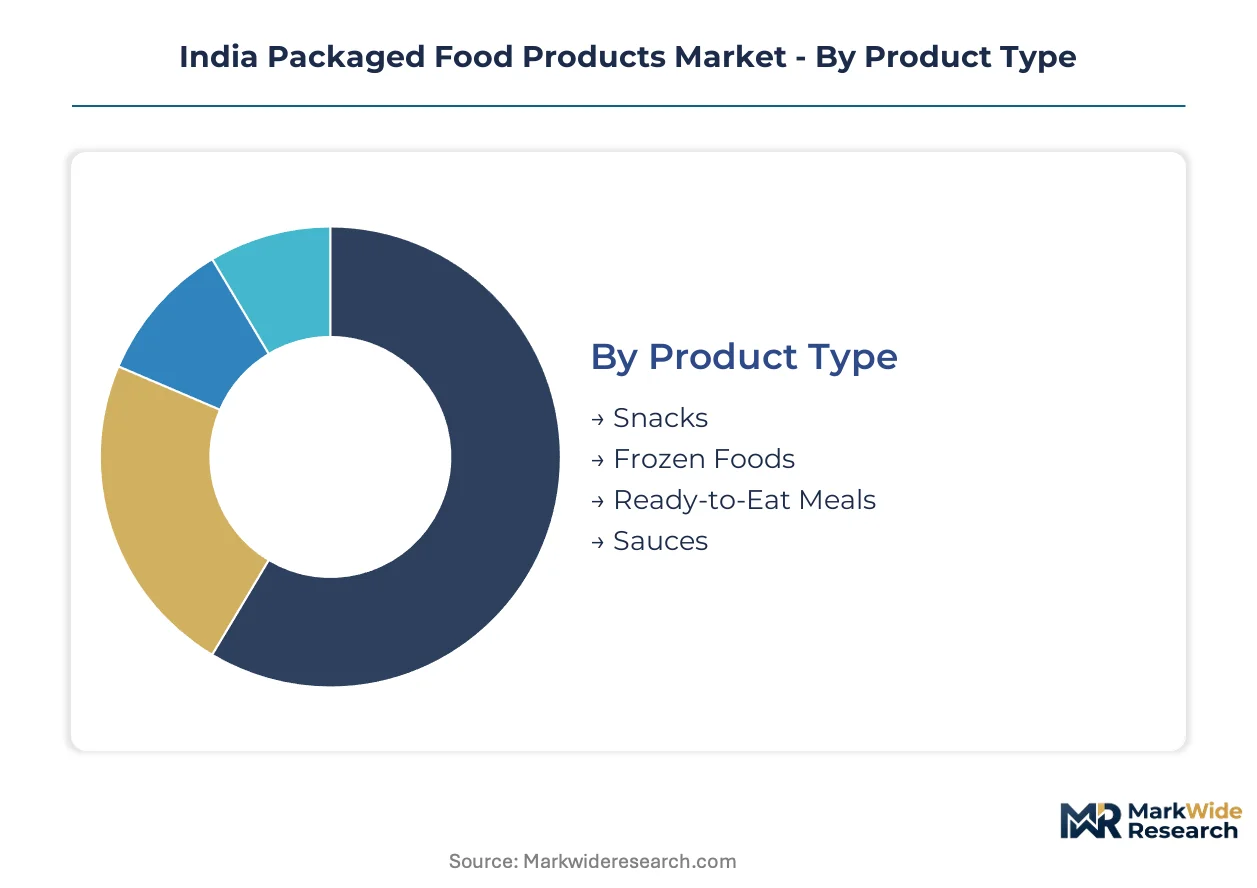
Segmentation reveals how processing infrastructure, channel economics, and demographic targeting intersect across India's packaged food landscape. Each dimension exposes distinct margin structures and compliance burdens that shape competitive positioning.
Product Type:
After-sales service intensity varies sharply across product categories, with frozen and ready-to-eat formats demanding cold-chain maintenance support that snack and sauce processors rarely provide.
- Frozen Foods:Temperature-controlled logistics and blast-freezing equipment define manufacturing scale. Demand concentrates in Mumbai, Bengaluru, and Delhi-NCR where dual-income households trade storage space for convenience; FSSAI's 2022 microbiological standards forced thermal processing upgrades that eliminated sub-scale operators.
- Ready-to-Eat Meals:Retort pouch technology enables ambient distribution without refrigeration. Maharashtra and Karnataka processing clusters serve quick-commerce dark stores with 15-minute fulfillment SKUs; urban time-scarcity drives premium pricing over fresh alternatives.
- Snacks:High-velocity kirana replenishment dominates volume throughput.
- Sauces:Tetra pack and pouch formats displace glass bottles in tier-two towns.
Frozen foods holds the largest share; momentum sits with ready-to-eat meals.
Distribution Channel:
Channel selection determines working capital intensity, with modern trade and quick-commerce demanding inventory financing capabilities that strain mid-scale processors.
- Supermarkets:Reliance Retail and D-Mart negotiate annual rate contracts that compress distributor margins. Direct-to-retailer procurement concentrates in Maharashtra and Karnataka where organized retail density supports centralized replenishment systems.
- Online Retail:Zepto, Blinkit, and Swiggy Instamart networks require SKU rationalization and localized production for 15-minute fulfillment. Kirana stockist credit systems give way to platform payment terms that reward scale.
- Convenience Stores:Extended hours capture impulse purchases in urban corridors.
- Specialty Shops:Ayurveda-positioned wellness products command premium shelf placement.
Supermarkets anchor volume; online retail is climbing the fastest.
Consumer Age Group:
Demographic targeting shapes fortification mandates and packaging safety standards, with infant and senior segments triggering the strictest FSSAI compliance protocols.
- Children:Infant cereals and fortified snacks carry mandatory micronutrient blending requirements. Nestlé India's dairy R&D infrastructure sustains premium positioning through certified laboratory partnerships and FSSAI fortification compliance.
- Adults:Time-scarce professionals in metro corridors drive ready-to-eat and frozen meal penetration. Dual-income households in Delhi-NCR and Mumbai-Pune logistics corridors absorb convenience premiums.
- Seniors:Digestive health and low-sodium claims attract Ayurveda-positioned portfolios.
- Teenagers:Snack velocity dominates with kirana channel overlap and social media-influenced trial.
Adults generate the highest absolute spend; seniors are gaining share fastest on wellness positioning.
Packaging Type:
Material selection directly determines logistics economics and shelf-visibility advantages, with flexible formats displacing rigid containers across liquid and semi-liquid categories.
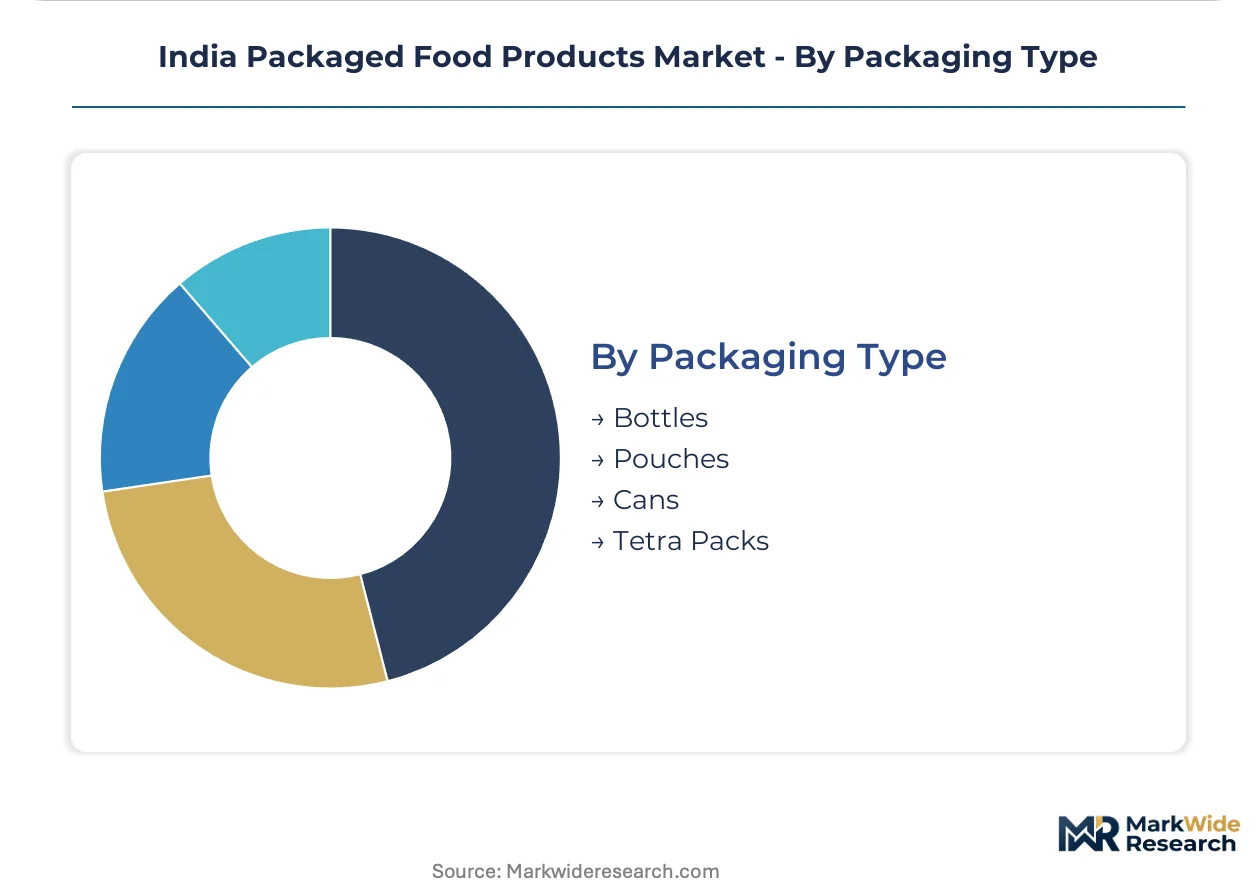
- Tetra Packs:Aseptic filling technology enables ambient distribution without preservatives. Britannia Industries and Nestlé deploy this format for liquid dairy and juices; BIS packaging standards govern laminate specifications and seal integrity testing.
- Pouches:Retort and stand-up formats cut material costs and improve kirana shelf visibility. Patanjali Foods utilizes pouches for Ayurveda-positioned staples; cost efficiency drives adoption in tier-two towns.
- Bottles:PET and glass retain share in premium sauce and beverage segments.
- Cans:Metal packaging persists in export-oriented marine and spice processing.
Tetra packs hold the largest installed base; pouches are expanding most quickly on cost and logistics advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FSSAI fortification mandates and cold-chain infrastructure investments anchor Maharashtra's processing dominance. State-level FDA enforcement variance creates compliance navigation costs for multi-state operators expanding across India.
Maharashtra
Mumbai-Pune logistics corridors concentrate ready-to-eat and frozen food capacity as urban time-scarcity intensifies. The state's FDA enforces microbiological standards with laboratory testing protocols that exceed national baselines. Processing clusters near Nashik and Nagpur absorb PLI scheme subsidies for packaging automation.
Gujarat
Edible oil fortification mandates drive blending infrastructure investment in Ahmedabad-Surat industrial belts. BIS packaging standards govern laminate specifications for dairy and beverage processors. Anand and Vadodara host dairy cooperatives with captive cold-chain networks reaching Rajasthan and Madhya Pradesh.
Karnataka
Bengaluru's quick-commerce dark stores demand SKU rationalization for 15-minute fulfillment. State FDA enforcement focuses on ready-to-eat microbiological thresholds aligned with FSSAI's 2022 revision. Mysuru and Hubli-Dharwad processing parks serve southern retail density.
Tamil Nadu
Chennai's organized retail anchors tetra pack distribution for liquid dairy and juices. The state's food processing policy incentivizes retort pouch manufacturing for ambient-stable formats. Coimbatore's ingredient sourcing clusters support spice and marine export processors.
Delhi-NCR
Dual-income households in Gurugram and Noida drive premium convenience food penetration. Central FDA jurisdiction overlaps with Haryana and Uttar Pradesh state enforcement, creating multi-layer compliance. Sonipat and Ghaziabad cold-chain operators serve quick-commerce networks with automated temperature logging.
India Packaged Food Products Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. Multinational nutrition specialists and domestic dairy cooperatives hold R&D infrastructure and distribution depth. Ayurveda-positioned wellness players and regional snack specialists occupy differentiated niches. Competitive moves center on backward integration into ingredient sourcing and direct-to-retailer procurement models that disintermediate traditional stockist layers.
Among multinational nutrition specialists, Nestlé India occupies a position exemplifying premium-tier fortification compliance. Britannia Industries and Patanjali Foods represent contrasting archetypes: the former anchors deep distribution into tier-two towns, while the latter exemplifies wellness-claim differentiation through Ayurveda positioning. These three entities collectively illustrate how R&D infrastructure, distribution density, and brand positioning create defensible market presence.
| Leading Market Players |
|---|
| Nestlé India |
| ITC Foods |
| Britannia Industries |
| Patanjali Foods |
| Amul |
| PepsiCo India |
| Haldiram's |
| Parle Products |
| Tata Consumer Products |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Maharashtra's ready-to-eat processing corridors compresses contract margins for ambient meal producers while simultaneously elevating pricing power for cold-chain operators with automated temperature logging infrastructure. FSSAI fortification mandates and PLI scheme subsidies reshape supplier behavior toward certified blending investments that pass through as tiered cost structures.
Pricing Analysis
Maharashtra-to-Gujarat price spreads for fortified edible oils reflect state FDA enforcement variance and logistics cost differentials across the Mumbai-Pune and Ahmedabad-Surat corridors. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and cold-chain integrity, with Ayurveda-positioned wellness portfolios commanding brand premiums. Cost compression in economy-tier snacks intensifies as palm oil volatility feeds through to biscuit manufacturers. Kirana stockists in tier-three towns exhibit highest price sensitivity; quick-commerce platforms in Bengaluru and Delhi-NCR absorb convenience premiums with least elasticity.
Supply Chain Analysis
Single-source vulnerability for dairy solids from Gujarat's Anand and Vadodara cooperatives dominates supply chain risk assessment for infant cereal and dessert manufacturers. Input streams draw from palm oil shipments through Malaysian and Indonesian ports, domestic wheat from Madhya Pradesh and Uttar Pradesh, and spice concentrates from Kerala's APEDA-registered export clusters. Distribution runs through modern trade annual rate contracts that disintermediate traditional stockist layers in Maharashtra and Karnataka, while kirana credit systems persist in tier-two towns. Regulatory restriction from FSSAI's microbiological standards revision forces thermal processing upgrades that eliminate sub-scale operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cold-chain maintenance contracts and fortification certification services expand faster than base product sales, creating recurring-revenue layers that improve cash flow predictability for processors with laboratory partnerships.
For Market Incumbents: Insulate margin position through backward integration into dairy solids sourcing from Gujarat cooperatives and captive spice procurement from Kerala clusters. PLI scheme subsidies for packaging automation tighten quality standards while raising capital barriers against unorganized processors. State FDA enforcement variance demands compliance infrastructure that multi-state operators can amortize across volume bases smaller rivals cannot match. For New Entrants and Emerging Players: Pursue quick-commerce dark store supply partnerships in Bengaluru and Delhi-NCR where 15-minute fulfillment SKUs reward localized production with minimal distributor credit exposure. Tier-three town Ayurveda-positioned wellness segments offer white-space penetration with premium pricing power against commodity competition. Go-to-market through direct-to-retailer annual rate contracts with Reliance Retail and D-Mart bypasses legacy stockist financing requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among processors with FSSAI-certified fortification infrastructure and captive laboratory partnerships serving export-oriented spice and marine segments. Long-term viability over a multi-year horizon rests on defensible input sourcing positions and channel control depth rather than brand equity alone. Acquisition targets should demonstrate backward integration into at least one critical input stream; the signal to watch is state FDA enforcement harmonization that would compress compliance navigation costs for national operators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dairy Sourcing | Gujarat cooperative linkages secure input cost stability against milk solids volatility. |
| Cold-Chain Automation Investment | Automated temperature logging satisfies FSSAI's 2022 microbiological standards revision. |
| Quick-Commerce SKU Rationalization | Localized production for Zepto and Blinkit networks captures 15-minute fulfillment premiums. |
| Ayurveda Wellness Portfolio Extension | Digestive health claims differentiate against commodity snacks in urban wellness cohorts. |
| Direct-to-Retailer Procurement Model | Annual rate contracts with Reliance Retail disintermediate traditional stockist margin layers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with category buyers at Reliance Retail and D-Mart, cold-chain logistics operators in Mumbai-Pune and Delhi-NCR corridors, FSSAI-notified laboratory directors, and brand managers at Ayurveda-positioned wellness processors. Secondary validation incorporated FSSAI fortification mandate documentation, BIS packaging standard filings, PLI scheme subsidy disbursement records, APEDA export registration databases, and Nielsen retail audit data for modern trade velocity patterns. Bottom-up SKU-level demand modeling and top-down category spend allocation were triangulated to constrain variance.
Calibration against historical capacity utilization rates and channel shift velocities anchored projection frameworks across the analysis window. Segmentation dimensions modeled include product type, distribution channel, consumer age group, and packaging format, with regional regulatory cluster as an additional industry-specific layer. CAGRs were derived from slope-constrained growth curves fitted to observed penetration rates and income elasticity estimates. Forecast inputs incorporated urban household formation trends in metro corridors and quick-commerce platform expansion trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive capacity addition by dairy cooperatives or harmonized state FDA enforcement would shift outcomes materially. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Middle East and Africa Energy Bar Market
Packaged Foods
North America Chewing Gum Market
Packaged Foods
Cookie Butter Spread Market
Packaged Foods
Spreads Market
Packaged Foods
Packaged Zhug Market
Packaged Foods
Canned Beans Market
Packaged Foods
North America Breakfast Cereals Market
Packaged Foods
North America Instant Noodles Market
Packaged Foods
Asia-Pacific Ready-To-Eat Food Market
Packaged Foods
Organic Energy Bar Market
Packaged Foods
Condensed Canned Soups Market
Packaged Foods
Air-Dried Food Market
Packaged Foods
Global Dessert Mixes Market
Packaged Foods
Europe Ready Meals Market
Packaged Foods
Sugar Free Cookies Market
Packaged Foods
Instant Noodles Market