
 Germany Food Enzymes Market | 2026-2036
Germany Food Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Food Enzymes Market Foresight
Consolidation among German bakery and dairy cooperatives is realigning procurement volumes toward fewer, larger enzyme contracts. BASF SE leverages its Ludwigshafen integrated chemical complex to sustain captive fermentation capacity for industrial-scale enzyme output. Novozymes anchors Northern European supply through specialized biotechnology manufacturing in Denmark with deep distribution into German beverage producers. Associated British Foods plc competes via AB Enzymes' dedicated baking and milling enzyme portfolio tailored to Central European wheat profiles.
Food enzymes are protein-based biocatalysts, typically operating at 30–70°C and pH 4.0–8.0, that accelerate specific biochemical reactions in food matrices without becoming consumed in the process. Industrial production relies on submerged fermentation of genetically optimized microbial strains, followed by downstream recovery, formulation stabilization, and standardization to declared activity units. Proteases command substantial volume in German dairy processing for cheese ripening and milk clotting applications, while amylases lead brewing adjunct conversion where Reinheitsgebot-exempt industrial beers require enzymatic starch hydrolysis. Lipases represent the fastest-expanding product class, driven by fat modification demand in structured lipids for bakery margarines and confectionery coatings across Bavarian production hubs.
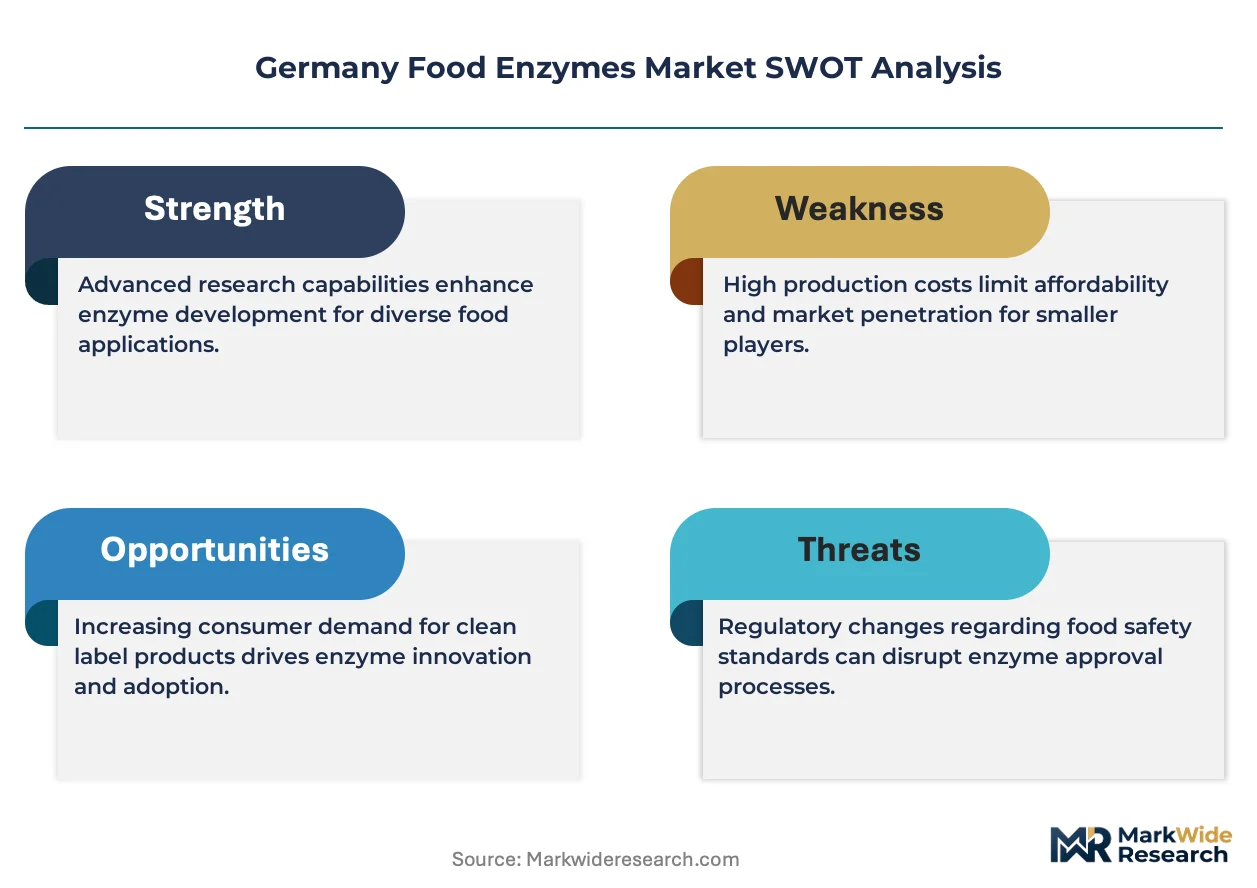
German food enzyme commercialization falls under EFSA Novel Food evaluations, BfR safety assessments, and EU Regulation 1332/2008 on food enzymes, which mandates positive-list authorization and toxicological dossier submission before market entry. The EU Green Deal's Farm to Fork strategy tightens residue monitoring and pushes reformulation toward enzymatic alternatives to chemical processing aids, directly shaping R&D priorities for domestic manufacturers. Stakeholders must monitor the pending harmonized EU positive list implementation timeline and pre-position compliance dossiers for specialty enzymes currently operating under transitional national provisions.
Market Dynamics
Consolidation among Bavarian and Baden-Württemberg food cooperatives is compressing procurement toward fewer, larger enzyme supply contracts with tiered volume commitments. This buyer-side concentration is reshaping supplier negotiation leverage and forcing fermentation capacity investments at industrial scale.
Growth Catalysts
- EU Green Deal Farm to Fork:The strategy mandates residue reduction and chemical processing aid replacement, directly accelerating enzymatic reformulation in dairy and bakery applications.
- Bavarian manufacturing clusters:Dense concentration of large-scale food processors in Munich and Nuremberg corridors generates concentrated demand for specialized lipase and protease formulations.
- Submerged fermentation advances:Continuous bioprocessing improvements are lowering unit production costs for industrial-scale food-grade enzymes.
Market Restraints
- EFSA positive-list authorization:The pending harmonized EU implementation timeline creates regulatory uncertainty for specialty enzymes operating under transitional German national provisions.
- Feedstock volatility:Corn syrup and wheat-derived carbohydrate substrates face price instability tied to agricultural commodity cycles.
- Denmark-centered supply concentration:Northern European biotechnology manufacturing clusters create geographic single-point vulnerability for German beverage and dairy enzyme supply.
Strategic Opportunities
- Baden-Württemberg precision fermentation:Stuttgart-region biotech infrastructure offers underutilized capacity for next-generation enzyme strain development.
- Clean-label confectionery coatings:Structured lipid demand in Bavarian chocolate and margarine production is opening volume contracts for tailored lipase portfolios.
- BfR-EFSA regulatory convergence:Early dossier preparation for harmonized authorization creates first-mover positioning ahead of transitional provision expiration.
Industry Challenges
- Genetic strain optimization expertise:Shortage of microbial fermentation specialists with CRISPR-enabled strain engineering capabilities constrains R&D throughput.
- Downstream recovery capex:Chromatography and membrane filtration equipment for food-grade purity standards demands substantial capital deployment.
- Legacy ERP integration:Batch record digitization for EU Regulation 1332/2008 compliance creates friction with established quality management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Food Enzymes Market |
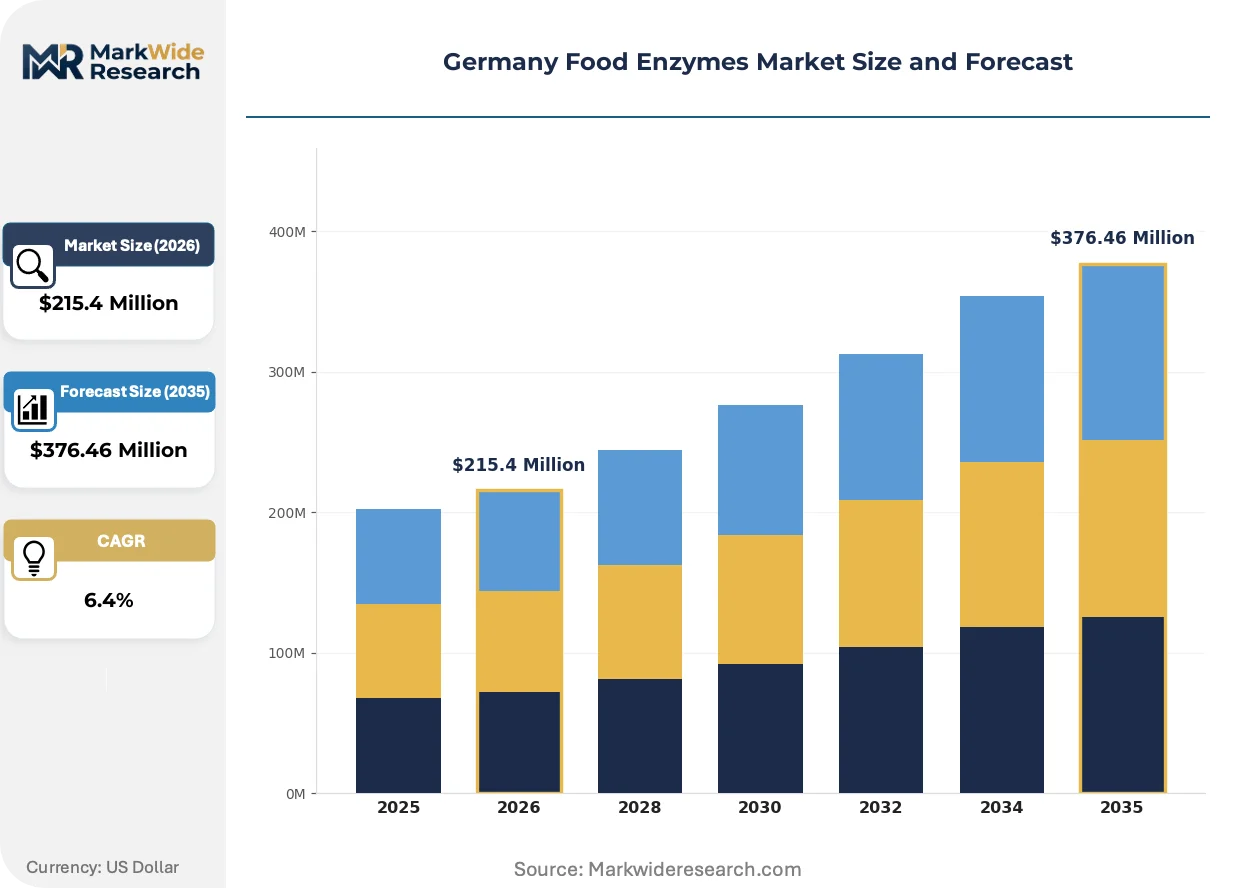
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $376.46 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proteases, Amylases, Lipases, Cellulases, Pectinases Application: Dairy Processing, Brewing, Baking, Fruit & Vegetable Processing, Meat Processing End User: Food Manufacturers, Beverage Producers, Bakeries, Meat Processors, Ingredient Suppliers Form: Liquid, Powder, Granular, Encapsulated |
| Companies Covered | BASF SE, Novozymes, DuPont, Associated British Foods plc (AB Enzymes), Koninklijke DSM NV, Chr. Hansen Holding, Archer Daniels Midland Company, Kerry Group plc, Amano Enzyme Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Food Enzymes Market Shifts & Advancements
Precision fermentation and enzyme engineering are converging to reshape German food processing economics. Three developments are compressing development cycles and reconfiguring competitive positioning across dairy, brewing, and bakery verticals.
Cell-free enzyme synthesis is unifying biosynthesis and formulation stages into continuous production architectures. Specialty chemical suppliers in the Rhine-Neckar triangle are piloting these systems for protease manufacturing. The technology is unifying upstream fermentation and downstream recovery into single-unit operations, collapsing capital intensity thresholds for mid-scale entrants.
EU Regulation 1332/2008 implementation is tightening toxicological dossier requirements for novel enzyme submissions. German manufacturers must now pre-position comprehensive safety data ahead of the harmonized positive list activation. Dairy processing applications face the steepest compliance burden due to historical reliance on nationally authorized transitional enzymes.
Buyer consortium formation among Baden-Württemberg dairy cooperatives is displacing spot-market enzyme purchasing with multi-year framework agreements. Volume aggregation is compressing supplier margins while securing supply continuity for cheese ripening operations. This pattern is most visible in the Stuttgart-Ulm corridor where processor density enables collective bargaining scale.
Germany Food Enzymes Market Segmentation
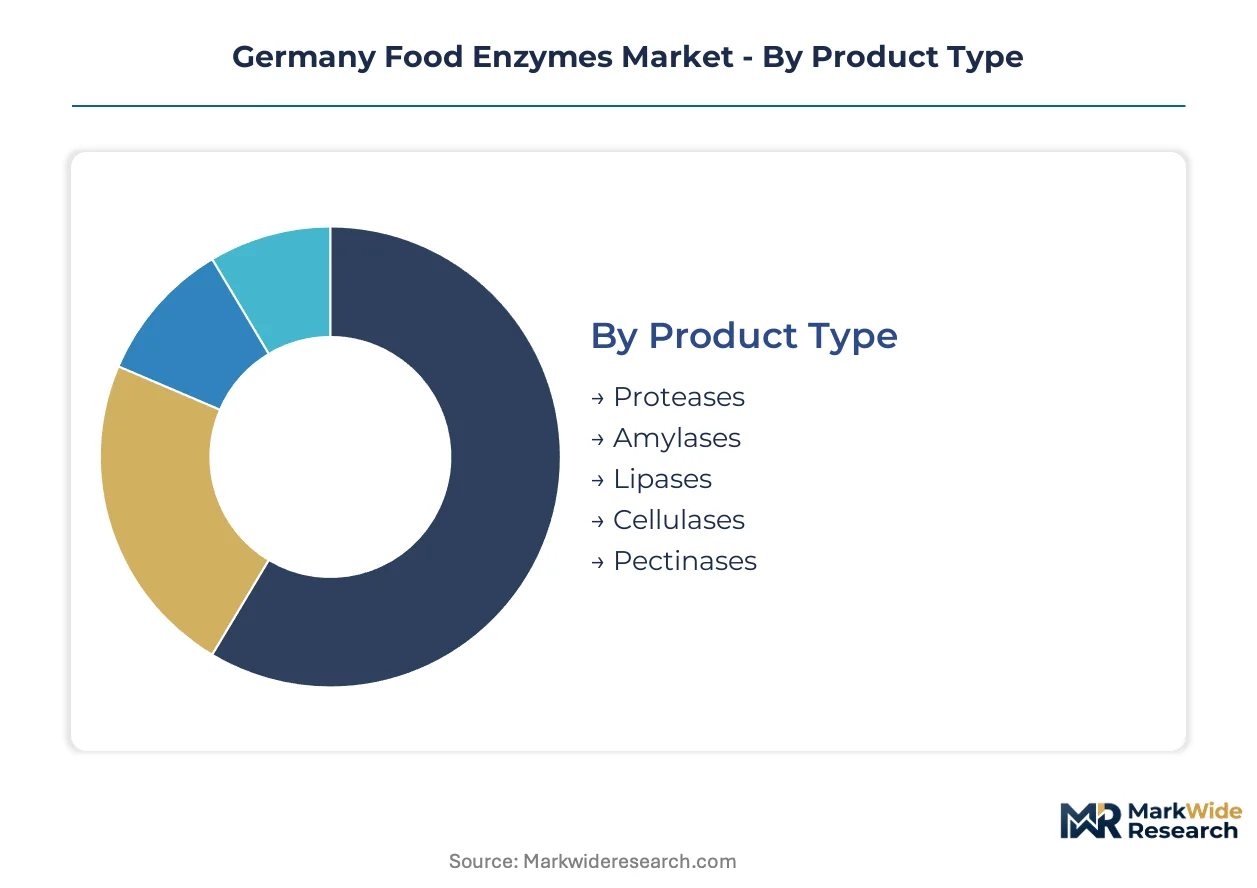
German food enzyme procurement concentrates around distinct technical specifications and application requirements. Segment boundaries reflect divergent fermentation economics, downstream processing costs, and regulatory dossier burdens across product categories.
Product Type:
Fermentation capacity allocation across German biotechnology infrastructure tilts heavily toward protease and lipase production, with strain optimization investments clustering in Bavarian and Baden-Württemberg manufacturing hubs.
- Proteases:These protein-hydrolyzing enzymes operate optimally at 45–60°C and pH 5.5–7.5, with subtilisin variants dominating dairy applications. Bavarian cheese ripening operations in the Allgäu region absorb substantial volumes for Emmental and Camembert-style production, though EFSA positive-list authorization timelines constrain formulation flexibility for novel microbial sources.
- Lipases:Triglyceride-modifying biocatalysts enable structured lipid synthesis for bakery margarines and confectionery coatings. Demand concentrates in Munich-Nuremberg corridor processors seeking clean-label alternatives to chemical interesterification, with Baden-Württemberg chocolate manufacturers driving fastest volume expansion.
- Amylases:Starch-degrading enzymes catalyze brewing adjunct conversion where Reinheitsgebot exemptions apply.
- Cellulases:Cell wall-degrading complexes facilitate fruit juice extraction and yield improvement.
- Pectinases:Pectin-depolymerizing formulations clarify fruit and vegetable processing streams.
Proteases absorb the bulk of installed capacity; lipases are expanding most quickly.
Application:
End-use concentration patterns mirror Germany's regional food manufacturing geography, with dairy processing and baking commanding premium formulation attention from enzyme suppliers.
- Dairy Processing:Milk-clotting and cheese-ripening applications require chymosin and microbial protease blends standardized to international milk clotting units. Allgäu and Bavarian cooperative processors negotiate multi-year supply agreements, though transitional national enzyme authorizations create compliance exposure pending EU harmonization.
- Baking:Dough conditioning and shelf-life extension drive fungal amylase and xylanase demand. Large-scale Baden-Württemberg and Bavarian bakery manufacturers consolidate procurement through fewer, larger contracts with tiered volume commitments.
- Brewing:Adjunct liquefaction and attenuation control utilize heat-stable amylase variants.
- Fruit & Vegetable Processing:Maceration and clarification operations deploy pectinase-cellulase cocktails.
- Meat Processing:Tenderization and flavor development applications employ papain and bromelain alternatives.
Dairy processing commands the steepest regulatory compliance investment; baking exhibits the steepest expansion trajectory.
End User:
Buyer scale and technical sophistication determine formulation service levels, with large food manufacturers extracting dedicated strain development support unavailable to smaller processors.
- Food Manufacturers:Industrial-scale dairy, bakery, and confectionery producers in Bavaria and Baden-Württemberg negotiate framework agreements covering multi-site supply with technical service attachments. These buyers demand batch consistency documentation for EU Regulation 1332/2008 compliance.
- Beverage Producers:Brewing and soft drink manufacturers concentrate in Northern Germany with Denmark-dependent supply chains.
- Bakeries:Artisanal and mid-scale operations purchase spot quantities through ingredient distributors.
- Meat Processors:Sausage and prepared meat facilities utilize protease tenderization selectively.
- Ingredient Suppliers:Blend houses and premix formulators rebundle enzymes into compound processing aids.
Food manufacturers capture priority fermentation allocation; beverage producers face geographic supply concentration risk.
Form:
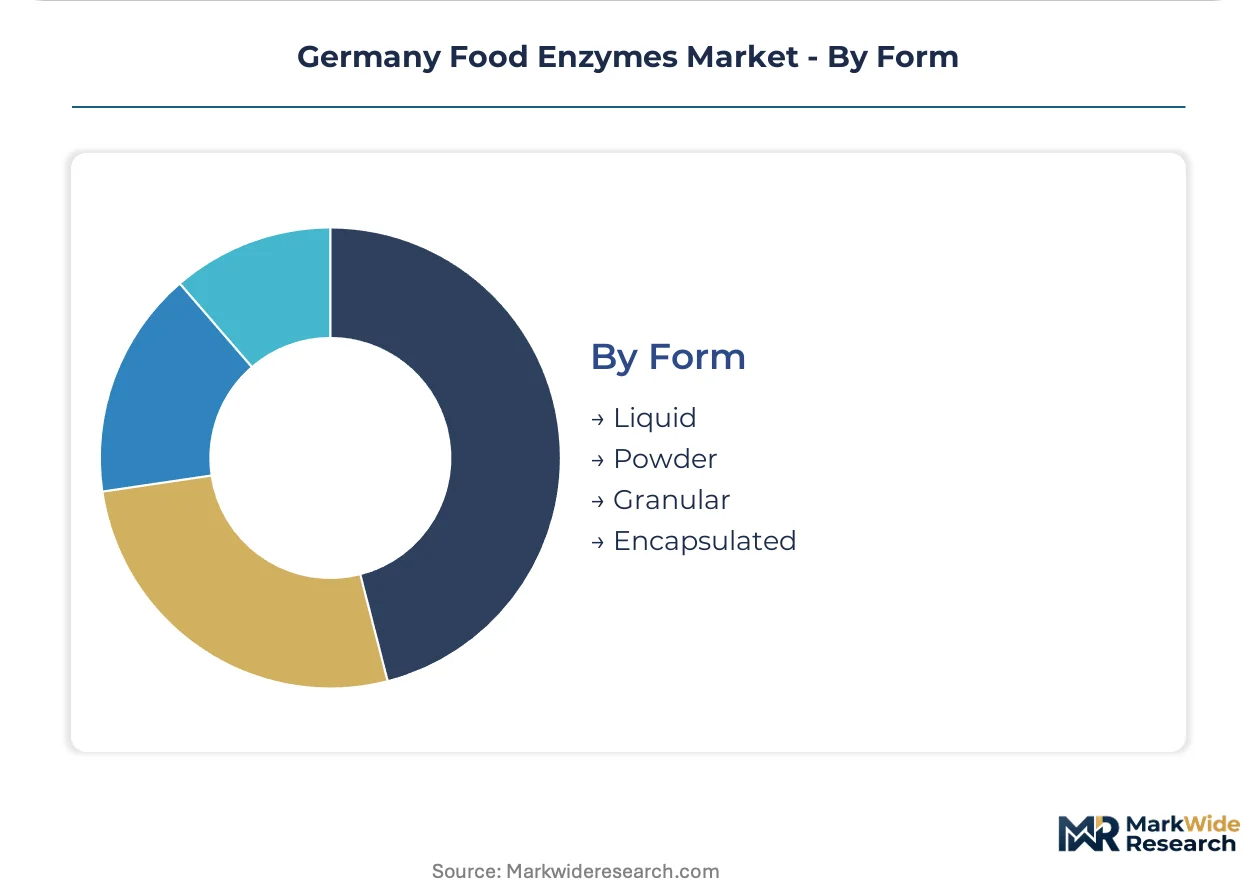
Physical formulation selection balances activity stability, dosing precision, and downstream processing compatibility against unit economics.
- Liquid:Aqueous enzyme concentrates offer straightforward metering and rapid dispersion in fluid food matrices. Bavarian dairy processors prefer liquid protease and lipase formats for continuous cheese-making operations, though cold-chain distribution adds logistics cost.
- Powder:Spray-dried formulations provide extended shelf stability and reduced shipping weight. Baden-Württemberg baking premix suppliers favor powdered amylases and xylanases for dry-blend compatibility.
- Granular:Agglomerated particles reduce dust exposure and improve flow characteristics.
- Encapsulated:Protected enzyme variants enable controlled release in specific pH or temperature conditions.
Liquid formulations dominate dairy and beverage applications; powder is gaining share fastest in bakery and premix channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for food enzymes across Germany concentrates in southern manufacturing corridors where dairy cooperatives and industrial bakeries operate at scale. Bavaria and Baden-Württemberg together absorb the majority of national procurement volumes for protease and lipase formulations.
Bavaria
Allgäu cheese-ripening operations and Munich-Nuremberg bakery clusters drive concentrated protease and lipase consumption. The BfR maintains transitional national enzyme authorizations for regional dairy processors pending full EU harmonization. Ingolstadt and Regensburg host industrial-scale food manufacturing facilities negotiating multi-year enzyme supply frameworks.
Baden-Württemberg
Stuttgart-Ulm chocolate manufacturers and margarine producers are expanding structured lipid applications for clean-label confectionery coatings. EU Regulation 1332/2008 compliance timelines pressure local processors to pre-position toxicological dossiers. The Rhine-Neckar triangle shelters precision fermentation pilot facilities for next-generation strain development.
North Rhine-Westphalia
Brewing adjunct conversion applications in the Lower Rhine industrial zone sustain steady amylase demand for Reinheitsgebot-exempt beer production. The EU Green Deal Farm to Fork strategy accelerates chemical processing aid replacement in regional beverage facilities. Cologne and Düsseldorf anchor distribution logistics for enzyme imports from Danish biotechnology clusters.
Lower Saxony
Dairy processing cooperatives in the Oldenburg Münsterland milk shed negotiate volume-aggregated enzyme contracts for cheese-making operations. National sustainability mandates under the German Climate Action Plan push reformulation toward enzymatic alternatives. Wolfsburg and Hanover corridor food manufacturers consolidate procurement through fewer supplier relationships.
Hesse
Frankfurt-Rhine-Main ingredient blend houses rebundle enzymes into compound processing aids for Central European export markets. EFSA Novel Food evaluation requirements extend approval timelines for innovative microbial enzyme sources. Offenbach and Darmstadt host technical service operations supporting multi-site food manufacturer accounts.
Germany Food Enzymes Market Competitive Landscape
German chemical conglomerates anchor one tier; Danish and Dutch biotechnology specialists hold fermentation capacity advantages in adjacent markets. Supplier consolidation among Bavarian and Baden-Württemberg food cooperatives compresses procurement toward fewer, larger contracts with tiered volume commitments. Three strategic archetypes dominate: integrated chemical majors with captive fermentation infrastructure, dedicated enzyme biotechnology firms with specialized strain libraries, and diversified ingredient suppliers bundling enzymes within broader portfolios. Competitive moves center on backward integration into carbohydrate feedstock supply and multi-year framework agreement capture.
Within the integrated chemical tier, BASF SE leverages its Ludwigshafen manufacturing complex to sustain industrial-scale enzyme output. Novozymes and Associated British Foods plc occupy positions as dedicated biotechnology specialists with focused fermentation expertise. These three entities exemplify the geographic split between German-based integrated producers and Northern European enzyme-focused competitors serving German end-use markets through established distribution relationships.
| Leading Market Players |
|---|
| BASF SE |
| Novozymes |
| DuPont |
| Associated British Foods plc (AB Enzymes) |
| Koninklijke DSM NV |
| Chr. Hansen Holding |
| Archer Daniels Midland Company |
| Kerry Group plc |
| Amano Enzyme Inc. |
| Others |
Supply & Pricing Matrix
Corn syrup and wheat-derived carbohydrate substrates flow through submerged fermentation economics into three-tier pricing structures across premium, standard, and economy levels. Bavarian dairy cooperatives and Baden-Württemberg bakery manufacturers absorb differentiated enzyme costs based on formulation complexity and EFSA dossier compliance status.
Pricing Analysis
Volume-scale buyers extract preferential terms through multi-year framework agreements, while spot-market purchasers face margin compression from fermentation capacity constraints. Price differentiation hinges on EU Regulation 1332/2008 compliance certification and strain optimization depth. Pricing pressure stems from buyer-side consolidation among southern German food cooperatives aggregating procurement leverage. Artisanal bakeries exhibit highest price sensitivity; large-scale dairy processors prioritize supply continuity over unit cost.
Supply Chain Analysis
EFSA positive-list authorization acts as the primary qualification gate for strain sourcing into German food manufacturing. Supply concentrates in Denmark, Germany, and the Netherlands for submerged fermentation capacity. Raw material dependencies include corn syrup, wheat-derived substrates, and specialized nitrogen sources. Single-source vulnerability runs through Denmark-centered biotechnology clusters for beverage enzyme supply. Distribution runs through Rhine-Neckar triangle logistics hubs and Ingolstadt distribution centers serving Bavarian manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation and cell-free enzyme synthesis are displacing legacy submerged batch processing, compressing development cycles and capital intensity thresholds for market participants.
For Market Incumbents: Lock in multi-year supply agreements with Bavarian and Baden-Württemberg dairy cooperatives before transitional national enzyme authorizations expire under EU harmonization timelines. Backward integration into carbohydrate feedstock supply secures margin control against agricultural commodity volatility. CRISPR-enabled strain engineering capabilities represent the critical defensive lever against precision fermentation entrants.
For New Entrants and Emerging Players: Enter via Baden-Württemberg precision fermentation infrastructure, where underutilized biotech capacity supports next-generation enzyme strain development without greenfield capex. Clean-label confectionery coating applications in Stuttgart-Ulm chocolate manufacturing corridors offer the most penetrable white-space target. Technical service bundling with formulation customization provides the essential go-to-market angle against established supplier relationships.
For Investors and Strategic Acquirers: EFSA positive-list authorization timeline announcements are the leading indicator that regulatory consolidation will reshape competitive positioning and valuation multiples for specialty enzyme portfolios. Five-to-ten year viability favors dedicated biotechnology firms with harmonized dossier pre-positioning and captive strain libraries. Watch for BfR-EFSA regulatory convergence milestones as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | Cell-free synthesis collapses capital barriers for mid-scale protease and lipase manufacturing in Rhine-Neckar facilities. |
| EFSA Dossier Pre-Positioning | Early toxicological submission secures first-mover positioning ahead of transitional provision expiration for dairy enzymes. |
| Buyer Consortium Framework Capture | Multi-year agreements with Baden-Württemberg cooperatives lock in volume commitments and displace spot-market competitors. |
| Backward Integration into Feedstock Supply | In-house carbohydrate sourcing buffers margin compression from corn syrup and wheat substrate price volatility. |
| CRISPR Strain Engineering Investment | Genetic optimization capabilities constrain R&D throughput for competitors lacking microbial fermentation specialist access. |
Research Methodology
Document review covered EFSA Novel Food evaluations, BfR safety assessments, EU Regulation 1332/2008 implementation timelines, and industry trade data, complemented by interviews with fermentation plant managers, procurement leads at Bavarian dairy cooperatives, enzyme distribution channel partners, and technical R&D directors at biotechnology firms. Secondary validation drew from customs records, SEC filings of listed chemical conglomerates, Cefic sector reports, and German Federal Statistical Office production data. Bottom-up strain-level volume estimates and top-down market sizing triangulated through cross-reference against fermentation capacity disclosures.
Historical volume trajectories were cross-referenced against panel input from industry stakeholders to anchor growth assumptions across the projection horizon. Segmentation modeling spanned product type, application vertical, end-user scale, and physical formulation dimensions. CAGRs were derived from trend extrapolation adjusted for regulatory implementation pacing and technology substitution curves. Forecast inputs incorporated EU Green Deal Farm to Fork compliance timelines and submerged fermentation yield improvement trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EFSA authorization delays or feedstock price spikes. Model outputs reflect assumptions around harmonized positive-list implementation and precision fermentation adoption rates. A model refresh is warranted upon material change in EFSA regulatory timelines or breakthroughs in cell-free enzyme synthesis economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
United States Food Preservatives Market
Food Additives and Ingredients
South America Food Stabilizers Market
Food Additives and Ingredients
Germany Food Emulsifiers Market
Food Additives and Ingredients
United States Food Enzymes Market
Food Additives and Ingredients
United States Feed Additives Market
Food Additives and Ingredients
Plant Based Preservatives Market
Food Additives and Ingredients
Germany Food Acidulants Market
Food Additives and Ingredients
Beverages Additives Market
Food Additives and Ingredients
North America Clean Label Ingredient Market
Food Additives and Ingredients
Beverage Stabilizer Market
Food Additives and Ingredients
Calcium Inosinate Market
Food Additives and Ingredients
Food Grade Sodium Hydroxide Market
Food Additives and Ingredients
Gum Hydrocolloid Market
Food Additives and Ingredients
Global Organic Food Preservatives Market
Food Additives and Ingredients
Spain Food Emulsifiers Market
Food Additives and Ingredients
North America Microencapsulation Market