
 Middle East and Africa Food Starch Market | 2026-2036
Middle East and Africa Food Starch Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Food Starch Market Foresight
The gap between premium modified starch and commodity native starch is expanding across the Middle East and Africa, with Gulf food processors paying substantial premiums for cold-water swelling and cross-linked variants while North African buyers prioritize cost-optimized native grades. Cargill Incorporated leverages its Red Sea logistics infrastructure to serve Egyptian and Saudi manufacturing clusters. Tate & Lyle PLC sustains technical service density in Dubai and Johannesburg for beverage and dairy formulators. Ingredion Inc. anchors its regional position through corn wet milling partnerships in South Africa.
Food starch comprises carbohydrate polymers extracted from cereals, tubers, and legumes through wet milling, drying, and optional chemical or physical modification to control viscosity, gel strength, and retrogradation behavior; these functional properties govern texture stabilization in processed foods, pharmaceutical binders, and cosmetic emulsions. Modified starch commands margin premiums in Gulf beverage applications where acid-thinned and oxidized variants resist shear degradation during ultra-high-temperature processing. Native starch from corn and wheat dominates North African and sub-Saharan price-sensitive segments where clean-label positioning remains secondary to unit cost control. Pregelatinized starch grows fastest in Nigerian and Kenyan instant soup and baby food formats where cold-water dispersibility eliminates cooking steps.
Saudi Food and Drug Authority and South African Health Products Regulatory Authority standards govern additive purity and labeling across the two largest national markets, while Gulf Standardization Organization harmonization efforts reduce cross-border formulation complexity. Halal certification requirements from Emirates Authority for Standardization and Metrology and South African National Halaal Authority shape enzyme sourcing and processing aid selection throughout the value chain. Stakeholders must monitor accelerating local content mandates in Egyptian and Moroccan industrial policies that threaten imported starch volumes.
Market Dynamics
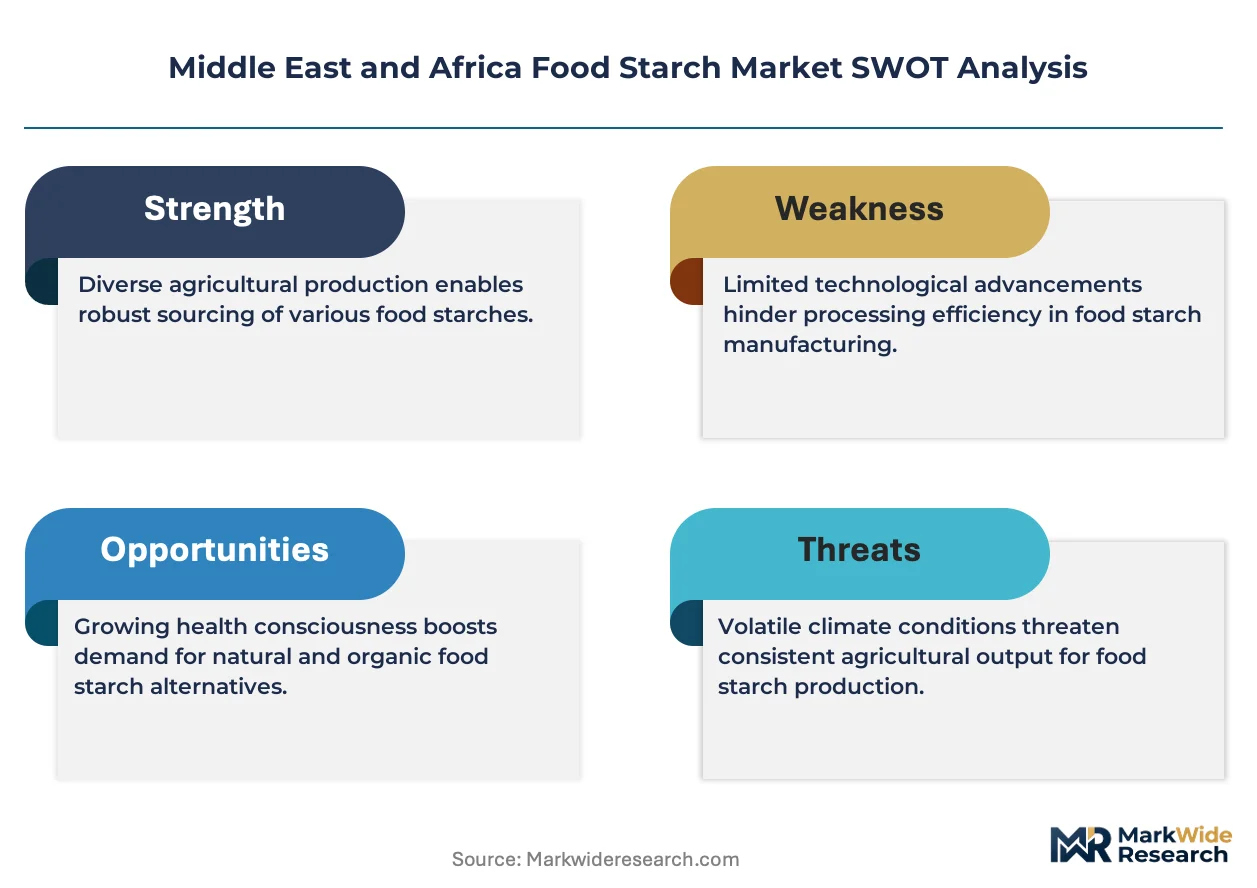
Halal certification complexity and Gulf Cooperation Council additive harmonization are restructuring procurement relationships, forcing starch suppliers to reconfigure enzyme sourcing and processing documentation across Egyptian, Saudi, and South African manufacturing corridors.
Growth Catalysts
- Instant food format proliferation:Nigerian and Kenyan baby food manufacturers are scaling cold-water dispersible pregelatinized starch procurement to eliminate consumer cooking steps.
- Gulf Standardization Organization alignment:Cross-border formulation complexity reduction is accelerating modified starch adoption among UAE and Saudi beverage processors seeking acid-thinned variants for ultra-high-temperature stability.
- South African wet milling infrastructure:Corn starch production partnerships are anchoring regional supply security for sub-Saharan processed food manufacturers.
Market Restraints
- Maize price volatility:Input cost swings for corn-based native starch are compressing margins for North African cost-optimized buyers in Egypt's confectionery sector.
- Gulf supplier concentration:Cold-water swelling and cross-linked modified starch production clusters in Saudi Arabia and UAE are creating single-source dependency risks for premium beverage formulators.
- Clean-label substitution ceiling:Native starch functional limitations in acid stability and shear resistance prevent displacement of modified grades in Gulf ultra-high-temperature processing applications.
Strategic Opportunities
- Moroccan industrial policy localization:Egyptian and Moroccan local content mandates are creating captive production incentives for starch manufacturers establishing North African milling assets.
- Enzymatic modification convergence:Halal-compliant enzyme processing paired with physical modification technologies is opening certification-differentiated product lines for Gulf Cooperation Council markets.
- Direct-to-manufacturer digital channels:B2B platform procurement is disintermediating traditional distributor networks for mid-scale Nigerian soup and sauce producers.
Industry Challenges
- Halal certification timeline compression:Emirates Authority for Standardization and Metrology documentation requirements are extending product qualification cycles for new enzyme-sourced modified starch introductions.
- Retrograde technical talent scarcity:Food polymer rheology expertise gaps in Johannesburg and Dubai technical service centers are constraining formulation support scaling for beverage and dairy clients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Food Starch Market |
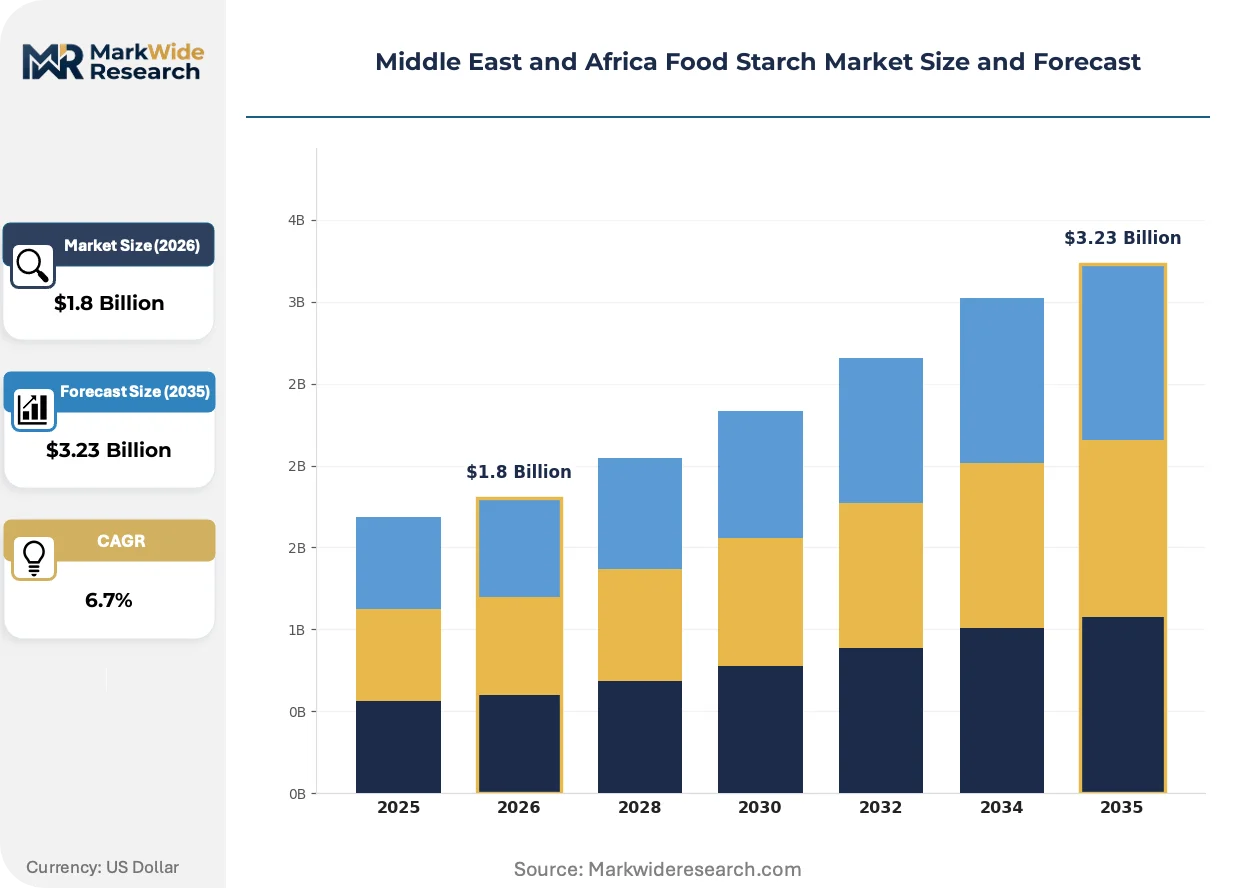
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modified Starch, Native Starch, Pregelatinized Starch, Liquid Starch End Use Sector: Food & Beverage, Pharmaceuticals, Cosmetics, Feed Industry Source: Corn, Potato, Wheat, Tapioca Form: Powder, Granules, Gels, Liquids |
| Companies Covered | Archer Daniels Midland Company, Cargill Incorporated, Tate & Lyle PLC, Ingredion Inc., Roquette Frères, AGRANA Beteiligungs-AG, Kerry Group PLC, Tongaat Hulett, Emsland Group, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Food Starch Market Shifts & Advancements
Physical modification technologies and halal processing protocols are converging to redefine starch functional performance benchmarks across Middle Eastern beverage corridors and African instant food manufacturing.
Dual-modification processing combining enzymatic thinning with cross-linking chemistry is rewriting viscosity stability standards for Gulf ultra-high-temperature dairy applications. Saudi beverage formulators are adopting these hybrid variants at accelerated qualification cycles. The technology is compressing premium pricing power for single-modification legacy grades.
Gulf Standardization Organization additive harmonization efforts are tightening purity documentation requirements across Saudi, UAE, and Kuwait manufacturing clusters. Industrial consequence includes mandatory batch-level traceability systems for enzyme-sourced modified starch imports. Egyptian exporters to Gulf markets are investing in dedicated halal-certified production lines to maintain access.
Ready-meal manufacturers in Saudi Arabia's production corridors are consolidating supplier relationships around full-service technical partnerships rather than transactional commodity purchasing. Traditional distributor networks serving smaller UAE and Qatar processors are losing volume to direct manufacturer engagement models. This concentration is most visible in Riyadh and Jeddah ready-meal production zones where formulation support integration determines supplier selection.
Middle East and Africa Food Starch Market Segmentation
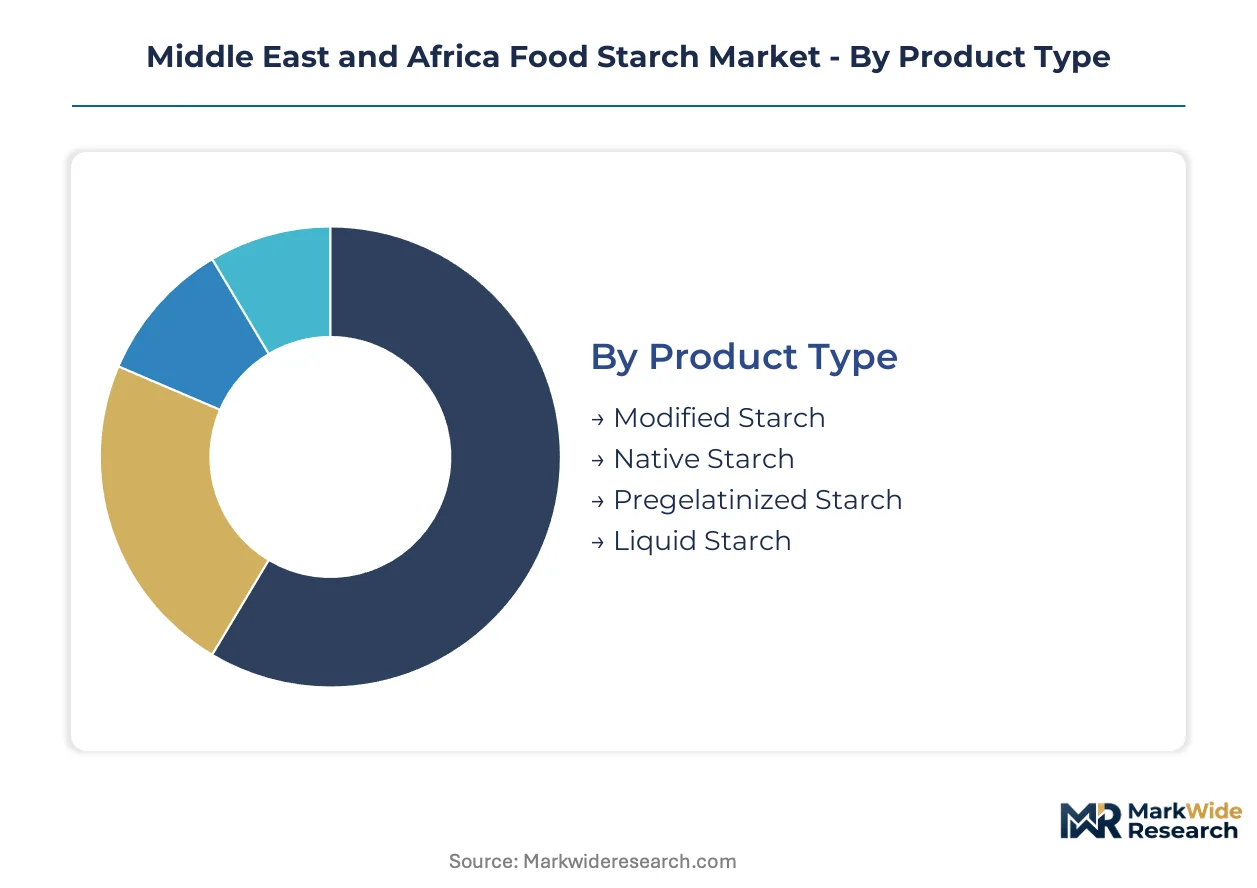
Starch functional specifications diverge sharply across Middle Eastern and African processing corridors. Gulf beverage manufacturers prioritize shear-stable modified grades while North African and sub-Saharan buyers optimize around native starch cost structures. Segmentation discipline separates premium formulation partnerships from commodity procurement relationships.
Product Type:
Supply concentration in modified starch production clusters across Saudi Arabia and UAE creates premium pricing power for cold-water swelling and cross-linked variants.
- Modified Starch:Chemical or physical alteration—cross-linking, acid-thinning, oxidation—delivers controlled viscosity and acid stability. Saudi dairy processors specify these grades for ultra-high-temperature lines where shear degradation destroys native starch performance. Gulf beverage formulators pay substantial premiums for dual-modification variants combining enzymatic thinning with cross-linking chemistry.
- Native Starch:Unmodified carbohydrate polymers extracted through wet milling retain natural retrogradation behavior and gel characteristics. Egypt's confectionery sector and Nigerian soup manufacturers anchor procurement here, prioritizing unit cost control over functional performance in low-acid, ambient-temperature applications.
- Pregelatinized Starch:Thermal pre-processing eliminates cooking requirements through cold-water dispersibility. Nigerian and Kenyan instant food corridors—baby foods, dry soup mixes—are scaling procurement fastest to eliminate consumer preparation steps.
- Liquid Starch:Suspension or solution formats reduce dust handling and hydration time in high-throughput manufacturing environments.
Today's leader: Modified Starch. Tomorrow's challenger: Pregelatinized Starch.
End Use Sector:
Application-specific rheology requirements fragment procurement patterns across technical service-intensive versus price-optimized buyer segments.
- Food & Beverage:Texture stabilization dominates—dairy gels, beverage emulsions, bakery structures, ready-meal sauces. Saudi Arabia's expanding Riyadh and Jeddah production corridors consolidate supplier relationships around integrated formulation support rather than transactional purchasing.
- Pharmaceuticals:Tablet binders and capsule fillers demand batch-level purity documentation under SFDA and South African Health Products Regulatory Authority standards. Enzyme-sourced modified starch faces extended qualification cycles from Emirates Authority for Standardization and Metrology documentation requirements.
- Cosmetics:Emulsion stabilization and powder flow control utilize starch rheology in lower-volume, higher-margin applications.
- Feed Industry:Pellet binding and energy density applications prioritize cost-optimized native grades with minimal processing overhead.
Food & Beverage commands current volume concentration. Pharmaceuticals represents the steepest expansion trajectory as regional manufacturing localizes.
Source:
Raw material procurement geography shapes supply security and halal certification complexity across the value chain.
- Corn:Wet milling infrastructure in South Africa anchors regional supply security for sub-Saharan processed food manufacturers. Maize price volatility compresses margins for Egyptian and North African buyers dependent on import flows.
- Potato:Higher amylopectin content delivers superior clarity and freeze-thaw stability. European import dependency creates currency exposure for Gulf processors.
- Wheat:Gluten contamination risks require dedicated processing lines for celiac-safe applications. North African proximity to Mediterranean suppliers reduces landed cost.
- Tapioca:Clean-label positioning and neutral flavor profile command niche premiums in premium beverage and cosmetic formulations.
Corn supplies the volume base. Tapioca gains share fastest on clean-label differentiation.
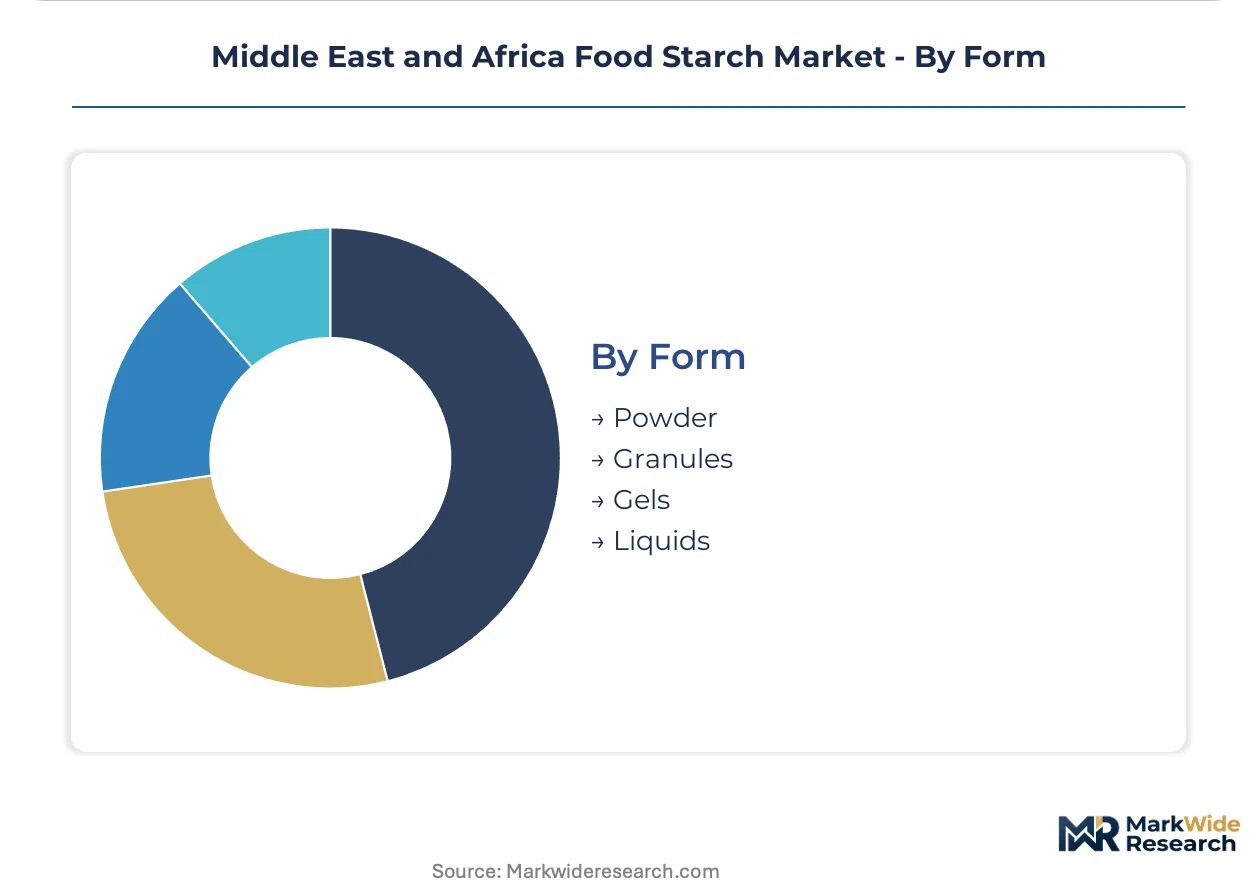
Form:
Physical presentation determines handling economics, hydration kinetics, and manufacturing integration complexity.
- Powder:Standard milled formats dominate bulk procurement for dry mix manufacturing. Dust control and explosion prevention add capital requirements.
- Granules:Agglomerated particles improve flowability and reduce dust generation in high-speed packaging lines.
- Gels:Pre-hydrated systems eliminate cooking steps and ensure batch-to-batch consistency in ready-meal and sauce applications.
- Liquids:Pumpable formats integrate directly into continuous processing without powder handling infrastructure.
Powder retains manufacturing dominance. Gels are climbing fastest on ready-meal production automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia commands premium modified starch procurement while Egypt anchors native starch consumption across North African cost-sensitive segments. Divergent functional requirements and regulatory frameworks fragment procurement patterns across the Middle East and Africa.
Saudi Arabia
Riyadh and Jeddah ready-meal production corridors consolidate supplier relationships around integrated formulation support. SFDA additive purity standards govern batch-level documentation for enzyme-sourced modified starch imports. Eastern Province industrial clusters scale cold-water swelling and cross-linked variant procurement for ultra-high-temperature dairy processing.
Egypt
Cairo-Alexandria confectionery manufacturers prioritize cost-optimized native corn and wheat grades. Local content mandates in Egyptian industrial policy threaten imported starch volumes while incentivizing captive milling assets. Nile Delta food processing zones anchor regional native starch demand.
United Arab Emirates
Dubai beverage formulators adopt acid-thinned modified starch variants under Gulf Standardization Organization harmonization protocols. MOHAP and Emirates Authority for Standardization and Metrology documentation requirements extend qualification cycles for new enzyme-sourced introductions. Jebel Ali logistics corridors serve as regional distribution hubs for Gulf Cooperation Council markets.
South Africa
Johannesburg technical service centers support beverage and dairy formulators across sub-Saharan markets. South African Health Products Regulatory Authority standards govern pharmaceutical-grade starch purity. KwaZulu-Natal and Gauteng wet milling partnerships anchor regional corn starch supply security.
Nigeria
Lagos and Kano instant food manufacturers scale pregelatinized starch procurement for baby food and dry soup applications. Cold-water dispersibility eliminates consumer cooking steps in price-sensitive urban markets. Nigerian soup and sauce producers increasingly adopt direct-to-manufacturer digital procurement channels.
Middle East and Africa Food Starch Market Competitive Landscape
Top-tier vendors anchor Gulf premium modified starch procurement, while regional milling partnerships and technical service specialists occupy mid-market positions. The vendor base stratifies across three tiers: multinational ingredient conglomerates with Red Sea logistics infrastructure, European and North American specialists with halal-certified production lines, and emerging local millers responding to Egyptian and Moroccan localization mandates. Dominant competitive moves include backward integration into corn wet milling assets and geographic expansion through Dubai and Johannesburg technical service hubs.
Within the multinational conglomerate tier, Cargill Incorporated and Tate & Lyle PLC exemplify logistics-anchored positioning across Egyptian and Saudi manufacturing clusters. Ingredion Inc. occupies a distinct position through South African corn wet milling partnerships. These three entities represent the dominant archetypes: logistics-integrated suppliers, technical service-intensive formulators, and regional production-anchored processors.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Tate & Lyle PLC |
| Ingredion Inc. |
| Roquette Frères |
| AGRANA Beteiligungs-AG |
| Kerry Group PLC |
| Tongaat Hulett |
| Emsland Group |
| Others |
Supply & Pricing Matrix
Maize futures price volatility in South African commodity exchanges cascades through Egyptian confectionery procurement budgets and Gulf beverage formulator cost structures, compressing margins for native starch buyers while sustaining premium pricing power for cold-water swelling modified variants.
Pricing Analysis
Capacity additions in Saudi Arabia and UAE are reshaping price floors for cross-linked and acid-thinned modified starch grades. Three-tier pricing structure across premium modified, standard native, and economy feed-grade levels stratifies buyer segments. Price differentiation rests on halal certification tier and integrated formulation support bundling. Cost compression in North African native starch procurement is intensifying because Egyptian buyers prioritize unit cost control over functional performance. Egyptian confectionery manufacturers exhibit highest price sensitivity; Saudi ultra-high-temperature dairy processors show lowest.
Supply Chain Analysis
Regional distribution centers in Jebel Ali and Johannesburg anchor hub-and-spoke patterns serving Gulf Cooperation Council and sub-Saharan manufacturing clusters. Supply concentrates in South Africa, Saudi Arabia, and Egypt for wet milling and modification processing. Raw material flows draw from Ukrainian and Argentine corn origins, European potato starch imports, and local South African maize harvests. Single-source vulnerability risks concentrate in premium modified starch enzyme sourcing from halal-certified production lines. Distribution runs through technical service-integrated direct channels for Saudi ready-meal producers and traditional distributor networks for smaller Nigerian soup manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa food starch market functions as a stable compounder anchored by irreversible processed food format proliferation across Nigerian instant food corridors and Saudi ready-meal production zones.
For Market Incumbents: Cement Gulf premium positioning through captive halal-certified enzyme modification capacity in Saudi Arabia's Eastern Province industrial clusters. Deepen backward integration into South African corn wet milling assets to defend against Egyptian and Moroccan localization mandates threatening imported starch volumes. Anchor technical service density in Dubai and Johannesburg to lock in beverage and dairy formulator relationships before regional competitors replicate formulation support integration. For New Entrants and Emerging Players: Gulf Standardization Organization additive harmonization in UAE and Saudi Arabia opens a window for documentation-compliant modified starch introductions from Egyptian exporters investing in dedicated halal-certified production lines. Target Nigerian direct-to-manufacturer digital procurement channels where B2B platform adoption disintermediates traditional distributor networks serving mid-scale soup and sauce producers. Lead with pregelatinized starch cold-water dispersibility demonstrations for instant food format manufacturers in Lagos and Kano. For Investors and Strategic Acquirers: Asymmetric upside sits with regional milling partnerships possessing halal-certified modification capabilities and Red Sea logistics infrastructure. Long-term viability hinges on exposure to Saudi and Egyptian manufacturing localization trends rather than pure commodity native starch plays. Monitor Emirates Authority for Standardization and Metrology documentation requirement intensification as inflection indicator for qualification cycle compression and captive production incentives.| Strategic Initiative | Industry Significance |
|---|---|
| Halal-Certified Production Line Investment | Egyptian exporters to Gulf markets secure SFDA and MOHAP compliant batch-level traceability systems. |
| Backward Integration into Corn Wet Milling | South African partnerships anchor regional supply security for sub-Saharan processed food manufacturers. |
| Technical Service Hub Expansion | Dubai and Johannesburg centers lock in beverage and dairy formulator relationships through integrated formulation support. |
| Direct-to-Manufacturer Digital Channel Development | B2B platforms disintermediate traditional distributor networks for Nigerian soup and sauce producers. |
| Dual-Modification Processing Capability Buildout | Saudi beverage formulators adopt hybrid enzymatic-cross-linked variants for ultra-high-temperature stability. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement captured plant managers at Egyptian and Saudi starch modification facilities, procurement leads at Nigerian instant food manufacturers, Gulf beverage formulator technical directors, and South African wet milling partnership executives. Secondary validation drew from Gulf Standardization Organization additive harmonization protocols, SFDA and MOHAP regulatory filings, South African Health Products Regulatory Authority pharmaceutical-grade standards, and regional customs and trade flow data. Bottom-up volume modeling and top-down value triangulation cross-checked segment outputs.
Historical reference periods anchored growth trajectory assumptions across the projection horizon. The analytical framework modeled segmentation dimensions spanning product type tiers, end-use sector application requirements, raw material source origins, and physical form handling economics. CAGRs were derived through regression-based trending adjusted for halal certification timeline compression and local content mandate acceleration. Industry-specific forecast inputs incorporated maize price volatility patterns and Gulf beverage processor ultra-high-temperature processing specification evolution.
Revisions become necessary when Egyptian or Moroccan industrial policy localization mandates accelerate beyond modeled timelines, or when Emirates Authority for Standardization and Metrology documentation requirements extend product qualification cycles unpredictably. Forecasts reflect documented assumptions around halal enzyme sourcing availability and Red Sea logistics corridor stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Italy Food Additives Market
Food Additives and Ingredients
North America Food Emulsifiers Market
Food Additives and Ingredients
Australia Food Additives Market
Food Additives and Ingredients
Nanoencapsulated Food Additives Market
Food Additives and Ingredients
China Food Additives Market
Food Additives and Ingredients
Noodles Preservatives Market
Food Additives and Ingredients
France Food Acidulants Market
Food Additives and Ingredients
Germany Food Additives Market
Food Additives and Ingredients
Acetylated Distarch Adipate Market
Food Additives and Ingredients
Sucroglycerides Market
Food Additives and Ingredients
United States Feed Additives Market
Food Additives and Ingredients
North America Fermented Ingredient Market
Food Additives and Ingredients
North America Food Anti Caking Agents Market
Food Additives and Ingredients
Egg Wash Substitute Market
Food Additives and Ingredients
India Food Enzymes Market
Food Additives and Ingredients
Fat-Replacing Starch Market