
 Global Bispecific Antibody Therapeutics Market | 2026-2036
Global Bispecific Antibody Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bispecific Antibody Therapeutics Market Foresight
Oncology centers are bifurcating demand between academic medical centers and community hospital systems. Amgen leverages its BiTE platform to dominate T-cell engager development. Roche sustains leadership through its IgG-like bispecific pipeline and manufacturing scale. Janssen competes across multiple myeloma indications with differentiated dosing strategies.
Bispecific antibody therapeutics are recombinant proteins engineered to bind two distinct antigens simultaneously, typically constructed with dual variable domains or fragment-based architectures that enable simultaneous immune cell recruitment and tumor targeting. IgG-like bispecifics anchor current revenue pools due to favorable pharmacokinetics and established manufacturing workflows, while fragment-based formats capture fastest-growing demand in solid tumor applications where tumor penetration governs efficacy. Oncology commands the dominant therapy area as CAR-T limitations create openings for off-the-shelf bispecific alternatives, and subcutaneous delivery technology reshapes administration economics across outpatient settings.
FDA accelerated approval and EMA conditional marketing authorization frameworks compress development timelines but intensify post-market evidence requirements for bispecific developers. China's NMPA innovation drug pathways and Germany's BfArM early benefit assessments create divergent market access conditions across major jurisdictions. Stakeholders must monitor evolving reimbursement thresholds for combination regimens and manufacturing capacity constraints for complex multi-specific formats.
Market Dynamics
Subcutaneous delivery technology is compressing administration economics and shifting site-of-care decisions away from infusion centers toward outpatient clinics and home settings.
Growth Catalysts
- EMA Conditional Marketing Authorization:Compressed development timelines accelerate patient access to novel bispecific formats in hematological malignancies across European oncology centers.
- CAR-T manufacturing bottlenecks:Production capacity constraints for autologous cell therapies are redirecting institutional procurement toward off-the-shelf bispecific alternatives.
- China's NMPA innovation drug pathways:Expedited review procedures for breakthrough therapies attract multinational development investment toward domestic manufacturing partnerships.
Market Restraints
- Complex bioprocessing inputs:Dual-variable-domain engineering requires specialized cell line development and purification resin costs that inflate COGS relative to monoclonal antibodies.
- US reimbursement uncertainty:Medicare's evolving site-of-care payment differentials create margin compression for hospital outpatient department administration.
- Fragment-based pharmacokinetic limitations:Shorter half-lives necessitate more frequent dosing, constraining uptake in chronic maintenance settings where patient compliance governs outcomes.
Strategic Opportunities
- Germany's BfArM early benefit assessments:Structured HTA pathways for oncology innovations enable rapid AMNOG pricing negotiations for differentiated bispecific entrants.
- Solid tumor penetration:Smaller-format bispecifics addressing tumor microenvironment barriers represent underdeveloped white space beyond hematology.
- Home administration models:Subcutaneous device compatibility opens channel innovation through specialty pharmacy distribution and patient self-management protocols.
Industry Challenges
- Multi-specific manufacturing talent scarcity:Cell culture scientists with cross-flow filtration and viral clearance expertise command premium compensation, constraining capacity expansion timelines.
- Cytokine release syndrome management protocols:Institutional credentialing requirements for step-up dosing administration create operational friction in community hospital adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bispecific Antibody Therapeutics Market |
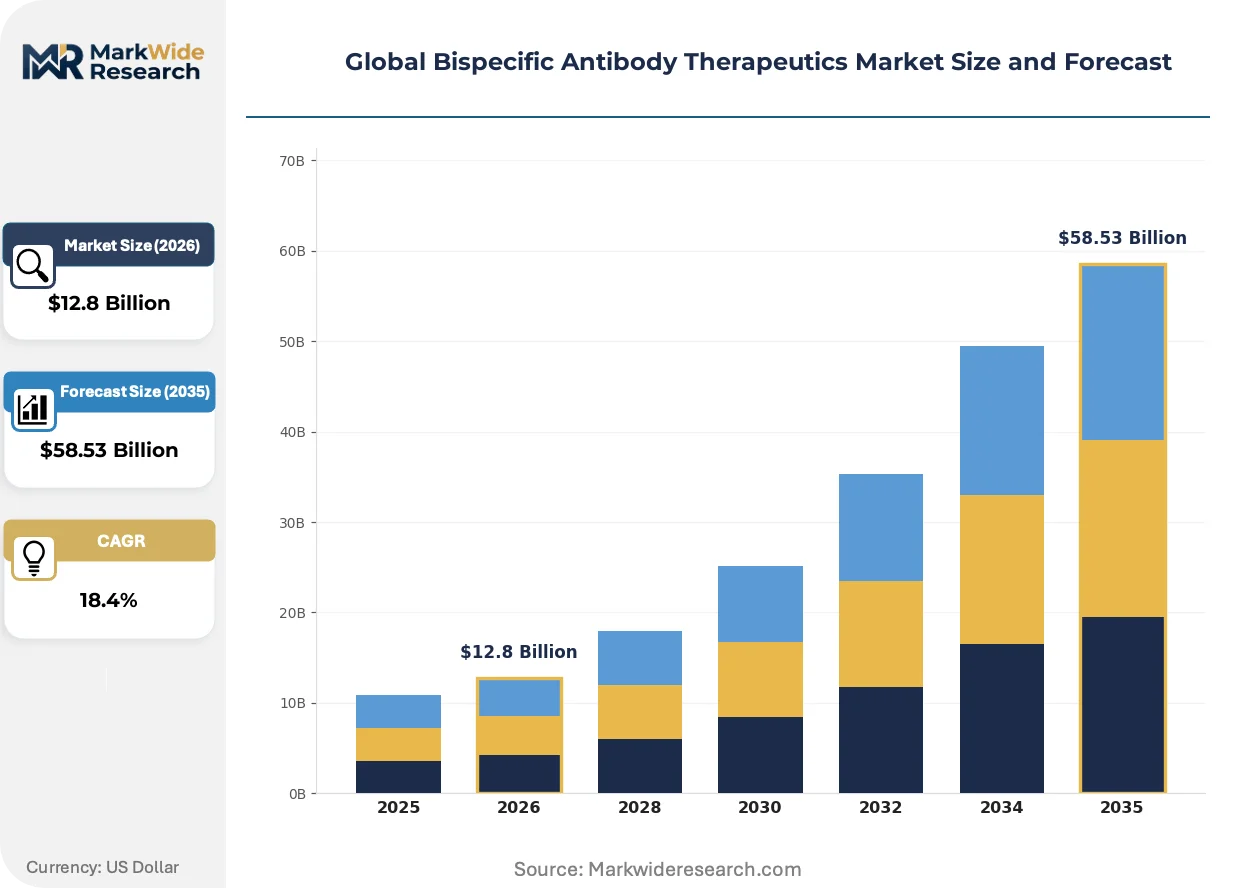
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $58.53 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IgG-like BsAbs, Fragment-based BsAbs, Fusion Protein BsAbs, Dual Variable Domain BsAbs, Others Therapy Area: Oncology, Infectious Diseases, Autoimmune Disorders, Hematological Disorders, Neurological Diseases End User: Research Institutes, Contract Research Organizations, Pharmaceutical Companies, Biotechnology Firms Delivery Technology: Intravenous Injection, Subcutaneous Injection, Intramuscular Injection, Targeted Delivery Systems |
| Companies Covered | Roche, Amgen, Genentech, Janssen, Bristol-Myers Squibb, Pfizer, AstraZeneca, Immunocore, Akeso Biopharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bispecific Antibody Therapeutics Market Shifts & Advancements
IgG-like bispecific architectures are yielding to format diversification as developers prioritize tumor penetration and manufacturing simplicity over half-life extension.
Common-light-chain technologies are displacing traditional knob-into-hole engineering for reduced immunogenicity risk and simplified downstream processing. Roche and Amgen manufacturing networks are adopting these platforms at scale for pipeline candidates. The shift is compressing development timelines and reducing regulatory CMC scrutiny for novel bispecific entrants.
FDA's Project Optimus dose-optimization mandate is reshaping oncology trial design by requiring randomized evaluations of multiple dose levels rather than maximum-tolerated-dose paradigms. Bispecific developers must now incorporate expanded cohorts and longer follow-up periods into Phase I protocols. This regulatory pivot most acutely affects T-cell engager programs where cytokine release syndrome dosing strategies require granular characterization.
Hospital pharmacy committees are consolidating formulary decisions through centralized value-assessment frameworks that weigh acquisition cost against avoided adverse-event expenditure. Community oncology practices are losing autonomy to integrated delivery network procurement offices that negotiate system-wide contracts. This concentration is most visible in United States metropolitan markets where IDN penetration exceeds sixty percent of infused therapy volume.
Global Bispecific Antibody Therapeutics Market Segmentation
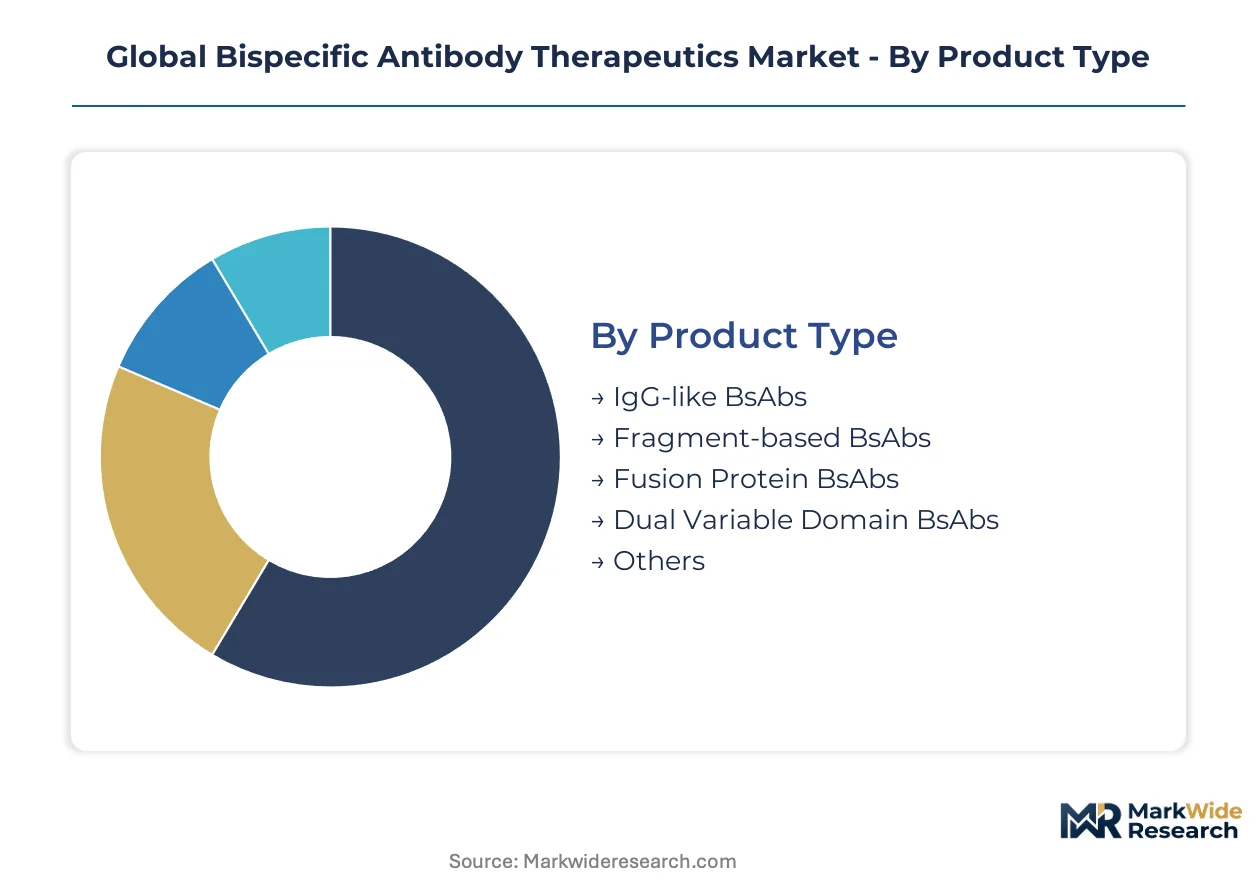
Bispecific antibody developers navigate divergent technical and commercial trade-offs across molecular formats, therapeutic applications, and administration pathways. Segmentation clarity enables precise resource allocation where manufacturing complexity, regulatory evidence requirements, and reimbursement dynamics vary substantially.
Product Type:
Fragment-based formats face intensifying substitution pressure from IgG-like alternatives as developers balance tumor penetration against pharmacokinetic durability.
- IgG-like BsAbs:Full-length immunoglobulin architectures retain Fc-mediated effector functions and extended serum half-life through neonatal Fc receptor recycling. Hospital outpatient departments in the United States and Germany prioritize these formats for reduced dosing frequency and established infusion workflows. Favorable pharmacokinetics anchor procurement decisions where site-of-care economics dominate value assessment.
- Fragment-based BsAbs:Smaller molecular constructs—BiTEs, DARTs, and nanobody fusions—achieve superior solid tumor penetration at the cost of rapid renal clearance. China's NMPA breakthrough therapy designations accelerate development timelines for these formats in hepatocellular carcinoma and gastric cancer indications. Manufacturing simplicity and reduced immunogenicity risk attract early-stage biotechnology investment.
- Fusion Protein BsAbs:Cytokine-fused or albumin-binding domain constructs extend half-life without full IgG backbone complexity.
- Dual Variable Domain BsAbs:Tandem variable region arrangements enable simultaneous binding to tumor antigen and T-cell receptor.
- Others:Emerging scaffold technologies including DARPins and antibody-like protein architectures.
IgG-like BsAbs retain volume leadership; fragment-based BsAbs hold the steepest expansion curve.
Therapy Area:
Oncology applications concentrate manufacturing investment and clinical trial enrollment, while autoimmune indications present longer development horizons with distinct regulatory evidence standards.
- Oncology:Hematological malignancies—multiple myeloma, diffuse large B-cell lymphoma, acute lymphoblastic leukemia—dominate approved indications and pipeline allocation. EMA conditional marketing authorization frameworks compress timelines for T-cell engager programs in relapsed/refractory settings. CAR-T manufacturing bottlenecks redirect institutional procurement toward off-the-shelf bispecific alternatives.
- Infectious Diseases:Bispecific neutralizing antibodies targeting HIV and respiratory syncytial virus exploit dual-epitope binding to overcome viral escape mechanisms. NIAID and CEPI funding channels support preclinical development where monoclonal antibody resistance limits therapeutic durability.
- Autoimmune Disorders:Cytokine dual-targeting approaches in rheumatoid arthritis and inflammatory bowel disease require extended safety databases.
- Hematological Disorders:Non-malignant applications including hemophilia A with inhibitors leverage bispecific cofactor mimetic mechanisms.
- Neurological Diseases:Blood-brain barrier penetration challenges constrain current development except for intrathecal delivery formats.
Oncology commands absolute revenue concentration; infectious disease applications are climbing the fastest toward proof-of-concept milestones.
End User:
Pharmaceutical company R&D budgets dwarf academic and service provider expenditure, yet contract research organizations capture expanding method development work as platform technologies fragment.
- Pharmaceutical Companies:Integrated discovery-through-commercialization operations at Roche, Amgen, and Janssen drive platform standardization and manufacturing scale. Internal cell line development capabilities and dedicated viral clearance suites constrain outsourcing appetite for late-stage candidates. Patent estate consolidation around common-light-chain and knob-into-hole technologies reinforces in-house preference.
- Biotechnology Firms:Venture-backed developers including those in Boston-Cambridge and Shanghai clusters license platform technologies to accelerate IND-enabling timelines. Lean organizational structures mandate strategic outsourcing for GLP toxicology and GMP manufacturing.
- Contract Research Organizations:Charles River and WuXi Biologics expand biologics capacity to capture bispecific cell line development and analytical characterization demand.
- Research Institutes:NIH-funded academic centers generate mechanistic insights and novel target validation.
Pharmaceutical companies retain volume leadership; biotechnology firms hold the steepest expansion curve.
Delivery Technology:
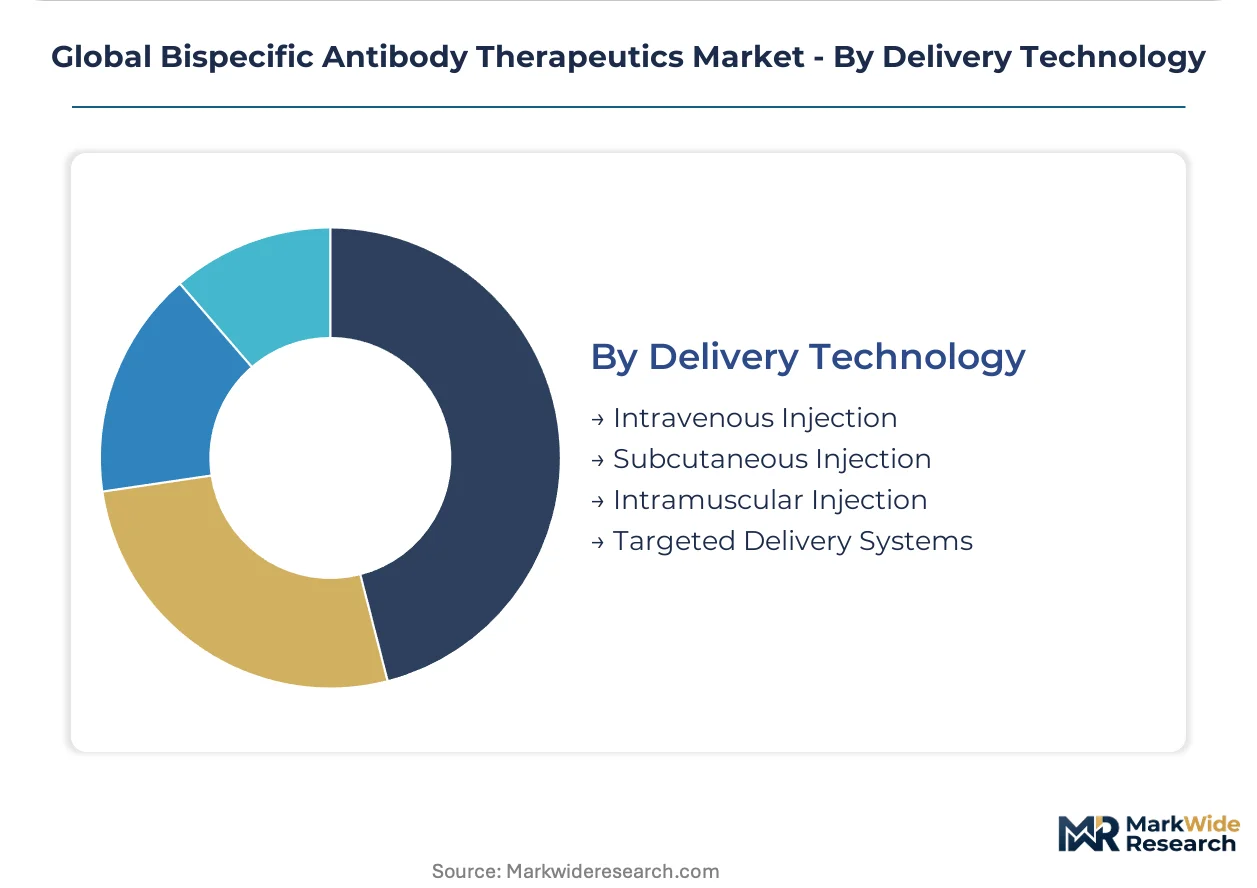
Subcutaneous administration formats are displacing intravenous dominance as device engineering and formulation science converge on outpatient-compatible delivery systems.
- Intravenous Injection:Infusion center administration remains standard for cytokine release syndrome monitoring and step-up dosing protocols. Hospital outpatient departments in the United States negotiate site-of-care differentials that marginally favor IV over subcutaneous alternatives for high-acuity initial doses.
- Subcutaneous Injection:Prefilled syringe and autoinjector compatibility enables home administration and specialty pharmacy distribution. Amgen's BiTE platform and Roche's Tecentriq subcutaneous formulation establish precedent for reduced healthcare utilization costs.
- Intramuscular Injection:Limited current application except for certain vaccine-adjuvanted bispecific constructs.
- Targeted Delivery Systems:Nanoparticle encapsulation and tumor microenvironment-activated prodrug approaches remain preclinical.
Intravenous injection retains volume leadership; subcutaneous injection holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German biopharmaceutical exports supply oncology departments across France and the Netherlands, while Chinese contract manufacturers ship intermediate biologics to United States-based finishers. The United States, Germany, China, Japan, and the United Kingdom concentrate manufacturing infrastructure, regulatory expertise, and reimbursement frameworks that govern bispecific antibody commercialization.
United States
FDA accelerated approval pathways compress development timelines for T-cell engager programs in hematological malignancies. Medicare's site-of-care payment differentials reshape hospital outpatient department economics for infused bispecific therapies. The Boston-Cambridge corridor anchors venture-backed biotechnology clusters developing novel common-light-chain platforms.
Germany
BfArM early benefit assessments under AMNOG enable rapid pricing negotiations for differentiated bispecific entrants in oncology. EMA conditional marketing authorization frameworks accelerate patient access across European hospital networks. The Munich and Heidelberg regions concentrate viral clearance and cross-flow filtration manufacturing expertise for multi-specific formats.
China
NMPA innovation drug pathways attract multinational development investment toward domestic manufacturing partnerships for solid tumor bispecifics. Breakthrough therapy designations compress review timelines for hepatocellular carcinoma indications. Shanghai and Suzhou biotech clusters scale contract development capacity for fragment-based formats targeting tumor microenvironment barriers.
Japan
PMDA sakigake designation programs expedite bispecific antibody reviews for relapsed/refractory lymphoma indications. National health insurance price premiums reward therapies demonstrating superior progression-free survival against existing standards. The Kanto region around Tokyo houses specialized cell line development facilities serving Asia-Pacific clinical trial supply.
United Kingdom
MHRA innovative licensing and access pathways facilitate early bispecific availability through managed access agreements. NHS England cancer drug fund evaluations concentrate procurement decisions for hematology-oncology therapies. The Oxford-Cambridge-London golden triangle sustains academic-industry partnerships for novel target validation and mechanistic research.
Global Bispecific Antibody Therapeutics Market Competitive Landscape
Listed leaders compete with private specialists across platform technology ownership and manufacturing scale. The market structures around three tiers: integrated pharmaceutical conglomerates with end-to-end biologics infrastructure, venture-backed biotechnology firms licensing proprietary formats, and contract research organizations capturing outsourced method development. Strategic archetypes include Fc-engineering platform holders, T-cell engager specialists, and common-light-chain technology licensors. Competitive moves concentrate on manufacturing capacity expansion and strategic partnerships for cell line development.
Within the integrated pharmaceutical tier, Roche and Amgen exemplify platform-scale competitors, while Janssen occupies a differentiated position across multiple myeloma indications. Roche represents the IgG-like bispecific archetype with established manufacturing workflows, Amgen anchors T-cell engager development through its BiTE platform, and Janssen illustrates dosing strategy differentiation in competitive hematology markets. These three entities collectively demonstrate how regulatory acceleration, subcutaneous delivery investment, and step-up dosing protocol refinement shape competitive positioning in hospital-based oncology procurement.
| Leading Market Players |
|---|
| Roche |
| Amgen |
| Genentech |
| Janssen |
| Bristol-Myers Squibb |
| Pfizer |
| AstraZeneca |
| Immunocore |
| Akeso Biopharma |
| Others |
Supply & Pricing Matrix
Common-light-chain platform substitution for knob-into-hole engineering is redrawing manufacturing geography toward Germany and the United States while compressing purification resin costs and flattening price premiums for novel bispecific entrants.
Pricing Analysis
Current-generation IgG-like bispecifics command premium positioning against fragment-based predecessors, while next-generation subcutaneous formats threaten to collapse infusion-center economics entirely. Pricing stratifies across premium, standard, and economy tiers anchored by Fc-engineering sophistication, viral clearance certification grade, and geographic delivery cost differentials. Cost compression in fragment-based segments is intensifying because China's NMPA breakthrough designations accelerate domestic manufacturing scale-up. Community hospital systems exhibit acute price sensitivity; integrated delivery networks with captive GPO contracts demonstrate relative inelasticity.
Supply Chain Analysis
Strategic stockpile preferences dominate bioprocessing inputs as dual-variable-domain cell line development cycles extend and viral clearance resin lead times stretch. Manufacturing concentrates in Germany, the United States, and China, each feeding distinct regulatory approval pathways. Supply chains draw from specialized CHO cell banks, protein A purification resins, and single-use bioreactor components. Single-source vulnerability concentrates in cross-flow filtration membrane supply. Distribution runs through hospital outpatient departments, specialty pharmacy networks, and emerging home-infusion channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection is reshaping competitive returns as common-light-chain interoperability standards enable developer switching costs and manufacturing network effects.
For Market Incumbents: Compound manufacturing scale advantages through backward integration into CHO cell line development and viral clearance suite capacity in the United States and Germany. Lock in GPO formulary position through step-up dosing protocol standardization that raises switching costs for hospital systems facing T-cell engager substitution threats from emerging BiTE competitors. For New Entrants and Emerging Players: Differentiate on solid tumor penetration mechanics where IgG-like formats fail and fragment-based architectures achieve superior microenvironment access. Target hepatocellular carcinoma and gastric cancer indications in China where NMPA breakthrough pathways compress development timelines and domestic manufacturing partnerships lower regulatory friction. Pursue licensing arrangements with established CDMOs rather than captive capacity buildout. For Investors and Strategic Acquirers: Secondary-cycle assets sit with venture-backed biotechnology firms holding Phase I-ready common-light-chain platforms but lacking GMP manufacturing infrastructure. Five-to-ten-year viability hinges on subcutaneous delivery technology maturation and AMNOG pricing negotiation outcomes in Germany. Watch FDA Project Optimus dose-optimization enforcement intensity as the signal indicating regulatory burden expansion or contraction for T-cell engager programs.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Amgen and Roche expansion of BiTE and IgG-like capacity tightens CDMO availability for competitors. |
| Regulatory Approval Pathway | FDA accelerated approval and EMA conditional authorization compress timelines but intensify post-market evidence obligations. |
| Licensing Agreement | Common-light-chain technology transfers from Roche to Asian biotechnology partners reshape platform access economics. |
| Clinical Trial Advancement | Janssen's multiple myeloma dosing strategy refinement under Project Optimus establishes precedent for T-cell engager trials. |
| Pipeline Diversification | Akeso Biopharma and domestic Chinese developers expand solid tumor bispecific pipelines beyond hematology saturation. |
Research Methodology
The analysis maps IgG-like, fragment-based, fusion protein, and dual-variable-domain bispecific formats, each validated through drug development executives, regulatory affairs leads, hospital formulary directors, and payer access specialists. Primary interview data triangulates against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient-flow modeling and top-down revenue reconciliation ensure cross-validation across molecular format and therapy area segments.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segments by product architecture, therapeutic application, delivery technology, and regional regulatory cluster. CAGRs derive from patient population incidence projections, pricing elasticity assumptions, and manufacturing capacity expansion schedules. Forecast inputs incorporate step-up dosing protocol adoption curves and subcutaneous delivery technology penetration rates.
The analysis sits within stated boundaries; outcomes outside sustained FDA accelerated approval pathway utilization or EMA conditional marketing authorization retention would require recalibration. Forecasts reflect assumptions regarding CAR-T manufacturing bottleneck persistence and Medicare site-of-care payment differential stability. Revision becomes warranted when cytokine release syndrome management protocol standardization crosses institutional credentialing thresholds or when China's NMPA innovation drug pathway throughput exceeds domestic manufacturing partnership capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Thyroid Cancer Drugs Market
Pharmaceuticals
Global Online Pharmacy Market
Pharmaceuticals
Global Finasteride Market
Pharmaceuticals
Conjunctivitis Drugs Market
Pharmaceuticals
Injectable Targeted Therapy Market
Pharmaceuticals
Global Hemostasis and Tissue Sealing Agents Market
Pharmaceuticals
Global Janus Kinase Inhibitor (JAK) Market
Pharmaceuticals
Antibody Therapy Market
Pharmaceuticals
BRAF-MEK Inhibitors Market
Pharmaceuticals
Europe Sodium-Dependent Glucose Cotransporter 2 Market
Pharmaceuticals
Alectinib Drugs Market
Pharmaceuticals
Global Immuno Oncology Drugs Market
Pharmaceuticals
Canine Dilated Cardiomyopathy Drugs Market
Pharmaceuticals
Global Exocrine Pancreatic Insufficiency (EPI) Market
Pharmaceuticals
Global Orally Disintegrating Tablet Market
Pharmaceuticals
Global Two Piece Empty Hard Capsule Market