
 Non-Sterile Liquids/Suspensions Market | 2026-2036
Non-Sterile Liquids/Suspensions Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Sterile Liquids/Suspensions Market Analytics
Premium oral solutions and commodity topical suspensions is decoupling along excipient quality and cold-chain handling standards. Pfizer Inc. leverages its biopharma manufacturing footprint to anchor high-margin pediatric liquid portfolios in regulated markets. Dr. Reddy's Laboratories competes on API-backward integration into non-sterile suspensions for cost-sensitive geographies. Sanofi differentiates through preservative-system R&D that extends shelf life in tropical distribution corridors.
Non-sterile liquids and suspensions comprise aqueous or oil-based dispersions containing dissolved or suspended active pharmaceutical ingredients, typically formulated within defined pH ranges of 3.5 to 7.5 and viscosity specifications measured in centipoise for accurate dosing and patient compliance. These dosage forms serve primarily as alternatives for patients unable to swallow solid tablets, including pediatric, geriatric, and dysphagic populations across human and veterinary medicine. Oral solutions command the largest revenue pool due to manufacturing scalability and bioavailability advantages, while topical suspensions represent the fastest-expanding segment driven by dermatology and wound-care demand. Liquid fill powders occupy a niche margin position where stability and reconstitution convenience justify premium positioning in hospital and home care channels.
FDA Current Good Manufacturing Practice regulations for pharmaceutical quality systems shape batch-release protocols and facility inspection frequency for US-bound non-sterile liquids. EMA's Quality Guidelines and REACH chemical safety standards govern excipient sourcing and environmental release thresholds for European manufacturing and import. India's CDSCO and BIS packaging standards mandate child-resistant closures and label declarations that dictate bottle and sachet procurement decisions for domestic and export formulations. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and IP monographs to avoid reformulation costs and market access delays.
Market Dynamics
CDSCO stability requirement tightening is forcing Indian pharmaceutical manufacturers to revalidate shelf-life protocols and upgrade analytical testing infrastructure for oral solutions and topical suspensions bound for regulated markets.
Growth Catalysts
- Pediatric formulation demand:Dysphagic and geriatric populations in the United States, Germany, and Japan sustain volume for swallowable liquid medicines as tablet alternatives face compliance barriers.
- EMA Quality Guidelines harmonization:Excipient sourcing standardization across REACH chemical safety thresholds is streamlining cross-border batch release for European manufacturing and import channels.
- Dermatology suspension volumes:Topical wound-care applications are expanding faster than oral solutions, driven by ambulatory surgical center protocols and home-care channel growth.
Market Restraints
- API cost volatility:Backward integration into active pharmaceutical ingredient production requires capital-intensive fermentation and synthesis capacity that mid-tier formulators cannot finance.
- Cold-chain infrastructure gaps:Tropical distribution corridors in Southeast Asia and sub-Saharan Africa lack validated temperature-controlled logistics for preservative-sensitive liquid formulations.
- Pharmacopeial divergence:USP, EP, and IP monograph misalignment on dissolution testing and impurity thresholds forces parallel stability studies and redundant documentation.
Strategic Opportunities
- Liquid fill powder niches:Hospital and home care channels in Japan are accepting premium positioning for reconstitution-convenient formats that reduce shipping weight and extend shelf life.
- Preservative-system R&D:Novel antimicrobial complexes that function in high-humidity climates open access to distribution networks previously limited by mold and yeast contamination risks.
- PLI scheme manufacturing:India's production-linked incentive framework is subsidizing dedicated non-sterile liquid lines for export-oriented contract development and manufacturing organizations.
Industry Challenges
- Analytical chemist scarcity:HPLC and mass spectrometry proficiency for forced degradation studies and impurity profiling outpaces training pipeline output in emerging manufacturing hubs.
- Legacy equipment retrofit costs:Existing tank farms and filling lines require stainless steel upgrades, in-line viscosity monitoring, and isolator integration to meet current FDA Current Good Manufacturing Practice expectations.
- Label declaration compliance:Child-resistant closure validation and multi-language sachet printing create procurement bottlenecks when BIS packaging standards revise without grandfathering provisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Sterile Liquids/Suspensions Market |
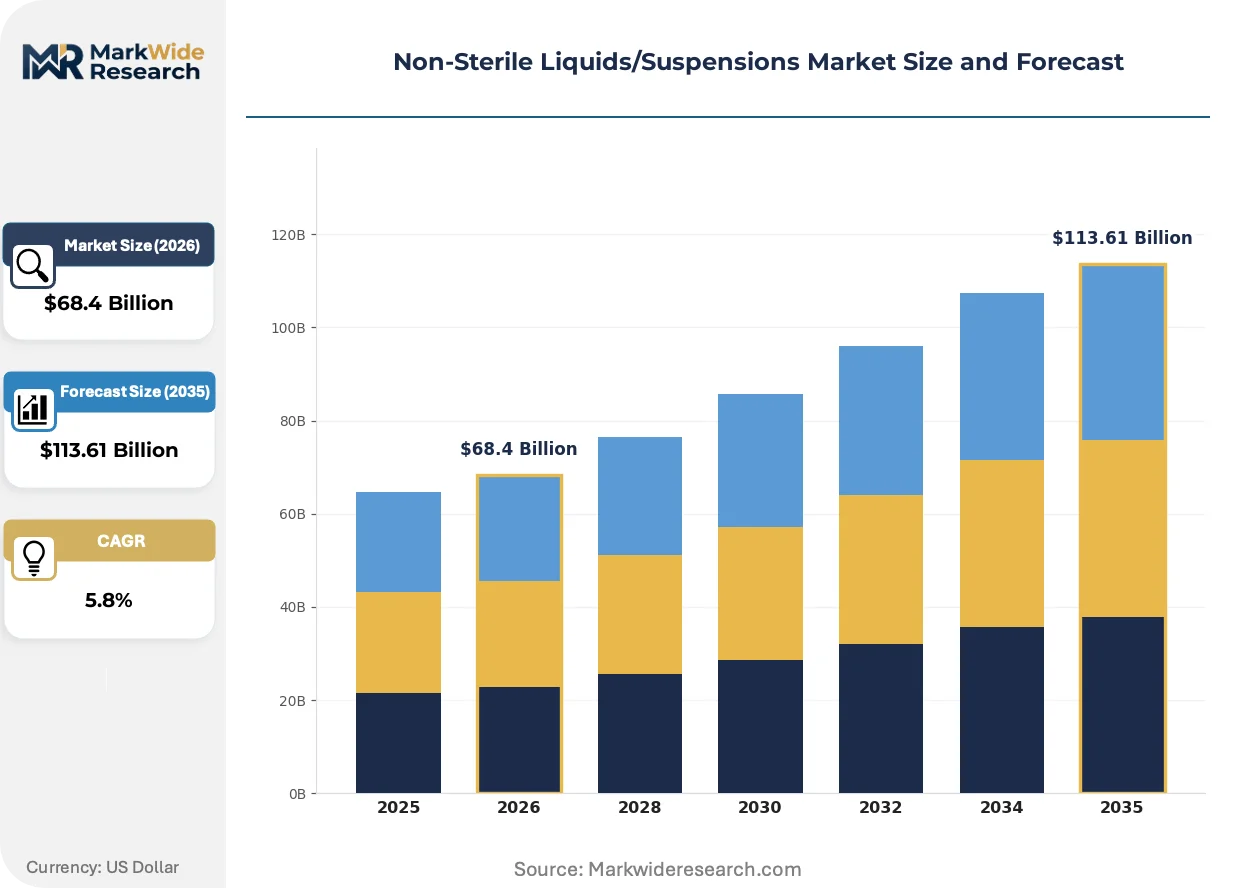
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $113.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Solutions, Topical Suspensions, Liquid Fill Powders, Emulsions End User: Pharmacies, Hospitals, Clinics, Home Care Application: Pediatric Care, Geriatric Care, Veterinary Use, Personal Care Packaging Type: Bottles, Sachets, Blisters, Jars |
| Companies Covered | Teva Pharmaceutical Industries, Sanofi, Pfizer Inc., Dr. Reddy's Laboratories, Catalent Pharma Solutions, Novartis, GlaxoSmithKline, Sun Pharmaceutical Industries, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Sterile Liquids/Suspensions Market Evolving Landscape
Continuous manufacturing platforms and single-use bioprocessing technologies are compressing batch cycle times and reducing cross-contamination risk in multi-product liquid formulation facilities.
Single-use mixing and storage systems for aqueous suspensions is overtaking fixed stainless steel tank infrastructure in new facility builds. Contract manufacturers serving pediatric portfolios in North America are adopting disposable fluid contact surfaces to eliminate CIP/SIP validation burdens. This shift is compressing capital deployment timelines from thirty-six months to eighteen months for greenfield liquid dosage sites.
REACH chemical safety standards are tightening excipient impurity disclosure thresholds for European-bound formulations. Manufacturers must now document full supply chain composition for surfactants and co-solvents previously treated as proprietary blends. Pediatric oral solutions containing polysorbates and propylene glycol face heightened analytical scrutiny and reformulation pressure.
Hospital procurement consortia are consolidating vendor panels and demanding real-time batch release documentation through electronic data interchange portals. Home care distributors in Germany are displacing traditional wholesale relationships with direct-to-patient subscription models for chronic condition liquid medicines. This channel restructuring concentrates volume with logistics-integrated formulators capable of cold-chain last-mile delivery.
Non-Sterile Liquids/Suspensions Market Segmentation
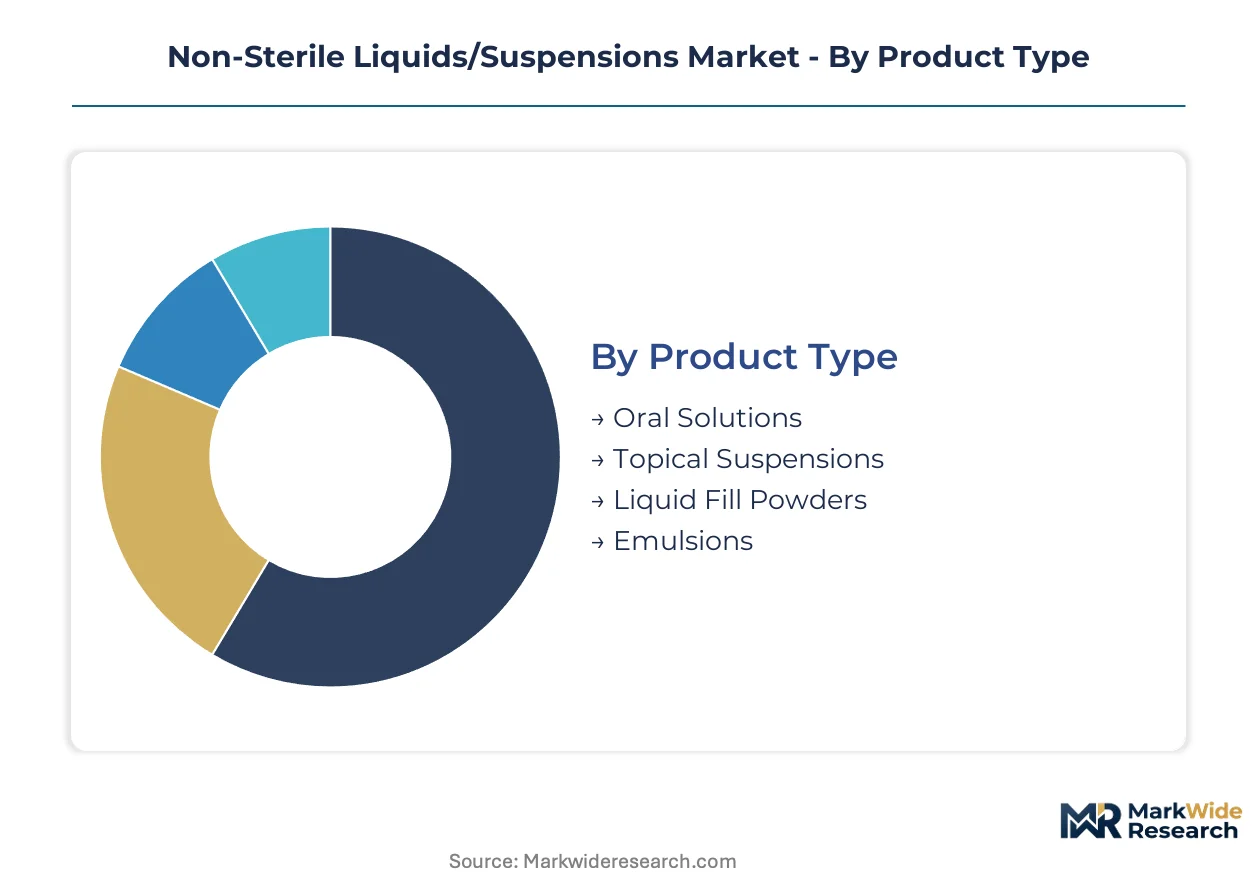
Non-sterile liquids and suspensions serve heterogeneous patient populations with divergent swallowing capabilities, dosing precision needs, and storage constraints. Segmentation reveals where formulation complexity, packaging compliance, and distribution economics concentrate margin capture.
Product Type:
Customization intensity spans from commodity aqueous solutions to engineered emulsion systems requiring specialized stability protocols.
- Oral Solutions:Homogeneous aqueous or hydroalcoholic systems with dissolved APIs formulated within tight pH windows for pediatric and geriatric compliance. Demand concentrates in United States retail pharmacies where dysphagic patient populations and Medicare reimbursement sustain volume.
- Topical Suspensions:Heterogeneous dispersions with suspended insoluble actives requiring viscosity control and resuspendability testing. Dermatology applications in German ambulatory surgical centers and Japanese wound-care protocols drive fastest expansion as post-operative home-care protocols displace inpatient stays.
- Liquid Fill Powders:Lyophilized or spray-dried formulations reconstituted at point of use. Hospital procurement in Japan accepts premium positioning for reduced cold-chain burden.
- Emulsions:Thermodynamically unstable oil-in-water or water-in-oil systems demanding surfactant optimization and accelerated stability programs. Veterinary applications in tropical corridors exploit extended shelf-life potential.
Leading the category by volume: Oral Solutions. Growing fastest: Topical Suspensions.
End User:
Channel concentration shifts from institutional procurement consortia toward direct-to-patient logistics as chronic condition management migrates outpatient.
- Pharmacies:Community and retail dispensaries handling high-SKU pediatric portfolios with child-resistant closure compliance. United States independent pharmacies and German Apotheken sustain volume through insurance reimbursement density.
- Hospitals:Acute care institutions with formulary committees demanding real-time batch release documentation. Japanese hospital consortia are consolidating vendor panels and displacing traditional wholesale relationships.
- Clinics:Outpatient facilities with limited storage capacity favoring single-unit sachet formats. Indian primary health centers under CDSCO procurement mandates.
- Home Care:Direct-to-patient distributors managing cold-chain last-mile delivery for chronic condition liquid medicines. German subscription models for geriatric compliance are gaining share fastest.
Dominant channel by prescription volume: Pharmacies. Steepest expansion trajectory: Home Care.
Application:
Demographic targeting aligns formulation palatability, dosing flexibility, and caregiver burden reduction with patient physiological constraints.
- Pediatric Care:Flavor-masked solutions with calibrated dosing devices for weight-based titration. United States demand sustains volume through FDA pediatric exclusivity incentives and caregiver compliance preferences.
- Geriatric Care:Low-viscosity formulations with easy-open packaging for arthritic populations. Japan's aging demographic and polypharmacy burden concentrate demand.
- Veterinary Use:Palatable suspensions for companion animal compliance. Tropical distribution corridors lacking cold-chain infrastructure favor preservative-robust emulsions.
- Personal Care:Cosmetic and wellness liquids outside pharmaceutical regulatory scope. Niche positioning with minimal GMP burden.
Primary demand anchor: Pediatric Care. Climbing fastest: Geriatric Care.
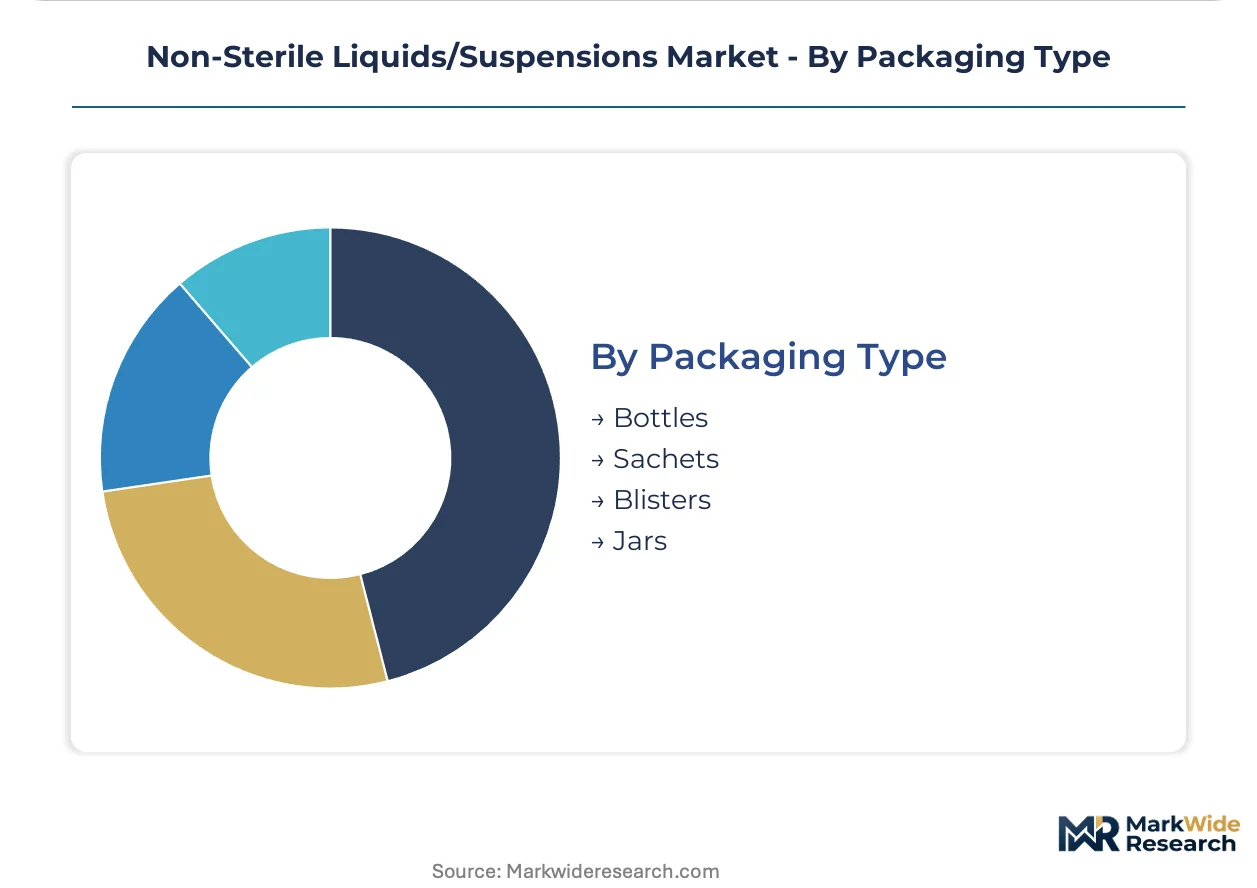
Packaging Type:
Unit economics and regulatory compliance intensity separate high-volume bottle formats from premium single-unit presentations.
- Bottles:Multi-dose HDPE or PET containers with child-resistant closures and graduated dosing devices. Indian BIS standards and United States 16 CFR 1700 compliance dictate procurement specifications.
- Sachets:Single-use flexible films with precise unit dosing and minimal storage footprint. Japanese hospital and home care channels accept premium positioning for convenience.
- Blisters:Unit-dose thermoformed cavities with barrier properties for hygroscopic powders. Limited penetration in liquid formats due to seal integrity challenges.
- Jars:Wide-mouth containers for topical suspensions requiring spatula or finger application. Dermatology and veterinary segments sustain volume.
Highest shipment volume: Bottles. Gaining share fastest: Sachets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyderabad anchors formulation activity for non-sterile liquids, with the Genome Valley corridor housing dedicated pediatric liquid lines and analytical testing infrastructure serving regulated export markets.
United States
Pediatric dysphagic populations and Medicare reimbursement density sustain volume for oral solutions in retail pharmacy channels. FDA Current Good Manufacturing Practice regulations enforce batch-release protocols and facility inspection frequency that shape capital deployment decisions. New Jersey's pharmaceutical corridor concentrates contract manufacturing capacity for high-margin liquid portfolios bound for hospital procurement consortia.
Germany
Geriatric polypharmacy and ambulatory surgical center protocols drive topical suspension demand through Apotheken and home-care subscription models. EMA Quality Guidelines and REACH chemical safety standards govern excipient sourcing and environmental release thresholds for manufacturing and import. The Rhine-Main region clusters logistics-integrated formulators capable of cold-chain last-mile delivery for chronic condition medicines.
India
API-backward integration and export-oriented contract manufacturing capacity expansion concentrate in oral solutions and topical suspensions. CDSCO stability requirement tightening and BIS packaging standards mandate child-resistant closures and label declarations that dictate procurement specifications. Gujarat's pharmaceutical belt scales dedicated non-sterile liquid lines under PLI scheme subsidies for regulated market exports.
Japan
Aging demographics and hospital formulary consolidation sustain premium positioning for liquid fill powders and low-viscosity geriatric formulations. PMDA pharmacopeial alignment with USP and EP monographs streamlines batch release documentation for vendor panels. The Kansai corridor around Osaka hosts reconstitution-convenient format specialists serving hospital and home care channels.
Non-Sterile Liquids/Suspensions Market Competitive Landscape
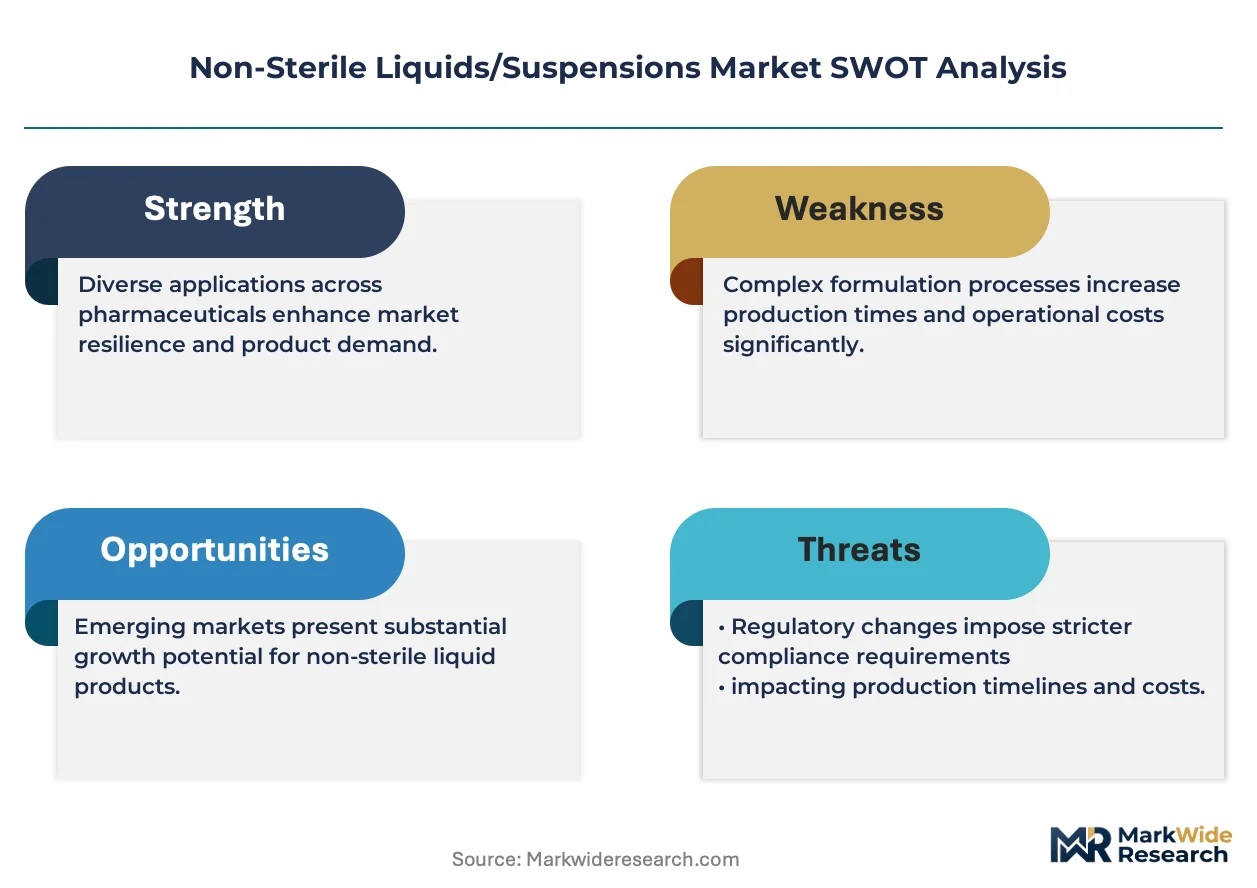
Capital-heavy producers compete with asset-light designers across the non-sterile liquids landscape, with integrated API-to-formulation operations commanding margin capture against contract development specialists. The structure tiers across multinational patent-holders, regional generic houses, and CDMO platforms. Three archetypes dominate: backward-integrated Indian formulators, biopharma-anchored Western multinationals, and preservative-system R&D specialists. Capacity expansion and strategic partnerships constitute the primary competitive moves, with single-use manufacturing technology licensing accelerating greenfield deployment timelines.
Within the multinational tier, Pfizer Inc. and Sanofi occupy positions exemplifying divergent specialization vectors—Pfizer anchoring biopharma manufacturing footprint for pediatric liquid portfolios, Sanofi representing preservative-system R&D investment for tropical distribution corridors. Among Indian formulators, Dr. Reddy's Laboratories exemplifies API-backward integration archetypes competing on cost-sensitive geography access. Teva Pharmaceutical Industries sits within the generic-specialist tier, its geographic origin and corporate structure signaling scale-driven oral solution capacity.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries |
| Sanofi |
| Pfizer Inc. |
| Dr. Reddy's Laboratories |
| Catalent Pharma Solutions |
| Novartis |
| GlaxoSmithKline |
| Sun Pharmaceutical Industries |
| Johnson & Johnson |
| Others |
Value Network & Pricing Analysis
Single-use bioprocessing technology adoption is compressing capital deployment timelines from thirty-six months to eighteen months for greenfield liquid dosage sites, simultaneously lowering entry barriers for contract manufacturers and fragmenting pricing power across pediatric formulation specialists. This manufacturing transition concentrates margin capture with logistics-integrated formulators capable of cold-chain last-mile delivery while commoditizing standard oral solution production.
Pricing Analysis
Yield-guaranteed throughput contracts anchor value-based pricing for hospital procurement consortia demanding real-time batch release documentation. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified pediatric portfolios from BIS-compliant domestic formulations and unregulated veterinary suspensions. Cost compression in commodity topical suspensions is intensifying because Indian API-backward integration is flooding export markets with capacity. Price-sensitive government clinics in India and Southeast Asia drive volume at economy tiers, while Japanese hospital formulary committees accept premium positioning for reconstitution-convenient formats.
Supply Chain Analysis
Excipient supply rests on German specialty chemical producers for surfactant complexes, Indian fermentation-derived API manufacturers for active pharmaceutical ingredients, and Chinese packaging converters for HDPE bottles and flexible films. Raw material dependencies include polysorbates facing REACH disclosure scrutiny, propylene glycol subject to pediatric safety alerts, and child-resistant closure resins governed by BIS standards. Single-source vulnerability in HPLC column and mass spectrometry consumables creates analytical testing bottlenecks for forced degradation studies. Distribution runs through German direct-to-patient subscription models, United States retail pharmacy chains, and Japanese hospital procurement consortia consolidating vendor panels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous manufacturing platforms are displacing fixed stainless steel tank infrastructure, creating a technology-transition phase where legacy equipment retrofit costs stratify competitive viability between capital-heavy incumbents and asset-light entrants.
For Market Incumbents: To counter single-use manufacturing technology licensing from CDMOs compressing greenfield deployment timelines, Pfizer Inc. and Sanofi should deepen backward integration into preservative-system R&D for tropical distribution corridors while retrofitting existing tank farms with in-line viscosity monitoring to meet FDA Current Good Manufacturing Practice expectations. Capacity addition in Gujarat's pharmaceutical belt under PLI scheme subsidies secures cost-competitive export positioning for regulated markets.
For New Entrants and Emerging Players: Home care distributors managing chronic condition liquid medicines in Germany represent the most penetrable buyer archetype, as direct-to-patient subscription models displace traditional wholesale relationships and concentrate volume with logistics-integrated formulators. Liquid fill powder niches in Japanese hospital channels accept premium positioning for reduced cold-chain burden. A regulatory-first go-to-market angle leveraging PMDA pharmacopeial alignment with USP and EP monographs streamlines vendor panel access.
For Investors and Strategic Acquirers: Exit pathways concentrate in contract development and manufacturing organization platforms with dedicated non-sterile liquid lines and analytical testing infrastructure serving regulated export markets. Long-term viability over the projection horizon hinges on preservative-system intellectual property portfolios and single-use manufacturing technology licensing agreements. The inflection signal to watch is CDSCO stability requirement tightening forcing shelf-life protocol revalidation and analytical chemist hiring acceleration across Indian formulators.
| Strategic Initiative | Industry Significance |
|---|---|
| Preservative-System R&D Investment | Novel antimicrobial complexes extend shelf life in high-humidity Southeast Asian and sub-Saharan African corridors. |
| Single-Use Manufacturing Technology Licensing | Disposable fluid contact surfaces eliminate CIP/SIP validation burdens for North American pediatric portfolios. |
| PLI Scheme Manufacturing Scale-Up | Indian production-linked incentives subsidize dedicated non-sterile liquid lines for export-oriented CDMOs. |
| Backward Integration into API Production | Dr. Reddy's Laboratories anchors cost-sensitive geography access through captive fermentation and synthesis capacity. |
| Direct-to-Patient Subscription Launch | German home care distributors displace wholesale relationships for chronic condition liquid medicines. |
Research Methodology
Multi-period observation of CDSCO stability requirement tightening, FDA facility inspection frequency, and EMA excipient sourcing standardization anchored the trend analysis, supplemented by interviews with regulatory affairs leads at Indian export-oriented formulators, formulary directors at Japanese hospital consortia, procurement managers at German home care distributors, and analytical testing directors at Hyderabad CDMOs. Secondary validation drew from FDA Current Good Manufacturing Practice guidance documents, EMA Quality Guidelines, CDSCO submission databases, USP-EP-IP pharmacopeial harmonization records, and REACH chemical safety threshold disclosures. Bottom-up patient population modeling and top-down pharmaceutical manufacturing capacity assessments were triangulated.
Segment-weighting across product type, end user, application, packaging format, and regional regulatory cluster shaped volume and value outputs throughout the forecast period. CAGRs were derived from longitudinal tracking of oral solution and topical suspension shipment volumes, pricing stratification across premium-standard-economy tiers, and capacity utilization rates at Genome Valley and Gujarat pharmaceutical belt facilities. Industry-specific forecast inputs included pediatric dysphagic population demographics in the United States, geriatric polypharmacy burden in Japan, and ambulatory surgical center protocol expansion in Germany.
Revisions become necessary when pharmacopeial divergence between USP, EP, and IP monographs forces parallel stability studies, when cold-chain infrastructure gaps in tropical corridors trigger preservative-system reformulation, or when analytical chemist scarcity outpaces training pipeline output. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Obsessive Compulsive Disorder (OCD) Drug Market
Pharmaceuticals
Global Non-Alcoholic Fatty Liver Disease (NAFLD) Drug Market
Pharmaceuticals
Antiglaucoma Drugs Market
Pharmaceuticals
Fucosidosis Therapeutics Market
Pharmaceuticals
BRAF-MEK Inhibitors Market
Pharmaceuticals
Cyclosporine Drugs Market
Pharmaceuticals
Long-Acting Insulin Market
Pharmaceuticals
HPV Vaccines Market
Pharmaceuticals
Viscosupplementation Market
Pharmaceuticals
Global Respiratory Drug Market
Pharmaceuticals
Global Hormonal Contraceptives Market
Pharmaceuticals
Global Pericarditis Drugs Market
Pharmaceuticals
Europe Pharmaceutical Warehousing Market
Pharmaceuticals
Istradefylline API Market
Pharmaceuticals
Global Hemostasis and Tissue Sealing Agents Market
Pharmaceuticals
Ophthalmic Drug Delivery Systems Market