
 Apocarotenal Market | 2026-2036
Apocarotenal Market Size, Share, and Industry Trends Forecast 2026-2036
Apocarotenal Market Outlook
Ingredient customization revenue is narrowing as synthetic apocarotenal margins compress against natural extraction alternatives. DSM Nutritional Products Ltd leverages its integrated biotechnology platforms to sustain premium positioning in fermented natural variants. Allied Biotech anchors its competitiveness through concentrated supply relationships with Asian pharmaceutical formulators. Divis Laboratories differentiates via captive fermentation capacity that controls raw material quality from strain to finished extract.
Apocarotenal denotes a group of carotenoid-derived compounds—specifically 8'-apo-beta-caroten-8'-al and related aldehydes—produced through either chemical synthesis or microbial fermentation of plant-derived precursors, functioning primarily as orange-yellow colorants and provitamin A precursors in formulated products. The natural product type segment captures expanding margin pools as clean-label procurement policies at European and North American food manufacturers displace synthetic alternatives. Pharmaceutical applications represent the fastest-growing demand channel, driven by apocarotenal incorporation into ophthalmic supplements and antioxidant formulations where bioavailability specifications exceed general food-grade requirements.
FDA color additive regulations under 21 CFR 73.300 govern apocarotenal deployment in U.S. food matrices, while EFSA's re-evaluation of carotenoid safety profiles shapes permissible exposure thresholds across European formulations. The EU Green Deal's sustainable chemistry mandates are redirecting capital toward fermentation-based production methods that reduce solvent intensity in extraction processes. Stakeholders must monitor evolving pharmacopeial monograph standards for carotenoid purity as pharmaceutical applications claim a larger share of qualified supply.
Market Dynamics
Clean-label procurement mandates at European and North American food manufacturers are systematically displacing synthetic apocarotenal formulations, compressing margin structures for chemical synthesis routes while expanding qualified supply requirements for fermentation-derived natural variants.
Growth Catalysts
- REACH chemical framework:The EU's tightening registration requirements are accelerating manufacturer reformulation toward natural carotenoid sources that bypass synthetic additive scrutiny.
- Fortified beverage expansion:Food and beverage manufacturers are expanding apocarotenal deployment as a natural colorant in fortified juices and dairy alternatives across Germany and France.
- Fermentation biotechnology:Microbial production methods are reducing solvent intensity in extraction processes, aligning with EU Green Deal sustainable chemistry mandates.
Market Restraints
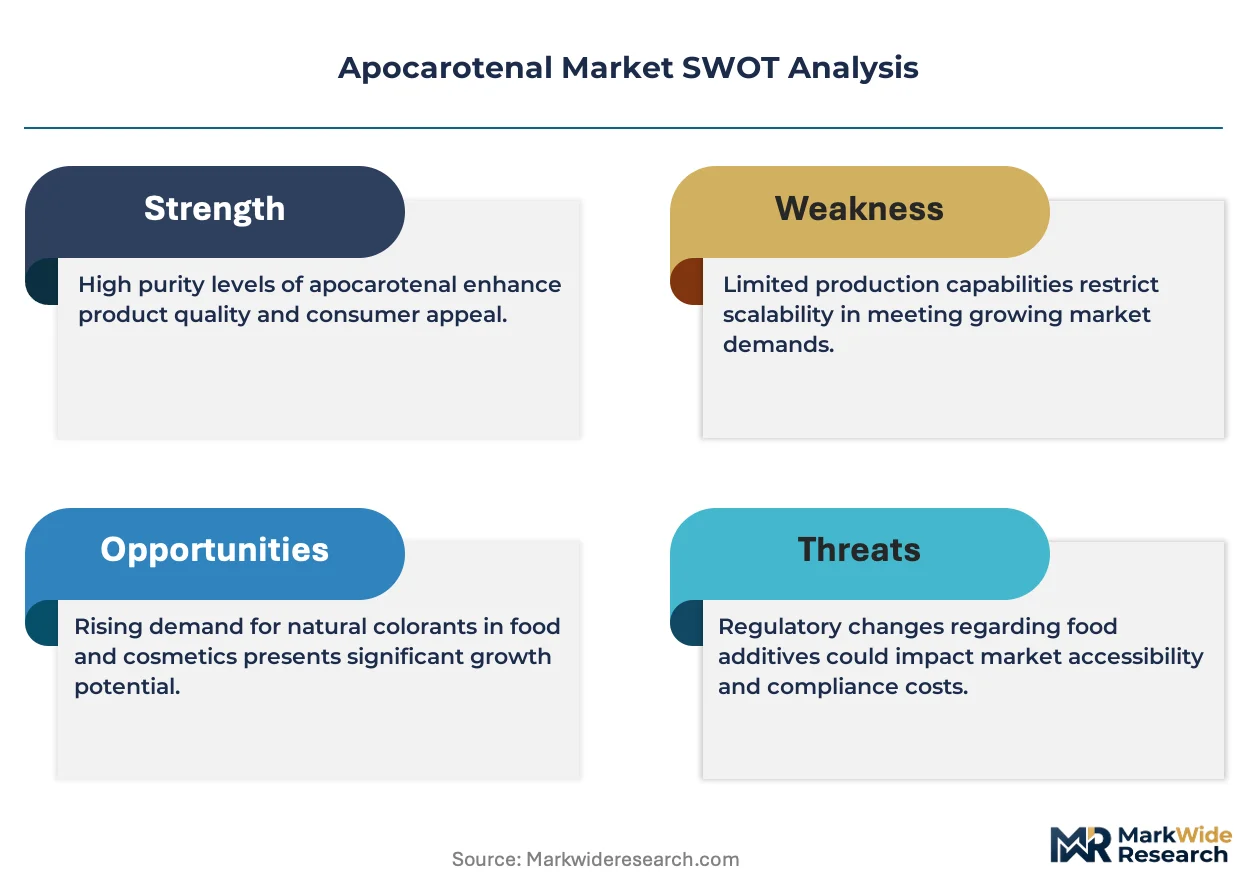
- Raw material concentration:Captive fermentation capacity concentrates among limited biotech platforms, creating supply vulnerability for pharmaceutical-grade specifications.
- Bioavailability thresholds:Ophthalmic supplement applications demand carotenoid purity levels that exceed general food-grade extraction yields, constraining qualified supplier pools.
- Synthetic margin compression:Chemical synthesis routes face narrowing margins as natural extraction alternatives capture premium positioning in clean-label procurement policies.
Strategic Opportunities
- Pharmaceutical formulators:Antioxidant formulations and ophthalmic supplements represent underpenetrated demand channels with bioavailability specifications exceeding current food-grade supply.
- Asian pharmaceutical partnerships:Concentrated supply relationships with pharmaceutical formulators in India and China offer volume expansion outside European market saturation.
- Pharmacopeial standard evolution:Evolving monograph standards for carotenoid purity create qualification barriers that favor suppliers with integrated strain-to-extract control systems.
Industry Challenges
- Fermentation scale-up capex:Captive bioreactor capacity requires substantial capital deployment to achieve pharmaceutical-grade contamination control and batch consistency.
- Dual regulatory compliance:Manufacturers must simultaneously satisfy FDA 21 CFR 73.300 color additive regulations and EFSA re-evaluation timelines for carotenoid safety profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Apocarotenal Market |
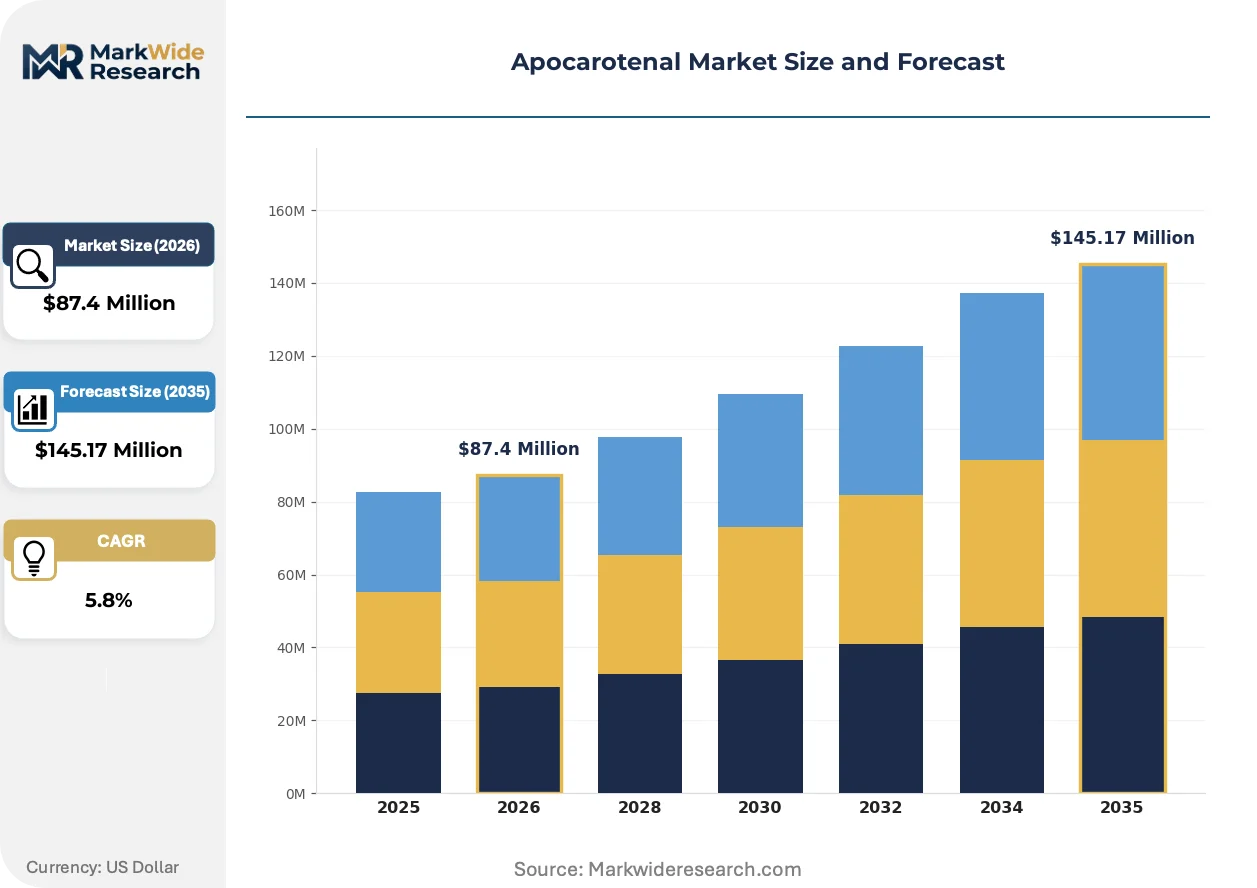
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $145.17 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Organic, Inorganic Application: Food & Beverage, Pharmaceuticals, Cosmetics, Nutraceuticals End User: Food Manufacturers, Cosmetic Companies, Nutraceutical Firms, Pharmaceutical Producers Distribution Channel: Online, Offline, Direct Sales, Distributors |
| Companies Covered | DSM Nutritional Products Ltd, Allied Biotech, Divis Laboratories, D.D. Williamson & Co., Inc., Sensient Technologies Corporation, BASF Corp, Valensa International, LLC, Kanegrade Ltd., Döhler Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Apocarotenal Market Strategic Shifts
Fermentation-based production platforms are collapsing the cost premium between natural and synthetic apocarotenal sources, while regulatory re-evaluations of carotenoid safety profiles are reshaping permissible exposure thresholds across formulated products.
Microbial fermentation of plant-derived precursors is collapsing the historical cost gap between synthetic and natural apocarotenal production. Pharmaceutical formulators in Germany and Switzerland are accelerating adoption of fermented natural variants for ophthalmic supplements. This technology compression is enabling mid-sized food processors to meet clean-label procurement policies without sacrificing colorant performance specifications.
EFSA's ongoing re-evaluation of carotenoid safety profiles is tightening permissible exposure thresholds across European formulations. Food manufacturers face reformulation timelines that compress against existing inventory cycles and supplier qualification periods. Fortified juice and dairy alternative segments in France and the Netherlands are responding by pre-qualifying alternative natural colorant suppliers ahead of finalized regulatory guidance.
Buyer concentration among mid-sized European food processors is compressing supplier negotiation cycles and unbundling traditional technical service packages. DSM Nutritional Products and Allied Biotech are responding with modular service tiers that separate colorant supply from formulation support. Germany's clean-label product development clusters are most visible in this shift, where procurement teams prioritize qualified supply security over integrated technical partnerships.
Apocarotenal Market Segmentation
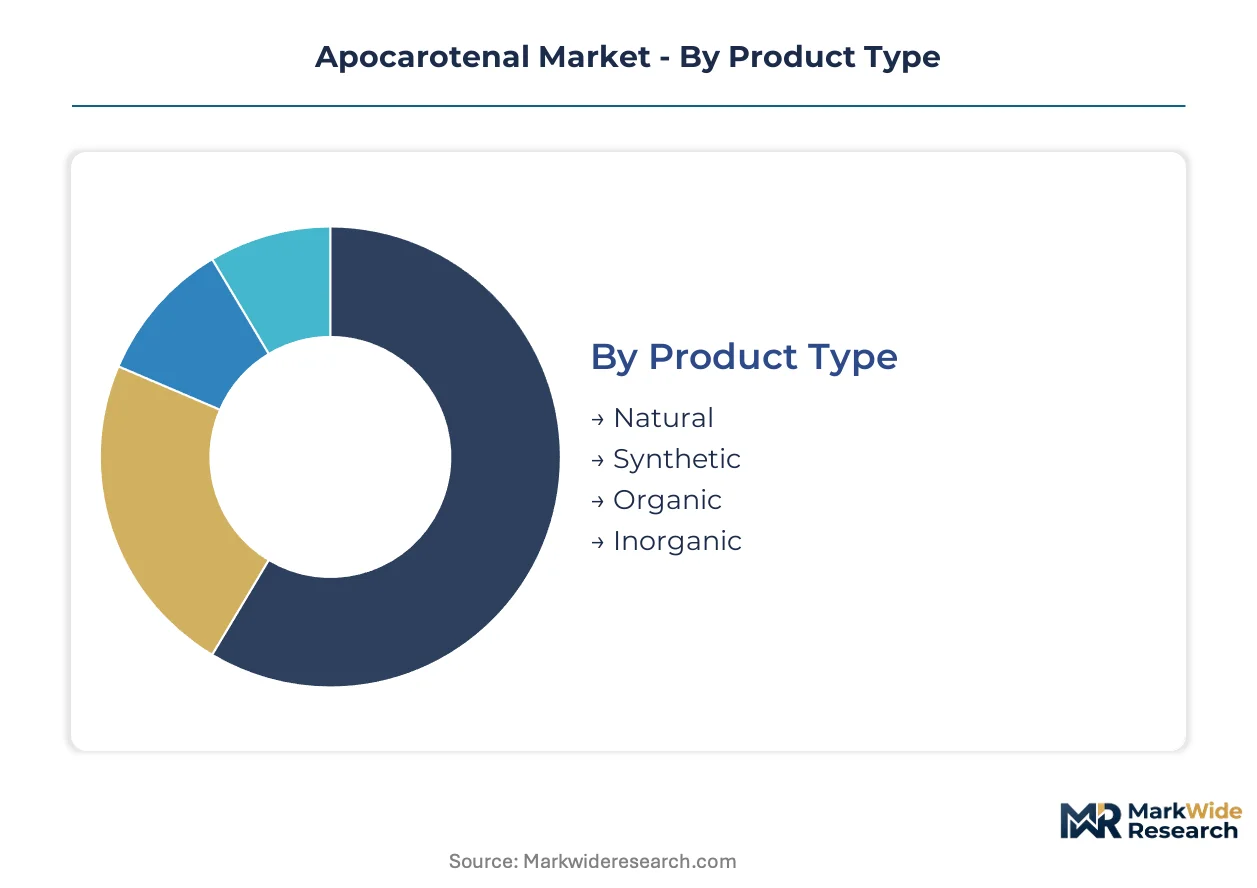
Apocarotenal procurement patterns diverge sharply across product origins and end-use specifications, with pharmaceutical-grade requirements commanding distinct supply relationships from food-grade colorant sourcing. Technical service intensity varies by segment, with fermentation-derived natural variants demanding strain-to-extract traceability that synthetic routes rarely require.
Product Type:
After-sales service intensity concentrates in natural and synthetic segments, where technical support for reformulation and regulatory documentation separates premium suppliers from commodity traders.
- Natural:Fermentation-derived apocarotenal from microbial conversion of plant precursors commands premium positioning as clean-label procurement policies at European food manufacturers displace synthetic alternatives. DSM Nutritional Products and Divis Laboratories compete through integrated biotechnology platforms that control strain development through finished extract quality.
- Synthetic:Chemical synthesis routes face narrowing margins as REACH registration requirements intensify scrutiny of artificial additives, compressing supplier pools to specialized chemical manufacturers with dedicated carotenoid production lines. Germany's mid-sized food processors are systematically eliminating synthetic colorants from reformulated product lines.
- Organic:Certified organic apocarotenal extraction meets stringent agricultural input standards for premium nutraceutical positioning in North American and European markets.
- Inorganic:Mineral-based colorant alternatives capture limited share in apocarotenal-adjacent applications where thermal stability exceeds bioavailability requirements.
Synthetic holds the largest share; momentum sits with natural.
Application:
Cost tier stratification separates pharmaceutical specifications from commodity food-grade supply, with bioavailability thresholds creating qualification barriers that few suppliers cross.
- Food & Beverage:Fortified juices and dairy alternatives in Germany and France represent the volume anchor for apocarotenal deployment as orange-yellow colorants, with EFSA's re-evaluation of carotenoid safety profiles compressing reformulation timelines against inventory cycles.
- Pharmaceuticals:Ophthalmic supplements and antioxidant formulations demand carotenoid purity levels exceeding general food-grade extraction yields, with pharmacopeial monograph standards evolving to favor suppliers with captive fermentation capacity. Swiss and German formulators are accelerating adoption of fermented natural variants.
- Cosmetics:Topical applications leverage apocarotenal provitamin A activity for skin conditioning claims in premium personal care lines.
- Nutraceuticals:Dietary supplement incorporation spans softgel and tablet formats where stability testing protocols vary by delivery mechanism.
Food & Beverage holds the largest share; Pharmaceuticals are expanding most quickly.
End User:
Customer type determines procurement modality, with pharmaceutical producers demanding batch-level documentation that food manufacturers rarely require.
- Food Manufacturers:Mid-sized European processors in Germany's clean-label clusters prioritize qualified supply security over integrated technical partnerships, unbundling traditional service packages into modular colorant supply arrangements.
- Pharmaceutical Producers:Ophthalmic and antioxidant formulators in Switzerland and Germany concentrate supply relationships with fermentation-capable suppliers who can demonstrate strain-to-extract contamination control.
- Cosmetic Companies:Premium personal care brands specify apocarotenal for color stability in emulsion-based formulations.
- Nutraceutical Firms:Dietary supplement manufacturers balance bioavailability claims against cost constraints in capsule and softgel applications.
Food Manufacturers hold the largest share; Pharmaceutical Producers are gaining share fastest.
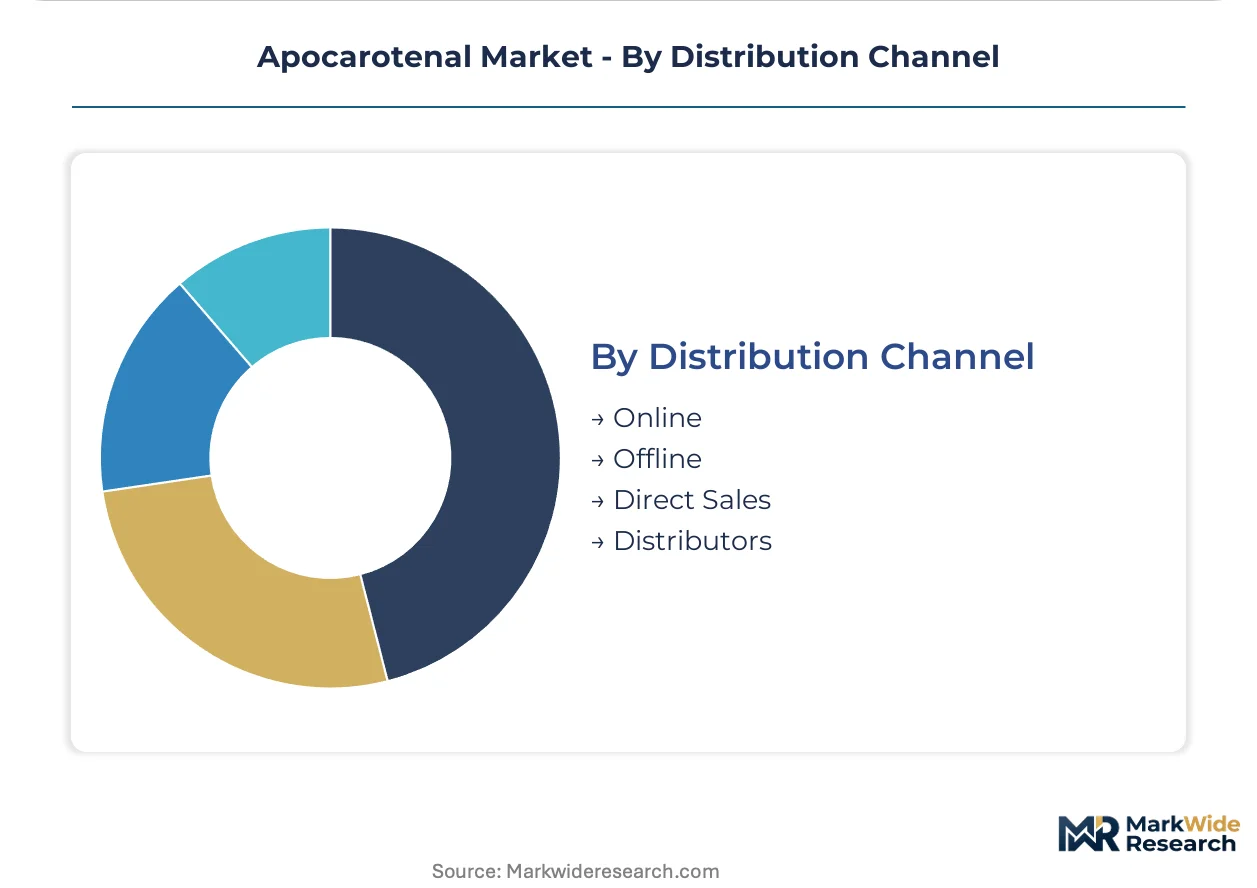
Distribution Channel:
Supply concentration shapes channel selection, with direct relationships dominating pharmaceutical-grade transactions while distributors capture fragmented food-grade volume.
- Direct Sales:Pharmaceutical-grade apocarotenal concentrates through direct technical relationships where batch consistency and documentation traceability outweigh price competition, particularly for German and Swiss ophthalmic supplement formulators.
- Distributors:Regional chemical distributors capture synthetic apocarotenal volume serving mid-sized food processors across France and the Netherlands, though margin compression is forcing consolidation toward natural variant specialists.
- Online:Digital procurement platforms serve small-scale nutraceutical and cosmetic formulators with standardized food-grade specifications.
- Offline:Traditional trade relationships persist in established European food manufacturing corridors where technical service bundling remains valued.
Distributors hold the largest share; Direct Sales show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. German food manufacturers absorb premium pricing for fermentation-derived natural variants, while Indian pharmaceutical formulators prioritize cost-efficient synthetic sourcing for volume antioxidant production.
Germany
Mid-sized food processors in Bavaria and Baden-Württemberg drive clean-label reformulation at rates outpacing broader European averages. EFSA's re-evaluation of carotenoid safety profiles compresses reformulation timelines against inventory cycles. Stuttgart's functional ingredient cluster concentrates pharmaceutical-grade fermentation capacity serving ophthalmic supplement formulators.
United States
Fortified beverage manufacturers deploy apocarotenal across orange juice and plant-based milk categories with accelerating velocity. FDA color additive regulations under 21 CFR 73.300 govern permissible deployment matrices and labeling thresholds. California's nutraceutical corridor in Orange County and San Diego anchors demand for high-bioavailability antioxidant formulations.
India
Pharmaceutical exporters in Telangana and Maharashtra scale apocarotenal incorporation into softgel antioxidant supplements for North American and European markets. CDSCO's evolving pharmaceutical-grade excipient standards shape supplier qualification requirements. Hyderabad's active pharmaceutical ingredient cluster concentrates fermentation capacity serving contract manufacturing organizations.
Switzerland
Ophthalmic supplement formulators in Basel and Zurich specify carotenoid purity thresholds exceeding general food-grade yields. Swissmedic's pharmacopeial alignment with European standards streamlines cross-border supply qualification. The Basel-Land biotechnology corridor anchors strain-to-extract traceability systems for premium nutraceutical positioning.
France
Fortified juice manufacturers in Île-de-France and Provence-Alpes-Côte d'Azur pre-qualify alternative natural colorant suppliers ahead of finalized EFSA guidance. ANSM's coordination with EFSA re-evaluation timelines creates regulatory anticipation effects. Paris-region food technology clusters accelerate clean-label procurement policy adoption among mid-sized processors.
Apocarotenal Market Competitive Environment
Integrated biotechnology platforms and specialized chemical manufacturers split the market along the natural-synthetic divide. Concentration is moderate at the top, with three to four fermentation-capable suppliers commanding pharmaceutical-grade premiums while synthetic routes fragment among regional chemical processors. Two strategic archetypes dominate: captive fermentation operators with strain-to-extract control, and distributed chemical synthesis specialists serving cost-sensitive food-grade volume. Competitive moves center on fermentation capacity expansion and modular service unbundling that separates colorant supply from technical support.
Within the integrated biotechnology tier, DSM Nutritional Products Ltd and Divis Laboratories exemplify archetypes built on captive fermentation capacity and upstream strain development control. Allied Biotech occupies a position bridging concentrated supply relationships with Asian pharmaceutical formulators and European clean-label food manufacturer demand. These three entities anchor the qualified supplier pool for specifications exceeding general food-grade thresholds, with their positioning reflecting divergent bets on geographic demand concentration and regulatory trajectory alignment.
| Leading Market Players |
|---|
| DSM Nutritional Products Ltd |
| Allied Biotech |
| Divis Laboratories |
| D.D. Williamson & Co., Inc. |
| Sensient Technologies Corporation |
| BASF Corp |
| Valensa International, LLC |
| Kanegrade Ltd. |
| Döhler Group |
| Others |
Value Chain & Pricing Dynamics
Stuttgart's functional ingredient cluster concentrates pharmaceutical-grade fermentation capacity that anchors premium pricing tiers for natural apocarotenal variants. This geographic concentration of captive bioreactor infrastructure enables suppliers to command sustained margin premiums over synthetic alternatives, while downstream food manufacturers in Bavaria absorb cost differentials to meet clean-label procurement mandates.
Pricing Analysis
Extended technical service contracts drive lifetime value for fermentation-derived natural apocarotenal, with three-tier pricing structure across premium, standard, and economy levels separating pharmaceutical-grade specifications from commodity food-grade supply. Price differentiation centers on certification tier—EFSA-compliant versus general food-grade—and volume scale, with ophthalmic supplement formulators showing least price sensitivity due to bioavailability requirements. Cost compression in synthetic routes is intensifying because REACH registration requirements intensify scrutiny of artificial additives, while mid-sized European food processors demonstrate highest price sensitivity as they balance reformulation timelines against inventory cycles.
Supply Chain Analysis
Export-control restrictions on fermentation biotechnology equipment limit capacity expansion in emerging production hubs, constraining supply growth for pharmaceutical-grade specifications. Raw material flows draw from India, China, and Germany, with plant-derived precursors and specialized bioreactor components serving as critical inputs. Single-source vulnerability concentrates in strain development IP held by integrated biotechnology platforms, while distribution runs through direct technical relationships for pharmaceutical-grade transactions and regional chemical distributors for food-grade volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Apocarotenal sits in early-cycle expansion as pharmaceutical applications for ophthalmic supplements and antioxidant formulations accelerate adoption beyond traditional food-colorant boundaries. Fermentation biotechnology maturation is collapsing the historical cost gap between natural and synthetic production routes, enabling broader penetration across mid-sized processor segments.
For Market Incumbents: Harden strain-to-extract traceability systems to defend against emerging biotechnology platforms with modular service offerings. Prioritize captive fermentation capacity expansion in Stuttgart and Basel-Land corridors to secure pharmaceutical-grade contamination control, while investing in EFSA pre-qualification documentation ahead of finalized carotenoid safety re-evaluations. For New Entrants and Emerging Players: Build out white-space positions in Asian pharmaceutical formulator supply chains, where concentrated relationships with Indian and Chinese antioxidant supplement manufacturers offer volume expansion outside European market saturation. Target contract manufacturing organizations in Hyderabad's active pharmaceutical ingredient cluster with fermentation-capable technical partnerships as the most penetrable entry vector. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because tightening EU and FDA additive frameworks systematically displace synthetic alternatives while favoring fermentation-derived natural variants with established pharmacopeial documentation. Acquisition focus should center on integrated biotechnology platforms with upstream strain control; monitor EFSA finalization timelines as the critical inflection signal for qualified supply premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Captive bioreactor infrastructure in Stuttgart and Basel-Land secures pharmaceutical-grade batch consistency for ophthalmic formulators. |
| Backward Integration into Strain Development | Upstream control over microbial strain IP reduces dependency on external biotechnology licensors for natural variant production. |
| EFSA Pre-Qualification Investment | Early documentation alignment with evolving carotenoid safety profiles compresses supplier qualification cycles for food manufacturers. |
| Asian Pharmaceutical Partnership | Concentrated supply relationships with Hyderabad and Shanghai formulators diversify revenue outside European clean-label saturation. |
| Modular Service Unbundling | Separation of colorant supply from technical support matches procurement preferences of Germany's mid-sized food processors. |
Study Parameters
A standing panel of fermentation technology directors, pharmaceutical formulator procurement leads, food manufacturer R&D heads, and regulatory affairs specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from EFSA safety re-evaluation documents, FDA 21 CFR 73.300 filings, REACH registration databases, and European customs trade records. Bottom-up volume modeling triangulated against top-down market sizing across natural, synthetic, organic, and inorganic product type segments.
Scenario-bracketing framed analytical outputs across the projection horizon, with segmentation dimensions spanning product origin, application tier, end-user archetype, and distribution channel structure. CAGRs derived from fitted growth curves applied to base-year market estimates, incorporating fermentation yield improvement trajectories and regulatory timeline probabilities as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by integrated biotechnology platforms or accelerated EFSA timeline finalization would shift outcomes. Material shifts in EU Green Deal sustainable chemistry enforcement or FDA color additive reclassification would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Caustic Sulphite Caramel Market
Additives
Hydroxyethyl Cellulose Market
Additives
1,4 Butanediol Derivatives Market
Additives
Biofuel Additives Market
Additives
Tamarind Gum Derivatives Market
Additives
Combustion Clean-Up Additives for High-Mileage Fleets Market
Additives
Monocalcium Phosphate Market
Additives
Diamino Stilbene Disulfonic Acid (DASDA) Market
Additives
Sodium Diacetate Market
Additives
Phthalate Plasticizer Market
Additives
Global Asphalt Additives Market
Additives
Global Polyurethane Additives Market
Additives
Sorbitan Tristearate Market
Additives
Fluid Loss Additives Market
Additives
Asia Pacific Plastic Additives Market
Additives
Polyethylene Terephthalate Additives Market