
 Grinding Aids Market | 2026-2036
Grinding Aids Market Size, Share, and Industry Trends Forecast 2026-2036
Grinding Aids Market Analytics
Vietnam is tilting toward expanded grinding aid production to serve clinker-intensive cement corridors along its northern coast. BASF SE leverages its synthetic formulation expertise to supply major cement producers across emerging Asian markets. Sika AG anchors its position through integrated concrete admixture and grinding aid portfolios that reduce customer procurement complexity. GCP Applied Technologies Inc. competes on technical service intensity, embedding field engineers directly at cement mill operations.
Grinding aids are surface-active chemical additives, typically comprising glycol, amine, or polyol-based compounds, that reduce particle agglomeration during cement and mineral comminution to lower specific energy consumption per ton of finished product. These additives function by neutralizing electrostatic charges on milled particles, thereby improving mill throughput and enabling finer particle size distribution at equivalent power input. Cement additives dominate current value capture due to their direct linkage with energy-intensive clinker grinding stages where cost savings are most measurable. Bio-based formulations represent the fastest-expanding formulation type as cement producers face Scope 3 emissions scrutiny from European and North American construction clients. Mineral grinding aids occupy a narrower but defensible niche serving ore processing operations in copper and gold extraction circuits.
The US EPA regulates volatile organic compound emissions from chemical manufacturing facilities producing synthetic grinding aid precursors, while REACH in Europe mandates full substance registration for glycolamine imports used in cement additive formulations. India's BIS certification requirements for construction chemicals create non-tariff barriers that favor domestic producers like Thermax Global and Ashtech India Pvt. Ltd. Stakeholders must monitor evolving carbon border adjustment mechanisms and their cascading effects on regional formulation strategies.
Market Dynamics
The EU Green Deal's Carbon Border Adjustment Mechanism is forcing cement exporters to reformulate grinding aids toward bio-based chemistries, compressing synthetic additive margins while rewarding low-carbon suppliers with procurement preference.
Growth Catalysts
- Clinker substitution mandates:India's infrastructure push accelerates blended cement adoption, expanding grinding aid demand for pozzolanic and slag-based formulations that require enhanced particle dispersion.
- REACH substance registration:European chemical compliance creates formulation barriers that favor established glycolamine suppliers with full dossier portfolios, consolidating supply relationships.
- Copper extraction intensity:Chilean and Peruvian mineral processing operations deploy grinding aids to improve ore comminution efficiency amid declining head grades.
Market Restraints
- Ethylene glycol price volatility:Synthetic grinding aid precursors face feedstock cost swings tied to petrochemical refining margins, compressing formulation profitability.
- Domestic certification barriers:India's BIS construction chemical standards favor local producers like Thermax Global, limiting import penetration from multinational suppliers.
- Mechanical activation substitutes:High-pressure grinding rolls and vertical roller mills reduce additive dependency in greenfield cement installations.
Strategic Opportunities
- Vietnam's northern cement corridor:Clinker-intensive production clusters near Ha Long Bay lack local grinding aid supply, creating white space for formulation tolling partnerships.
- CSRD disclosure requirements:European corporate sustainability reporting mandates cement producers to document Scope 3 chemical inputs, advantaging bio-based additive suppliers with certified carbon footprints.
- Admixture-grinding aid bundling:Integrated concrete chemical portfolios reduce procurement touchpoints for ready-mix operators, opening channel consolidation plays.
Industry Challenges
- Field formulation expertise scarcity:Cement mill optimization requires embedded chemical engineers capable of tuning additive dosing to clinker mineralogy variations.
- Bio-based raw material traceability:Certification of agricultural-derived polyol feedstocks demands supply chain documentation systems that small compounders lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grinding Aids Market |
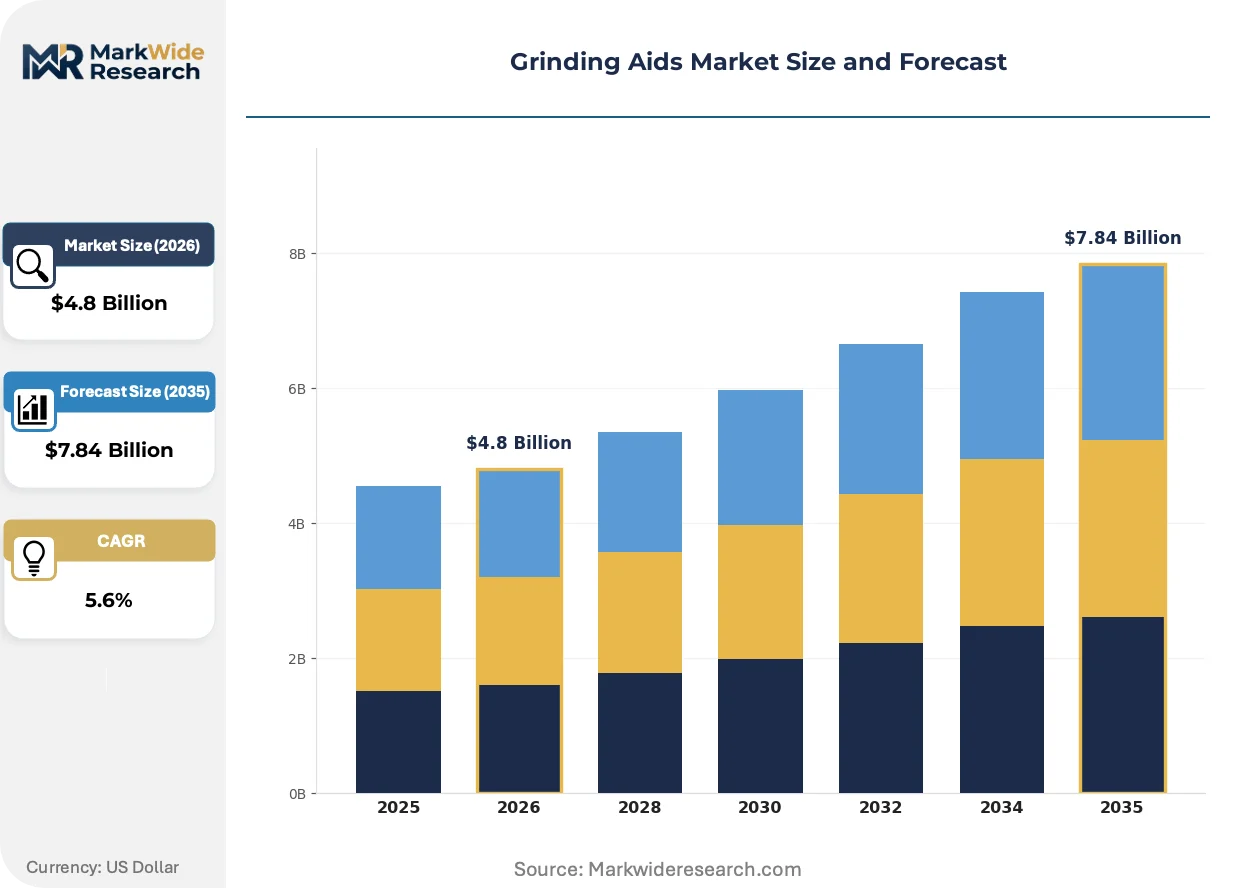
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cement Additives, Concrete Admixtures, Chemical Grinding Aids, Mineral Grinding Aids End User: Cement Manufacturers, Construction Companies, Ready-Mix Concrete Producers, Mining Industries Formulation Type: Synthetic, Natural, Bio-Based, Hybrid Application: Cement Production, Concrete Applications, Grinding Processes, Industrial Manufacturing |
| Companies Covered | BASF SE, Sika AG, GCP Applied Technologies Inc., W.R. Grace, Dow Chemical, Fosroc Chemicals, CHRYSO SAS, Thermax Global, Ashtech India Pvt. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grinding Aids Market Evolving Landscape
Grinding aid chemistry is pivoting from commodity glycol formulations toward specialty bio-polyols and hybrid amine-glycol systems that address simultaneous energy efficiency and carbon accounting pressures.
Enzymatic hydrolysis of lignocellulosic biomass is rendering obsolete first-generation bio-based grinding aids derived from edible crop oils. Brazilian and Nordic cement producers pilot these advanced polyols at commercial scale. The technology compresses feedstock costs while satisfying EU taxonomy criteria for sustainable chemistry.
REACH Annex XVII restrictions on ethylene oxide derivatives tighten precursor availability for conventional amine-based additives. German and French cement chemical suppliers reformulate with propoxylated alternatives. The shift elevates R&D intensity for mid-tier compounders lacking alternative synthesis capabilities.
Buyers now unbundle technical service contracts from chemical supply agreements, compressing supplier margins while elevating pure-play grinding aid vendors with lean cost structures. Southeast Asian cement groups lead this disintermediation, directly hiring mill optimization engineers rather than embedding vendor personnel. The practice spreads fastest in Vietnam and Indonesia where procurement functions centralize at holding-company level.
Grinding Aids Market Segmentation
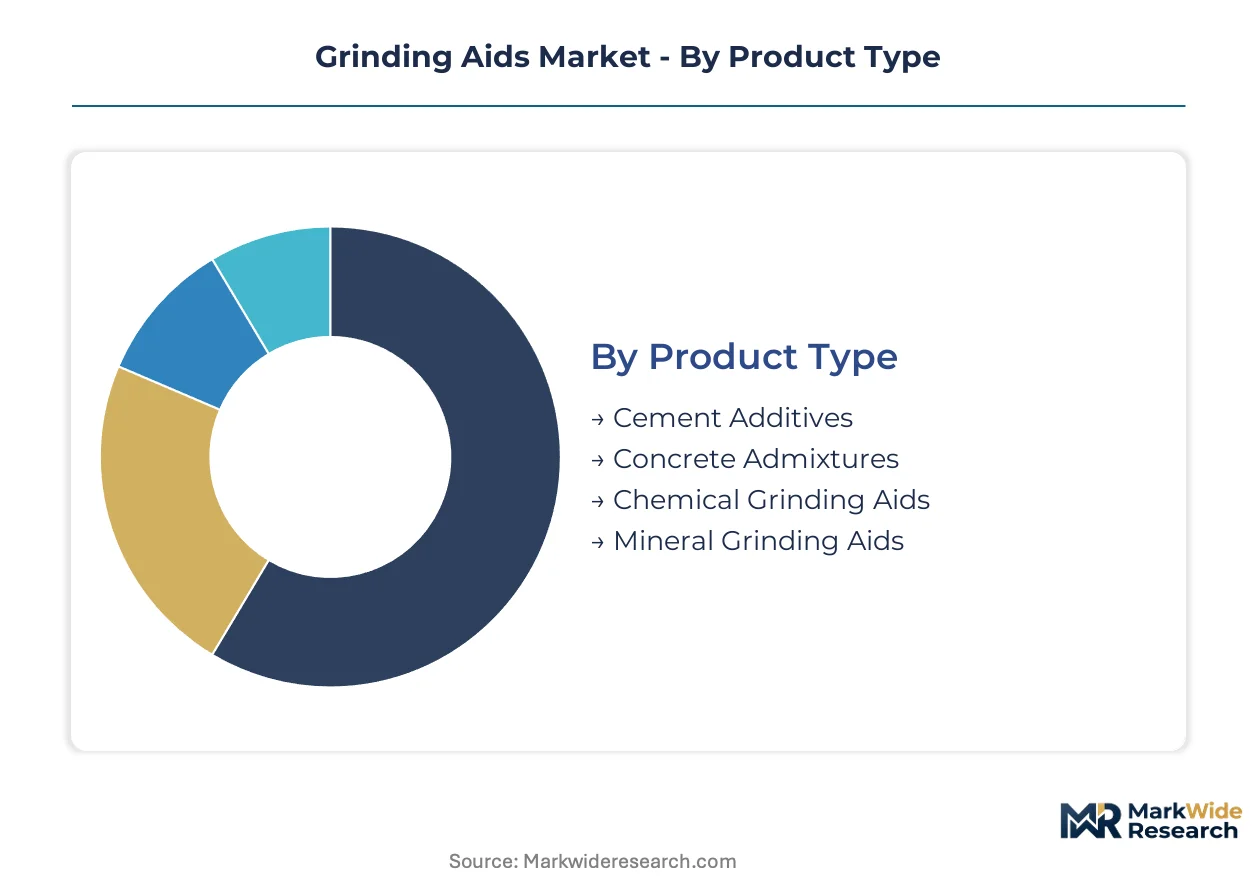
Grinding aid procurement patterns diverge sharply across end-use verticals, with cement manufacturers prioritizing energy efficiency metrics while mining operators emphasize throughput maximization. Formulation selection increasingly ties to carbon accounting requirements, reshaping supplier-customer technical service relationships.
Product Type:
After-sales-service intensity varies dramatically across product categories, with cement additives demanding embedded mill optimization engineers while mineral grinding aids require less frequent technical intervention.
- Cement Additives:Glycol-amine and polyol-based surface-active compounds that neutralize electrostatic charges during clinker comminution. Demand concentrates in India where infrastructure investment accelerates blended cement programs requiring enhanced particle dispersion for pozzolanic and slag-based formulations.
- Chemical Grinding Aids:Synthetic formulations comprising ethylene oxide derivatives and propoxylated alternatives. REACH Annex XVII restrictions on ethylene oxide derivatives are forcing German and French suppliers toward alternative synthesis pathways, elevating R&D intensity for mid-tier compounders.
- Concrete Admixtures:Integrated chemical portfolios bundling grinding aids with water reducers and retarders. Construction companies in Southeast Asia increasingly favor single-source procurement to reduce vendor management complexity.
- Mineral Grinding Aids:Specialized additives for copper and gold ore comminution circuits. Chilean and Peruvian processing operations deploy these formulations to improve efficiency amid declining head grades.
Cement Additives holds the largest share; momentum sits with Chemical Grinding Aids as regulatory pressure accelerates formulation reformulation.
End User:
Customer scale and technical sophistication create distinct service tiers, with multinational cement groups centralizing procurement at holding-company level while regional miners negotiate spot formulations.
- Cement Manufacturers:Energy-intensive clinker grinding operations represent the core value capture segment. Vietnam's northern cement corridor near Ha Long Bay exhibits acute supply gaps, creating white space for tolling partnerships.
- Ready-Mix Concrete Producers:Mid-stream operators demanding bundled admixture-grinding aid portfolios. These buyers now unbundle technical service contracts from chemical supply agreements, compressing supplier margins.
- Construction Companies:End-use customers driven by EU Green Deal carbon border requirements. European corporate sustainability reporting mandates force documentation of Scope 3 chemical inputs.
- Mining Industries:Copper and gold extraction circuits requiring ore-specific comminution optimization. Declining ore grades across Chile and Peru sustain additive demand despite mechanical grinding technology advances.
Cement Manufacturers dominates volume; Ready-Mix Concrete Producers are expanding most quickly through procurement consolidation.
Formulation Type:
Carbon intensity differentiation now structures pricing power, with certified low-carbon formulations commanding procurement preference under emerging border adjustment mechanisms.
- Bio-Based:Advanced polyols derived from enzymatic hydrolysis of lignocellulosic biomass. Brazilian and Nordic cement producers pilot these second-generation formulations at commercial scale, satisfying EU taxonomy criteria.
- Synthetic:Conventional glycol-amine systems facing feedstock volatility from petrochemical refining margin swings. Ethylene glycol price instability compresses formulation profitability for established suppliers.
- Natural:First-generation bio-based additives derived from edible crop oils. These formulations are rendering obsolete as enzymatic hydrolysis technologies compress feedstock costs.
- Hybrid:Amine-glycol combination systems addressing simultaneous energy efficiency and carbon accounting pressures. German suppliers lead development of propoxylated alternatives to REACH-restricted precursors.
Synthetic formulations retain volume leadership; Bio-Based products are gaining share fastest on regulatory tailwinds.
Application:
Process integration depth determines formulation complexity, with cement production requiring multi-stage additive dosing while discrete grinding applications permit simpler single-point injection.
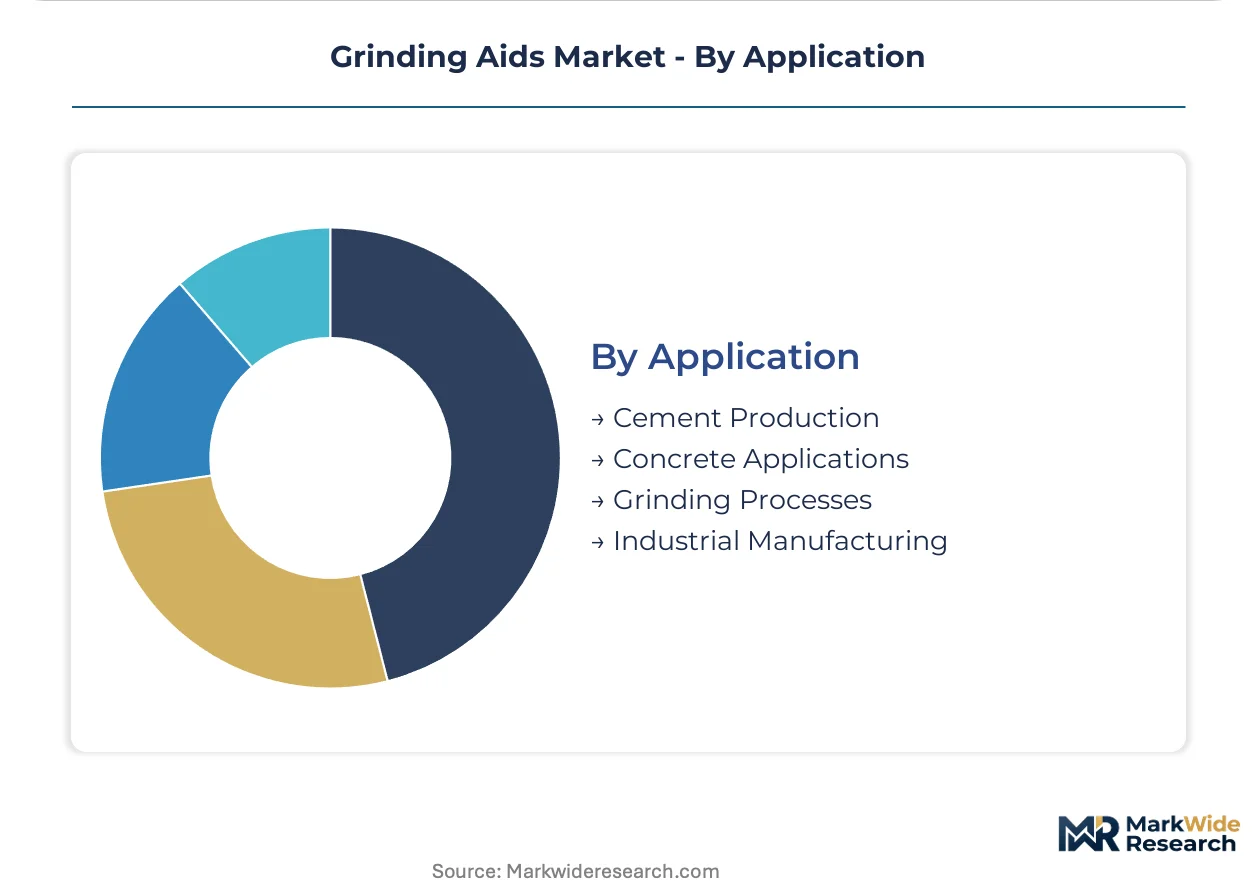
- Cement Production:Multi-stage comminution from raw meal grinding through finish milling. India's clinker substitution mandates expand demand for specialized dispersants in blended cement manufacturing.
- Grinding Processes:Discrete mineral and industrial comminution operations. High-pressure grinding rolls and vertical roller mills in greenfield installations reduce additive dependency in this segment.
- Concrete Applications:Ready-mix and precast production requiring compatibility with superplasticizers and retarders. Technical service intensity concentrates here due to variability in local aggregate mineralogy.
- Industrial Manufacturing:Niche ceramic and pigment grinding operations. Smaller volume but defensible margins due to specialized formulation requirements and limited supplier competition.
Cement Production commands the largest share; Grinding Processes faces headwinds from mechanical technology substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's BIS certification requirements for construction chemicals anchor procurement patterns across the dominant geography, while the EU Green Deal's Carbon Border Adjustment Mechanism reshapes formulation trade flows into European markets.
India
Clinker substitution mandates accelerate blended cement adoption, expanding grinding aid demand for pozzolanic and slag-based formulations. The Bureau of Indian Standards (BIS) construction chemical standards create non-tariff barriers favoring domestic producers. Infrastructure investment concentrates in Maharashtra and Gujarat, where cement producers expand procurement of specialized dispersants.
Vietnam
Clinker-intensive production clusters along the northern coast near Ha Long Bay lack local grinding aid supply, creating white space for formulation tolling partnerships. The country's national construction chemical regulator enforces quality standards that limit import penetration. Procurement centralization at holding-company level accelerates technical service unbundling across Hanoi and Hai Phong industrial zones.
Germany
REACH Annex XVII restrictions on ethylene oxide derivatives force reformulation toward propoxylated alternatives, elevating R&D intensity for mid-tier compounders. The European Chemicals Agency (ECHA) substance registration requirements consolidate supply relationships around established glycolamine suppliers. Chemical manufacturing concentrates in the Rhine-Ruhr and Bavaria regions, where suppliers pilot hybrid amine-glycol systems.
United States
The EPA regulates volatile organic compound emissions from chemical manufacturing facilities producing synthetic grinding aid precursors. Construction activity in Texas and California drives cement additive demand, though mechanical activation substitutes reduce additive dependency in greenfield installations. Ready-mix concrete producers in the Southeast favor bundled admixture-grinding aid portfolios to reduce vendor management complexity.
Brazil
Enzymatic hydrolysis of lignocellulosic biomass renders first-generation bio-based grinding aids obsolete, with cement producers piloting advanced polyols at commercial scale. ANVISA oversees chemical safety standards for construction materials. São Paulo and Minas Gerais anchor production of second-generation bio-based formulations satisfying EU taxonomy criteria for sustainable chemistry.
Grinding Aids Market Competitive Landscape
Capability concentration sits with specialty chemical compounders possessing full REACH dossier portfolios; scale advantage sits with diversified construction chemical conglomerates offering integrated admixture portfolios. The market structures around three tiers: multinational suppliers with embedded technical service networks, regional compounders leveraging domestic certification barriers, and emerging bio-based specialists capturing carbon-accounting premiums. Consolidation pressures favor backward integration into polyol feedstocks and tolling partnerships in supply-deficient corridors.
Among European-headquartered chemical conglomerates, BASF SE and Sika AG exemplify divergent archetypes: the former leverages synthetic formulation expertise across emerging Asian markets, while the latter anchors position through integrated concrete admixture and grinding aid portfolios that reduce customer procurement complexity. GCP Applied Technologies Inc. occupies a position emphasizing technical service intensity, embedding field engineers directly at cement mill operations. Thermax Global and Ashtech India Pvt. Ltd. represent domestic champions capitalizing on BIS certification requirements to defend market position against multinational penetration.
| Leading Market Players |
|---|
| BASF SE |
| Sika AG |
| GCP Applied Technologies Inc. |
| W.R. Grace |
| Dow Chemical |
| Fosroc Chemicals |
| CHRYSO SAS |
| Thermax Global |
| Ashtech India Pvt. Ltd |
| Others |
Value Network & Pricing Analysis
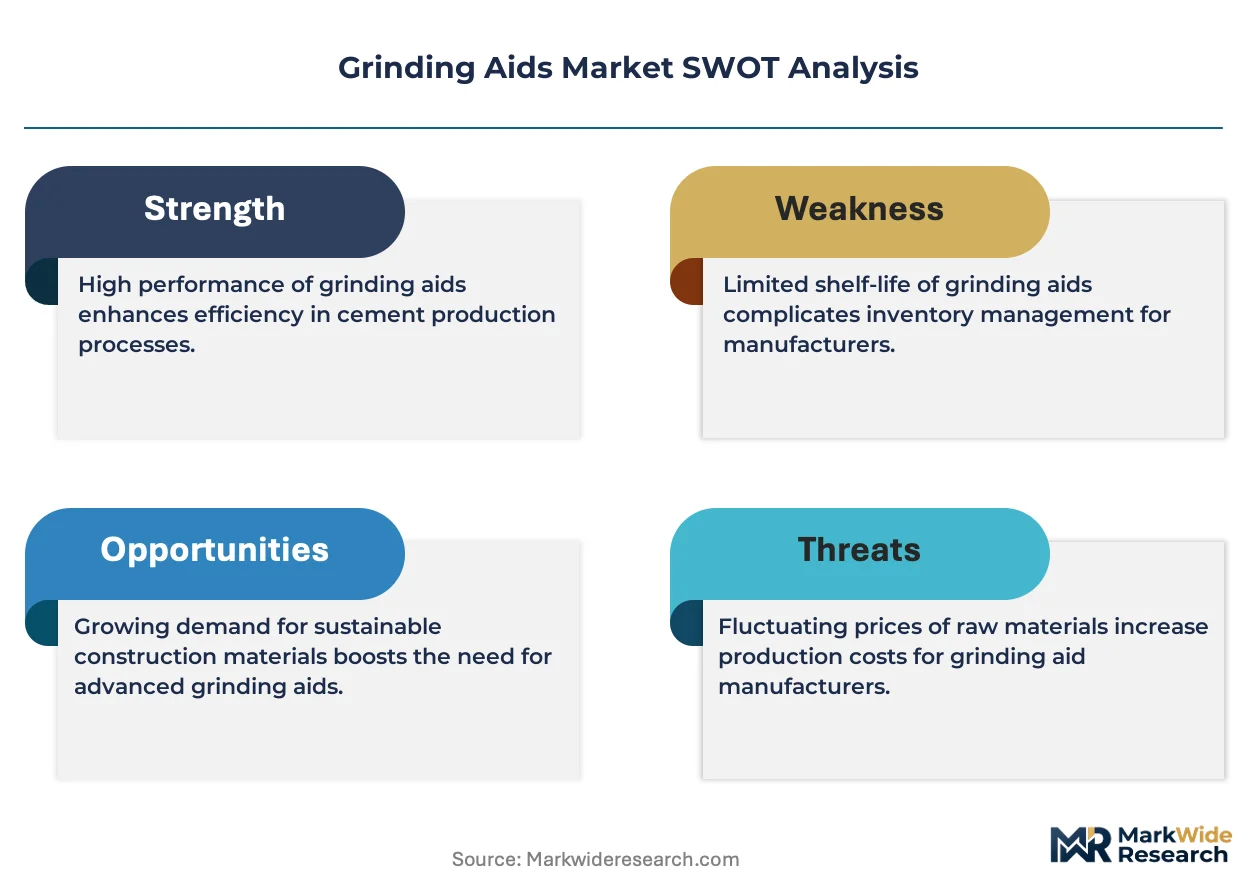
Ethylene glycol price volatility determines both the pricing tier spreads between synthetic and bio-based formulations and the geographic shape of supply chain investment. Feedstock cost swings tied to petrochemical refining margins compress margins for conventional glycol-amine suppliers while accelerating backward integration into lignocellulosic feedstocks by second-generation bio-based compounders.
Pricing Analysis
Price spreads between Germany and India exceed those between any other major cement chemical markets, reflecting REACH compliance costs and BIS certification barriers. The dominant pricing structure separates premium certified-low-carbon formulations from standard synthetic grades and economy unregistered imports, with certification grade and volume scale as the primary differentiation drivers. Pricing pressure stems from buyer unbundling of technical service contracts, which erodes the bundled premium that embedded mill engineers once commanded. Ready-mix concrete producers exhibit the highest price sensitivity due to procurement centralization, while cement manufacturers with clinker substitution mandates show lowest sensitivity to bio-based premiums.
Supply Chain Analysis
Upstream ethylene oxide and propylene oxide derivatives concentrate production in Germany, the United States, and Saudi Arabia, with enzymatic hydrolysis feedstocks emerging from Brazil and Nordic pulp processing regions. Formulation draws from glycol-amine precursors, lignocellulosic biomass, and specialty propoxylated alternatives as the three critical input streams. Single-source vulnerability runs through REACH-registered glycolamine suppliers with full dossier portfolios, which consolidate supply relationships and create chokepoints for mid-tier compounders lacking alternative synthesis pathways. Distribution runs through direct mill-supply contracts for cement additives and construction-chemical distributors for bundled admixture portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase as infrastructure investment cycles across India and Southeast Asia reaccelerate clinker grinding capacity utilization. Cement producers' capital deployment into blended cement programs creates sustained formulation demand despite mechanical grinding technology headwinds.
For Market Incumbents: Harden technical service capabilities against disintermediation by cement groups hiring in-house mill optimization engineers, particularly across Vietnam and Indonesia where procurement centralization accelerates fastest. Deepen backward integration into polyol feedstocks through tolling partnerships in supply-deficient corridors like Vietnam's northern cement belt, securing captive supply of enzymatic hydrolysis-derived biomass before second-generation bio-based specialists scale. For New Entrants and Emerging Players: Establish a beachhead in Vietnam's Ha Long Bay clinker corridor where local grinding aid supply gaps persist and national construction chemical quality standards limit import penetration. Target tolling partnerships with Brazilian or Nordic enzymatic hydrolysis technology holders to access EU taxonomy-compliant feedstock certification without capital-intensive biorefinery buildout. Lead with pure-play grinding aid positioning rather than bundled admixture portfolios to exploit procurement unbundling trends among Southeast Asian holding companies. For Investors and Strategic Acquirers: Regional compounders with domestic certification moats represent the most defensible acquisition archetype, particularly those leveraging India's BIS construction chemical standards or Vietnam's national quality enforcement. Long-term viability hinges on carbon border adjustment mechanism expansion beyond European markets, which would replicate EU Green Deal procurement preference effects across Middle Eastern and North African cement export corridors. Watch for CSRD disclosure mandate adoption by non-EU construction clients as the signal that Scope 3 chemical input documentation will become a global procurement requirement rather than a European anomaly.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Feedstocks | Captive supply of enzymatic hydrolysis biomass secures EU taxonomy compliance and insulates against ethylene glycol volatility. |
| Formulation Tolling Partnerships | Local production in Vietnam's northern corridor bypasses import barriers while avoiding greenfield chemical plant capital intensity. |
| REACH Dossier Portfolio Expansion | Full substance registration for propoxylated alternatives maintains market access as Annex XVII restrictions tighten on ethylene oxide derivatives. |
| Technical Service Unbundling Response | Pure-play lean cost structures capture procurement centralization among Southeast Asian cement holding companies. |
| CSRD-Aligned Carbon Certification | Documented Scope 3 chemical footprints command procurement preference under emerging corporate sustainability reporting mandates. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs and trade data, chemical industry association reports, SEC regulatory filings, and construction chemical certification databases. Primary interviews engaged cement plant managers, procurement leads at multinational cement groups, technical R&D directors at specialty chemical compounders, and distribution channel partners across India, Vietnam, Germany, and Brazil. Bottom-up volume estimates derived from clinker grinding capacity utilization and additive dosing rates were triangulated against top-down chemical consumption forecasts.
Forecast inputs include formulation type segmentation, end-use vertical adoption curves, and regional regulatory enforcement intensity across the projection horizon. The analytical framework models cement production, ready-mix concrete, mining extraction, and industrial manufacturing as distinct demand verticals with divergent technical service requirements and carbon accounting pressures. CAGRs were derived from segment-level volume trajectories weighted by pricing tier composition, with specific adjustment for clinker substitution mandate implementation timelines and mechanical grinding technology substitution rates in greenfield installations.
Stress conditions across ethylene glycol price bands, REACH enforcement stringency, and carbon border adjustment mechanism geographic expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding infrastructure investment continuity and regulatory harmonization timelines that could revise materially with construction cycle downturns or trade policy fragmentation. Cross-checking against cement industry capacity expansion announcements and chemical import customs records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Feed Additive Nosiheptide Premix Market
Additives
Caustic Sulphite Caramel Market
Additives
Competitive Inhibitors Market
Additives
Performance Minerals Additives Market
Additives
Refinery Fuel Additives Market
Additives
Middle East Lubricant Additives Market
Additives
Global Propyl Acetate Market
Additives
Organic Dispersants Market
Additives
Global Feed Acidifiers Market
Additives
Guanylic Acid Market
Additives
Antiknock Agents Market
Additives
Organic Friction Modifier Additives Market
Additives
Sorbitan Laurate Market
Additives
Glacial Acetic Acid Market
Additives
Carboxymethyl Cellulose Market
Additives
Lauroyl Methyl Glucamide Market