
 Pulp and Paper Chemicals Market | 2026-2036
Pulp and Paper Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Pulp and Paper Chemicals Market Outlook
Asset-light leasing models for on-site chemical generation is fragmenting competitive dynamics across the pulp and paper chemicals value chain. Kemira leverages long-term service contracts to anchor customer relationships in Nordic pulp corridors. BASF competes through backward integration into petrochemical feedstocks that sustain margin stability. Solenis differentiates via digital monitoring platforms that extend chemical dosing precision.
Pulp and paper chemicals comprise functional formulations including bleaching agents, process additives, and surface modifiers that control fiber bonding, brightness, and hydrophobicity through pH-adjusted reaction chemistry. These chemicals enable paper machine runnability and finished sheet performance across basis weights from 40 to 400 gsm. Bleaching agents command mature volume pools while coating chemicals capture expanding margin contribution from graphic paper substitution. Specialty grade formulations lead growth as pharmaceutical and food-contact certifications tighten material specifications across the packaging segment.
EPA effluent guidelines and OSHA process safety standards govern US manufacturing disclosures and chemical handling protocols, while REACH registration requirements in Europe restrict certain biocidal additives in paper for food contact. ECHA substance evaluations continue reshaping approved chemistries for pulp bleaching sequences. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and qualification timelines.
Market Dynamics
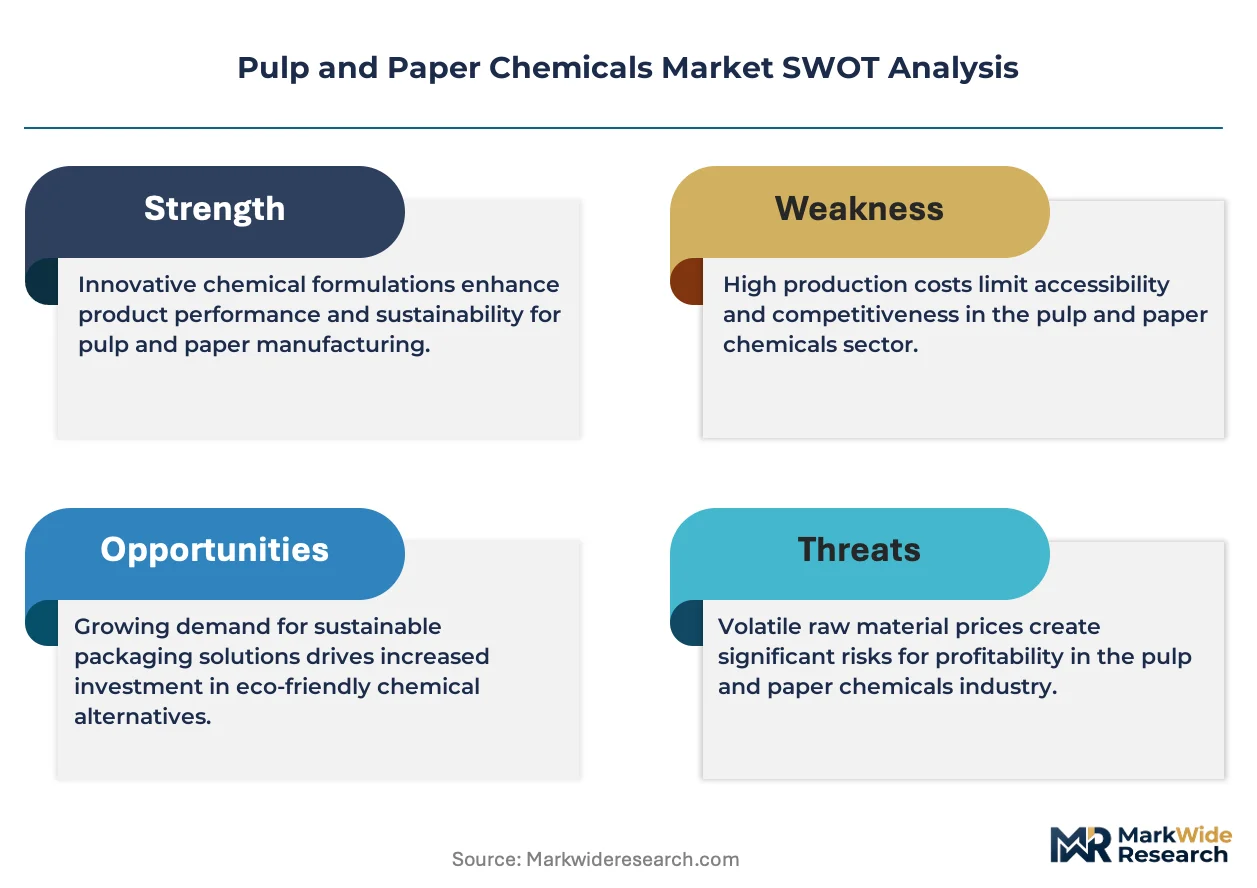
Chlorine-free bleaching mandates under REACH and the EU Green Deal are forcing mills to resequence chemical inputs, while e-commerce packaging demand concentrates formulation requirements around barrier coatings and food-contact compliance.
Growth Catalysts
- E-commerce fulfillment expansion:Specialty packaging grades for corrugated containers and flexible wraps drive demand for hydrophobic sizing agents and dry-strength polymers that withstand distribution stress.
- REACH biocidal restrictions:ECHA evaluations of slimicide chemistries push mills toward enzyme-based alternatives and peracetic acid sequences that reduce AOX discharge.
- China capacity modernization:State-backed upgrades of Hebei and Shandong pulp lines replace legacy chlorine bleaching with ECF and TCF sequences, lifting chemical consumption per ton.
Market Restraints
- Petrochemical feedstock volatility:Crude oil and natural gas price swings compress margins on alkyl ketene dimer and polyacrylamide derivatives that dominate sizing and retention chemistry.
- Supplier concentration in titanium dioxide:Chinese TiO2 producers control coating pigment supply, exposing paper mills to export quota disruptions and anti-dumping duty uncertainty.
- Technical ceiling in mechanical pulp brightness:Peroxide bleaching of stone groundwood hits optical limits near 75% ISO brightness, constraining premium graphic paper substitution.
Strategic Opportunities
- Underpenetrated Southeast Asia:Indonesian and Vietnamese packaging converters lack on-site chemical generation infrastructure, creating openings for leased dosing systems and technical service contracts.
- EU Green Deal carbon border adjustments:CBAM implementation favors low-carbon chemical sourcing, rewarding European mills with integrated bio-based polymer production.
- Digital dosing convergence:Machine learning algorithms paired with inline spectroscopy enable real-time brightness and ash control, displacing fixed-rate chemical addition.
Industry Challenges
- Process chemist scarcity:Retirement waves among papermakers with wet-end chemistry expertise outpace university training programs in fiber engineering.
- Food-contact certification timelines:FDA and BfR approvals for new barrier coatings extend 18-24 months, delaying revenue from compostable packaging launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pulp and Paper Chemicals Market |
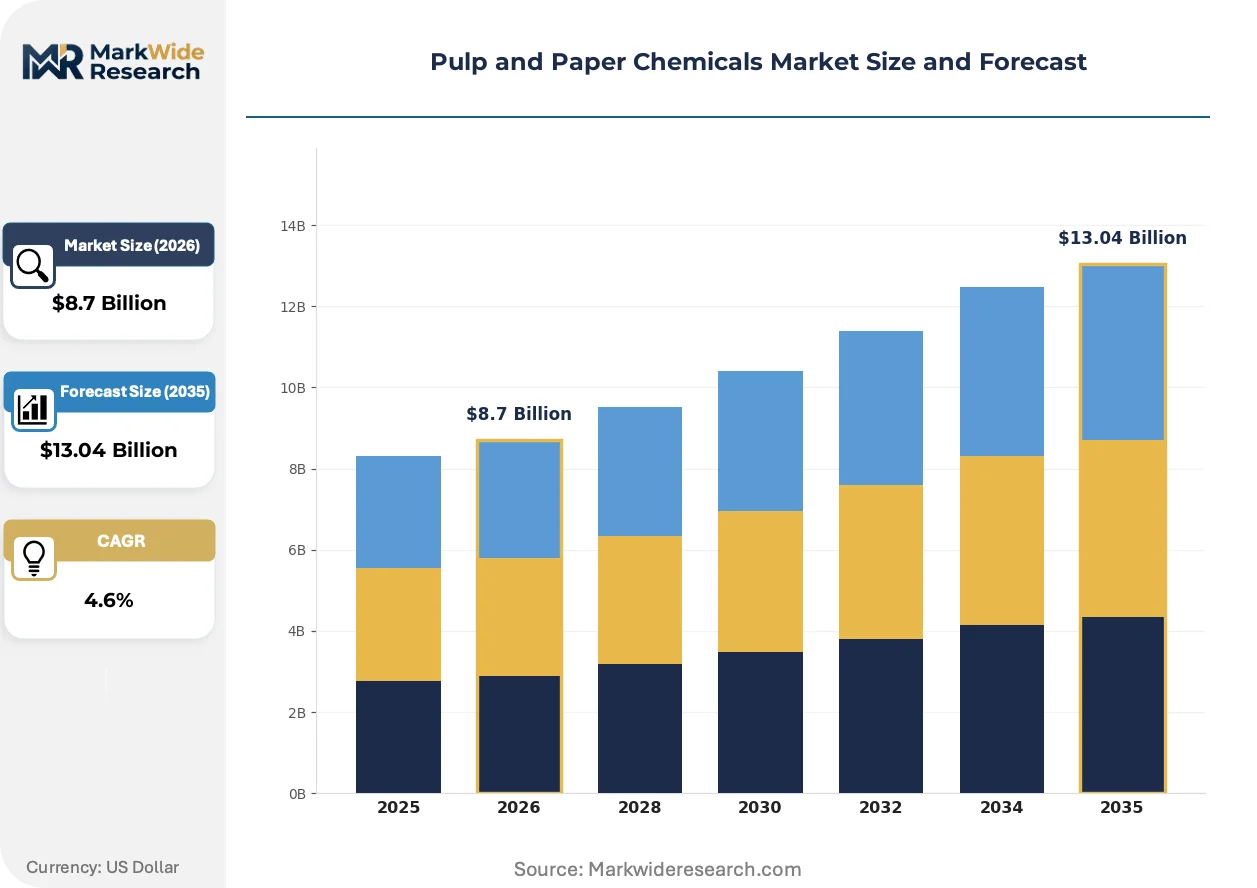
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
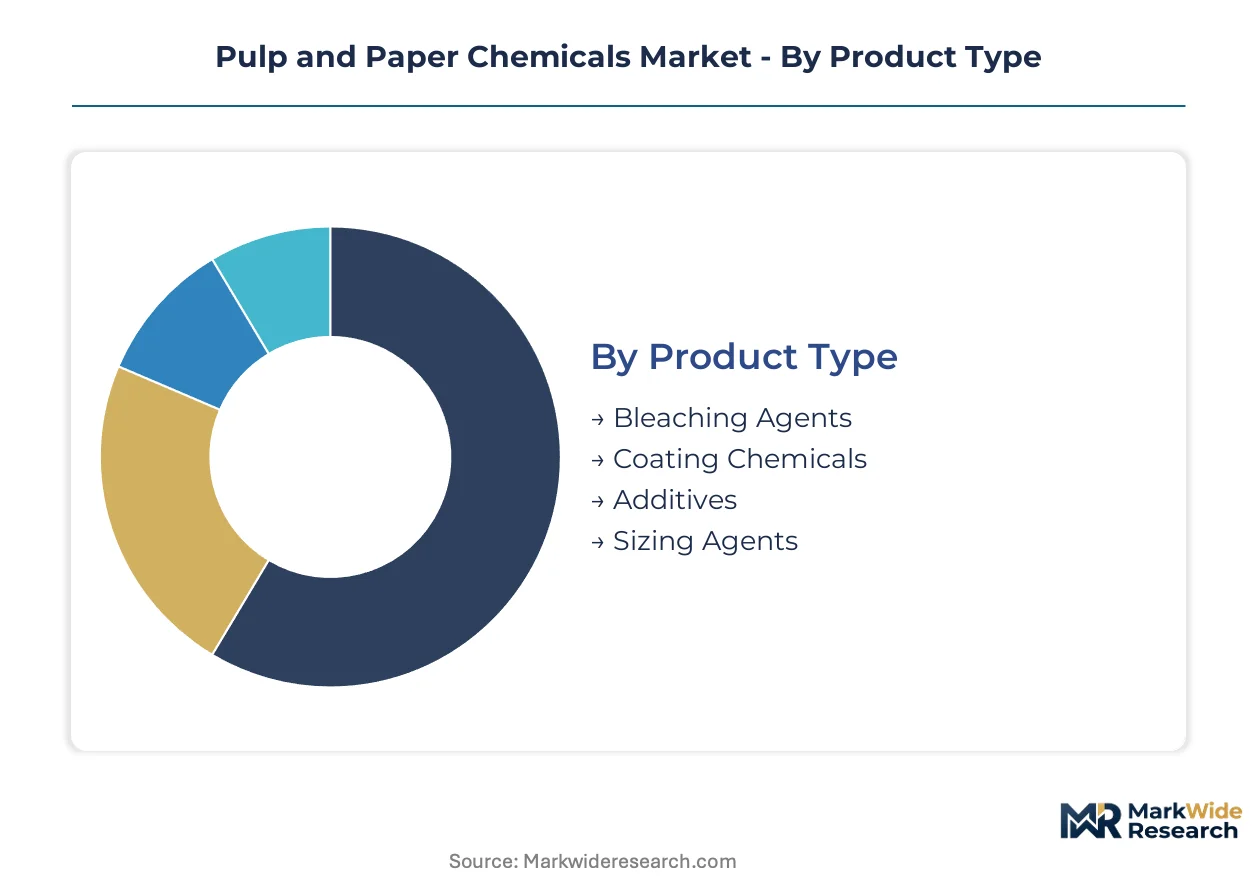
| Segmentation | Product Type: Bleaching Agents, Coating Chemicals, Additives, Sizing Agents Application: Pulp Production, Paper Coating, Surface Sizing, Wastewater Treatment End User: Packaging, Printing, Tissue, Newsprint Grade: Industrial Grade, Food Grade, Pharmaceutical Grade, Specialty Grade |
| Companies Covered | Kemira, BASF, Solenis, Ecolab, Ashland, Buckman, Clariant, Nouryon, SNF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pulp and Paper Chemicals Market Strategic Shifts
Bio-based chemistry and closed-loop dosing systems are redefining how mills manage chemical input costs and effluent compliance simultaneously.
Enzymatic bleaching catalysts are hybridizing oxygen and peroxide stages to reduce chlorine dioxide demand by 15-30% in hardwood kraft mills. Nordic and Canadian producers operating Boreal fiber lines adopt these sequences fastest. The technology is hybridizing capital planning decisions, forcing suppliers to bundle enzyme supply with process guarantees rather than standalone chemical sales.
EPA effluent limitation guidelines for pulp and paper mills tighten AOX and color parameters, requiring activated sludge upgrades or tertiary filtration. Mills in the US Southeast with aging wastewater infrastructure face the steepest compliance costs. Specialty chemical vendors respond with tailored flocculant programs that reduce biological oxygen demand discharge without capital-intensive plant rebuilds.
Leased on-site generation systems displace bulk chemical deliveries for chlorine dioxide and sodium chlorate. Major packaging converters in Germany and the Netherlands favor this model to decouple working capital from chemical inventory. The shift concentrates vendor relationships around service-level agreements rather than spot purchasing, locking incumbents into decade-long facility attachments.
Pulp and Paper Chemicals Market Segmentation
Pulp and paper chemical procurement cycles vary dramatically by segment, from quarterly bleaching agent tenders to multi-year coating formulation partnerships. Understanding these temporal patterns reveals where supplier relationships deepen and where spot purchasing persists.
Product Type:
Bleaching agents turn over fastest with quarterly contract renegotiations, while coating chemicals lock in annual or multi-year supply agreements due to qualification complexity.
- Bleaching Agents:Chlorine dioxide, hydrogen peroxide, and sodium chlorate formulations drive brightness in kraft and sulfite pulping. Demand concentrates in Chinese state-owned mills upgrading Hebei and Shandong lines to ECF sequences, where peroxide consumption per ton climbs with each retrofit.
- Coating Chemicals:Pigments, binders, and rheology modifiers control printability and gloss in coated fine paper and board. European graphic paper substitution toward packaging redirects coating demand toward barrier formulations with food-contact REACH compliance.
- Additives:Retention aids, drainage aids, and defoamers optimize wet-end chemistry.
- Sizing Agents:Alkyl ketene dimer and rosin derivatives impart liquid resistance.
Bleaching agents anchor the volume base while coating chemicals gain share at the steepest rate.
Application:
Cost tier stratification separates capital-intensive pulp production chemicals from operational expense-driven wastewater treatment chemistries.
- Pulp Production:Pulping, bleaching, and recovery chemicals dominate chemical spend per ton. Nordic Boreal fiber lines adopt enzymatic catalysts fastest, hybridizing oxygen and peroxide stages to cut chlorine dioxide demand.
- Paper Coating:Surface treatment formulations for brightness, smoothness, and print adhesion. E-commerce corrugated demand in Germany and the Netherlands favors leased on-site generation systems that decouple working capital from inventory.
- Surface Sizing:Hydrophobic agents applied at the size press for dimensional stability.
- Wastewater Treatment:Flocculants and coagulants for effluent compliance.
Pulp production absorbs the highest absolute chemical spend while wastewater treatment expands most quickly under tightening EPA effluent guidelines.
End User:
Application maturity shapes margin structure, with tissue and newsprint in consolidation against packaging and specialty printing in expansion.
- Packaging:Containerboard, corrugated, and flexible wrap formulations demand dry-strength polymers and barrier coatings. Chinese e-commerce fulfillment growth concentrates formulation requirements around distribution stress resistance and food-contact compliance.
- Printing:Coated woodfree and mechanical grades for commercial publishing. Peroxide bleaching of stone groundwood hits optical limits near 75% ISO brightness, constraining premium substitution.
- Tissue:Softness and absorbency chemistries for consumer and away-from-home products.
- Newsprint:Cost-optimized mechanical pulp brightness stabilization.
Packaging anchors the volume base while printing gains share fastest as pharmaceutical and food-contact certifications tighten specifications.
Grade:
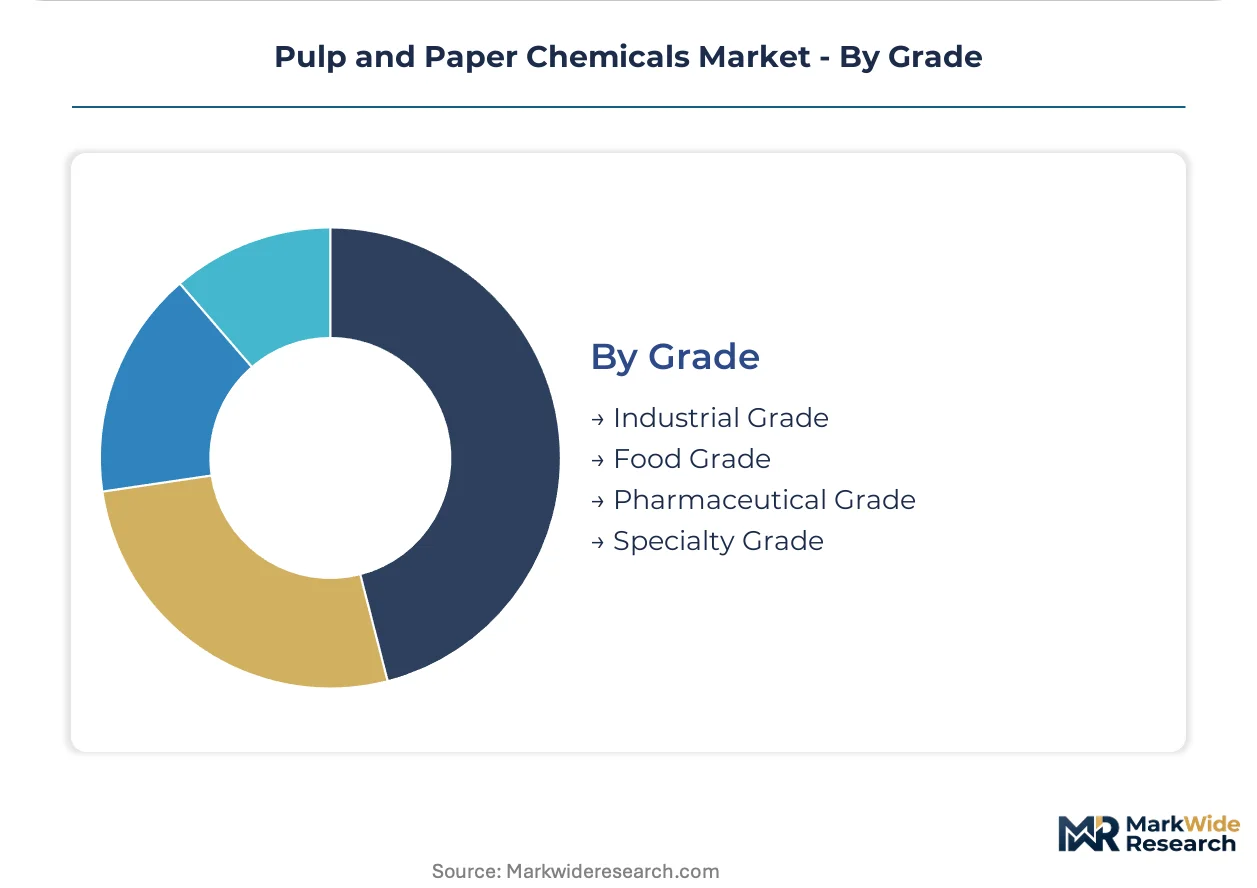
Certification intensity separates industrial commodity supply from pharmaceutical and food-grade qualification barriers.
- Industrial Grade:Standard formulations for non-contact applications. Mills in the US Southeast with aging wastewater infrastructure face steepest EPA compliance costs, driving tailored flocculant program adoption.
- Food Grade:FDA and BfR compliant barrier coatings for direct food contact. Approval timelines extend 18-24 months, delaying revenue from compostable packaging launches.
- Pharmaceutical Grade:Highest purity specifications for medical packaging.
- Specialty Grade:Custom formulations for technical or performance papers.
Industrial grade anchors the volume base while food grade climbs the fastest on compostable packaging and EU Green Deal carbon border adjustment alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-owned mills in China concentrate procurement authority for bleaching agents and process chemicals, while European packaging converters drive demand for food-contact compliant barrier formulations. Nordic pulp corridors and German industrial clusters anchor specialty chemical consumption patterns.
China
Hebei and Shandong pulp line retrofits to ECF and TCF sequences lift per-ton chemical consumption. MEE effluent standards tighten AOX discharge limits, accelerating chlorine-free bleaching adoption. State-backed capacity upgrades in Shandong Province replace legacy chlorine systems with enzymatic catalyst packages.
Germany
Corrugated packaging converters in the Rhine-Ruhr region favor leased on-site generation systems for chlorine dioxide. REACH biocidal restrictions on slimicide chemistries push mills toward peracetic acid sequences. The Hamburg industrial corridor hosts technical service contracts that bundle chemical supply with process guarantees.
United States
EPA effluent limitation guidelines tighten AOX and color parameters for mills in the Southeast with aging wastewater infrastructure. OSHA process safety standards govern chemical handling disclosures across Wisconsin and Georgia pulp corridors. Wisconsin's Fox River Valley cluster adopts tailored flocculant programs to reduce biological oxygen demand discharge.
Sweden
Nordic Boreal fiber lines adopt enzymatic bleaching catalysts fastest, hybridizing oxygen and peroxide stages. EU Green Deal carbon border adjustments favor low-carbon chemical sourcing from integrated bio-based polymer producers. The Sundsvall timber processing cluster anchors long-term service contracts for on-site chemical generation.
Indonesia
Packaging converters in Java lack on-site chemical generation infrastructure, creating openings for leased dosing systems. The country's national environmental regulator tightens industrial effluent standards for pulp mills in Sumatra. The Surabaya manufacturing corridor drives technical service contract adoption for barrier coating formulations.
Pulp and Paper Chemicals Market Competitive Environment
Channel-controlling players compete with product-specialist players across distinct value capture layers. The vendor base organizes into three tiers: integrated petrochemical suppliers with captive feedstock positions, specialty chemical houses with formulation expertise, and regional distributors with logistics density. Consolidation pressure runs highest in coating pigments where supplier concentration exposes mills to supply disruption. Competitive moves cluster around backward integration into bio-based feedstocks and digital dosing platform deployment.
Within the integrated chemical tier, BASF and Nouryon occupy positions anchored by petrochemical feedstock control. Specialty formulation expertise concentrates around Kemira and Solenis, both representing archetypes that bundle process guarantees with chemical supply. Buckman exemplifies the mid-scale specialist model focused on wet-end chemistry optimization.
| Leading Market Players |
|---|
| Kemira |
| BASF |
| Solenis |
| Ecolab |
| Ashland |
| Buckman |
| Clariant |
| Nouryon |
| SNF |
| Others |
Value Chain & Pricing Dynamics
Petrochemical feedstock volatility determines both pricing tier spreads and supply chain shape in pulp and paper chemicals, forcing mills to index contracts against crude oil benchmarks while concentrating procurement authority among state-backed buyers in China.
Pricing Analysis
Cost-plus contracts indexed to ethylene and propylene benchmarks dominate bleaching agent and sizing chemistry procurement, with quarterly renegotiations tracking petrochemical futures. Price differentiation separates pharmaceutical-grade barrier coatings requiring FDA and BfR certifications from industrial-grade flocculants. Cost compression in standard-grade alkyl ketene dimer is intensifying because of naphtha price swings. Packaging converters in Southeast Asia exhibit highest price sensitivity due to working capital constraints, while Nordic pulp mills show lowest sensitivity given long-term service contract structures.
Supply Chain Analysis
Contract manufacturing concentration for titanium dioxide pigments rests with Chinese producers controlling coating chemical supply. Geographic supply concentration clusters in China, Germany, and the United States for distinct chemistries: Chinese state-owned mills dominate chlorine dioxide consumption, German Rhine-Ruhr converters anchor leased generation systems, and US Southeast mills drive flocculant demand. Raw material dependencies include crude oil derivatives for polyacrylamide, natural gas for hydrogen peroxide, and ilmenite for TiO2. Single-source vulnerability in Chinese TiO2 exposes mills to export quota disruptions. Distribution runs through regional distributors with logistics density in Nordic pulp corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward state-backed Chinese mills consolidating procurement authority for bleaching agents, fragmenting supplier relationships elsewhere into spot purchasing for commodity chemistries.
For Market Incumbents: Entrench market position through backward integration into bio-based polymer production and deployment of digital dosing platforms with machine learning algorithms. Emerging enzyme-based alternatives threaten chlorine dioxide demand in Nordic Boreal fiber lines. Long-term service contracts locking decade-long facility attachments represent the critical defensive lever against spot purchasing fragmentation. For New Entrants and Emerging Players: Indonesian and Vietnamese packaging converters lacking on-site chemical generation infrastructure represent the most penetrable entry point for leased dosing systems and technical service contracts. Leased chlorine dioxide generation in Java and Sumatra offers immediate white-space capture. Go-to-market execution should bundle enzyme supply with process guarantees rather than standalone chemical sales. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialty formulation houses with digital platform capabilities over commodity chemical producers. Long-term viability across the five-to-ten year window hinges on EU Green Deal carbon border adjustment alignment and REACH biocidal restriction compliance. Acquisition targets should display integrated bio-based polymer production. The signal to watch is enzymatic bleaching catalyst adoption rates in hardwood kraft mills as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | EU Green Deal CBAM implementation rewards low-carbon chemical sourcing from integrated producers. |
| Digital Dosing Platform Deployment | Machine learning algorithms paired with inline spectroscopy displace fixed-rate chemical addition. |
| Long-term Service Contract Expansion | Leased on-site generation systems lock incumbents into decade-long facility attachments in Germany. |
| Enzymatic Bleaching Catalyst Supply | Hybrid oxygen-peroxide stages cut chlorine dioxide demand in Nordic and Canadian Boreal fiber lines. |
| Food-Contact Certification Investment | FDA and BfR approvals for barrier coatings capture compostable packaging revenue delayed by 18-24 month timelines. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with pulp mill process chemists, chemical procurement leads at packaging converters, distribution channel partners, and technical R&D directors at specialty formulation houses; and secondary validation through customs and trade data, American Chemistry Council and Cefic industry reports, SEC 10-K filings, and ECHA substance evaluation databases. Bottom-up and top-down triangulation cross-referenced chemical consumption per ton metrics against state-backed capacity upgrade announcements.
Forecast inputs considered grade tier stratification, end-use industry application maturity, packaging format requirements, and regional production hub modernization patterns across the analysis window. CAGRs were derived from segmented volume projections weighted by per-ton chemical intensity in ECF and TCF sequences. Industry-specific forecast inputs included EPA effluent guideline compliance cost trajectories and REACH biocidal restriction implementation timelines.
Macroeconomic conditions sit as an overlay; deviation in crude oil and natural gas price trajectories would shift the trajectory of alkyl ketene dimer and polyacrylamide derivative margins. Forecasts reflect documented assumptions about state-backed Chinese capacity upgrade completion rates and enzymatic catalyst adoption curves. Quarterly review of ECHA substance evaluation progress and MEE effluent standard enforcement intensity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Carbonless Paper Market
Paper Products
Africa Tissue Paper Market
Paper Products
Printing and Writing Papers Market
Paper Products
Dissolving Pulp Market
Paper Products
Paper Coating Materials Market
Paper Products
Leatheroid Paper Market
Paper Products
Photographic Paper Market
Paper Products
Speciality Pulp and Paper Chemicals Market
Paper Products
Woodfree Paper Market
Paper Products
Global Molded Pulp Products Market
Paper Products
Aramid Paper Market
Paper Products
Paper Based Laminates Market
Paper Products
Digital Printing Paper Market
Paper Products
Unbleached Softwood Kraft Pulp Market
Paper Products
North America Specialty Paper Market
Paper Products
Sawn Wood Market