
 Writing Paper Market | 2026-2036
Writing Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Writing Paper Market Analytics
Multi-source pulp procurement is shifting toward certified sustainable supply chains across the writing paper industry. International Paper leverages its North American forestland base to secure controlled wood certification. UPM-Kymmene anchors its competitive stance through integrated chemical pulp production in Finland. Stora Enso specializes in bio-based material alternatives that reduce fossil-derived binding agents.
Writing paper denotes cellulose-based sheet material engineered with specific grammage, brightness, and surface sizing for ink receptivity and archival stability, produced through kraft pulping and calendering to achieve uniform formation for handwriting and printing applications. Copy paper within the paper grade segment sustains the largest revenue pool due to bulk institutional contracting, while specialty paper commands the highest per-unit margins from artist-grade cotton fiber formulations. Notebook demand among students dominates volume throughput, though e-commerce as a distribution channel is capturing the fastest expansion in reorder frequency and SKU breadth.
The EPA enforces wastewater discharge limits under the Cluster Rule that elevate treatment capital for US mills, while the EU Ecodesign for Sustainable Products Regulation mandates recycled content thresholds that reshape fiber sourcing economics. China's MEE enforces stricter COD emission standards that filter smaller producers from export eligibility. Stakeholders must weigh certification investments against regional compliance fragmentation when allocating capacity expansion capital.
Market Dynamics
The writing paper market faces structural recalibration as virgin fiber content mandates under the EU Ecodesign for Sustainable Products Regulation force mills to reengineer pulp sourcing economics and certification pathways.
Growth Catalysts
- EU Ecodesign recycled content thresholds:Mandates under this regulation are pulling fiber investments toward circular supply chains, expanding certified recovered paper capacity across Nordic and Central European mills.
- Educational procurement expansion:Southeast Asian institutions are consolidating stationery purchasing through centralized tender programs, concentrating volume with suppliers meeting bulk delivery specifications.
- E-commerce channel penetration:Digital reorder platforms are compressing replenishment cycles for notebook and copy paper SKUs, particularly among small-office-home-office segments in India's tier-two cities.
Market Restraints
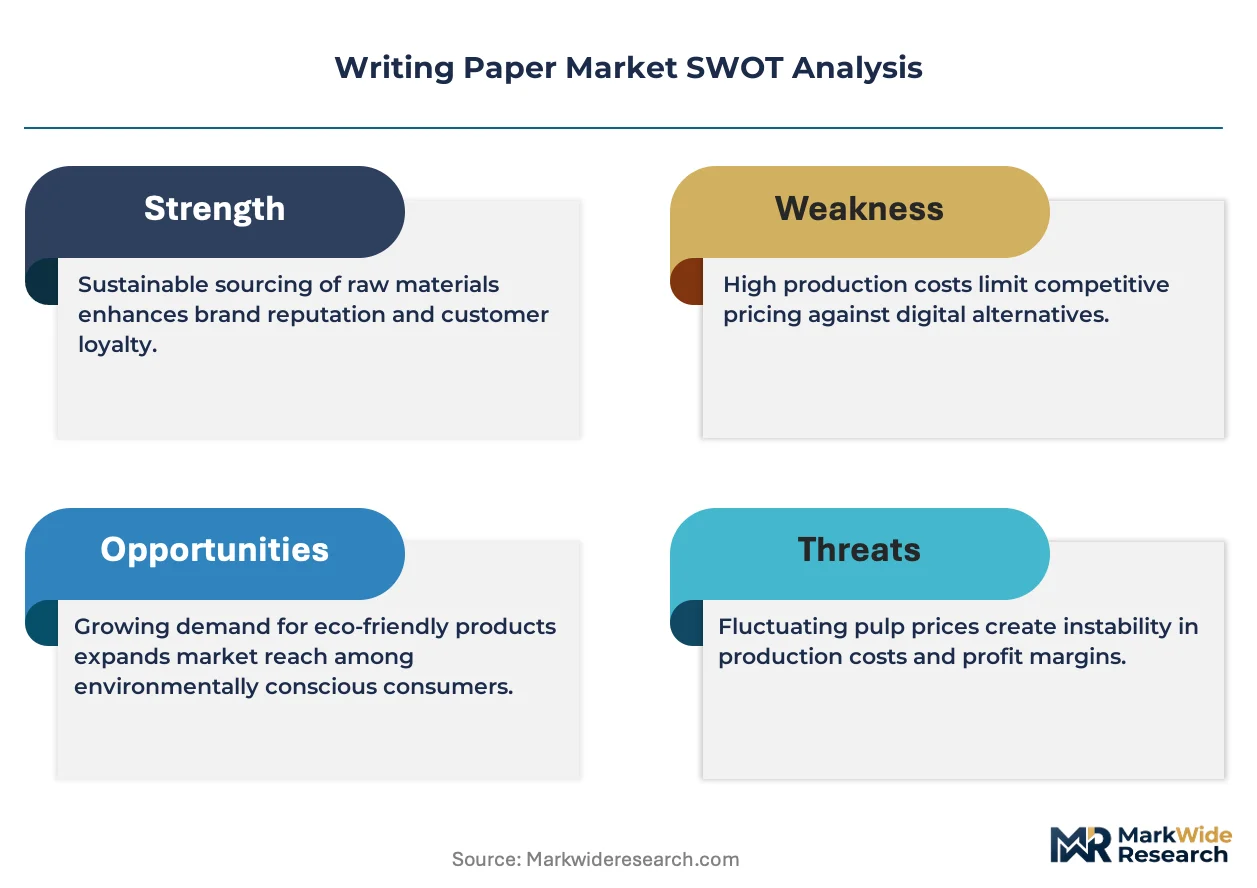
- Pulp cost volatility:Hardwood and softwood fiber prices fluctuate with energy-intensive kraft pulping costs, squeezing margin predictability for unintegrated producers lacking captive timberland.
- Regional supply concentration:Chemical pulp production clusters in Finland and Brazil create geographic vulnerability to port congestion and currency swings affecting landed cost in import-dependent markets.
- Digital substitution pressure:Tablet-based note-taking and cloud documentation platforms reduce per-student paper consumption in tertiary education segments across OECD economies.
Strategic Opportunities
- Tier-two city retail deepening:India's organized stationery chains are penetrating secondary urban centers where branded writing paper penetration remains below metro levels, creating whitespace for distribution partnerships.
- Bio-based binding agents:Convergence of lignin extraction technology with paper finishing processes enables fossil-free surface sizing, aligning with EU Green Deal procurement preferences.
- Artist-grade cotton fiber positioning:Specialty paper formulations using textile waste pulp streams command premium positioning in professional illustration and archival documentation segments.
Industry Challenges
- Certification timeline compression:FSC and PEFC chain-of-custody audits require 12-18 month implementation windows, delaying market access for mills transitioning from controlled wood to full certification.
- Wastewater treatment capex:EPA Cluster Rule discharge limits for absorbable organic halides and chlorinated compounds demand biological treatment upgrades costing $15-40 million per integrated mill.
- SKU proliferation complexity:E-commerce breadth requirements strain finishing line changeover efficiency, elevating working capital in inventory-holding distributors serving fragmented reorder patterns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Writing Paper Market |
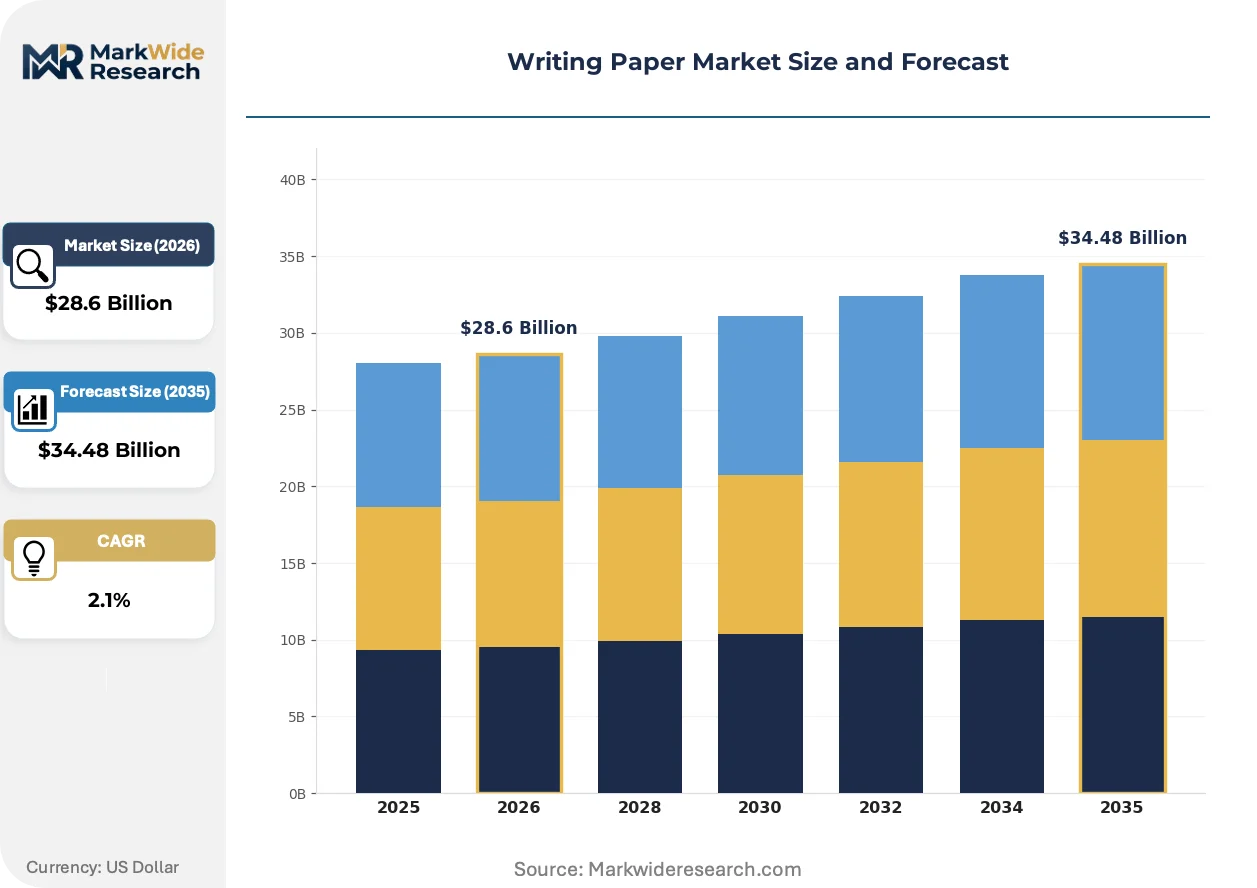
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $34.48 Billion |
| CAGR (2026 – 2036) | 2.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Notebooks, Loose Sheets, Writing Pads, Sketchbooks Paper Grade: Copy Paper, Notebook Paper, Specialty Paper, Recycled Paper End User: Students, Professionals, Artists, Schools Distribution Channel: Retail Stores, E-Commerce, Wholesale, Direct Sales |
| Companies Covered | International Paper, UPM-Kymmene Corporation, Stora Enso Oyj, Sappi Limited, Nippon Paper Industries Co., Ltd., Oji Holdings Corporation, WestRock Company, Mondi Group, Asia Pulp & Paper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Writing Paper Market Evolving Landscape
Automation and fiber traceability systems are restructuring how writing paper is specified, sourced, and delivered across institutional and retail channels.
Near-infrared spectroscopy is automating real-time fiber composition verification at mill intake points. North American and Nordic integrated producers are deploying these systems to validate recycled content percentages against EU Ecodesign thresholds. This technology is automating compliance documentation that previously required manual laboratory testing, compressing batch release timelines from days to hours.
REACH restrictions on formaldehyde-based wet-strength resins are forcing reformulation of copy paper surface chemistry. German and French mills are piloting glyoxal-free alternatives derived from chitosan biopolymers. Specialty paper grades requiring archival stability face the steepest adaptation costs, with premium cotton fiber producers accelerating certification under updated EU Ecolabel criteria.
Direct-to-institution procurement platforms are consolidating purchasing authority previously dispersed across departmental buyers. University systems in the United States and United Kingdom are aggregating annual copy paper requirements into single-source contracts with sustainability disclosure mandates. This consolidation is visible most acutely in California and England, where public procurement rules now require carbon footprint reporting alongside price evaluation.
Writing Paper Market Segmentation
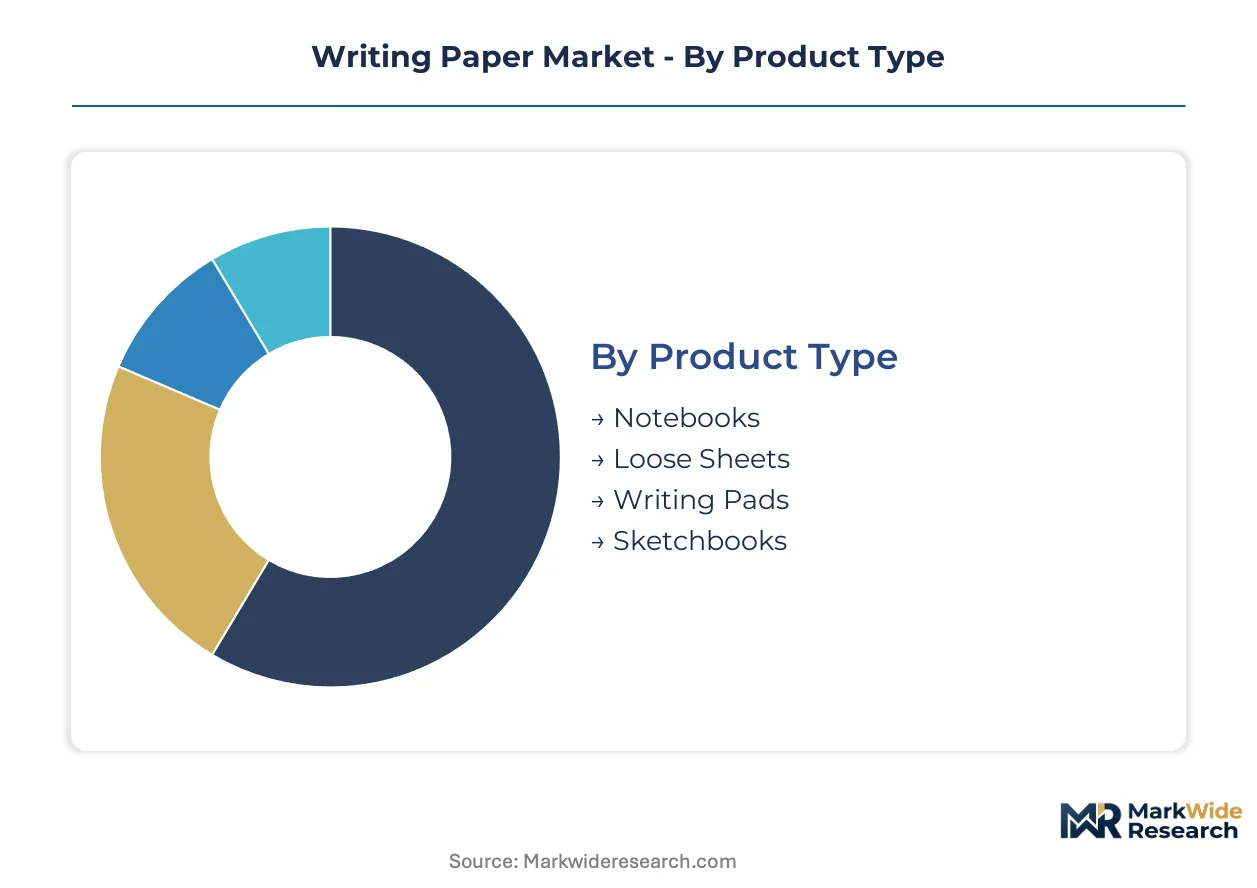
Writing paper demand fragments across distinct usage cycles, from semester-driven notebook replenishment to project-based specialty sheet procurement. Understanding these replacement rhythms illuminates where procurement authority concentrates and how channel preferences diverge across institutional versus individual buyers.
Product Type:
Upgrade cycles vary dramatically by format, with bound products commanding longer replacement intervals than consumable sheet formats.
- Notebooks:Spiral-bound and casebound formats with specified ruling patterns and page counts serve semester-length academic cycles. Demand concentrates in India's tier-two cities where organized retail chains are penetrating secondary education markets with branded SKUs.
- Loose Sheets:Unbound cellulose sheets sold in reams for institutional photocopying and laser printing operations. Schools across Southeast Asia are consolidating loose sheet procurement through centralized tender programs that specify brightness and grammage thresholds.
- Writing Pads:Glued-top or perforated formats designed for short-form notation and administrative correspondence. Legal and medical offices in Germany and France drive specification requirements for archival-quality surface sizing under updated EU Ecolabel criteria.
- Sketchbooks:Heavyweight sheets with tooth surfaces engineered for dry media reception. Artist communities in California and England prioritize cotton fiber content and acid-free certification for portfolio preservation.
Notebooks sit at the top of the volume ranking, with sketchbooks climbing the fastest as professional illustration segments expand.
Paper Grade:
Cost tiers separate commodity production from premium positioning, with fiber source and certification status driving price stratification.
- Copy Paper:Standardized uncoated woodfree sheets optimized for xerographic and inkjet reproduction. Bulk institutional contracting across US university systems sustains the largest revenue pool, with carbon footprint disclosure now mandatory under California and England public procurement rules.
- Specialty Paper:Formulations incorporating cotton fiber, laid finishes, or watermark security features for archival and ceremonial applications. Artist-grade specifications command the highest per-unit margins, with textile waste pulp streams enabling fossil-free positioning under EU Green Deal preferences.
- Notebook Paper:Medium-weight sheets with specific ruling and margin configurations for educational handwriting practice. BIS certification requirements in India filter import eligibility for products targeting government school procurement programs.
- Recycled Paper:Sheets manufactured from post-consumer recovered fiber meeting specified de-inked pulp percentages. EU Ecodesign recycled content thresholds are pulling Nordic and Central European mill investments toward circular supply chains and certified recovered paper capacity.
Copy paper sits at the top of the volume ranking, with specialty paper climbing the fastest as professional segments prioritize archival stability.
End User:
Customer type determines specification authority, with institutional buyers wielding consolidated purchasing power against fragmented individual decision-making.
- Students:Price-sensitive buyers prioritizing functional durability for semester-length usage cycles. E-commerce platforms are compressing replenishment cycles for this segment through subscription reorder models in India's expanding tier-two urban centers.
- Professionals:Administrative and legal practitioners requiring consistent sheet performance for client-facing documentation. REACH restrictions on formaldehyde-based wet-strength resins are forcing German and French mills to reformulate copy paper surface chemistry for this compliance-conscious segment.
- Artists:Professional illustrators and designers specifying tooth, weight, and fiber composition for media compatibility. Glyoxal-free alternatives derived from chitosan biopolymers are piloting in specialty grades serving this archival-priority segment.
- Schools:Centralized procurement authorities aggregating volume across departmental requirements. Direct-to-institution platforms in the United States and United Kingdom are consolidating purchasing authority previously dispersed across individual buyers, with sustainability disclosure mandates now standard in contract evaluation.
Students sit at the top of the volume ranking, with artists climbing the fastest as professional illustration markets expand.
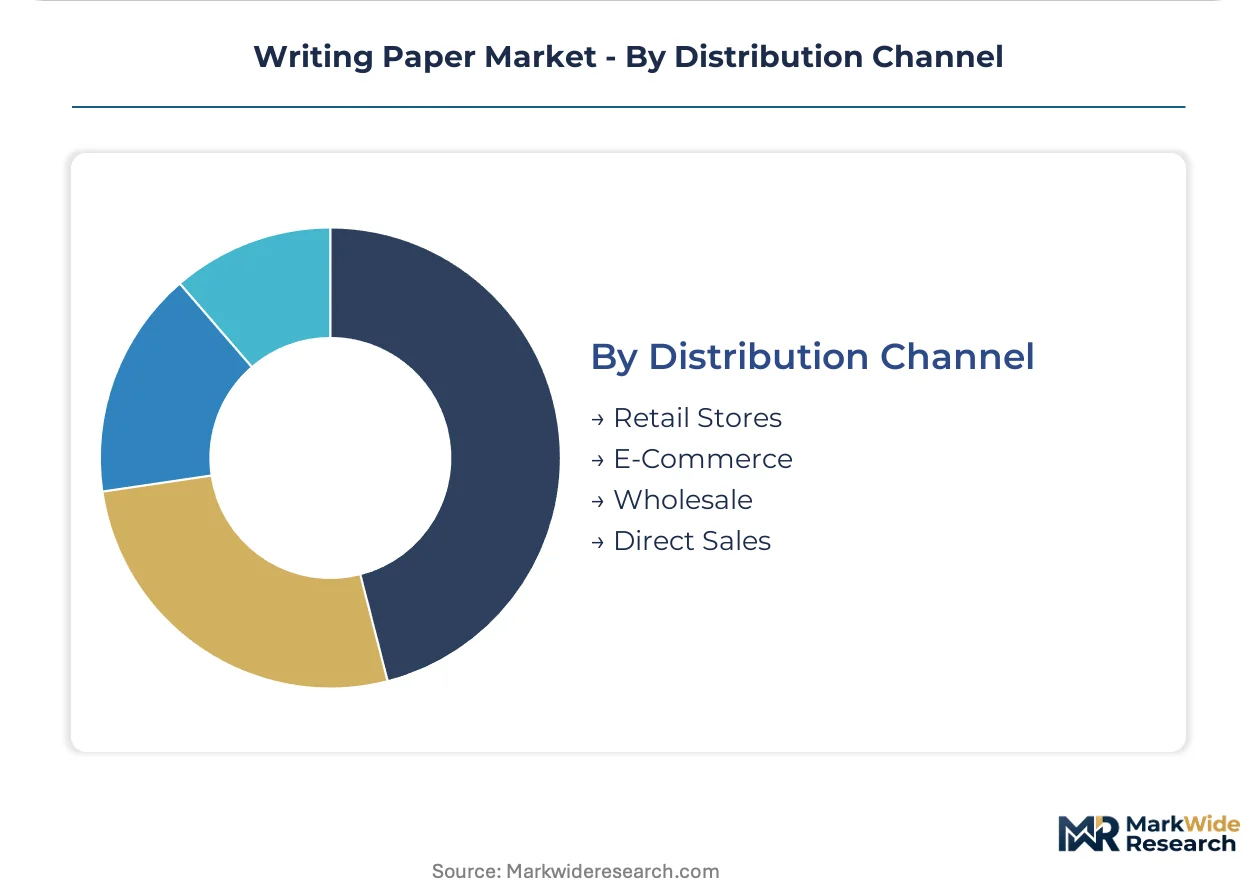
Distribution Channel:
Channel concentration shapes working capital requirements, with inventory-holding intermediaries facing pressure from direct digital fulfillment.
- Retail Stores:Physical stationery chains and office supply superstores carrying breadth across price tiers. Organized retail penetration in India's tier-two cities is deepening distribution reach where branded writing paper penetration remains below metro benchmarks.
- E-Commerce:Digital platforms enabling SKU breadth and subscription reorder patterns. This channel is capturing the steepest expansion trajectory in reorder frequency, particularly among small-office-home-office segments seeking convenience over price optimization.
- Wholesale:Volume distributors serving institutional and commercial accounts with pallet-scale fulfillment. SKU proliferation from e-commerce breadth requirements strains finishing line changeover efficiency, elevating working capital for distributors serving fragmented reorder patterns.
- Direct Sales:Manufacturer-to-institution contracts bypassing intermediary margin layers. University systems in California and England are aggregating annual requirements into single-source contracts with integrated sustainability reporting.
Retail stores sit at the top of the volume ranking, with e-commerce climbing the fastest as digital procurement platforms consolidate authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping capacity placement as mills migrate toward jurisdictions with lower compliance burdens or preferential fiber access. The EU Ecodesign for Sustainable Products Regulation's recycled content mandates have elevated European production costs relative to North American and Southeast Asian alternatives.
United States
University systems in California and England-style procurement consolidation is aggregating annual copy paper requirements into carbon-footprint-disclosed contracts. The EPA Cluster Rule enforces wastewater discharge limits that elevate treatment capital for integrated mills. Pacific Northwest pulp clusters supply controlled wood certification to domestic finishing operations.
Germany
Legal and medical offices drive specification requirements for archival-quality surface sizing under REACH restrictions on formaldehyde-based wet-strength resins. German mills pilot glyoxal-free alternatives derived from chitosan biopolymers. Rhine-Ruhr industrial corridor distributors serve fragmented reorder patterns from e-commerce breadth requirements.
Finland
Nordic integrated producers deploy near-infrared spectroscopy for real-time fiber composition verification against EU Ecodesign thresholds. Finnish chemical pulp production anchors competitive positioning through captive energy integration. Tampere and Kotka mill clusters expand certified recovered paper capacity under circular supply chain investments.
India
Organized stationery chains penetrate tier-two cities where branded writing paper penetration remains below metro benchmarks. BIS certification requirements filter import eligibility for government school procurement programs. Maharashtra and Gujarat distribution hubs serve expanding e-commerce subscription reorder models.
China
The MEE enforces stricter COD emission standards that filter smaller producers from export eligibility. Yangtze River Delta mills face wastewater treatment capex pressures while consolidating toward integrated producers. Shanghai and Jiangsu clusters reengineer pulp sourcing economics under tightening environmental enforcement.
Writing Paper Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based material alternatives and specialty-grade positioning. The vendor base concentrates around integrated forest products conglomerates with captive pulp supply and regional specialists serving institutional procurement channels. Three archetypes dominate: North American timberland-anchored multinationals, Nordic chemical pulp-integrated producers, and Asia-Pacific scale-driven exporters. Capacity expansion and certification investments represent the dominant competitive moves as mills adapt to fragmented regional compliance.
Among North American timberland-anchored producers, International Paper exemplifies controlled wood certification leverage through captive forestland assets. UPM-Kymmene Corporation occupies a position within the Nordic chemical pulp integration archetype, anchoring competitive stance through Finnish production clusters. Stora Enso Oyj represents the bio-based materials specialization vector, with Oyj suffix indicating Finnish public limited structure. These three entities illustrate how geographic origin and corporate form signal strategic positioning across certification-dependent procurement channels.
| Leading Market Players |
|---|
| International Paper |
| UPM-Kymmene Corporation |
| Stora Enso Oyj |
| Sappi Limited |
| Nippon Paper Industries Co., Ltd. |
| Oji Holdings Corporation |
| WestRock Company |
| Mondi Group |
| Asia Pulp & Paper |
| Others |
Value Network & Pricing Analysis
Hardwood pulp futures indices cascade through kraft pulping cost structures into three-tier pricing stratification across premium cotton fiber, certified recycled, and commodity woodfree grades. EU Ecodesign compliance premiums widen spreads against Brazilian and Southeast Asian supply as certification investments concentrate pricing power among Nordic and North American integrated producers.
Pricing Analysis
Input-cost pass-through from energy-intensive chemical pulping operations compresses margins for unintegrated mills lacking captive timberland. Pricing stratifies across premium, standard, and economy tiers based on fiber certification status and archival-grade surface chemistry specifications. Cost compression in commodity copy paper intensifies as Chinese COD enforcement filters smaller producers from export eligibility. Students in India's tier-two cities exhibit highest price sensitivity, while professional legal and medical offices in Germany and France absorb premiums for REACH-compliant glyoxal-free formulations.
Supply Chain Analysis
Reverse-logistics flows of post-consumer recovered paper feed Nordic mill intake points where near-infrared spectroscopy validates EU Ecodesign recycled content thresholds. Geographic supply concentration centers on Finland, Brazil, and Indonesia for chemical pulp production, with Yangtze River Delta finishing clusters serving Asian demand. Raw material dependencies rest on eucalyptus hardwood, northern softwood, and textile waste pulp streams. Single-source vulnerability runs through Baltic Sea port congestion affecting Finnish pulp export schedules. Distribution runs through wholesale pallet-scale fulfillment to institutional buyers and e-commerce subscription platforms for fragmented retail reorder patterns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Ecodesign compliance costs elevate European production relative to Southeast Asian export capacity with weaker environmental enforcement.
For Market Incumbents: Anchor competitive position through backward integration into certified forestland assets and captive chemical pulp production. Defend against digital substitution pressure by accelerating bio-based binding agent R&D and FSC chain-of-custody certification investments. Prioritize capacity control in Finland and Brazil to mitigate currency swing exposure on landed costs. For New Entrants and Emerging Players: Launch via direct-to-institution procurement platforms consolidating previously fragmented departmental purchasing authority. Target India's tier-two cities where organized retail penetration remains below metro benchmarks and BIS certification filters import competition. Pursue artist-grade cotton fiber positioning using textile waste pulp streams for fossil-free premium tier entry. For Investors and Strategic Acquirers: Asymmetric upside sits with bio-based material specialists possessing lignin extraction technology and EU Green Deal procurement alignment. Long-term viability over the next decade favors integrated producers with circular supply chain infrastructure and real-time fiber traceability systems. Monitor EPA Cluster Rule enforcement intensity and MEE COD standard tightening as inflection indicators for regional cost competitiveness shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Recovered Paper Capacity Expansion | Nordic mills validate EU Ecodesign thresholds through near-infrared spectroscopy automation. |
| Bio-Based Binding Agent Transition | German and French mills pilot chitosan biopolymer alternatives under REACH formaldehyde restrictions. |
| Direct-to-Institution Platform Launch | California and England university systems aggregate annual requirements with carbon footprint disclosure mandates. |
| Tier-Two City Distribution Partnership | Maharashtra and Gujarat hubs serve expanding e-commerce subscription models in underpenetrated secondary urban centers. |
| Artist-Grade Cotton Fiber Certification | Textile waste pulp streams enable fossil-free positioning under EU Green Deal procurement preferences. |
Research Methodology
Coverage spans the United States, Germany, Finland, India, and China, with primary inputs from each market cluster combining interviews with mill operations directors, procurement leads at university systems, stationery retail category managers, and regulatory compliance officers. Secondary validation draws from EPA discharge filings, EU Ecodesign implementing measures, BIS certification registries, and customs trade data for pulp and finished paper flows. Bottom-up capacity modeling triangulates against top-down demand aggregation across academic, professional, and artist end-use segments.
Granularity-level modeling disaggregates volume and value across product type, paper grade, end user, and distribution channel dimensions throughout the forecast period. CAGRs derive from segment-specific replacement cycle analysis and procurement pattern elasticity. Industry-specific inputs include semester-driven notebook replenishment rhythms, institutional tender consolidation trends, and e-commerce SKU proliferation effects on finishing line efficiency.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt regulatory enforcement shifts or pulp price volatility spikes. Practitioners should monitor EU Ecodesign threshold revisions, EPA Cluster Rule implementation timing, and MEE emission standard tightening for early signals of regional cost structure divergence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Global Paper Chemical Market
Paper Products
Africa Tissue Paper Market
Paper Products
Hardwood Pulp Market
Paper Products
Unbleached Kraft Pulp Market
Paper Products
Inlay Paper Market
Paper Products
Fluff Pulp Market
Paper Products
Wood-Based Panel Market
Paper Products
Bleached Hardwood Kraft Pulp Market
Paper Products
Solid Bleached Board Market
Paper Products
Decorative Plastic and Paper Laminates Market
Paper Products
Thin Printing Paper Market
Paper Products
Veneer Sheets Market
Paper Products
Europe Thermal Paper Market
Paper Products
Digital Printing Paper Market
Paper Products
Liquid Paperboard Market
Paper Products
Paper Making Machine Market