
 Europe Glucagon-Like Peptide-1 (GLP-1) Agonists Market | 2026-2036
Europe Glucagon-Like Peptide-1 (GLP-1) Agonists Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Glucagon-Like Peptide-1 (GLP-1) Agonists Market Foresight
Project finance for manufacturing facilities and asset-light licensing partnerships is rewriting competitive entry dynamics in European GLP-1 agonists. Novo Nordisk leverages captive biologics production to sustain supply security across Northern European markets. Eli Lilly and Company anchors its position through high-volume fermentation capacity and active pharmaceutical ingredient control. Sanofi competes via differentiated formulation expertise, particularly in sustained-release delivery technologies.
GLP-1 agonists are synthetic peptide analogs of endogenous glucagon-like peptide-1, typically formulated as acylated or non-acylated derivatives with half-life extensions achieved through albumin binding or fatty acid conjugation, designed to enhance glucose-dependent insulin secretion and suppress glucagon release in type 2 diabetes and obesity management. Semaglutide dominates current prescription volumes across European reimbursement formularies, reflecting its once-weekly dosing profile and cardiovascular outcome benefits. The oral delivery mode segment represents the fastest-expanding structural category, though injection formulations retain the deepest margin pools due to established manufacturing scale and biosimilar barriers. Therapy area concentration in obesity is accelerating fastest, yet type 2 diabetes maintains the largest absolute revenue base across hospital and pharmacy channels.
EMA's centralized marketing authorization procedures and the EU MDR's tightened device-drug combination requirements shape product standards and market access timelines for GLP-1 delivery systems. National health technology assessment bodies in Germany, France, and England impose incremental evidence thresholds that filter reimbursement eligibility and prescribing volume. Stakeholders must monitor HTA convergence patterns and manufacturing capacity commitments to anticipate supply allocation and pricing leverage shifts across European markets.
Market Dynamics
EMA's tightened reimbursement criteria and the EU MDR's device-drug combination requirements are compressing market access timelines while hospital procurement centralization concentrates volume allocation among fewer suppliers across Northern European markets.
Growth Catalysts
- Centralized Hospital Procurement:Germany, France, and the United Kingdom are consolidating GLP-1 agonist purchasing through specialist prescribing networks, amplifying volume concentration for formulary-approved therapies.
- EU MDR Compliance Pathways:The Medical Device Regulation's pre-market authorization requirements for combination products are filtering out marginal competitors and elevating standards for delivery system innovation.
- Integrated Care Pathways:Chronic disease management reforms across European health systems are embedding GLP-1 agonists into multi-disciplinary obesity and diabetes treatment protocols.
Market Restraints
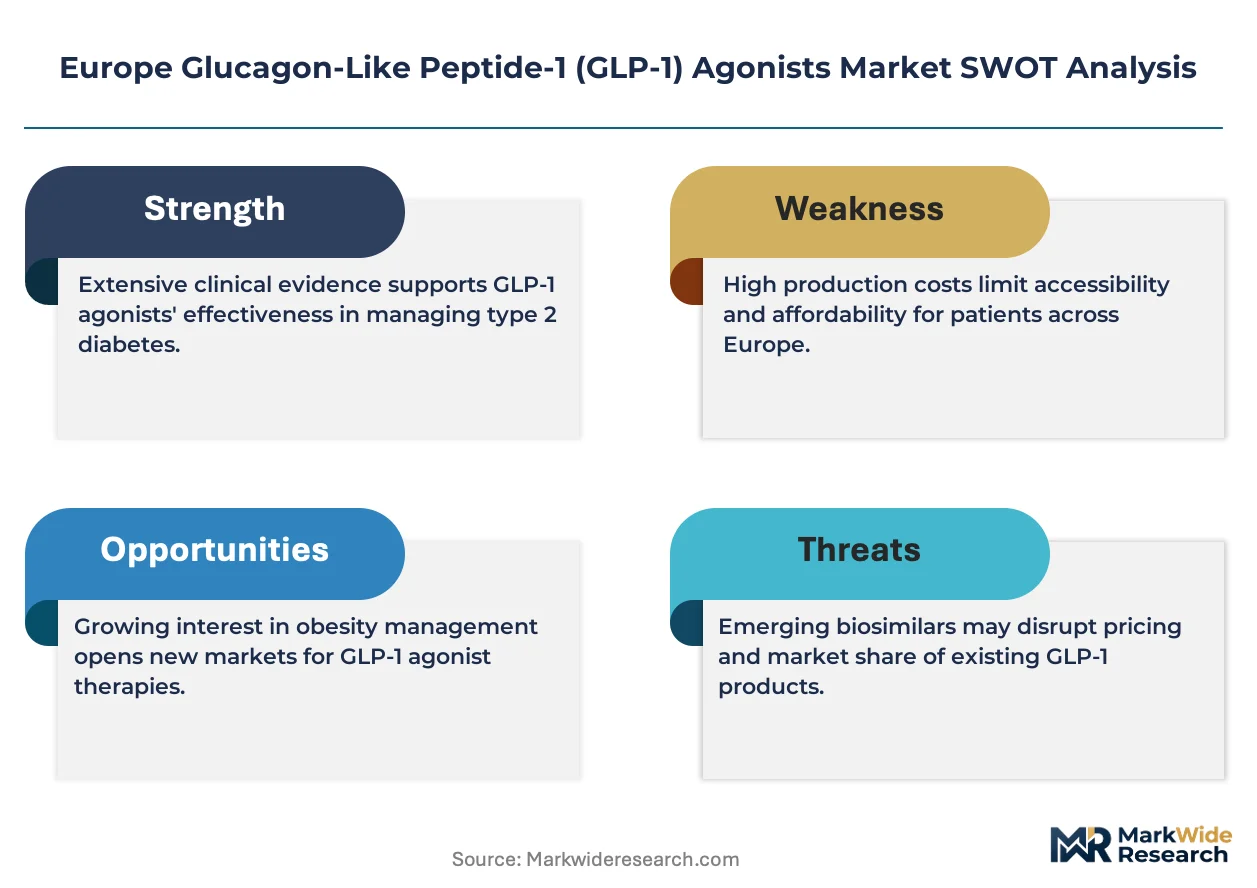
- Peptide Manufacturing Concentration:Fermentation capacity for long-acting acylated derivatives concentrates among a handful of Northern European biologics facilities, creating supply vulnerability during demand surges.
- HTA Evidence Thresholds:Germany's IQWiG and England's NICE impose incremental cost-effectiveness requirements that delay reimbursement decisions for novel formulations.
- Biosimilar Development Barriers:Complex immunogenicity profiles and formulation patents obstruct generic entry, sustaining incumbent pricing power but limiting competitive pressure.
Strategic Opportunities
- Oral Delivery Expansion:Non-injectable peptide absorption technologies open pharmacy-channel access beyond hospital-based specialist networks.
- Cardiovascular Outcome Labeling:EMA's willingness to approve expanded indications for heart failure and stroke risk reduction creates differentiation pathways for agents with proven cardiac benefits.
- Eastern European Penetration:Poland, Romania, and Czechia present underdeveloped reimbursement infrastructure where private-pay obesity segments outpace public formulary adoption.
Industry Challenges
- Biologics Talent Scarcity:Peptide process development and analytical characterization expertise concentrates among experienced cohorts approaching retirement across Danish and Swiss manufacturing hubs.
- Cold Chain Integrity:Multi-dose pen devices require maintained temperature controls through last-mile distribution to pharmacies, complicating logistics in Southern European markets with fragmented wholesale networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Glucagon-Like Peptide-1 (GLP-1) Agonists Market |
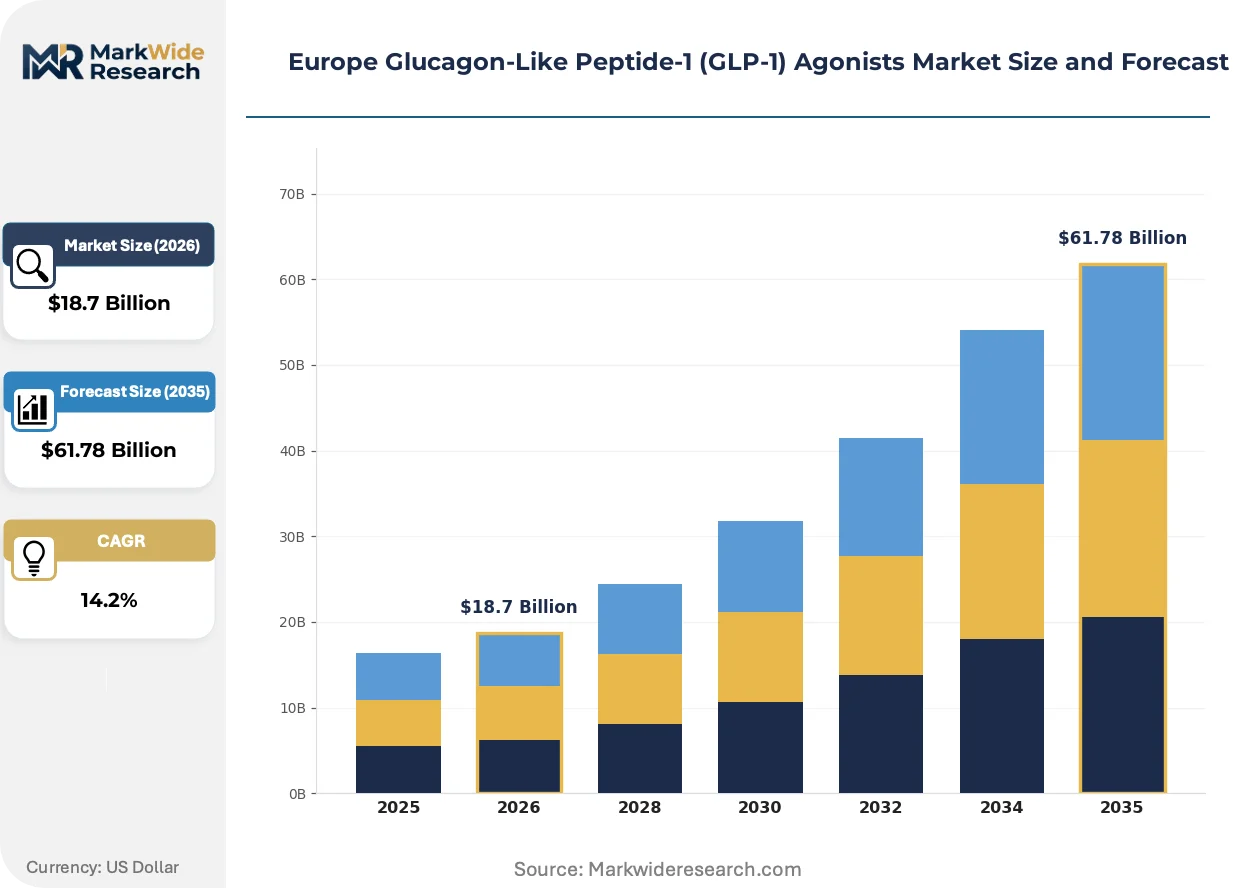
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Exenatide, Liraglutide, Dulaglutide, Semaglutide Delivery Mode: Injection, Oral, Inhalation, Transdermal Therapy Area: Type 2 Diabetes, Obesity, Metabolic Syndrome, Cardiovascular Disease End User: Hospitals, Clinics, Home Care, Pharmacies |
| Companies Covered | Novo Nordisk, Eli Lilly and Company, Sanofi, AstraZeneca, Pfizer, Biocon, Novartis, Boehringer Ingelheim, Zealand Pharma, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Glucagon-Like Peptide-1 (GLP-1) Agonists Market Shifts & Advancements
Delivery system miniaturization and digital health integration are compressing the boundary between pharmaceutical therapy and connected medical devices, while reimbursement models pivot toward outcomes-based contracts.
Dual-chamber injection devices with embedded connectivity sensors are virtualizing patient adherence monitoring by transmitting dosing timestamps to prescriber dashboards. Hospital endocrinology departments in Germany and the Netherlands are piloting these systems for high-risk obesity cohorts. This virtualization is compressing the role of traditional pharmacy-based refill tracking and enabling real-time intervention protocols.
EMA's centralized marketing authorization procedures now mandate cardiovascular outcome trial data for all novel GLP-1 agonists seeking type 2 diabetes indications. This regulatory elevation extends development timelines by eighteen to twenty-four months but elevates clinical evidence standards across the therapeutic class. Manufacturers are responding by embedding cardiac safety endpoints earlier in phase II programs.
Specialist prescribing networks are consolidating procurement authority through regional tender boards in France and hospital trusts in England. Traditional wholesale distribution faces disintermediation as direct-to-pharmacy agreements with centralized purchasing bodies capture volume allocation. This restructuring is most visible in Scandinavian markets where Apoteket and regional hospital pharmacies negotiate exclusive supply contracts.
Europe Glucagon-Like Peptide-1 (GLP-1) Agonists Market Segmentation
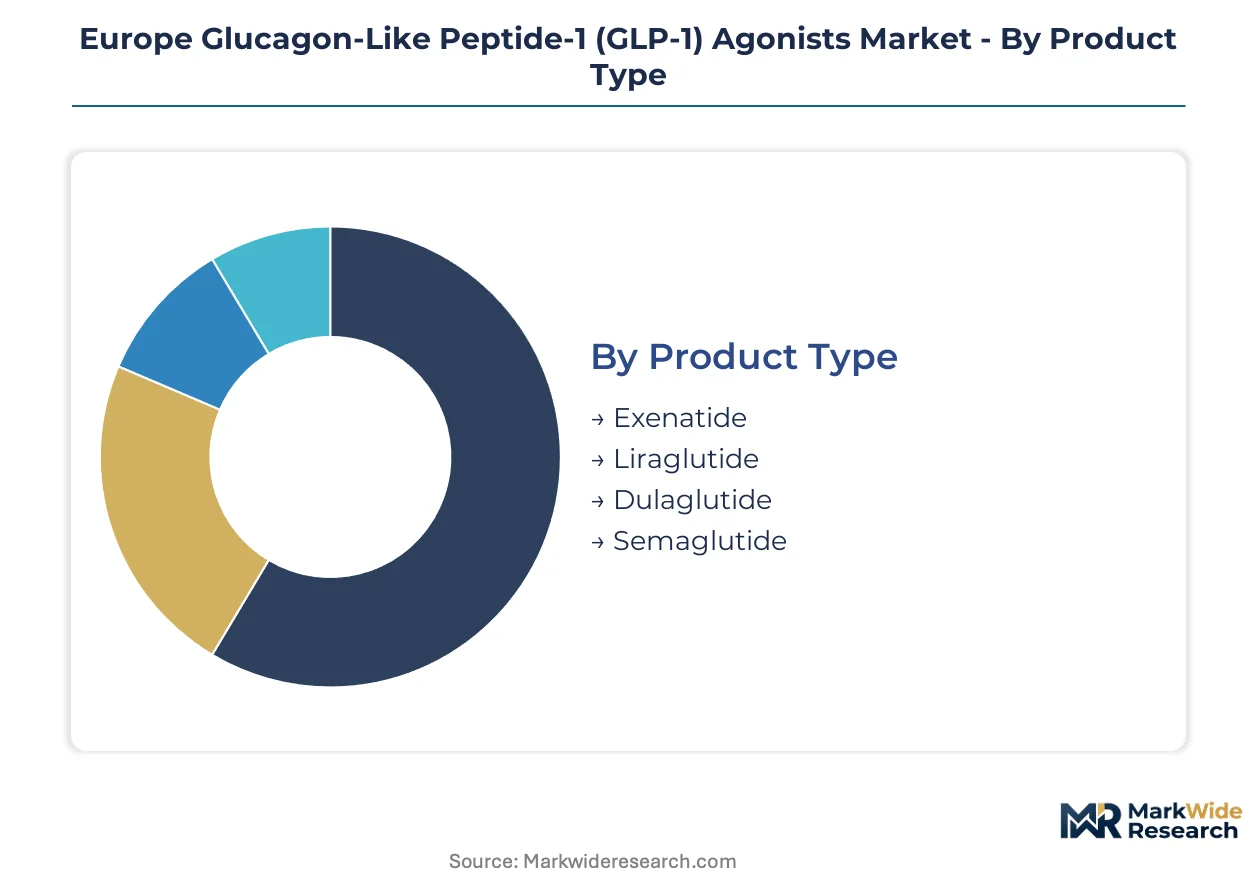
GLP-1 agonist segmentation reveals how formulation chemistry, delivery technology, and care setting intersect to determine reimbursement access and prescribing volume across European markets. Manufacturers configure portfolio depth around these dimensions to secure formulary positioning and defend against biosimilar pressure.
Product Type:
Mature acylated peptides anchor hospital formularies while emerging derivatives reshape competitive dynamics through cardiovascular labeling advantages.
- Exenatide:The first approved GLP-1 agonist employs a synthetic exendin-4 peptide structure with twice-daily or extended-release weekly dosing. German hospital pharmacies maintain residual volume for price-sensitive diabetes protocols where newer agents face reimbursement delays.
- Liraglutide:An acylated human GLP-1 analog with albumin-binding fatty acid side chains enabling once-daily administration. France's HAS and England's NICE have established extensive real-world evidence databases for this agent, entrenching it in obesity treatment pathways despite weekly competitor alternatives.
- Dulaglutide:A fusion protein combining GLP-1 analog with modified immunoglobulin Fc fragment for extended half-life. Eli Lilly's manufacturing scale supports volume tenders across Nordic hospital procurement consortia.
- Semaglutide:Engineered with C18 fatty di-acid chain and non-covalent albumin association for superior half-life extension. EMA's approval of cardiovascular outcome claims has accelerated specialist prescribing across German and UK cardiology-endocrinology integrated clinics.
Semaglutide handles the majority of throughput; semaglutide is also the fastest mover on share through oral formulation expansion.
Delivery Mode:
Route of administration determines cold chain requirements, patient adherence profiles, and margin architecture across pharmacy versus hospital channels.
- Injection:Pen devices and pre-filled syringes dominate current prescribing through established reimbursement codes and specialist administration training infrastructure. Scandinavian markets concentrate multi-dose pen procurement through regional tender boards, compressing price variation.
- Oral:Semaglutide tablets employing absorption enhancer technology (SNAC) enable non-specialist prescribing and pharmacy-channel distribution beyond hospital endocrinology departments. Netherlands pilot programs demonstrate adherence advantages for employed populations unwilling to inject.
- Inhalation:Dry powder and nebulized peptide formulations remain developmental with limited European clinical trial infrastructure. Thermostability advantages could eventually bypass cold chain constraints in Southern European markets with fragmented logistics.
- Transdermal:Microneedle patch and iontophoresis technologies for peptide delivery are preclinical or early-phase, facing EMA's EU MDR combination product scrutiny for device constituent qualification.
Injection retains the deepest installed base; oral delivery is expanding most quickly through retail pharmacy access.
Therapy Area:
Clinical indication breadth determines pricing flexibility and competitive differentiation as regulators tighten evidence requirements for novel claims.
- Type 2 Diabetes:The foundational indication with established HbA1c reduction endpoints and cardiovascular outcome trial mandates. German sickness funds and NHS England allocate largest absolute budgets here, though volume growth decelerates as market penetration matures.
- Obesity:Weight management protocols are accelerating fastest across private-pay segments in Eastern Europe and reimbursed pathways in France where ANSM has streamlined obesity pharmacotherapy access. Body mass index threshold criteria vary across national formularies.
- Metabolic Syndrome:Clustered risk factor targeting remains off-label or restricted across most European reimbursement systems, limiting commercial traction despite mechanistic rationale.
- Cardiovascular Disease:Heart failure with preserved ejection fraction and stroke risk reduction labels are emerging through EMA's expanded indication pathway, creating premium positioning opportunities for agents with proven cardiac benefit.
Type 2 diabetes commands the largest absolute revenue; obesity is gaining share fastest through indication expansion and private-market penetration.
End User:
Care setting concentration shapes procurement leverage and determines whether volume flows through centralized tender processes or fragmented retail channels.
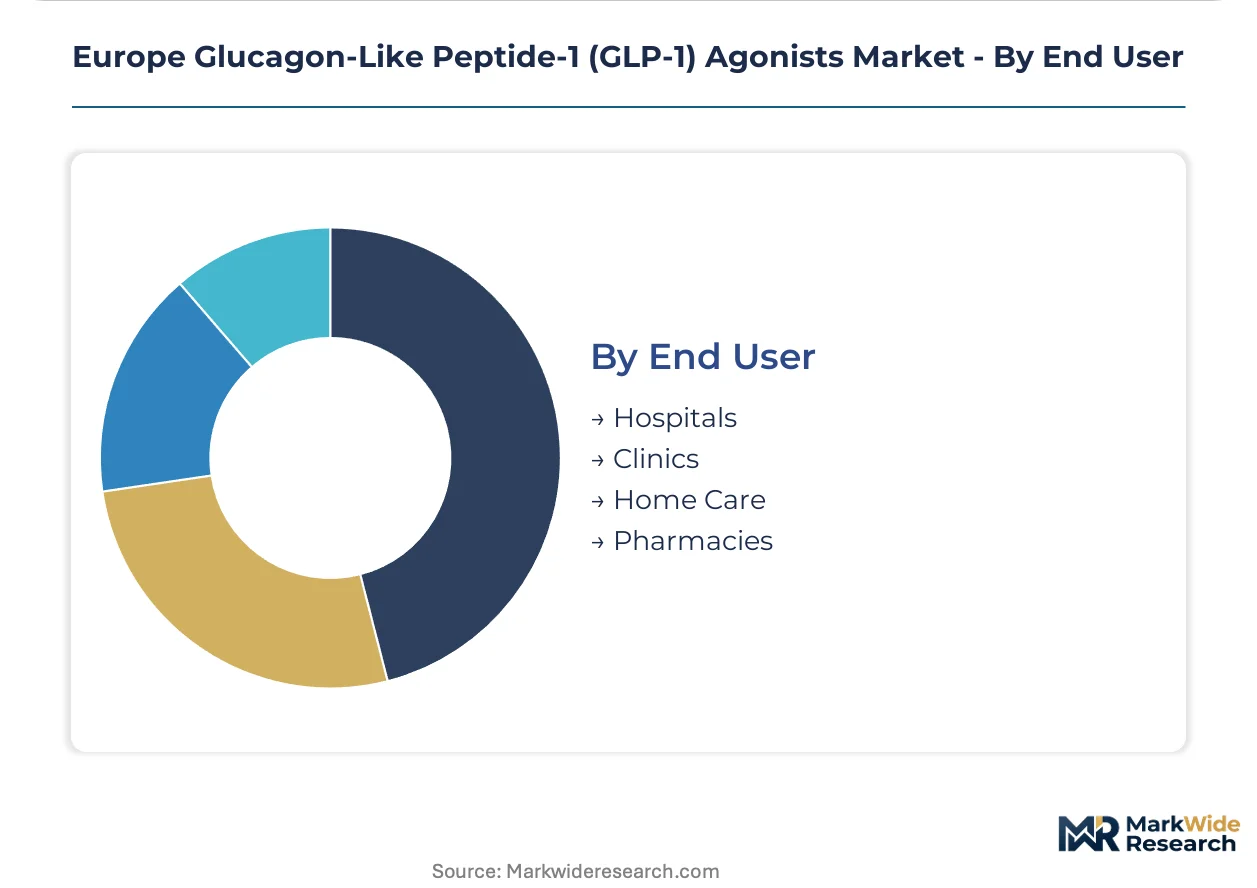
- Hospitals:Tertiary care endocrinology departments in Germany, France, and the United Kingdom administer complex initiation protocols and high-risk patient cohorts. Regional hospital trusts and university medical centers negotiate exclusive supply contracts with manufacturers.
- Clinics:Specialist diabetes and obesity outpatient facilities in the Netherlands and Denmark manage maintenance dosing for stabilized patients, bridging hospital initiation and community pharmacy refill.
- Home Care:Self-administration by patients with established tolerance profiles reduces healthcare system costs but requires cold chain integrity through last-mile delivery to residential addresses.
- Pharmacies:Community and hospital outpatient pharmacies handle prescription fulfillment, with automated dispensing systems in Sweden and Finland tracking adherence through national health identifier integration.
Hospitals control initiation volume and formulary gatekeeping; pharmacies are the fastest-expanding channel through oral formulation retail distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's GLP-1 agonist trade flows reflect a net import position for finished pharmaceutical products, with bulk peptide fermentation concentrated in Northern European biologics clusters and formulation fill-finish distributed across regional manufacturing networks serving hospital and pharmacy channels.
Germany
IQWiG's health technology assessments filter reimbursement eligibility for novel GLP-1 formulations, concentrating prescribing volume within sickness fund formularies. The country's national pharmaceutical regulator maintains stringent evidence requirements for cardiovascular outcome claims. Bavaria and North Rhine-Westphalia host tertiary endocrinology centers that negotiate exclusive supply contracts through regional hospital procurement consortia.
France
ANSM has streamlined obesity pharmacotherapy access pathways, accelerating specialist prescribing for weight management indications. HAS evaluates incremental cost-effectiveness through real-world evidence databases that entrench established agents in treatment protocols. The Île-de-France region anchors hospital-based initiation volume through integrated diabetes-obesity care networks in Parisian university medical centers.
United Kingdom
NICE imposes evidence thresholds that delay reimbursement decisions for novel GLP-1 derivatives, filtering market access through technology appraisal processes. NHS England allocates budgets through integrated care systems that concentrate volume among formulary-approved therapies. London and the Midlands host specialist prescribing networks managing high-risk obesity cohorts through regional hospital trusts.
Netherlands
Pilot programs demonstrate adherence advantages for oral semaglutide among employed populations unwilling to inject, expanding pharmacy-channel distribution. The country's national health identifier integration enables automated dispensing systems to track patient adherence. The Randstad cluster bridges hospital initiation and community pharmacy refill through specialist diabetes outpatient facilities.
Poland
Private-pay obesity segments outpace public formulary adoption, creating demand concentration outside reimbursed pathways. The country's national pharmaceutical regulator processes marketing authorization applications through decentralized procedures. Warsaw and Krakow host emerging private clinic networks specializing in metabolic disease management for self-funded patient cohorts.
Europe Glucagon-Like Peptide-1 (GLP-1) Agonists Market Competitive Landscape
On the supply side, the industry is consolidating around captive biologics production and high-volume fermentation capacity, with peptide manufacturing concentration creating barriers for marginal entrants. Three archetypes dominate: integrated pharmaceutical conglomerates with in-house fermentation assets, specialty biologics contractors with formulation expertise, and emerging oral delivery technology developers. Competitive moves center on manufacturing capacity commitments and strategic licensing partnerships for non-injectable absorption platforms.
Among Northern European integrated manufacturers, Novo Nordisk anchors the fermentation-dependent tier through Danish biologics production, while Eli Lilly and Company exemplifies scale-driven API control through high-volume manufacturing infrastructure. Sanofi occupies a differentiated position through sustained-release delivery technology specialization. These three represent distinct strategic postures within a market where formulation chemistry and manufacturing scale determine procurement leverage across centralized European tender processes.
| Leading Market Players |
|---|
| Novo Nordisk |
| Eli Lilly and Company |
| Sanofi |
| AstraZeneca |
| Pfizer |
| Biocon |
| Novartis |
| Boehringer Ingelheim |
| Zealand Pharma |
| Others |
Supply & Pricing Matrix
Fermentation capacity utilization above 85% across Danish and Swiss biologics clusters is compressing spot-market peptide availability and amplifying incumbent pricing power against tender-dependent hospital buyers. This tightness propagates through EMA-regulated supply chains as multi-year manufacturing commitments lock in volume allocation ahead of HTA reimbursement decisions.
Pricing Analysis
Hospital procurement consortia anchor contract-based long-term offtake pricing across German, French, and UK markets, with differentiation driven by cardiovascular outcome certification tiers and cold chain service bundling. Cost compression in standard-tier injection formulations is intensifying because biosimilar development barriers sustain incumbent margin pools while oral delivery entrants compete on pharmacy-channel access. Price-sensitive Eastern European private-pay segments contrast with least-sensitive German sickness funds prioritizing clinical evidence depth over unit cost.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard across peptide API procurement contracts as manufacturers finance working capital through supply-chain finance facilities. Bulk fermentation concentrates in Denmark, Switzerland, and Ireland, with fill-finish distribution drawing from regional networks in Germany, France, and the Netherlands. Single-source vulnerability persists for C18 fatty di-acid side chain inputs and specialized absorption enhancers. Distribution runs through direct-to-pharmacy agreements with centralized hospital procurement bodies, bypassing traditional wholesale intermediaries in Scandinavian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where regulatory entrenchment through EMA cardiovascular outcome trial mandates creates switching costs that protect incumbent formulary positions against emerging delivery technologies.
For Market Incumbents: Pre-empt oral delivery erosion by securing exclusive pharmacy distribution partnerships ahead of HTA reimbursement pathway expansion for non-injectable formulations. Expand captive biologics capacity in Northern European clusters to tighten supply security against emerging fermentation-dependent entrants. Prioritize cardiovascular outcome label maintenance through phase II cardiac safety endpoint embedding. For New Entrants and Emerging Players: Pursue private-pay obesity segments in Poland, Romania, and Czechia where reimbursement infrastructure gaps create white-space access outside centralized hospital procurement. Target oral peptide absorption technology licensing to bypass injection-formulation patent thickets and cold chain infrastructure requirements. Position through direct-to-consumer digital health platforms that virtualize adherence monitoring for employed populations. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across oral delivery technology development as SNAC-based absorption platforms require specialized formulation R&D infrastructure. Long-term viability favors acquisition targets with differentiated device-drug combination expertise aligned with EU MDR compliance pathways. Watch EMA expanded indication approvals for heart failure and stroke risk reduction as signals of premium pricing sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Eli Lilly's high-volume fermentation investments secure API control across Nordic hospital procurement consortia. |
| Regulatory Approval Pathway | EMA's cardiovascular outcome trial mandates filter market access and elevate clinical evidence standards. |
| Licensing Agreement | Oral delivery technology partnerships bypass injection-formulation barriers and expand pharmacy-channel reach. |
| Hospital System Partnership | Exclusive supply contracts with German regional hospital trusts concentrate volume allocation among formulary-approved therapies. |
| Pipeline Diversification | Dual-chamber connected devices with embedded sensors virtualize adherence monitoring for high-risk obesity cohorts. |
Research Methodology
A standing panel of drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from EMA centralized procedure filings, national HTA body assessments in Germany, France, and England, ClinicalTrials.gov cardiovascular outcome trial registrations, and hospital formulary database audits. Bottom-up prescription volume modeling and top-down reimbursement budget allocation analysis were triangulated against manufacturing capacity disclosures.
Scenario bracketing anchored volume projections across low, base, and high cases reflecting HTA evidence threshold variability and oral delivery adoption pace. Segmentation dimensions spanned product type, delivery mode, therapy area, and end-user care setting, with regional regulatory clusters modeled separately. CAGRs were derived from prescription volume trajectories and pricing elasticity assumptions calibrated to tender board behavior. Forecast inputs included EMA approval timelines, national reimbursement decision lags, and manufacturing capacity expansion announcements.
The forecast holds incumbent behavior within observed patterns; aggressive moves by oral peptide technology developers or biosimilar fermentation specialists would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Latin America Generic Injectables Market
Pharmaceuticals
Diphtheria Tetanus Pertussis Vaccine Market
Pharmaceuticals
New Zealand Diabetes Drugs Market
Pharmaceuticals
Alkylating Agents Market
Pharmaceuticals
Bisphosphonates Market
Pharmaceuticals
Esophageal Achalasia Drug Market
Pharmaceuticals
Collagenase Clostridium Histolyticum Market
Pharmaceuticals
Traumatic Brain Injury Drugs Market
Pharmaceuticals
Asia-Pacific Vaccines Market
Pharmaceuticals
Global Anti-Suicide Drugs Market
Pharmaceuticals
Trulicity Market
Pharmaceuticals
Global Anti-Infective Agents Market
Pharmaceuticals
Asia-Pacific Contraceptive Drugs and Devices Market
Pharmaceuticals
Dopamine and Norepinephrine Reuptake Inhibitor Market
Pharmaceuticals
Bulbospinal Muscular Atrophy Drugs Market
Pharmaceuticals
Global Pediatric Drugs Market