
 Anesthesia Breathing Circuits Market | 2026-2036
Anesthesia Breathing Circuits Market Size, Share, and Industry Trends Forecast 2026-2036
Anesthesia Breathing Circuits Market Analysis
The certified respiratory therapy technician workforce is collapsing across developed healthcare systems, forcing hospitals toward pre-assembled circuit kits that reduce bedside setup complexity. Medtronic plc leverages its vertical manufacturing footprint to sustain kit production at scale across North American distribution hubs. Fisher & Paykel Healthcare anchors its position through heated humidification integration within breathing circuits, a technical specialization that differentiates its product line from commodity competitors.
Anesthesia breathing circuits are closed or semi-closed conduit assemblies—typically constructed from medical-grade polyvinyl chloride, silicone, or polypropylene with standard 22mm/15mm connector diameters—that deliver anesthetic gases, oxygen, and ventilation support while scavenging exhaled agents. Their primary purpose is maintaining precise gas composition, pressure, and humidity control during controlled sedation or general anesthesia. Circuit kits dominate product-type revenue due to bundled procurement contracts, while laryngeal masks compete aggressively in ambulatory settings where rapid airway establishment reduces turnover time. High-flow delivery modes are gaining fastest among application segments, particularly in cardiac procedures where precise oxygenation management supports hemodynamic stability.
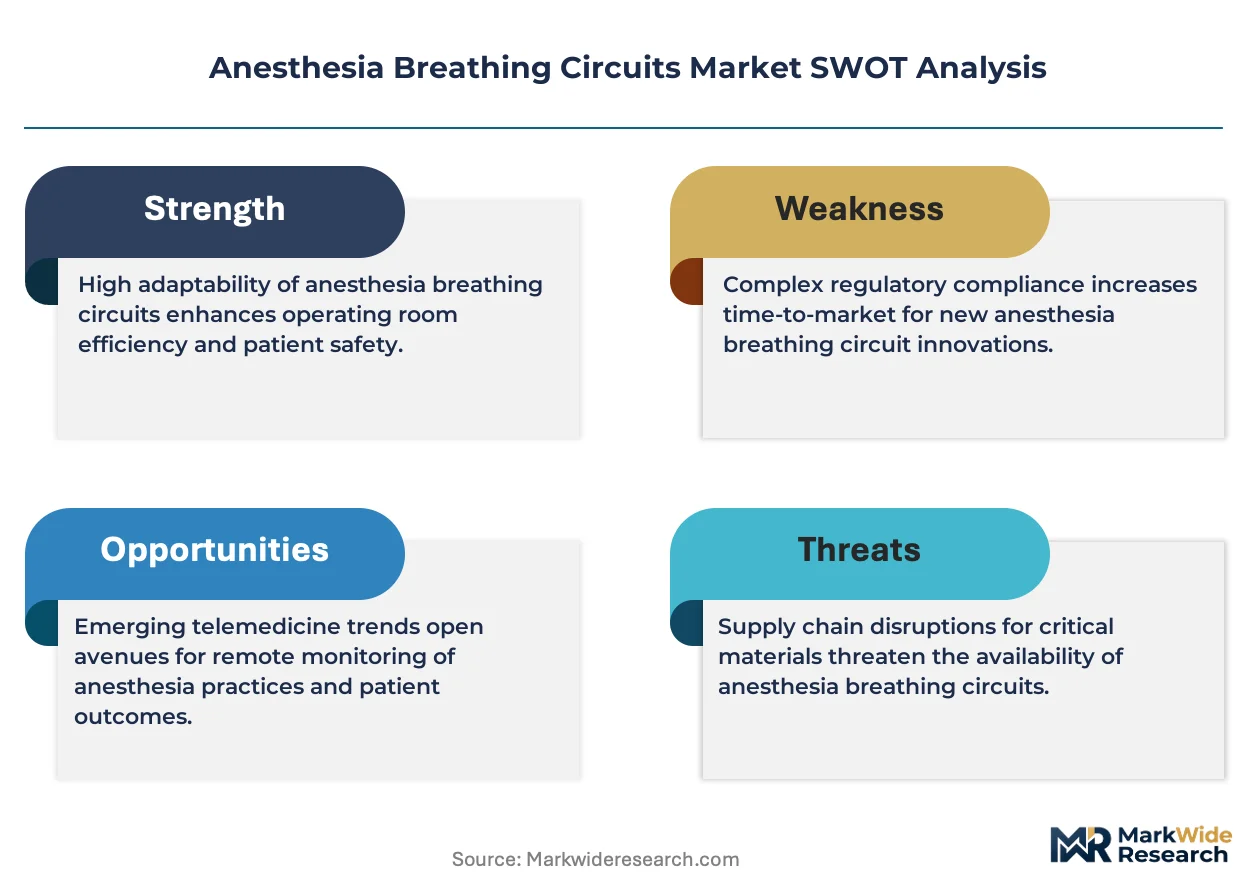
FDA 510(k) clearance requirements and ISO 5367 standards for breathing system connectors shape product design cycles and market access timelines for new entrants. The EU MDR and REACH substance restrictions are forcing material substitutions in European supply chains, raising compliance costs for PVC-dependent manufacturers. Stakeholders must monitor evolving single-use sustainability mandates and assess whether bio-based polymer investments will become a procurement differentiator or a cost burden.
Market Dynamics
Hospital procurement consolidation across the United States is compressing vendor counts and forcing single-use circuit suppliers to defend shelf space through bundled kit contracts rather than component pricing alone.
Growth Catalysts
- Ambulatory surgical center expansion:Freestanding ASCs in the United States are expanding operating room throughput, driving kit consumption for rapid-turnover anesthesia workflows.
- ISO 5367 connector standardization:Universal 22mm/15mm breathing system connectors are reducing interoperability failures and enabling cross-manufacturer kit assembly.
- Heated humidification integration:Active humidification modules embedded within circuits are reducing ventilator-associated complications in cardiac and thoracic procedures.
Market Restraints
- Medical-grade polymer cost volatility:PVC and silicone resin prices fluctuate with petrochemical feedstock markets, squeezing margin on commodity circuit lines.
- EU REACH substance restrictions:Phthalate plasticizer bans under Annex XVII are forcing European manufacturers toward bio-based alternatives with unproven scale economics.
- Respiratory therapist workforce contraction:Certified RT staffing shortages in the United States are capping procedure volume growth regardless of physical supply availability.
Strategic Opportunities
- Pediatric anesthesia specialization:Neonatal and infant-specific circuit geometries remain underdeveloped relative to adult standard kits, offering white space for dedicated product lines.
- Single-use sustainability mandates:Extended producer responsibility frameworks in Germany and France are creating first-mover advantage for bio-polymer circuit suppliers.
- Remote monitoring convergence:Integration of pressure and flow sensors within disposable circuits enables real-time anesthesia depth telemetry without capital equipment upgrades.
Industry Challenges
- FDA 510(k) clearance timelines:Novel material substitutions for PVC require extensive biocompatibility documentation, stretching product development cycles to 18-24 months.
- Legacy anesthesia machine interfacing:Proprietary connector configurations from installed base equipment manufacturers create integration friction for standardized circuit suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anesthesia Breathing Circuits Market |
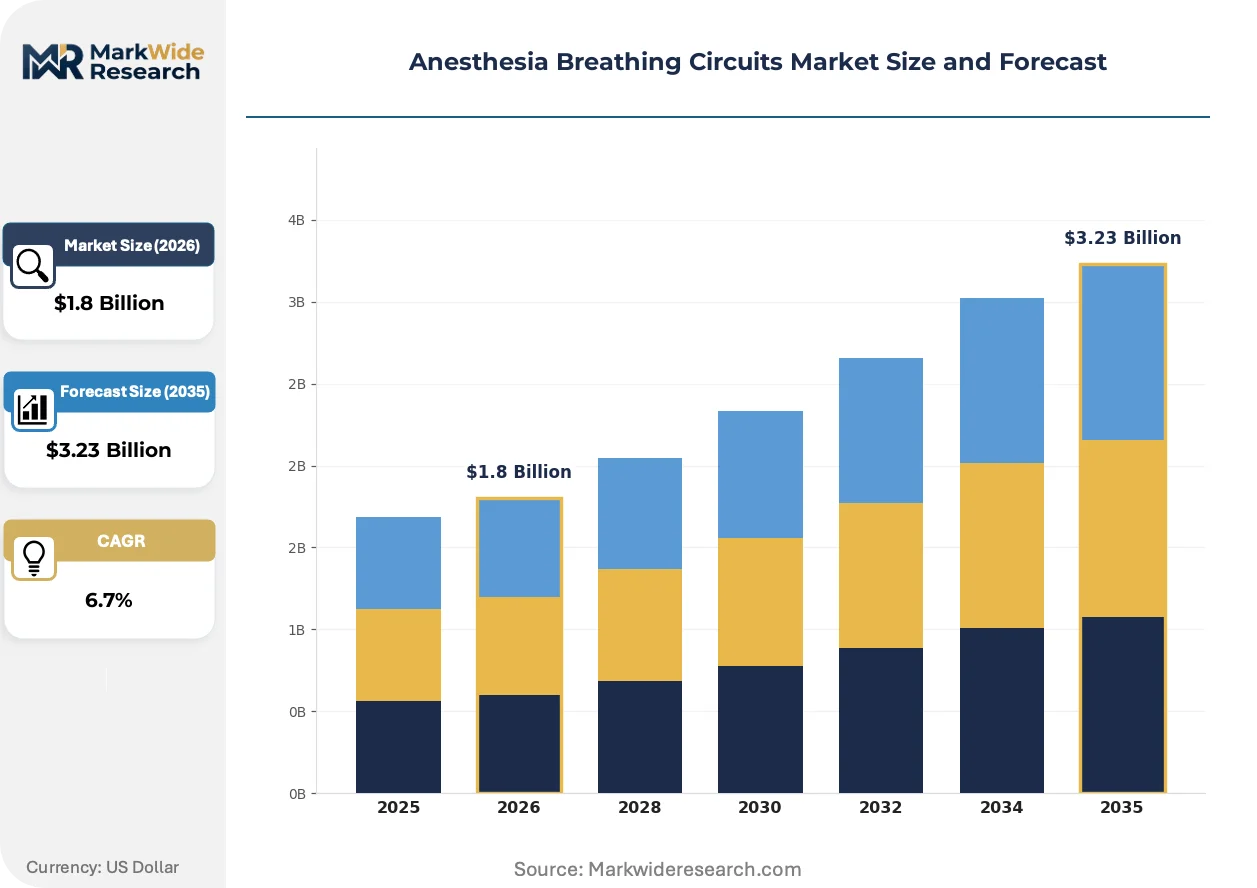
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Circuit Kit, Laryngeal Mask, Endotracheal Tube, Breathing Bag Application: General Surgery, Cardiac Procedures, Pain Management, Emergency Care End User: Hospitals, Surgical Centers, Emergency Departments, Veterinary Clinics Delivery Mode: Manual, Automated, Semi-Automated, High-Flow |
| Companies Covered | Koninklijke Philips N.V., Teleflex Incorporated, Medtronic plc, Smiths Medical, Ambu A/S, GE HealthCare, Fisher & Paykel Healthcare, ICU Medical, Inc., Draegerwerk AG & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anesthesia Breathing Circuits Market Emerging Trajectories
Active humidification and embedded sensor technologies are transforming anesthesia breathing circuits from passive conduits into intelligent delivery systems that capture procedure data.
Coaxial breathing circuits with inner inspiratory and outer expiratory lumens in a single tube are supplanting traditional dual-hose configurations in ambulatory settings. United States ASCs are adopting these space-efficient designs to reduce clutter and accelerate room turnover. The structural compression of component counts per procedure is enabling kit suppliers to bundle additional accessories without violating sterile field ergonomics.
REACH substance restrictions and the EU MDR are compelling material transitions across European supply chains. Manufacturers serving Germany, France, and Italy are reformulating PVC compounds to eliminate restricted phthalates ahead of 2025 enforcement deadlines. Pediatric and neonatal circuit segments face the steepest compliance burden due to heightened toxicity sensitivity for low-body-weight patients.
Hospital buying groups in the United States are consolidating anesthesia supply contracts under single-source agreements that span drugs, devices, and disposables. Integrated delivery networks in Texas, Florida, and Ohio are replacing fragmented purchasing with system-wide kit standardization. This behavioral shift favors suppliers with vertical manufacturing control over humidification modules, filters, and circuit tubing rather than assembly-only competitors.
Anesthesia Breathing Circuits Market Segmentation
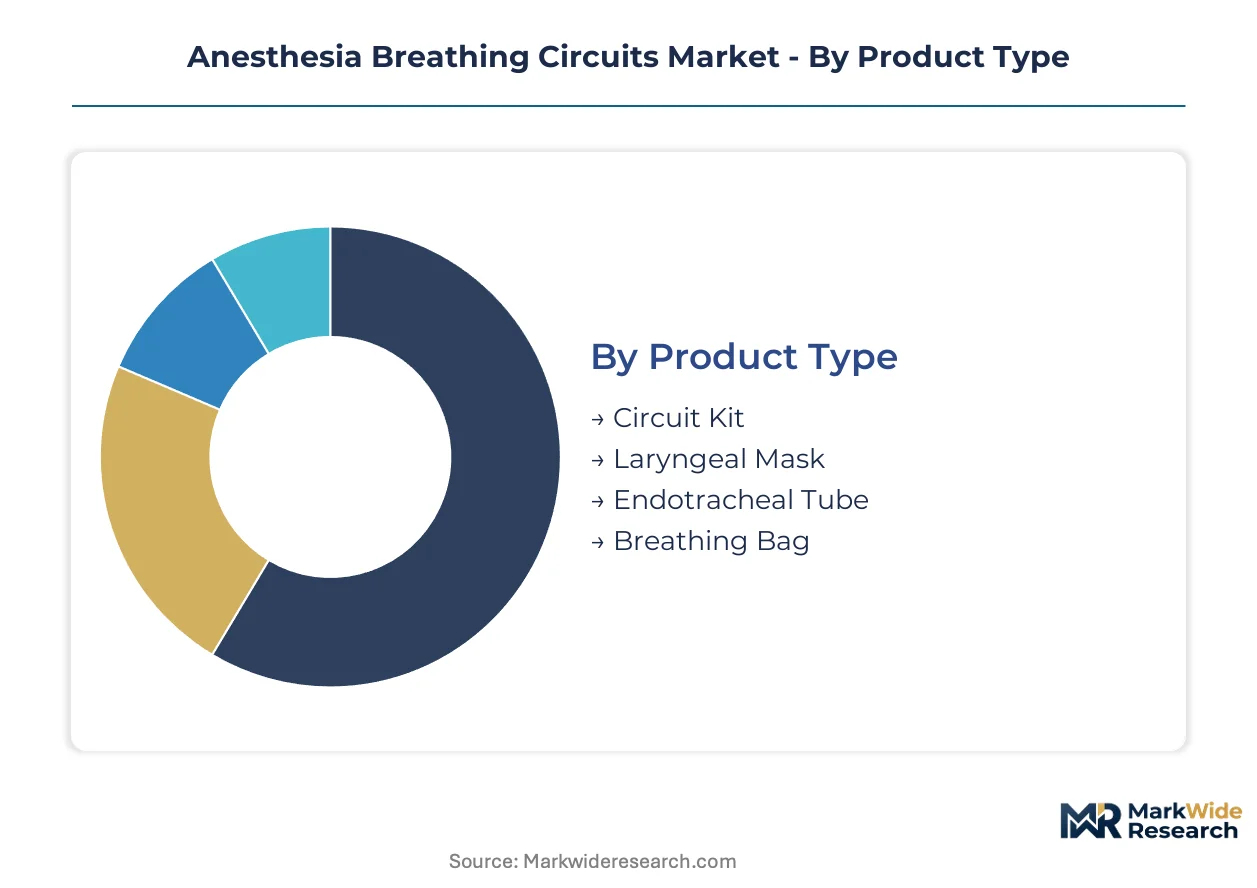
Anesthesia breathing circuits serve distinct clinical workflows with incompatible technical specifications. Segmentation reveals where regulatory pressure, reimbursement structures, and procedural volume concentrate purchasing power across product configurations.
Product Type:
FDA 510(k) clearance pathways diverge sharply between sterile single-use kits and reusable component systems, shaping supplier R&D allocation and hospital contracting strategies.
- Circuit Kit:Pre-assembled bundles containing tubing, filters, and connectors in sterile packaging eliminate bedside configuration errors. Hospital procurement consolidation across the United States favors these kits through bundled contracts that span multiple procedure types.
- Laryngeal Mask:Supraglottic airway devices with inflatable cuffs enable rapid airway establishment without laryngoscopy. Ambulatory surgical centers in Florida and Texas deploy these masks to accelerate room turnover and reduce anesthesia staffing demands.
- Endotracheal Tube:Cuffed tracheal tubes with Murphy eyes and radiopaque lines for definitive airway control in prolonged procedures.
- Breathing Bag:Reservoir bags for manual ventilation and circuit compliance testing in induction and emergence phases.
Established volume favors circuit kits; emerging adoption favors laryngeal masks.
Application:
Reimbursement intensity varies threefold across procedure categories, concentrating capital equipment and disposable purchasing in high-margin surgical segments.
- General Surgery:Laparoscopic and open abdominal procedures requiring standard circle system configurations with carbon dioxide absorption. Academic medical centers in Ohio and Illinois drive standardization across high-volume general surgery suites.
- Cardiac Procedures:Cardiopulmonary bypass and off-pump coronary interventions demand precise oxygenation control with heated humidification integration. Cleveland Clinic and Mayo Clinic procurement specifications shape vendor product development priorities for this segment.
- Pain Management:Sedation circuits for interventional pain procedures with low-flow delivery and scavenging systems.
- Emergency Care:Rapid-sequence intubation setups with disposable components for contamination control in trauma bays.
Revenue concentration sits with cardiac applications; procedure volume expansion runs through pain management.
End User:
Customer scale determines whether procurement favors single-source agreements or fragmented multi-vendor relationships.
- Hospitals:Integrated delivery networks with 500+ beds negotiate system-wide anesthesia supply contracts covering drugs, devices, and disposables. HCA Healthcare and CommonSpirit Health purchasing patterns demonstrate this consolidation dynamic.
- Surgical Centers:Freestanding ASCs with 2-4 operating rooms prioritize rapid-turnover kits and space-efficient coaxial circuit designs.
- Emergency Departments:Hospital-based EDs with 24/7 anesthesia coverage require crash cart-compatible circuit configurations.
- Veterinary Clinics:Companion animal and equine practices with in-house surgical capabilities drive modest volume for small-diameter pediatric circuits.
Contract leverage concentrates in hospital systems; growth velocity clusters in surgical centers.
Delivery Mode:
Technology sophistication separates capital-intensive automated platforms from manual alternatives in cost-sensitive settings.
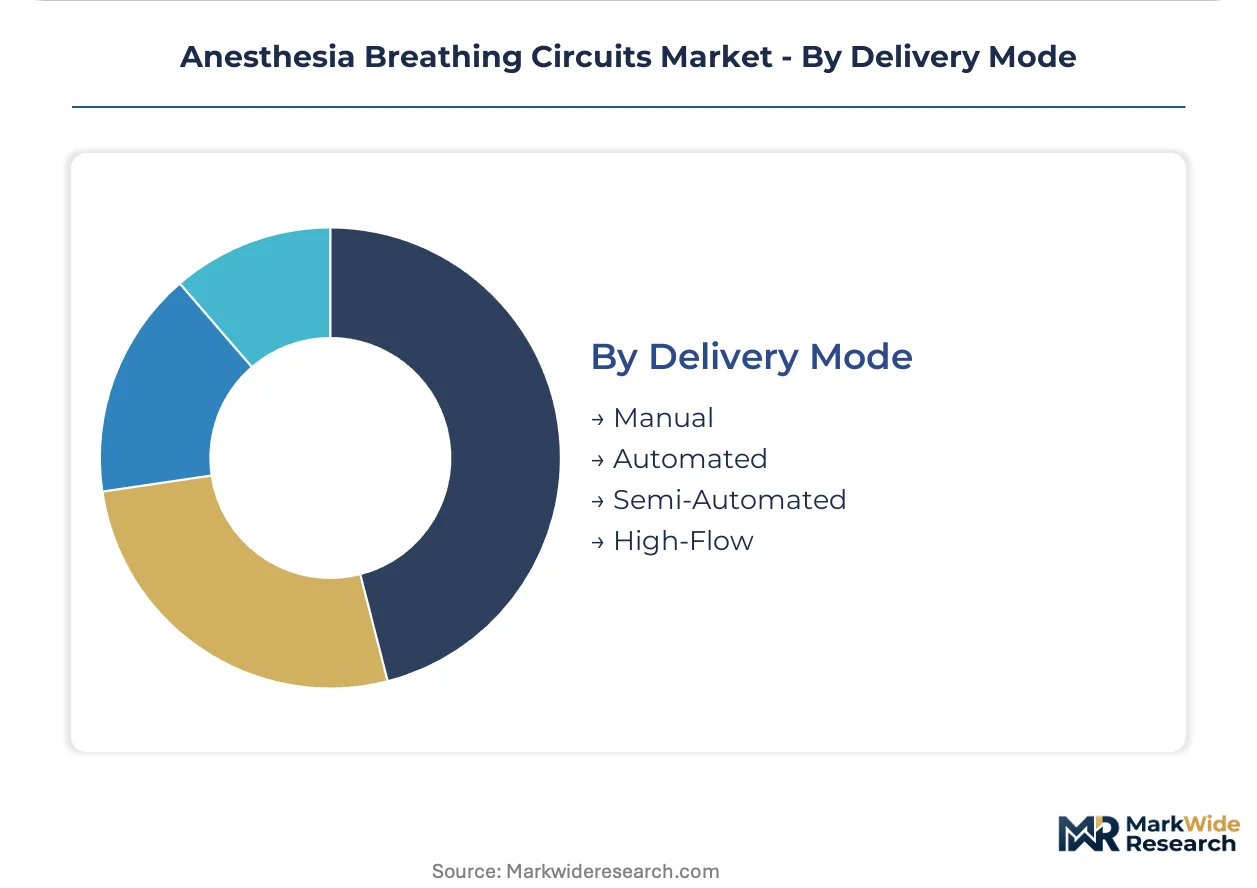
- Manual:Bag-valve-mask and Ayre's T-piece configurations for resource-limited environments and anesthesia machine backup. Rural critical access hospitals in Montana and Wyoming maintain manual capability as primary or contingency systems.
- Automated:Microprocessor-controlled ventilators with precision tidal volume delivery and pressure-limited modes. Tertiary cardiac centers specify these systems for hemodynamic stability during complex procedures.
- Semi-Automated:Ventilators with manual override capability for hybrid anesthesia workflows.
- High-Flow:Heated, humidified oxygen delivery systems exceeding 40 liters per minute for preoxygenation and apneic oxygenation.
Capital deployment favors automated systems; flexibility demands sustain semi-automated configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement consolidation in the United States extracts pricing concessions that German and French suppliers cannot match domestically, creating a transatlantic margin asymmetry that shapes regional investment priorities.
United States
Ambulatory surgical center expansion across Florida and Texas drives kit consumption for rapid-turnover workflows. FDA 510(k) clearance pathways for novel circuit materials stretch development cycles to 18-24 months. The Cleveland Clinic procurement consortium in Ohio sets technical specifications that cascade through integrated delivery networks nationwide.
Germany
REACH Annex XVII phthalate restrictions force PVC compound reformulations ahead of enforcement deadlines. The country's national pharmaceutical regulator, BfArM, coordinates with ECHA on medical device substance safety. Manufacturing clusters in Baden-Württemberg and North Rhine-Westphalia specialize in heated humidification modules for cardiac anesthesia circuits.
China
NMPA medical device registration requirements tighten biocompatibility documentation for polymer-based airway products. Domestic hospital procurement centralization under provincial unified bidding platforms compresses vendor margins. Production concentrates in Jiangsu and Zhejiang provinces where medical-grade silicone processors serve both domestic and export markets.
Japan
PMDA quality management system inspections extend market access timelines for foreign circuit manufacturers. Aging surgical demographics elevate demand for pediatric and geriatric-specific circuit geometries. The Nagoya medical device cluster hosts precision molding specialists supplying heated-wire circuit components to Asia-Pacific markets.
India
CDSCO medical device rules implementation raises registration barriers for imported anesthesia consumables. Government hospital procurement through the HLL Lifecare central agency favors cost-optimized kit configurations. Manufacturing activity clusters in Gujarat and Maharashtra where domestic polymer processors compete on PVC and polypropylene circuit tubing.
Anesthesia Breathing Circuits Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with humidification-integrated specialists commanding premium positioning against assembly-scale competitors. The vendor base separates into three tiers: diversified medical technology conglomerates with vertical manufacturing control, mid-scale specialists in heated humidification or pediatric geometries, and regional fabricators competing on kit pricing. Consolidation dynamics favor suppliers bundling circuits with anesthesia machines or drugs through single-source contracts. Capacity expansion and strategic partnerships represent the dominant competitive moves as procurement centralization accelerates.
Among diversified medical technology conglomerates, Koninklijke Philips N.V. and Medtronic plc occupy positions defined by vertical manufacturing footprints spanning humidification modules to circuit tubing. Fisher & Paykel Healthcare exemplifies the specialization archetype, anchoring competitive positioning through technical concentration in active humidification integration. Ambu A/S represents the disposable-focused tier, with Danish corporate structure signaling single-use device prioritization. These three anchors illustrate how geographic origin and corporate form predict strategic emphasis across the competitive spectrum.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Teleflex Incorporated |
| Medtronic plc |
| Smiths Medical |
| Ambu A/S |
| GE HealthCare |
| Fisher & Paykel Healthcare |
| ICU Medical, Inc. |
| Draegerwerk AG & Co. KGaA |
| Others |
Supply Flow & Price Mechanics
FDA 510(k) clearance requirements and ISO 5367 breathing system connector standards gate both supplier qualification and price differentiation in anesthesia breathing circuits, compressing margins for PVC-dependent manufacturers while rewarding heated humidification specialists with premium positioning.
Pricing Analysis
Configured-to-order pricing for pediatric-specific geometries and embedded sensor modules commands substantial premiums over standard adult circuit kits. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and heated humidification integration. Pricing pressure stems from hospital procurement consolidation across United States integrated delivery networks, which extract volume concessions through bundled single-source contracts. Ambulatory surgical centers exhibit highest price sensitivity due to thin procedure margins, while cardiac centers at Cleveland Clinic and Mayo Clinic procurement specifications demonstrate lowest sensitivity to premium tiers.
Supply Chain Analysis
China and Germany anchor medical-grade polymer processing and heated-wire component manufacturing for anesthesia breathing circuits. Jiangsu and Zhejiang provinces host silicone extrusion specialists serving export markets, while Baden-Württemberg clusters concentrate precision molding for active humidification modules. Raw material dependencies rest on petrochemical-derived PVC resins, platinum-cured silicone formulations, and polypropylene connector stock. Single-source vulnerability concentrates in heated-wire elements for humidification circuits, where Nagoya-based specialists control Asia-Pacific supply. Distribution runs through North American GPO contracts, European hospital buying groups, and provincial unified bidding platforms in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR substance restrictions and REACH Annex XVII phthalate enforcement deadlines are disrupting material formulations across European supply chains, creating acquisition opportunities for bio-polymer specialists and compliance-ready incumbents.
For Market Incumbents: Fortify market position through backward integration into heated humidification module production and captive supply of medical-grade silicone compounding. Medtronic plc and Fisher & Paykel Healthcare demonstrate how vertical manufacturing control defends shelf space against assembly-only competitors. Invest in bio-based polymer R&D ahead of German and French extended producer responsibility mandates to capture sustainability premiums.
For New Entrants and Emerging Players: Differentiate on pediatric and neonatal circuit geometries, where FDA 510(k) clearance timelines have deterred incumbent R&D allocation. Target ambulatory surgical centers in Florida and Texas with coaxial circuit designs that reduce room turnover time. Pursue hospital system partnerships through GPO contract participation rather than direct component sales.
For Investors and Strategic Acquirers: EU MDR implementation reshapes the acquisition landscape toward suppliers with demonstrated biocompatibility documentation and material substitution capabilities. Over a multi-year horizon, valuation premiums will concentrate in heated humidification specialists and bio-polymer circuit developers. Monitor FDA 510(k) clearance velocity for novel material submissions as the critical inflection signal for competitive repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Heated Humidification Module Integration | Fisher & Paykel Healthcare anchors differentiation through technical specialization in active humidification circuits. |
| Bio-Polymer Material Transition | REACH Annex XVII compliance investments create first-mover advantage in German and French procurement frameworks. |
| Pediatric Circuit Geometry Development | Neonatal-specific configurations remain underdeveloped relative to adult standards, offering white-space expansion. |
| Hospital System Partnership | HCA Healthcare and CommonSpirit Health consolidation patterns favor suppliers with bundled kit contract capabilities. |
| Embedded Sensor Technology | Pressure and flow sensor integration enables real-time anesthesia telemetry without capital equipment upgrades. |
Methodological Framework
The analysis maps circuit kit configurations, laryngeal mask airway devices, heated humidification modules, and pediatric-specific geometries, each validated through hospital procurement managers, biomedical engineers, GPO contracts managers, and anesthesia department directors. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and GPO contract repositories. Bottom-up procedure volume modeling and top-down market sizing triangulated across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including CMS Medicare procedure data, ambulatory surgical center utilization reports, and medical device trade flow statistics. The analytical framework modeled segmentation across product type, application, end user, and delivery mode dimensions throughout the forecast period. CAGRs derived from procedure volume elasticity to surgical throughput expansion and material cost trajectory assumptions. Forecast inputs incorporated respiratory therapist workforce contraction rates and REACH enforcement timeline uncertainty.
Decision-makers should treat outputs as directional under assumptions of steady surgical volume growth and regulatory enforcement continuity; material deviation in polymer cost volatility or staffing shortages would warrant model refresh. Recalibration cycles align with material shifts in FDA clearance timelines and EU MDR substance restriction implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Anesthesiology
Anesthesia CO2 Absorbent Market
Anesthesiology
Aspirating System Market
Anesthesiology
Delirium Market
Anesthesiology
Artificial Airway Holders Market
Anesthesiology
Global Anesthesia and Respiratory Devices Market
Anesthesiology
Sedation in ICU Setting Market
Anesthesiology
Epinephrine Market
Anesthesiology
US Anesthesiology Service Market
Anesthesiology
Anaesthesia Machines Market
Anesthesiology
Smart Anesthesia System Market
Anesthesiology
Inhalation Anesthetics Market
Anesthesiology
Anesthetics Market
Anesthesiology
Airway Catheters Market
Anesthesiology
Global Inhalation Anesthesia Market
Anesthesiology
Global Anesthesia Endotracheal Tubes Market
Anesthesiology
Anesthesia Delivery Units Market