
 Anesthetics Market | 2026-2036
Anesthetics Market Size, Share, and Industry Trends Forecast 2026-2036
Anesthetics Market Analytics
US FDA Good Manufacturing Practice certification for parenteral drug production is collapsing the supplier base for hospital-grade anesthetic formulations. Baxter International sustains vertical integration across sterile manufacturing and delivery systems. AbbVie anchors its position through R&D intensity in proprietary sedation molecules. Fresenius SE & Co. KGaA dominates European distribution networks for intravenous anesthetic agents.
Anesthetics are pharmacological compounds inducing reversible loss of sensation or consciousness, typically formulated as lipophilic small molecules with specific blood-gas partition coefficients determining onset and recovery profiles, manufactured under aseptic conditions for parenteral or inhalational delivery. Their primary purpose is enabling surgical intervention without patient awareness or pain response. General anesthetics command the largest revenue pool due to their essential role in major surgical procedures, while local anesthetics represent the fastest-expanding category driven by proliferation of outpatient orthopedic and dental interventions. Injectable anesthetics concentrate margin capture through prefilled syringe formats that reduce pharmacy preparation burden.
FDA oversight of anesthetic drug labeling and post-market surveillance shapes product development timelines and safety documentation requirements. The European Medicines Agency enforces centralized marketing authorization for novel anesthetic agents across EU member states. The International Organization for Standardization provides harmonized quality benchmarks for anesthetic equipment and delivery systems. Stakeholders must monitor evolving pharmacovigilance mandates and anesthesia shortage mitigation protocols to secure supply continuity and regulatory alignment.
Market Dynamics
Hospital procurement consolidation is compressing the supplier base for sterile anesthetic formulations, forcing manufacturers to demonstrate compliance with FDA Good Manufacturing Practice certification at scale or exit the hospital-grade segment entirely.
Growth Catalysts
- Same-day surgical protocols:Ambulatory surgical centers are expanding procedural capacity for outpatient orthopedic and dental interventions, amplifying demand for rapid-onset local anesthetic formulations.
- REACH regulatory harmonization:The European Chemicals Agency is streamlining centralized marketing authorization for novel anesthetic agents across EU member states, reducing time-to-market for compliant manufacturers.
- Prefilled delivery systems:Injectable anesthetics in prefilled syringe formats are reducing pharmacy preparation burden and capturing margin through operational efficiency gains in acute care settings.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production for propofol and volatile agents concentrates in a limited number of manufacturing sites, creating vulnerability to single-source disruption.
- EMA pharmacovigilance escalation:The European Medicines Agency is tightening post-market surveillance documentation requirements, extending product development timelines and elevating compliance costs for novel entrants.
- Generic erosion of proprietary molecules:Patent expiration on established intravenous anesthetic agents is commoditizing segments previously protected by formulation exclusivity.
Strategic Opportunities
- Underpenetrated outpatient dentistry:Brazil's expanding private dental clinic network presents unmet demand for topical and infiltration anesthetic products with simplified administration protocols.
- Japan's aging surgical population:METI-backed initiatives for geriatric-optimized sedation protocols are creating demand for anesthetic agents with reduced cardiovascular impact and faster cognitive recovery profiles.
- Closed-loop delivery convergence:Integration of pharmacokinetic modeling software with infusion pump hardware is enabling real-time depth-of-anesthesia monitoring and automated titration.
Industry Challenges
- Aseptic manufacturing certification backlog:FDA inspection queues for parenteral drug facilities are extending approval timelines, constraining capacity expansion for sterile anesthetic production.
- Anesthesia workforce shortages:The pipeline of certified nurse anesthetists and anesthesiologists is failing to match surgical volume expansion, limiting utilization of advanced anesthetic delivery systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anesthetics Market |
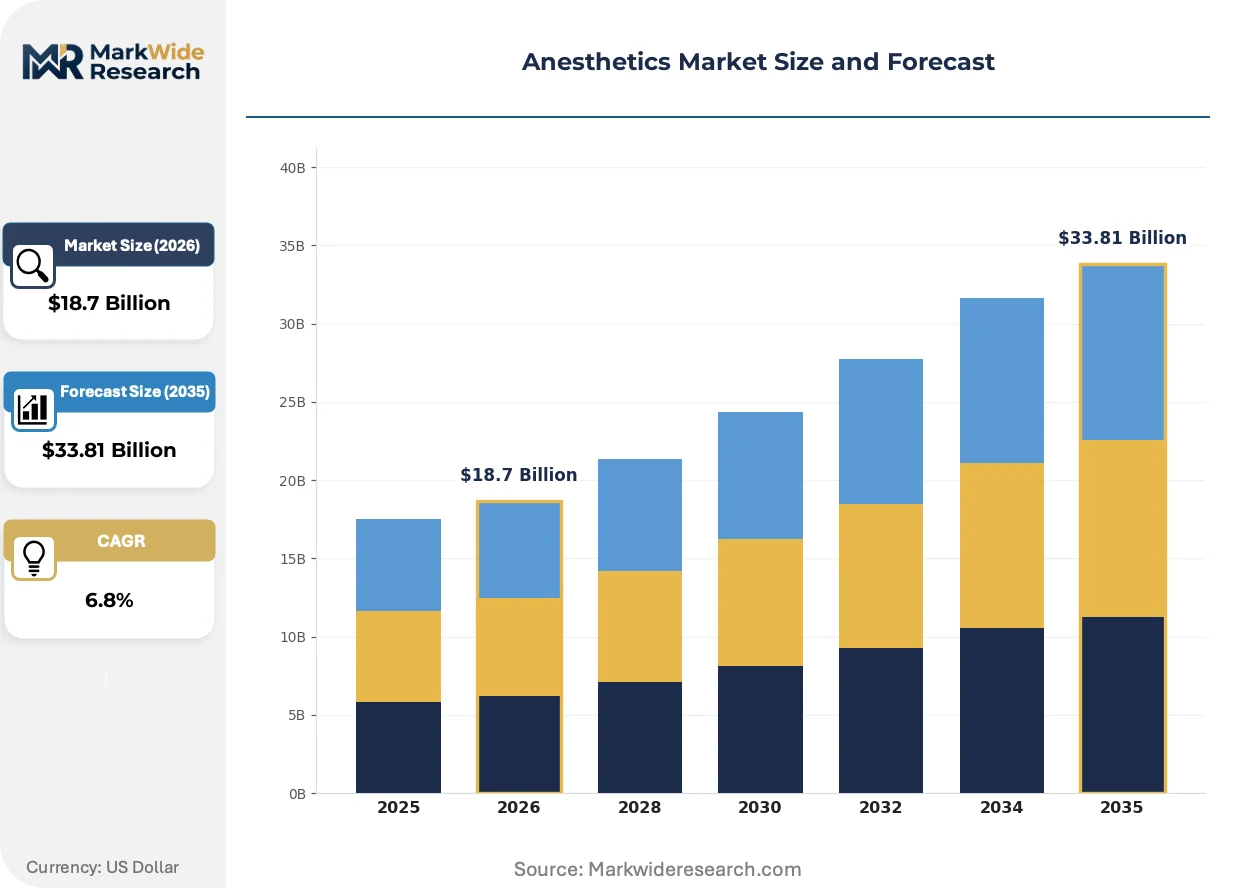
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: General Anesthetics, Local Anesthetics, Regional Anesthetics, Injectable Anesthetics Administration Route: Intravenous, Inhalation, Topical, Peripheral Nerve Blocks End User: Hospitals, Clinics, Ambulatory Surgical Centers, Pain Management Centers Therapy Area: Dental Surgery, Orthopedic Surgery, Cardiovascular Procedures, Obstetrics |
| Companies Covered | Baxter International Inc., AbbVie Inc., AstraZeneca, B. Braun Melsungen AG, Fresenius SE & Co. KGaA, Pfizer Inc., Hikma Pharmaceuticals PLC, Aspen Pharmacare Holdings Limited, Piramal Enterprises Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anesthetics Market Evolving Landscape
Target-controlled infusion systems and AI-assisted depth monitoring are bifurcating the anesthesia delivery landscape, separating institutions capable of capital-intensive technology adoption from those reliant on conventional pharmacologic protocols.
Total intravenous anesthesia platforms employing propofol-remifentanil combinations are displacing volatile gas-based maintenance in tertiary surgical centers. Academic medical centers in Germany and the United States are adopting these systems at accelerating pace. The technology is bifurcating the market into high-complexity automated delivery environments and cost-constrained settings maintaining inhalational agent dependence.
The FDA's updated guidance on anesthetic drug safety monitoring is mandating enhanced post-operative respiratory surveillance documentation. Manufacturers must now integrate continuous capnography and pulse oximetry data logging into their labeling claims. Injectable anesthetic agents used in outpatient settings face the most stringent adverse event reporting thresholds, driving reformulation toward shorter-acting ester compounds.
Centralized hospital procurement consortia are consolidating vendor relationships for anesthetic agents and delivery systems. Independent ambulatory surgical centers are losing direct purchasing access to preferred manufacturer pricing tiers, forcing reliance on group purchasing organizations. This concentration is most visible across the southeastern United States, where health system mergers have collapsed previously fragmented buying authority into single-source contracts.
Anesthetics Market Segmentation
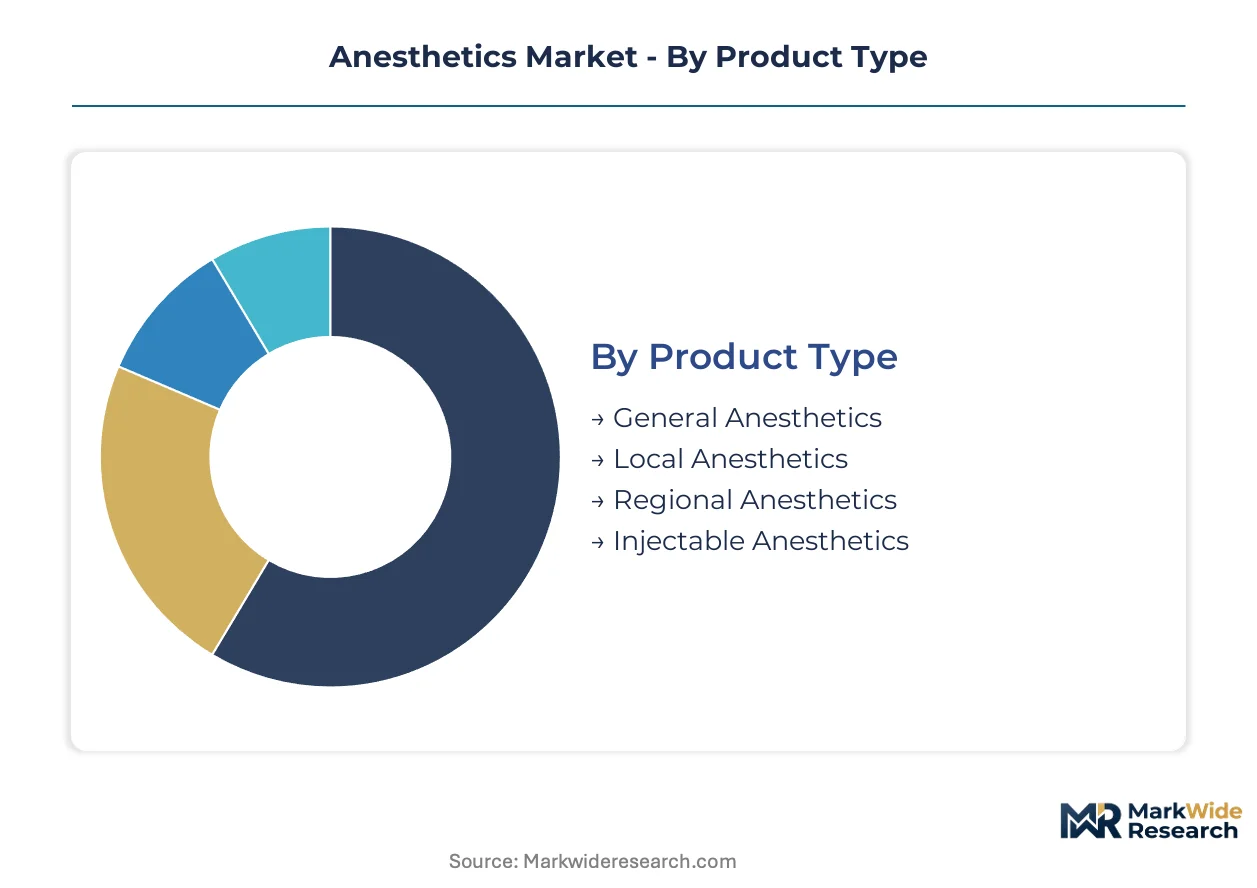
Anesthetic procurement channels diverge sharply by clinical setting, with hospital consortia demanding bulk sterile formulations while ambulatory centers prioritize unit-dose convenience. Understanding these pathway distinctions enables manufacturers to align formulation, packaging, and compliance investments with actual purchasing behavior.
Product Type:
General anesthetics flow predominantly through hospital centralized pharmacy systems, while local and regional variants reach end-users via distributor networks serving outpatient facilities.
- General Anesthetics:Lipophilic small molecules inducing reversible unconsciousness, typically propofol, sevoflurane, or desflurane formulations. Demand concentrates in United States tertiary surgical centers where hospital consolidation has collapsed purchasing into single-source contracts with manufacturers demonstrating FDA-scaled GMP compliance.
- Local Anesthetics:Ester and amide-class compounds blocking sodium channels in peripheral nerves. Brazil's expanding private dental clinic network drives unmet demand for topical and infiltration products with simplified administration protocols.
- Regional Anesthetics:Spinal and epidural formulations including bupivacaine and ropivacaine. Labor and delivery units in academic medical centers represent the core installed base.
- Injectable Anesthetics:Prefilled syringe and vial formats for parenteral delivery. Prefilled formats reduce pharmacy preparation burden and capture margin through operational efficiency gains in acute care settings.
General anesthetics dominate installed base. Local anesthetics are where expansion concentrates.
Administration Route:
Route selection directly determines manufacturing certification requirements, with parenteral formats subject to FDA aseptic facility inspections and inhalational agents regulated under distinct vapor pressure and environmental release standards.
- Intravenous:Bolus and infusion delivery of propofol, etomidate, or ketamine formulations. Total intravenous anesthesia platforms employing propofol-remifentanil combinations displace volatile gas-based maintenance in German and United States tertiary surgical centers.
- Inhalation:Volatile agents including sevoflurane, isoflurane, and desflurane delivered via calibrated vaporizers. Cost-constrained settings maintain inhalational agent dependence while high-complexity centers automate delivery.
- Topical:Surface-applied lidocaine, benzocaine, or tetracaine for mucosal and dermal procedures. EMA pharmacovigilance escalation tightens post-market surveillance documentation for ester compounds in outpatient settings.
- Peripheral Nerve Blocks:Ultrasound-guided catheter and single-injection techniques using ropivacaine or bupivacaine. Ambulatory orthopedic centers expanding same-day procedural capacity amplify demand for rapid-onset formulations.
Intravenous delivery commands the highest compliance investment. Peripheral nerve blocks are climbing the fastest.
End User:
Customer type shapes contract structure, with hospitals negotiating multi-year supply agreements and ambulatory centers transacting through group purchasing organizations.
- Hospitals:Integrated health systems with centralized pharmacy and anesthesia departments. United States hospital procurement consolidation compresses the supplier base, forcing manufacturers to demonstrate FDA GMP certification at scale.
- Clinics:Office-based procedure rooms for minor surgical interventions. Japan's METI-backed geriatric-optimized sedation protocols create demand for agents with reduced cardiovascular impact.
- Ambulatory Surgical Centers:Same-day discharge facilities for orthopedic, ophthalmic, and gastrointestinal procedures. Independent centers lose direct manufacturer pricing access, forcing reliance on group purchasing organizations.
- Pain Management Centers:Interventional suites for chronic pain procedures. Closed-loop delivery convergence integrating pharmacokinetic modeling with infusion pumps enables real-time depth monitoring.
Hospitals dominate installed base. Ambulatory surgical centers are gaining share fastest.
Therapy Area:
Procedure type dictates anesthetic depth requirements, cardiovascular and obstetric cases demanding hemodynamic stability while dental and orthopedic interventions prioritize rapid recovery.
- Dental Surgery:Local infiltration and topical anesthesia for extractions, implants, and periodontal procedures. Brazil's private dental clinic network presents underpenetrated demand for simplified administration protocols.
- Orthopedic Surgery:Regional blocks and general anesthesia for joint replacement and arthroscopy. Same-day surgical protocols amplify demand for rapid-onset local anesthetic formulations in ambulatory settings.
- Cardiovascular Procedures:High-risk anesthesia requiring hemodynamic monitoring and cardiopulmonary support. Japan's aging surgical population drives demand for agents with faster cognitive recovery profiles.
- Obstetrics:Epidural and spinal anesthesia for labor analgesia and cesarean delivery. Regional anesthetics concentrate margin capture through catheter-based continuous delivery systems.
Orthopedic surgery dominates procedure volume. Dental surgery shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement consolidation and regulatory tightening are reshaping anesthetic demand patterns across major surgical markets. FDA Good Manufacturing Practice certification requirements are compressing supplier bases in developed economies, while emerging markets expand outpatient procedural capacity.
United States
Health system mergers across the southeastern United States have collapsed fragmented buying authority into single-source contracts for sterile anesthetic formulations. The FDA's updated guidance on anesthetic drug safety monitoring mandates enhanced post-operative respiratory surveillance documentation. Academic medical centers in Boston and the Research Triangle are accelerating adoption of total intravenous anesthesia platforms.
Germany
German tertiary surgical centers are displacing volatile gas-based maintenance with propofol-remifentanil combination systems at accelerating pace. The EMA enforces centralized marketing authorization for novel anesthetic agents across EU member states. Industrial clusters in Baden-Württemberg and Bavaria concentrate manufacturing of precision vaporizers and infusion pump hardware.
Japan
METI-backed initiatives for geriatric-optimized sedation protocols are creating demand for agents with reduced cardiovascular impact and faster cognitive recovery profiles. The PMDA maintains stringent pharmacovigilance documentation requirements for ester-based compounds in outpatient settings. Surgical volume concentrates in Tokyo's Kanto region and Osaka's Kansai corridor, where aging demographics drive procedure mix toward cardiovascular interventions.
Brazil
Private dental clinic networks in São Paulo and Rio de Janeiro present underpenetrated demand for topical and infiltration anesthetic products with simplified administration protocols. ANVISA regulates import licensing for active pharmaceutical ingredients used in propofol formulations. The southeast region's outpatient orthopedic centers are expanding same-day procedural capacity, amplifying demand for rapid-onset local anesthetic formulations.
India
CDSCO oversight of parenteral drug manufacturing is tightening compliance requirements for domestic producers of intravenous anesthetic agents. The PLI scheme incentivizes backward integration into active pharmaceutical ingredient production for propofol and midazolam. Pharmaceutical manufacturing clusters in Maharashtra and Gujarat are scaling aseptic fill-finish capacity to supply hospital consortia across South Asia.
Anesthetics Market Competitive Landscape
Player mix skews toward diversified pharmaceutical conglomerates with captive sterile manufacturing infrastructure. Baxter International sustains upstream control over parenteral drug production and delivery systems. AbbVie anchors its position through proprietary sedation molecule development. Fresenius SE & Co. KGaA dominates European distribution networks for intravenous agents. Competitive moves concentrate on M&A for aseptic manufacturing assets and strategic partnerships for closed-loop delivery technology.
Among diversified pharmaceutical conglomerates, Baxter International Inc., AbbVie Inc., and Fresenius SE & Co. KGaA exemplify the archetype of verticalized players controlling sterile formulation capacity. These companies occupy positions where FDA-scaled Good Manufacturing Practice certification creates defensive moats against commodity competition. Pfizer Inc. and AstraZeneca represent the research-intensive tier, anchoring portfolios through proprietary molecule pipelines rather than manufacturing scale. B. Braun Melsungen AG and Hikma Pharmaceuticals PLC sit within the generic-specialist segment, where formulation expertise and regional regulatory navigation determine competitive position.
| Leading Market Players |
|---|
| Baxter International Inc. |
| AbbVie Inc. |
| AstraZeneca |
| B. Braun Melsungen AG |
| Fresenius SE & Co. KGaA |
| Pfizer Inc. |
| Hikma Pharmaceuticals PLC |
| Aspen Pharmacare Holdings Limited |
| Piramal Enterprises Ltd. |
| Others |
Value Network & Pricing Analysis
FDA-scaled aseptic manufacturing capacity anchors both supply concentration and price floors for sterile anesthetic formulations, compressing viable suppliers to conglomerates with captive fill-finish infrastructure and elevating entry barriers for commodity competitors.
Pricing Analysis
Certification level creates the primary spread across pricing tiers, with FDA-grade GMP-compliant propofol formulations commanding substantial premiums over CE-marked alternatives in United States hospital consortia. Three-tier pricing structure separates premium proprietary molecules from standard generic formulations and economy-grade volatile agents. Cost compression in the generic injectable segment intensifies as patent expirations commoditize established intravenous agents. Ambulatory surgical centers transacting through group purchasing organizations exhibit highest price sensitivity, while integrated health systems with single-source contracts demonstrate lowest sensitivity due to bundled service agreements.
Supply Chain Analysis
Inventory buffers for propofol API stretch to six months given single-source concentration in India and China, constraining just-in-time procurement flexibility for European and North American formulators. Active pharmaceutical ingredient production for propofol and sevoflurane concentrates in India, China, and limited United States sites. Finished formulation draws from isoflurane precursors, specialized lipophilic base compounds, and precision vaporizer hardware. Single-source vulnerability pervades the propofol API tier, where regulatory shutdowns at any major site trigger allocation protocols. Distribution runs through regional pharmaceutical wholesalers and direct hospital consortia contracts, bypassing traditional distributor markups for high-volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement consolidation across the southeastern United States has shifted bargaining power decisively toward buyers, collapsing fragmented purchasing into centralized single-source contracts that extract volume discounts and compliance guarantees from anesthetic suppliers.
For Market Incumbents: Consolidate manufacturing scale through backward integration into propofol API production, securing supply continuity against Indian and Chinese regulatory disruptions. Deepen hospital system partnerships by embedding closed-loop delivery systems that create switching costs. Baxter International's verticalized model demonstrates how captive sterile infrastructure defends margin position against generic entrants.
For New Entrants and Emerging Players: Lead with simplified administration protocols targeting Brazil's private dental clinic network, where topical and infiltration anesthetic demand outpaces established supply. Japan's METI-backed geriatric-optimized sedation protocols present second white-space opportunity for cardiovascular-sparing formulations. Direct-to-clinic distribution bypassing group purchasing organization markups offers viable go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers with installed base of infusion pump hardware and disposable delivery sets, generating consumable pull-through. Long-term viability favors targets with FDA-scaled aseptic certification and propofol API backward integration. Watch FDA inspection queue clearance rates as inflection indicator for capacity expansion feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Manufacturing Scale-Up | FDA-scaled GMP certification collapses competitor base to vertically integrated conglomerates with captive fill-finish infrastructure. |
| Closed-Loop Delivery Partnership | Integration of pharmacokinetic software with infusion pump hardware creates switching costs in tertiary surgical centers. |
| API Backward Integration | Captive propofol active pharmaceutical ingredient production insulates against Indian and Chinese regulatory disruption risk. |
| Hospital System Partnership | Single-source contracts with consolidated United States health systems lock in volume commitments and compliance co-development. |
| Geriatric Formulation Development | METI-backed protocols in Japan reward cardiovascular-sparing agents with faster cognitive recovery profiles. |
Research Methodology
Initial hypotheses were tested against primary input from anesthesia department directors, hospital pharmacy procurement managers, regulatory affairs leads at parenteral drug manufacturers, and group purchasing organization contract specialists, then refined against FDA 483 inspection observations, EMA centralized marketing authorization submissions, CDSCO manufacturing compliance circulars, and hospital procurement database extracts, with bottom-up facility capacity modeling cross-validated against top-down therapeutic demand projections.
Variance decomposition across the projection horizon isolates volume drivers by administration route, end-user facility type, and therapy area procedure mix, with CAGRs derived from segmented adoption curves for total intravenous anesthesia platforms and inhalational maintenance protocols, incorporating propofol supply elasticity constraints and workforce shortage impacts on delivery system utilization.
Underlying assumptions cover sustained FDA aseptic inspection capacity, REACH regulatory harmonization continuity, and anesthesia workforce pipeline recovery, with deviation risk concentrated in API supply disruption and pharmacovigilance documentation escalation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Anesthesiology
Endotracheal Tube Cuffs Market
Anesthesiology
Global Anesthesia and Respiratory Devices Market
Anesthesiology
Anesthesia Breathing Bags Market
Anesthesiology
Anesthesia Delivery Units Market
Anesthesiology
Delirium Market
Anesthesiology
Dental Anesthesia Market
Anesthesiology
Anesthesia Breathing Circuits Market
Anesthesiology
Global Anesthesia Delivery Systems Market
Anesthesiology
Vasopressin for Vasoplegic Shock Market
Anesthesiology
Sedation in ICU Setting Market
Anesthesiology
Epinephrine Market
Anesthesiology
Anesthesia CO2 Absorbent Market
Anesthesiology
Global Anesthesia Endotracheal Tubes Market
Anesthesiology
Anaesthesia Machines Market
Anesthesiology
Inhalation Anesthetics Market
Anesthesiology
Smart Anesthesia System Market