
 Electro-Pneumatic Transducers Market | 2026-2036
Electro-Pneumatic Transducers Market Size, Share, and Industry Trends Forecast 2026-2036
Electro-Pneumatic Transducers Market Foresight
A widening capability gap between vertically integrated conglomerates and component specialists is redrawing competitive boundaries in electro-pneumatic transducers. Emerson Electric Co. leverages its Plantweb digital ecosystem to bundle transducers with predictive diagnostics, capturing long-term service contracts. Festo SE & Co. KG anchors its position through captive pneumatics manufacturing and modular valve terminal integration. SMC Corporation dominates compact electropneumatic positioning systems for semiconductor fabrication equipment.
Electro-pneumatic transducers convert standardized electrical signals, typically 4-20 mA or 0-10 V, into proportional pneumatic output pressures ranging from 3-15 psi or 6-30 psi for precise actuator control in automated process loops. These devices serve as the critical interface between electronic control systems and pneumatic final control elements, enabling closed-loop regulation of flow, pressure, and mechanical positioning in environments where intrinsic safety or explosion protection is required. Analog control transducers retain the largest installed base across process industries, though digital control variants with integrated fieldbus communication are gaining fastest in greenfield automation projects. The manufacturing vertical consumes the majority of unit volume, while aerospace applications command premium pricing due to qualification rigor and traceability requirements. OEMs represent the most concentrated demand channel, particularly for machine builders standardizing on single-supplier pneumatic architectures.
EPA emissions monitoring requirements and OSHA process safety management standards shape product certification requirements for US installations, while REACH compliance and CE marking under the EU Machinery Directive govern European market access. Siemens AG navigates this regulatory landscape through pre-certified TIA Portal-integrated transducer families, reducing customer compliance burden. Stakeholders must monitor evolving cybersecurity standards for networked pneumatic devices, as IEC 62443 adoption begins penetrating industrial valve control architectures.
Market Dynamics
The European Union's F-Gas Regulation is compressing adoption timelines for leak-free pneumatic architectures, forcing manufacturers to redesign transducer housings and sealing systems ahead of the 2030 phase-down milestones.
Growth Catalysts
- Process automation mandates:Chemical processing plants in Germany's industrial automation corridor specify integrated electro-pneumatic systems for assembly-line pressure control, driving replacement cycles.
- REACH compliance frameworks:CE marking under the EU Machinery Directive accelerates certification of fieldbus-integrated transducers for greenfield automation projects.
- Semiconductor fabrication expansion:Positioning systems for wafer-handling equipment consume compact electropneumatic transducers at premium specification tiers.
Market Restraints
- Input cost volatility:Rare earth magnet prices and precision-machined aluminum housings expose margins to commodity swings.
- Supply concentration risk:Captive pneumatics manufacturing clusters in Southern Germany limit second-source availability for modular valve terminal integration.
- Technical limitation:Analog control transducers face displacement pressure from digital variants, stranding installed base investments.
Strategic Opportunities
- Underpenetrated aerospace qualification:Traceability requirements for flight-control pneumatics command pricing premiums in US and EU defense supply chains.
- Regulatory tailwind:OSHA process safety management standards create compliance-driven replacement demand for US chemical installations.
- Technology convergence:IEC 62443 cybersecurity standards and predictive diagnostics integration open service-contract revenue streams.
Industry Challenges
- Certification timeline compression:EPA emissions monitoring requirements and FAA qualification protocols extend product validation cycles.
- Integration complexity:TIA Portal-integrated transducer families demand specialized commissioning expertise for legacy DCS migration.
- Skill gap in fieldbus commissioning:Profibus and EtherNet/IP configuration expertise concentrates among German and Japanese automation specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electro-Pneumatic Transducers Market |
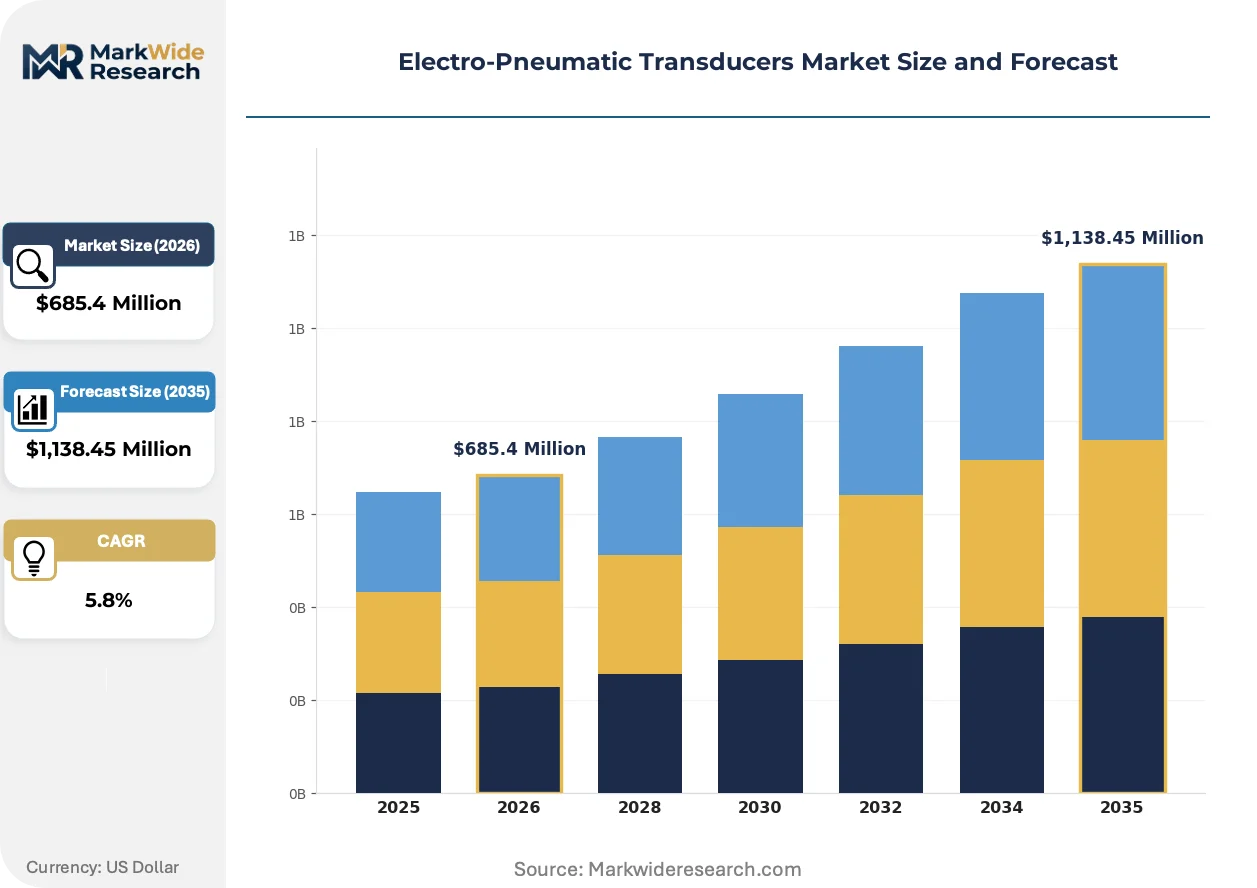
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Acting, Double Acting, Pneumatic Actuators, Solenoid Valves Industry Vertical: Manufacturing, Aerospace, Automotive, Healthcare End User: OEMs, End Users, Distributors, System Integrators Technology: Analog Control, Digital Control, Wireless Control, Hybrid Systems |
| Companies Covered | Emerson Electric Co., Festo SE & Co. KG, Parker Hannifin, SMC Corporation, Rotork, Siemens AG, ABB, Yokogawa Electric, Bosch Rexroth AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electro-Pneumatic Transducers Market Shifts & Advancements
Digital control variants with integrated diagnostics are compressing the technology lifecycle for analog transducers, while regulatory pressure on fluorinated gases reshapes pneumatic architecture design priorities.
Intelligent electro-pneumatic positioners with embedded HART or IO-Link communication are displacing conventional analog transducers in process industries. Chemical and pharmaceutical OEMs specify these devices for predictive maintenance integration. The shift compresses aftermarket service margins for legacy calibration providers.
REACH substance restrictions and the EU F-Gas Regulation mandate elimination of perfluorinated seals and lubricants in pneumatic devices. Manufacturers redesign diaphragm materials and housing interfaces to maintain leak-free performance. German automotive OEMs now require supplier documentation of fluorine-free content for assembly-line equipment procurement.
Machine builders consolidate pneumatic sourcing under single-supplier architectures to reduce integration risk. This procurement concentration favors vendors with captive valve terminal and transducer portfolios. The pattern concentrates specification authority with German and Japanese automation conglomerates serving packaging and assembly equipment markets.
Electro-Pneumatic Transducers Market Segmentation
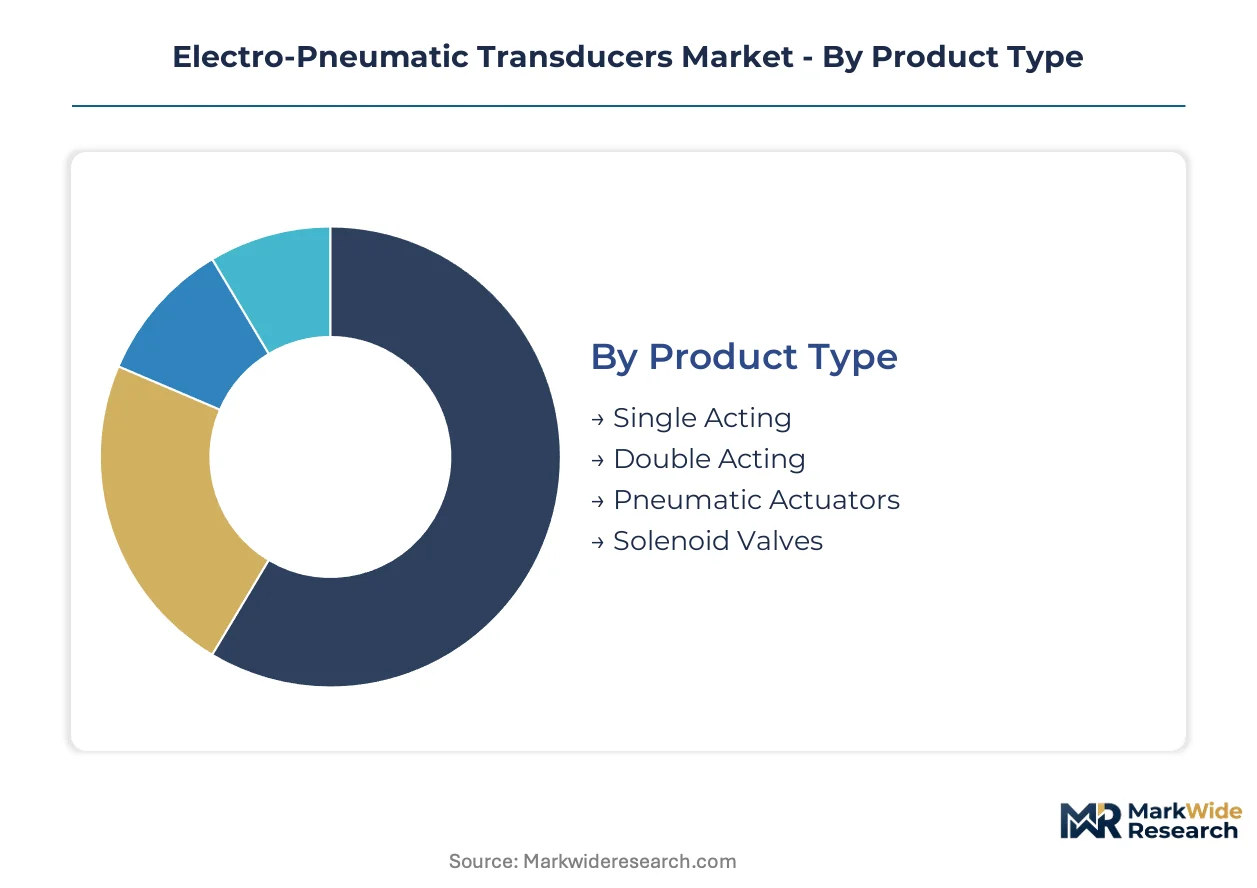
Segmentation in electro-pneumatic transducers reveals how pressure-interface technologies fragment across control architectures, procurement channels, and certification requirements. Each dimension carries distinct margin profiles and substitution vulnerabilities that reshape competitive positioning.
Product Type:
Double Acting transducers face the most acute displacement pressure from integrated valve-terminal systems that bundle positioning intelligence upstream.
- Double Acting:Bidirectional pressure modulation enables precise positioning of linear and rotary actuators in closed-loop process control. German automotive OEMs specify these for assembly-line welding fixtures where rapid direction reversal cuts cycle times.
- Single Acting:Unidirectional output with spring-return functionality dominates safety-critical applications where fail-safe positioning is mandatory. Aerospace flight-control systems in US and EU defense supply chains consume premium-specification variants with full material traceability.
- Pneumatic Actuators:Self-contained motion devices with integrated transducer feedback serve packaging machinery builders standardizing on Festo and SMC architectures.
- Solenoid Valves:On/off switching elements with electropneumatic pilots anchor discrete automation in material handling and sorting systems.
Double Acting retains volume leadership; Single Acting holds the steepest expansion curve.
Industry Vertical:
Cost-tier stratification separates specification-heavy aerospace from price-sensitive manufacturing procurement patterns.
- Manufacturing:Machine builders and assembly-line integrators consume the majority of unit volume across packaging, metalworking, and electronics fabrication. REACH compliance documentation now gates supplier qualification for EU-based OEMs.
- Aerospace:FAA and EASA qualification protocols extend validation cycles but command 3-5x pricing premiums over industrial grades. Traceability requirements for flight-control pneumatics limit vendor pools to pre-certified suppliers.
- Automotive:Germany's industrial automation corridor drives demand for leak-free architectures under tightening F-Gas Regulation phase-down milestones.
- Healthcare:FDA-regulated ventilator and diagnostic equipment applications require ISO 13485 quality systems and biocompatible seal materials.
Manufacturing dominates absolute volume; Aerospace delivers the highest margin realization per unit.
End User:
Procurement authority concentrates with OEMs consolidating pneumatic sourcing under single-supplier architectures to reduce integration risk.
- OEMs:Machine builders specify integrated electro-pneumatic systems during original design phases, locking in multi-year component supply agreements. German and Japanese packaging equipment manufacturers represent the most concentrated demand channel.
- System Integrators:Specialized commissioning firms bridge legacy DCS migration to fieldbus-integrated transducers, capturing value from TIA Portal and EtherNet/IP configuration expertise.
- Distributors:Channel partners stock standard analog variants for maintenance-driven replacement demand in process industries.
- End Users:Chemical and pharmaceutical plant operators specify predictive-diagnostics-enabled devices for greenfield automation projects.
OEMs control specification authority; System Integrators are expanding most quickly as fieldbus complexity rises.
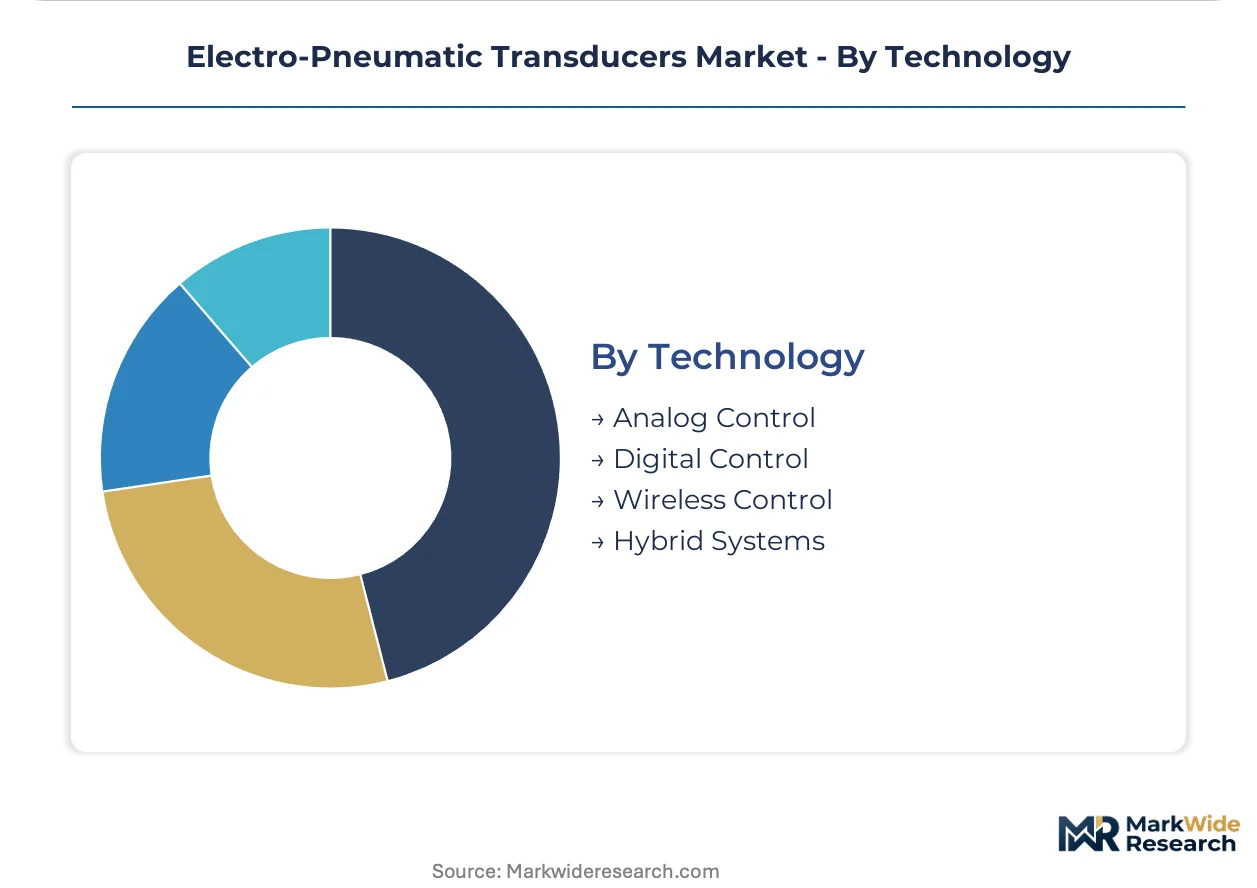
Technology:
Technology maturity curves separate legacy analog installed bases from digitally native architectures gaining share in greenfield projects.
- Analog Control:4-20 mA and 0-10 V signal conversion retains the largest installed base across process industries. OSHA process safety management standards sustain replacement demand in US chemical installations despite displacement pressure.
- Digital Control:Embedded HART, Profibus, and IO-Link communication enables predictive maintenance integration. Semiconductor fabrication equipment for wafer-handling consumes compact variants at premium specification tiers.
- Wireless Control:Battery-powered or energy-harvesting architectures penetrate remote monitoring applications where cabling costs dominate.
- Hybrid Systems:Dual-mode devices bridge analog legacy and digital infrastructure during phased automation upgrades.
Analog Control retains installed base dominance; Digital Control is gaining share fastest in new construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States commands premiums three to five times above industrial-grade benchmarks, while Germany's industrial automation corridor concentrates procurement authority through single-supplier pneumatic architectures. This asymmetry shapes regional competitive positioning and margin realization across the electro-pneumatic transducers value chain.
United States
Chemical processing plants under OSHA process safety management standards drive compliance-driven replacement cycles for predictive-diagnostics-enabled transducers. EPA emissions monitoring requirements extend product certification timelines for installations serving petrochemical and refining operations. The Gulf Coast petrochemical corridor consumes premium-specification variants for pressure control in automated process loops.
Germany
Automotive OEMs and machinery builders specify integrated electro-pneumatic systems for assembly-line welding fixtures requiring rapid direction reversal. The EU F-Gas Regulation compresses adoption timelines for leak-free pneumatic architectures ahead of 2030 phase-down milestones. Bavaria's industrial automation corridor anchors captive pneumatics manufacturing clusters serving packaging and metalworking equipment markets.
China
Semiconductor fabrication expansion for wafer-handling equipment consumes compact electropneumatic transducers at premium specification tiers. MIIT industrial automation policies accelerate domestic substitution in process control instrumentation. The Yangtze River Delta concentration of electronics manufacturing drives demand for fieldbus-integrated variants in greenfield automation projects.
Japan
METI industrial digitization frameworks promote predictive maintenance integration for pneumatic positioning systems in electronics fabrication. JIS standards certification gates supplier qualification for domestic machine builders standardizing on single-supplier architectures. The Nagoya industrial corridor concentrates demand from automotive component suppliers and robotics integrators.
South Korea
Memory chip and display panel fabrication facilities specify compact electropneumatic positioning systems for cleanroom automation. The country's national industrial safety regulator enforces process safety management standards aligned with IEC frameworks. The Seoul Capital Area concentration of semiconductor equipment OEMs drives procurement of digital control variants with embedded IO-Link communication.
Electro-Pneumatic Transducers Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics in the electro-pneumatic transducers market. Vertically integrated conglomerates with captive pneumatics manufacturing anchor the premium tier through bundled digital ecosystems and predictive diagnostics. Component specialists occupy mid-market positions through modular valve terminal integration and application-specific positioning systems. Scale-driven fabricators compete on unit economics for standard analog variants serving maintenance-driven replacement demand. Dominant competitive moves include backward integration into precision-machined aluminum housings and strategic partnerships for fieldbus communication protocol certification.
Among diversified industrial conglomerates, Emerson Electric Co. and Siemens AG exemplify the technology-integrator archetype through pre-certified transducer families that reduce customer compliance burden. Festo SE & Co. KG occupies a distinctive position as a German-based specialist with captive pneumatics manufacturing and modular valve terminal integration. These three companies represent contrasting strategic postures: ecosystem bundling, regulatory pre-certification, and captive vertical manufacturing.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Festo SE & Co. KG |
| Parker Hannifin |
| SMC Corporation |
| Rotork |
| Siemens AG |
| ABB |
| Yokogawa Electric |
| Bosch Rexroth AG |
| Others |
Supply & Pricing Matrix
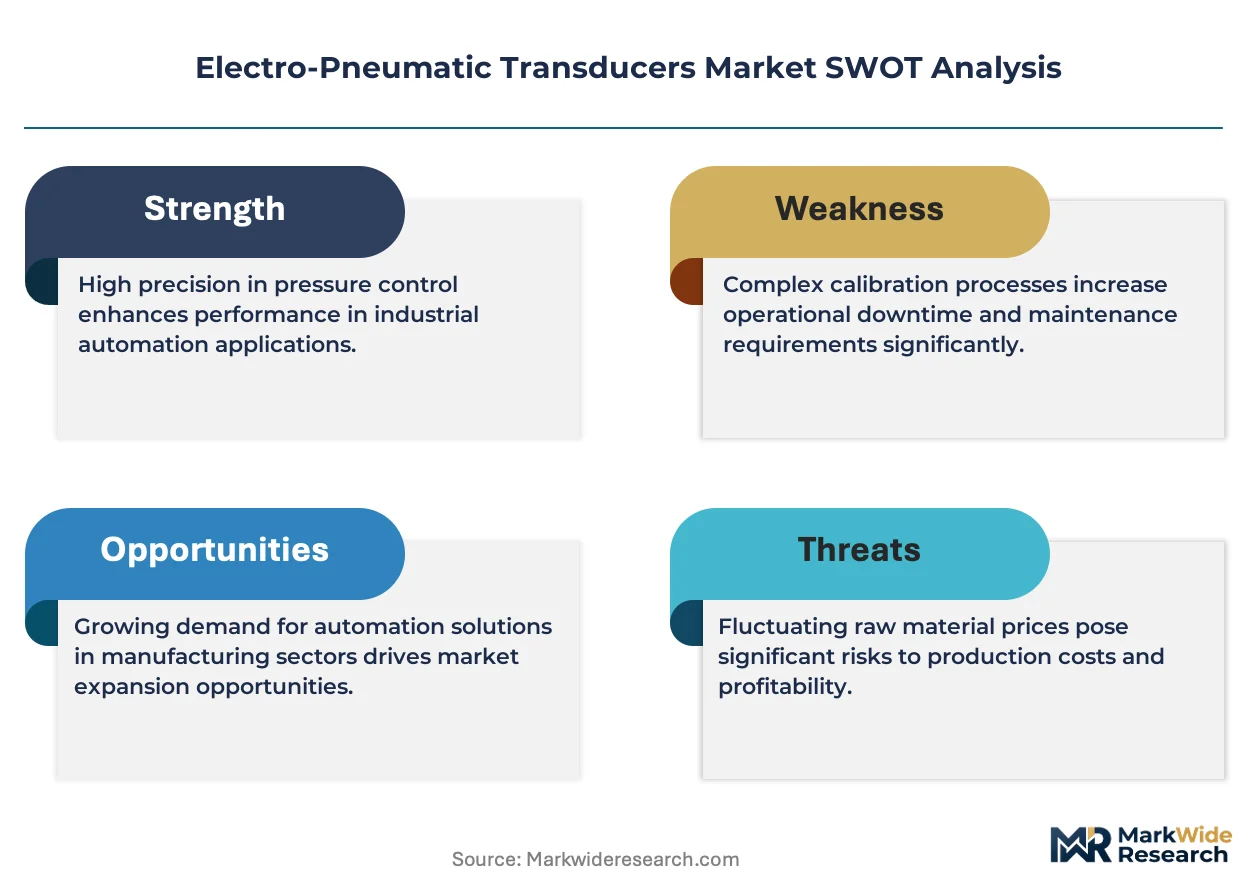
Capacity utilization in Southern Germany's captive pneumatics manufacturing clusters creates steep scale advantages that simultaneously concentrate supply and establish price floors for precision-machined aluminum housings and rare earth magnet assemblies. This scale geometry leaves smaller fabricators exposed to commodity swings while anchoring premium realization for vertically integrated conglomerates.
Pricing Analysis
Configured-to-order pricing for fieldbus-integrated transducers commands spreads of 40-60 percent above standard analog variants, with aerospace qualification tiers extracting further premiums through FAA and EASA traceability documentation. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales bundling, though cost compression in economy tiers is intensifying because of aluminum and magnet price volatility. OEM procurement teams in automotive and packaging machinery represent the most price-sensitive demand channel, while semiconductor fabrication equipment buyers absorb premium specifications with limited negotiation leverage.
Supply Chain Analysis
Just-in-time inventory strategies dominate German and Japanese automation corridors, though strategic stockpiling of rare earth magnets and fluorine-free seal materials is accelerating ahead of EU F-Gas Regulation phase-down milestones. Supply concentrates in Germany, Japan, and China, with precision-machined housings drawing from Bavarian metalworking clusters and magnet assemblies resting on Chinese rare earth processing. Single-source vulnerability concentrates in modular valve terminal integration, where captive manufacturing limits second-source availability. Distribution runs through OEM direct channels for configured systems and distributor networks for maintenance-driven replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electro-pneumatic transducers sit in early-cycle expansion as digital control variants with predictive diagnostics displace legacy analog installed bases across greenfield automation projects. Semiconductor fabrication expansion and tightening process safety mandates create durable adoption tailwinds.
For Market Incumbents: Shield service-contract revenue streams by embedding IEC 62443 cybersecurity certification into transducer families before fieldbus complexity rises further. Deepen backward integration into precision-machined aluminum housings to offset rare earth magnet price volatility and deny margin capture to mid-tier fabricators. For New Entrants and Emerging Players: CE marking fast-track under EU Machinery Directive opens qualification pathways for fieldbus-integrated variants targeting system integrators bridging legacy DCS migration. Aerospace traceability requirements in US and EU defense supply chains present the most penetrable premium tier, with predictive maintenance integration as the differentiated go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors bundling transducers with long-term predictive diagnostics service contracts, suggesting durable cash flow quality in ecosystem-integrated archetypes. Five-to-ten year viability favors targets with captive pneumatics manufacturing and modular valve terminal portfolios. The signal to watch is semiconductor capital expenditure inflection, which drives premium-tier demand for compact positioning systems.| Strategic Initiative | Industry Significance |
|---|---|
| Fieldbus Communication Certification | Profibus and EtherNet/IP validation gates specification authority with German automotive OEMs. |
| Backward Integration into Housings | In-house aluminum machining insulates margins from commodity volatility in precision components. |
| Predictive Diagnostics Integration | HART and IO-Link embedding captures aftermarket service contracts from legacy calibration providers. |
| Fluorine-Free Material Transition | REACH-compliant seal redesign maintains EU market access under tightening F-Gas restrictions. |
| Aerospace Qualification Investment | FAA and EASA traceability documentation unlocks 3-5x pricing premiums in defense supply chains. |
Research Methodology
Cross-validation between primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and distribution channel partners anchors the qualitative findings against secondary validation from SEC filings, customs and trade data, ACC and Cefic industry reports, and regulatory filing databases. Bottom-up demand modeling triangulates against top-down market sizing across the analysis window.
Sensitivity analysis on input cost trajectories and adoption curve assumptions shapes the analytical framework across product type, industry vertical, end-user channel, and technology segmentation dimensions. CAGRs derive from installed base replacement cycles and greenfield penetration rates, with semiconductor capital expenditure and chemical plant automation spend serving as industry-specific demand drivers throughout the forecast period.
Underlying assumptions cover regulatory timeline adherence and rare earth supply continuity, with deviation risk concentrated in F-Gas Regulation phase-down acceleration and cybersecurity standard enforcement timing. Revision becomes warranted when semiconductor fabrication investment or OSHA process safety audit intensity crosses thresholds that materially alter replacement demand velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
GPS Tracking Device Market
Sensors and Controls
Middle East and Africa Bulk Acoustic Wave Sensors Market
Sensors and Controls
ASEAN Safety Sensors and Switches Market
Sensors and Controls
Asia Pacific Touch Screen Controllers Market
Sensors and Controls
Surface Acoustic Wave Sensors Market
Sensors and Controls
Spain Digital Thermometer Market
Sensors and Controls
Touchless Sensing Market
Sensors and Controls
Asia-Pacific Smart Glove Market
Sensors and Controls
Asia-Pacific Current Transducer Market
Sensors and Controls
Fluid Sensors Market
Sensors and Controls
Capacitive Pressure Sensor Market
Sensors and Controls
Piece-Level Inventory Tracking and Vision Systems Market
Sensors and Controls
Non-Dispersive Infrared Sensing Market
Sensors and Controls
Fiber Optic Pressure Sensors Market
Sensors and Controls
Electronics Control Management Market
Sensors and Controls
Piezoresistive Pressure Sensor Market