
 Global in Dash Navigation System Market | 2026-2036
Global in Dash Navigation System Market Size, Share, and Industry Trends Forecast 2026-2036
Global in Dash Navigation System Market Intelligence
The capability gap between integrated cockpit system developers and single-component suppliers is collapsing. Robert Bosch GmbH leverages its extensive automotive electronics portfolio to offer complete digital cockpit solutions. Continental AG competes by providing scalable hardware and software platforms for various vehicle segments. In contrast, Garmin Ltd. specializes in standalone and semi-integrated navigation units with strong brand recognition in specific aftermarket and recreational vehicle niches.
An in-dash navigation system is an electronic unit integrated into a vehicle's dashboard, featuring a dedicated display and a GNSS receiver. These systems provide real-time, turn-by-turn directions using signals from constellations like GPS and Galileo. The passenger cars application constitutes the largest volume. Touchscreen displays remain the standard, but Heads-Up Displays are expanding rapidly, especially in premium vehicles equipped with advanced safety features.
Regulatory frameworks influence system design, particularly concerning driver distraction and data privacy. Guidelines from the NHTSA in the United States shape human-machine interface development. Concurrently, UNECE regulations in Europe and China's GB standards for automotive electronics impose strict safety and performance requirements. Stakeholders must now decide on software monetization strategies, balancing subscription models against one-time hardware sales.
Market Dynamics
The central structural force shaping the market is the convergence of infotainment, safety, and navigation into a unified digital cockpit architecture. This shift, accelerated by the software-defined vehicle concept, pressures single-function suppliers to develop comprehensive, integrated platform solutions or risk marginalization.
Growth Catalysts
- EV Adoption:The expansion of electric vehicle fleets, especially in China, creates direct demand for energy-aware navigation that optimizes routes based on charging station availability and vehicle state-of-charge.
- ADAS Integration Mandates:Safety frameworks, including Europe's General Safety Regulation, are compelling automakers to install higher-quality navigation systems that provide precise location data for advanced driver-assistance features.
- Augmented Reality Overlays:The commercialization of AR for Heads-Up Displays provides a powerful new use case, enhancing driver awareness and creating a premium feature differentiator for passenger cars.
Market Restraints
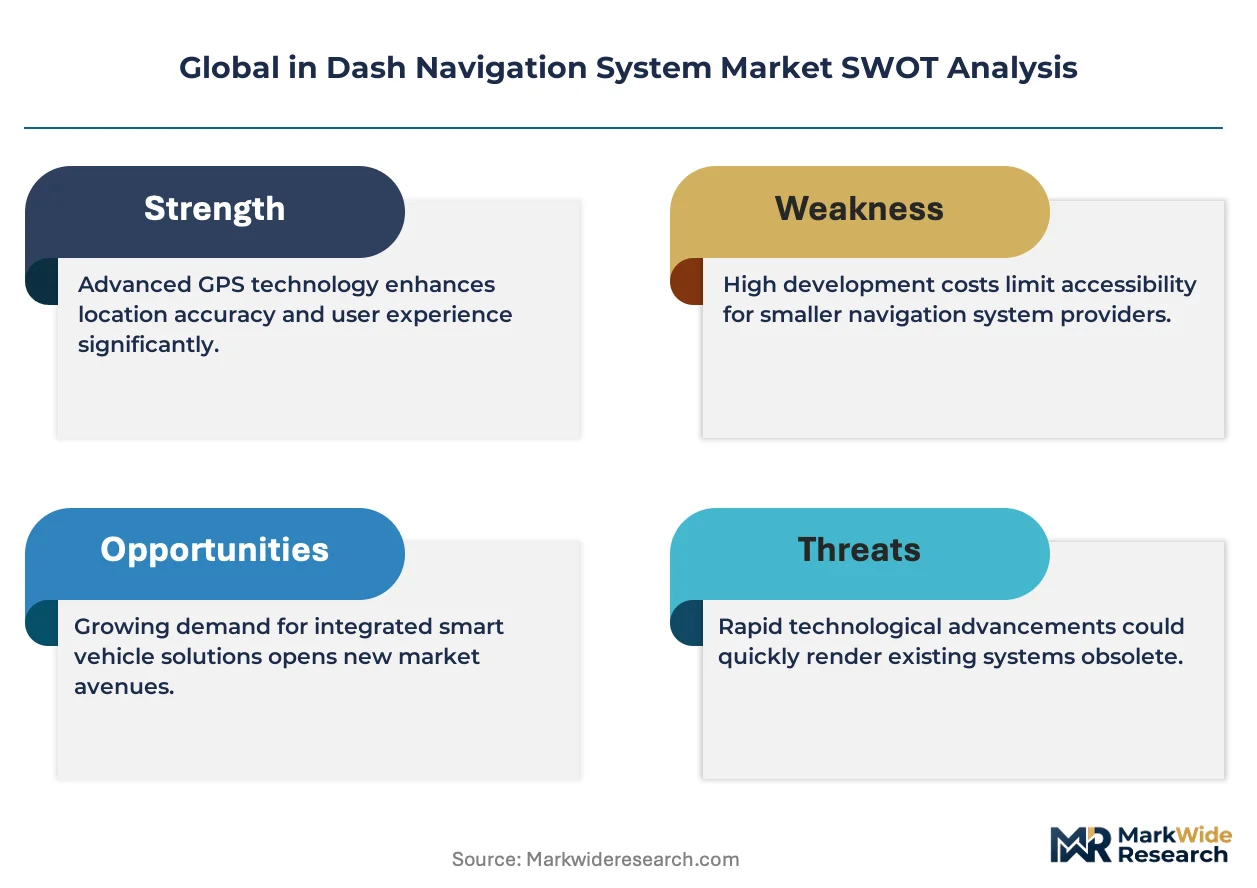
- Smartphone Substitution:Free, high-quality navigation applications on smartphones present a persistent substitution threat, particularly in the aftermarket and for base-trim vehicle models lacking integrated systems.
- Semiconductor Supply Volatility:The industry's reliance on a concentrated supply chain for microprocessors and display drivers creates vulnerability to shortages and price fluctuations, impacting infotainment unit production schedules.
- High Development Costs:Integrating navigation software with diverse vehicle hardware platforms and ensuring compliance with standards like AUTOSAR incurs significant R&D expenditure, creating a high barrier to entry.
Strategic Opportunities
- Commercial Vehicle Telematics:Significant underpenetration exists in the light and heavy commercial vehicle segments for integrated navigation that supports fleet management, logistics optimization, and hours-of-service compliance.
- Software Monetization Models:Shifting from one-time hardware sales to subscription models for live traffic, map updates, and premium features offers a recurring revenue stream for system developers and automakers.
- Expansion in Southeast Asia:Rising vehicle ownership in countries like Indonesia and Vietnam presents a new growth frontier for factory-fitted and aftermarket in-dash systems as automotive and digital infrastructure develops.
Industry Challenges
- Cybersecurity Vulnerability:As navigation systems become more connected with critical vehicle functions, ensuring protection against remote exploits and data breaches becomes a paramount and complex engineering challenge.
- Data Privacy Compliance:Managing user location data in accordance with disparate global regulations, such as GDPR in Europe and China's PIPL, creates significant legal and technical overhead for developers.
- HMI Standardization Gaps:The lack of a universal standard for Human-Machine Interface design to mitigate driver distraction, despite guidelines from the NHTSA, leads to fragmented development and inconsistent user experiences.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global in Dash Navigation System Market |
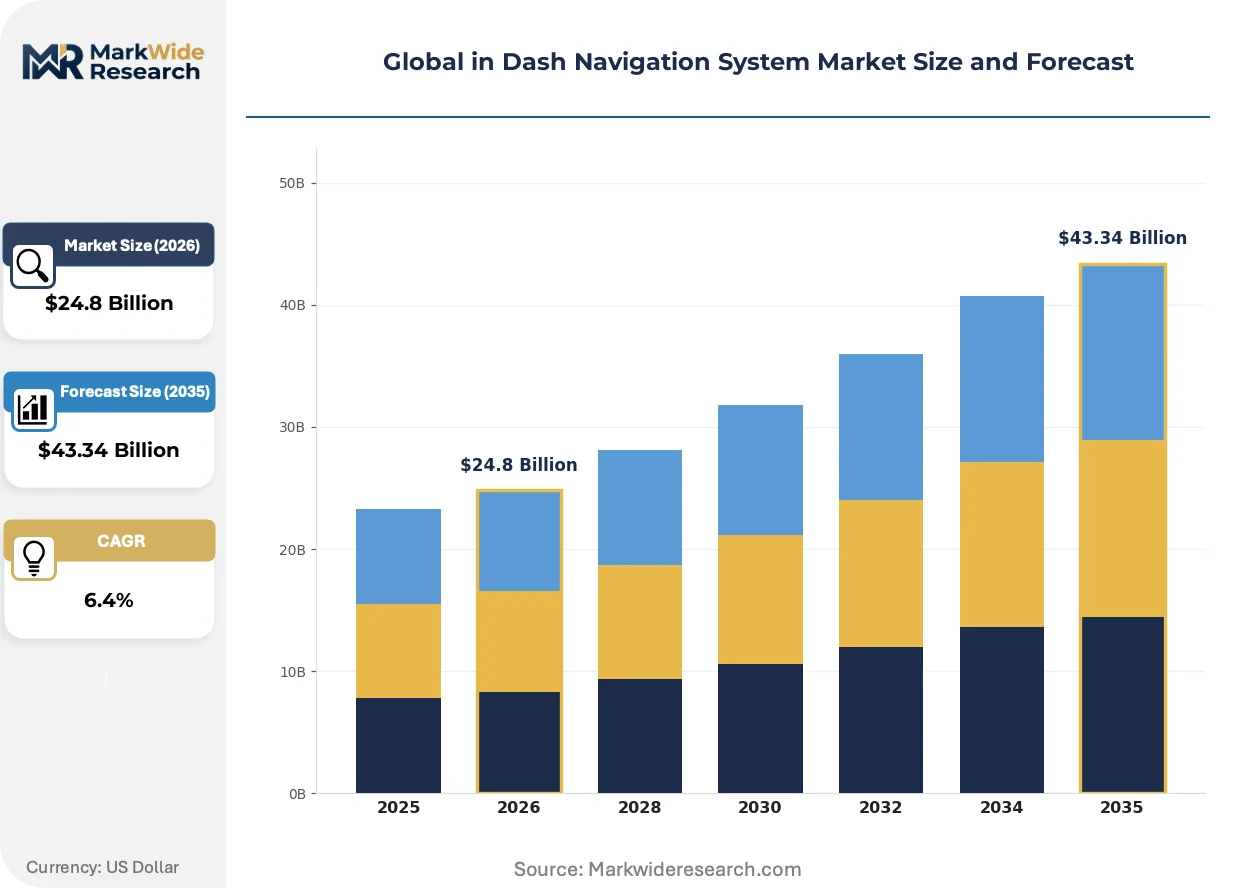
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Touchscreen Displays, Voice-Controlled Systems, Heads-Up Displays, Gesture-Based Interfaces Technology: GPS, GLONASS, Galileo, BeiDou, Assisted GPS Application: Passenger Cars, Commercial Trucks, Two-Wheelers, Recreational Vehicles End User: Vehicle Manufacturers, Fleet Operators, Rental Agencies, Logistics Providers |
| Companies Covered | Continental AG, Robert Bosch GmbH, Denso Corporation, Harman International, Alpine Electronics, Garmin Ltd., Pioneer Corporation, TomTom NV, JVCKENWOOD Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global in Dash Navigation System Market Strategic Shifts & Innovations
A fundamental shift is occurring as in-dash navigation evolves from a standalone routing tool into a central data hub within the vehicle's ecosystem. This integration with connected services and advanced driver-assistance systems is redefining the technology's value proposition and competitive landscape.
Augmented reality navigation projects real-time directional cues and points of interest directly onto the driver's view via a HUD or central screen. Premium and electric vehicle manufacturers are rapidly adopting this technology to improve situational awareness and reduce cognitive load. This innovation is decomposing the traditional map-centric interface into a more intuitive, context-aware visual experience integrated with the real world.
The United Nations Economic Commission for Europe (UNECE) has introduced regulations on cybersecurity (UN R155) and software updates (UN R156). This framework mandates secure-by-design principles and verifiable software integrity management throughout the vehicle's lifecycle. Navigation system suppliers must now provide robust over-the-air update capabilities and demonstrate comprehensive threat mitigation to achieve type approval in signatory countries.
Consumer preferences are shifting toward subscription-based feature activation over one-time hardware purchases for premium functionalities. Buyers are becoming accustomed to paying for ongoing services like live traffic data, satellite imagery, and specialized EV routing planners after the initial vehicle sale. This model is most prominent in the luxury passenger car segment in North America and Europe.
Global in Dash Navigation System Market Segmentation
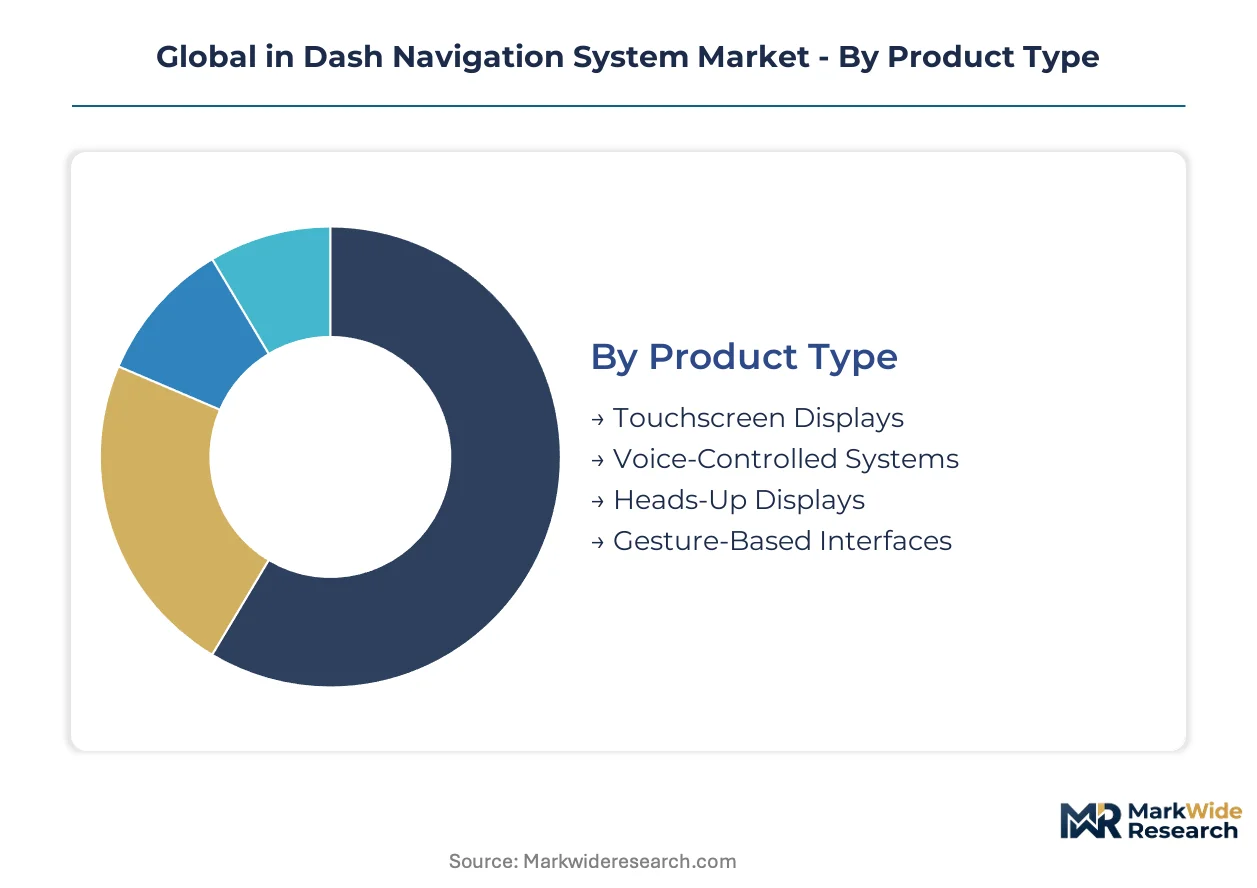
Understanding the Global in Dash Navigation System Market by its constituent segments reveals where innovation is concentrated and where value pools are forming. This granular view allows stakeholders to identify specific growth vectors and tailor product development to distinct user needs and technological requirements within various vehicle types and end-user ecosystems.
Product Type:
Margin pools within product types are increasingly shifting towards advanced visualization and interactive interfaces. Heads-Up Displays and sophisticated Touchscreen Displays command premium pricing due to their integration with vehicle safety systems and advanced infotainment features.
- Heads-Up Displays:These systems project navigation information directly onto the windshield within the driver's line of sight, often incorporating augmented reality overlays for real-time guidance. Adoption is accelerating in premium and electric vehicles, enhancing driver awareness and reducing cognitive load.
- Touchscreen Displays:Integrated into the dashboard, these units feature dedicated displays for map viewing, route planning, and infotainment control, forming the standard human-machine interface. Passenger cars represent the largest volume segment, with demand concentrated in new vehicle sales across all major automotive markets.
- Voice-Controlled Systems:These interfaces allow drivers to interact with navigation functions using natural language commands, minimizing manual input and enhancing safety. Integration with AI assistants is a key development focus for automakers.
- Gesture-Based Interfaces:Utilizing sensors to detect hand movements for system control, these nascent technologies offer a futuristic interaction method, primarily appearing in high-end luxury vehicle concepts.
The dominant share belongs to Touchscreen Displays, while Heads-Up Displays are expanding most quickly.
Technology:
The impact of different navigation technologies varies significantly based on their precision, global coverage, and resilience in diverse environments. Multi-constellation receivers enhance accuracy and reliability across all application areas.
- GPS:The Global Positioning System remains the foundational satellite navigation technology, providing widespread global coverage for basic positioning and timing services. Its ubiquity makes it an indispensable component in nearly all in-dash navigation units.
- Galileo:Europe's global navigation satellite system offers enhanced accuracy and signal robustness, particularly beneficial for urban environments and autonomous driving applications. European vehicle manufacturers are increasingly integrating Galileo for advanced driver assistance features.
- GLONASS:Russia's satellite navigation system provides an alternative or complementary signal source to GPS, improving positional accuracy and availability, especially in northern latitudes. Many global navigation systems incorporate GLONASS for redundancy.
- BeiDou:China's independent satellite navigation system offers comprehensive coverage within the Asia-Pacific region and is expanding globally, becoming a critical component for systems targeting the Chinese market.
- Assisted GPS:This technology enhances GPS performance by using cellular network data to speed up initial position fixes and improve accuracy in challenging signal conditions. Smartphone integration often leverages A-GPS for rapid location services.
The integration of GPS and Galileo creates a robust solution for high-precision navigation.
Application:
Volume distribution across applications highlights the primary market drivers and specific functional requirements for in-dash navigation systems. Each vehicle segment demands tailored features for optimal utility.
- Passenger Cars:This segment represents the largest volume for in-dash navigation systems, driven by consumer demand for integrated infotainment and connectivity features. New EV models, particularly in China, are accelerating adoption of advanced digital cockpits.
- Commercial Trucks:Navigation systems in commercial trucks prioritize route optimization for oversized loads, real-time traffic avoidance, and integration with fleet management telematics. Fleet operators seek solutions that enhance efficiency and compliance.
- Two-Wheelers:Integrated navigation for motorcycles and scooters focuses on compact, weatherproof displays and intuitive controls, often with helmet audio integration. Urban mobility solutions are driving demand in this niche.
- Recreational Vehicles:RV navigation systems require specialized routing for vehicle dimensions, campground POIs, and off-grid mapping capabilities. Aftermarket solutions hold a significant share in this segment.
The growth trajectory of Passenger Cars is significantly influenced by software-defined vehicle concepts.
End User:
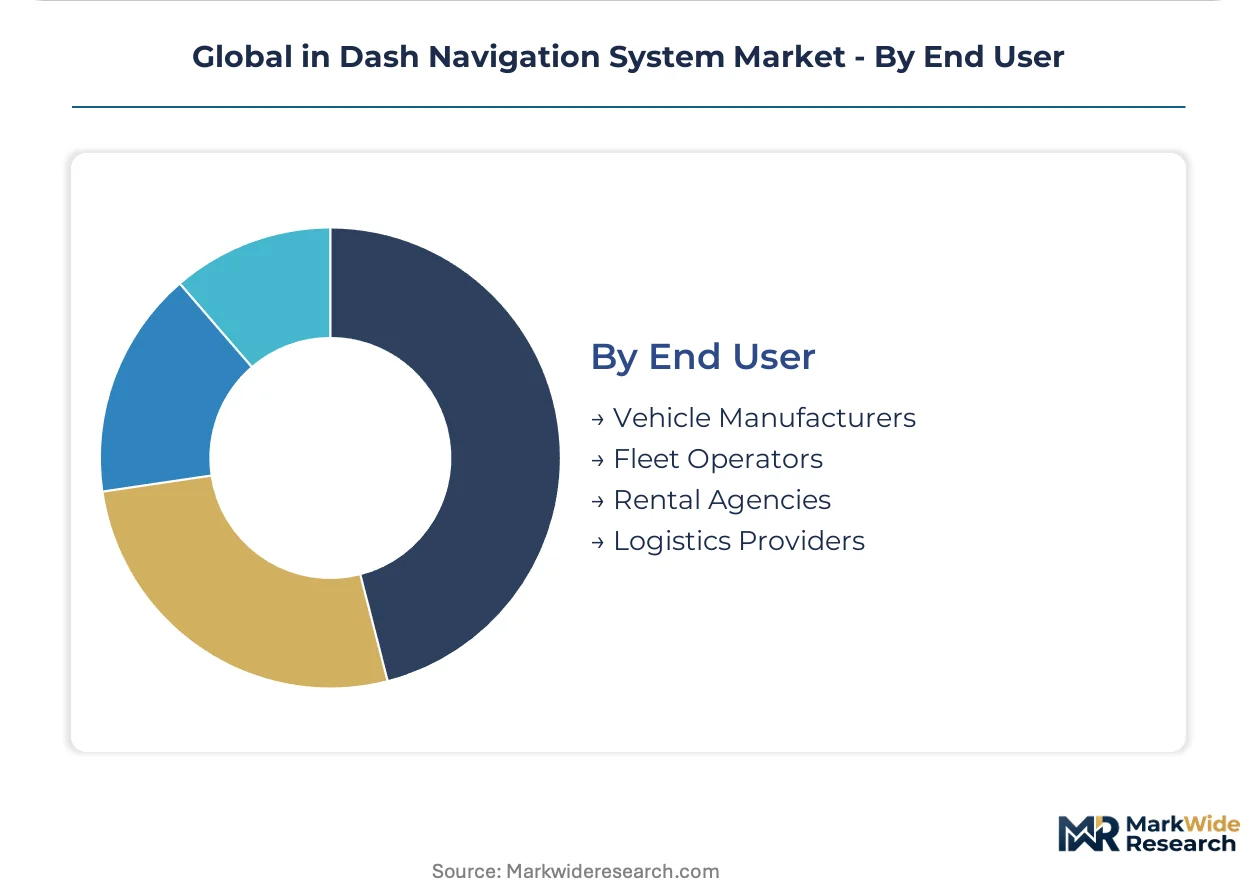
Supply concentration for end users is primarily with large vehicle manufacturers, who integrate systems directly into new vehicles. This contrasts with fleet operators and logistics providers who often opt for aftermarket or specialized telematics solutions.
- Vehicle Manufacturers:These entities integrate in-dash navigation systems directly into new vehicles as original equipment, controlling design, software, and hardware specifications. Their procurement strategies define the bulk of the market.
- Fleet Operators:Companies managing commercial vehicle fleets deploy navigation systems for route optimization, driver monitoring, and regulatory compliance. Telematics integration is a primary requirement for these users.
- Rental Agencies:These businesses equip their vehicles with navigation systems to enhance customer experience and offer value-added services. Standardized, user-friendly interfaces are critical for diverse clientele.
- Logistics Providers:Specialized navigation tools assist logistics companies with complex delivery routes, real-time tracking, and efficient resource allocation. Integration with supply chain management platforms is essential.
Strategic partnerships between Vehicle Manufacturers and Fleet Operators are redefining value delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for in-dash navigation systems varies significantly, with premium vehicle segments exhibiting lower price sensitivity compared to entry-level models. Buyers in emerging markets often prioritize cost-effectiveness, while established automotive hubs seek advanced feature sets. This dynamic influences regional investment and product development strategies.
China
The expansion of electric vehicle fleets in China creates direct demand for energy-aware navigation that optimizes routes based on charging station availability. China's GB standards for automotive electronics impose strict safety and performance requirements on system design. Shenzhen's technology cluster fosters rapid innovation in digital cockpit solutions for new energy vehicles.
Germany
Premium vehicle manufacturers in Germany integrate advanced navigation systems for enhanced safety and driver assistance features. UNECE regulations, including UN R155 for cybersecurity, significantly influence the development of secure navigation platforms. Bavaria's automotive industry drives innovation in augmented reality heads-up display technologies.
United States
Consumer preference for integrated infotainment and connectivity features drives demand for in-dash navigation systems in the United States. NHTSA guidelines shape human-machine interface development to minimize driver distraction. Silicon Valley companies collaborate with automakers on advanced connected car services and software integration.
Japan
The Japanese automotive sector seeks high-precision navigation systems that provide accurate real-time traffic information and situational awareness. METI promotes smart mobility initiatives that integrate advanced navigation with urban infrastructure. Tokyo's dense urban environment encourages the development of sophisticated traffic management and routing features.
India
A growing vehicle ownership base in India creates demand for factory-fitted and aftermarket in-dash navigation solutions. BIS standards for automotive components ensure quality and reliability for systems deployed in the country. Maharashtra's industrial belt contributes to local manufacturing and assembly capabilities for automotive electronics.
Global in Dash Navigation System Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the market structure. These players offer comprehensive digital cockpit solutions, contrasting with suppliers focused on specific components or aftermarket units. Strategic archetypes include full-stack system integrators, hardware-centric providers, and niche navigation specialists. Strategic partnerships and technology licensing are dominant competitive moves.
Within the integrated solutions provider archetype, Robert Bosch GmbH and Continental AG exemplify the trend towards comprehensive digital cockpit offerings. These German-based entities leverage extensive automotive electronics portfolios to deliver scalable hardware and software platforms. Garmin Ltd., a US-based firm, anchors the specialized segment, maintaining strong brand recognition in standalone and semi-integrated navigation units for aftermarket and recreational vehicle niches.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| Denso Corporation |
| Harman International |
| Alpine Electronics |
| Garmin Ltd. |
| Pioneer Corporation |
| TomTom NV |
| JVCKENWOOD Corporation |
| Others |
Cost & Logistics Intelligence
Long-term capacity reservation contracts in the semiconductor industry lock in both supply access and price visibility for critical in-dash navigation components. This strategic procurement ensures stability against market fluctuations.
Pricing Analysis
Subscription models for live traffic and map updates drive significant after-sales revenue, enhancing the lifetime value of in-dash navigation systems. Pricing stratifies across premium, standard, and economy tiers, reflecting feature sets and vehicle integration depth. Pricing softness in the aftermarket stems from pervasive smartphone substitution. Premium vehicle segments exhibit lower price sensitivity compared to base-trim models in emerging markets.
Supply Chain Analysis
Extended inventory holding periods for specialized microprocessors are common due to long lead times in the automotive electronics supply chain. Component supply concentrates in Taiwan, South Korea, and China, forming critical dependencies for display drivers and GNSS receivers. Single-source vulnerability for advanced chipsets represents a structural risk. Distribution runs primarily through direct integration into new vehicles by manufacturers, supplemented by aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a fragmentation opportunity as demand for specialized navigation services, such as EV routing and commercial telematics, creates distinct niches.
For Market Incumbents:
Compound existing strengths in comprehensive digital cockpit solutions by integrating advanced AI for voice control and predictive routing. This defends against software-defined vehicle shifts and the marginalization of single-function suppliers. Invest in secure-by-design principles and robust over-the-air update capabilities to meet evolving UNECE cybersecurity regulations. Leverage extensive automotive electronics portfolios to offer scalable hardware and software platforms.
For New Entrants and Emerging Players:
Specialized EV routing software, optimizing for charging infrastructure and state-of-charge, represents a service-layer gap. Target the light commercial vehicle segment in Southeast Asia, which remains underpenetrated for integrated navigation that supports fleet management. Develop subscription-based solutions tailored for specific logistics challenges. A direct-to-fleet go-to-market angle can bypass traditional automotive procurement cycles.
For Investors and Strategic Acquirers:
Capital is best deployed toward software specialists and AI/AR technology providers that can accelerate integration into next-generation digital cockpits. Long-term viability hinges on companies capable of delivering comprehensive, software-defined navigation experiences. The increasing adoption of subscription models for premium features serves as a key signal to watch for revenue stability and growth potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | This accelerates integration of navigation with critical vehicle functions and connected services. |
| Charging Infrastructure Partnership | This enhances EV-specific routing capabilities and driver convenience for electric vehicles. |
| Platform Standardization | This reduces development costs and accelerates time-to-market for new navigation features. |
| Acquisition of AI/AR Specialist Firm | This strengthens capabilities in augmented reality overlays and advanced human-machine interfaces. |
| Cybersecurity Certification Program | This ensures compliance with UN R155 regulations and builds trust in connected navigation systems. |
Research Approach
The analysis maps in-dash navigation systems across product types, technologies, and applications, each validated through primary interviews with OEM platform engineers, Tier 1 suppliers, fleet managers, and HMI designers. This approach combines insights from direct industry engagement with secondary data from vehicle production databases, automotive electronics standards, and patent filings. Bottom-up and top-down triangulation ensures data accuracy.
Consistency checks against external benchmarks were performed throughout the forecast period to validate volume and value outputs. The analytical framework models segmentation dimensions including product type, technology, application, end user, and regional adoption patterns. CAGRs were derived from historical data and projected market shifts influenced by EV sales forecasts and ADAS integration rates across the analysis window.
Forecasts assume regulatory continuity in major automotive regimes, including UNECE and NHTSA; material policy shifts would require re-modeling. Key risk factors like semiconductor supply volatility, cybersecurity threats, and data privacy regulations could influence market trajectory. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Electric Vehicle Infotainment Market
Telematics and Infotainment
Car DVR Market
Telematics and Infotainment
Global Automotive Navigation System Market
Telematics and Infotainment
India Fleet Management Software Market
Telematics and Infotainment
Europe Automotive Infotainment Systems Market
Telematics and Infotainment
Telematics Control Unit Market
Telematics and Infotainment
Motor Racing Telematics Market
Telematics and Infotainment
Intelligent Transport Systems (ITS) Market
Telematics and Infotainment
Asia Pacific Automotive Infotainment Systems Market
Telematics and Infotainment
Dashboard Camera Market
Telematics and Infotainment
Internet of Things Vehicle-To-Vehicle Communication Market
Telematics and Infotainment
North America Commercial Vehicle Telematics Market
Telematics and Infotainment
Automotive Embedded Telematics Market
Telematics and Infotainment
GCC Commercial Telematics Market
Telematics and Infotainment
In-Vehicle Infotainment Systems Market
Telematics and Infotainment
Automotive Personal Navigation Systems Market