
 GPS Tracker Market | 2026-2036
GPS Tracker Market Size, Share, and Industry Trends Forecast 2026-2036
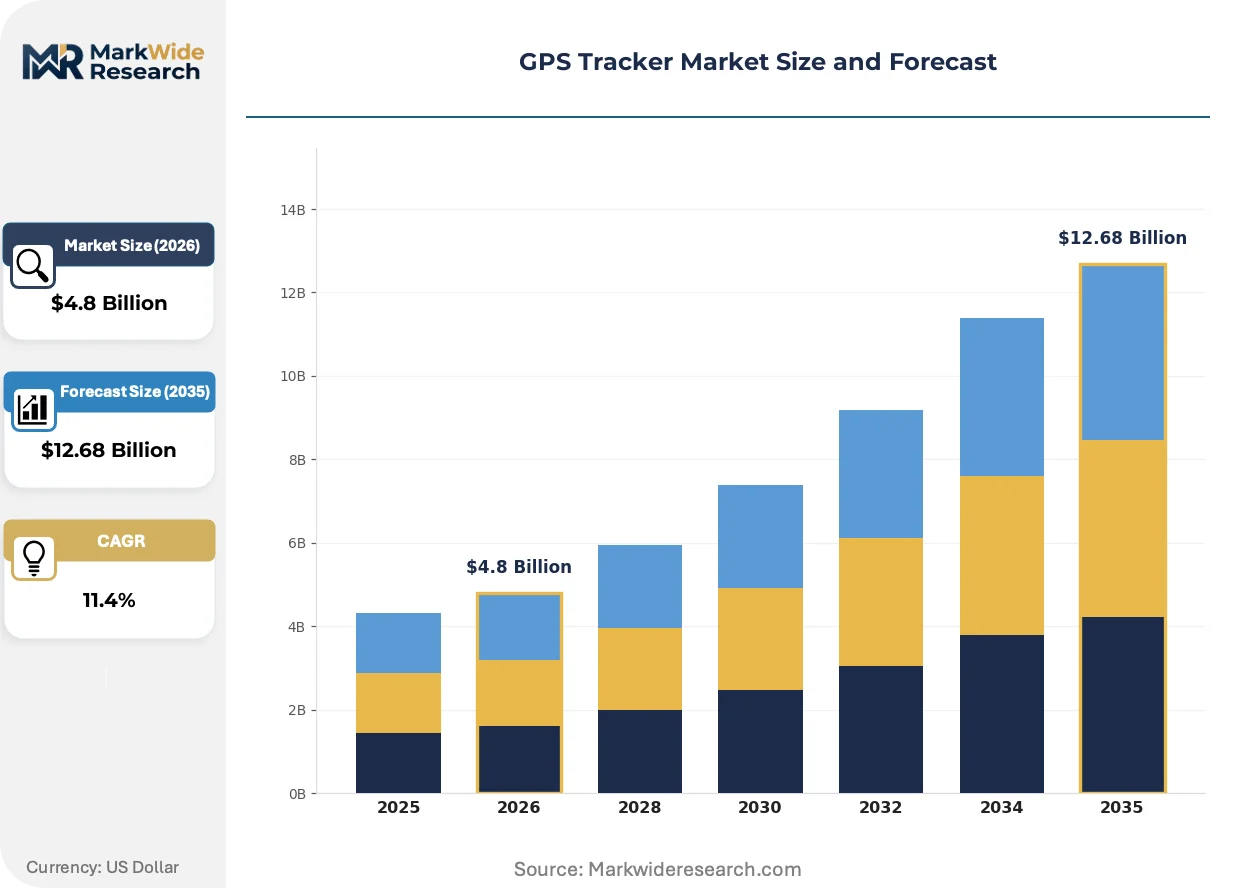
GPS Tracker Market Outlook
Multi-sourced component procurement is repositioning how GPS tracker manufacturers manage chipset supply and firmware development. Teltonika anchors its European manufacturing footprint with in-house assembly lines in Lithuania. Queclink competes through specialized hardware for insurance telematics and cold-chain monitoring. Samsara dominates the North American fleet software layer by bundling cellular-enabled trackers with cloud analytics.
A GPS tracker is an electronic device that receives satellite signals from constellations including GPS, GLONASS, Galileo, and BeiDou to calculate geographic position, typically incorporating a cellular or satellite modem for data transmission to centralized platforms. Vehicle trackers constitute the largest installed base due to mandatory fleet compliance programs and insurance discount incentives, while wearable trackers represent the fastest-expanding margin pool as consumer subscription models displace one-time hardware sales. Portable trackers serve construction and logistics sectors where temporary asset deployment demands battery-optimized form factors with magnetic mounting.
The FCC enforces Part 15 and Part 90 equipment authorization standards that govern radio frequency emissions and cellular modem certification for devices sold in the United States. ETSI harmonizes spectrum allocation and interoperability benchmarks across EU member states under the Radio Equipment Directive. Fleet managers and device vendors must monitor evolving mandates from the EU AI Act and emerging cybersecurity labeling requirements that will reshape firmware update obligations and data governance architectures.
Market Dynamics
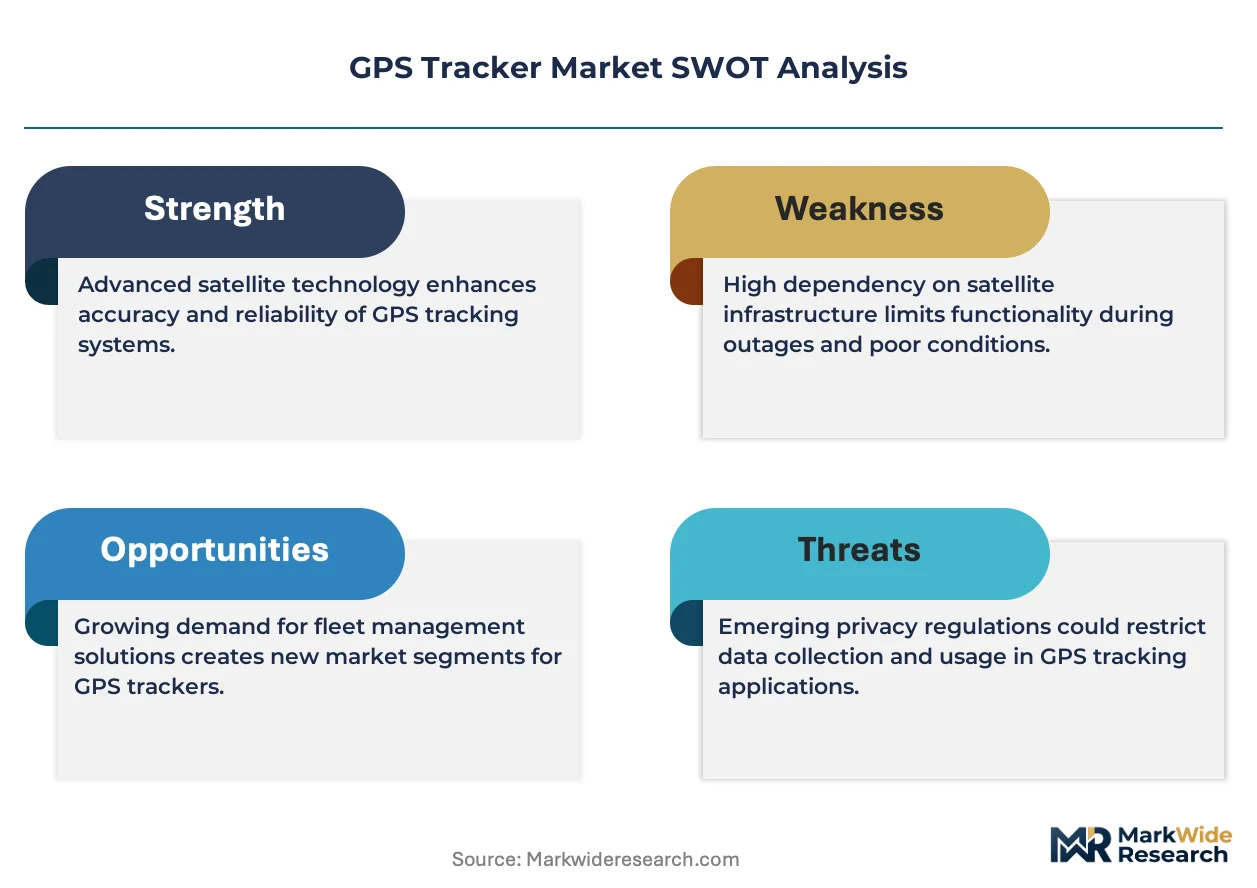
Fleet operators are consolidating telematics procurement around integrated hardware-software bundles, compressing standalone device margins while elevating firmware and analytics capabilities as the primary value differentiator.
Growth Catalysts
- ELD Mandate Compliance:Hours-of-service regulations in the United States compel commercial carriers to deploy certified logging devices, creating baseline demand for cellular-connected vehicle trackers across long-haul and regional fleets.
- Insurance Telematics:Usage-based insurance programs leverage real-time driving behavior data to price risk dynamically, expanding device installations in passenger and light commercial vehicles.
- LoRaWAN Network Expansion:Low-power wide-area infrastructure rollouts in urban logistics corridors enable battery-optimized asset tracking without cellular subscription burdens.
Market Restraints
- Semiconductor Supply Concentration:Cellular modem and GNSS chipset fabrication concentrates among a limited set of foundries, exposing device manufacturers to allocation volatility and extended lead times.
- FCC Certification Friction:Part 15 and Part 90 equipment authorization timelines for radio frequency devices routinely extend six to nine months, delaying product launches and compressing revenue recognition windows.
- Smartphone Substitution:Bring-your-own-device policies in light fleet applications allow operators to repurpose consumer handsets for basic location tracking, eroding addressable volume in entry-tier hardware.
Strategic Opportunities
- EU Cybersecurity Labeling:Emerging RED cybersecurity requirements create first-mover advantage for vendors with pre-certified firmware architectures and over-the-air update capabilities.
- Cold-Chain Monitoring:Temperature-sensitive pharmaceutical and food logistics operators seek combined location and environmental sensing, opening premium hardware configurations with multi-sensor integration.
- Construction Equipment Rental:Temporary asset deployment models in building and infrastructure projects favor portable magnetic-mount trackers with extended battery autonomy and ruggedized enclosures.
Industry Challenges
- Firmware Engineering Scarcity:Embedded systems development for multi-constellation GNSS and cellular modem integration outpaces qualified talent availability, elongating product development cycles.
- Legacy Fleet Integration:Heterogeneous installed bases of proprietary protocols and aged telematics platforms complicate unified data aggregation for enterprise fleet managers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GPS Tracker Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Trackers, Fixed Trackers, Vehicle Trackers, Wearable Trackers Technology: GPS, GLONASS, Galileo, BeiDou End User: Fleet Managers, Outdoor Enthusiasts, Law Enforcement, Personal Users Application: Vehicle Tracking, Asset Tracking, Pet Tracking, Personal Tracking |
| Companies Covered | Coban, WanWay, Concox (Jimi IoT), Samsara, Ruptela, Teltonika, Queclink, Galileosky, Sinotrack, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GPS Tracker Market Strategic Shifts
Edge computing architectures are redistributing processing loads from cloud platforms to device firmware, altering how location data is filtered, stored, and transmitted across fleet networks.
Dual-frequency GNSS reception is decentralizing precision positioning capabilities previously reserved for survey-grade equipment. Logistics operators in dense urban canyons adopt L1/L5 band receivers to mitigate multipath interference. The technology is compressing subscription premiums for sub-meter accuracy services.
ETSI's Radio Equipment Directive cybersecurity amendments are mandating secure boot chains and cryptographic key storage for connected devices sold in EU member states. Manufacturers must revalidate existing product lines against EN 303 645 baseline requirements. Fleet procurement specifications in Germany and France now prioritize RED-certified hardware.
Subscription bundling is displacing transactional hardware sales as the dominant commercial model. Fleet software vendors integrate device costs into per-vehicle monthly fees, obscuring capital expenditure visibility. This shift is most pronounced among North American last-mile delivery operators consolidating vendor relationships.
GPS Tracker Market Segmentation
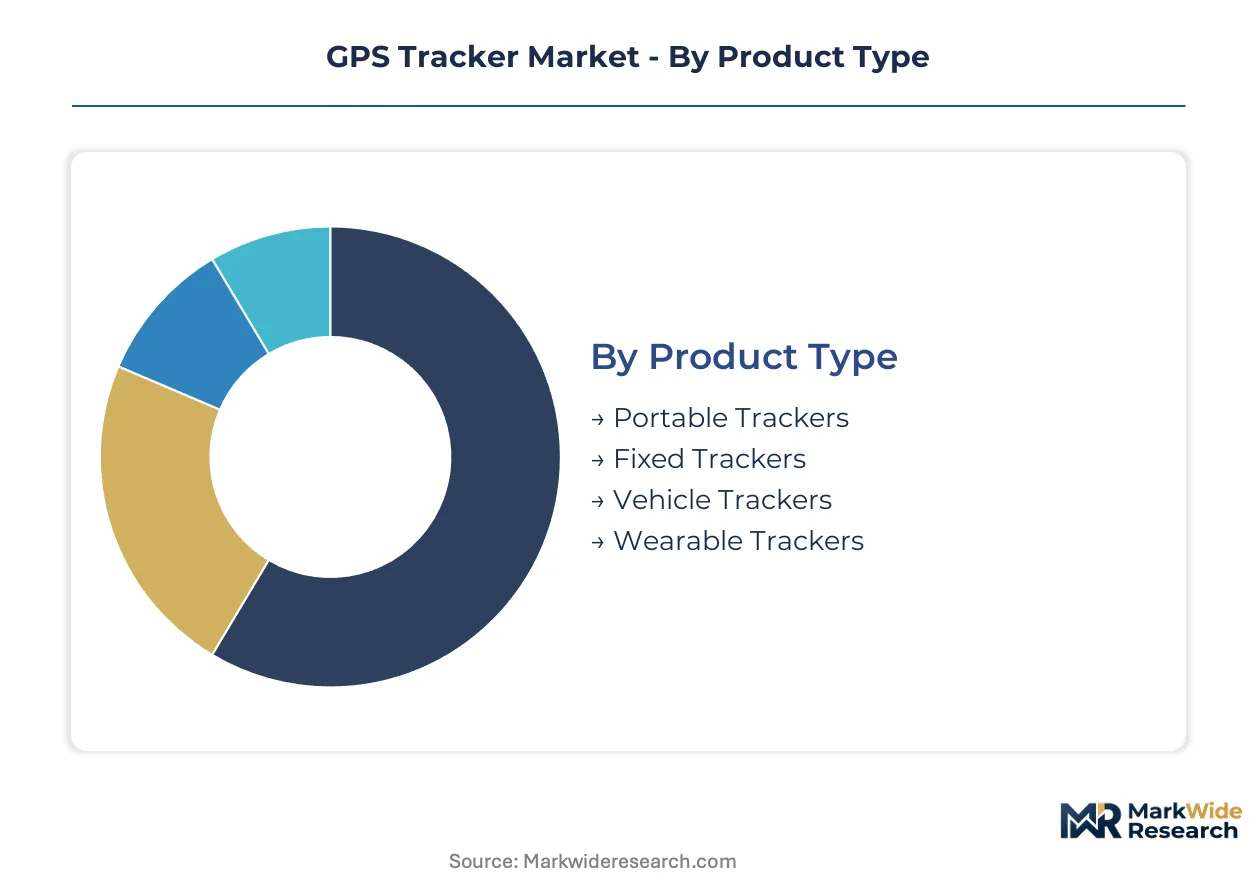
GPS tracker segmentation reveals divergent hardware requirements across mobility patterns and power constraints. Fleet procurement teams evaluate devices against installation permanence, constellation accuracy, and subscription economics rather than unit cost alone.
Product Type:
The customization-vs-standardization spectrum spans magnetic-mount portability against hardwired integration depth.
- Vehicle Trackers:Hardwired units draw power from automotive electrical systems and integrate OBD-II or direct-battery connections for continuous operation. Long-haul carriers in the United States deploy these for ELD mandate compliance, with insurance discount programs accelerating replacement cycles in light commercial fleets.
- Portable Trackers:Battery-optimized enclosures with magnetic mounting serve construction equipment rental yards and temporary logistics deployments where installation permanence is impractical. Extended autonomy requirements drive lithium-thionyl chloride chemistry selections over standard lithium-ion.
- Fixed Trackers:AC-powered stationary units anchor warehouse and yard management systems with minimal mobility requirements. These configurations prioritize Ethernet or Wi-Fi backhaul over cellular modems to reduce recurring subscription burdens.
- Wearable Trackers:Consumer-oriented form factors with biometric integration target outdoor recreation and elderly care monitoring segments.
Leading the category by volume: Vehicle Trackers. Growing fastest: Wearable Trackers.
Technology:
Cost tier stratification separates single-constellation economy hardware from multi-band precision receivers.
- GPS:The original NAVSTAR constellation maintains backward compatibility across installed device bases. Legacy fleet telematics platforms rely exclusively on L1 C/A code reception, though urban canyon multipath limits accuracy in dense metropolitan corridors.
- GLONASS:Russian Federation constellation coverage improves high-latitude positioning reliability where GPS geometry degrades. Nordic logistics operators and Siberian resource extraction fleets specify GLONASS-enabled receivers for polar route redundancy.
- Galileo:European Union's civilian-designed constellation offers dual-frequency E1/E5a reception for ionospheric error correction without augmentation services. German automotive OEMs increasingly mandate Galileo compatibility for connected vehicle platforms.
- BeiDou:China's completed global constellation provides regional signal strength advantages across Asia-Pacific terrestrial and maritime routes. Domestic fleet operators in China face regulatory nudges toward BeiDou-first receiver prioritization.
Volume leadership: GPS-enabled devices. Steepest expansion trajectory: Multi-constellation receivers combining GPS with Galileo or BeiDou.
End User:
Customer type determines procurement scale and firmware customization depth.
- Fleet Managers:Enterprise telematics buyers negotiate thousand-unit deployments with API integration requirements and white-label dashboard provisions. These accounts drive demand for over-the-air firmware update capabilities and cybersecurity certification documentation.
- Personal Users:Individual consumers purchase through retail channels or insurance bundling programs with minimal technical support expectations. Subscription attachment rates vary sharply by distribution channel.
- Law Enforcement:Covert tracking applications require compact form factors and extended standby modes with judicial authorization workflows. These specifications diverge substantially from commercial fleet hardware.
- Outdoor Enthusiasts:Recreational users prioritize waterproofing ratings and SOS beacon integration over positional accuracy specifications.
Procurement volume concentrates with Fleet Managers. Margin expansion concentrates with Law Enforcement specialty configurations.
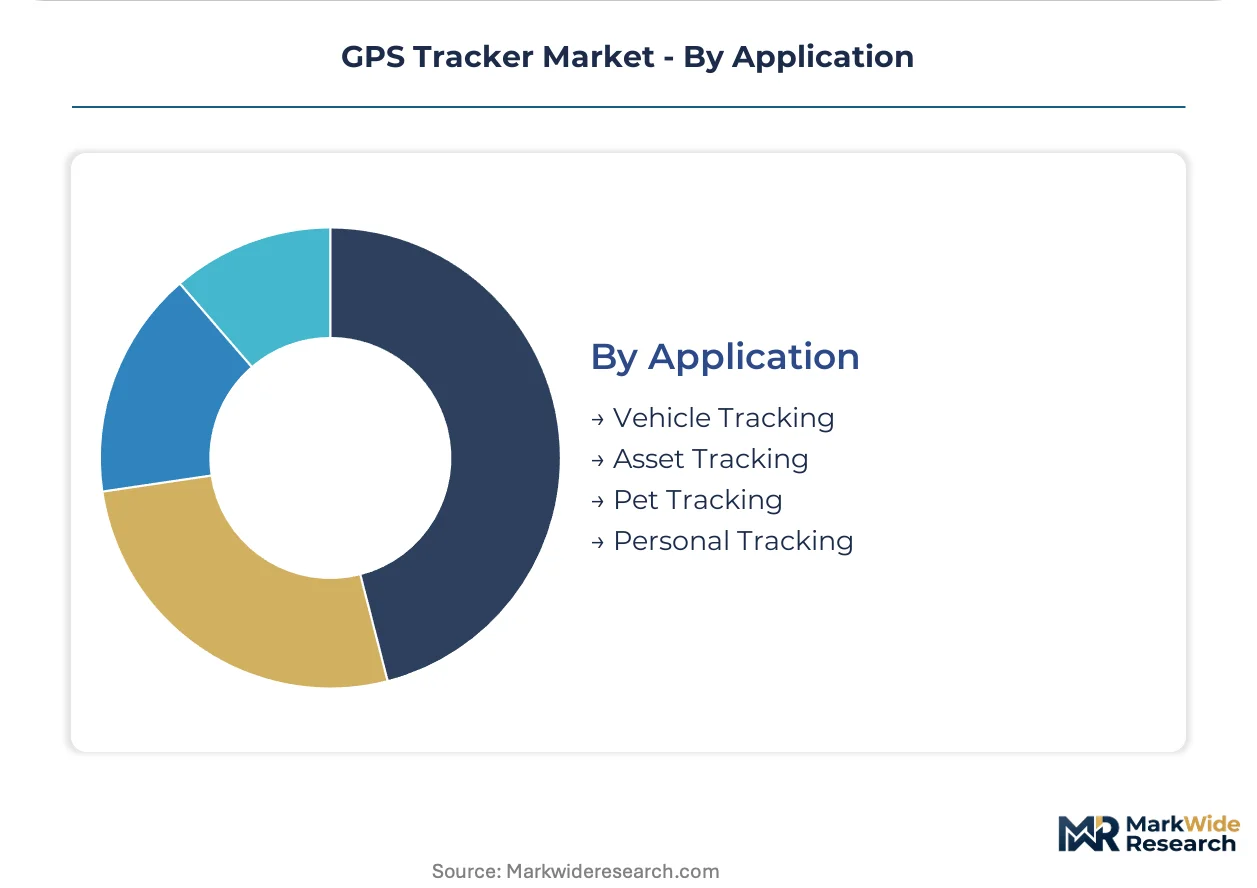
Application:
Maturity differentiation separates established vehicle telematics from emerging pet and personal monitoring segments.
- Vehicle Tracking:Regulatory mandates and insurance underwriting requirements sustain replacement demand across commercial and passenger vehicle pools. FCC Part 90 certification requirements create compliance barriers for new hardware entrants.
- Asset Tracking:Construction, agriculture, and intermodal container operators deploy ruggedized units with extended battery autonomy. LoRaWAN network expansion in urban logistics corridors is displacing cellular subscriptions for non-time-critical asset visibility.
- Personal Tracking:Child safety and elderly care applications drive consumer subscription models with geofencing alert functionality. These deployments emphasize ease-of-use over technical specification depth.
- Pet Tracking:Collar-integrated devices with activity monitoring represent the smallest volume pool but highest subscription attachment rates per active device.
Application maturity: Vehicle Tracking dominates installed base. Climbing the fastest: Asset Tracking in construction and cold-chain logistics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer fabrication capacity in Taiwan and South Korea anchors upstream component flows for GPS tracker assembly. Fleet telematics deployment concentrates where logistics density and regulatory mandates intersect.
United States
Last-mile delivery operators and long-haul carriers drive hardware procurement at scale. FCC Part 15 and Part 90 certification requirements create compliance barriers for new entrants. Chicago and Dallas-Fort Worth logistics corridors host fleet management software development clusters.
Germany
Automotive OEM telematics programs and cold-chain logistics operators specify multi-constellation receivers. ETSI Radio Equipment Directive cybersecurity amendments mandate secure boot chains for connected devices. Stuttgart and Munich engineering centers anchor precision positioning R&D activity.
China
Domestic fleet operators face regulatory nudges toward BeiDou-first receiver prioritization. MIIT equipment certification governs cellular modem integration for devices sold domestically. Shenzhen and Dongguan manufacturing clusters dominate PCB assembly and firmware integration.
United Kingdom
Insurance telematics programs and construction equipment rental fleets sustain device demand. DVLA commercial vehicle regulations align with EU-type approval frameworks post-Brexit. Birmingham and Manchester logistics hubs drive regional fleet modernization cycles.
India
Two-wheeler fleet operators and intermodal container tracking applications expand addressable volume. BIS certification requirements and PLI scheme incentives shape domestic manufacturing investment. Pune and Chennai automotive corridors host telematics integration facilities.
GPS Tracker Market Competitive Environment
Strategic partnerships dominate the current landscape as vendors bundle hardware with cloud analytics platforms. The vendor base stratifies across integrated hardware-software providers, specialized device manufacturers, and regional assembly specialists. Three archetypes define competitive positioning: fleet software bundlers, component-specialist fabricators, and value-engineered volume producers. M&A activity and firmware licensing agreements represent the primary competitive moves reshaping market structure.
Among European-based specialists, Teltonika anchors the integrated manufacturing archetype with Lithuanian assembly operations. Queclink and Concox occupy positions within the component-specialist tier, representing hardware-focused competitive positioning against bundled software offerings. Samsara exemplifies the fleet software bundler archetype, embedding device costs within per-vehicle subscription models.
| Leading Market Players |
|---|
| Coban |
| WanWay |
| Concox (Jimi IoT) |
| Samsara |
| Ruptela |
| Teltonika |
| Queclink |
| Galileosky |
| Sinotrack |
| Others |
Value Chain & Pricing Dynamics
Lithium carbonate spot indices and cellular modem chipset contract rates cascade through GPS tracker manufacturing into three distinct pricing tiers segmented by firmware certification depth and after-sales service bundling.
Pricing Analysis
Extended warranty and over-the-air firmware update bundling separate premium-tier hardware from unbundled economy configurations. Three-tier pricing structure across premium, standard, and economy levels stratifies by FCC Part 90 certification tier and GNSS constellation support. Cost compression in entry-tier vehicle trackers is intensifying because smartphone substitution policies erode standalone device volumes. Fleet managers purchasing thousand-unit deployments exhibit lowest price sensitivity; personal users through retail channels show highest elasticity.
Supply Chain Analysis
ETSI RED cybersecurity certification and FCC Part 15 equipment authorization function as qualification gates that filter supplier eligibility and elongate procurement cycles. Cellular modem fabrication concentrates in Taiwan and South Korea; PCB assembly and final integration anchor in China and Lithuania. Raw material dependencies span lithium-thionyl chloride battery chemistry, multi-layer ceramic capacitors, and precision GNSS antenna substrates. Single-source vulnerability in cellular baseband chipsets exposes manufacturers to allocation volatility. Distribution runs through fleet management software vendors bundling hardware into per-vehicle subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GPS tracker market sits in a technology-transition phase as dual-frequency GNSS receivers displace legacy single-constellation hardware across logistics fleets.
For Market Incumbents: Deepen backward integration into cellular modem firmware development to offset semiconductor supply concentration risk. Secure ETSI RED cybersecurity pre-certification for existing product lines before mandatory EN 303 645 deadlines compress compliance windows. Prioritize over-the-air update infrastructure as the primary retention lever against software-centric entrants. For New Entrants and Emerging Players: EU AI Act and emerging cybersecurity labeling requirements in Germany open a window for firmware-native vendors without legacy hardware baggage. Cold-chain monitoring applications in pharmaceutical logistics present the most penetrable white-space segment. Pursue white-label OEM partnerships with regional fleet software platforms rather than direct enterprise sales. For Investors and Strategic Acquirers: Distressed-cycle entries favor component-specialist fabricators with captive certification expertise in Lithuania and Poland. Long-term viability hinges on subscription revenue attachment rates displacing transactional hardware margins. Watch LoRaWAN network coverage expansion as the inflection signal for cellular subscription displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| ETSI RED Cybersecurity Certification | EN 303 645 compliance secures German and French fleet procurement specifications against uncertified rivals. |
| Dual-Frequency GNSS Integration | L1/L5 band reception captures urban logistics premiums previously reserved for survey-grade equipment vendors. |
| LoRaWAN Module Development | Battery-optimized asset tracking without cellular subscriptions penetrates construction rental yard deployments. |
| Firmware Licensing Agreements | White-label telemetry stacks accelerate time-to-market for regional hardware assemblers lacking software depth. |
| Vertical Integration into Battery Chemistry | Lithium-thionyl chloride cell sourcing secures extended autonomy specifications for magnetic-mount portable units. |
Study Parameters
Document review covered FCC equipment authorization databases, ETSI harmonized standards filings, and cellular carrier IoT connectivity disclosures, complemented by interviews with fleet telematics procurement directors, embedded systems firmware engineers, and logistics corridor operations managers. Secondary validation drew from customs import records, semiconductor foundry capacity reports, and fleet management software vendor SEC filings. Bottom-up device shipment estimates and top-down fleet penetration rates were triangulated against cellular IoT connection disclosures.
Segment-level projections across vehicle, portable, fixed, and wearable form factors were generated over the projection horizon. Constellation technology splits, end-user procurement scale tiers, and application-specific regulatory compliance requirements structured the analytical framework. CAGRs were derived from logistic curve adoption modeling calibrated against ELD mandate compliance deadlines and insurance telematics penetration benchmarks. Forecast inputs incorporated cellular modem allocation lead times and GNSS chipset roadmap disclosures.
The model assumes a particular technology adoption path; alternative pathways for satellite-based narrowband IoT would alter the outlook for terrestrial cellular-dependent hardware. Forecasts reflect documented assumptions regarding fleet replacement cycles and regulatory enforcement intensity. A model refresh is warranted upon material change in FCC equipment authorization timelines or EU cybersecurity labeling implementation schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Car Generated Data Market
Telematics and Infotainment
Edge Computing in Automotive Market
Telematics and Infotainment
Internet of Things Vehicle-To-Vehicle Communication Market
Telematics and Infotainment
Japan Commercial Telematics Market
Telematics and Infotainment
Automotive Human Machine Interface (HMI) Market
Telematics and Infotainment
Marine Telematics Market
Telematics and Infotainment
Europe Automotive Telematics Market
Telematics and Infotainment
United States Commercial Telematics Market
Telematics and Infotainment
Mobility on Demand (Mod) Market
Telematics and Infotainment
Automotive Infotainment Market
Telematics and Infotainment
Global in Dash Navigation System Market
Telematics and Infotainment
Vehicle Digital Cockpit Market
Telematics and Infotainment
Asia-Pacific Connected Cars Market
Telematics and Infotainment
GCC Commercial Telematics Market
Telematics and Infotainment
North America Dashboard Camera Market
Telematics and Infotainment
Consumer Telematics Market