
 North America in-Building Wireless Market | 2026-2036
North America in-Building Wireless Market Size, Share, and Industry Trends Forecast 2026-2036
North America in-Building Wireless Market Outlook
RF engineering talent scarcity is unwinding project timelines across the North America in-Building Wireless Market as carriers and neutral-host operators compete for the same specialized workforce. CommScope leverages its captive supply of passive components to control deployment costs for distributed antenna systems. JMA Wireless specializes in software-defined baseband units that differentiate its offering in venues requiring rapid carrier onboarding. Crown Castle anchors the managed services layer through its extensive fiber backhaul footprint tied to indoor cellular hubs.
In-building wireless encompasses the infrastructure, active equipment, and radio frequency distribution systems that deliver cellular and Wi-Fi connectivity inside structures where outdoor macro signals degrade, typically operating across 700 MHz to 3.5 GHz bands with power levels below 1 watt per remote unit to avoid interference. The primary commercial purpose is ensuring seamless voice and data coverage for occupants, first responders, and IoT devices in dense architectural environments. Distributed antenna systems still occupy the largest share of product type revenue due to their carrier-grade reliability in healthcare facilities and Class A office towers. Small cells are registering the fastest expansion among product categories as enterprises deploy private 5G networks in manufacturing plants and logistics warehouses. Wi-Fi 6 technology leads the technology segment in volume terms though 5G commands premium pricing in venues requiring guaranteed service-level agreements.
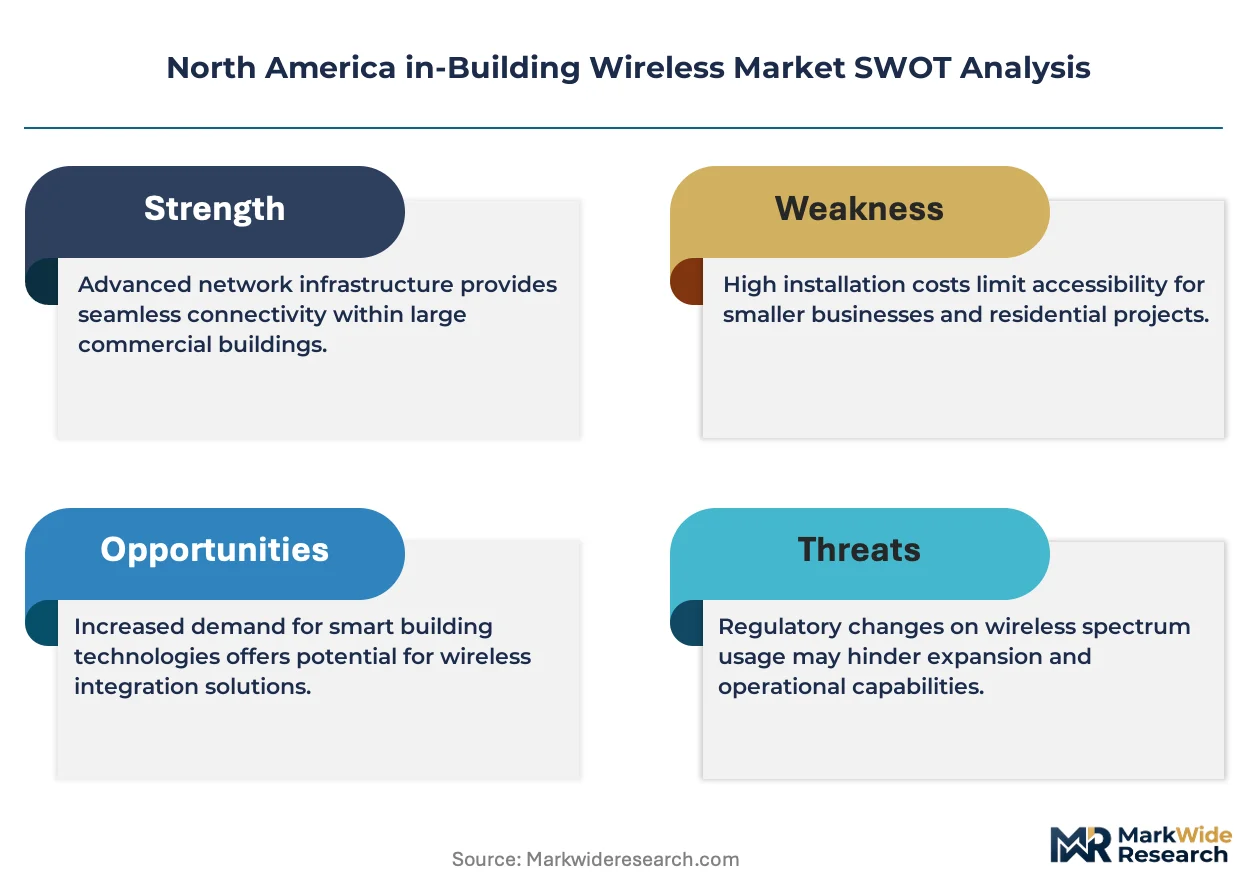
The FCC governs spectrum allocation and device certification through OET procedures that directly shape which frequencies in-building systems can exploit, while the National Fire Protection Association's NFPA 1221 standard mandates minimum signal strength for public safety radio inside buildings. OSHA compliance for tower and rooftop worker safety adds cost layers to antenna placement projects. Stakeholders must monitor CBRS Priority Access License auction outcomes and state-level building codes to determine whether private network deployments or carrier-owned infrastructure delivers superior returns on indoor coverage investments.
Market Dynamics
The North America in-Building Wireless Market is experiencing structural compression as stadium operators and mixed-use developers consolidate procurement around neutral-host architectures, forcing equipment vendors to reconfigure pricing and service models around shared infrastructure economics rather than carrier-specific deployments.
Growth Catalysts
- CBRS Spectrum Liberalization:The FCC's Citizens Broadband Radio Service framework reallocates 3.5 GHz spectrum for private LTE and 5G networks, enabling enterprises to bypass carrier negotiations entirely.
- Stadium Connectivity Mandates:Fan experience investments across NFL and MLB venues are creating standardized procurement templates that accelerate neutral-host system adoption.
- Texas and California Development Concentration:Large-scale mixed-use projects in Dallas-Fort Worth and Los Angeles corridors generate contiguous demand blocks that justify dedicated RF engineering teams.
Market Restraints
- RF Engineering Talent Scarcity:Specialized workforce pools in antenna design and propagation modeling are concentrated among three national labor markets, creating bidding wars that extend project timelines.
- Passive Component Supply Concentration:Coaxial cable and power splitter manufacturing clusters in Southeast Asia expose DAS deployments to freight cost volatility and customs processing delays.
- NFPA 1221 Compliance Burden:The National Fire Protection Association's public safety radio signal strength mandates add specialized testing phases that increase deployment costs for healthcare and government facilities.
Strategic Opportunities
- Private 5G in Manufacturing:Automotive and electronics assembly plants in Michigan and Tennessee present underpenetrated demand for guaranteed-latency wireless replacing Wi-Fi for AGV control.
- First Responder Broadband Integration:FirstNet deployment deadlines create regulatory tailwinds for dual-purpose infrastructure serving both commercial subscribers and emergency personnel.
- Software-Defined Baseband Convergence:Virtualized RAN architectures merging 5G NR and Wi-Fi 6 management planes enable venue operators to collapse multiple vendor relationships into single-dashboard operations.
Industry Challenges
- Multi-Carrier Interoperability Testing:Certification timelines for Verizon, AT&T, and T-Mobile coexistence protocols extend system acceptance phases, compressing venue operator revenue recognition windows.
- Legacy DAS Retrofit Complexity:Existing 700 MHz and AWS-1 infrastructure in Class A office towers requires expensive headend upgrades to support 5G mid-band capacity without full cable replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America in-Building Wireless Market |
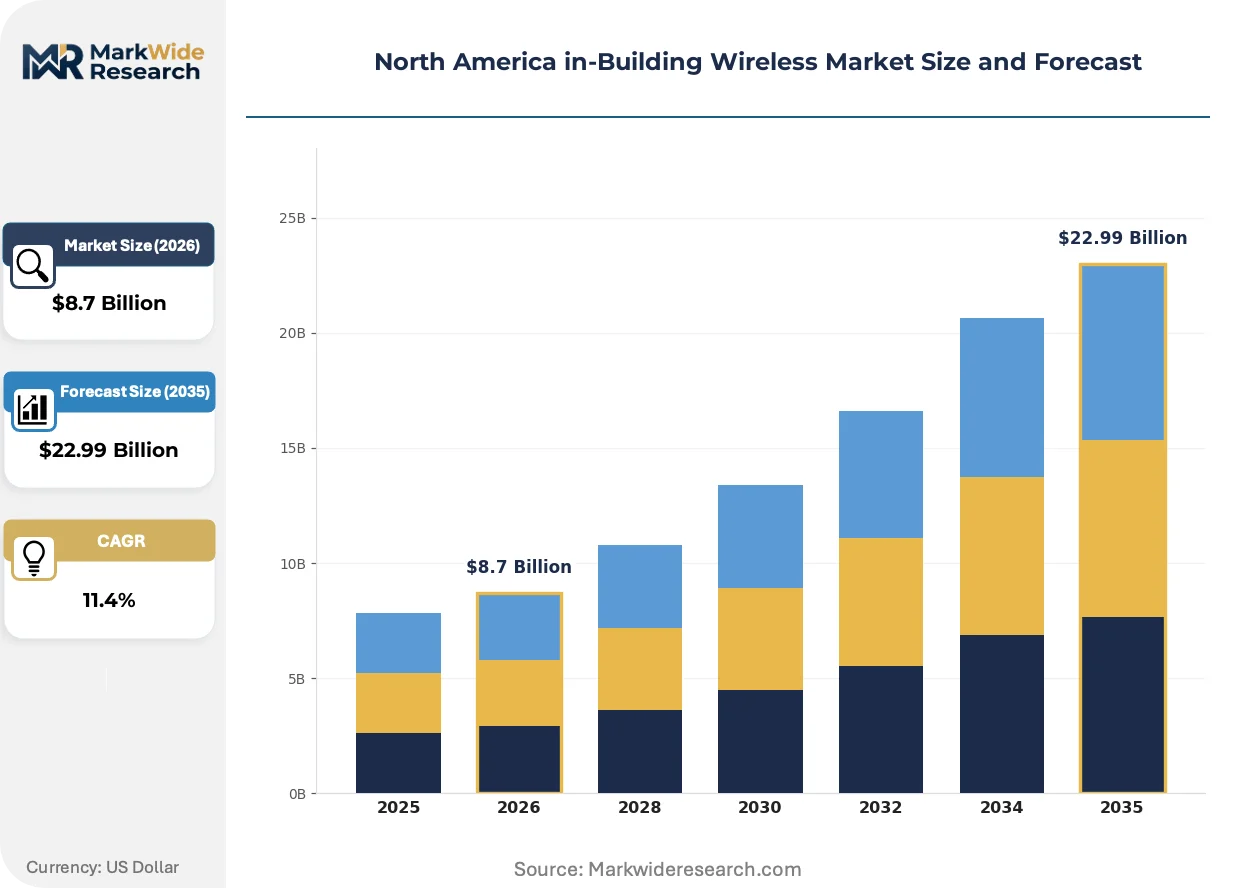
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Distributed Antenna Systems, Small Cells, Repeaters, Wi-Fi Solutions End User: Commercial Buildings, Residential Complexes, Educational Institutions, Healthcare Facilities Technology: LTE, 5G, Wi-Fi 6, DAS Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | CommScope, Crown Castle, Airspan Networks, Corning Incorporated, JMA Wireless, Nokia, Ericsson, Cobham Limited, Boingo, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America in-Building Wireless Market Strategic Shifts
Active antenna systems and software-defined radio architectures are compressing hardware footprints while expanding spectral agility, fundamentally altering how venue operators negotiate with carriers and neutral-host providers over infrastructure ownership and revenue sharing.
Remote radio units incorporating gallium nitride power amplifiers are miniaturizing thermal management requirements, allowing deployment in ceiling plenums previously reserved for passive coaxial distribution. Healthcare facilities in Boston and Philadelphia are adopting these compact active units to preserve HVAC clearance while adding 5G capacity. The reduced footprint is miniaturizing equipment room requirements, enabling retrofits in historic buildings with constrained mechanical infrastructure.
The FCC's Part 96 CBRS rules are mandating Spectrum Access System coordination for indoor 3.5 GHz deployments, creating a new compliance layer for private network operators. This framework forces enterprises to contract with certified SAS administrators, adding recurring operational costs but reducing interference risk. Manufacturing plants in Ohio and Illinois are absorbing these overhead structures to secure guaranteed spectrum blocks for robotics control.
Venue procurement teams are consolidating vendor relationships through managed service contracts that bundle equipment, installation, and ongoing optimization into per-square-foot pricing. Sports arenas in Texas and California are leading this transition, replacing capital-intensive ownership models with operational expenditure structures aligned to event calendars. This reconfiguration transfers technology obsolescence risk from facility owners to infrastructure providers, compressing sales cycles for active equipment vendors willing to assume long-term service commitments.
North America in-Building Wireless Market Segmentation
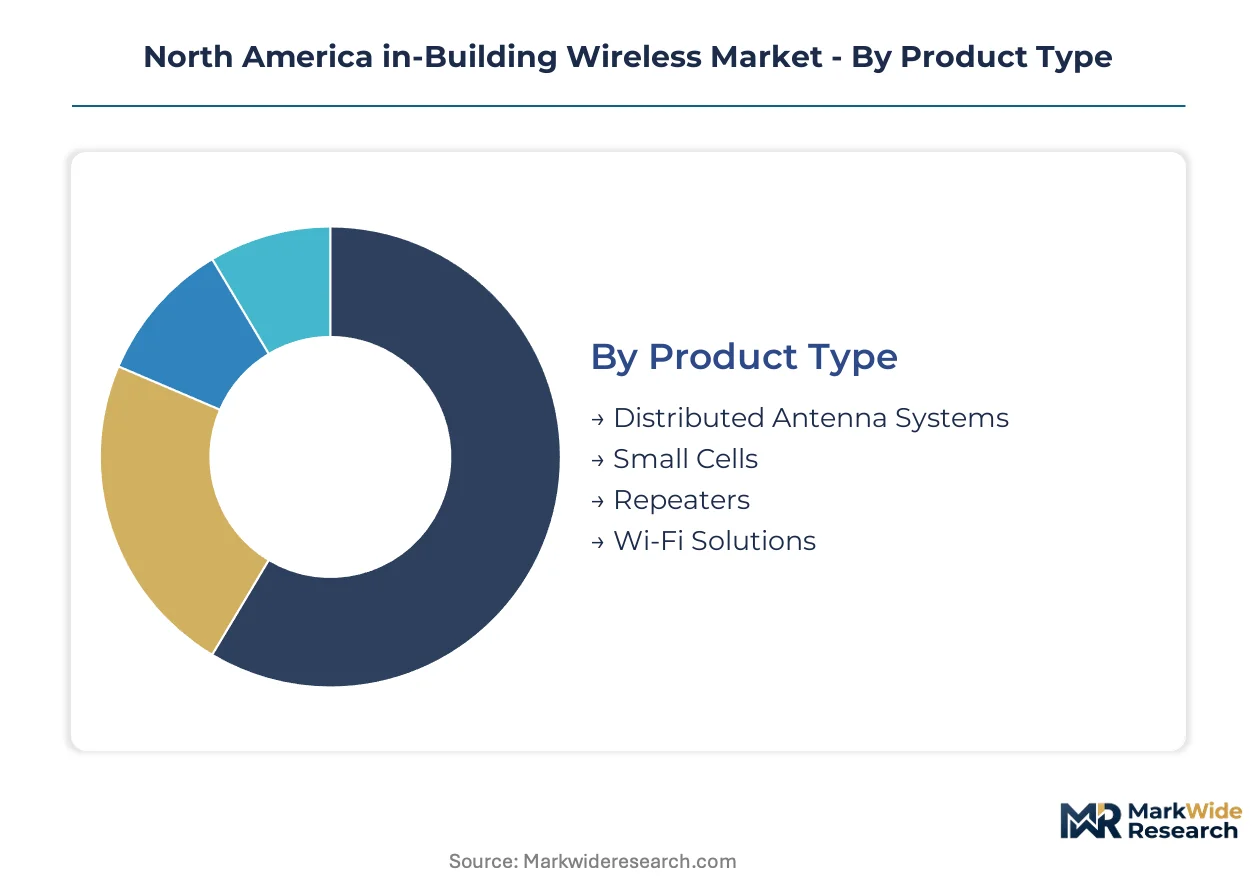
Segmentation in the North America in-Building Wireless Market reveals how procurement patterns diverge between carrier-owned infrastructure and enterprise-managed deployments. Understanding these splits enables vendors to calibrate pricing models and service architectures to specific buyer economics across stadiums, healthcare campuses, and mixed-use developments.
Product Type:
Distributed antenna systems dominate procurement in Texas and California where stadium operators and mixed-use developers specify carrier-grade reliability. Small cells concentrate in Michigan and Tennessee manufacturing corridors where private 5G networks bypass traditional carrier negotiations entirely.
- Distributed Antenna Systems:Passive coaxial infrastructure distributes cellular signals through remote antenna nodes powered from centralized headend equipment. Demand clusters in Dallas-Fort Worth and Los Angeles mixed-use towers where NFPA 1221 public safety mandates require hardened signal distribution. Healthcare facilities in Boston and Philadelphia specify these systems for guaranteed coverage during emergencies.
- Small Cells:Compact base stations with integrated radio and baseband functions operate at sub-1-watt power levels for localized capacity injection. Automotive assembly plants in Michigan deploy these for guaranteed-latency AGV control, while Tennessee electronics manufacturers use them to replace Wi-Fi for robotics coordination.
- Repeaters:Bidirectional amplifiers extend outdoor macro signals into building interiors without fiber backhaul requirements.
- Wi-Fi Solutions:Unlicensed spectrum access points handle data offload in venues where cellular capacity economics prove prohibitive.
Distributed antenna systems command the established base. The steepest expansion runs through small cells.
End User:
Cost tier differentiation separates premium healthcare and government facilities from price-sensitive residential deployments. Commercial buildings absorb the highest per-square-foot infrastructure spend due to multi-carrier interoperability requirements.
- Commercial Buildings:Class A office towers and retail complexes require simultaneous support for Verizon, AT&T, and T-Mobile with guaranteed service-level agreements. Procurement in Texas and California concentrates around neutral-host architectures that amortize costs across multiple carriers.
- Healthcare Facilities:Hospitals and medical centers combine commercial cellular coverage with NFPA 1221 public safety radio mandates. Boston and Philadelphia facilities prioritize active antenna systems with reduced mechanical footprints to preserve HVAC clearance.
- Educational Institutions:University campuses balance coverage density against capital constraints through phased deployment models.
- Residential Complexes:Multi-family housing developments prioritize Wi-Fi solutions over cellular infrastructure due to lower tenant willingness-to-pay.
Healthcare facilities absorb premium pricing for compliance-hardened systems. Commercial buildings generate the highest absolute volume.
Technology:
Application urgency determines technology selection, with guaranteed-latency use cases commanding 5G premiums while general connectivity accepts Wi-Fi 6 economics.
- 5G:New radio interfaces in sub-6 GHz and mmWave bands enable private network slicing for manufacturing automation. Ohio and Illinois plants absorb FCC Part 96 CBRS compliance costs to secure guaranteed spectrum blocks for robotics control.
- Wi-Fi 6:OFDMA and MU-MIMO enhancements improve spectral efficiency in high-density venues. Volume leadership reflects deployment in educational institutions and residential complexes where unlicensed economics dominate.
- LTE:Mature infrastructure supports voice continuity and IoT device backhaul in buildings with legacy DAS investments.
- DAS:Technology-agnostic distribution architecture accommodates multiple radio access technologies through common passive infrastructure.
Wi-Fi 6 leads in deployment count. 5G claims the steepest value expansion.
Deployment Model:
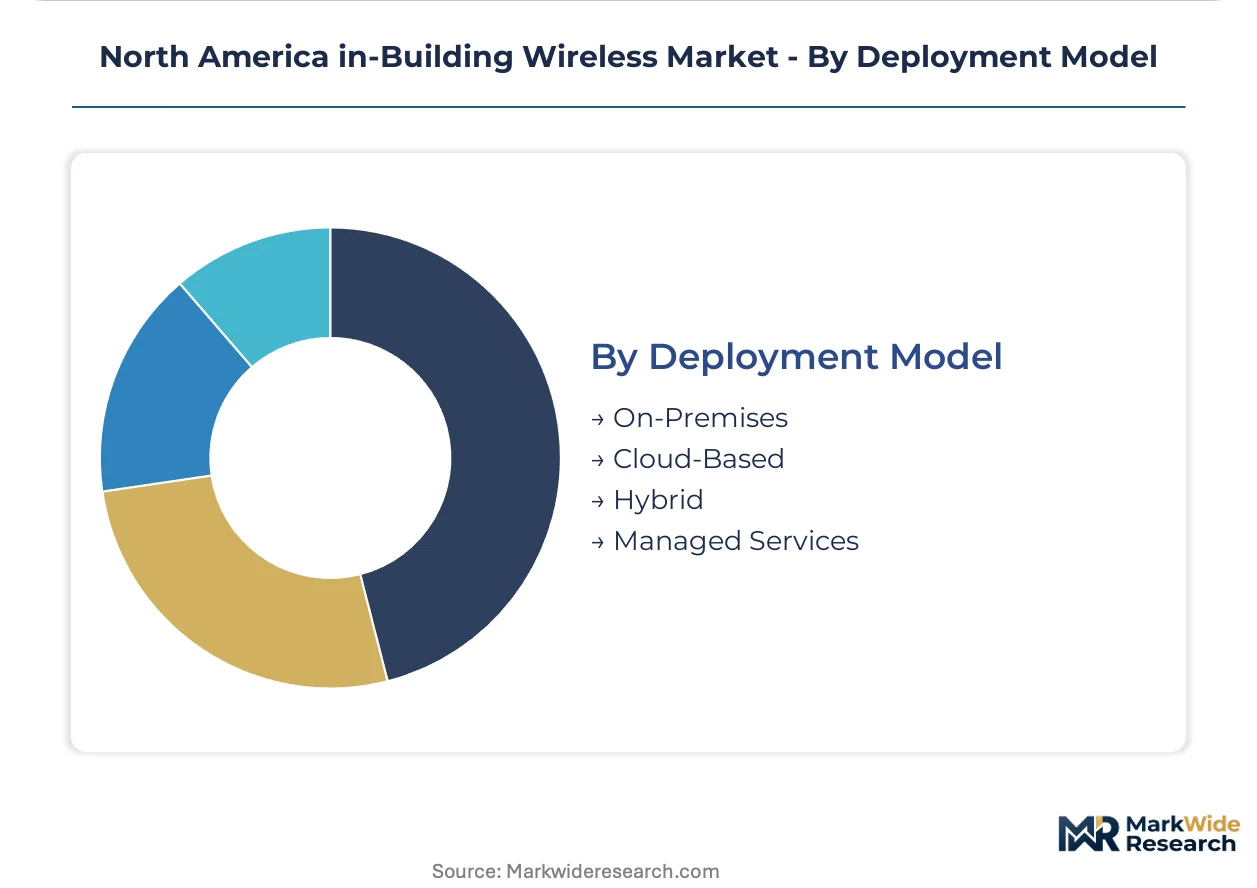
Customer type separates capital-rich facility owners from operators preferring operational expenditure structures aligned to event calendars and occupancy cycles.
- Managed Services:Bundled per-square-foot contracts transfer technology obsolescence risk from venue operators to infrastructure providers. Texas and California sports arenas lead this shift, replacing ownership with service agreements tied to seasonal event schedules.
- Hybrid:Split architectures combine on-premises radio units with cloud-orchestrated baseband processing. Manufacturing plants in Ohio and Illinois favor this model for balancing local latency requirements against centralized management economies.
- On-Premises:Full ownership models persist in government facilities with stringent data sovereignty requirements.
- Cloud-Based:Fully virtualized RAN functions enable rapid carrier onboarding in venues with fluctuating tenant mixes.
Managed services capture the fastest-growing contract structure. Hybrid deployments anchor the transitional middle.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across North America. The United States absorbs the bulk of neutral-host infrastructure investment. Canada prioritizes public safety integration. Mexico concentrates on cost-optimized coverage for industrial corridors.
United States
Stadium operators in Texas and California are consolidating procurement around neutral-host architectures that amortize costs across multiple carriers. The FCC's CBRS framework reallocates 3.5 GHz spectrum for private LTE and 5G networks, enabling enterprises to bypass traditional carrier negotiations. Dallas-Fort Worth and Los Angeles mixed-use towers generate contiguous demand blocks that justify dedicated RF engineering teams.
Canada
Healthcare facilities in Toronto and Vancouver combine commercial cellular coverage with municipal public safety radio mandates. Health Canada regulates device certification through procedures that parallel FCC OET standards but impose additional cold-weather operational testing. Greater Toronto's Class A office towers anchor demand for multi-carrier interoperability systems.
Mexico
Manufacturing plants in Nuevo León and Baja California deploy cost-optimized small cell networks for logistics automation. The country's federal telecommunications regulator governs spectrum allocation with frameworks that prioritize affordable coverage expansion over premium capacity tiers. Tijuana-San Diego cross-border industrial parks create unique dual-jurisdiction deployment complexity.
North America in-Building Wireless Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the North America in-Building Wireless Market. The upper tier controls captive supply of passive components and fiber backhaul footprints that shape deployment economics. The specialist tier concentrates on software-defined architectures and rapid carrier onboarding capabilities. Competitive moves center on managed service contract bundling and strategic partnerships with venue operators seeking operational expenditure structures.
Within the integrated infrastructure tier, CommScope and Crown Castle anchor positions through supply chain control and backhaul dominance respectively. JMA Wireless exemplifies the software-specialist archetype with its focus on virtualized baseband solutions. These three entities represent the strategic poles around which neutral-host procurement patterns are consolidating across Texas and California developments.
| Leading Market Players |
|---|
| CommScope |
| Crown Castle |
| Airspan Networks |
| Corning Incorporated |
| JMA Wireless |
| Nokia |
| Ericsson |
| Cobham Limited |
| Boingo |
| Others |
Value Chain & Pricing Dynamics
Ninety-day lead times for gallium nitride power amplifiers concentrate pricing power among RF component distributors serving Texas stadium operators and California mixed-use developers, compressing margins for system integrators unable to secure long-term offtake agreements with Southeast Asian foundries.
Pricing Analysis
Long-term managed service contracts dominate procurement in sports arenas and healthcare campuses, replacing capital-intensive ownership with per-square-foot operational expenditure structures. Pricing stratifies across premium, standard, and economy tiers based on carrier-grade certification requirements and NFPA 1221 public safety compliance bundling. Cost compression in passive coaxial infrastructure intensifies as freight volatility from Southeast Asia exposes DAS deployments to margin pressure. Residential complexes exhibit highest price sensitivity, while Class A office towers absorb premium pricing for multi-carrier interoperability guarantees.
Supply Chain Analysis
Inventory buffers for remote radio units and software-defined baseband processors rest on semiconductor fabrication concentrated in Taiwan, South Korea, and the United States. Raw material dependencies span gallium nitride substrates, high-purity copper for coaxial cable, and specialized RF filters. Single-source vulnerability in SAS administrator certification for CBRS compliance creates chokepoints for private 5G deployments in Ohio and Illinois manufacturing plants. Distribution runs through neutral-host operators and carrier procurement channels anchored in Dallas-Fort Worth and Los Angeles corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized RF engineering talent pools concentrated in three national labor markets constrain deployment velocity, forcing stakeholders to compete through alternative capability acquisition rather than headcount expansion alone.
For Market Incumbents: Secure captive supply relationships for passive components through backward integration into coaxial cable manufacturing or exclusive distribution agreements with Southeast Asian foundries. Anchor managed service contracts with Texas and California venue operators to lock out emerging software-defined specialists threatening carrier onboarding speed advantages. For New Entrants and Emerging Players: Differentiate on rapid CBRS private network deployment timelines for Michigan and Tennessee automotive assembly plants underserved by incumbent DAS-centric portfolios. Target manufacturing automation segments where guaranteed-latency requirements bypass traditional carrier negotiation complexity. Lead with hybrid cloud-orchestrated baseband solutions that collapse multiple vendor relationships into single-dashboard operations. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-as-a-service play because venue operators across North America are systematically transferring technology obsolescence risk to providers through operational expenditure structures. Acquisition candidates with software-defined RAN capabilities and certified SAS administrator relationships command structural scarcity premiums. Monitor FCC Part 96 rulemaking evolution as the critical inflection signal for private 5G deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Managed Service Contract Consolidation | Bundles equipment, installation, and optimization into per-square-foot pricing for Texas sports arenas. |
| Software-Defined Baseband Convergence | Merges 5G NR and Wi-Fi 6 management planes into single-dashboard operations for venue operators. |
| CBRS Spectrum Access System Certification | Secures FCC Part 96 compliance for private network deployments in Ohio and Illinois manufacturing. |
| Passive Component Supply Integration | Controls deployment costs for DAS infrastructure through captive coaxial cable and power splitter supply. |
| First Responder Broadband Integration | Aligns dual-purpose infrastructure with FirstNet deployment deadlines for emergency personnel coverage. |
Study Parameters
Operator-level perspectives from stadium procurement directors, neutral-host network engineers, healthcare facility IT managers, and FCC regulatory counsel anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through FCC OET equipment certification databases, NFPA 1221 standard documentation, CBRS Priority Access License auction records, and carrier capex disclosure filings. Bottom-up deployment volume estimates triangulated against top-down infrastructure spend projections across the analysis window.
Sensitivity analysis around RF engineering labor availability and gallium nitride component lead times shaped the analytical framework. Segmentation dimensions modeled include product type, end user vertical, technology generation, and deployment model complexity. CAGRs derived from installation volume trajectories and average revenue per square foot across managed service contracts. Industry-specific inputs encompassed stadium event calendar density and manufacturing automation penetration rates.
Material uncertainties — CBRS rulemaking revisions, NFPA standard updates, and semiconductor trade policy shifts — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding carrier coexistence protocol certification timelines and venue operator procurement cycle normalization. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Europe Wireless Microphone Market
Wireless Technologies
Telecom Wireless Data Market
Wireless Technologies
Wireless Telecommunication Services Market
Wireless Technologies
Wi-Fi 7 Market
Wireless Technologies
Wireless Connectivity Market
Wireless Technologies
Public Wi-Fi Market
Wireless Technologies
Global Wireless Data Communication Market
Wireless Technologies
5G Fixed Wireless Access Market
Wireless Technologies
Mobile Hotspot Device Market
Wireless Technologies
Industrial Wireless Broken Signal Solutions Market
Wireless Technologies
Latin America Wireless Mesh Networking Market
Wireless Technologies
Wireless Communication Technologies in Healthcare Market
Wireless Technologies
Outdoor Wi-Fi Market
Wireless Technologies
Industrial Wireless Solution Market
Wireless Technologies
Near Field Communication Market
Wireless Technologies
APAC Small Cell Tower Market