
 Mobile WLAN Access Points Market | 2026-2036
Mobile WLAN Access Points Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile WLAN Access Points Market Foresight
Wireless network engineering talent scarcity is reorganizing vendor competitive dynamics across the mobile WLAN access points landscape. Cisco Systems leverages its certification ecosystem to sustain channel loyalty among enterprise integrators. Aruba Networks anchors its position through in-house silicon development for Wi-Fi 6E performance optimization. Huawei Technologies competes aggressively on manufacturing scale for outdoor AP deployments in emerging infrastructure markets.
Mobile WLAN access points are radio-frequency networking devices that provide wireless local area network connectivity in locations without fixed infrastructure, typically operating across 2.4 GHz, 5 GHz, and 6 GHz spectrum bands with throughput capabilities exceeding 9.6 Gbps in Wi-Fi 6 implementations. These units serve industrial, emergency, and temporary commercial environments where cabled backhaul proves impractical or cost-prohibitive. Indoor APs dominate current revenue pools due to enterprise refresh cycles and office densification requirements, while rugged APs command premium positioning for mining, military, and maritime applications where environmental sealing and shock resistance justify higher unit economics. Wi-Fi 6 technology leads technology transition spending as organizations phase out Wi-Fi 5 inventories, though LTE-integrated hybrid units gain traction in transportation and public safety verticals requiring guaranteed coverage beyond Wi-Fi range.
The FCC governs unlicensed spectrum power limits and emission standards in the United States, directly constraining transmit power and thus coverage radius for outdoor mobile deployments. ETSI enforces harmonized radio equipment standards across European member states, creating a unified testing framework that reduces fragmentation but extends certification timelines for new frequency introductions. IEEE 802.11 standards bodies coordinate technical specifications that vendors must implement to ensure interoperability, with working group decisions on future amendments shaping multi-year R&D roadmaps. Stakeholders must monitor spectrum auction outcomes and standards ratification schedules to align product development cycles with regulatory availability of 6 GHz and future millimeter-wave allocations.
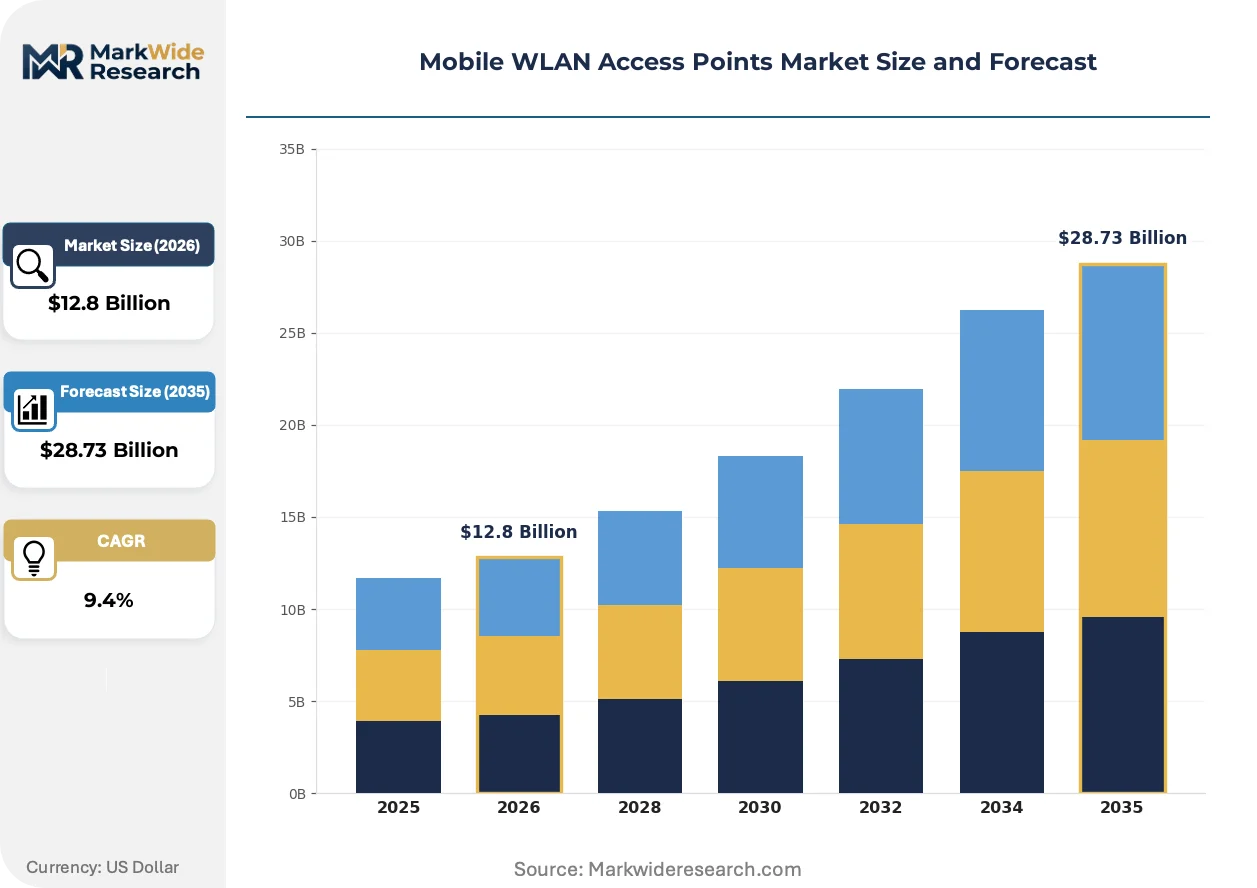
Market Dynamics
Enterprise Wi-Fi 6E upgrade cycles and FCC spectrum reallocation are compressing deployment timelines while fragmenting vendor procurement patterns across healthcare, manufacturing, and transportation verticals.
Growth Catalysts
- Clinical Mobility Mandates:Hospital IT departments in the United States are expanding mobile WLAN footprints to support FDA-regulated connected medical devices and nurse-worn communication badges.
- Smart Factory Initiatives:Germany's Industrie 4.0 framework is accelerating rugged access point procurement for automated production lines requiring deterministic wireless latency.
- 6 GHz Spectrum Liberalization:The FCC's 2020 unlicensed spectrum reallocation is expanding channel availability for high-density enterprise deployments previously constrained by 5 GHz congestion.
Market Restraints
- Silicon Supply Concentration:Advanced Wi-Fi 6E chip fabrication concentrates among a limited set of foundry operators, creating lead time volatility for access point manufacturers.
- Outdoor Power Constraints:FCC Part 15 emission limits cap transmit power for unlicensed outdoor mobile deployments, restricting coverage radius in mining and maritime applications.
- Private 5G Substitution:Enterprises with guaranteed coverage requirements are piloting CBRS-based private cellular networks as alternatives to Wi-Fi in warehouse and logistics environments.
Strategic Opportunities
- Emerging Infrastructure Markets:Brazil's ANATEL spectrum harmonization is opening procurement channels for outdoor rugged APs in agricultural automation and remote resource extraction.
- Wi-Fi 7 Convergence:Multi-link operation technology is enabling simultaneous 2.4 GHz, 5 GHz, and 6 GHz band utilization for ultra-low-latency industrial control applications.
- Managed Service Channels:Network-as-a-service distribution models are displacing capital-heavy equipment purchases among mid-market enterprises lacking in-house wireless engineering talent.
Industry Challenges
- RF Engineering Talent Scarcity:Enterprise IT departments face acute shortages of certified wireless network engineers capable of designing high-density 6 GHz deployments.
- ETSI Certification Timelines:European market entry requires extended testing cycles under harmonized radio equipment standards, delaying product launches relative to FCC jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile WLAN Access Points Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $28.73 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Outdoor APs, Indoor APs, Portable APs, Rugged APs Technology: Wi-Fi 6, Wi-Fi 5, LTE, 5G End User: Event Venues, Educational Institutions, Transportation, Hospitality Application: Public Safety, Emergency Services, Temporary Connectivity, Remote Work |
| Companies Covered | Cisco Systems, Aruba Networks, Ubiquiti Networks, Ruckus Wireless, TP-Link, Netgear, Extreme Networks, Huawei Technologies, Fortinet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile WLAN Access Points Market Shifts & Advancements
Three forces are restructuring competitive positioning: silicon-level performance optimization, spectrum policy fragmentation across regulatory regimes, and procurement model migration toward operational expenditure frameworks.
Wi-Fi 6E chipsets with dedicated 6 GHz radio chains are displacing legacy dual-band architectures in enterprise refresh cycles. Healthcare systems and financial services firms are adopting these units at accelerated pace to support 4K video collaboration and real-time IoT telemetry. This silicon transition is compressing gross margins for vendors lacking in-house semiconductor design capabilities.
The FCC's continued unlicensed spectrum expansion in the United States contrasts with ETSI's cautious harmonization pace across European member states. This regulatory divergence is forcing vendors to maintain parallel SKU lineups with different power profiles and channel plans. Outdoor mobile deployments face the steepest compliance burden as transmit limits vary materially between jurisdictions.
Enterprise buyers are unbundling hardware procurement from managed services, treating wireless infrastructure as a subscription rather than capital asset. Systems integrators and telecom operators are capturing this shift through multi-year service contracts with embedded refresh guarantees. This pattern is most pronounced in Germany and the United States among mid-market manufacturers lacking dedicated network operations staff.
Mobile WLAN Access Points Market Segmentation
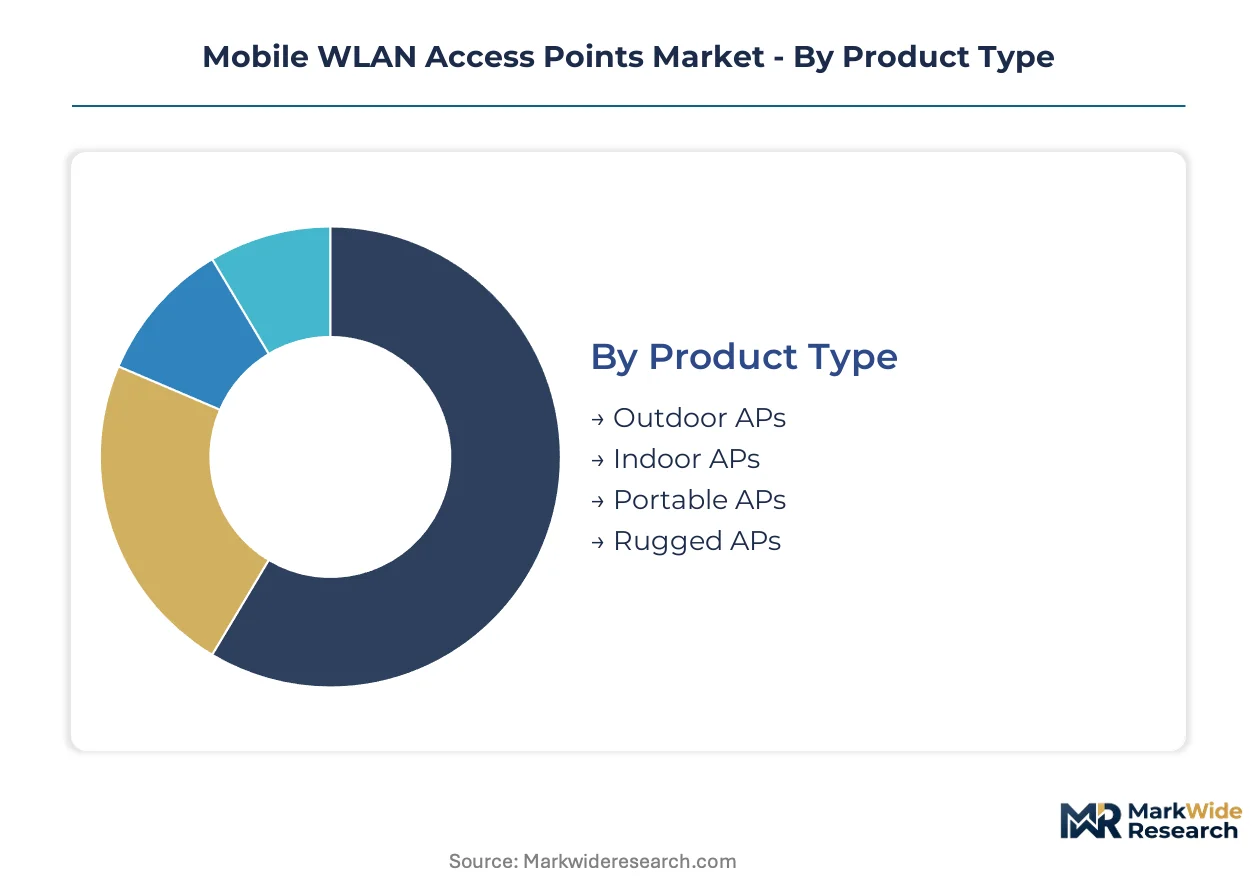
Mobile WLAN access points serve heterogeneous deployment environments where spectrum allocation, environmental sealing requirements, and backhaul constraints fragment procurement patterns across product architectures. Segmentation reveals how regulatory frameworks and use-case durability specifications reshape vendor portfolio priorities.
Product Type:
FCC Part 15 emission limits and ETSI harmonized radio equipment standards impose divergent power and sealing specifications on form factor design, creating parallel certification tracks for indoor versus outdoor units.
- Outdoor APs:Weather-sealed enclosures with IP67 ratings and directional antenna arrays withstand precipitation and temperature extremes. Mining operations in Australia and agricultural automation in Brazil concentrate procurement, though FCC transmit power caps restrict coverage radius relative to European deployments.
- Indoor APs:Plenum-rated plastic housings with integrated omnidirectional antennas dominate enterprise refresh cycles. Hospital systems in the United States and financial services firms in Germany drive density-focused 6 GHz deployments for high-bandwidth clinical and trading floor applications.
- Portable APs:Battery-powered units with cellular backhaul serve disaster response and field journalism in regions lacking fixed infrastructure.
- Rugged APs:MIL-STD-810G tested housings absorb shock and vibration for military convoys and maritime vessels.
Established volume favors Indoor APs; emerging adoption favors Rugged APs.
Technology:
Silicon foundry capacity constraints and IEEE 802.11 standards ratification schedules compress technology transition windows, forcing buyers to weigh backward compatibility against spectral efficiency gains.
- Wi-Fi 6:OFDMA and 1024-QAM modulation deliver 9.6 Gbps theoretical throughput with improved battery efficiency for IoT endpoints. Enterprise IT departments in the United States prioritize these units to support FDA-regulated connected medical devices and 4K video collaboration platforms.
- Wi-Fi 5:256-QAM architectures with SU-MIMO dominate legacy installed bases in cost-constrained educational institutions. Districts in India defer replacement cycles amid budget pressures, extending revenue tail for maintenance-dependent vendors.
- LTE:Licensed spectrum integration guarantees coverage beyond Wi-Fi range for public safety agencies.
- 5G:Millimeter-wave backhaul options serve stadium and arena deployments requiring ultra-reliable low-latency connectivity.
Wi-Fi 6 captures the steepest expansion trajectory; Wi-Fi 5 retains residual maintenance value.
End User:
Procurement authority fragmentation—central IT versus facilities management versus event operations—creates pricing dispersion across verticals with diverging total cost of ownership models.
- Event Venues:Temporary high-density configurations with rapid deployment tooling serve music festivals and sporting events. Operators in Germany and the United States favor rental-based procurement to avoid capital commitment for seasonal demand spikes.
- Educational Institutions:Campus-wide coverage with student device management prioritizes affordability over premium features. K-12 districts in India and community colleges in Brazil concentrate demand for mid-tier Wi-Fi 6 units with cloud-managed control planes.
- Transportation:Rolling stock and port terminals require handoff optimization for mobile clients.
- Hospitality:Guest-facing deployments with captive portal authentication prioritize aesthetic concealment and simple management.
Educational Institutions anchor current volume; Event Venues show the most volatile growth pattern.
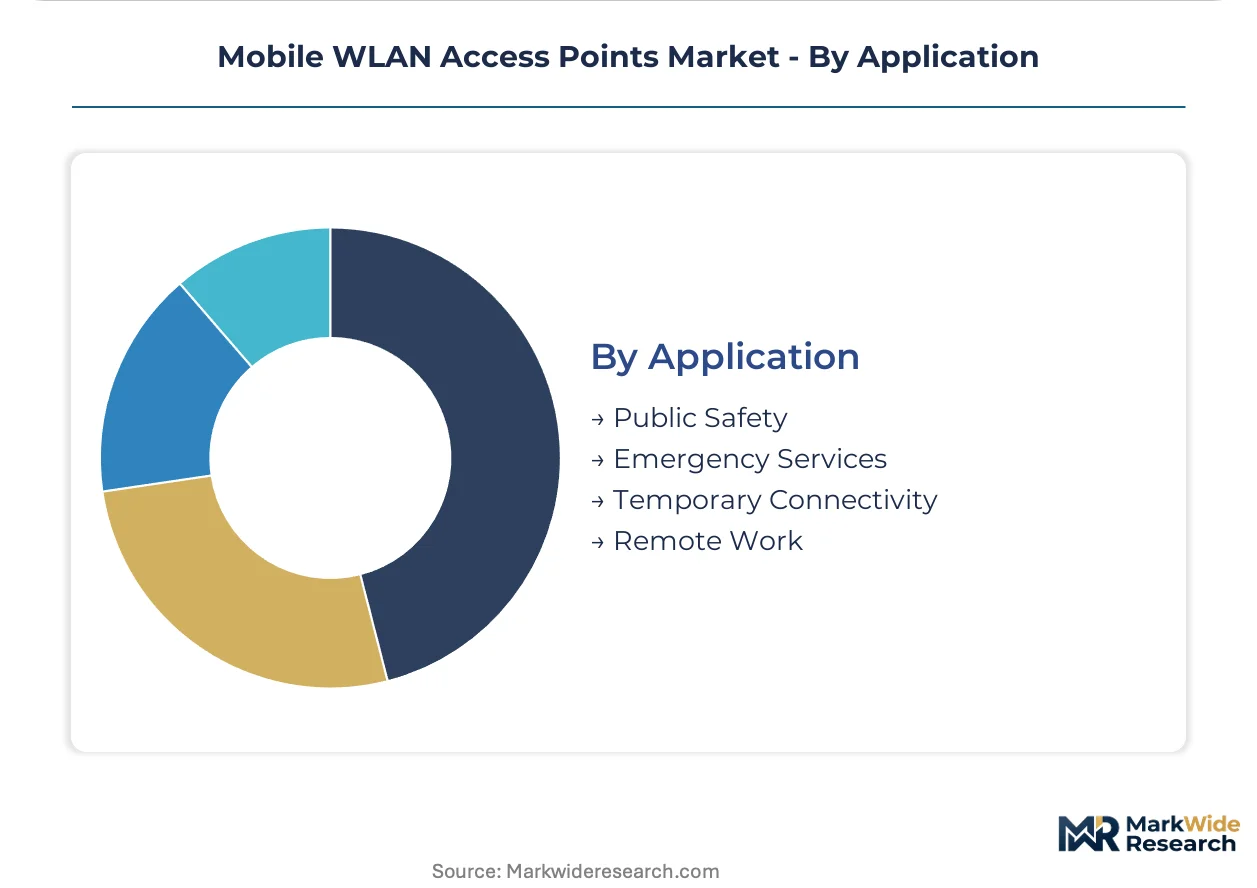
Application:
Service level requirements—ranging from best-effort connectivity to mission-critical availability—determine whether Wi-Fi suffices or private cellular alternatives displace procurement.
- Public Safety:Encrypted, priority-tagged traffic with mesh failover capabilities serves police and fire departments. Agencies in the United States pilot LTE-integrated hybrid units to ensure coverage beyond Wi-Fi range during infrastructure failures.
- Emergency Services:Rapid-deploy kits with satellite backhaul support disaster response in hurricane-prone regions of the United States and earthquake zones in Japan. Procurement concentrates in federal and prefectural preparedness budgets.
- Temporary Connectivity:Pop-up networks for construction sites and remote film production emphasize rental flexibility over ownership.
- Remote Work:Home office extensions and mobile worker kits serve distributed enterprise workforces.
Emergency Services command premium pricing; Temporary Connectivity expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys mobile WLAN access points primarily for deterministic industrial automation, while the United States concentrates procurement on clinical mobility and emergency response scenarios. This consumption-mix differential shapes divergent product specifications across major markets.
United States
Hospital IT departments and federal emergency agencies drive mobile WLAN procurement for FDA-regulated connected medical devices and rapid-deploy disaster kits. The FCC's 2020 unlicensed spectrum reallocation expanded 6 GHz channel availability for high-density enterprise deployments. Texas and California medical centers anchor clinical mobility spending, while Gulf Coast states concentrate federal preparedness budgets for hurricane response infrastructure.
Germany
Industrie 4.0 smart factory initiatives accelerate rugged access point procurement for automated production lines requiring deterministic wireless latency. ETSI harmonized radio equipment standards enforce unified testing frameworks that extend certification timelines relative to FCC jurisdictions. Bavaria's automotive manufacturing clusters and North Rhine-Westphalia's chemical processing facilities dominate industrial automation deployments.
China
MIIT spectrum policies and GB standards govern unlicensed equipment certification for mining operations and agricultural automation in remote provinces. The country's national telecommunications regulator coordinates technical specifications with IEEE 802.11 standards bodies to ensure interoperability. Yangtze River Delta manufacturing hubs and Western China resource extraction zones concentrate outdoor rugged AP procurement.
Brazil
ANATEL spectrum harmonization opens procurement channels for outdoor rugged APs in agricultural automation and remote resource extraction. The national telecommunications agency aligns regional testing protocols with international standards to reduce import barriers. São Paulo industrial corridors and Minas Gerais mining districts drive demand for weather-sealed units with IP67 ratings.
Japan
METI industrial policy and JIS standards shape procurement for maritime vessels and earthquake-zone emergency response infrastructure. The Ministry of Economy, Trade and Industry coordinates spectrum allocation with private sector R&D roadmaps. Kanto region manufacturing centers and Kyushu port terminals concentrate rolling stock and terminal connectivity deployments.
Mobile WLAN Access Points Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in mobile WLAN access points. Cisco Systems and Huawei Technologies occupy the integrated leadership position through captive silicon development and manufacturing scale. Specialist vendors concentrate on vertical-specific durability certifications and managed service distribution models. Strategic moves center on Wi-Fi 6E portfolio transitions and network-as-a-service channel partnerships.
Among North American networking vendors, Cisco Systems, Aruba Networks, and Ruckus Wireless exemplify divergent competitive archetypes. Cisco represents the certification-ecosystem model sustaining channel loyalty among enterprise integrators. Aruba Networks anchors the in-house silicon optimization tier for Wi-Fi 6E performance differentiation. Ruckus Wireless occupies a position within the density-focused specialist segment serving high-client-count venues.
| Leading Market Players |
|---|
| Cisco Systems |
| Aruba Networks |
| Ubiquiti Networks |
| Ruckus Wireless |
| TP-Link |
| Netgear |
| Extreme Networks |
| Huawei Technologies |
| Fortinet |
| Others |
Supply & Pricing Matrix
Foundry-scale economies in advanced Wi-Fi 6E semiconductor fabrication concentrate supply leverage among a limited set of operators, compressing price floors for access point manufacturers while elevating margins for silicon-integrated vendors. This concentration pattern cascades through procurement negotiations, with enterprise buyers consolidating volume commitments to extract preferential terms from distribution channels.
Pricing Analysis
Long-term offtake agreements dominate enterprise procurement, though spot purchasing persists among event venue operators with seasonal demand spikes. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—FCC Part 15 and ETSI harmonized standards tiers command 15-25% premiums over uncertified alternatives. Cost compression in mid-tier Wi-Fi 6 units is intensifying because silicon foundry capacity constraints extend lead times and force premium payments for allocation priority. Educational institutions exhibit highest price sensitivity, deferring refresh cycles amid budget pressures, while healthcare systems prioritize deterministic latency guarantees over unit cost.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for Wi-Fi 6E chipsets, with Malaysia and Mexico concentrating final assembly and testing operations. Advanced node silicon, RF front-end modules, and weather-sealed enclosure polymers constitute critical input dependencies. Single-source vulnerability concentrates in 6 GHz radio chain components, where Qualcomm and Broadcom captive designs limit second-sourcing options. Distribution runs through systems integrators and telecom operators capturing network-as-a-service transitions, displacing direct OEM relationships among mid-market enterprises.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated healthcare systems and manufacturing conglomerates with multi-site deployment authority, fragmenting vendor pricing power across heterogeneous procurement committees. This consolidation pattern favors vendors with certification ecosystem depth and managed service packaging capabilities.
For Market Incumbents: Secure captive silicon supply through foundry partnership extensions or in-house design investments to defend margin position against Qualcomm-dependent competitors. Private 5G substitution threats in warehouse and logistics verticals demand LTE-integrated hybrid portfolio expansion. Channel control through certification program loyalty sustains enterprise integrator relationships against Aruba's silicon-optimized positioning. For New Entrants and Emerging Players: Lead with ruggedized outdoor AP specialization for Brazil's agricultural automation and Australia's mining corridors, where IP67 sealing and shock resistance command premium positioning absent from Cisco's indoor-dominant portfolio. Managed service distribution partnerships with regional telecom operators offer the most penetrable channel architecture, bypassing capital-intensive direct sales buildout. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated specialists with in-house semiconductor design capabilities and ETSI pre-certification assets. Long-term viability across the 5-10 year window hinges on Wi-Fi 7 multi-link operation readiness and 6 GHz spectrum policy alignment. The signal to monitor is FCC millimeter-wave allocation proceedings, which would obsolete current 6 GHz-heavy R&D roadmaps if accelerated.| Strategic Initiative | Industry Significance |
|---|---|
| Wi-Fi 6E Portfolio Transition | Silicon-integrated vendors capture healthcare refresh cycles requiring FDA-regulated device support. |
| Managed Service Channel Partnership | Telecom operators displace direct OEM sales among mid-market manufacturers lacking wireless engineering staff. |
| ETSI Pre-Certification Investment | Harmonized radio equipment testing assets accelerate European market entry relative to FCC-first competitors. |
| Rugged AP Vertical Specialization | IP67-rated units command premium economics in German Industrie 4.0 and Brazilian agricultural automation. |
| LTE-Integrated Hybrid Development | Public safety agencies pilot guaranteed-coverage alternatives to pure Wi-Fi in transportation corridors. |
Research Methodology
Desk research of IEEE 802.11 standards documentation, FCC spectrum allocation proceedings, and ETSI harmonized radio equipment specifications preceded structured interviews with enterprise wireless network engineers, hospital IT procurement directors, manufacturing automation specialists, and systems integrator channel managers. Secondary validation drew from vendor SEC filings, hyperscaler capex disclosures, and customs trade data for networking equipment. Bottom-up unit shipment estimates triangulated against top-down enterprise IT spending allocations across healthcare, manufacturing, and transportation verticals.
Variance decomposition across product type, technology generation, end-user vertical, and geographic regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate reconciliation against macroeconomic infrastructure investment indices. Modeled inputs included FCC 6 GHz channel availability trajectories, ETSI certification timeline assumptions, and foundry capacity utilization projections for advanced node Wi-Fi chipsets.
The analysis sits within stated boundaries; outcomes outside continued unlicensed spectrum liberalization or sustained semiconductor supply concentration would require recalibration. Forecasts reflect documented assumptions regarding enterprise refresh cycle timing and regulatory harmonization pace. Specific risks that could revise projections include accelerated private 5G substitution in logistics environments and abrupt foundry capacity reallocations toward automotive or AI chip demand. Recalibration cycles align with material shifts in spectrum policy proceedings and IEEE standards ratification schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
APAC Small Cell Tower Market
Wireless Technologies
France Fixed Wireless Access (FWA) Market
Wireless Technologies
Distributed Antenna System Market
Wireless Technologies
Enterprise WLAN Market
Wireless Technologies
5G Technology ROI Market
Wireless Technologies
North America Wireless Microphone Market
Wireless Technologies
Global Massive MIMO Market
Wireless Technologies
Wi-Fi Booster Market
Wireless Technologies
Cellular Repeater Market
Wireless Technologies
LTE and 5G Market
Wireless Technologies
Multefire Market
Wireless Technologies
5G Fixed Wireless Access Market
Wireless Technologies
North America in-Building Wireless Market
Wireless Technologies
Global Wireless Data Radio Modem Market
Wireless Technologies
Outdoor Wi-Fi Market
Wireless Technologies
Near Field Communication Market