
 Industrial Hand Gloves Market | 2026-2036
Industrial Hand Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Hand Gloves Market Outlook
Malaysian nitrile glove producers is recalibrating capacity allocation after pandemic-era expansion left sustained overhang in industrial grades. Ansell leverages its vertically integrated manufacturing footprint across Thailand and Sri Lanka to sustain cost leadership in chemical-resistant lines. Honeywell competes through advanced fiber technology in cut-resistant segments, while Hartalega Holdings Berhad anchors volume supply to North American distributors through automated production lines.
Industrial hand gloves are personal protective equipment engineered from nitrile, latex, leather, or engineered fibers to shield workers from mechanical, thermal, and chemical hazards during operational tasks. Manufacturing specifications include ANSI cut-level ratings, EN 388 mechanical resistance scores, and thickness tolerances measured in mils for chemical permeation resistance. Disposable nitrile gloves dominate procurement volumes in food processing and chemical handling applications where contamination control is paramount. Reusable leather and engineered-fiber variants command margin pools in construction and oil & gas end uses where durability requirements justify higher unit costs.
The U.S. Occupational Safety and Health Administration mandates hazard assessment protocols that directly determine glove selection criteria across manufacturing facilities. The European Union's PPE Regulation and CE marking requirements create compliance barriers that filter non-certified suppliers from regulated supply chains. ISO 21420 and EN 388 testing standards further stratify product performance tiers, compelling manufacturers to invest in certified laboratory infrastructure. Stakeholders must monitor evolving state-level enforcement patterns and material substitution dynamics as bio-based alternatives challenge petroleum-derived nitrile economics.
Market Dynamics
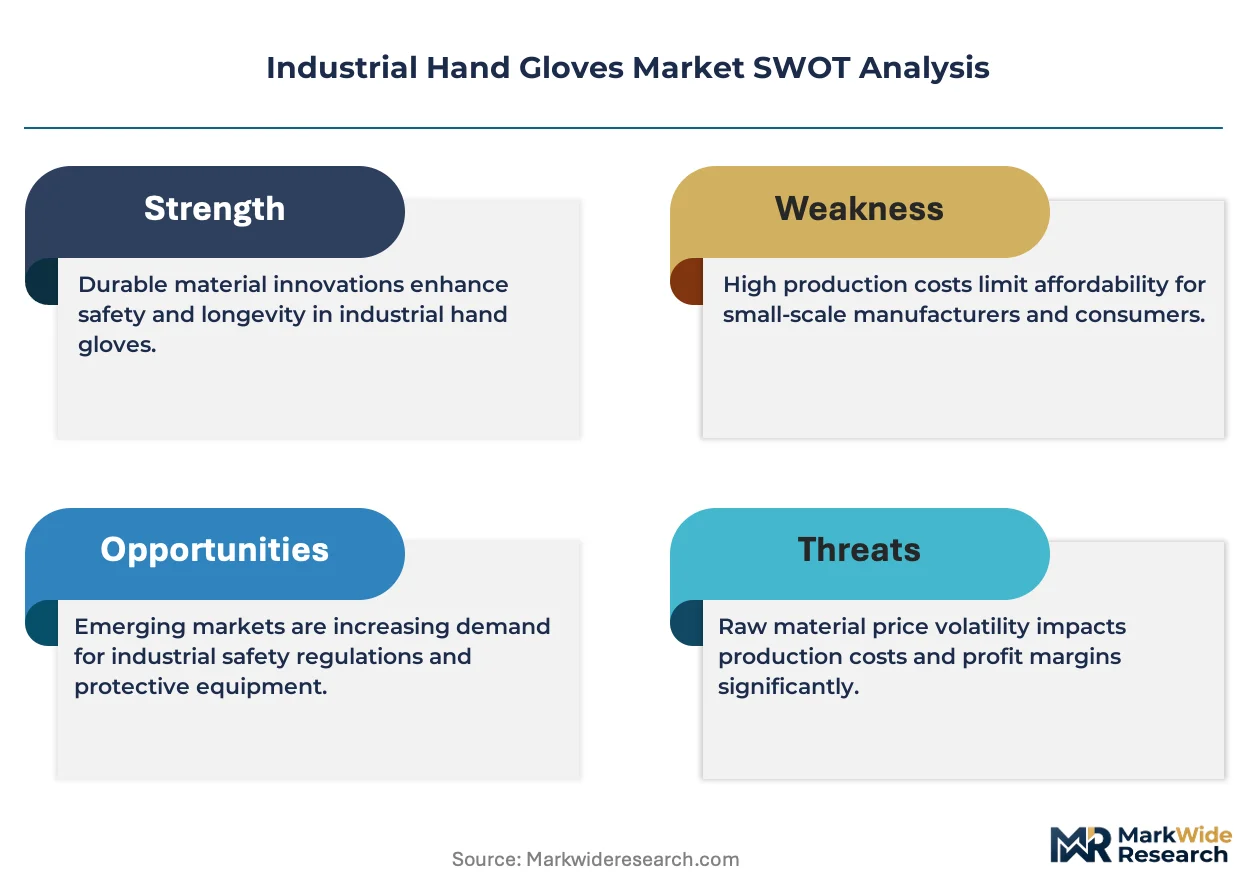
Malaysian nitrile overcapacity from pandemic-era expansion continues compressing margins for industrial-grade suppliers while EU PPE Regulation enforcement filters uncertified competitors from regulated procurement channels.
Growth Catalysts
- Chemical handling mandates:OSHA hazard assessment protocols in U.S. manufacturing plants mandate glove selection criteria that expand procurement volumes for chemical-resistant nitrile variants in process industries.
- China coastal enforcement:Intensified industrial safety inspections across Guangdong and Zhejiang manufacturing zones are accelerating replacement rates for non-compliant hand protection equipment.
- EN 388 certification tiers:Mechanical resistance testing standards stratify product performance, compelling facilities to upgrade from basic cotton to cut-rated engineered fiber gloves in metal fabrication.
Market Restraints
- Butadiene price volatility:Nitrile rubber feedstock costs fluctuate with crude oil indices, squeezing margin pools for disposable glove producers lacking backward integration into polymer supply.
- Thai-Sri Lankan supply concentration:Vertically integrated manufacturing clusters in Southeast Asia create geographic risk exposure for buyers dependent on single-source chemical-resistant lines.
- Leather substitution ceiling:Natural hide durability advantages in oil and gas applications limit synthetic fiber penetration despite higher unit costs for animal-derived materials.
Strategic Opportunities
- India manufacturing scale-up:Production-Linked Incentive schemes for textiles and technical fibers create white space for domestic cut-resistant glove capacity serving metalworking hubs in Pune and Chennai.
- Bio-based polymer convergence:Fermentation-derived nitrile alternatives from agricultural feedstocks intersect with EU Green Deal procurement preferences to open premium positioning against petroleum-derived competitors.
- Direct distributor disintermediation:Automated production lines enable Malaysian producers to bypass North American distribution layers and capture margin through e-commerce channels serving mid-sized industrial buyers.
Industry Challenges
- ANSI cut-level testing backlog:Certified laboratory infrastructure shortages delay new product qualification timelines for engineered fiber variants targeting high-performance segments.
- Legacy ERP integration friction:Automated glove production systems require reconfiguration of existing inventory management platforms at contract manufacturing facilities.
- Multi-standard compliance complexity:Simultaneous EN 388, ISO 21420, and OSHA alignment demands specialized regulatory affairs staffing that smaller tier-two producers struggle to retain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Hand Gloves Market |
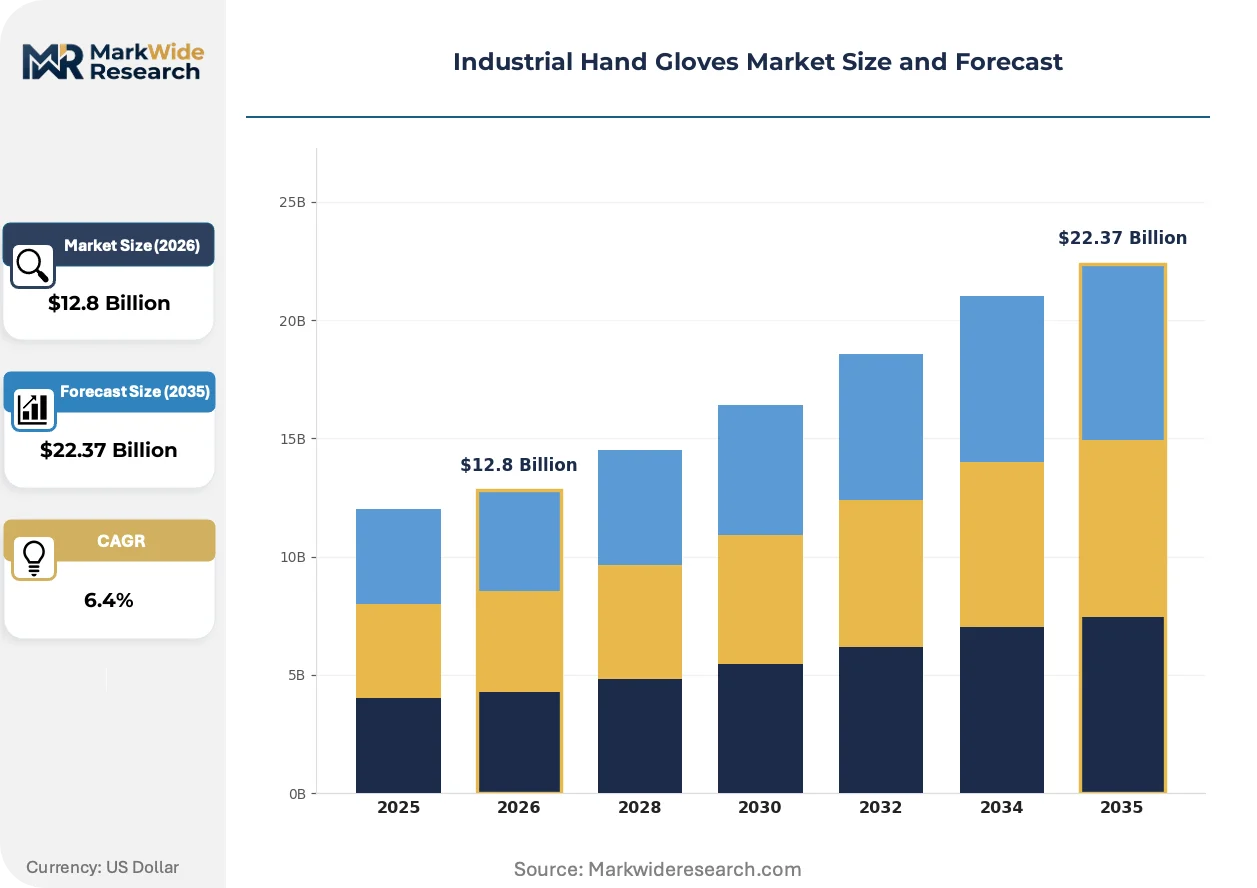
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Cut-Resistant, Heat-Resistant Material: Latex, Nitrile, PVC, Leather End User: Manufacturing, Construction, Oil & Gas, Food Processing Application: Chemical Handling, Electrical Work, Construction Sites, Maintenance Tasks |
| Companies Covered | Ansell, Honeywell, 3M, Top Glove Corporation, DuPont, Showa Group, MCR Safety, Hartalega Holdings Berhad, Superior Glove, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Hand Gloves Market Strategic Shifts
Material science advances and enforcement intensification are compressing product lifecycles while reshaping how performance specifications translate into procurement decisions across industrial end uses.
Smart sensor-embedded glove technology is modularizing workplace safety monitoring by integrating force detection and chemical exposure alerts into nitrile and engineered fiber shells. Automotive assembly plants in Germany and electronics manufacturers in South Korea are piloting these systems for real-time ergonomic hazard tracking. The technology is modularizing traditional PPE procurement by bundling hardware, data analytics, and compliance documentation into single-source contracts that displace commodity purchasing.
EU PPE Regulation 2016/425 enforcement is tightening CE marking verification through notified body audits that reject self-certified imports from non-EU manufacturing zones. Industrial buyers in France and Italy now demand third-party test reports for chemical permeation resistance before contract award. Cut-resistant segments face the steepest compliance burden as EN 388:2016+A1:2018 updates require blade cut testing that obsolete laboratory equipment cannot perform.
Buyer consolidation among North American industrial distributors is compressing supplier counts and extending payment terms for glove manufacturers. Three national distributors now control the majority of stocking decisions for manufacturing facilities with over 500 employees. This concentration is most visible in chemical handling applications where volume commitments determine allocation of limited nitrile supply from Thai producers during feedstock shortage periods.
Industrial Hand Gloves Market Segmentation
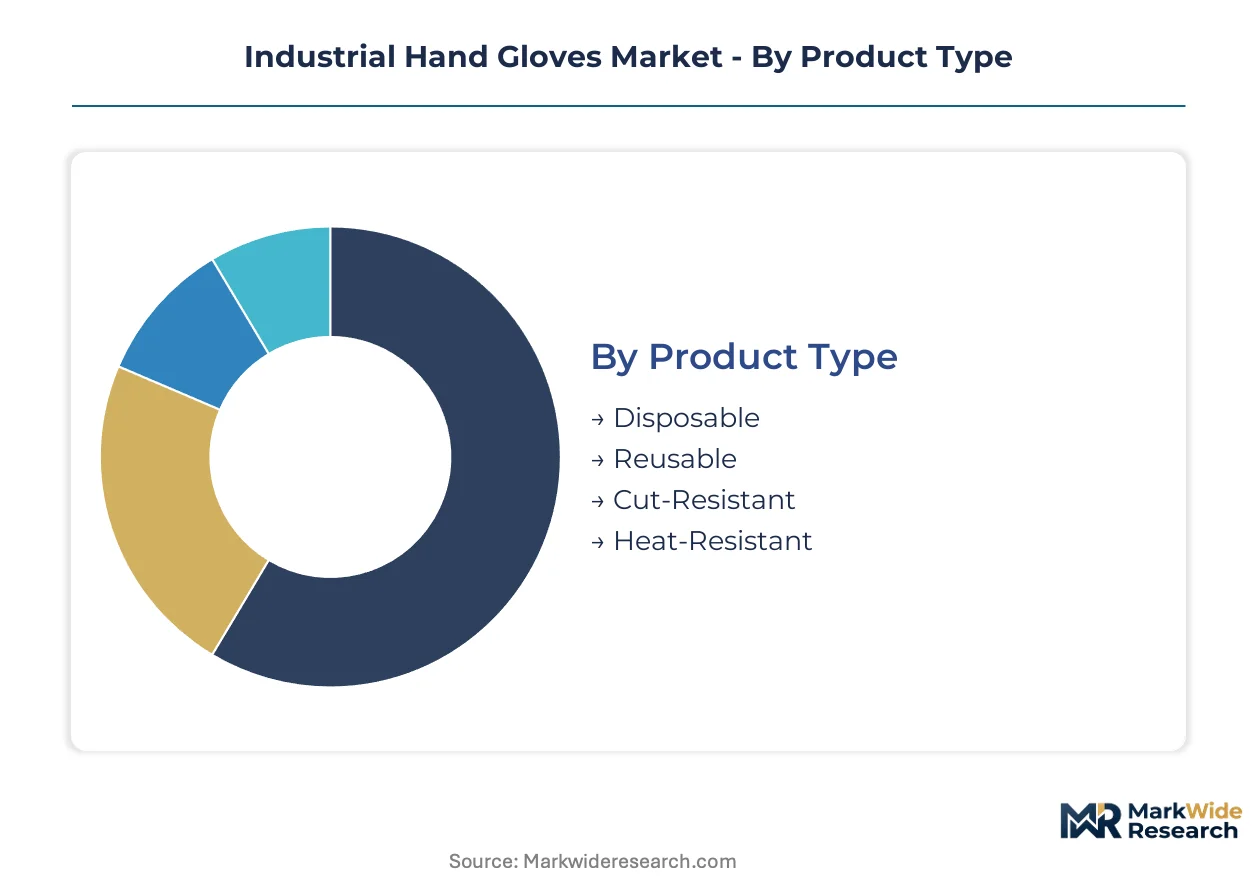
Industrial hand glove procurement splits across four intersecting dimensions that determine specification requirements, compliance burdens, and margin structures. Buyers navigate these categories simultaneously when qualifying suppliers for multi-hazard manufacturing environments.
Product Type:
Supply concentration in Thai and Malaysian production clusters shapes availability and lead times across disposable and reusable categories differently.
- Disposable:Nitrile formulations dominate chemical handling and food processing applications where single-use protocols prevent cross-contamination. Malaysian overcapacity from pandemic-era expansion continues compressing margins for industrial-grade suppliers serving North American distributors. Demand concentrates in pharmaceutical manufacturing and electronics assembly where particle control mandates frequent glove changes.
- Reusable:Engineered fiber and leather constructions target durability requirements in construction and oil & gas end uses where unit economics favor extended service life over disposability. Ansell and Honeywell anchor supply through vertically integrated manufacturing footprints across Thailand and Sri Lanka. Procurement volumes track capital expenditure cycles in heavy industry rather than operational consumables budgets.
- Cut-Resistant:ANSI-rated engineered fiber variants address mechanical hazards in metal fabrication and glass handling operations.
- Heat-Resistant:Aramid and leather composites protect workers in foundry, welding, and furnace maintenance applications.
Today's leader: Disposable nitrile. Tomorrow's challenger: Cut-resistant engineered fiber.
Material:
Raw material cost tiers stratify competitive positioning, with petroleum-derived synthetics facing pressure from bio-based alternatives and natural hide supply constraints.
- Nitrile:Acrylonitrile-butadiene rubber formulations deliver chemical permeation resistance superior to latex in solvent and oil exposure scenarios. Butadiene price volatility tied to crude oil indices squeezes margin pools for producers lacking backward integration into polymer supply. EN 388 and ANSI cut-level certification requirements favor nitrile blends in multi-hazard specifications.
- Latex:Natural rubber maintains cost advantages in general-purpose applications where protein allergen concerns are manageable. Malaysian and Indonesian plantation supply chains face sustainability scrutiny under EU Green Deal procurement preferences.
- PVC:Polyvinyl chloride compounds serve budget-conscious chemical handling applications with lower mechanical performance requirements.
- Leather:Natural hide durability advantages in oil and gas applications limit synthetic fiber penetration despite higher unit costs and batch-to-batch variability.
Petroleum-derived nitrile commands current volume. Fermentation-derived alternatives are climbing the fastest as EU procurement shifts toward bio-based feedstocks.
End User:
Customer concentration among large manufacturing facilities creates divergent procurement patterns across volume-driven and specification-intensive segments.
- Manufacturing:Automotive, electronics, and machinery producers drive standardized nitrile consumption through MRO procurement contracts. OSHA hazard assessment protocols mandate glove selection criteria that expand procurement volumes for chemical-resistant variants in process industries. Three national distributors now control majority stocking decisions for facilities with over 500 employees.
- Construction:Project-based purchasing and fragmented contractor bases complicate demand forecasting for reusable leather and engineered fiber lines.
- Oil & Gas:Exploration and production operations prioritize cut and abrasion resistance in upstream environments.
- Food Processing:FDA compliance and HACCP protocols mandate disposable nitrile for contamination control in protein and dairy handling.
Manufacturing anchors procurement volume. Food processing represents the steepest expansion trajectory as safety enforcement intensifies across processing facilities.
Application:
Task-specific hazard profiles determine certification requirements and replacement rates across operational environments.
- Chemical Handling:Permeation testing against solvent, acid, and caustic exposure drives specification complexity in process industries. EU PPE Regulation enforcement tightens CE marking verification through notified body audits that reject self-certified imports.
- Electrical Work:Voltage-rated insulating gloves face mandatory periodic testing protocols that create recurring service revenue streams.
- Construction Sites:Multi-hazard exposure combines mechanical, thermal, and chemical risks in single procurement decisions.
- Maintenance Tasks:General-purpose requirements favor cost-optimized specifications over performance-rated alternatives.
Chemical handling dominates specification intensity. Electrical work offers the most predictable replacement cycle visibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing cost differentials between compliance regimes are redirecting procurement flows toward jurisdictions where certification overhead remains lower. Thai and Malaysian producers exploit this arbitrage to serve buyers facing stringent EU and US testing mandates.
United States
OSHA enforcement intensification across Midwest manufacturing corridors is accelerating glove replacement cycles in metal fabrication plants. The Department of Labor's National Emphasis Program on amputations mandates cut-resistant protection for machinery operators. Detroit automotive suppliers and Houston petrochemical clusters dominate procurement volume for chemical-resistant nitrile variants.
Germany
Automotive assembly automation is expanding demand for precision-fit engineered fiber gloves in Stuttgart and Wolfsburg production complexes. CE marking verification under EU PPE Regulation 2016/425 filters non-compliant imports from Asian suppliers. Bavarian machinery producers anchor specification-intensive procurement for multi-hazard protection systems.
China
Guangdong and Zhejiang provincial safety bureaus are conducting unannounced inspections that confiscate non-certified hand protection from factory floors. The Ministry of Emergency Management's dual carbon goals are pressuring petroleum-derived nitrile suppliers toward bio-based alternatives. Suzhou electronics manufacturers represent the fastest-growing demand segment for disposable cleanroom gloves.
India
Production-Linked Incentive schemes for technical textiles are attracting cut-resistant glove capacity to Pune and Chennai metalworking hubs. The Bureau of Indian Standards is harmonizing domestic testing protocols with EN 388 mechanical resistance benchmarks. Gujarat chemical processing zones are expanding procurement for solvent-resistant nitrile blends as state pollution control boards tighten worker exposure limits.
Thailand
Vertically integrated manufacturing clusters in Rayong and Chonburi provinces supply chemical-resistant lines to buyers seeking alternatives to Malaysian overcapacity. The Thailand Board of Investment offers tax incentives for PPE export facilities serving EU and North American distributors. Bangkok-based logistics networks enable direct e-commerce fulfillment to mid-sized industrial buyers in Australia and Japan.
Industrial Hand Gloves Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue bio-based material differentiation and smart-sensor integration. The market structures around three tiers: multinational specialists with captive polymer supply, regional volume fabricators serving distributor networks, and niche technology developers targeting high-performance segments. Consolidation pressure concentrates among disposable nitrile suppliers facing margin compression from Malaysian overcapacity. Strategic moves center on backward integration into butadiene supply and direct-to-buyer e-commerce channel development.
Among vertically integrated specialists, Ansell and Honeywell exemplify divergent positioning archetypes. Ansell anchors chemical-resistant supply through manufacturing footprints spanning Thailand and Sri Lanka. Honeywell occupies the engineered fiber tier where cut-resistant technology commands specification premiums. Hartalega Holdings Berhad represents the volume-driven model, leveraging automated production lines to serve North American distributor consolidation. These three patterns illustrate how competitive advantage derives from supply chain configuration rather than product differentiation alone.
| Leading Market Players |
|---|
| Ansell |
| Honeywell |
| 3M |
| Top Glove Corporation |
| DuPont |
| Showa Group |
| MCR Safety |
| Hartalega Holdings Berhad |
| Superior Glove |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal procurement preferences gate qualified supply and premium-tier pricing access by filtering petroleum-derived nitrile from public tenders while rewarding fermentation-based alternatives with margin premiums. Buyers seeking CE-marked chemical-resistant lines face tiered qualification costs that stratify supplier access across European and North American distributor networks.
Pricing Analysis
Distributor margin layers absorb 15-25 points between Thai manufacturing clusters and end-user procurement desks in North America and Europe. Three-tier pricing structure across premium, standard, and economy levels separates EN 388-certified engineered fiber gloves from basic cotton work gloves and uncertified imports. Price differentiation centers on ANSI cut-level ratings and chemical permeation test documentation. Cost compression in industrial-grade disposable nitrile is intensifying because Malaysian overcapacity from pandemic-era expansion continues to depress spot pricing. Mid-sized manufacturing facilities with 100-500 employees exhibit highest price sensitivity, while oil and gas operators prioritize specification compliance over unit economics.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles anchor hub-and-spoke patterns that consolidate Thai and Malaysian production into channel-ready inventory. Manufacturing concentrates in Thailand, Malaysia, and Sri Lanka, with Rayong and Chonburi provinces hosting vertically integrated chemical-resistant lines. Raw material inputs draw from butadiene feedstocks tied to crude oil indices, acrylonitrile monomer, and natural rubber latex from Indonesian plantations. Single-source vulnerability runs through concentrated nitrile production zones exposed to monsoon logistics disruptions. Distribution runs through three national distributors controlling majority stocking decisions for large manufacturing facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial hand gloves constitute a late-cycle quality story as enforcement intensification across OSHA and EU PPE Regulation jurisdictions shifts procurement toward certified premium specifications. Buyers increasingly reject uncertified imports, compressing viable supplier pools and extending margin retention to qualified producers.
For Market Incumbents: Lock in polymer supply security through backward integration into butadiene or acrylonitrile feedstocks, or through long-term offtake agreements with petrochemical suppliers. Anchor distributor relationships by extending payment terms and co-investing in certification documentation that satisfies notified body audits under EU PPE Regulation 2016/425. Bio-based polymer substitutes threaten petroleum-derived nitrile economics; incumbents should pilot fermentation-derived alternatives to defend positioning in EU public procurement.
For New Entrants and Emerging Players: Begin with India manufacturing scale-up under Production-Linked Incentive schemes for technical textiles, targeting Pune and Chennai metalworking hubs with EN 388-certified cut-resistant capacity. E-commerce direct fulfillment to mid-sized industrial buyers in Australia and Japan offers the most penetrable channel, bypassing consolidated North American distributor layers. Go-to-market positioning should emphasize smart sensor-embedded glove technology for automotive and electronics assembly pilot programs.
For Investors and Strategic Acquirers: Roll-up economics work for regional cut-resistant specialists with certified laboratory infrastructure because ANSI and EN 388 testing backlogs create scarcity value for qualified production assets. The 5-10 year viability window favors producers with demonstrated compliance across multiple regulatory jurisdictions. Acquisition target archetype: mid-cap engineered fiber fabricators with EN 388:2016+A1:2018 blade cut testing capability and established OEM relationships in metal fabrication. Signal to watch: acceleration of bio-based polymer qualification timelines as EU Green Deal procurement thresholds tighten.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Feedstocks | Captive butadiene supply insulates margin pools from crude oil price volatility. |
| CE Marking Investment for EU Access | Notified body certification filters non-compliant competitors from regulated procurement channels. |
| Smart Sensor-Embedded Product Development | Automotive assembly plants in Germany pilot real-time ergonomic hazard tracking systems. |
| E-Commerce Channel Expansion | Direct fulfillment bypasses consolidated distributor layers serving mid-sized industrial buyers. |
| Bio-Based Polymer Transition | Fermentation-derived alternatives align with EU Green Deal public procurement preferences. |
Study Parameters
Multiple input streams — primary interviews with safety procurement managers and plant engineers, customs and trade flow data, regulatory filing databases — were reconciled to construct bottom-up demand estimates and top-down market sizing. Industry stakeholders interviewed included EHS directors at automotive and electronics manufacturers, category buyers at industrial distributors, regulatory affairs specialists at PPE producers, and laboratory certification managers. Secondary validation drew from OSHA enforcement records, EU PPE Regulation notified body audit reports, SEC 10-K filings of listed glove manufacturers, and Bureau of Indian Standards harmonization notices.
Data-stream reconciliation across product type, material formulation, end-use industry, and geographic production hub enabled segmentation-level modeling over the projection horizon. CAGRs were derived from trend extrapolation of enforcement-driven replacement rates and capital expenditure cycles in heavy industry. Forecast inputs incorporated butadiene price indices, provincial safety bureau inspection frequency in China, and distributor consolidation patterns in North America.
Caveats apply where feedstock price shocks, regulatory enforcement pauses, or bio-based polymer scale-up delays could materially shift the outlook. Forecasts reflect documented assumptions about certification timeline continuity and trade flow stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective and Workwear Textiles
Asbestos Gloves Market
Protective and Workwear Textiles
High Visibility Clothing Market
Protective and Workwear Textiles
Flame Resistant (FR) Coveralls Market
Protective and Workwear Textiles
North America Western Wear Market
Protective and Workwear Textiles
US UPF Sun Protective Clothing Market
Protective and Workwear Textiles
Global Law Enforcement and Firefighting Protective Clothing Fabrics Market
Protective and Workwear Textiles
Cut Resistant Fabrics Market
Protective and Workwear Textiles
Anti-Stain Fabrics Market
Protective and Workwear Textiles
Industrial Protective Fabrics Market
Protective and Workwear Textiles
Functional Workwear Apparel Market
Protective and Workwear Textiles
Rain Coat Market
Protective and Workwear Textiles
Winter Wear Market
Protective and Workwear Textiles
Compression Garments Market
Protective and Workwear Textiles
Fabric Protection Market
Protective and Workwear Textiles
Uniforms and Workwears Market
Protective and Workwear Textiles
Rainwear Market