
 Global Flame Resistant Fabric Market | 2026-2036
Global Flame Resistant Fabric Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flame Resistant Fabric Market Foresight
Oil and gas sector procurement is decoupling from legacy cotton-based treated fabrics toward inherently flame-resistant aramid and modacrylic systems. DuPont de Nemours, Inc. leverages its Kevlar and Nomex fiber platforms to anchor supply relationships with integrated oil majors across North American shale basins. Teijin Limited competes through backward integration into para-aramid polymer production, sustaining cost discipline against commodity fiber volatility. Syensqo SA/NV specializes in polybenzimidazole chemistry, occupying the ultra-high-temperature niche above four hundred degrees Celsius where standard aramids degrade.
Flame resistant fabric denotes textile engineered to self-extinguish upon flame source removal, typically achieving limited oxygen indices above twenty-six percent through inherent fiber chemistry or durable surface treatment. These materials protect workers in flash fire and electric arc environments by forming a stable char barrier that insulates skin from thermal transfer. Aramid fiber systems dominate value pools in military and aerospace end uses where weight-specific protection commands premium positioning. Modacrylic segments lead growth velocity in industrial laundering environments due to retained FR performance across fifty-plus wash cycles. Woven product forms maintain volume leadership in structural firefighting turnout gear, though knit constructions penetrate industrial base-layer applications where stretch recovery matters.
OSHA 1910.269 mandates arc-rated clothing for electrical utility workers, while NFPA 2112 governs flash fire protection in oil and gas operations, collectively standardizing minimum performance thresholds. ECHA REACH restrictions on halogenated flame retardants are forcing European formulators toward phosphorus-based and nitrogen-synergist chemistries with altered durability profiles. Stakeholders must monitor divergence between U.S. self-extinguishing standards and EU chemical hazard classifications, as misalignment threatens cross-Atlantic product certification costs and inventory segmentation.
Market Dynamics
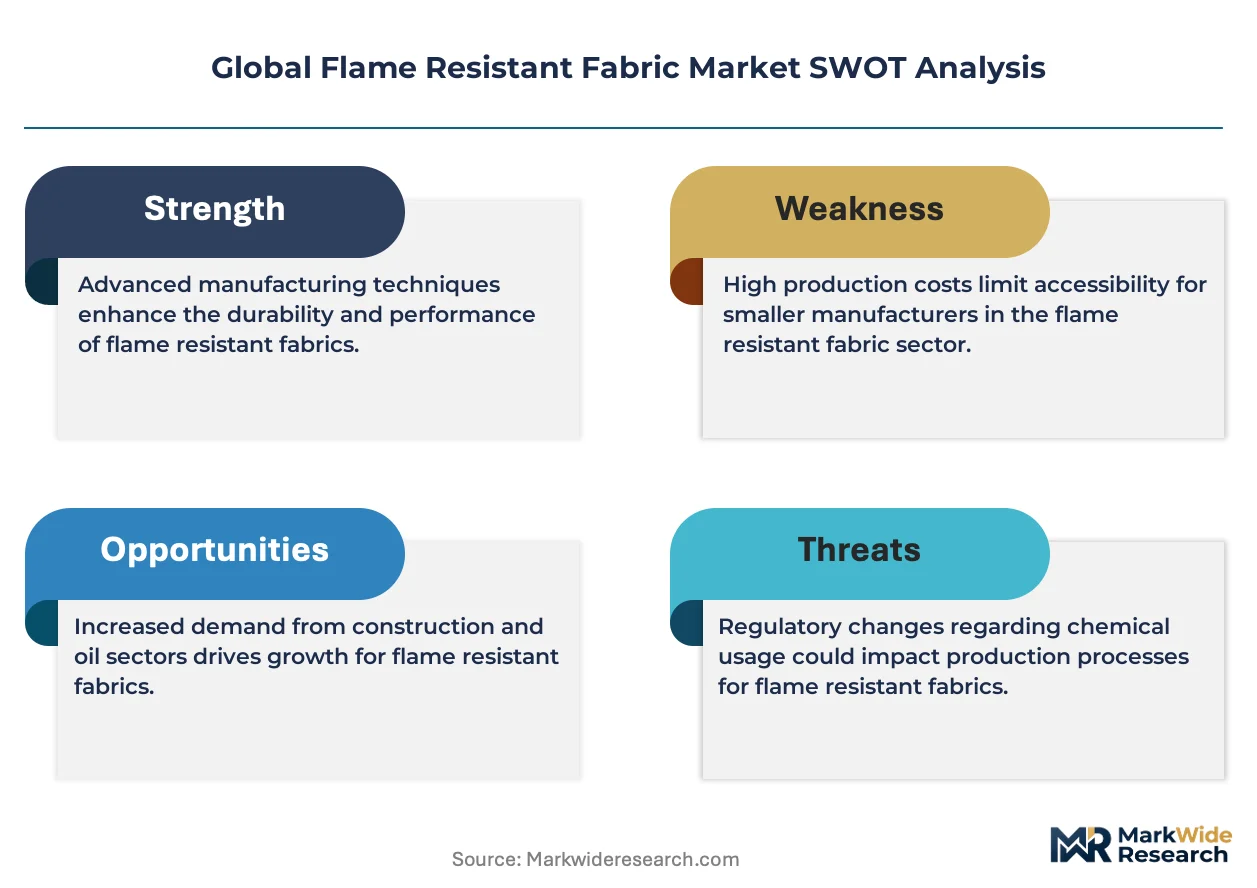
REACH chemical restrictions under ECHA are forcing European formulators to abandon halogenated flame retardants, accelerating fiber substitution toward phosphorus-based and nitrogen-synergist chemistries with altered durability profiles.
Growth Catalysts
- OSHA 1910.132 enforcement:Gulf Coast petrochemical operators face accelerated replacement cycles for personal protective equipment, driving volume demand for inherently flame-resistant garments.
- Electric utility infrastructure modernization:Grid hardening investments across North American shale basins expand arc-rated clothing mandates under OSHA 1910.269.
- Modacrylic fiber performance:Industrial laundering environments favor retained FR performance across fifty-plus wash cycles, displacing shorter-life treated alternatives.
Market Restraints
- Para-aramid supply concentration:Backward integration into polymer production limits supplier pool to three dominant chemical conglomerates with pricing power.
- Meta-aramid input volatility:Petroleum-derived precursor costs fluctuate with benzene and meta-phenylenediamine spot markets, compressing converter margins.
- REACH authorization delays:ECHA's substance evaluation timelines extend eighteen to thirty-six months, freezing product reformulation pipelines.
Strategic Opportunities
- Saudi downstream petrochemical expansion:SABIC and Aramco joint ventures in Jubail Industrial City create concentrated demand for high-temperature protective textiles.
- Polybenzimidazole ultra-high-temperature niche:Applications above four hundred degrees Celsius remain underserved by standard aramids, commanding premium positioning.
- EU Green Deal public procurement:Circular economy criteria in PPE purchasing guidelines favor durable, recyclable fiber systems over disposable alternatives.
Industry Challenges
- NFPA 2112 recertification complexity:Third-party testing laboratory capacity constraints extend flash fire protection validation timelines by four to six months.
- Knit construction technical expertise:Industrial base-layer manufacturing requires stretch-recovery engineering capabilities scarce outside established technical textile clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flame Resistant Fabric Market |
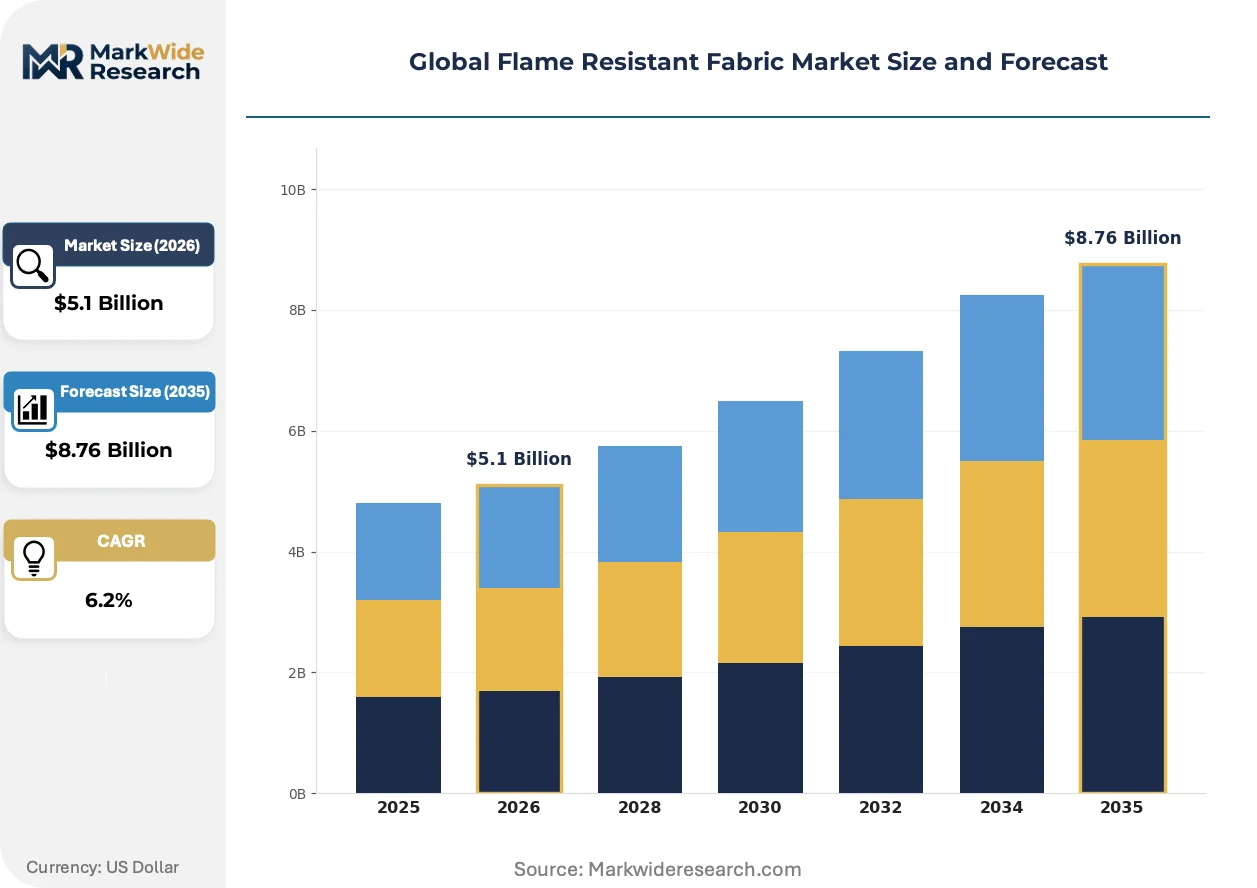
| Market Size in 2026 | $5.1 Billion |
| Market Size in 2035 | $8.76 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fiber Type: Aramid, Modacrylic, Inherent FR Cotton, FR Polyester, Cellulose, Glass Fiber End User Industry: Oil & Gas, Fire Services, Military, Electrical Utilities, Chemical Processing, Aerospace Product Form: Woven, Nonwoven, Knit, Coated, Laminated, Blend Fabrics Fabric Treatment: Pre-treatment, Post-treatment, Durable Flame Retardant, Chemical Finishing, Heat Resistant Coating, Water Repellent |
| Companies Covered | Teijin Limited, Klopman International, DuPont de Nemours, Inc., Syensqo SA/NV, Nam Liong Global Corporation, TenCate Protective Fabrics, Indorama Ventures Public Company Limited, PBI Performance Products, Inc., Milliken & Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flame Resistant Fabric Market Shifts & Advancements
Flame resistant fabric innovation centers on fiber chemistry convergence, regulatory chemistry substitution mandates, and procurement model compression toward specification-driven direct sourcing.
Phosphorus-based flame retardant chemistry is converging with cellulosic fiber substrates to create halogen-free alternatives that satisfy ECHA REACH restrictions while maintaining vertical flame test performance. European industrial laundries adopt these systems fastest, driven by chemical compliance liabilities. The convergence is compressing market share for legacy brominated formulations in export-oriented supply chains.
ECHA REACH Annex XIV authorization requirements for halogenated flame retardants are forcing European formulators toward phosphorus-nitrogen synergist systems with altered hydrolytic stability profiles. Industrial laundries face reformulation costs and compatibility testing with existing equipment fleets. Modacrylic segments in Germany and Benelux respond fastest due to concentrated textile chemical infrastructure.
Integrated oil majors are consolidating specification authority at corporate procurement centers, bypassing regional distributor networks for direct mill relationships. Gulf Coast petrochemical operators now mandate fiber origin disclosure and batch-level testing documentation. This concentration is most visible in Texas and Louisiana, where OSHA 1910.132 enforcement drives centralized PPE standardization across multi-site operators.
Global Flame Resistant Fabric Market Segmentation
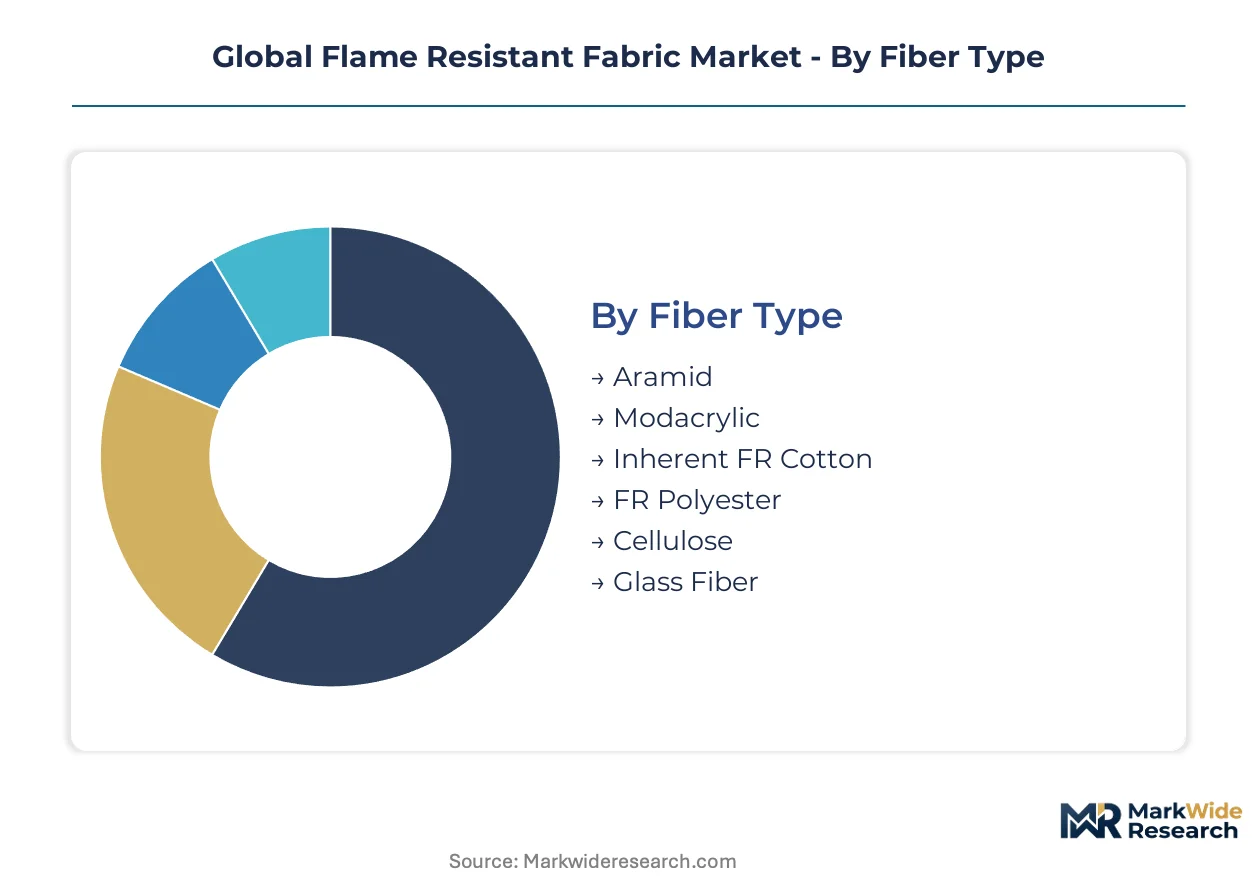
Flame resistant fabric segmentation reveals how fiber chemistry, end-use hazard profiles, and manufacturing processes create distinct value pools with divergent margin structures. Procurement specifications in regulated industries lock suppliers into certification-bound segment positions that resist rapid switching.
Fiber Type:
Technology leadership and thermal performance thresholds define competitive positioning across fiber systems.
- Aramid:Para-aramid and meta-aramid polymers deliver the highest strength-to-weight ratios among flame resistant fibers. Military and aerospace procurement in the United States, France, and Japan sustains premium positioning where ballistic and thermal protection converge.
- Modacrylic:Acrylic copolymers with inherent flame resistance retain protective properties across industrial laundering cycles. German and Benelux industrial laundries favor modacrylic base layers for oil and gas workers under ECHA REACH chemical compliance mandates.
- Inherent FR Cotton:Grown varieties and engineered cellulosic modifications provide cotton-like comfort with self-extinguishing characteristics. Limited to lower-temperature applications below three hundred degrees Celsius.
- FR Polyester:Phosphorus-modified polyester staple serves cost-sensitive industrial applications where durability requirements moderate. Chinese textile converters dominate volume production.
- Cellulose:Regenerated cellulosic fibers with nitrogen-based flame retardant incorporation offer biodegradable positioning for EU Green Deal procurement criteria.
- Glass Fiber:Silicate-based inorganic filaments withstand continuous exposure above five hundred degrees Celsius. Saudi petrochemical expansion and United States aerospace insulation drive niche demand.
Mature deployment sits with aramid systems in military and aerospace specifications. Newer deployment is concentrated in modacrylic segments responding to European chemical regulation substitution pressures.
End User Industry:
Regulatory enforcement intensity and hazard severity create tiered specification requirements across industrial verticals.
- Oil & Gas:Flash fire protection under NFPA 2112 mandates drives replacement cycles for coveralls and base layers. United States Gulf Coast operators in Texas and Louisiana concentrate procurement volume through integrated oil major corporate centers.
- Fire Services:Structural turnout gear specifications under NFPA 1971 require thermal protective performance ratings above thirty-five cal/cm². Woven aramid outer shells and moisture barriers dominate municipal procurement in Germany, Japan, and the United Kingdom.
- Military:Ballistic-thermal combined protection specifications in the United States, France, and South Korea sustain para-aramid volume leadership. Combat uniform modernization programs drive fiber specification tightening.
- Electrical Utilities:OSHA 1910.269 arc-rated clothing mandates expand across North American grid hardening investments. Arc ratings from eight to forty cal/cm² segment procurement by exposure risk.
- Chemical Processing:Combined chemical splash and flame resistance requirements favor multi-barrier laminate constructions. German and Swiss pharmaceutical-chemical clusters specify polybenzimidazole for ultra-high-temperature reactor maintenance.
- Aerospace:Flame resistant textiles in aircraft interiors meet FAA fireworthiness standards for seat covers, cargo liners, and insulation blankets. Boeing and Airbus supply chains certify fiber origins through batch-level documentation.
Procurement consolidation concentrates in oil and gas and electrical utilities. Specification complexity and certification longevity favor established fiber platforms in military and fire services.
Product Form:
Manufacturing process selection determines stretch recovery, surface integrity, and multi-layer integration possibilities.
- Woven:Interlaced warp and weft constructions provide structural stability for outer protective layers. Firefighter turnout gear and industrial coveralls in the United States and Germany specify woven aramid face fabrics.
- Nonwoven:Entangled fiber webs without yarn structure create lightweight thermal barriers and moisture management layers. Needle-punched aramid felts serve as insulation in aerospace applications.
- Knit:Loop-forming constructions deliver stretch recovery for base-layer comfort and mobility. Industrial laundries in Belgium and the Netherlands favor knit modacrylic for oil and gas workers requiring range of motion.
- Coated:Polymer film deposition adds chemical splash resistance or waterproofing to woven substrates. Chemical processing applications in Switzerland and Germany specify fluoropolymer or polyurethane coatings.
- Laminated:Multi-layer bonding combines flame resistance with moisture barriers and thermal liners. Three-layer laminate systems dominate structural firefighting gear specifications.
- Blend Fabrics:Intimate fiber mixing or yarn blending optimizes cost-performance ratios. Cotton-modacrylic blends serve developing economy industrial markets where full inherent FR cost premiums resist adoption.
Volume concentration remains with woven constructions for heavy-duty outer protection. Knit forms are gaining share fastest in next-to-skin industrial base-layer applications.
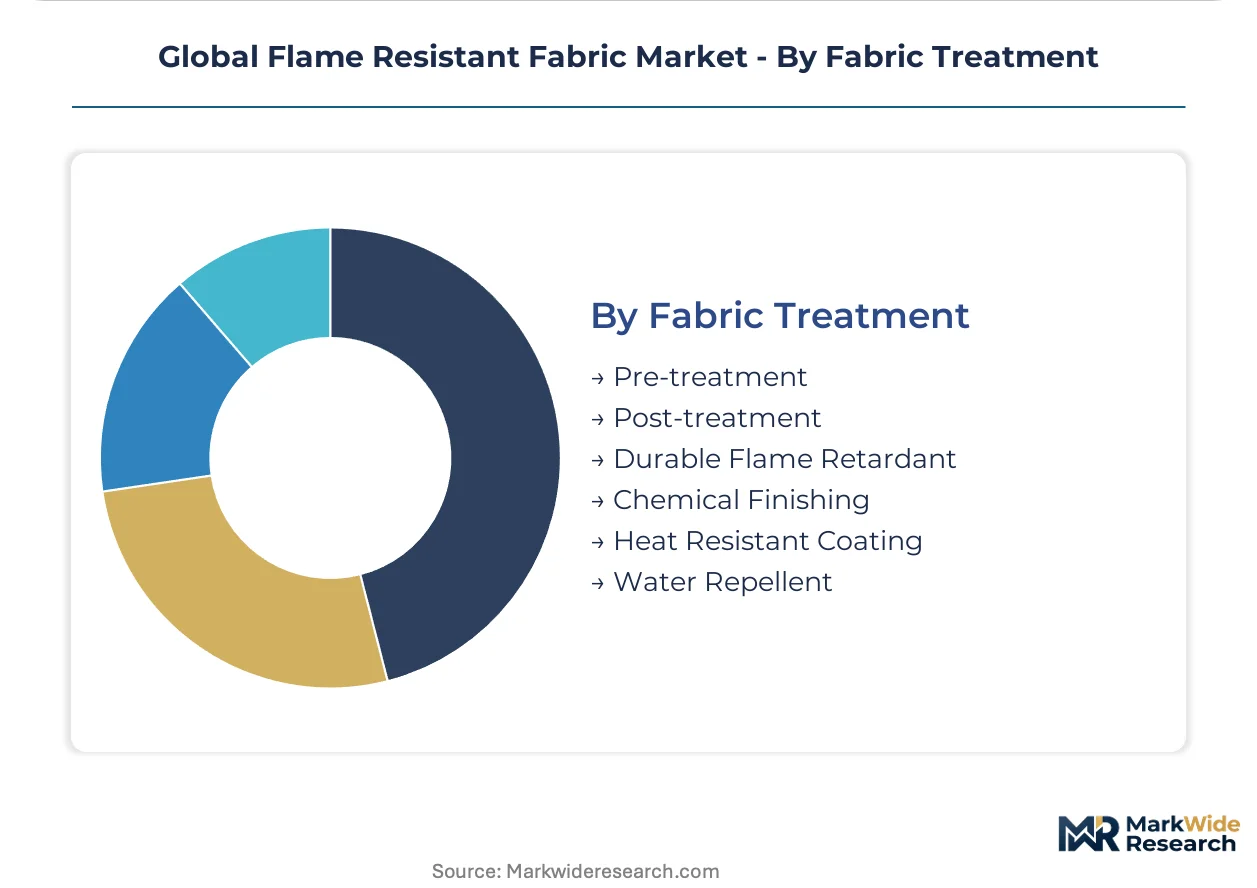
Fabric Treatment:
Chemistry application timing and durability mechanisms separate temporary compliance from lifecycle performance assurance.
- Pre-treatment:Flame retardant incorporation during fiber spinning or polymerization creates inherent protection that survives garment lifecycle. Aramid and modacrylic production in the United States, Japan, and Belgium relies on pre-treatment chemistry.
- Post-treatment:Surface application to finished fabrics offers retrofit compliance for existing textile inventories. ECHA REACH restrictions on halogenated chemistries are compressing European post-treatment viability.
- Durable Flame Retardant:Covalent bonding or resin encapsulation extends wash durability beyond fifty industrial cycles. German industrial laundries specify durable treatments for rental workwear programs.
- Chemical Finishing:Auxiliary treatments add water repellency, anti-static, or antimicrobial functions alongside flame resistance. Oil and gas operators in Norway and the United Kingdom specify multi-functional finishes.
- Heat Resistant Coating:Ceramic or silicone-based surface layers extend temperature thresholds for specialized applications. Saudi petrochemical maintenance and United States steelmaking specify coated fabrics above four hundred degrees Celsius exposure.
- Water Repellent:Fluorocarbon or silicone treatments maintain breathability while preventing liquid penetration. Fire services in the United Kingdom and Australia specify water repellent outer shells for wet climate operations.
Regulatory chemistry substitution is forcing transition from post-treatment halogenated systems toward pre-treatment inherent fibers and phosphorus-based durable finishes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jubail Industrial City's petrochemical special economic zone concentrates procurement for ultra-high-temperature protective textiles. SABIC and Aramco joint ventures anchor demand for fabrics rated above four hundred degrees Celsius. This Saudi downstream expansion exemplifies how tax-advantaged zones reshape geographic demand distribution.
United States
Gulf Coast petrochemical operators in Texas and Louisiana drive replacement cycles for inherently flame-resistant garments. OSHA 1910.132 enforcement mandates centralized PPE standardization across multi-site operators. Houston's energy corridor concentrates corporate procurement centers that bypass regional distributor networks.
Germany
Industrial laundries in the Ruhr and Benelux border regions favor modacrylic base layers for oil and gas rental workwear programs. ECHA REACH chemical restrictions force abandonment of halogenated flame retardants toward phosphorus-nitrogen synergist systems. Frankfurt-Rhine-Main textile chemical infrastructure responds fastest to reformulation mandates.
Japan
Military and aerospace procurement sustains premium positioning for para-aramid fiber systems with combined ballistic-thermal protection. METI standards tighten fiber specifications for combat uniform modernization programs. Nagoya's technical textile cluster maintains backward integration into polymer production for cost discipline.
Belgium
Knit modacrylic manufacturing concentrates in Flanders for oil and gas base-layer applications requiring stretch recovery. ECHA authorization timelines for alternative chemistries extend eighteen to thirty-six months, freezing product pipelines. Antwerp's port infrastructure supports chemical import dependencies for nitrogen-synergist formulations.
Saudi Arabia
Downstream petrochemical expansion in Jubail Industrial City creates concentrated demand for glass fiber and polybenzimidazole systems. SFDA chemical compliance aligns with EU REACH restrictions for export-oriented production. Eastern Province maintenance operations specify coated fabrics for reactor environments above five hundred degrees Celsius.
Global Flame Resistant Fabric Market Competitive Landscape
Top-tier vendors anchor para-aramid and meta-aramid polymer production, while mid-tier converters compete on specification compliance and laundering durability. The supplier pool concentrates around three dominant chemical conglomerates with captive polymer production. Strategic archetypes include fiber-origin specialists, industrial laundry service integrators, and multi-barrier laminate system providers. Competitive moves center on backward integration into precursor chemicals and direct mill relationships with integrated oil majors.
Among Japanese and Belgian fiber-origin specialists, Teijin Limited and Syensqo SA/NV exemplify contrasting technology positioning. Teijin represents backward integration archetypes with in-house para-aramid polymer production. Syensqo occupies the ultra-high-temperature niche through polybenzimidazole chemistry specialization. DuPont de Nemours, Inc. anchors the premium-tier vector with established Kevlar and Nomex platforms serving North American shale basin operators. These three entities illustrate how fiber chemistry leadership translates into specification authority at corporate procurement centers.
| Leading Market Players |
|---|
| Teijin Limited |
| Klopman International |
| DuPont de Nemours, Inc. |
| Syensqo SA/NV |
| Nam Liong Global Corporation |
| TenCate Protective Fabrics |
| Indorama Ventures Public Company Limited |
| PBI Performance Products, Inc. |
| Milliken & Company |
| Others |
Supply & Pricing Matrix
Phosphorus-nitrogen synergist chemistry migration simultaneously compresses converter margins and concentrates supply relationships among polymer producers with captive precursor capacity. ECHA REACH authorization timelines extend eighteen to thirty-six months, freezing product pipelines and forcing buyers toward contract-based offtake with established fiber-origin specialists.
Pricing Analysis
Short lead-time premiums command fifteen to twenty percent markups over standard delivery windows as industrial laundries face compressed inventory cycles under chemical reformulation mandates. Three-tier pricing structure across premium, standard, and economy levels separates Kevlar-Nomex platforms from modacrylic intermediates and FR polyester commodity tiers. Price differentiation hinges on certification grade and fiber origin disclosure documentation. Cost compression in treated cotton segments is intensifying because ECHA halogenated flame retardant restrictions eliminate European post-treatment viability. Mid-tier converters exhibit highest price sensitivity due to meta-aramid input volatility, while military-aerospace procurement demonstrates lowest sensitivity given ballistic-thermal performance requirements.
Supply Chain Analysis
Industrial laundry returns and refurbishment flows create reverse logistics complexity as rental workwear programs extend garment lifecycle through fifty-plus wash cycles. Para-aramid polymer production concentrates in the United States, Japan, and Belgium, with meta-aramid precursor chemistry anchored in German and Benelux chemical infrastructure. Raw material dependencies rest on benzene and meta-phenylenediamine spot markets, acrylonitrile modacrylic feedstocks, and phosphorus-based flame retardant intermediates. Single-source vulnerability sits with three dominant chemical conglomerates controlling backward integration into polymer production. Distribution runs through corporate procurement centers at integrated oil majors, bypassing regional distributor networks for direct mill relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into precursor chemicals and captive fiber production represents the decisive competitive lever as ECHA authorization timelines freeze reformulation pipelines and concentrate specification authority.
For Market Incumbents: Deploy certification investment to lock in NFPA 2112 and OSHA 1910.269 validation longevity against emerging phosphorus-nitrogen synergist formulators. Deepen backward integration into meta-phenylenediamine and para-aramid polymer production to insulate margin structures from benzene spot volatility. Channel control through direct mill relationships with Gulf Coast petrochemical operators resists distributor disintermediation. For New Entrants and Emerging Players: Industrial laundry service providers represent the most accessible channel partners for modacrylic base-layer penetration in German and Benelux rental workwear programs. White-space targets include polybenzimidazole ultra-high-temperature niches above four hundred degrees Celsius and EU Green Deal circular economy procurement for recyclable fiber systems. A specification-first go-to-market angle leveraging ECHA REACH compliance liabilities accelerates adoption against legacy halogenated alternatives. For Investors and Strategic Acquirers: Re-rating potential sits with fiber-origin specialists given ECHA authorization delays and chemical substitution mandates compressing post-treatment viability. Long-term viability over a five-to-ten-year window favors entities with captive para-aramid or polybenzimidazole polymer production. Monitor ECHA Annex XIV substance evaluation timelines and OSHA enforcement intensity across Texas and Louisiana as inflection indicators for replacement cycle velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Chemicals | Captive meta-phenylenediamine supply insulates Teijin and DuPont from benzene spot volatility. |
| Direct Mill Relationships with Oil Majors | Houston procurement centers bypass distributors for fiber origin disclosure and batch-level testing. |
| Phosphorus-Nitrogen Synergist Reformulation | European industrial laundries abandon halogenated systems under ECHA REACH authorization pressure. |
| Polybenzimidazole Capacity Expansion | SABIC-Aramco Jubail ventures create concentrated demand above four hundred degrees Celsius. |
| NFPA 2112 Recertification Investment | Third-party testing laboratory relationships extend flash fire protection validation timelines. |
Research Methodology
SEC 10-K filings, ECHA substance registration databases, and OSHA enforcement action records formed the secondary backbone for supply concentration and regulatory trajectory assessment. Primary interviews with plant managers at Gulf Coast petrochemical operators, procurement leads at industrial laundry service providers, technical R&D directors at fiber converters, and regulatory affairs specialists at chemical conglomerates validated secondary findings. Bottom-up fiber volume estimates and top-down end-use industry demand projections were triangulated against customs trade data and ACC industry reports.
Historical trendline analysis across fiber type, end-use industry, and product form dimensions established baseline growth patterns over the projection horizon. Segmentation modeling incorporated fiber chemistry tier, hazard severity specification, manufacturing process complexity, and regional regulatory cluster. CAGRs were derived through regression analysis of replacement cycle frequencies, enforcement intensity indices, and chemical substitution velocity. Forecast inputs included OSHA 1910.132 inspection data and ECHA authorization pipeline status.
Caveats apply where ECHA REACH authorization timeline extensions or OSHA enforcement intensity variations could materially shift the outlook. Forecasts reflect assumptions regarding chemical substitution rates and petrochemical capital expenditure continuity. Practitioners should monitor ECHA Annex XIV substance evaluation progress and Saudi downstream project commissioning schedules for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective and Workwear Textiles
Global Fire Resistant Fabric Market
Protective and Workwear Textiles
Industrial Curtains Market
Protective and Workwear Textiles
US UPF Sun Protective Clothing Market
Protective and Workwear Textiles
Anti-Stain Fabrics Market
Protective and Workwear Textiles
High Visibility Clothing Market
Protective and Workwear Textiles
Compression Garments Market
Protective and Workwear Textiles
Rain Coat Market
Protective and Workwear Textiles
Rainwear Market
Protective and Workwear Textiles
Functional Workwear Apparel Market
Protective and Workwear Textiles
Flame Resistant (FR) Coveralls Market
Protective and Workwear Textiles
Fabric Protection Market
Protective and Workwear Textiles
Asbestos Gloves Market
Protective and Workwear Textiles
Industrial Wearable Market
Protective and Workwear Textiles
Workwear Market
Protective and Workwear Textiles
Industrial Protective Fabrics Market
Protective and Workwear Textiles
Fashion Face Mask Market