
 Rain Coat Market | 2026-2036
Rain Coat Market Size, Share, and Industry Trends Forecast 2026-2036
Rain Coat Market Analytics
Specialized textile engineering talent is unwinding supply constraints as technical fabric mills in Asia-Pacific expand workforce training programs. Columbia Sportswear Company leverages its vertical manufacturing network to control Gore-Tex allocation and pricing. Arc'teryx sustains premium positioning through obsessive seam-taping precision and alpine-specific design. Patagonia anchors its rainwear portfolio with recycled nylon supply chains and repair-service infrastructure.
A rain coat is a waterproof or water-resistant outer garment engineered with taped seams, DWR-treated face fabrics, and breathable membranes rated to minimum hydrostatic head thresholds, manufactured through cut-and-sew assembly with ultrasonic welding or hot-seam taping. Its primary commercial purpose is protecting wearers from precipitation while managing interior moisture vapor transport during active use. Parka and anorak styles dominate volume in cold-climate markets where extended coverage and hood integration matter most, while trench coats retain margin concentration in urban fashion channels. Gore-Tex and advanced nylon laminates command premium price tiers against commodity polyester alternatives that flood discount retail.
EPA oversight of PFAS chemicals and REACH restrictions on perfluorinated compounds in Europe are forcing material reformulation across membrane and DWR suppliers. The EU Green Deal's textile sustainability requirements and emerging state-level disclosure laws in the US are reshaping labeling and recyclability obligations. China's GB standards for textile safety and MIIT directives on chemical manufacturing add compliance layers for brands sourcing from domestic mills. Stakeholders must monitor which technical fabric suppliers achieve scalable non-fluorinated waterproofing without sacrificing breathability benchmarks.
Market Dynamics
PFAS phase-out mandates across multiple jurisdictions are forcing membrane and DWR suppliers to rebuild their chemistry foundations from scratch, compressing margins while opening first-mover advantages for fluorine-free innovators.
Growth Catalysts
- REACH Annex XVII restrictions:European chemical safety rules are accelerating R&D investment in bio-based waterproofing polymers as brands race to secure compliant material pipelines before enforcement deadlines tighten.
- Trail running and gravel cycling:These endurance sports are expanding the addressable market for packable emergency shells that balance breathability with sub-200-gram weights.
- China's technical fabric cluster:Domestic mills in Zhejiang and Jiangsu provinces are scaling membrane lamination capacity, reducing lead times for Asia-Pacific brands and export orders.
Market Restraints
- Petrochemical feedstock volatility:Nylon 6,6 and polyester chip prices swing with crude oil indices, squeezing contract manufacturers who cannot pass through costs to locked retail pricing.
- Membrane supplier concentration:Gore-Tex and eVent control premium breathable waterproof film supply, creating allocation bottlenecks during seasonal demand spikes.
- Performance gaps in fluorine-free DWR:Current silicone and hydrocarbon treatments degrade faster under abrasion and washing than legacy C8 chemistry, frustrating durability claims.
Strategic Opportunities
- India's monsoon apparel gap:Organized retail penetration remains below fifteen percent for technical rainwear, leaving room for domestic brands to build category awareness before international entrants scale.
- Repair and resale infrastructure:Patagonia's Worn Wear model demonstrates margin capture from lifetime garment servicing, an underexploited channel for mid-tier competitors.
- EU Green Deal textile labeling:Mandatory digital product passports create competitive differentiation for brands with verified recycled content and transparent supply chain mapping.
Industry Challenges
- Ultrasonic welding technician scarcity:Seam-taping precision requires specialized operators that vocational programs in Vietnam and Bangladesh have not yet scaled to match factory demand.
- Dual certification burden:Brands must simultaneously satisfy bluesign and OEKO-TEX requirements while navigating diverging PFAS testing protocols between EPA and ECHA methodologies.
- Legacy inventory stranding:Warehouse stocks of C6 DWR-treated fabrics face accelerated obsolescence as state-level disclosure laws in Maine and Washington trigger preemptive retailer rejections.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rain Coat Market |
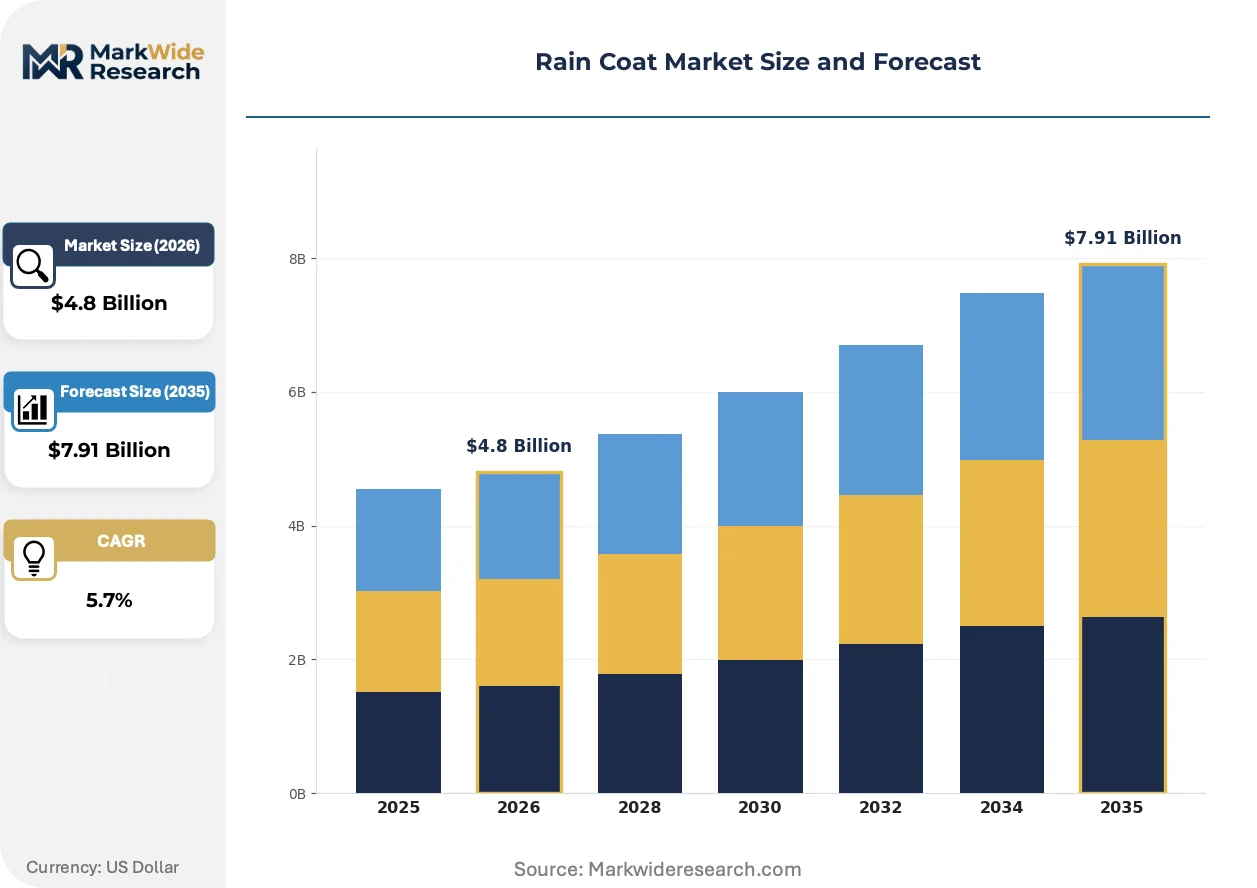
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Parka, Anorak, Trench Coat, Poncho Material: Gore-Tex, Nylon, Polyester, Rubber End User: Men, Women, Children, Unisex Distribution Channel: Online Retail, Specialty Stores, Department Stores, Discount Retailers |
| Companies Covered | Rains, Zhengxin Group, Patagonia, Inc., Stutterheim, Wildcraft India Private Limited, Columbia Sportswear Company, Zeel Raincoat, Arc’teryx, The North Face, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rain Coat Market Evolving Landscape
Material science breakthroughs are fragmenting the once-dominant membrane hierarchy, while regulatory chemistry bans and circular economy mandates rewrite how waterproof garments are designed, sold, and retired.
Biomimetic surface treatments inspired by lotus leaf microstructures are decomposing the traditional membrane-plus-DWR stack into simpler single-layer solutions. Startups in Switzerland and Japan are piloting these textures on polyester base fabrics for cycling and running brands seeking weight reduction. The technology is decomposing premium pricing tiers by enabling commodity mills to achieve hydrostatic head ratings previously gated behind licensed film laminates.
ECHA's proposal to restrict per- and polyfluoroalkyl substances under REACH is forcing membrane suppliers to submit dossiers on fluorine-free alternatives by 2025. German and French testing laboratories report eighteen-month queues for validation studies, compressing product launch windows. Alpine and Nordic brands with EU manufacturing footprints are accelerating partnerships with bio-based chemistry firms to secure early compliance positioning.
Direct-to-consumer refurbishment programs are capturing margin that traditional wholesale channels forfeit. Brands with owned repair facilities in Portland and Munich report customer lifetime value multiples exceeding standard retail economics. This channel pivot is most visible in North American and German markets where environmental registration fees and extended producer responsibility laws make garment longevity a cost-avoidance strategy.
Rain Coat Market Segmentation
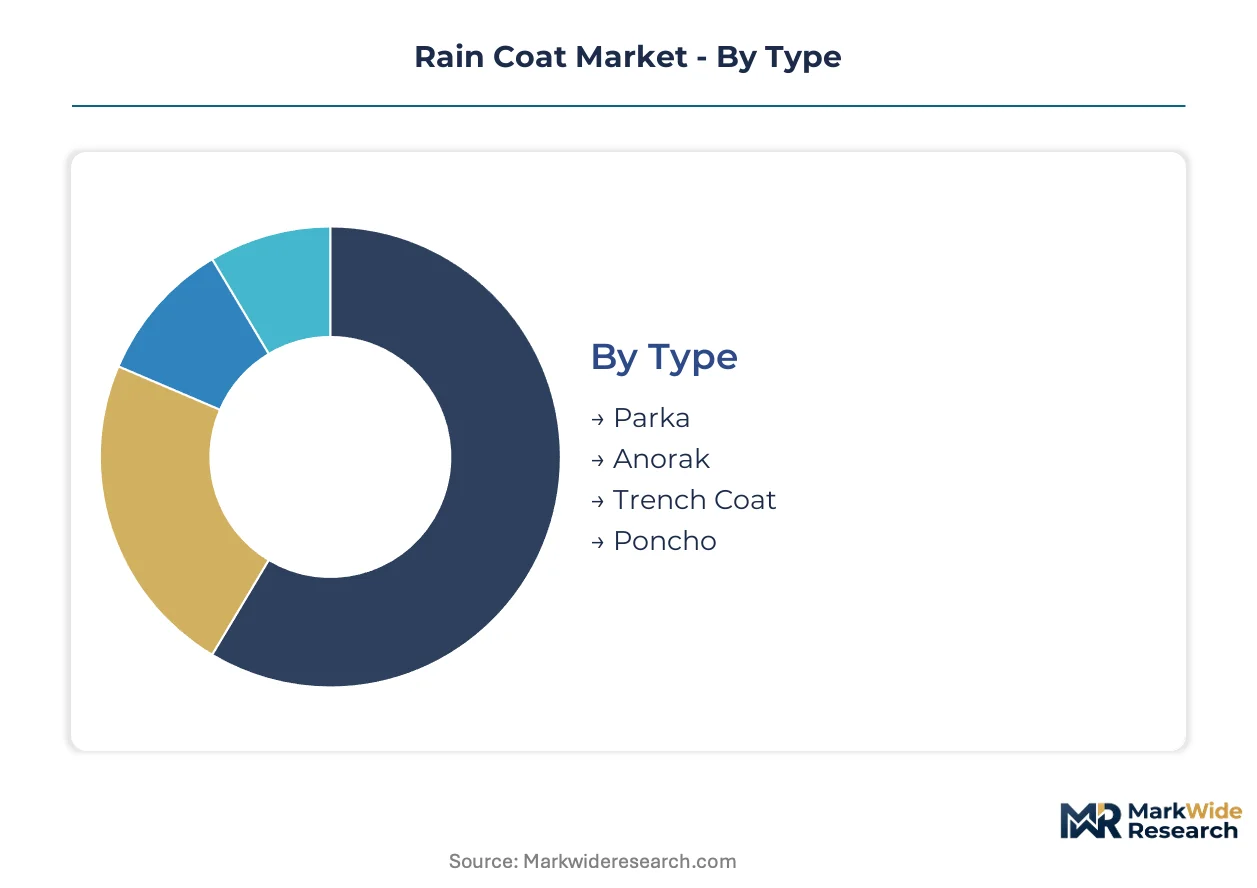
Rain coat segmentation separates technical performance tiers from fashion positioning, with material chemistry and distribution channel determining margin capture. Regulatory pressure on waterproofing compounds forces parallel supply chains for compliant and legacy products.
Type:
REACH Annex XVII restrictions on perfluorinated compounds create divergent design requirements between alpine-technical and urban-fashion silhouettes.
- Parka:Extended coverage designs integrate helmet-compatible hoods and two-way zippers for harness access. Demand concentrates in Norway, Sweden, and Canada's British Columbia where extended backcountry exposure necessitates thermal layering compatibility.
- Anorak:Pullover construction with kangaroo pockets and half-zip ventilation reduces zipper failure points. Trail running communities in Switzerland's Engadin valley and Japan's Japanese Alps drive ultralight sub-150-gram specifications.
- Trench Coat:Double-breasted silhouettes with belted waists prioritize urban aesthetics over breathability metrics. London, Paris, and Milan fashion buyers specify water-resistant cotton gabardine with acetate linings.
- Poncho:Rectangular drape construction with side-snap closures enables bicycle commuting coverage. Mexico City, Bogotá, and Jakarta urban mobility programs distribute reflective variants for informal transit workers.
Parka handles the majority of throughput; Anorak is expanding most quickly on share.
Material:
Cost tier stratification separates licensed membrane laminates from commodity woven alternatives.
- Gore-Tex:Expanded polytetrafluoroethylene membranes laminated to nylon face fabrics achieve hydrostatic head ratings exceeding 20,000mm. Alpine rescue services in Austria's Tyrol and Switzerland's Valais mandate this specification for professional use.
- Nylon:Polyamide 6,6 ripstop constructions with polyurethane coatings offer tear resistance at mid-tier price points. China's Zhejiang province mills supply domestic outdoor brands and Korean export orders.
- Polyester:Recycled polyethylene terephthalate face fabrics with TPU membranes satisfy EU Green Deal recycled content thresholds. German and Dutch municipal procurement specifications increasingly require this material class.
- Rubber:Vulcanized natural or synthetic rubber sheets with cotton backing provide industrial-grade waterproofing. Commercial fishing fleets in Alaska, Newfoundland, and Scotland's Shetland Islands specify this construction for deck work.
Nylon handles the majority of throughput; Polyester is climbing the fastest on share.
End User:
Application-specific sizing and mobility requirements drive pattern engineering specialization.
- Men:Broader shoulder grading and longer sleeve lengths accommodate upper-body muscle mass. German and Austrian mountaineering associations influence fit standards for technical shells.
- Women:Contoured waist shaping and articulated bust darts reduce fabric bunching during dynamic movement. Scandinavian brands lead pattern development for female-specific alpine gear.
- Children:Growth-adjustable hem systems and reflective safety elements address rapid sizing changes. Japanese school uniform suppliers integrate rainwear into standardized physical education kits.
- Unisex:Modular sizing with adjustable cuffs and hems serves rental markets and emergency preparedness stockpiles. Norwegian civil defense and Swiss military procurement specify this category for reserve mobilization.
Men handles the majority of throughput; Women is gaining share fastest.
Distribution Channel:
Margin structure varies sharply between owned digital platforms and third-party retail intermediaries.
- Online Retail:Direct-to-consumer websites and marketplace listings enable size-exchange programs and repair-service bundling. Portland, Oregon and Munich, Germany host the densest concentrations of brand-operated digital fulfillment centers.
- Specialty Stores:Staffed climbing and cycling shops provide membrane breathability education and fit consultation. Chamonix, Innsbruck, and Boulder, Colorado maintain the highest specialist store density per capita.
- Department Stores:Multi-brand concessions in urban retail landmarks handle fashion-oriented trench coat and commuter poncho volume. Tokyo's Shibuya, London's Oxford Street, and New York's Fifth Avenue anchor this channel.
- Discount Retailers:Big-box and off-price channels move polyurethane-coated polyester shells with minimal warranty support. Walmart's US footprint and Auchan's French hypermarket network dominate volume here.
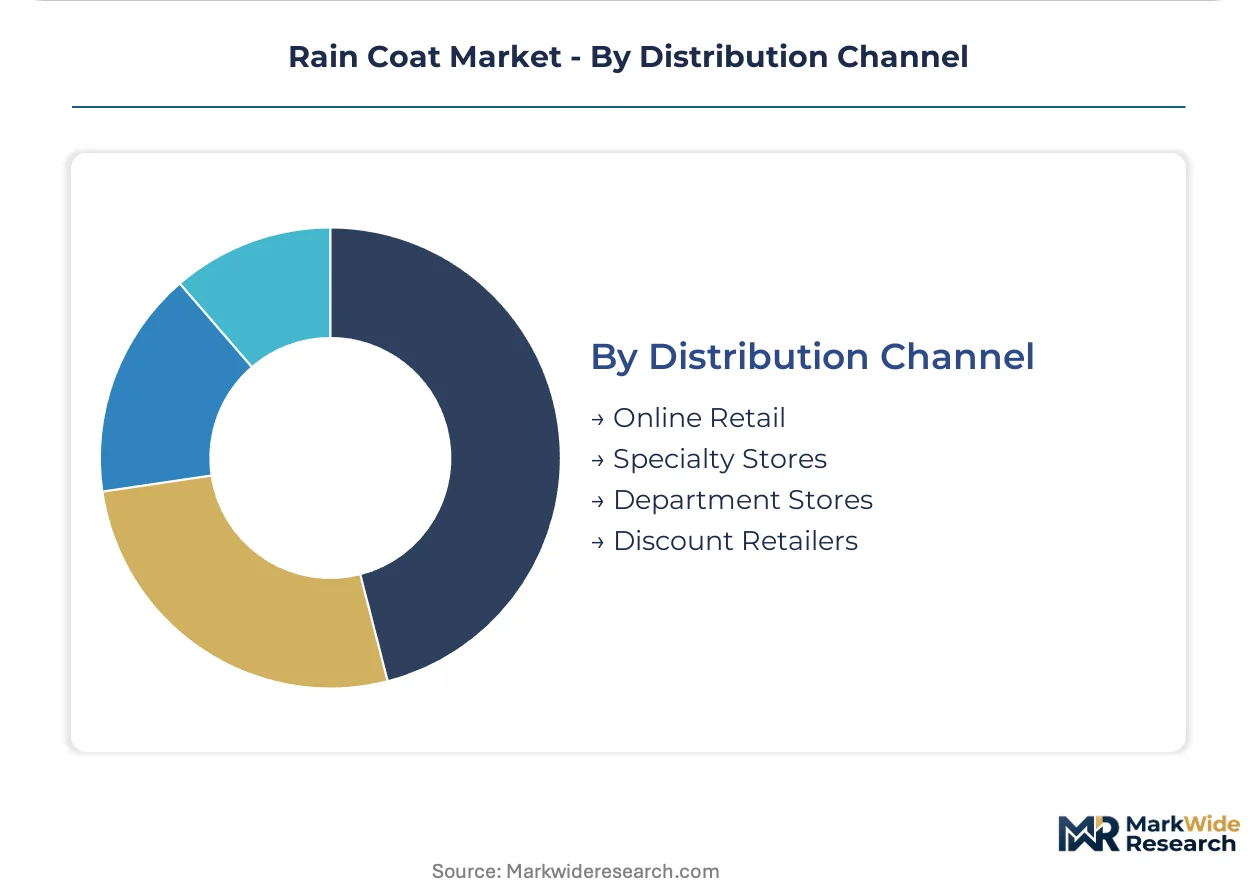
Specialty Stores handles the majority of throughput; Online Retail shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA oversight of PFAS chemicals in the United States anchors the dominant geography, with state-level disclosure laws in Maine and Washington triggering preemptive supply chain adjustments that cascade through international sourcing networks.
United States
Trail running and gravel cycling communities in Colorado and Oregon expand demand for packable emergency shells. State-level PFAS restrictions in Maine and Washington accelerate material transitions away from legacy DWR coatings. Portland hosts dense concentrations of brand-operated digital fulfillment centers with integrated repair-service bundling.
China
Domestic outdoor participation surges in Zhejiang and Jiangsu provinces drive technical fabric consumption. MIIT directives on chemical manufacturing add compliance layers for brands sourcing from domestic mills. Technical fabric clusters in Shaoxing and Suzhou scale membrane lamination capacity for Asia-Pacific brands and export orders.
Germany
Alpine rescue services in Bavaria mandate Gore-Tex specifications for professional use, sustaining premium-tier demand. ECHA's proposal to restrict PFAS under REACH forces membrane suppliers to submit fluorine-free alternative dossiers by 2025. Munich hosts brand-operated refurbishment facilities capturing margin from lifetime garment servicing.
Japan
Trail running communities in the Japanese Alps drive ultralight sub-150-gram anorak specifications. METI standards influence pattern engineering for female-specific alpine gear. Tokyo's Shibuya district anchors department store concessions handling fashion-oriented trench coat volume.
India
Organized retail penetration below fifteen percent for technical rainwear leaves room for domestic brand building. BIS textile safety standards shape import compliance requirements. Maharashtra and Karnataka industrial corridors scale cut-and-sew assembly capacity for monsoon apparel distribution.
Rain Coat Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with membrane innovation concentrated among specialized outdoor brands while volume manufacturing clusters in Asian industrial corridors. The vendor base separates into premium technical specialists, mid-tier diversified sportswear houses, and regional scale fabricators. Three archetypes dominate: vertical manufacturing networks controlling material allocation, design-centric premium positioning through precision construction, and sustainability-anchored circular economy operators. Competitive moves concentrate on strategic partnerships with bio-based chemistry firms and owned repair infrastructure deployment.
Among outdoor apparel specialists, Columbia Sportswear Company, Arc'teryx, and Patagonia, Inc. occupy positions across distinct tier definitions. Columbia represents the diversified sportswear house with manufacturing network control. Arc'teryx exemplifies the precision-construction premium archetype. Patagonia anchors the circular economy operator model with repair-service infrastructure. Regional scale fabricators including Zhengxin Group and Zeel Raincoat sit within Asian supply clusters. Fashion-oriented urban specialists Rains and Stutterheim represent European design-centric positioning. India-based Wildcraft India Private Limited occupies emerging market domestic brand territory.
| Leading Market Players |
|---|
| Rains |
| Zhengxin Group |
| Patagonia, Inc. |
| Stutterheim |
| Wildcraft India Private Limited |
| Columbia Sportswear Company |
| Zeel Raincoat |
| Arc'teryx |
| The North Face |
| Others |
Value Network & Pricing Analysis
Membrane lamination scale economies in China's Zhejiang and Jiangsu provinces concentrate supply-side leverage among technical fabric mills, compressing price floors for mid-tier nylon shells while premium Gore-Tex laminates sustain three-tier pricing separation through allocation control.
Pricing Analysis
Price spreads between Portland-branded technical shells and Bangladesh-assembled commodity rainwear exceed fourfold at wholesale. Premium-mid-economy pricing differentiation rests on hydrostatic head certification tiers and bluesign compliance status. Cost compression in polyurethane-coated polyester runs through petrochemical feedstock volatility that contract manufacturers cannot pass to locked retail pricing. Discount retail buyers exhibit highest price sensitivity; alpine rescue procurement shows lowest.
Supply Chain Analysis
China, Vietnam, and Bangladesh anchor cut-and-sew assembly capacity for waterproof outerwear. Nylon 6,6 chip, ePTFE membrane film, and fluorine-free DWR chemistry feed from petrochemical and specialty chemical suppliers. Single-source vulnerability concentrates in Gore-Tex and eVent membrane allocation during seasonal demand spikes. Distribution runs through brand-operated digital fulfillment centers, specialty outdoor retailers, and department store concessions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ultrasonic welding technician scarcity constrains quality throughput at Vietnamese and Bangladeshi factories, creating a bottleneck that rewards early investment in vocational training partnerships or automated seam-taping equipment.
For Market Incumbents: Compound technical differentiation through captive membrane R&D partnerships with bio-based chemistry firms before ECHA dossier deadlines tighten. Secure fluorine-free DWR supply pipelines to preempt state-level disclosure law rejections in Maine and Washington. Channel control through owned repair infrastructure in Portland and Munich captures lifetime customer value multiples. For New Entrants and Emerging Players: Lead with India's sub-fifteen-percent organized retail penetration for technical rainwear, building domestic brand awareness before international competitors scale. Target Maharashtra and Karnataka industrial corridors for cut-and-sew assembly partnerships. Go-to-market through municipal procurement specifications favoring recycled polyester content. For Investors and Strategic Acquirers: Regional scale fabricators with backward integration into membrane lamination represent prime acquisition targets for mid-cap outdoor brand portfolios. Long-term viability hinges on compliance positioning ahead of REACH Annex XVII enforcement waves. Watch ECHA validation study queue lengths as inflection indicator for product launch window compression.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Chemistry Transition | REACH and EPA PFAS restrictions force material reformulation across membrane suppliers. |
| Repair Infrastructure Buildout | Patagonia's Worn Wear model demonstrates margin capture from lifetime garment servicing. |
| Technical Fabric Cluster Expansion | Zhejiang and Jiangsu mills reduce lead times for Asia-Pacific brands and export orders. |
| Digital Product Passport Compliance | EU Green Deal labeling creates differentiation for verified recycled content supply chains. |
| Vocational Training Partnerships | Ultrasonic welding technician scarcity constrains quality throughput at Vietnamese factories. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with technical fabric mill managers, outdoor brand supply chain directors, specialty retail buyers, and membrane R&D chemists; and secondary validation through customs trade records, ECHA regulatory filings, bluesign certification databases, and SEC apparel company disclosures. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Across the analysis window, forecasts model rain coat demand by type (parka, anorak, trench, poncho), material chemistry tier, end-user demographic, and distribution channel. CAGRs derive from regression analysis against outdoor participation rates, regulatory compliance cost curves, and petrochemical price indices. Segment-level projections incorporate membrane supplier allocation patterns and repair-service adoption trajectories.
The analysis sits within stated boundaries; outcomes outside sustained PFAS phase-out timelines or abrupt petrochemical price shocks would require recalibration. Forecasts reflect assumptions on technical fabric cluster capacity expansion and vocational training program scaling. Recalibration cycles align with material shifts in REACH enforcement protocols and state-level disclosure law adoptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective and Workwear Textiles
Workwear Market
Protective and Workwear Textiles
Garment Active Insulation Market
Protective and Workwear Textiles
Industrial Hand Gloves Market
Protective and Workwear Textiles
Global Protective Fabrics Market
Protective and Workwear Textiles
Global Flame Resistant Fabric Market
Protective and Workwear Textiles
Water-Proof Dust Covers Market
Protective and Workwear Textiles
Fashion Face Mask Market
Protective and Workwear Textiles
Rainwear Market
Protective and Workwear Textiles
Personal Protective Textile Market
Protective and Workwear Textiles
Percussion Vests Market
Protective and Workwear Textiles
Industrial Curtains Market
Protective and Workwear Textiles
US UPF Sun Protective Clothing Market
Protective and Workwear Textiles
Flame Resistant (FR) Coveralls Market
Protective and Workwear Textiles
Fabric Protection Market
Protective and Workwear Textiles
Winter Wear Market
Protective and Workwear Textiles
Welding Curtains Market