
 Stain-Resistant Fabric Market | 2026-2036
Stain-Resistant Fabric Market Size, Share, and Industry Trends Forecast 2026-2036
Stain-Resistant Fabric Market Analytics
Silicone-based finishes is rebalancing cost-performance trade-offs that long favored fluorocarbon chemistry. DuPont sustains technology leadership through its heritage in polymer science and application-specific formulations. Milliken & Company anchors North American manufacturing capacity with integrated finishing operations in South Carolina. Huntsman Corporation differentiates through textile effects chemistry that spans both apparel and technical fabric segments.
Stain-resistant fabric denotes textile substrates engineered with surface treatments or inherent fiber properties that repel liquid and particulate soiling, typically achieving oil repellency ratings of 6-8 on the AATCC 118 scale and water repellency of 90-100 on the AATCC 22 spray test. These materials serve commercial and residential end users requiring extended aesthetic life cycles under high-use conditions. Polyester dominates volume in home textiles and upholstery applications where hydrophobic fiber properties complement topical treatments. Nano Technology represents the fastest-growing technology segment as atomic-layer deposition and sol-gel processes enable thinner, more durable barriers without hand modification. Coating remains the margin pool leader in automotive interiors where OEM qualification cycles create sticky supply relationships.
The EPA oversees chemical substance reporting under TSCA Section 5 for new stain-resistant chemistries entering US commerce, while the EU REACH framework restricts long-chain perfluorinated compounds that historically anchored performance standards. ISO 14419 specifies oil repellency benchmarking that shapes product claims and cross-border trade acceptance. Stakeholders must monitor regulatory phase-out timelines and alternative chemistry validation costs as they rebalance formulation portfolios.
Market Dynamics
REACH restrictions on perfluorinated chemistry are forcing European formulators to rebuild supply chains around silicone and bio-based alternatives, compressing lead times while opening specification windows for new entrants.
Growth Catalysts
- Hospitality Durability Mandates:North Carolina textile mills are expanding finishing capacity to serve Florida and Nevada casino-hotel operators tightening upholstery replacement cycles.
- Nano Technology Maturation:Atomic-layer deposition processes enable sub-micron barrier films without hand modification, unlocking premium residential furniture applications.
- REACH Phase-Out Timeline:The European Union's restriction on long-chain perfluorinated compounds redirects R&D spending toward compliant chemistry validation.
Market Restraints
- Fluorocarbon Input Cost Volatility:Legacy C6 chemistry feedstock prices fluctuate with fluorosurfactant supply concentration in Chinese manufacturing zones.
- Automotive OEM Qualification Cycles:Tier-1 seating suppliers face 18-36 month validation timelines that freeze formulation switches mid-contract.
- Performance-Hand Trade-Off:Silicone-based finishes struggle to match fluorocarbon oil repellency above AATCC 118 grade 6 in heavy-duty commercial upholstery.
Strategic Opportunities
- India Hospitality Build-Out:New Delhi and Mumbai hotel operators are specifying performance fabrics for the first time as international brand standards penetrate the market.
- Bio-Based Chemistry Convergence:Plant-derived hydrophobic agents combined with enzymatic surface activation offer paths to carbon-neutral certification.
- Direct-to-Designer Channels:North Carolina finishers are bypassing traditional distributors to capture specification authority from hospitality interior designers.
Industry Challenges
- Formulation Chemist Scarcity:Talent pools with expertise in both textile engineering and fluorine-free polymer science concentrate in South Carolina and Massachusetts.
- Cross-Border Certification Complexity:ISO 14419 oil repellency benchmarking diverges from EPA TSCA Section 5 notification timelines, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stain-Resistant Fabric Market |
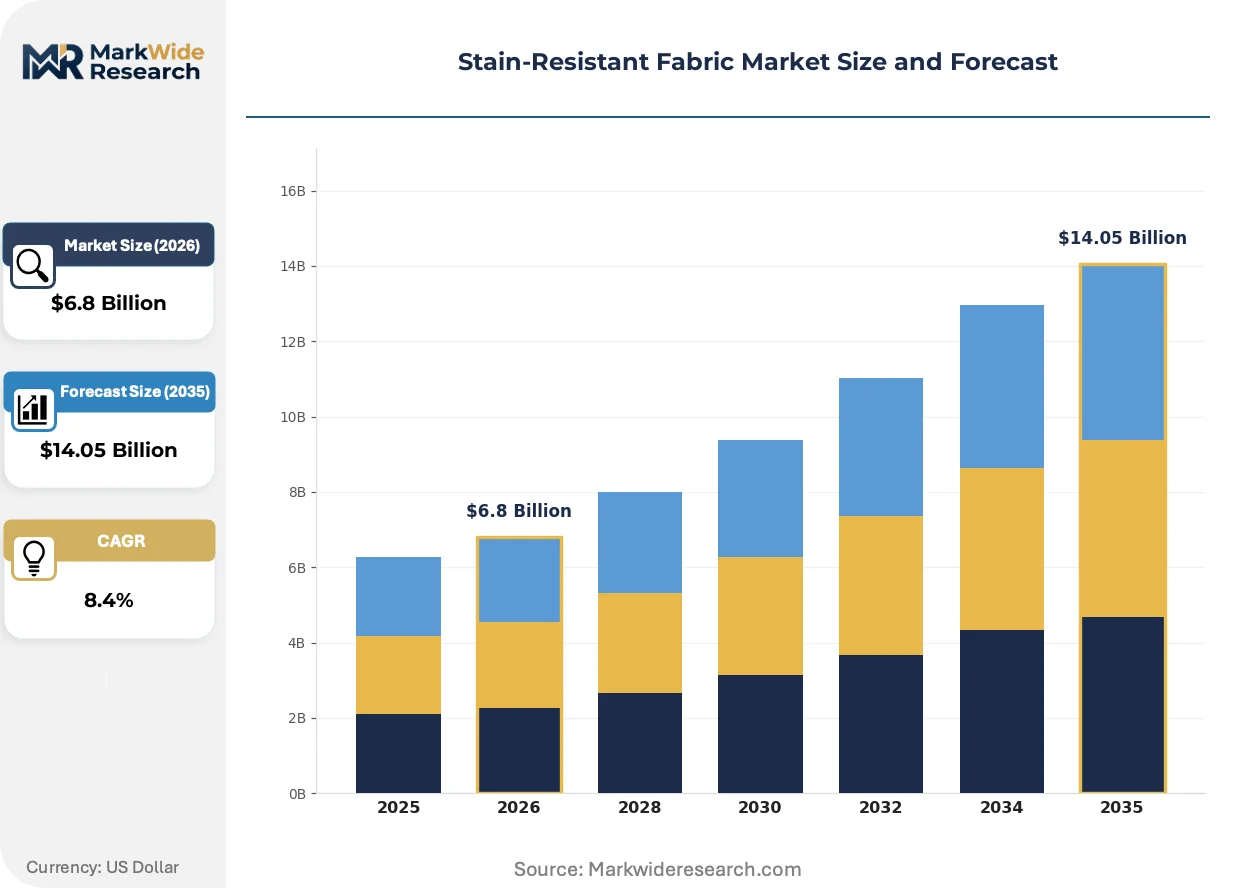
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, Nylon, Cotton, Blends Application: Home Textiles, Upholstery, Clothing, Automotive Interiors End User: Residential, Commercial, Industrial, Hospitality Technology: Coating, Nano Technology, Weaving, Finishing |
| Companies Covered | Invista, The Chemours Company, Milliken & Company, Crypton, Nanotex, DuPont, Huntsman Corporation, Revolution Performance Fabric, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stain-Resistant Fabric Market Evolving Landscape
Atomic-scale deposition methods and plant-derived hydrophobic agents are rewriting performance benchmarks while regulatory phase-outs accelerate chemistry turnover across finishing operations.
Sol-gel nano-coating is absorbing the technical validation burden previously carried by fluorocarbon topcoats, with hospitality procurement teams in Nevada and Florida running parallel qualification trials. The technology enables thinner barrier layers that preserve fabric hand while meeting AATCC 118 grade 7 oil repellency thresholds. Equipment retrofits at South Carolina finishing plants are absorbing capital budgets that might otherwise expand solvent-based coating capacity.
REACH restrictions on perfluorinated compounds are compressing the viable chemistry set for European upholstery suppliers, with ECHA enforcement timelines accelerating reformulation programs. The regulation forces dual-track R&D spending as manufacturers maintain legacy production for export markets while building silicone-based capacity for EU compliance. Italian and German automotive seating suppliers face the steepest requalification burdens given existing OEM contracts specifying fluorocarbon performance.
Hospitality procurement teams are consolidating vendor panels around integrated finishers with in-house polymer development capabilities, displacing arm's-length chemical supplier relationships. Casino operators in Nevada and Florida now require mill-direct certification documentation rather than distributor attestations. This concentration of specification authority favors South Carolina operations with captive laboratory facilities over merchant finishers dependent on external formulation support.
Stain-Resistant Fabric Market Segmentation
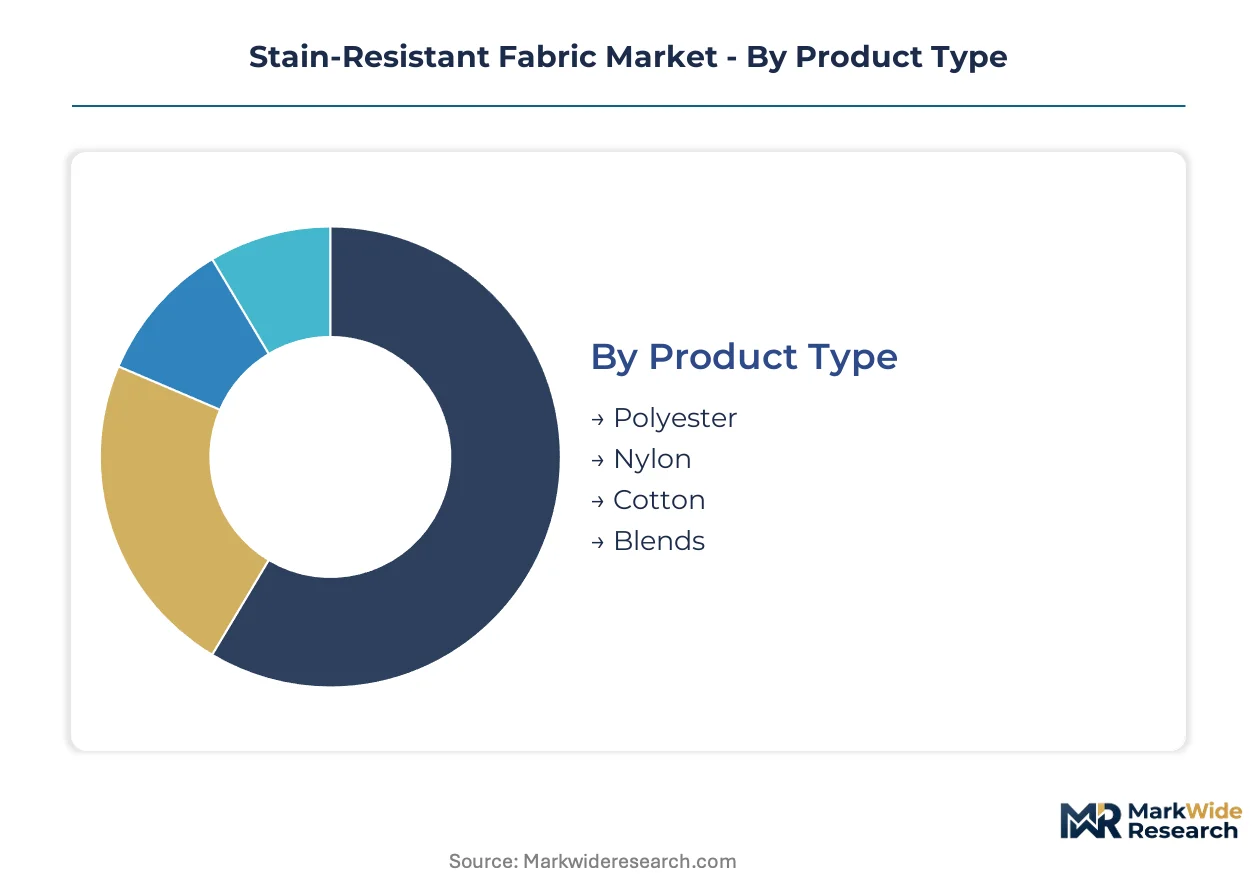
Segmentation in stain-resistant fabrics reveals how performance requirements, regulatory constraints, and end-use durability standards fragment demand across distinct chemistry and substrate combinations. Procurement patterns diverge sharply between hospitality operators seeking multi-year upholstery cycles and residential buyers prioritizing hand feel over oil repellency grades.
Product Type:
Buyers in this category differentiate primarily by fiber hydrophobicity and compatibility with topical finishing systems.
- Polyester:Hydrophobic fiber properties complement fluorocarbon and silicone topical treatments, achieving AATCC 118 grade 6-8 oil repellency without hand modification. Demand concentrates in home textiles and upholstery applications across North Carolina textile mills serving Florida hospitality hubs.
- Nylon:Superior abrasion resistance supports high-traffic commercial seating, though amine end-groups require specialized pretreatment before stain-resistant finishing. Casino operators in Nevada specify nylon-polyester blends for gaming floor furniture replacement cycles.
- Cotton:Cellulosic substrates demand heavier finish add-ons to overcome inherent absorbency, limiting commercial adoption where AATCC 22 water repellency below 80 is acceptable.
- Blends:Fiber engineering combines polyester durability with cotton aesthetics for residential furniture targeting premium price tiers.
Polyester leads volumes today; Nano Technology-enhanced nylon is gaining share fastest.
Application:
Specification authority in this category rests with distinct gatekeepers: interior designers for residential, procurement directors for hospitality, and Tier-1 suppliers for automotive.
- Home Textiles:Drapery and bedding applications prioritize water repellency over oil resistance, with AATCC 22 grade 90-100 thresholds sufficient for most residential use cases.
- Upholstery:Heavy-duty commercial seating demands AATCC 118 grade 7-8 oil repellency plus 50,000+ double rub abrasion resistance, driving silicone and nano-coating adoption in South Carolina finishing plants.
- Clothing:Performance apparel segments accept lower durability standards for improved breathability, with 20-30 wash cycle retention defining acceptable chemistry.
- Automotive Interiors:OEM qualification cycles lock formulations for 18-36 months, with seating suppliers in Germany and Italy facing steepest requalification burdens under REACH phase-out timelines.
Upholstery commands the largest revenue pool; automotive interiors exhibit the stickiest supplier relationships.
End User:
Budget authority and replacement cycle length separate buyers in this category more than technical specifications alone.
- Residential:Consumers prioritize fabric hand and aesthetic longevity over standardized test performance, with distributor channels dominating purchase pathways.
- Commercial:Office furniture operators specify mid-tier AATCC 118 grade 5-6 oil repellency with 3-5 year replacement horizons, balancing durability against first cost.
- Industrial:Workwear and protective applications demand chemical resistance beyond standard stain repellency, overlapping with technical textile specifications.
- Hospitality:Casino-hotel operators in Nevada and Florida now require mill-direct certification and 7+ year upholstery lifecycles, consolidating vendor panels around integrated finishers with captive laboratories.
Hospitality drives specification innovation; residential channels move the highest fabric volumes.
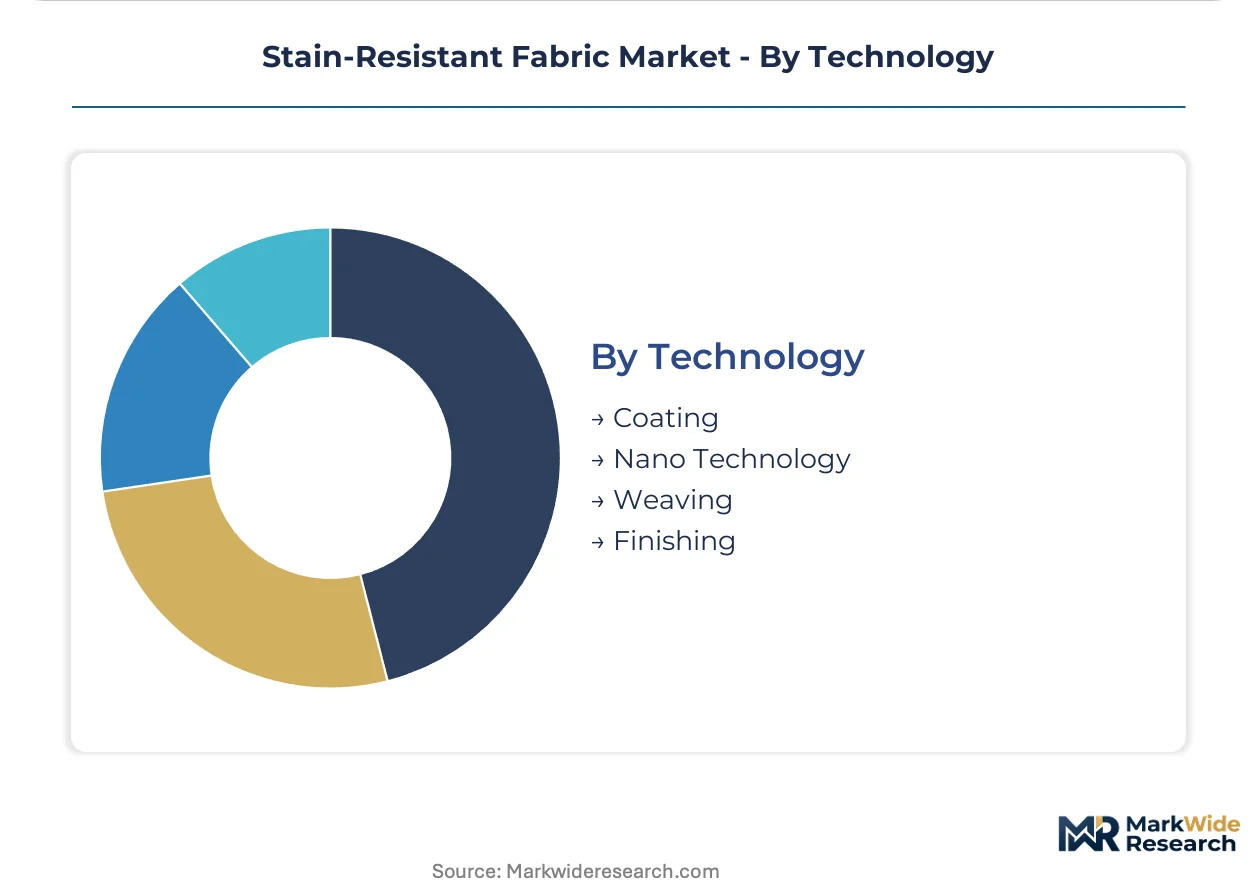
Technology:
Capital intensity and chemistry validation timelines create divergent competitive moats across finishing approaches.
- Coating:Solvent-based and waterborne systems dominate automotive interiors where 50-150 micron film builds provide abrasion resistance alongside stain repellency.
- Nano Technology:Atomic-layer deposition and sol-gel processes enable sub-micron barrier films without hand modification, absorbing technical validation burden previously carried by fluorocarbon topcoats in Nevada and Florida qualification trials.
- Weaving:Inherent fiber engineering through bicomponent extrusion creates durable barriers without topical chemistry, though capital requirements limit adoption to large-scale polyester producers.
- Finishing:Conventional pad-dry-cure equipment at South Carolina plants is retrofitting for silicone-based chemistry as REACH restrictions compress viable European formulation sets.
Coating retains the broadest installed base; Nano Technology shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North Carolina's textile corridor anchors global finishing capacity, with South Carolina integrated mills and Nevada hospitality procurement hubs forming a contiguous supply chain. Regulatory divergence between EPA TSCA oversight and EU REACH phase-outs is fragmenting formulation strategies across major producing regions.
United States
Nevada casino operators and Florida hospitality groups are mandating mill-direct certification with 7-year upholstery lifecycles, consolidating procurement around captive laboratory operations. EPA TSCA Section 5 notification requirements govern new chemistry introductions. North Carolina textile mills in the Piedmont Triad are expanding silicone-based finishing lines to serve these durability mandates.
Germany
Automotive seating suppliers face the steepest REACH requalification burdens as ECHA enforcement timelines accelerate fluorocarbon phase-outs. The EU Green Deal's chemical sustainability criteria are redirecting R&D budgets toward bio-based validation. Stuttgart-area Tier-1 suppliers are maintaining dual formulation tracks for export versus EU-compliant production.
China
Fluorosurfactant feedstock concentration in eastern manufacturing zones is driving input cost volatility for legacy C6 chemistry. MIIT industrial standards for textile chemicals are tightening disclosure requirements. Zhejiang and Jiangsu province finishing plants are absorbing nano-coating equipment retrofits as export buyers demand REACH-compliant alternatives.
India
New Delhi and Mumbai hotel operators are specifying performance fabrics for the first time as international brand standards penetrate the hospitality sector. BIS textile standards are evolving to incorporate AATCC-equivalent test methods. Gujarat chemical clusters are building silicone formulation capacity to serve domestic upholstery mills.
Italy
Luxury furniture manufacturers in the Brianza district are qualifying nano-enhanced finishes that preserve hand feel while meeting premium residential durability expectations. ECHA REACH restrictions are compressing viable chemistry sets for EU-bound production. Como-area finishing houses are retrofitting pad-dry-cure lines for plant-derived hydrophobic agents.
Stain-Resistant Fabric Market Competitive Landscape
Capacity expansion dominates the current landscape as integrated finishers retrofit solvent-based coating lines for waterborne and nano-deposition systems. The vendor base stratifies between global chemical conglomerates with textile effects divisions, regional merchant finishers dependent on external formulation support, and captive upholstery mills with in-house polymer development. Three archetypes define competitive positioning: polymer science heritage players, integrated manufacturing specialists, and nano-technology pure-plays. M&A activity concentrates on acquiring REACH-compliant formulation IP, while strategic partnerships between finishers and hospitality procurement directors are displacing traditional distributor relationships.
Within the polymer science heritage tier, DuPont and Huntsman Corporation exemplify formulation depth spanning apparel and technical fabric segments. Milliken & Company anchors integrated North American manufacturing with captive South Carolina finishing operations. Among specialty technology providers, Nanotex occupies a position representing atomic-scale deposition approaches that hospitality procurement teams in Nevada and Florida are actively qualifying.
| Leading Market Players |
|---|
| Invista |
| The Chemours Company |
| Milliken & Company |
| Crypton |
| Nanotex |
| DuPont |
| Huntsman Corporation |
| Revolution Performance Fabric |
| 3M |
| Others |
Value Network & Pricing Analysis
Fluorosurfactant feedstock indices in eastern Chinese manufacturing zones cascade through three distinct pricing tiers as REACH-compliant silicone chemistry commands premium positioning over legacy C6 formulations. Hospitality procurement directors in Nevada and Florida now negotiate mill-direct contracts that internalize certification costs previously borne by distributors, compressing margin pools for merchant finishers without captive laboratory assets.
Pricing Analysis
Input-cost pass-through from fluorocarbon feedstock volatility concentrates margin pressure on mid-tier finishers lacking backward integration into polymer synthesis. Three-tier pricing structure across premium nano-enhanced, standard silicone-based, and economy-grade fluorocarbon levels separates specification-grade hospitality contracts from residential distributor channels. Cost compression in standard tiers is intensifying because South Carolina integrated mills are absorbing equipment retrofit expenses for sol-gel deposition capacity. Commercial hospitality buyers exhibit lowest price sensitivity given replacement cycle guarantees, while residential consumers through distributor channels drive volume at compressed margins.
Supply Chain Analysis
Reverse-logistics flows for hospitality upholstery refurbishment create secondary material streams that South Carolina finishers are qualifying for downgraded residential applications. Supply concentration rests on China for fluorosurfactant intermediates, the United States for integrated finishing capacity in the Carolinas, and Italy for luxury furniture textile production. Raw material dependencies center on perfluorinated feedstocks, silicone polymer resins, and nano-precursor sol-gel formulations. Single-source vulnerability in Chinese fluorosurfactant zones exposes formulators to input cost spikes. Distribution runs through mill-direct specification channels for hospitality, traditional distributor networks for residential, and Tier-1 supplier integration for automotive seating.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The stain-resistant fabric market functions as a stable compounder anchored by replacement-cycle mandates from commercial hospitality operators that institutionalize demand regardless of macroeconomic cyclicality.
For Market Incumbents: Anchor specification authority by deepening captive laboratory investment in South Carolina and Nevada corridor proximity, while accelerating silicone-based formulation validation ahead of ECHA enforcement timelines. Defend against nano-technology pure-plays by locking hospitality procurement directors into multi-year upholstery lifecycle contracts with embedded certification documentation. Prioritize backward integration into polymer resin production to insulate margin pools from Chinese fluorosurfactant volatility. For New Entrants and Emerging Players: Atomic-layer deposition expertise offers entry into premium residential furniture segments where Italian luxury manufacturers prioritize hand-feel preservation. White-space concentration sits with India hospitality build-outs in New Delhi and Mumbai where international brand standards are penetrating without established supplier relationships. Target direct-to-designer specification channels in North Carolina's hospitality interior design clusters as the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated finishers possessing REACH-compliant formulation IP and mill-direct hospitality relationships. Long-term viability over a 5-10 year horizon favors assets with demonstrated ECHA requalification execution and captive South Carolina manufacturing footprints. Monitor ECHA enforcement acceleration and Florida-Nevada hospitality procurement consolidation as the critical inflection signal for valuation step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Resin Production | Insulates margin pools from Chinese fluorosurfactant supply concentration and price volatility. |
| REACH-Compliant Formulation Validation | Unlocks EU hospitality and automotive seating contracts as ECHA phase-out timelines accelerate. |
| Mill-Direct Specification Channel Development | Bypasses distributor margin extraction and captures authority from Nevada and Florida procurement directors. |
| Nano-Coating Equipment Retrofit | Enables sub-micron barrier films that preserve fabric hand for premium residential furniture applications. |
| India Hospitality Market Entry | Positions for first-mover advantage as New Delhi and Mumbai hotel operators adopt international brand standards. |
Research Methodology
Direct dialogue with textile finishing plant managers, hospitality procurement directors in Nevada and Florida, ECHA regulatory affairs specialists, and polymer chemistry R&D directors grounded qualitative insights. Secondary validation drew from EPA TSCA Section 5 filings, ECHA restriction proposal documentation, AATCC test method archives, and SEC 10-K disclosures from listed chemical conglomerates. Bottom-up demand modeling across upholstery replacement cycles triangulated with top-down chemistry spend analysis.
Bottom-up segment modeling tracked fiber substrate volumes, finishing technology adoption curves, and end-use replacement frequencies across the projection horizon. Segmentation dimensions spanned product type, application, technology, and end-user budget authority. CAGRs derived from regression against historical hospitality construction permits, automotive production forecasts, and residential furniture shipment data. Industry-specific inputs included AATCC 118 oil repellency grade migration patterns and REACH-compliant chemistry validation timelines.
The model holds under stable ECHA enforcement schedules and continued hospitality durability mandate expansion; deviation in fluorosurfactant supply disruption or automotive OEM requalification acceleration would shift volume and value trajectories. Forecasts embed assumptions regarding silicone chemistry performance parity achievement and nano-coating equipment adoption rates. Practitioners should monitor ECHA restriction timeline announcements and Nevada-Florida hospitality procurement panel consolidation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective and Workwear Textiles
Rainwear Market
Protective and Workwear Textiles
Asbestos Gloves Market
Protective and Workwear Textiles
Global Fire Resistant Fabric Market
Protective and Workwear Textiles
Winter Wear Market
Protective and Workwear Textiles
Compression Garments Market
Protective and Workwear Textiles
Workwear Accessories Market
Protective and Workwear Textiles
Camouflage Suit Market
Protective and Workwear Textiles
Percussion Vests Market
Protective and Workwear Textiles
Flame Resistant (FR) Coveralls Market
Protective and Workwear Textiles
Fashion Face Mask Market
Protective and Workwear Textiles
Welding Curtains Market
Protective and Workwear Textiles
Sun Protective Clothing Market
Protective and Workwear Textiles
Garment Active Insulation Market
Protective and Workwear Textiles
North America Western Wear Market
Protective and Workwear Textiles
Global Flame Resistant Fabric Market
Protective and Workwear Textiles
Personal Protective Textile Market