
 Biometric Gun Safe Market | 2026-2036
Biometric Gun Safe Market Size, Share, and Industry Trends Forecast 2026-2036
Biometric Gun Safe Market Insights
Subscription-based financing and lease-to-own programs for premium biometric safes is reshaping competitive dynamics, allowing mid-tier brands to challenge incumbents without heavy balance sheets. Vaultek leverages direct-to-consumer channel control to maintain pricing power across portable and vault categories. Hornady anchors its position through ammunition-to-storage bundling that sustains repeat engagement. Liberty Safe dominates large-format floor installation with manufacturing scale that competitors struggle to replicate.
A biometric gun safe employs electromechanical locking mechanisms activated by unique biological identifiers, typically capacitive fingerprint sensors with sub-500-millisecond authentication cycles and tamper-alert circuitry, designed to prevent unauthorized firearm access while enabling rapid owner retrieval. Portable safes lead volume shipments among product types due to apartment-dwelling gun owners and travel-use cases, though wall-mounted units command higher per-unit margins from permanent residential installations. Fingerprint recognition technology occupies the dominant share of authentication methods, while smart locking systems integrating Bluetooth and Wi-Fi represent the fastest-growing technology segment as remote monitoring features attract law enforcement and commercial enterprise buyers.
The Consumer Product Safety Commission and ASTM International standards govern mechanical integrity and biometric false-acceptance rates in the United States, while state legislatures in California and New York enforce safe storage statutes that directly stimulate replacement demand. The FBI's National Instant Criminal Background Check System indirectly shapes market scope by tracking ownership expansion patterns that correlate with safe purchases. Stakeholders must monitor pending federal safe storage legislation and evolving biometric accuracy standards to anticipate certification requirements that will determine market access.
Market Dynamics
State-level safe storage mandates in California, New York, and Massachusetts are compressing replacement cycles and redirecting procurement toward quick-access biometric systems that satisfy statutory access restrictions while preserving retrieval speed for authorized users.
Growth Catalysts
- California DOJ Roster Mandate:The state's certified safe roster eliminates non-compliant products from lawful sale, creating guaranteed replacement demand as older mechanical safes phase out of eligibility.
- Capacitive Fingerprint Sensors:Sub-500-millisecond authentication cycles now match or exceed mechanical lock speeds, removing the historical speed penalty that suppressed biometric adoption among defensive firearm owners.
- Apartment-Dwelling Gun Owners:Urban residential density restrictions on permanent installations drive portable safe volumes, with landlords in Chicago, Seattle, and Denver increasingly requiring tenant-owned storage solutions.
Market Restraints
- Semiconductor Supply Concentration:Fingerprint sensor ASIC fabrication concentrates in Taiwan and South Korea foundries, exposing lead times to geopolitical friction and foundry allocation priorities.
- ASTM F2957 Certification Burden:Mechanical integrity testing and false-acceptance rate validation add six-to-nine month pre-market timelines that mechanical lock competitors bypass entirely.
- Keypad-and-Key Hybrids:Lower-unit-cost electromechanical alternatives without biometric components retain price-sensitive segments, particularly in rural markets with limited law enforcement response requirements.
Strategic Opportunities
- Bluetooth-WiFi Convergence:Remote monitoring capabilities attract law enforcement agency armory contracts and commercial security buyers seeking audit trails and unauthorized-access alerts.
- Lease-to-Own Financing:Subscription models reduce upfront capital barriers for mid-tier residential buyers, enabling brand switching without incumbent balance-sheet advantages.
- Wall-Mounted Premium Tier:Permanent residential installations command margin premiums over portable units, with custom cabinetry integration creating stickier customer relationships.
Industry Challenges
- Embedded Firmware Talent Scarcity:Biometric algorithm optimization, tamper-detection circuitry, and wireless stack integration require skill sets concentrated in consumer electronics hubs, not traditional safe manufacturing regions.
- False-Rejection Rate Tuning:Balancing security against accessibility demands extensive field calibration; units too sensitive lock out authorized users during high-stress retrieval scenarios, generating liability exposure.
- Legacy Mechanical Inventory Stranding:Distributors and retailers face write-downs on non-compliant mechanical inventory as state rosters tighten, compressing working capital for biometric SKU expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biometric Gun Safe Market |
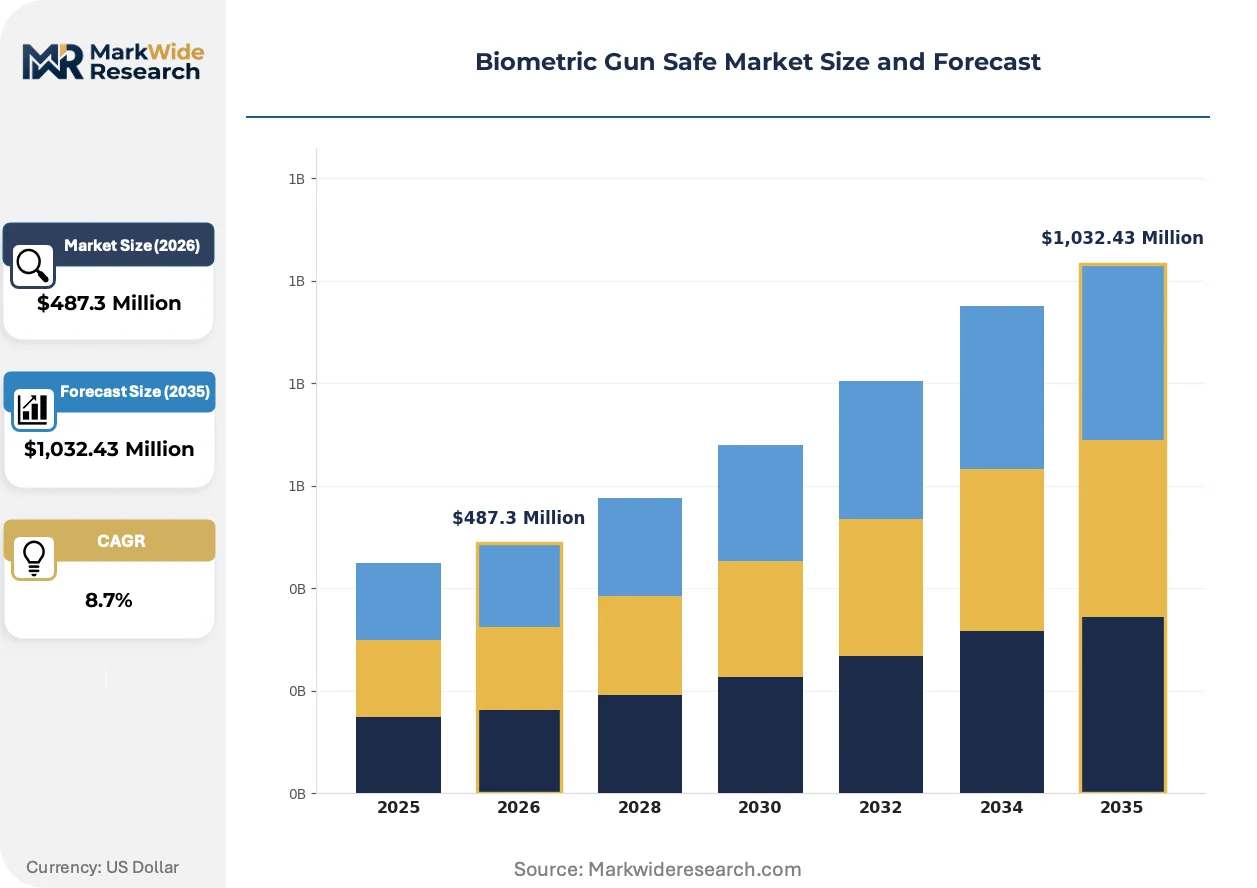
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Safes, Wall-Mounted Safes, Vaults, Biometric Locks Technology: Fingerprint Recognition, Iris Scanning, Facial Recognition, Smart Locking Systems End User: Residential Users, Law Enforcement, Military, Commercial Enterprises Installation: In-Wall Installation, Floor Installation, Surface Mount, Free-Standing |
| Companies Covered | Vaultek, Hornady, Barska, SentrySafe, Onnais, Liberty Safe, Cannon Safe, Fort Knox, Stack-On Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biometric Gun Safe Market Trends and Innovations
Authentication architecture is migrating from standalone electromechanical modules toward networked, sensor-fusion platforms that integrate environmental monitoring and remote management capabilities.
Multi-factor biometric fusion is virtualizing the authentication layer in premium installations. Capacitive fingerprint modules now pair with capacitive touch sensors and accelerometer-based tamper detection to create behavioral signatures. Law enforcement armories and commercial security directors in Texas and Florida are piloting these systems for chain-of-custody documentation. This convergence is virtualizing hardware differentiation into software-configurable policy engines that vendors update post-installation.
ASTM International is revising biometric performance standards to address presentation attack detection and environmental resilience testing. The draft framework expands false-acceptance rate validation to include spoofed fingerprint films and temperature-extreme operation. California and New York legislators are referencing these standards in pending safe storage statute amendments. Residential buyers in these states face prospective retrofit requirements if current units fail anticipated certification tiers.
Direct-to-consumer channel capture is fragmenting traditional sporting goods and firearms retail distribution. Vaultek and comparable brands bypass distributor markups through owned e-commerce platforms and social media targeting. Subscription-based ownership models and lease-to-own financing now originate through these channels, not FFL-adjacent retail. This pattern concentrates in suburban and exurban markets where buyers research extensively online before purchase.
Biometric Gun Safe Market Segmentation
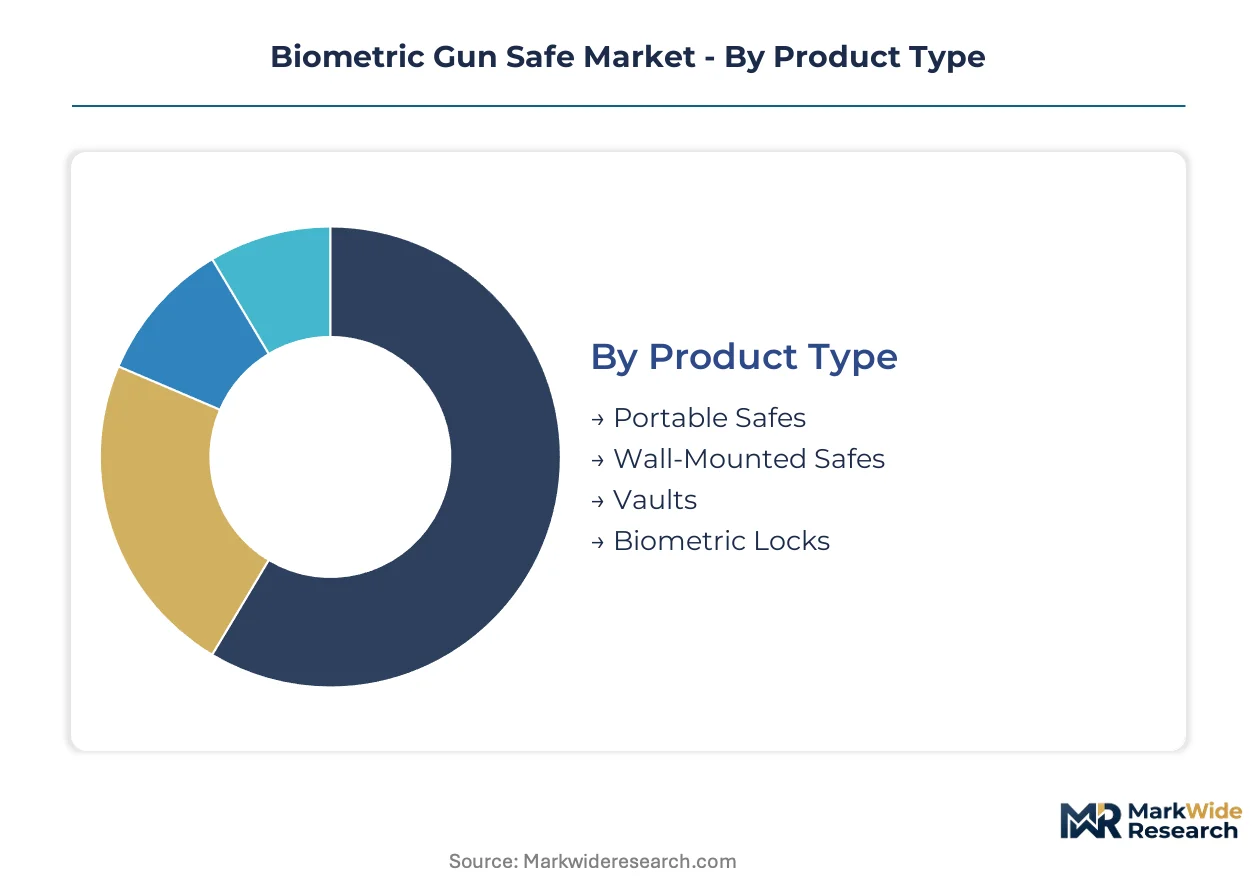
Biometric gun safe segmentation reveals divergent engineering priorities across use cases. Portable units optimize for speed and concealment, while permanent installations emphasize structural integrity and integration with residential architecture.
Product Type:
Mature formats dominate revenue, yet emerging configurations are capturing apartment-dwelling and travel-oriented demand.
- Portable Safes:Compact electromechanical enclosures weighing under 10 pounds, typically with tether cables and TSA-compliant dimensions. Chicago, Seattle, and Denver landlords increasingly mandate tenant-owned portable storage, compressing replacement cycles for urban gun owners.
- Wall-Mounted Safes:Recessed or surface-mounted steel cabinets with biometric modules integrated into door panels. Custom cabinetry integration in California and New York suburban markets commands margin premiums through permanent residential installations.
- Vaults:Large-format floor-standing units with reinforced door jambs and fire-resistant liners. Liberty Safe's manufacturing scale in this category creates replication barriers for mid-tier competitors.
- Biometric Locks:Retrofit modules converting mechanical safes to fingerprint-activated systems. California DOJ roster mandates accelerate replacement demand as older mechanical units phase out of eligibility.
Portable safes retain volume leadership; wall-mounted units hold the steepest expansion curve.
Technology:
Cost tier stratification separates proven capacitive sensors from premium multi-modal systems.
- Fingerprint Recognition:Capacitive sensors with sub-500-millisecond authentication cycles and sub-0.001% false-acceptance rates. Taiwan and South Korea foundry concentration for fingerprint ASICs exposes lead times to geopolitical friction.
- Smart Locking Systems:Bluetooth-WiFi convergence enabling remote monitoring, audit trails, and unauthorized-access alerts. Texas and Florida law enforcement armories are piloting these platforms for chain-of-custody documentation.
- Iris Scanning:Near-infrared imaging systems with higher spoof resistance than capacitive fingerprint modules. Limited deployment due to cost premiums and environmental sensitivity to lighting conditions.
- Facial Recognition:3D structured-light or time-of-flight sensors for contactless authentication. Presentation attack detection requirements under draft ASTM standards complicate certification timelines.
Fingerprint recognition retains volume leadership; smart locking systems are expanding most quickly.
End User:
Application context determines authentication speed requirements versus audit rigor.
- Residential Users:Suburban homeowners and apartment dwellers prioritizing quick-access retrieval for defensive firearms. State safe storage mandates in California, New York, and Massachusetts redirect procurement toward biometric compliance.
- Law Enforcement:Agency armories requiring chain-of-custody documentation and multi-user access protocols. Remote monitoring capabilities attract procurement officers seeking unauthorized-access alerts.
- Military:Armory installations with hardened specifications for environmental resilience and tamper detection. False-rejection rate tuning demands extensive field calibration for high-stress retrieval scenarios.
- Commercial Enterprises:Security departments in financial services and critical infrastructure managing contractor firearm access. Audit trail requirements drive smart locking system adoption over standalone biometric modules.
Residential users retain volume leadership; law enforcement agencies hold the steepest expansion curve.
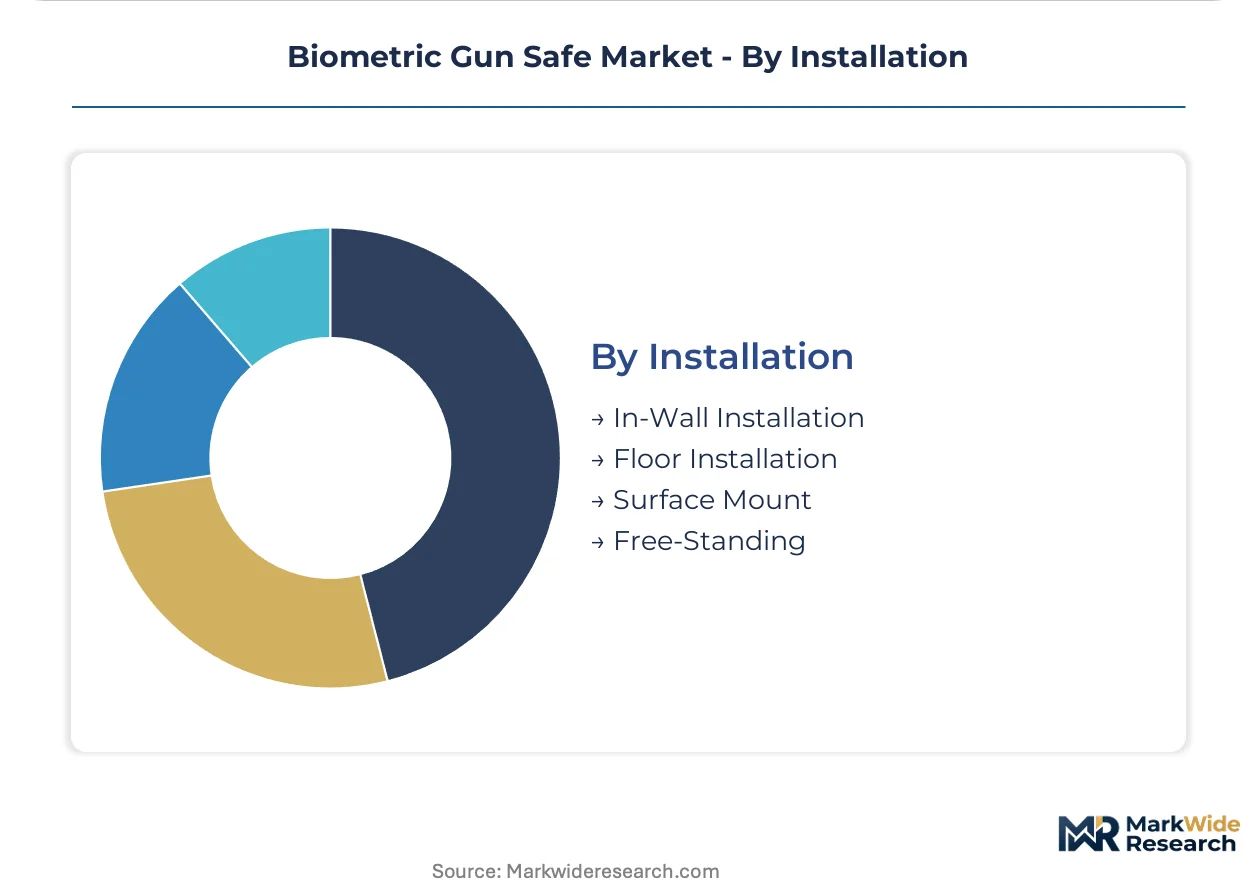
Installation:
Customer type separates permanent residential investments from flexible deployment options.
- Surface Mount:Bracket-attached units for rapid installation without structural modification. Rental property restrictions in dense urban markets sustain demand for non-permanent solutions.
- Free-Standing:Furniture-integrated or standalone vaults requiring no wall penetration. Floor installation dominates large-format procurement, with Liberty Safe's manufacturing scale creating replication barriers.
- In-Wall Installation:Recessed mounting between studs with flush-finish door panels. Custom cabinetry integration in premium suburban markets creates stickier customer relationships.
- Floor Installation:Bolt-down vaults with reinforced anchoring for theft resistance. Permanent residential installations command margin premiums over portable alternatives.
Free-standing units retain volume leadership; in-wall installation holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential homeowners concentrate procurement across jurisdictions with tightening firearm storage mandates. State-level certification requirements and quick-access biometric preferences reshape demand geography.
United States
State safe storage statutes in California, New York, and Massachusetts compress replacement cycles. The California DOJ certified safe roster eliminates non-compliant mechanical products from lawful sale. Suburban markets in Orange County and Dallas-Fort Worth drive wall-mounted premium installations with custom cabinetry integration.
Canada
Urban apartment dwellers in Toronto and Vancouver sustain portable safe volumes under landlord-mandated storage policies. The country's national firearms regulator enforces storage specifications that favor quick-access biometric systems. Montreal and Calgary security distributors report rising law enforcement agency procurement for armory chain-of-custody documentation.
Germany
Commercial security departments in Frankfurt and Munich adopt smart locking systems with remote monitoring capabilities. CE marking requirements and national firearms storage regulations create compliance-driven replacement demand. Bavarian manufacturing clusters near Nuremberg supply precision electromechanical components to biometric lock producers.
Australia
State-level firearm safe storage laws in New South Wales and Victoria redirect residential procurement toward biometric compliance. The country's national firearms registry tracks ownership expansion patterns that correlate with safe purchases. Sydney and Melbourne metropolitan markets concentrate demand for portable units among apartment-dwelling gun owners.
United Kingdom
Home Office firearms licensing requirements mandate secure storage for certificate holders. London and Birmingham security integrators report commercial enterprise adoption of audit-trail-capable smart locking systems. Manchester distribution channels serve northern England's rural estate market with large-format vault installations.
Biometric Gun Safe Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. Direct-to-consumer platforms and traditional firearms retail networks split volume distribution. Three archetypes dominate: direct-to-consumer brands with owned e-commerce, legacy safe manufacturers with manufacturing scale, and electronics-integrated specialists with firmware capabilities. Capacity expansion and strategic partnerships represent the dominant competitive moves as players address semiconductor supply constraints and certification timelines.
Within the direct-to-consumer archetype, Vaultek occupies a position exemplifying channel control through owned platforms. Hornady represents the ammunition-to-storage bundling model that sustains repeat customer engagement. Liberty Safe anchors the manufacturing-scale tier with replication barriers in large-format floor installations. These three players illustrate the competitive vectors shaping procurement relationships across residential and institutional segments.
| Leading Market Players |
|---|
| Vaultek |
| Hornady |
| Barska |
| SentrySafe |
| Onnais |
| Liberty Safe |
| Cannon Safe |
| Fort Knox |
| Stack-On Products |
| Others |
Pricing and Supply Chain Analysis
Trans-Pacific container freight corridors from Kaohsiung and Busan to Long Beach anchor landed cost structures for capacitive fingerprint sensor modules, concentrating pricing power among Taiwan and South Korea foundries while forcing downstream tiering between premium biometric vaults and economy keypad alternatives.
Pricing Analysis
Cost-plus contracts with steel and semiconductor indexation dominate procurement between safe assemblers and component suppliers. Three-tier pricing structure across premium wall-mounted installations, standard portable units, and economy mechanical-keypad hybrids separates buyers by certification grade and customization depth. Cost compression in the portable tier intensifies as Chinese OEMs flood direct-to-consumer channels with unrostered products. Rural firearm owners exhibit highest price sensitivity, while law enforcement armories prioritize audit-trail capabilities over unit economics.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Taiwan and South Korea foundries stabilize working capital for mid-tier safe assemblers facing California DOJ roster compliance timelines. Fingerprint sensor ASIC fabrication concentrates in Taiwan and South Korea, with precision steel forming anchored in domestic US and Mexican maquiladora operations. Single-source vulnerability in semiconductor foundry allocation poses structural risk amid geopolitical friction. Distribution runs through direct-to-consumer platforms and FFL-adjacent retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biometric gun safe markets increasingly resemble service businesses as subscription-based financing and firmware-update revenue layers expand faster than hardware shipments. Recurring revenue from remote monitoring subscriptions and lease-to-own programs now commands higher valuation multiples than transactional safe sales.
For Market Incumbents: Entrench manufacturing scale advantages in large-format vault production while capturing portable segment share through captive financing subsidiaries. Direct-to-consumer channel control defends against Chinese OEM entrants flooding unrostered products. ASTM F2957 certification investment creates compliance moats as state rosters tighten.
For New Entrants and Emerging Players: Establish a beachhead in Bluetooth-WiFi smart locking systems for law enforcement armory contracts. Texas and Florida agency procurement remains underpenetrated by firmware-capable specialists. Go-to-market through security integrators rather than firearms retail bypasses incumbent distributor relationships.
For Investors and Strategic Acquirers: Carve-out targets emerge from consumer electronics conglomerates with dormant safe manufacturing divisions and stranded biometric sensor inventory. Five-to-ten-year viability hinges on firmware talent retention and state roster compliance breadth. Watch California DOJ roster expansion announcements as inflection indicators for replacement demand velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Certification Investment | ASTM F2957 compliance secures California DOJ roster eligibility before statute amendments. |
| Direct-to-Consumer Platform Launch | Owned e-commerce bypasses distributor markups and captures subscription financing origination. |
| Smart Locking System Integration | Bluetooth-WiFi convergence attracts Texas and Florida law enforcement armory procurement. |
| Lease-to-Own Financing Program | Subscription models reduce upfront barriers for mid-tier residential buyers in suburban markets. |
| Foundry Partnership Agreement | Taiwan and South Korea supply agreements stabilize fingerprint sensor lead times against allocation risk. |
Research Methodology
A standing panel of safe manufacturing executives, firearms retail buyers, law enforcement procurement officers, and biometric sensor engineers provided ongoing calibration against secondary validation. Primary fieldwork combined structured interviews with distribution channel partners and regulatory affairs specialists at ASTM International and state-level DOJ certification bodies. Secondary sources included FBI NICS background check data, California DOJ roster filings, customs import records for fingerprint sensor modules, and SEC 10-K disclosures from publicly traded safe manufacturers. Bottom-up unit shipment estimates triangulated against top-down replacement demand modeling.
Scenario-bracketing around state mandate acceleration, semiconductor supply disruption, and biometric accuracy standard revisions bounded high and low growth paths across the projection horizon. Segmentation modeling spanned product type, authentication technology, end-user application, and installation method, with regional regulatory clusters treated as distinct demand environments. CAGRs derived from fitted logistic adoption curves for biometric displacement of mechanical locks, calibrated against historical safe storage statute implementation patterns.
Sensitivities concentrate around pending federal safe storage legislation, ASTM false-acceptance rate standard revisions, and foundry allocation disruptions affecting fingerprint sensor availability. Forecasts reflect assumptions about state roster expansion timelines and urban landlord mandate diffusion. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Global Law Enforcement Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Anti-Static Safety Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Global above the Waist PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Particulate Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Respiratory Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Self-Contained Breathing Apparatus (SCBA) Cylinders Market
Safety Equipment and Personal Protective Equipment (PPE)
Process Safety System Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Non Ionizing Radiation/EMF Detection, Measurement, and Safety Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Intrinsically Safe Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Biodegradable Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Household Eye Protection Lamp Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Fall Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Respirator Market
Safety Equipment and Personal Protective Equipment (PPE)
South America Protective Coating Market
Safety Equipment and Personal Protective Equipment (PPE)
Firefighter Tape Market