
 Industrial PC Market | 2026-2036
Industrial PC Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial PC Market Intelligence
Software-defined remote monitoring subscriptions is rebalancing how vendors monetize hardware deployments. Siemens AG leverages its automation software stack to bundle recurring service revenue with box PC shipments. Beckhoff Automation specializes in PC-based control architectures that anchor its position in precision manufacturing segments. Advantech Co., Ltd. extends its channel control across Asia-Pacific distribution networks for panel PC and edge gateway lines.
An industrial PC is a ruggedized computing platform engineered for continuous operation in harsh environments, typically specified with extended temperature ranges from negative forty to seventy degrees Celsius, fanless or conduction-cooled enclosures, and deterministic I/O for real-time process control. Its primary purpose is to execute automation, visualization, and data acquisition tasks where consumer-grade systems would fail from vibration, dust, or thermal stress. Panel PCs command the largest installed base due to their integration of HMI and compute in sealed front-bezel designs, while edge computing deployments represent the fastest-growing structural segment as plants push analytics closer to production lines. ARM-based architectures are gaining traction in power-constrained transportation and energy applications where wattage budgets limit x86 deployment.
FCC emissions compliance shapes product design for any industrial PC sold into US automation infrastructure, while CE marking and RoHS substance restrictions govern European market access and material selection. In Asia, JIS standards from Japan and GB standards from China create divergent certification pathways that fragment regional supply chains. Buyers must weigh whether to standardize on globally certified platforms or accept the procurement complexity of geography-specific SKUs.
Market Dynamics
Edge computing architectures are compressing decision latency in manufacturing environments, forcing industrial PC vendors to re-engineer thermal management and deterministic I/O for plant-floor deployment without climate-controlled enclosures.
Growth Catalysts
- EU F-Gas Regulation:German manufacturing facilities are accelerating embedded PC replacements to meet refrigerant monitoring compliance deadlines, creating hardware refresh cycles across automotive and chemical processing plants.
- ARM architecture migration:Transportation and energy infrastructure operators are specifying ARM-based industrial PCs for wattage-constrained deployments where x86 power budgets exceed thermal envelopes.
- Automotive assembly concentration:Edge analytics procurement in Japan and South Korea is concentrating demand for ruggedized compute nodes capable of real-time quality inspection and predictive maintenance.
Market Restraints
- Semiconductor supply concentration:Foundry capacity constraints in Taiwan and South Korea create lead time volatility for industrial-grade processors and FPGA components.
- Certification fragmentation:Divergent JIS standards in Japan and GB standards in China force vendors to maintain geography-specific SKUs, inflating inventory carrying costs.
- Extended lifecycle requirements:Industrial automation buyers demand 10-15 year supply guarantees that conflict with consumer semiconductor roadmaps, forcing costly last-time-buy negotiations.
Strategic Opportunities
- Software-defined remote monitoring:Subscription-based predictive maintenance services bundled with box PC shipments create recurring revenue streams that decouple vendor economics from hardware replacement cycles.
- Panel PC penetration in food processing:Sealed front-bezel designs with IP69K washdown ratings are displacing separate HMI and compute stacks in USDA-inspected facilities.
- CE marking convergence:Unified RoHS and electromagnetic compatibility testing is enabling single-SKU strategies for European Economic Area access, reducing certification overhead.
Industry Challenges
- Real-time programming expertise scarcity:Deterministic control software development requires specialized PLCopen and EtherCAT competency that outpaces vocational training pipeline output.
- Legacy fieldbus integration complexity:Brownfield deployments must bridge proprietary protocols from 1990s-era automation infrastructure to modern Ethernet-based industrial networks.
- FCC emissions pre-compliance testing:Unintentional radiator certification for US automation infrastructure requires iterative shielding redesigns that compress product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial PC Market |
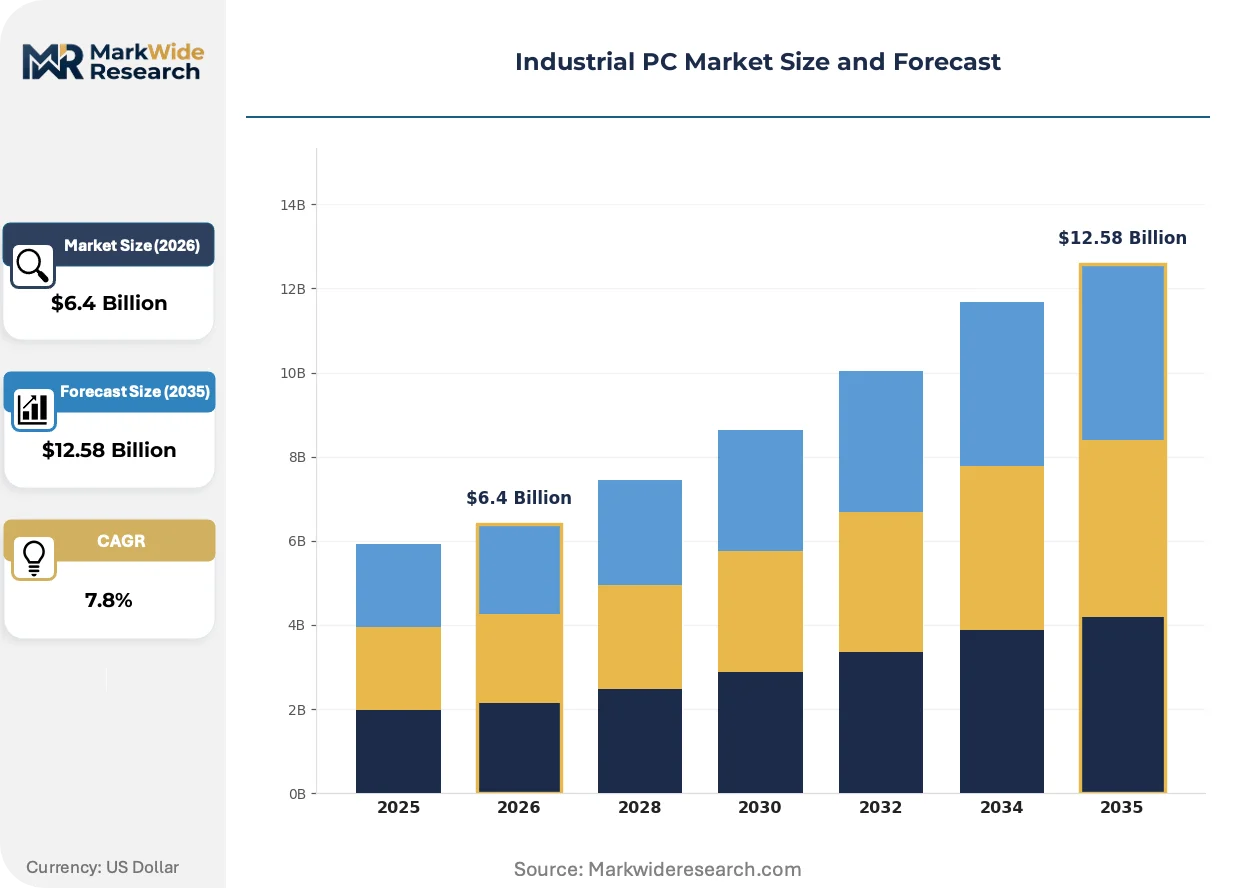
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $12.58 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panel PCs, Embedded PCs, Rackmount PCs, Box PCs Technology: X86, ARM, FPGA, Industrial IoT End User: Manufacturing, Transportation, Energy, Automation Deployment: On-Premises, Edge Computing, Cloud-Based, Hybrid |
| Companies Covered | Kontron, IEI Integration Corporation, Advantech Co., Ltd., DFI, Avalue Technology, Beckhoff Automation, Mitsubishi Electric Corporation, American Portwell Technology Inc., Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial PC Market Strategic Shifts & Innovations
Deterministic computing is migrating from centralized control rooms to machine-mounted enclosures, compressing the physical and temporal distance between sensor acquisition and actuation commands.
Time-sensitive networking is converging with OPC UA pub-sub architectures to unify motion control and IT traffic on single Ethernet cables. Automotive tier-one suppliers in Germany are piloting these converged stacks for synchronized robotic welding cells. This convergence is displacing dedicated fieldbus hardware and collapsing network infrastructure costs per production line.
Japan's METI has issued guidance tightening energy efficiency benchmarks for factory automation equipment. Industrial PC vendors must now document idle-state power draw and thermal design power across operating temperature ranges. Panel PC and edge gateway categories face the steepest redesign requirements, with Japanese distributors demanding compliance documentation before stocking new models.
Buying committees in process industries are unbundling hardware procurement from integration services, treating industrial PCs as commoditized infrastructure while negotiating separately for system integrator labor. This pattern is most pronounced in North American oil and gas automation, where EPC firms now specify compute platforms independently from the control system vendors that previously bundled them.
Industrial PC Market Segmentation
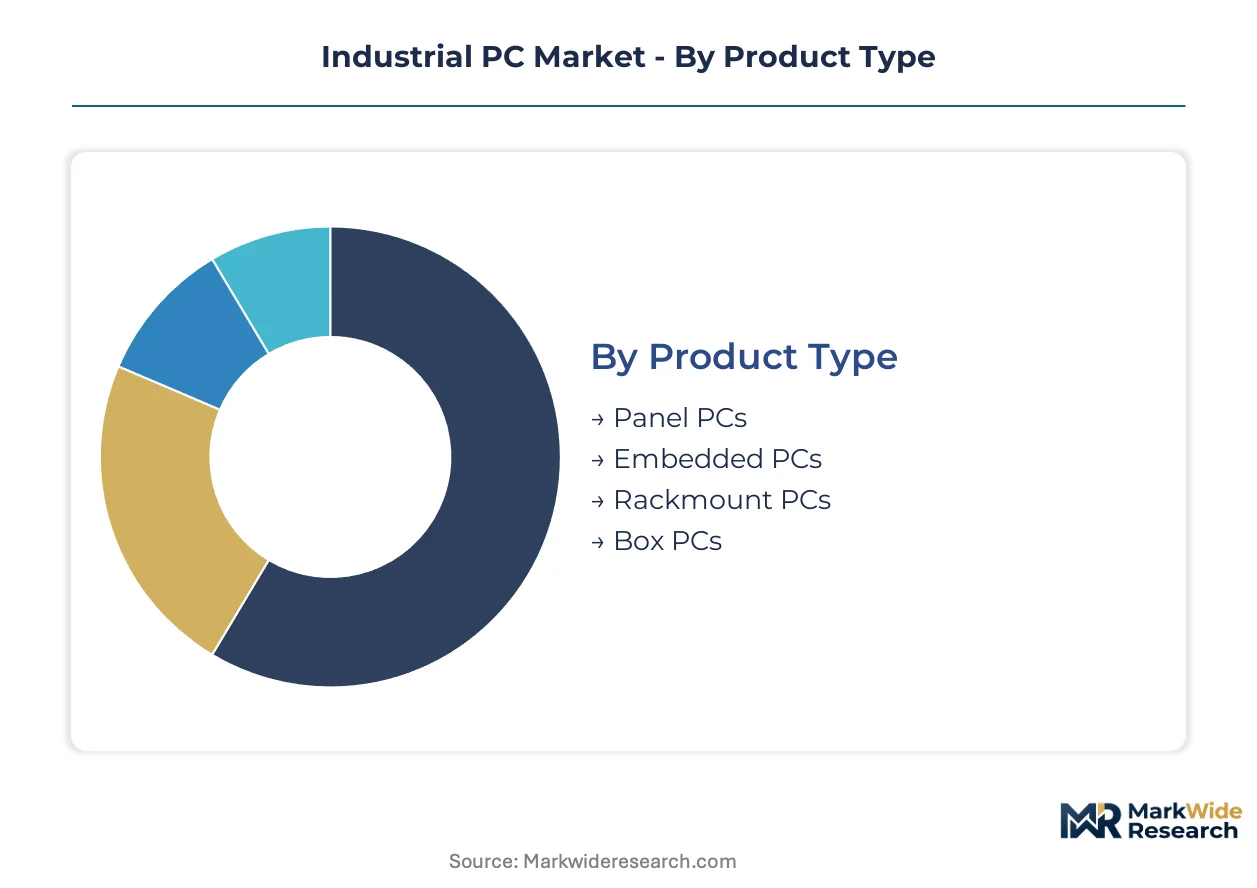
Industrial PC segmentation reflects the tension between standalone operator interfaces and deeply embedded control nodes. Procurement patterns diverge sharply between facilities seeking visible HMI integration and those prioritizing invisible compute density within machinery enclosures.
Product Type:
Integration depth separates panel-mounted operator stations from machine-embedded controllers, with thermal management and sealing requirements scaling accordingly.
- Panel PCs:Sealed front-bezel designs integrate display and compute in washdown-rated enclosures. Food processing facilities in Germany specify IP69K-rated units under EU hygiene regulations, displacing separate HMI and controller stacks.
- Embedded PCs:Compact form factors mount directly onto DIN rails or machine frames without dedicated enclosures. Automotive assembly plants in Japan deploy these for real-time quality inspection where cabinet space is constrained.
- Rackmount PCs:Standardized 19-inch chassis house compute for centralized control rooms and data acquisition hubs.
- Box PCs:Fanless aluminum enclosures with conduction cooling serve edge analytics deployments in outdoor energy infrastructure.
Volume placements concentrate in Panel PCs; the faster expansion belongs to Embedded PCs.
Technology:
Instruction set architecture determines power budgets, software ecosystem access, and deterministic control capabilities across deployment scenarios.
- X86:Dominant architecture for Windows-based HMI and legacy automation software stacks. Manufacturing facilities in South Korea standardize on Intel Core and Atom variants for compatibility with existing SCADA investments.
- ARM:RISC-based designs deliver compute-per-watt advantages for battery-backed and thermally constrained installations. Railway signaling systems in Germany specify ARM Cortex-A72 platforms under EN 50155 rolling stock standards.
- FPGA:Reconfigurable logic enables deterministic microsecond-cycle control for motion applications.
- Industrial IoT:Integrated connectivity stacks bundle edge analytics, protocol translation, and cloud telemetry in single modules.
X86 architectures retain the largest installed base; ARM platforms are climbing the fastest.
End User:
Environmental severity and regulatory exposure shape ruggedization requirements across vertical applications.
- Manufacturing:Discrete and process automation demand continuous operation amid vibration, dust, and thermal cycling. Chemical processing plants in Germany refresh embedded controllers to meet EU F-Gas refrigerant monitoring mandates.
- Transportation:Rolling stock, marine, and aerospace applications impose shock, vibration, and extended temperature specifications. Railway operators in Japan specify JIS E 5006-compliant computers for Shinkansen signaling infrastructure.
- Energy:Oil and gas, renewables, and grid infrastructure require explosion-proof or wide-temperature enclosures.
- Automation:Robotics and material handling systems prioritize deterministic I/O and real-time operating systems.
Manufacturing generates the highest shipment volumes; Transportation shows the steepest expansion trajectory.
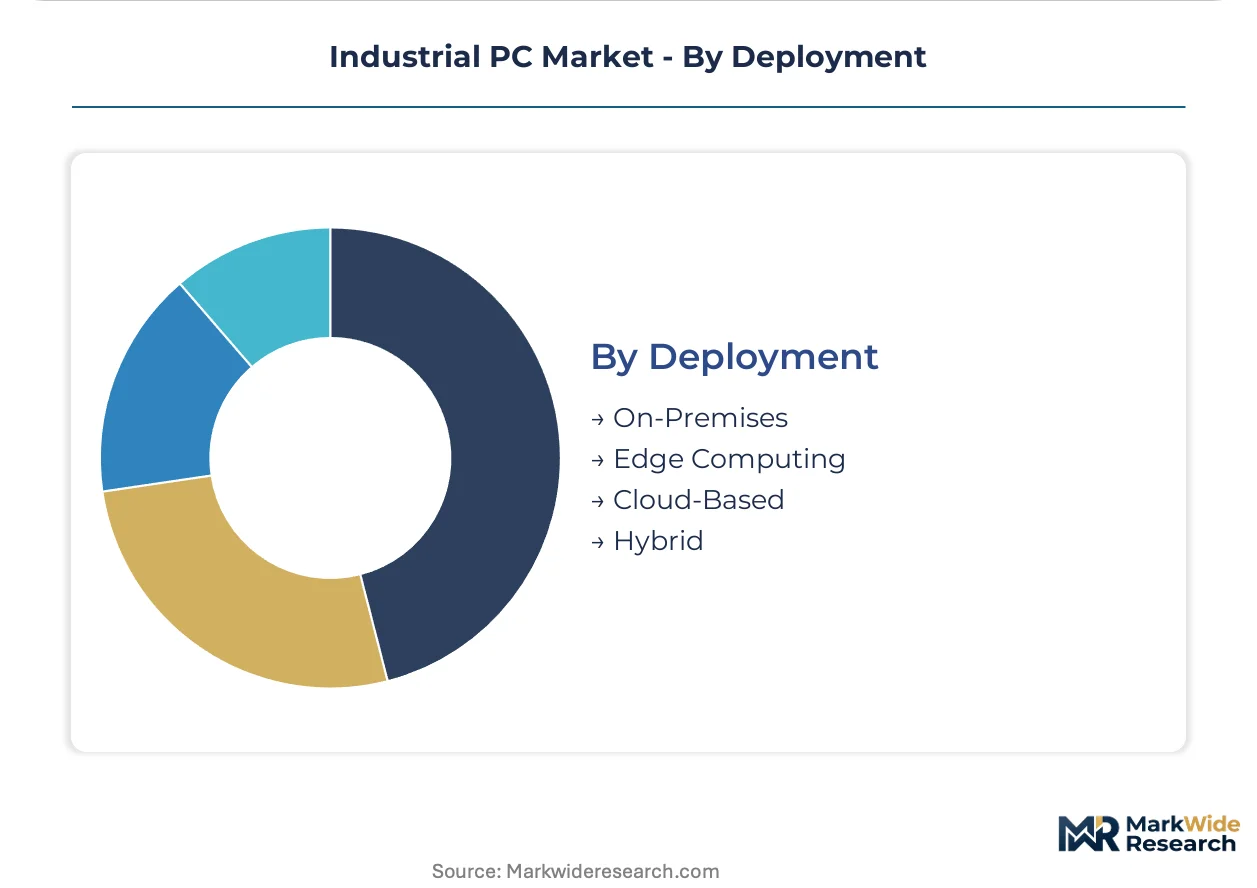
Deployment:
Data gravity and latency tolerance determine whether compute resides in climate-controlled facilities or plant-floor edge nodes.
- On-Premises:Centralized server rooms and control houses host SCADA historians and engineering workstations. North American oil and gas automation maintains this pattern for cybersecurity air-gapping.
- Edge Computing:Machine-mounted nodes execute analytics within milliseconds of sensor acquisition. South Korean automotive tier-one suppliers deploy ruggedized edge gateways for synchronized robotic welding cells.
- Cloud-Based:SaaS visualization and remote diagnostics reduce on-site compute footprints.
- Hybrid:Tiered architectures balance real-time control at the edge with optimization analytics in cloud or enterprise data centers.
On-Premises deployments retain the largest installed base; Edge Computing configurations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany produces industrial automation equipment at scale while importing specialized compute components from Asian foundries. Japanese and South Korean facilities consume the highest density of edge-grade PCs per production line. Chinese assembly plants now source a growing share of ARM-based controllers from domestic designers.
Germany
Automotive OEMs in Stuttgart and Wolfsburg refresh embedded controllers to meet EU F-Gas refrigerant monitoring deadlines. The F-Gas Regulation mandates leak detection systems across chemical processing and cold chain logistics. Bavarian automation integrators bundle panel PCs with predictive maintenance software for food processing clients.
Japan
METI energy efficiency benchmarks now require idle-state power documentation for factory automation equipment. Railway operators specify JIS E 5006-compliant computers for Shinkansen signaling infrastructure in the Tokaido corridor. Nagoya-area automotive tier-one suppliers deploy edge gateways for synchronized robotic welding cells.
South Korea
Hyundai Motor Group and battery cell manufacturers concentrate procurement of ruggedized compute nodes for real-time quality inspection. MFDS pharmaceutical manufacturing guidelines drive sealed panel PC deployments in biologics production. Busan-Ulsan industrial clusters favor x86 architectures for SCADA compatibility.
United States
FCC emissions pre-compliance testing shapes shielding redesigns for automation infrastructure sold into Texas and Gulf Coast petrochemical corridors. OSHA process safety management rules mandate continuous monitoring systems that embed industrial PCs directly into field enclosures. Midwest automotive stamping plants source rackmount PCs for centralized control rooms.
China
GB standards create divergent certification pathways that fragment supply chains for domestic versus export-oriented production. MIIT industrial internet initiatives subsidize edge computing deployments in Yangtze River Delta smart factories. Shenzhen-based designers now supply ARM-based controllers for wattage-constrained transportation applications.
Industrial PC Market Key Industry Players
Top-tier vendors anchor the premium automation software tier, while mid-scale specialists populate the hardware-centric segments. The vendor base arranges across three strata: diversified industrial conglomerates with automation software stacks, pure-play industrial PC fabricators with channel depth, and regional system integrators with vertical expertise. Dominant competitive moves include bundling recurring service revenue with hardware shipments and consolidating distribution control across Asia-Pacific networks.
Among diversified industrial conglomerates, Siemens AG and Mitsubishi Electric Corporation exemplify the software-hardware convergence archetype, leveraging automation software stacks to capture service revenue alongside box PC shipments. Beckhoff Automation and Advantech Co., Ltd. occupy distinct positions within the pure-play tier—Beckhoff anchoring PC-based control architectures for precision manufacturing, Advantech extending channel control across Asia-Pacific distribution networks for panel PC and edge gateway lines. Kontron and IEI Integration Corporation represent the European and Taiwanese specialist fabricators respectively, each sitting within regional supply chain ecosystems shaped by local certification requirements and foundry proximity.
| Leading Market Players |
|---|
| Kontron |
| IEI Integration Corporation |
| Advantech Co., Ltd. |
| DFI |
| Avalue Technology |
| Beckhoff Automation |
| Mitsubishi Electric Corporation |
| American Portwell Technology Inc. |
| Siemens AG |
| Others |
Cost & Logistics Intelligence
EU F-Gas Regulation compliance deadlines gate qualified supply access for refrigerant monitoring systems, concentrating premium-tier pricing power among vendors with pre-certified embedded controller platforms. German automotive and chemical processing buyers face compressed procurement timelines that favor suppliers holding validated hardware SKUs, while uncertified competitors absorb redesign costs or exit tender processes entirely.
Pricing Analysis
Margin tightening in standard-grade panel PCs reflects semiconductor foundry concentration in Taiwan and South Korea, where capacity allocation favors automotive and consumer electronics over industrial batches. Three-tier pricing structure across premium, standard, and economy levels separates IP69K washdown-rated food processing units from DIN-rail embedded controllers and bare-board compute modules. Cost-down pressure on economy-tier box PCs accelerates because Chinese ARM-based designers now undercut x86 alternatives in wattage-constrained transportation bids. Process industry buyers exhibit highest price sensitivity, treating compute hardware as commoditized infrastructure while negotiating separately for integration labor.
Supply Chain Analysis
Regional distribution centers in Singapore, Rotterdam, and Los Angeles anchor hub-and-spoke fulfillment patterns for industrial PC vendors serving multi-site manufacturing footprints. Foundry capacity concentrates in Taiwan, South Korea, and China, with industrial-grade processors and FPGA components drawing from the same 300mm wafer allocations as consumer semiconductors. Raw material dependencies span aluminum extrusions for conduction-cooled enclosures, industrial-grade capacitors with extended temperature ratings, and conformal coating chemistries. Single-source vulnerability around TSMC's mature-node capacity creates lead time volatility that distributors buffer through safety stock carrying costs. Distribution runs through authorized channel partners with technical pre-sales capability rather than commodity electronics wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial PC competition has become a vertical-integration race where control over edge software stacks and foundry allocation agreements determines margin sustainability. Players capturing upstream semiconductor procurement leverage or downstream predictive maintenance subscriptions separate from hardware replacement economics.
For Market Incumbents: Deepen automation software stack integration to bundle recurring service revenue with box PC shipments, mirroring Siemens AG's subscription-based remote monitoring architecture. Fortify foundry allocation agreements in Taiwan and South Korea against emerging Chinese ARM-based competitors. Prioritize CE marking convergence and single-SKU European strategies to reduce certification overhead versus fragmented JIS and GB compliance pathways. For New Entrants and Emerging Players: Direct-to-distributor digital channels in Southeast Asia bypass established Advantech channel control for panel PC and edge gateway lines. Target South Korean automotive tier-one suppliers with x86-compatible SCADA alternatives where incumbent pricing has hardened. White-space exists in ARM-based transportation signaling under EN 50155 and JIS E 5006 standards where wattage budgets exclude legacy x86 suppliers. For Investors and Strategic Acquirers: METI energy efficiency benchmark compliance announcements are the leading indicator that Japanese distributors will demand idle-state power documentation before stocking new models, favoring acquirees with pre-validated thermal design portfolios. Long-term viability hinges on 10-15 year supply guarantee capabilities that conflict with consumer semiconductor roadmaps, making last-time-buy negotiation expertise a scarce asset. Target regional system integrators with vertical expertise in food processing or railway signaling rather than pure hardware fabricators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Allocation | Secures industrial-grade processor supply against automotive and consumer electronics capacity competition. |
| Software-Defined Remote Monitoring Launch | Beckhoff Automation and Siemens AG demonstrate recurring revenue decoupling from hardware replacement cycles. |
| Single-SKU CE Marking Convergence | Reduces inventory carrying costs versus geography-specific JIS and GB certification pathways. |
| ARM Architecture Platform Expansion | Captures wattage-constrained transportation and energy applications where x86 thermal envelopes fail. |
| Channel Control Consolidation in Asia-Pacific | Advantech's distribution network depth creates procurement friction for competing panel PC lines. |
Research Approach
Independent corroboration across automation vendor executive interviews, semiconductor distribution channel partners, and plant engineer site assessments underwrites the qualitative findings in this study. Primary fieldwork engaged plant engineers at German automotive facilities, procurement leads at South Korean battery manufacturers, and aftermarket service heads at Japanese railway operators. Secondary validation drew from EU F-Gas Regulation implementation reports, METI energy efficiency guidance documents, and SEC filings from diversified industrial conglomerates with automation segments. Bottom-up shipment estimates by product type and technology architecture triangulate against top-down industrial automation capital expenditure forecasts.
Rate-of-change decomposition across the analysis window separates volume growth from average selling price movements by segment. The analytical framework models product type, technology architecture, end-use vertical, and deployment topology dimensions throughout the forecast period. CAGRs derive from shipment trajectory analysis calibrated against foundry capacity expansion announcements and regulatory compliance deadline clustering. Industry-specific forecast inputs include EU F-Gas refrigerant monitoring mandate timelines and METI factory automation equipment efficiency benchmarks.
The model holds under stable foundry capacity allocation and regulatory deadline adherence; deviation in Taiwan Strait logistics or EU enforcement intensity would shift shipment timing and geographic sourcing patterns. Forecasts reflect documented assumptions regarding semiconductor supply continuity and certification pathway convergence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Transparent Plastics Market
Others
Baking Paper Market
Others
Africa Cotton Market
Others
Depth Gauge Market
Others
Global Lavender Extracts Market
Others
Global Snow Sports Apparel Market
Others
Dental Ceramics Market
Others
Tanned Fish Skin Leather Market
Others
US Tablet Market
Others
Eye Balm Market
Others
Smartphone Gimbal Market
Others
Taiwan Retail Market
Others
Global Military Apparel Market
Others
Global Emergency Spill Response Market
Others
Underwater Communication System Market
Others
Nonlinear Editing System Market