
 Tanned Fish Skin Leather Market | 2026-2036
Tanned Fish Skin Leather Market Size, Share, and Industry Trends Forecast 2026-2036
Tanned Fish Skin Leather Market Insights
Custom finishing and dye-matching services is shifting how tanneries monetize output beyond raw hide sales. Nova Kaeru leverages its Paris atelier relationships to secure placement in haute couture supply chains. Kalaparkki oy anchors Nordic production through direct contracts with Finnish and Norwegian design houses. ICTYOS differentiates via proprietary vegetable-tanning protocols that meet EU chemical standards.
Tanned fish skin leather consists of collagen-based dermal layers from salmon, cod, or perch, processed through chrome-free or vegetable tanning to achieve thicknesses of 0.4–1.2 mm for flexible applications. The material serves luxury goods manufacturers seeking exotic leather alternatives with lower environmental footprints than conventional reptile or bovine hides. Accessories and footwear command the deepest margin pools among product type segments, as unit economics favor small-batch artisan production over upholstery scale. Eco-friendly material grade segments attract premium positioning from brands targeting sustainability-certified supply chains, while artificial grade products compete on price in mass-market channels.
REACH in the European Union and ECHA chemical restrictions shape tanning chemistry choices, limiting chromium discharge and mandating wastewater treatment protocols. The US EPA and state-level environmental agencies in California and New York enforce comparable effluent standards for imported leather goods. Stakeholders must monitor regulatory divergence between jurisdictions to avoid compliance costs that erode the cost advantage fish leather holds over traditional exotic hides.
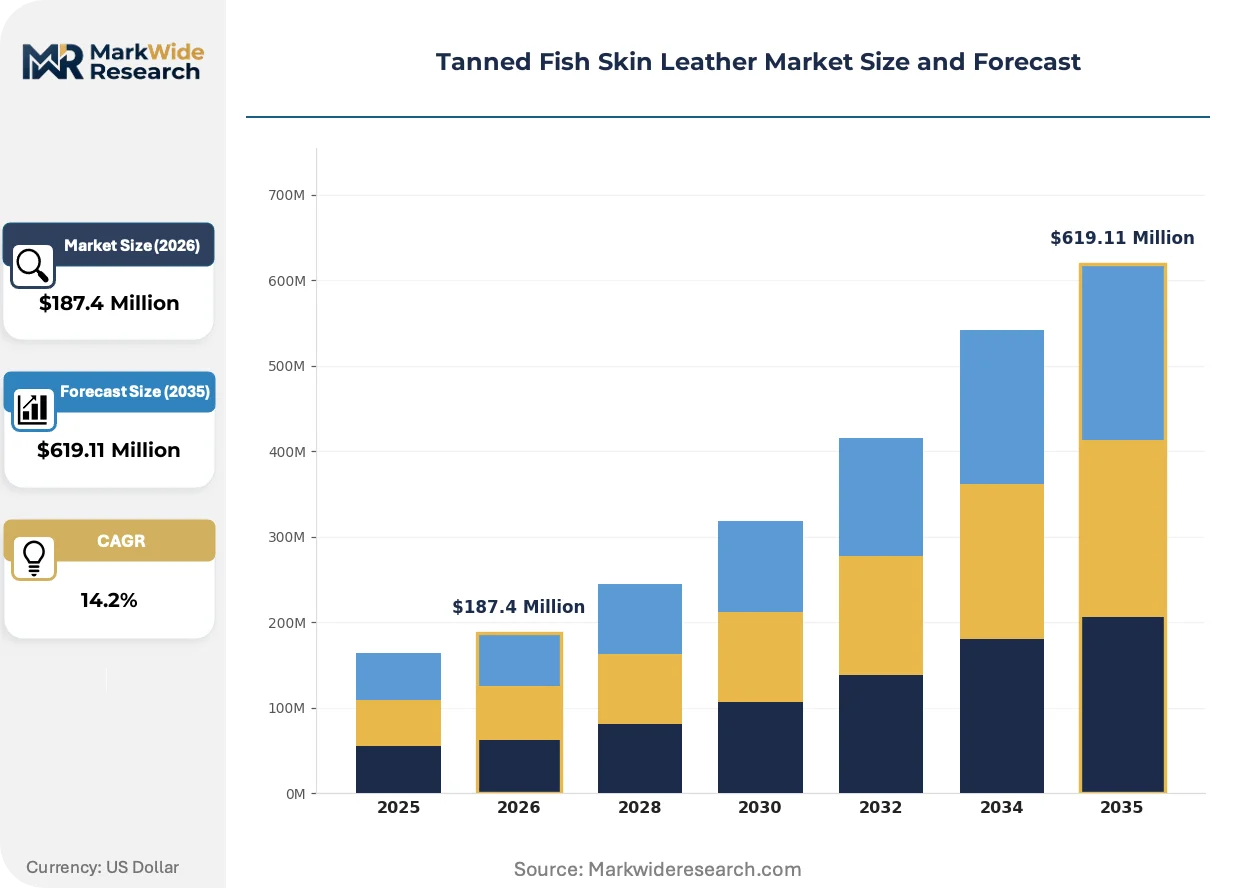
Market Dynamics
REACH compliance and ECHA chemical restrictions are forcing European tanneries to abandon chromium-based processes, redirecting capital toward vegetable-tanning infrastructure and rewiring supply relationships with luxury goods manufacturers.
Growth Catalysts
- REACH Phase-out Mandates:The European Union's restriction on chromium discharge eliminates conventional exotic leather cost advantages, positioning fish skin as the compliant alternative for accessories and footwear supply chains.
- Biomaterial Innovation:Collagen extraction and fiber-alignment technologies now yield thickness consistency of 0.4–1.2 mm, matching bovine leather performance specifications for flexible applications.
- Paris and Milan Design Houses:Haute couture ateliers in France and Italy have embedded fish skin leather into seasonal collections, creating pull-through demand from mid-tier accessory manufacturers seeking material legitimacy.
Market Restraints
- Raw Material Concentration:Salmon and cod skin supply clusters in Iceland, Norway, and Vietnam create geographic dependency risk for tanneries without multi-source contracts.
- Processing Cost Structure:Vegetable-tanning cycles require 4–6 weeks versus 24–48 hours for chromium, locking working capital and compressing margin recovery for small-batch producers.
- Labor Skill Scarcity:Artisan-level finishing expertise concentrates in Nordic and Vietnamese clusters, limiting production scaling outside these geographies without training infrastructure investment.
Strategic Opportunities
- Brazilian Artisan Cluster Expansion:Untapped capacity in Brazilian coastal processing cooperatives offers near-term volume growth for export-grade material targeting North American luxury distributors.
- EU Green Deal Procurement Mandates:Public-sector sustainable purchasing guidelines create certified-material preference windows for fish leather in institutional gift and uniform accessory segments.
- Digital Traceability Integration:Blockchain-linked supply chain verification converges with sustainability certification to unlock premium positioning in brand-direct e-commerce channels.
Industry Challenges
- ISO Leather Certification Timelines:Standard-setting delays for fish-specific material testing protocols extend product validation cycles, freezing new supplier qualification for 12–18 months.
- Tanning Chemistry IP Complexity:Proprietary vegetable-tanning formulations create licensing friction between Nordic technology holders and emerging-market processors seeking process transfer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tanned Fish Skin Leather Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Garments, Accessories, Upholstery, Footwear Application: Fashion, Automotive Interiors, Home Decor, Sporting Goods Material Grade: Premium, Standard, Eco-friendly, Artificial End User: Manufacturers, Retailers, Designers, Brands |
| Companies Covered | Salmo Leather GmbH, Nova Kaeru, Kalaparkki oy, Shadi Leather, Felsie, Nordic Fishleather Iceland, ICTYOS, Searious Fish Leather, 7 Leagues, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tanned Fish Skin Leather Market Trends and Innovations
Processing technology convergence with digital supply chain verification is compressing the gap between artisan production and industrial-scale quality consistency, reshaping how tanneries compete for luxury brand contracts.
Collagen fiber cross-linking via enzymatic pre-treatment is rewriting the performance ceiling for fish skin durability. Luxury footwear manufacturers in Italy now specify enzymatically processed material for stress-point applications previously reserved for calf leather. The technology is compressing the historical quality gap between exotic alternatives and conventional hides, forcing incumbent suppliers to accelerate process investment or cede positioning.
ECHA's 2024 update to restricted substance lists tightens chromium discharge thresholds for imported leather goods entering the European Union. Tanneries serving EU-bound luxury supply chains must retrofit wastewater treatment or exit the market. Accessory and footwear segments with EU-dominant revenue exposure are responding fastest, with French and Italian manufacturers consolidating supplier bases around REACH-certified processors.
Brand-direct material sourcing is displacing traditional hide merchant intermediaries in premium segment procurement. Luxury houses now contract directly with Icelandic and Vietnamese tanneries for exclusive dye-lot production, compressing margin capture for distribution layers. This pattern concentrates most visibly in Paris and Milan ateliers, where design teams specify custom finishing protocols that require producer-level collaboration unavailable through merchant channels.
Tanned Fish Skin Leather Market Segmentation
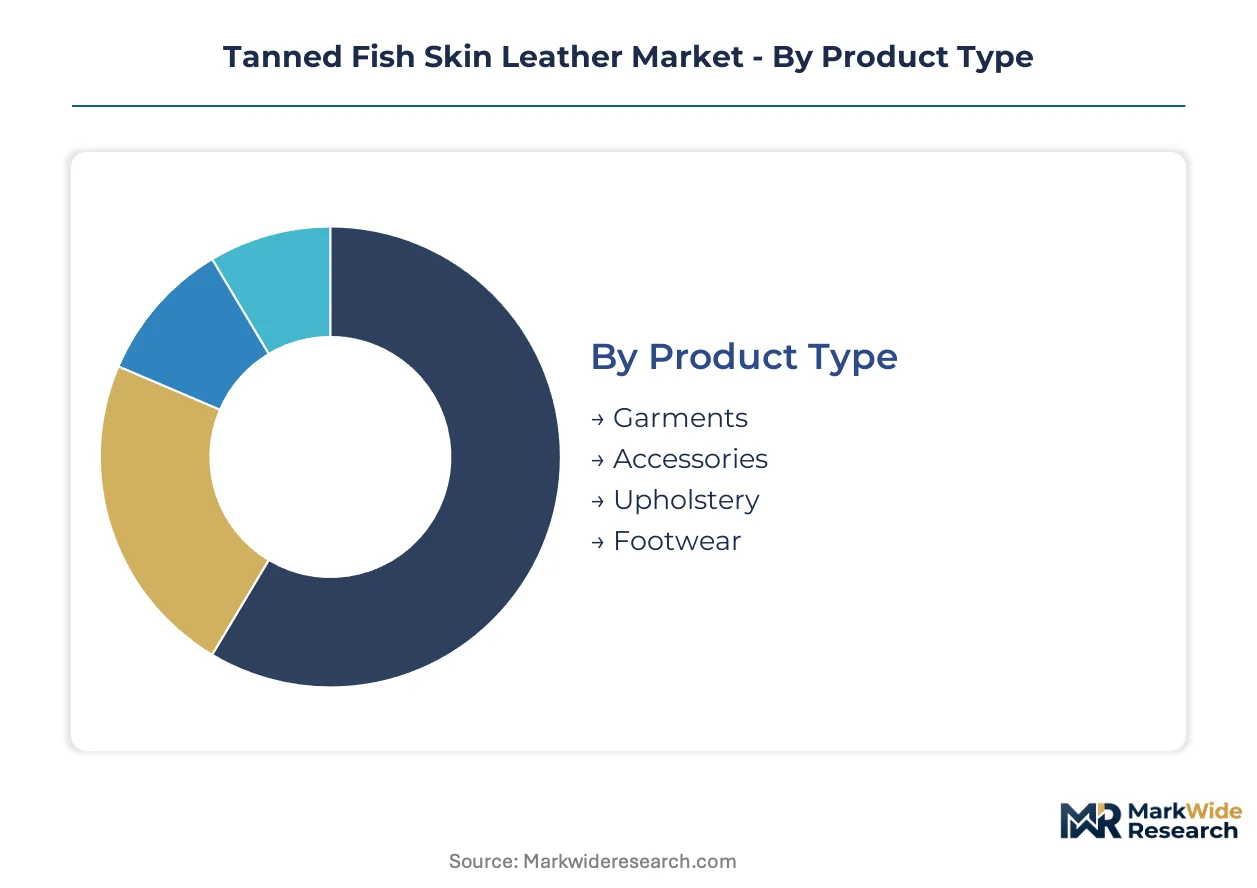
Segmentation in the tanned fish skin leather market determines which supply chains qualify for REACH-certified procurement and which remain locked out of EU luxury distribution. Certification requirements vary sharply across product categories, creating tiered access to premium pricing pools.
Product Type:
REACH compliance burden falls heaviest on segments supplying EU-bound finished goods, with accessories and footwear facing the strictest chemical residue testing protocols.
- Accessories:Small-batch production of wallets, belts, and watch straps from salmon and cod skin at 0.4–0.8 mm thickness. Paris and Milan ateliers specify this segment for haute couture collections, driving demand from mid-tier manufacturers seeking material legitimacy through association.
- Footwear:Enzymatic pre-treatment now yields stress-point durability matching calf leather specifications. Italian luxury footwear manufacturers specify fish skin for flexible upper applications, compressing the quality gap with conventional exotic hides.
- Garments:Limited to panel applications and trim due to seam strength constraints at scale.
- Upholstery:Volume-driven segment competing on price against bovine leather with thinner profit margins.
Leading the category by volume: Accessories. Growing fastest: Footwear.
Application:
Margin structure across applications correlates directly with batch size flexibility and finishing customization depth.
- Fashion:Deep margin pools concentrate in seasonal collections where custom dye-matching commands premium positioning. Direct contracts between tanneries and design houses displace traditional hide merchant intermediaries.
- Automotive Interiors:Emerging demand from electric vehicle manufacturers seeking sustainability-certified cabin materials for ESG reporting compliance.
- Home Decor:Panel and accent applications with standardized finishing requirements.
- Sporting Goods:Niche positioning in premium equipment grips and protective gear.
Highest margin capture: Fashion. Expanding most quickly: Automotive Interiors.
Material Grade:
Certification tier determines price positioning and channel access, with sustainability credentials acting as gatekeepers to brand-direct supply relationships.
- Eco-friendly:Vegetable-tanned material meeting ECHA chemical standards and EU Green Deal procurement guidelines. Blockchain-linked traceability verification unlocks premium positioning in brand-direct e-commerce channels.
- Premium:Custom-finished lots with exclusive dye protocols specified by Paris and Milan ateliers.
- Standard:Mid-market positioning with consistent thickness and color matching.
- Artificial:Chrome-tanned or synthetic-blend material competing on price in mass-market channels excluded from EU luxury supply chains.
Steepest price premium: Eco-friendly. Largest volume base: Standard.
End User:
Procurement authority concentration shapes how tanneries structure sales relationships and technical support investment.
- Brands:Direct material sourcing with custom finishing protocols and exclusive dye-lot production. Consolidating supplier bases around REACH-certified processors to manage ECHA compliance risk.
- Designers:Small-batch procurement with high customization requirements and relationship-driven vendor selection.
- Manufacturers:Volume contracting with specification-driven quality thresholds.
- Retailers:Indirect procurement through finished goods distributors with limited material specification influence.
Greatest pricing power: Brands. Fastest consolidation: Manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paris and Milan ateliers command the highest-value procurement channels for tanned fish skin leather, with French and Italian design houses setting material specifications that cascade through mid-tier supply chains worldwide.
France
Haute couture houses in Paris specify custom-dyed fish skin for seasonal accessories collections. REACH compliance mandates from ECHA restrict chromium-tanned imports, pushing manufacturers toward vegetable-tanned alternatives. The Île-de-France region concentrates finishing ateliers that serve luxury brand supply chains with exclusive dye-lot production.
Italy
Footwear manufacturers in Tuscany and Veneto now specify enzymatically processed fish skin for flexible upper applications. The country's leather goods sector operates under EU chemical discharge standards that favor chrome-free tanning methods. Milan-based design studios consolidate supplier relationships directly with Icelandic and Vietnamese tanneries.
Iceland
Salmon skin processing clusters along the Reykjanes Peninsula supply raw material to European luxury distributors. National environmental regulations align with EU wastewater treatment protocols, easing export certification. Artisan tanneries in the capital region specialize in thickness-calibrated material for accessories and small leather goods.
Vietnam
Coastal processing cooperatives in Da Nang and Quy Nhon scale export-grade production for North American and European markets. The country's industrial zone incentives support wastewater treatment infrastructure required for EU-bound shipments. Ho Chi Minh City serves as the commercial hub for contract negotiations with international luxury distributors.
Brazil
Artisan clusters in coastal Santa Catarina state develop untapped capacity for export-grade material. ANVISA chemical standards and emerging state-level environmental enforcement shape tanning process choices. São Paulo-based distributors broker relationships between regional processors and international fashion brands seeking South American supply alternatives.
Tanned Fish Skin Leather Market Competitive Landscape
Capital-heavy producers compete with asset-light designers for positioning in tanned fish skin leather supply chains. The vendor base separates between integrated tanneries owning raw material contracts and specialist finishers relying on third-party hide supply. Three archetypes dominate: Nordic integrated processors with captive fish skin supply, Paris-linked atelier specialists serving haute couture channels, and emerging-market scale operators targeting mid-tier export volumes. Competitive moves concentrate on backward integration into raw material sourcing and direct contracting with luxury brand procurement teams.
Within the Nordic integrated tier, Salmo Leather GmbH and Nordic Fishleather Iceland anchor supply relationships with EU luxury distributors through geographic proximity to salmon processing infrastructure. Nova Kaeru occupies a position exemplifying the atelier-linked specialist archetype, with Paris relationships enabling placement in haute couture supply chains. Kalaparkki oy represents the design house contract model, anchoring Finnish and Norwegian production through direct agreements with regional manufacturers. ICTYOS sits within the compliance-driven technology tier, with proprietary vegetable-tanning protocols that meet ECHA chemical standards for REACH-certified procurement.
| Leading Market Players |
|---|
| Salmo Leather GmbH |
| Nova Kaeru |
| Kalaparkki oy |
| Shadi Leather |
| Felsie |
| Nordic Fishleather Iceland |
| ICTYOS |
| Searious Fish Leather |
| 7 Leagues |
| Others |
Pricing and Supply Chain Analysis
Artisan-level finishing expertise concentrated in Nordic and Vietnamese clusters drives labor-cost differentials that widen pricing-tier spreads between atelier-grade custom production and standardized export material. REACH compliance costs in the European Union compress margins for chrome-dependent processors while rewarding vegetable-tanning specialists with premium positioning access.
Pricing Analysis
Yield-based pricing tied to defect-free surface area anchors value capture for tanneries serving haute couture channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and customization depth, with ECHA-compliant vegetable-tanned material commanding the widest spreads. Cost compression in mid-market tiers is intensifying because Brazilian and Vietnamese processors compete on volume throughput. Brand-direct buyers exhibit the least price sensitivity, while mass-market distributors face margin pressure from artificial-grade substitutes.
Supply Chain Analysis
Domestic-content requirements under the EU Green Deal procurement guidelines are reshaping sourcing patterns for institutional buyers seeking certified fish leather. Raw material supply concentrates in Iceland, Vietnam, and Brazil, with salmon and cod skin availability tethered to seasonal fishing yields. Enzymatic pre-treatment chemicals, vegetable-tanning extracts, and dye formulations constitute critical input dependencies. Single-source vulnerability runs through Icelandic salmon skin contracts that lack multi-species diversification. Distribution runs through direct contracts between tanneries and Paris or Milan design houses, displacing traditional hide merchant intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where captive control over raw material sourcing determines margin durability and REACH compliance certainty.
For Market Incumbents: Deploy proprietary vegetable-tanning IP licensing to emerging-market processors seeking ECHA compliance pathways. Secure multi-year salmon and cod skin offtake agreements in Iceland and Vietnam to defend against supply concentration risk from new Nordic entrants. Certification investment in blockchain-linked traceability systems protects positioning as brand-direct procurement displaces merchant channels. For New Entrants and Emerging Players: Brand-direct e-commerce channels offer the most penetrable route for artisan tanneries seeking bypass of established distribution layers. Target Brazilian coastal processing cooperatives with underutilized capacity and favorable ANVISA chemical standards for near-term volume scaling. White-space exists in automotive interior applications where electric vehicle manufacturers seek sustainability-certified cabin materials for ESG reporting. For Investors and Strategic Acquirers: Re-rating potential sits with REACH-certified integrated processors given ECHA's tightening chromium discharge thresholds and consolidation pressure on non-compliant suppliers. Acquisition targets should demonstrate captive raw material contracts and direct design house relationships. The signal to watch is ISO leather certification timeline acceleration for fish-specific material testing protocols, which would unlock supplier qualification bottlenecks and validate premium positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Supply | Captive salmon and cod skin contracts in Iceland and Vietnam secure volume certainty for REACH-certified production. |
| Proprietary Vegetable-Tanning Technology Licensing | ECHA-compliant process transfer to emerging-market processors expands addressable supply base for EU-bound luxury brands. |
| Blockchain-Linked Traceability Implementation | Digital supply chain verification unlocks premium positioning in brand-direct e-commerce channels targeting sustainability-certified buyers. |
| Direct Design House Contracting | Paris and Milan atelier relationships displace hide merchant intermediaries and capture margin from custom finishing protocols. |
| Automotive Interior Segment Expansion | Electric vehicle manufacturer procurement for ESG-compliant cabin materials diversifies revenue beyond fashion-dependent seasonality. |
Research Methodology
Trade databases, tannery association publications, and ECHA regulatory filings formed the secondary backbone for supply-side calibration. Primary interviews with tanning process engineers, luxury brand procurement directors, and sustainability certification auditors combined with customs records and REACH compliance registries. Bottom-up and top-down triangulation validated volume estimates across product type and material grade segments.
Bottom-up modeling built from individual tannery capacity declarations and design house contract announcements, while top-down cross-checks applied spend-ratio analysis to luxury accessories and footwear sector revenue. Segmentation dimensions included product type, material grade, application, and end-user procurement authority across the analysis window. CAGRs derived from fitted growth curves incorporating regulatory phase-out timelines and biomaterial innovation adoption rates. Forecast inputs incorporated enzymatic pre-treatment yield improvements and EU Green Deal procurement mandate expansion.
The model holds under sustained ECHA enforcement of chromium discharge restrictions and stable artisan labor availability in Nordic and Vietnamese clusters; deviation in tanning chemistry breakthroughs or raw material supply disruptions would shift trajectory. Forecasts reflect documented assumptions regarding certification timeline delays and brand-direct procurement consolidation. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Healthcare Bioconvergence Market
Others
Pollen Allergy Market
Others
Free Space Optics (FSO) Market
Others
Versatile Video Coding Market
Others
Aerospace Engineering Services Outsourcing Market
Others
Global Supply Chain Risk Management Software Market
Others
Technical Films Market
Others
Global Food Fiber Market
Others
Europe Meditation Market
Others
Solar Lighting Tower Market
Others
Global Aircraft Sensors Market
Others
UAE Location-Based Services Market
Others
Global Injectable Nanomedicine Market
Others
Global Molded Plastics Market
Others
Manometers Market
Others
North America Compressor Oil Market