
 Ultra-Low-VOC Methacrylate Reactive Diluents Market | 2026-2036
Ultra-Low-VOC Methacrylate Reactive Diluents Market Size, Share, and Industry Trends Forecast 2026-2036
Ultra-Low-VOC Methacrylate Reactive Diluents Market Insights
REACH is decoupling legacy formulation economics from viable market entry in Europe, forcing reformulation investments that favor suppliers with pre-certified product lines. Mitsubishi Chemical Group leverages captive monomer supply to anchor cost positions across alkyl and hydroxyalkyl grades. Evonik Industries differentiates through R&D intensity in specialty methacrylates for electronics-grade applications. BASF sustains broad geographic coverage by operating integrated diluent-coating resin platforms across multiple industrial zones.
Ultra-low-VOC methacrylate reactive diluents are monofunctional or multifunctional methacrylate monomers with volatile organic compound content below regulatory thresholds, typically serving as viscosity reducers in radiation-curable or ambient-cure systems while participating in polymerization. These materials incorporate functional groups such as hydroxyethyl or glycidyl methacrylate to enable crosslinking in coatings, adhesives, and composite matrices without solvent release. Hydroxyalkyl methacrylate dominates formulation portfolios due to adhesion-promoting hydroxyl functionality, while alkyl methacrylate occupies high-volume industrial coating segments where cost efficiency governs specification. Branched methacrylate variants represent the fastest-growing structural category, as steric hindrance properties enable low-shrinkage performance in precision electronics and optical applications where dimensional stability commands premium positioning.
EPA VOC regulations, EU REACH restrictions on hazardous substance authorization, and F-Gas Regulation phase-down targets collectively constrain conventional solvent use and redirect procurement toward reactive diluent architectures. Japan's METI chemical management framework and China's GB standards on architectural coatings impose parallel compliance burdens that standardize low-emission formulation requirements across major manufacturing jurisdictions. Stakeholders must monitor evolving substance restriction lists and pre-qualify alternative chemistries before existing raw materials face sunset dates that would disrupt qualified supplier lists and customer certifications.
Market Dynamics
REACH authorization timelines are compressing reformulation windows across European coating houses, forcing rapid qualification of alternative chemistries before legacy raw materials face sunset restrictions that would disrupt certified supplier lists.
Growth Catalysts
- EPA VOC limits:Automotive refinishing operations in the United States face tightening emission caps under federal air quality standards, accelerating solvent-to-reactive diluent substitution in collision repair networks.
- Electronics miniaturization:Precision optical and semiconductor packaging applications demand low-shrinkage methacrylate architectures that steric hindrance properties uniquely deliver.
- Germany's automotive OEM specification pull:Industrial coating houses serving Volkswagen, BMW, and Mercedes-Benz operations drive volume concentration for solvent-free methacrylate systems.
Market Restraints
- Acrylic acid feedstock volatility:Crude oil price swings and refinery operating rates transmit directly into methacrylate monomer cost structures, squeezing formulator margins during upstream tightness.
- Specialty monomer supply concentration:Hydroxyalkyl and glycidyl methacrylate production clusters in Western European and East Asian chemical corridors, creating geographic single-source risk for qualified material.
- UV-cure substitution threat:Acrylate-based reactive diluents offer faster cure kinetics and lower unit costs in high-speed industrial coating lines, pressuring methacylate share in non-automotive segments.
Strategic Opportunities
- India's architectural coatings compliance gap:BIS implementation of GB-aligned VOC standards for decorative paints creates first-mover positioning for pre-certified low-emission diluent suppliers.
- EV battery thermal management:Potting and encapsulation applications in electric vehicle power electronics represent an emerging specification channel for thermally stable methacrylate formulations.
- EU Green Deal industrial decarbonization incentives:Carbon border adjustment mechanisms and green public procurement rules redirect public infrastructure coating budgets toward verified low-emission chemistries.
Industry Challenges
- Formulation chemist talent scarcity:Radiation-cure and ambient-cure system expertise concentrates among aging technical workforces in Germany and Japan, constraining R&D velocity at mid-tier coating houses.
- REACH pre-registration cascade timelines:ECHA substance evaluation windows and authorization list updates compress product requalification cycles, forcing parallel development tracks before regulatory certainty emerges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultra-Low-VOC Methacrylate Reactive Diluents Market |
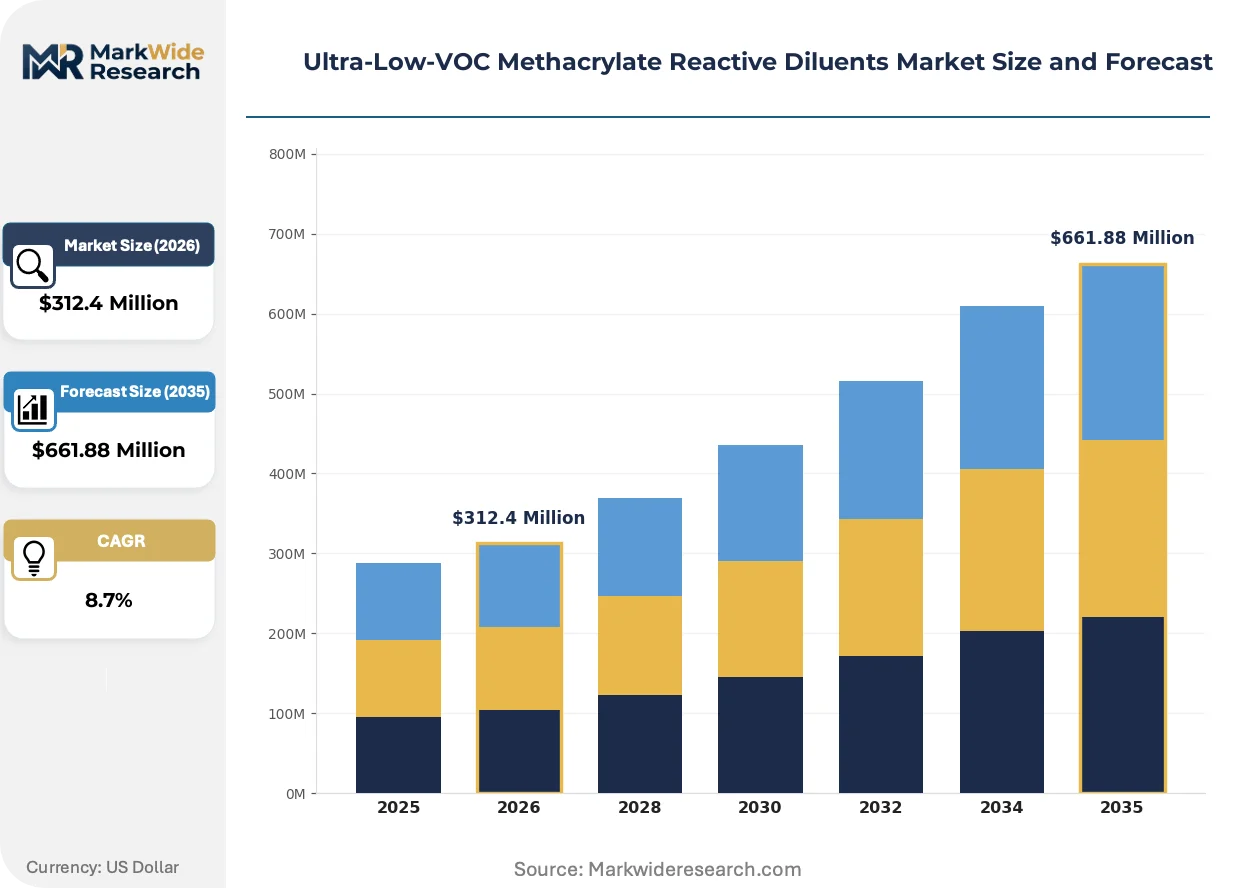
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkyl Methacrylate, Hydroxyalkyl Methacrylate, Aromatic Methacrylate, Branched Methacrylate Application: Coatings, Adhesives, Sealants, Composites, Printing Inks End User Industry: Construction, Electronics Manufacturing, Packaging, Marine Equipment, Consumer Goods Formulation Type: Liquid, Prepolymer, Solvent-Free, Waterborne |
| Companies Covered | Mitsubishi Chemical Group, Evonik Industries, BASF, Arkema, Dow, Mitsui Chemicals, Covestro, Nippon Shokubai, Allnex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultra-Low-VOC Methacrylate Reactive Diluents Market Trends and Innovations
Formulation automation and digital twin modeling are compressing development cycles for reactive diluent systems, while regulatory pre-certification investments increasingly separate viable suppliers from qualified ones.
Photoinitiator package optimization is automating cure response calibration across variable substrate chemistries. Automotive OEM coating engineers are deploying machine-learning-driven formulation databases to predict methacrylate reactivity profiles without extensive wet-lab iteration. This capability is automating specification lock-in for suppliers with pre-validated monomer libraries.
F-Gas Regulation phase-down targets are redirecting conventional solvent procurement toward reactive architectures in European industrial maintenance coatings. The restriction of hydrofluorocarbon blowing agents and cleaning solvents creates parallel pressure for methacrylate diluent adoption in adjacent process steps. German marine and protective coating operations face the most immediate compliance deadlines, accelerating technical service investments by qualified material suppliers.
Direct specification relationships between automotive OEMs and raw material suppliers are displacing traditional distributor-mediated procurement in high-volume coating programs. Tier-1 applicators serving Volkswagen and BMW operations now require methacrylate diluent suppliers to maintain technical service presence within 200 kilometers of assembly plant locations. This pattern concentrates supplier development resources in Lower Saxony and Bavaria manufacturing corridors.
Ultra-Low-VOC Methacrylate Reactive Diluents Market Segmentation
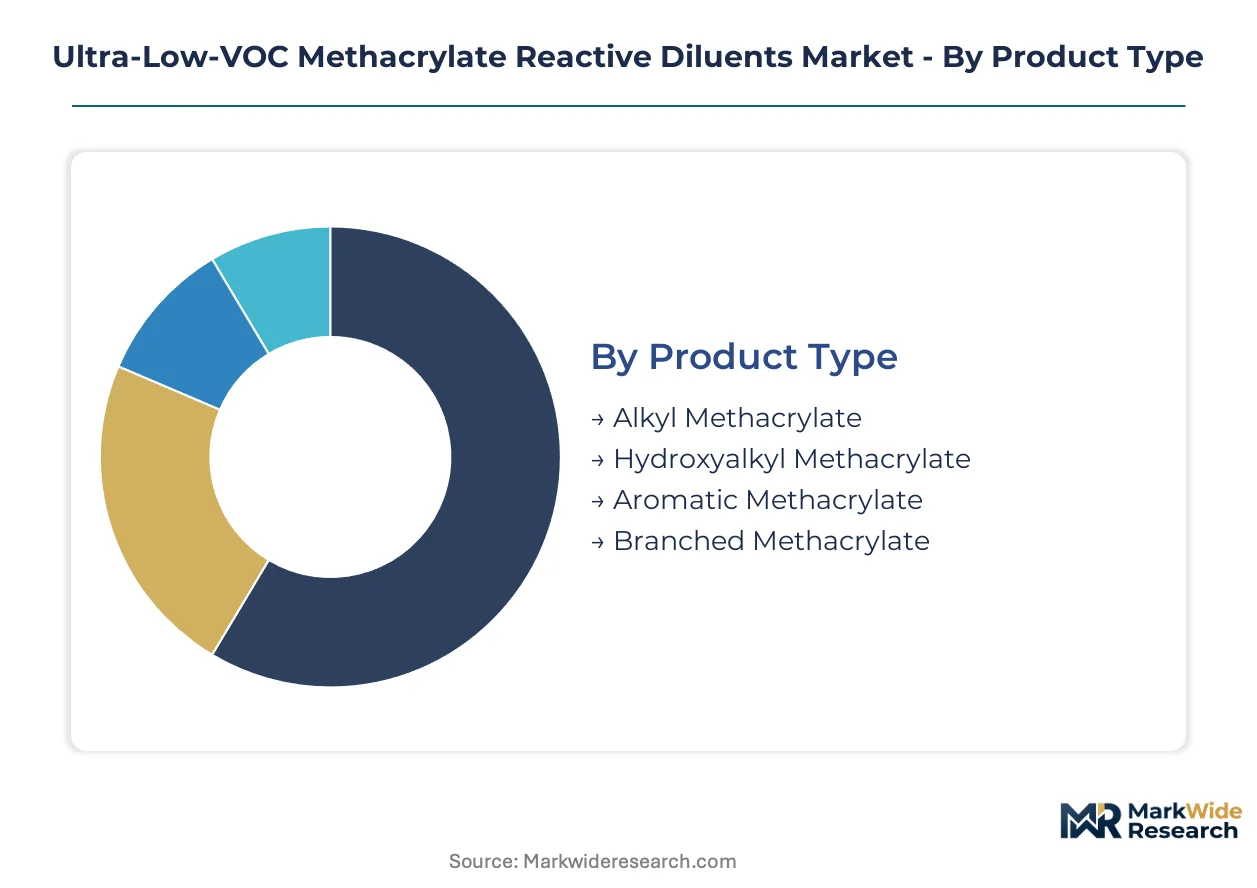
Segmentation in ultra-low-VOC methacrylate reactive diluents reveals distinct specification tiers where reformulation cycles and regulatory compliance windows create divergent growth trajectories across product architectures and end-use channels.
Product Type:
Upgrade cycles in radiation-cure systems favor methacrylate architectures with enhanced functionality over commodity alkyl grades, driving portfolio rebalancing among European and Japanese formulators.
- Hydroxyalkyl Methacrylate:Hydroxyl-functional monomers enable adhesion promotion and crosslinking density in automotive clearcoats and industrial primers. German automotive OEM specifications pull this grade into solvent-free refinish systems as EPA and REACH deadlines compress reformulation timelines.
- Alkyl Methacrylate:Straight-chain and cyclic alkyl variants deliver cost-efficient viscosity reduction in high-volume industrial coatings. Demand concentrates in marine protective applications across German and Japanese shipyards where F-Gas Regulation and METI frameworks restrict conventional solvent use.
- Branched Methacrylate:Steric hindrance properties minimize polymerization shrinkage for precision electronics potting and optical adhesive applications.
- Aromatic Methacrylate:Benzyl and phenyl derivatives provide refractive index matching and thermal stability in specialty coating segments.
Hydroxyalkyl methacrylate sits at the top of the volume ranking, with branched methacrylate climbing the fastest.
Application:
Cost tier differentiation separates specification-intensive automotive and electronics applications from price-sensitive industrial maintenance segments, fragmenting procurement patterns across customer categories.
- Coatings:Automotive OEM and refinish operations dominate consumption, with collision repair networks in the United States and assembly plant suppliers in Germany driving solvent-to-reactive substitution under tightening EPA and EU emission caps.
- Adhesives:Structural bonding in electronics packaging and automotive assembly demands low-shrinkage methacrylate architectures that acrylate alternatives cannot match for dimensional stability.
- Sealants:Construction and marine applications specify hydroxyalkyl grades for moisture-cure compatibility and substrate adhesion.
- Composites:Resin infusion and pultrusion processes in wind energy and transportation sectors utilize methacrylate diluents for ambient-temperature cure profiles.
- Printing Inks:UV-flexo and screen printing applications favor faster-cure acrylate chemistries, constraining methacrylate penetration in high-speed packaging lines.
Coatings commands the largest value share, while adhesives gains share fastest on electronics miniaturization demand.
End User Industry:
Customer type concentration in automotive supply chains creates specification pull that cascades through tiered supplier networks, privileging formulators with pre-certified reactive diluent portfolios.
- Electronics Manufacturing:Semiconductor packaging, display lamination, and optical component bonding require low-shrinkage branched methacrylates. Japanese and South Korean electronics clusters specify these materials for precision assembly tolerance control.
- Construction:Architectural coatings and flooring systems in Germany and France face EU Green Deal procurement rules that redirect public infrastructure budgets toward verified low-emission chemistries.
- Marine Equipment:Protective coatings for commercial vessels and offshore structures in German and Japanese shipyards confront F-Gas Regulation and METI compliance deadlines.
- Packaging:Food-contact and consumer goods applications face divergent regulatory requirements across FDA, EFSA, and GB standard jurisdictions.
- Consumer Goods:Specialty adhesives and coatings for durable goods assembly occupy niche specification tiers with limited volume scale.
Electronics manufacturing leads on margin contribution, with construction expanding most quickly on green public procurement redirection.
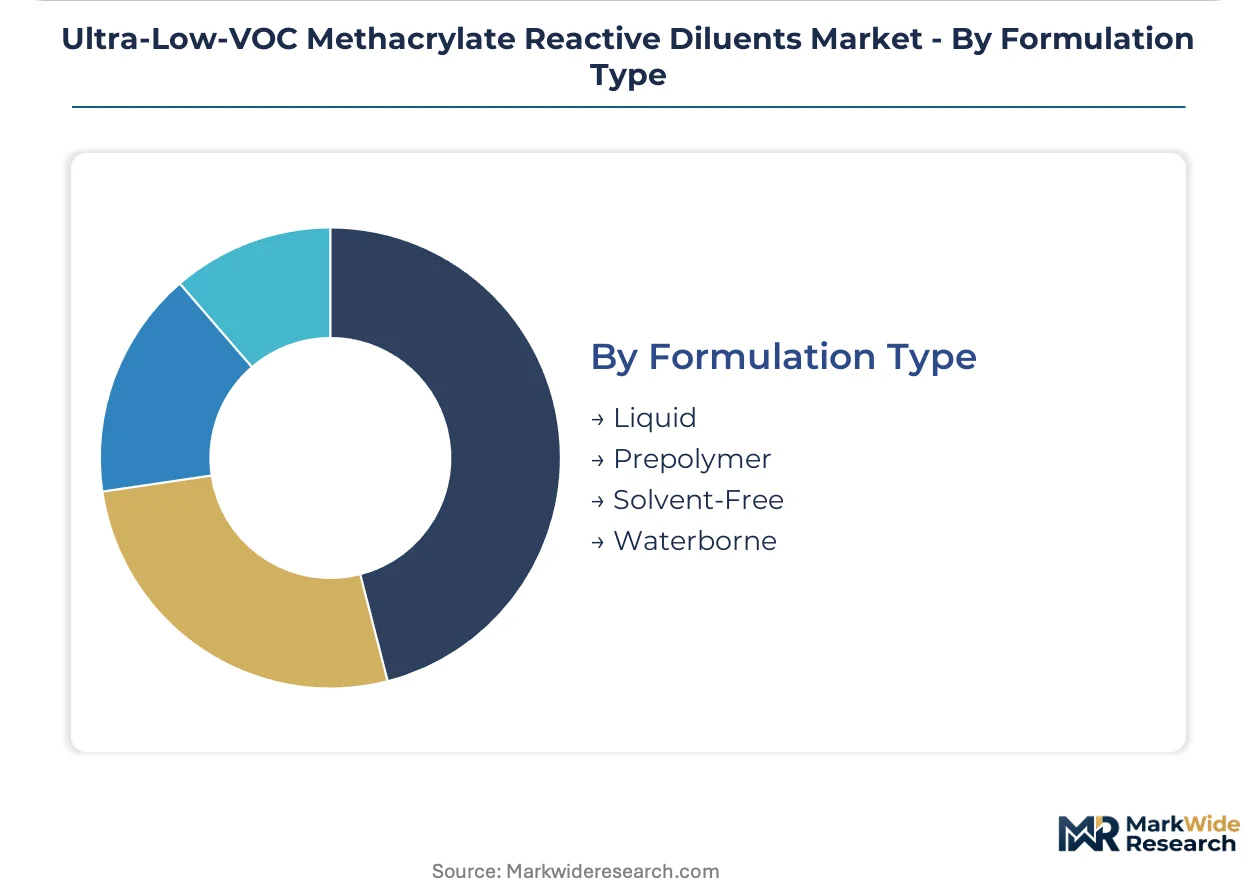
Formulation Type:
Supply concentration in solvent-free and prepolymer systems reflects integrated resin-diluent production capabilities among Western European and East Asian chemical producers.
- Solvent-Free:Pure reactive diluent systems eliminate VOC release entirely, satisfying the most stringent EPA automotive refinish limits and EU industrial coating directives. German automotive OEMs mandate this formulation class for assembly plant and certified collision repair networks.
- Liquid:Standard monomeric diluents balance handling convenience with reactivity control in ambient-cure industrial coatings.
- Prepolymer:Oligomeric methacrylate architectures reduce shrinkage and improve toughness in structural adhesive and composite applications.
- Waterborne:Emulsified reactive diluents address architectural coating segments where spray application and cleanup economics favor aqueous systems.
Solvent-free formulations dominate specification-driven segments, with prepolymer systems showing steepest expansion trajectory on electronics and composite demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical engineering traditions established methacrylate monomer production at industrial scale during the 1960s, with Ludwigshafen and Marl complexes serving as foundational sites for reactive diluent chemistry that now spans automotive and electronics applications worldwide.
Germany
Automotive OEM specification pull from Volkswagen, BMW, and Mercedes-Benz drives solvent-free methacrylate system adoption across Lower Saxony and Bavaria coating corridors. REACH authorization timelines compress reformulation windows for industrial coating houses serving these assembly plants. Technical service investments concentrate within 200 kilometers of Wolfsburg and Munich manufacturing clusters.
United States
Collision repair networks face tightening EPA VOC limits under federal air quality standards, accelerating solvent-to-reactive diluent substitution. Automotive refinishing operations in Michigan and Ohio industrial belts specify low-emission methacrylate architectures for certified repair programs. Chicago and Detroit metropolitan areas host the largest concentration of qualified applicator training facilities.
Japan
Semiconductor packaging and display lamination demand precision branched methacrylates for dimensional stability in Kyushu and Kansai electronics clusters. METI chemical management frameworks impose parallel compliance burdens that standardize low-emission formulation requirements. Osaka and Nagoya metropolitan areas concentrate formulation expertise for radiation-cure system development.
China
GB standards on architectural coatings impose VOC compliance requirements that redirect procurement toward reactive diluent architectures in Yangtze River Delta manufacturing zones. NMPA and MIIT frameworks standardize low-emission requirements across coating and adhesive applications. Shanghai and Jiangsu province chemical parks concentrate domestic methacrylate monomer production capacity.
South Korea
Electronics miniaturization in Gyeonggi-do and Busan-Ulsan clusters demands low-shrinkage methacrylate architectures for precision optical assembly. MFDS and national chemical management standards align with EU REACH substance restrictions for export-oriented manufacturing. Suwon and Hwaseong industrial complexes specify these materials for smartphone and display component bonding.
Ultra-Low-VOC Methacrylate Reactive Diluents Market Competitive Landscape
The competitive structure tilts toward integrated petrochemical conglomerates with captive monomer supply. Three to five multinational chemical groups control the majority of hydroxyalkyl and glycidyl methacrylate production capacity, while regional specialists occupy niche specification tiers. Strategic archetypes include upstream-integrated resin producers, specialty monomer houses with R&D intensity, and formulation service providers with geographic anchoring. Capacity expansion and regulatory pre-certification investments represent the dominant competitive moves, with technical service proximity to automotive OEM assembly plants serving as a secondary differentiation axis.
Among integrated chemical producers, Mitsubishi Chemical Group, Evonik Industries, and BASF occupy positions that exemplify distinct strategic archetypes within this structure. Mitsubishi Chemical Group represents upstream-integrated production with captive monomer supply chains. Evonik Industries sits within the specialty methacrylate tier with concentrated R&D positioning. BASF anchors broad geographic coverage through integrated diluent-coating resin platforms. These three entities collectively illustrate how scale, specialization, and geographic scope define viable competitive positioning in ultra-low-VOC methacrylate reactive diluents.
| Leading Market Players |
|---|
| Mitsubishi Chemical Group |
| Evonik Industries |
| BASF |
| Arkema |
| Dow |
| Mitsui Chemicals |
| Covestro |
| Nippon Shokubai |
| Allnex |
| Others |
Pricing and Supply Chain Analysis
Upstream-integrated petrochemical conglomerates with captive acrylic acid supply chains anchor pricing discipline across hydroxyalkyl and alkyl methacrylate grades, while independent formulators absorb margin compression during feedstock volatility. This ownership pattern concentrates volume leverage among three to five multinational producers, forcing mid-tier coating houses into long-term offtake contracts that lock in cost predictability against spot market swings.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs methacrylate reactive diluent transactions, with certification grade under REACH and F-Gas Regulation compliance creating the primary price differentiation driver. Cost compression in standard alkyl grades is intensifying because acrylic acid feedstock volatility transmits directly from refinery operating rates, while automotive OEM specification channels show the least price sensitivity due to regulatory compliance mandates.
Supply Chain Analysis
Reverse-logistics flows for off-specification monomer batches and expired inventory create secondary material channels that discipline primary market pricing in German and Japanese chemical corridors. Production gravity centers on Germany, Japan, and China, with supply chains drawing from crude oil derivatives, acrylic acid, and methanol feedstocks. Single-source vulnerability concentrates in hydroxyalkyl methacrylate qualified material, while distribution runs through integrated resin-diluent platforms and technical service-proximate direct sales to automotive OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA automotive refinish limits and REACH authorization timelines cascade through tiered supplier networks, converting compliance deadlines into specification lock-in advantages for pre-certified portfolios.
For Market Incumbents: Deepen captive monomer supply integration to defend margin positions against acrylic acid volatility, while accelerating REACH pre-certification investments ahead of ECHA substance evaluation windows that threaten legacy raw material sunset dates. Prioritize technical service proximity within 200 kilometers of Volkswagen and BMW assembly clusters to automate specification lock-in. For New Entrants and Emerging Players: Capture India's architectural coatings compliance gap as BIS implements GB-aligned VOC standards, where first-mover positioning for pre-certified low-emission diluents faces limited domestic competition. Target EV battery thermal management applications through thermally stable methacrylate formulations, leveraging formulation partnerships with power electronics specialists rather than direct OEM sales cycles. For Investors and Strategic Acquirers: Specialty chemical conglomerates seeking coating resin portfolio gaps are the most active acquirer in this space, particularly those lacking radiation-cure system capabilities. Long-term viability hinges on regulatory pre-certification asset values that compound through successive REACH authorization cycles. Monitor ECHA authorization list updates for inflection signals that trigger forced reformulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Pre-Certification Investment | Automates specification lock-in before ECHA sunset deadlines disrupt qualified supplier lists. |
| Captive Acrylic Acid Integration | Mitsubishi Chemical Group and BASF leverage upstream control to anchor cost positions during feedstock tightness. |
| Technical Service Proximity Expansion | German automotive OEMs mandate 200-kilometer service radius for assembly plant coating programs. |
| Specialty Monomer R&D Intensity | Evonik Industries concentrates development in electronics-grade branched methacrylates for precision applications. |
| Long-Term Automotive OEM Contracts | Direct specification relationships with Volkswagen and BMW displace distributor-mediated procurement. |
Research Methodology
Bottom-up coatings and adhesives demand modeling reconciled against top-down monomer production tracking forms the analytical core, combining primary interviews with procurement leads at automotive OEMs, technical R&D directors at industrial coating houses, plant managers at methacrylate production facilities, and distribution channel partners. Secondary validation draws from ECHA substance registration databases, EPA automotive refinish compliance filings, customs and trade flow data, and SEC 10-K disclosures from integrated chemical producers.
Input-output matrices map methacrylate monomer consumption across grade tier, end-use industry, formulation type, and regional production hub, with value trajectories derived from price-volume elasticity modeling and regulatory-driven substitution elasticity coefficients across the analysis window. Forecast inputs incorporate REACH authorization timeline probabilities, automotive OEM specification cycle schedules, and electronics miniaturization content-per-unit trends.
Feedstock price volatility, ECHA regulatory acceleration, and UV-cure acrylate substitution advances are the dominant revision risks to modeled outcomes. Practitioners should monitor ECHA substance evaluation windows and acrylic acid refinery operating rates for early signals requiring forecast recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Para Nitrochlorobenzene Market
Solvents
Reactive Diluents Market
Solvents
Propylene Glycol Methyl Ether Market
Solvents
Retardant Solvent Market
Solvents
Global Solvent Dyes Market
Solvents
Benzyl Alcohol Market
Solvents
Trichloroacetyl Chloride Market
Solvents
Global Xylenols Market
Solvents
3-Methyl-3-Penten-2-One (3M3P) Market
Solvents
Global Glycidol Market
Solvents
Global Ink Solvents Market
Solvents
2-Phenylethanol Market
Solvents
Ketone-Based Solvents Market
Solvents
Global Acetonitrile Market
Solvents
Ethyl Pyruvate Market
Solvents
Nitromethane Market