
 Xenon Headlights Market | 2026-2036
Xenon Headlights Market Size, Share, and Industry Trends Forecast 2026-2036
Xenon Headlights Market Analytics
Asset-light leasing models for automotive lighting production equipment is fragmenting competitive barriers across the xenon headlamp supply base. Hella leverages its vertical integration into electronic control modules to sustain margin capture on ballast and igniter systems. Koito Manufacturing anchors high-volume supply contracts with Japanese OEMs through dedicated manufacturing lines in Aichi Prefecture. Osram competes on phosphor chemistry expertise, controlling rare gas sourcing relationships that underpin xenon arc tube consistency.
Xenon headlights are high-intensity discharge lamps that produce illumination by exciting xenon gas within a quartz arc tube via high-voltage pulse, generating color temperatures typically ranging from 4,000K to 6,000K with luminous efficacy exceeding halogen alternatives by roughly threefold. Bi-Xenon configurations now lead product mix evolution by combining high and low beam functions within a single projector module, reducing hardware count for OEMs. Aftermarket Providers represent the fastest-growing end-user channel as vehicle owners seek retrofit kits for aging halogen platforms, though OEM fitment still occupies the dominant margin pool through bundled lighting packages on premium trims.
NHTSA's Federal Motor Vehicle Safety Standard 108 governs headlamp photometric performance and aiming requirements in the United States, while ECE Regulation 98 specifies xenon source approval criteria across European type certification frameworks. These standards directly shape product development cycles, as manufacturers must navigate separate homologation pathways for transatlantic vehicle programs. Stakeholders should monitor how EPA fuel-economy incentives for efficient lighting systems interact with NHTSA safety mandates to determine whether xenon retains platform share against solid-state alternatives.
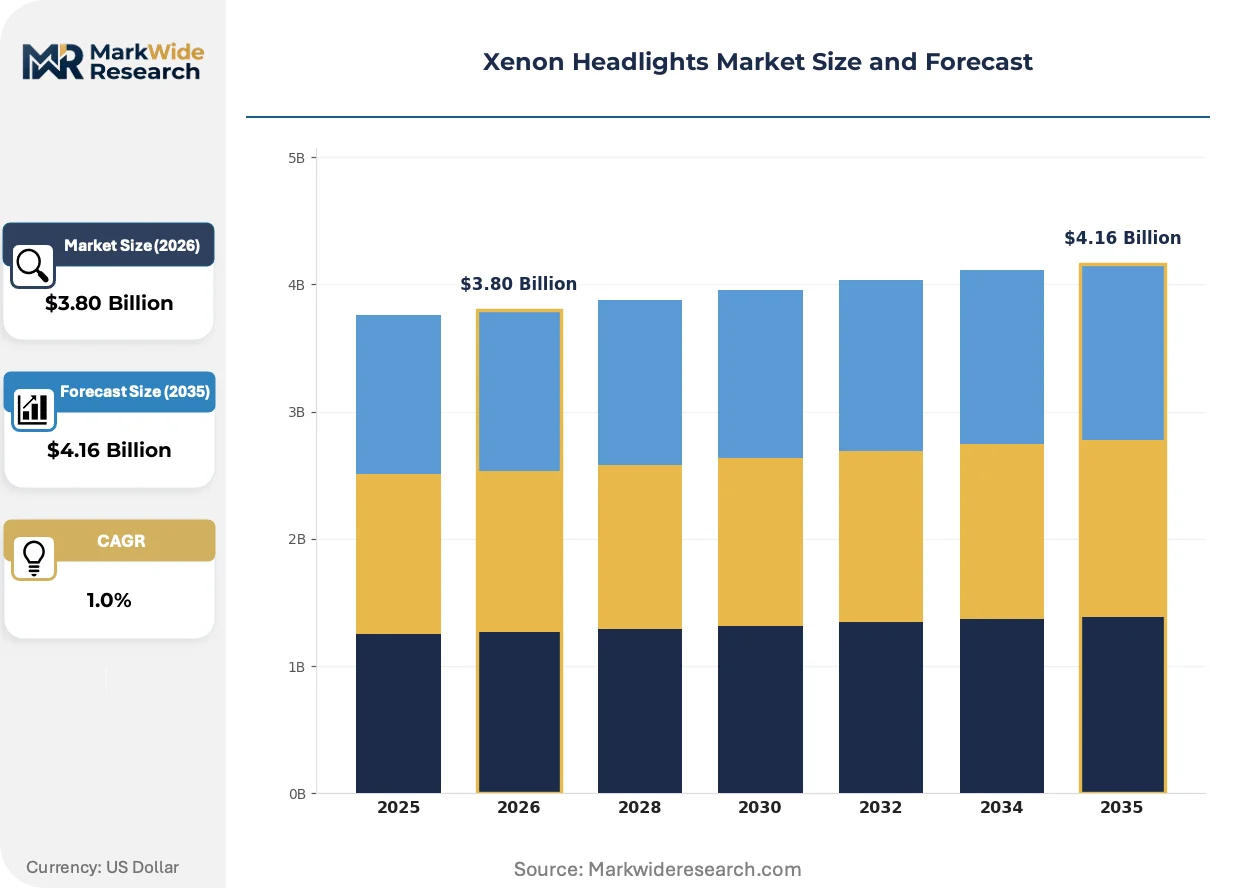
Market Dynamics
The transition from halogen to solid-state lighting architectures is compressing xenon's addressable platform base, forcing incumbent suppliers to defend residual premium fitment contracts and aftermarket retrofit demand channels.
Growth Catalysts
- ECE Regulation 48 compliance:European type-approval requirements for headlamp installation and performance sustain OEM specification of xenon systems on premium vehicle lines requiring certified arc-discharge photometric output.
- Aftermarket retrofit demand:Vehicle owners operating aging halogen-equipped platforms drive replacement kit consumption through independent service channels and e-commerce distributors.
- Germany's premium manufacturing corridor:Concentrated OEM engineering centers in Stuttgart, Munich, and Ingolstadt specify xenon for select model tiers where arc-source color temperature and beam pattern consistency remain valued.
Market Restraints
- Rare gas supply concentration:Xenon extraction depends on fractional distillation of atmospheric gases at limited cryogenic separation facilities, creating input cost volatility and sourcing bottlenecks.
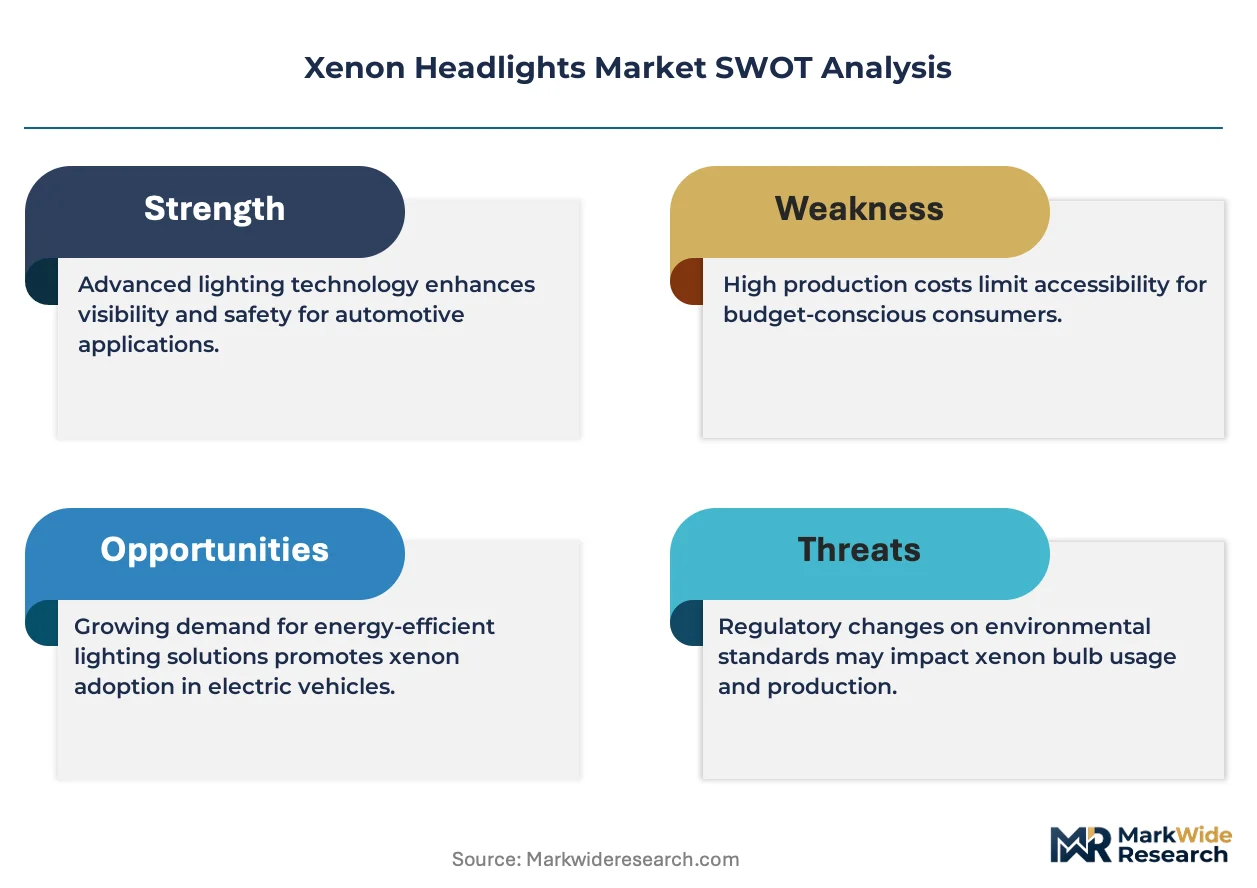
- LED luminous efficacy crossover:Solid-state sources now match or exceed xenon output per watt, eliminating the efficiency advantage that originally justified arc-discharge platform costs.
- NHTSA Federal Motor Vehicle Safety Standard 108:US photometric and aiming requirements impose separate homologation burdens that extend development timelines and certification expenses for transatlantic vehicle programs.
Strategic Opportunities
- Asset-light production equipment leasing:Third-party financing of ballast and igniter assembly lines reduces capital barriers for mid-tier suppliers seeking OEM contract access.
- Bi-Xenon projector convergence:Single-module high/low beam integration reduces hardware count and wiring complexity, preserving xenon relevance where packaging constraints favor consolidated optical systems.
- India's premium vehicle segment expansion:Domestic luxury automotive assembly growth creates new specification opportunities as local OEM subsidiaries evaluate lighting tier strategies.
Industry Challenges
- Phosphor chemistry expertise scarcity:Formulation consistency for arc tube color rendering requires specialized materials science talent that concentrates at incumbent suppliers.
- Dual homologation pathway management:Engineers must simultaneously satisfy ECE Regulation 98 source approval and NHTSA FMVSS 108 performance criteria, complicating platform engineering resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Xenon Headlights Market |
| Market Size in 2026 | $3.80 Billion |
| Market Size in 2035 | $4.16 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Xenon High Beam, Xenon Low Beam, Bi-Xenon, Xenon Fog Light End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Car Dealerships Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Off-Road Vehicles Technology: Gas Discharge, LED, Halogen, Hybrid |
| Companies Covered | Hella, Koito Manufacturing, Osram, Marelli, Stanley Electric, Philips, Valeo, Cree, GE Lighting, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Xenon Headlights Market Evolving Landscape
Product architecture consolidation and regulatory harmonization pressures are reshaping how xenon systems retain relevance against solid-state alternatives. Three developments merit particular attention.
Bi-Xenon projector modules combine high and low beam functions within a single optical assembly, eliminating separate reflector hardware. OEMs specify these configurations for premium vehicle lines where packaging density and styling flexibility outweigh incremental module cost. This integration is rendering obsolete the dual-lamp front-end architectures that previously required discrete high-beam supplementation.
ECE Regulation 98 establishes xenon source approval criteria that govern European type certification, including arc tube construction, igniter pulse characteristics, and ballast electromagnetic compatibility. The framework's technical prescriptions constrain design freedom but create compliance moats that deter low-cost competitors lacking homologation infrastructure. German KBA enforcement of these provisions most directly affects suppliers serving Audi, BMW, and Mercedes-Benz development programs.
Aftermarket channel unbundling separates lighting component procurement from dealer service networks, with vehicle owners increasingly sourcing retrofit kits through independent installers and direct-to-consumer platforms. This disintermediation compresses margin capture for traditional tier-one distributors while expanding addressable volume for specialized xenon suppliers. The shift is most visible in North American and Western European markets where consumer technical literacy and online parts availability enable self-directed upgrade decisions.
Xenon Headlights Market Segmentation
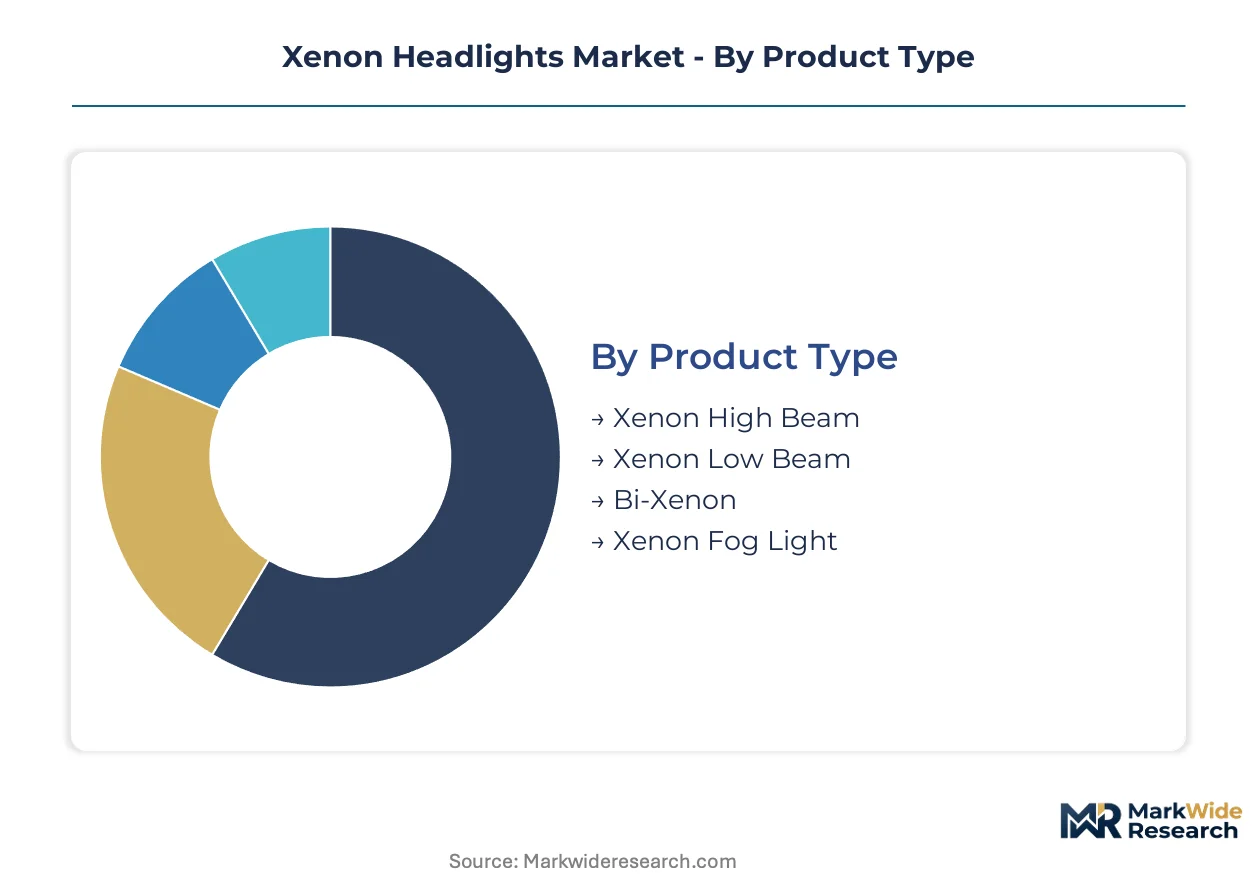
Xenon headlamp segmentation reveals how arc-discharge technology retains commercial relevance across distinct performance tiers and supply channels. Each dimension exposes where solid-state substitution pressures concentrate versus where xenon specifications persist.
Product Type:
Mature configurations dominate OEM fitment while emerging architectures reshape optical packaging strategies.
- Bi-Xenon:Single-projector modules integrate high and low beam functions through mechanical shutter mechanisms, eliminating separate lamp housings. German premium OEMs specify Bi-Xenon for mid-tier luxury sedans where styling flexibility and reduced front-end complexity outweigh incremental ballast costs.
- Xenon Low Beam:Dedicated arc-discharge projectors for dipped illumination remain the default specification on entry-premium vehicle lines. Stuttgart-based engineering centers retain this configuration for cost-optimized lighting packages where full Bi-Xenon upgrade penetration remains incomplete.
- Xenon High Beam:Standalone arc-discharge high beams persist in dual-lamp architectures for heavy commercial platforms requiring maximum luminous intensity at extended ranges.
- Xenon Fog Light:Compact arc-discharge modules for auxiliary forward illumination address niche aftermarket retrofit demand and select OEM auxiliary lighting tiers.
Bi-Xenon retains volume leadership across premium OEM platforms; Xenon Fog Light holds the steepest expansion curve through independent service channel retrofit activity.
End User:
Cost tier stratification separates bundled factory specification from unbundled replacement procurement.
- OEMs:Original equipment manufacturers specify xenon systems as tiered trim differentiators, with arc-discharge lighting reserved for mid-to-upper vehicle configurations where package pricing absorbs ballast and igniter hardware costs.
- Aftermarket Providers:Independent distributors and specialized retrofit shops serve vehicle owners seeking halogen-to-xenon conversions on aging platforms, sourcing ballast assemblies and projector modules through direct-import channels.
- Vehicle Assemblers:Contract manufacturing facilities integrate complete lighting modules supplied under tier-one procurement agreements, with specification authority residing at parent OEM engineering centers.
- Car Dealerships:Authorized dealer networks handle warranty replacements and accessory upgrades, though margin capture is compressing as consumers shift toward independent installers and e-commerce procurement.
OEMs retain volume leadership through bundled trim packaging; Aftermarket Providers hold the steepest expansion curve as channel disintermediation accelerates.
Application:
Customer type segmentation separates mass-market passenger transport from specialized commercial and recreational duty cycles.
- Passenger Vehicles:Sedans, SUVs, and crossovers represent the core addressable base for xenon fitment, with specification concentrated in D-segment and above where premium positioning justifies arc-discharge hardware investment.
- Commercial Vehicles:Heavy trucks and transit buses specify xenon for durability-critical forward lighting, leveraging arc-source longevity advantages over halogen in high-mileage duty cycles.
- Motorcycles:Two-wheeled applications favor compact projector formats with reduced power draw, though LED substitution is accelerating fastest in this segment due to packaging constraints and vibration resistance requirements.
- Off-Road Vehicles:Agricultural, mining, and construction equipment specify ruggedized xenon modules for extreme environmental exposure where sealed optical assemblies and electromagnetic compatibility certification prove essential.
Passenger Vehicles retain volume leadership; Off-Road Vehicles hold the steepest expansion curve through specialized equipment replacement demand.
Technology:
Supply concentration patterns reveal how incumbent arc-discharge specialists defend position against solid-state substitution.
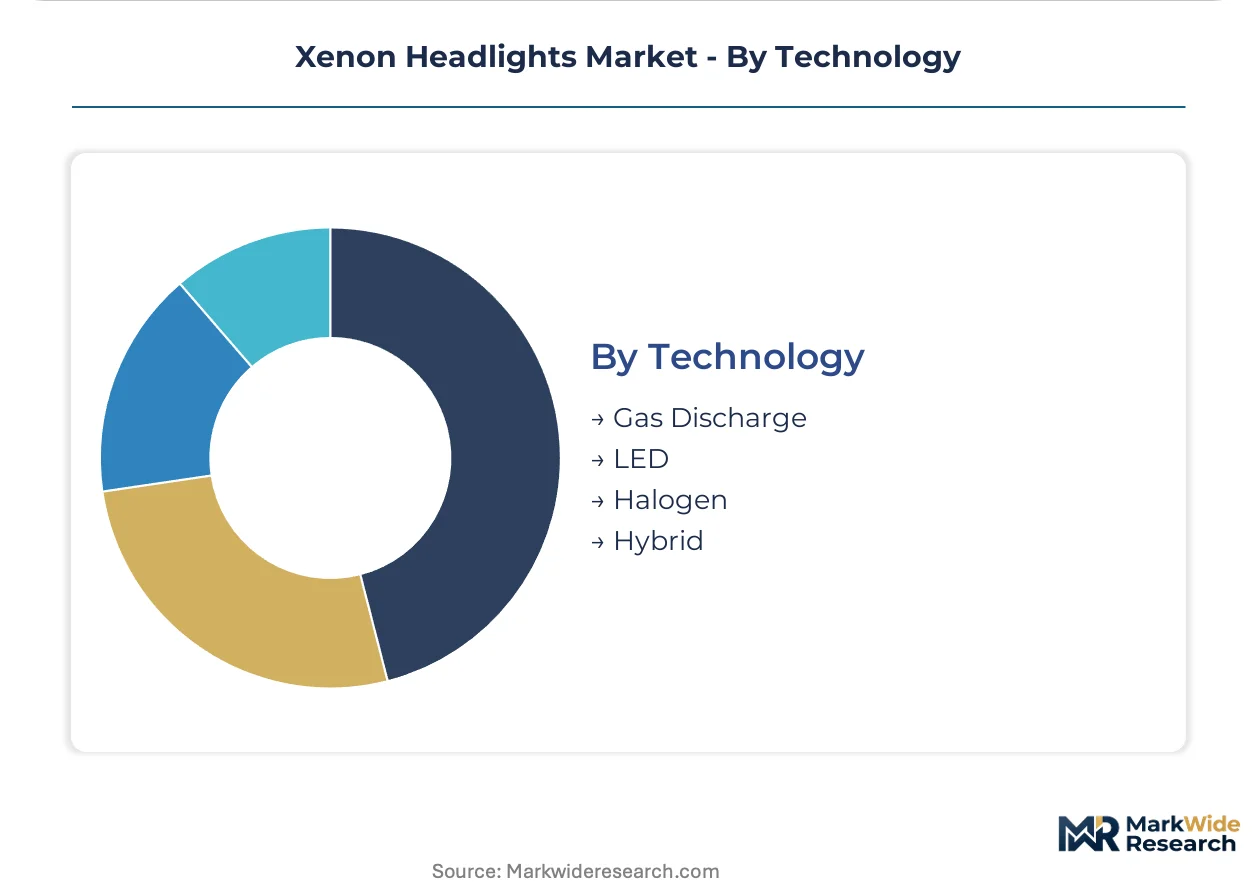
- Gas Discharge:Conventional xenon arc technology relies on high-voltage pulse ignition and electronic ballast stabilization, with incumbent suppliers controlling rare gas sourcing and phosphor chemistry expertise that constrains new entrant replication.
- LED:Solid-state sources now dominate new vehicle lighting architecture, displacing xenon from mainstream specification through superior luminous efficacy and reduced system complexity.
- Halogen:Incandescent tungsten-halogen technology retains economy-tier fitment where lowest acquisition cost outweighs efficiency or performance considerations.
- Hybrid:Combined arc-discharge and solid-state configurations pair xenon low beams with LED daytime running lights or signature elements, preserving xenon relevance in transitional lighting architectures.
Gas Discharge retains volume leadership among arc-source categories; Hybrid holds the steepest expansion curve as OEMs bridge technology transitions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fuel-economy incentives and safety mandates across major automotive manufacturing jurisdictions sustain xenon specification on residual premium vehicle platforms despite solid-state substitution pressures.
Germany
KBA enforcement of ECE Regulation 98 governs xenon source approval for Audi, BMW, and Mercedes-Benz engineering centers concentrated in Stuttgart, Munich, and Ingolstadt. The premium OEM corridor specifies Bi-Xenon modules for mid-tier luxury sedans where arc-discharge color temperature consistency remains a trim differentiator.
United States
NHTSA Federal Motor Vehicle Safety Standard 108 imposes separate photometric and aiming requirements that extend homologation timelines for transatlantic vehicle programs. Detroit-based engineering centers specify xenon for select domestic premium truck and SUV platforms where bundled lighting packages justify ballast hardware costs.
Japan
METI industrial standards and JIS certification frameworks shape component procurement for Toyota, Honda, and Nissan development programs. Aichi Prefecture manufacturing clusters anchor high-volume supply contracts through dedicated ballast and igniter assembly lines serving domestic OEM specifications.
China
MIIT vehicle type-approval requirements and GB standards for automotive lighting govern xenon fitment on domestically assembled premium vehicles. Yangtze River Delta automotive manufacturing corridors evaluate arc-discharge specifications for joint-venture luxury platforms where European engineering influence persists.
India
BIS certification mandates and PLI scheme incentives for automotive component localization create specification opportunities as domestic luxury assembly expands. Maharashtra and Gujarat manufacturing corridors host Audi, BMW, and Mercedes-Benz subsidiaries evaluating lighting tier strategies for locally assembled premium vehicles.
Xenon Headlights Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated incumbents controlling rare gas sourcing and phosphor chemistry expertise. Tier-one suppliers dominate OEM fitment contracts through captive ballast and igniter production, while mid-tier specialists capture aftermarket retrofit demand through direct-import channels. Three archetypes define competitive positioning: integrated lighting system suppliers, component specialists, and aftermarket distributors. Capacity rationalization and portfolio diversification toward solid-state alternatives represent the dominant competitive moves as addressable platform base contracts.
Among German-integrated system suppliers, Hella exemplifies vertical control over electronic control modules. Osram anchors phosphor chemistry and rare gas sourcing relationships that constrain new entrant replication. Koito Manufacturing occupies a position within Japanese high-volume supply chains through dedicated production infrastructure.
| Leading Market Players |
|---|
| Hella |
| Koito Manufacturing |
| Osram |
| Marelli |
| Stanley Electric |
| Philips |
| Valeo |
| Cree |
| GE Lighting |
| Others |
Value Network & Pricing Analysis
Aichi Prefecture's dedicated ballast and igniter assembly lines anchor capacity for Japanese OEM procurement, with volume concentration translating directly into tier-one supplier pricing leverage over mid-tier competitors seeking contract access.
Pricing Analysis
Certification level creates the primary spread across xenon headlamp procurement tiers. ECE Regulation 98 source approval and NHTSA FMVSS 108 compliance separate premium OEM fitment from aftermarket retrofit channels, with homologated systems commanding substantial ballast and igniter hardware premiums. Pricing pressure stems from LED luminous efficacy crossover eliminating xenon's efficiency justification, compressing margins on entry-premium vehicle lines. Aftermarket Providers exhibit highest price sensitivity due to channel disintermediation and direct-import sourcing alternatives, while German premium OEMs remain least sensitive where bundled lighting packages absorb component costs.
Supply Chain Analysis
Contract manufacturing concentration rests with Hella's in-house electronic control module production, Koito Manufacturing's dedicated Aichi Prefecture lines, and Osram's captive phosphor chemistry operations. Geographic supply concentration centers on Germany, Japan, and China, with Stuttgart and Ingolstadt engineering clusters specifying Bi-Xenon modules and Yangtze River Delta corridors evaluating arc-discharge fitment for joint-venture platforms. Raw material dependencies draw from rare gas cryogenic separation facilities, quartz arc tube substrates, and electromagnetic shielding components. Single-source vulnerability concentrates in fractional distillation capacity for xenon extraction. Distribution runs through tier-one supplier direct OEM contracts, aftermarket independent service channels, and e-commerce direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Xenon headlamps trace a cyclical recovery pattern tied to premium vehicle production schedules, with German OEM platform refreshes providing intermittent demand pulses despite secular LED substitution.
For Market Incumbents: Harden rare gas sourcing relationships and phosphor chemistry expertise against emerging solid-state substitution threats. Koito Manufacturing anchors high-volume supply through dedicated Aichi Prefecture capacity expansion, while backward integration into electronic ballast production preserves margin capture against component commoditization pressures from aftermarket distributors.
For New Entrants and Emerging Players: India's Maharashtra and Gujarat manufacturing corridors offer underpenetrated specification opportunities as Audi, BMW, and Mercedes-Benz subsidiaries evaluate lighting tier strategies for locally assembled premium vehicles. Target aftermarket retrofit demand through direct-import channel partnerships with independent installers, leveraging BIS certification pathways as a differentiated entry mechanism against established tier-one supplier relationships.
For Investors and Strategic Acquirers: Long-term, this sits as a cash-cow consolidation play because residual premium OEM fitment contracts and aftermarket retrofit channels generate predictable returns despite contracting addressable platform base. Target acquisition archetypes include specialized xenon suppliers with ECE Regulation 98 homologation infrastructure and rare gas sourcing relationships. Monitor LED cost parity progression and EPA fuel-economy incentive shifts as inflection indicators for accelerated platform share erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Bi-Xenon Module Standardization | Single-projector high/low beam integration reduces hardware count for Stuttgart-based OEM engineering centers. |
| Rare Gas Supply Agreement | Long-term cryogenic separation contracts with atmospheric gas processors stabilize input cost volatility. |
| Aftermarket Channel Partnership | Independent installer alliances bypass dealer network margin compression from e-commerce disintermediation. |
| ECE Regulation 98 Certification Investment | Homologation infrastructure creates compliance moats deterring low-cost competitor replication. |
| Hybrid Lighting Architecture Development | Combined xenon-LED configurations preserve arc-discharge relevance through transitional platform specifications. |
Research Methodology
Operator-level perspectives from OEM platform engineers, tier-one supplier procurement leads, aftermarket distributor operations heads, and dealership service managers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through vehicle production databases, IHS Markit registration data, ECE type-approval filings, and NHTSA FMVSS 108 compliance records. Bottom-up segment enumeration triangulated against top-down market sizing across product type, end user, application, and technology dimensions.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation modeling spanning vehicle class, OEM tier, regional production cluster, and content-per-vehicle specifications. CAGRs derived from trend extrapolation of premium vehicle production schedules, LED substitution curves, and aftermarket retrofit penetration patterns. Industry-specific forecast inputs incorporated ECE Regulation 98 homologation timelines and EPA fuel-economy incentive program interactions with NHTSA safety mandates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by LED-dominant solid-state specialists or accelerated rare gas supply consolidation would shift outcomes beyond modeled ranges. Quarterly review of German premium vehicle platform specifications, LED luminous efficacy benchmarks, and aftermarket channel disintermediation metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Industrial Lighting Cybersecurity Market
Lighting
Street and Roadway Lighting Market
Lighting
Lighting Market
Lighting
Industrial UV-C Disinfection Lighting Market
Lighting
Explosion Proof Lighting Market
Lighting
Hazardous Location LED Lighting Market
Lighting
Smart Street Lighting Systems Market
Lighting
Industrial Lighting Lifecycle Services Market
Lighting
Xenon Lights Market
Lighting
Hazardous Lighting Market
Lighting
Solar Column Headlight Market
Lighting
Industrial Lighting Market
Lighting
Illuminating Signs Market
Lighting
Fluorescent Lighting Market
Lighting
Lighting Control Components Market
Lighting
Global Work Lights Market